
 Global HPV Testing and Pap Test Market | 2026-2036
Global HPV Testing and Pap Test Market Size, Share, and Industry Trends Forecast 2026-2036
Global HPV Testing and Pap Test Market Foresight
Community health programs are redrawing procurement priorities across the Global HPV Testing and Pap Test Market, shifting volume toward decentralized screening models. Hologic, Inc. leverages its installed base of cytology platforms to sustain laboratory relationships in North America. QIAGEN anchors molecular testing workflows through PCR amplification systems that dominate reference lab configurations. Abbott Laboratories differentiates with integrated instrument-reagent architectures that reduce per-test operational complexity.
HPV testing and Pap testing encompass cytological and molecular diagnostic methods designed to detect human papillomavirus nucleic acids or abnormal cervical cellular morphology, typically requiring liquid-based specimen preservation and automated slide imaging systems operating at 200-400x magnification for adequate squamous epithelial assessment. The primary commercial purpose centers on early cervical cancer detection and precancerous lesion triage to enable therapeutic intervention before invasive disease progression. PCR amplification technology leads the technology segment due to its analytical sensitivity for high-risk HPV genotyping, while automated cytology commands margin pools through capital-intensive platform placements that lock in reagent annuity streams. Co-testing applications are expanding fastest as clinical guidelines in multiple jurisdictions endorse simultaneous HPV DNA and cytology evaluation for women over thirty.
FDA premarket notification pathways shape device commercialization timelines for US manufacturers, while EMA's In Vitro Diagnostic Regulation reclassifies HPV assays into higher-risk categories that demand expanded clinical evidence. WHO's cervical cancer elimination strategy directs procurement standards for low- and middle-income country programs, creating divergence between premium automated platforms and manual screening alternatives. Stakeholders must monitor evolving guideline harmonization between national screening programs and molecular test manufacturers to anticipate volume shifts between cytology-dependent and HPV-primary protocols.
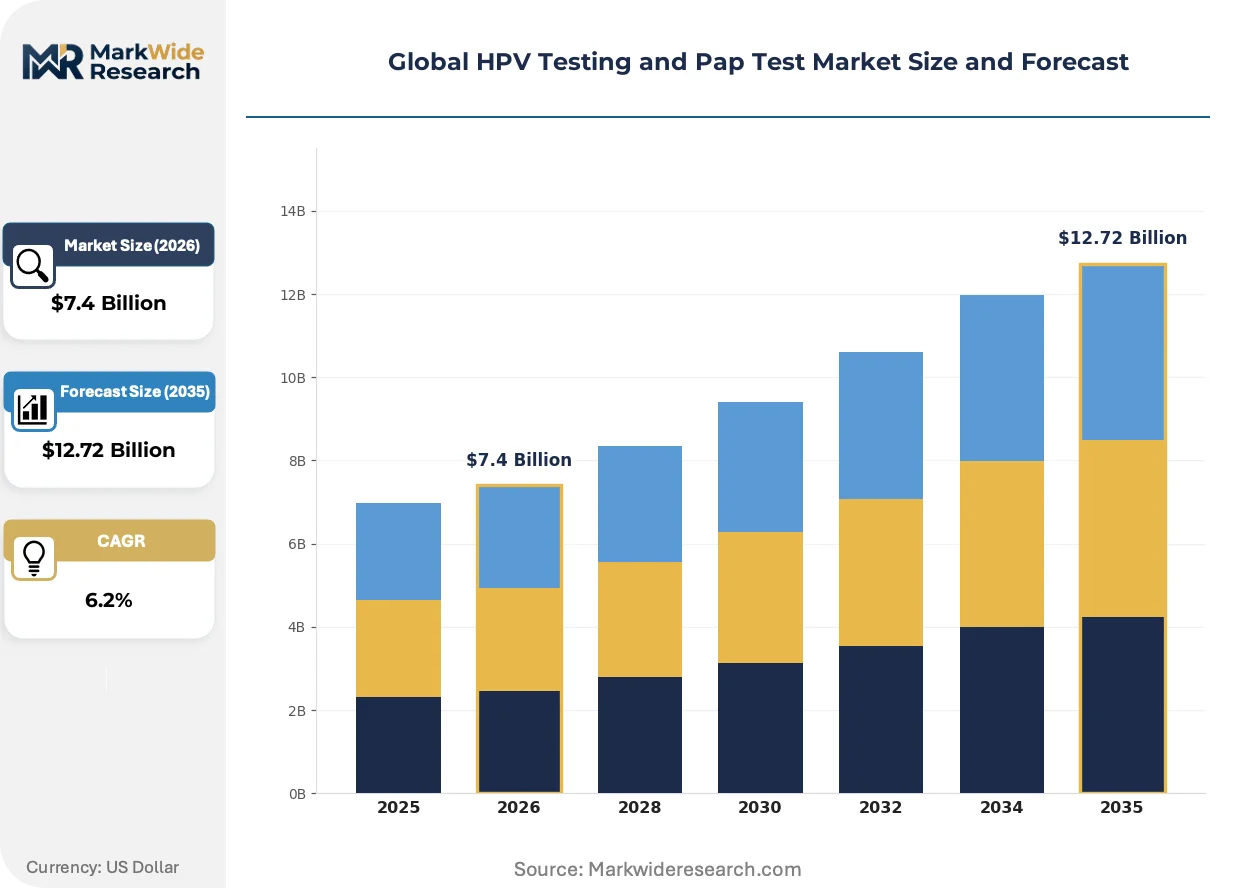
Market Dynamics
Co-testing protocols are compressing the historical cytology-dominant workflow into molecular-first architectures, forcing capital redeployment across diagnostic infrastructure worldwide.
Growth Catalysts
- WHO cervical cancer elimination targets:The WHO strategy mandates HPV-DNA testing as the primary screening method, redirecting public procurement budgets toward molecular platforms in low- and middle-income health systems.
- EMA In Vitro Diagnostic Regulation reclassification:Higher-risk categorization for HPV assays demands expanded clinical evidence, creating competitive moats for manufacturers with robust trial infrastructure.
- Self-sampling specimen collection:Vaginal self-collection kits are expanding screening access beyond clinic-dependent populations, particularly in rural Brazil and India where ANVISA and CDSCO pathways are accelerating approvals.
Market Restraints
- Reimbursement fragmentation:Inconsistent coding between HPV genotyping and cytology co-tests across US Medicare, Medicaid, and commercial payers creates revenue recognition uncertainty for laboratory operators.
- Platform switching costs:Capital-intensive liquid-based cytology installations in Germany and Japan lock facilities into reagent annuity contracts, delaying PCR amplification conversions.
- Manual screening persistence:Cost-constrained health systems in parts of Africa and Southeast Asia continue deploying conventional Pap smear microscopy, constraining molecular test addressable markets.
Strategic Opportunities
- Point-of-care molecular testing:Cartridge-based isothermal amplification systems enable same-result screening in decentralized settings, opening primary care clinics and pharmacy chains as new channels.
- Extended genotyping panels:Beyond HPV 16/18, expanded high-risk genotype detection supports risk stratification algorithms that guide colposcopy referral intensity.
- AI-augmented cytology review:Automated image analysis algorithms reduce pathologist reading burden in Japan and South Korea, where MFDS and PMDA are establishing validation frameworks for machine learning-assisted diagnostics.
Industry Challenges
- Laboratory information system integration:Molecular test result formats require HL7 FHIR mapping to legacy cytology reporting modules, extending implementation timelines for hospital networks.
- Cytotechnologist workforce constraints:Specialized training pipelines for morphological assessment are contracting in the United States and United Kingdom, creating bottlenecks for hybrid co-testing workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global HPV Testing and Pap Test Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $12.72 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HPV DNA Test, Pap Smear Test, Liquid-Based Cytology, Visual Inspection with Acetic Acid, Co-Testing Technology: Chemiluminescence, PCR Amplification, Hybrid Capture, Immunocytochemistry, Automated Cytology, Fluorescence In Situ Hybridization Application: Cervical Cancer Screening, Precancerous Lesion Detection, Infection Monitoring, Post-Treatment Follow-Up, Risk Assessment End User: Diagnostic Laboratories, Women’s Health Clinics, Research Institutes, Family Planning Centers, Community Health Programs |
| Companies Covered | Hologic, Inc., QIAGEN, Abbott Laboratories, Becton, Dickinson and Company, F. Hoffmann-La Roche Ltd, Quest Diagnostics Incorporated, Seegene Inc., Arbor Vita Corporation, Femasys Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global HPV Testing and Pap Test Market Shifts & Advancements
Digital pathology infrastructure and automated specimen processing are collapsing the cost structure of cervical screening, enabling volume expansion into previously uneconomical populations.
Next-generation sequencing is decomposing the discrete assay-per-genotype model into multiplexed detection architectures. Reference laboratories in the United States and Germany are adopting targeted NGS panels that simultaneously profile HPV integration sites and host genomic alterations. This convergence is compressing the timeline from screening to treatment planning into single-visit pathways.
EMA's MDR implementation is forcing retrospective clinical performance studies for legacy HPV assays already on market. Manufacturers must generate real-world evidence from European screening registries to maintain CE marking. The regulatory burden is favoring larger diagnostic firms with established post-market surveillance infrastructure over mid-tier entrants.
Subscription-based reagent contracts are displacing per-test purchasing in integrated delivery networks. Health systems in Brazil and Australia are negotiating multi-year supply agreements that bundle instruments, consumables, and algorithm updates into predictable operational expenditures. This procurement model concentrates purchasing authority within centralized supply chain functions rather than individual laboratory directors.
Global HPV Testing and Pap Test Market Segmentation
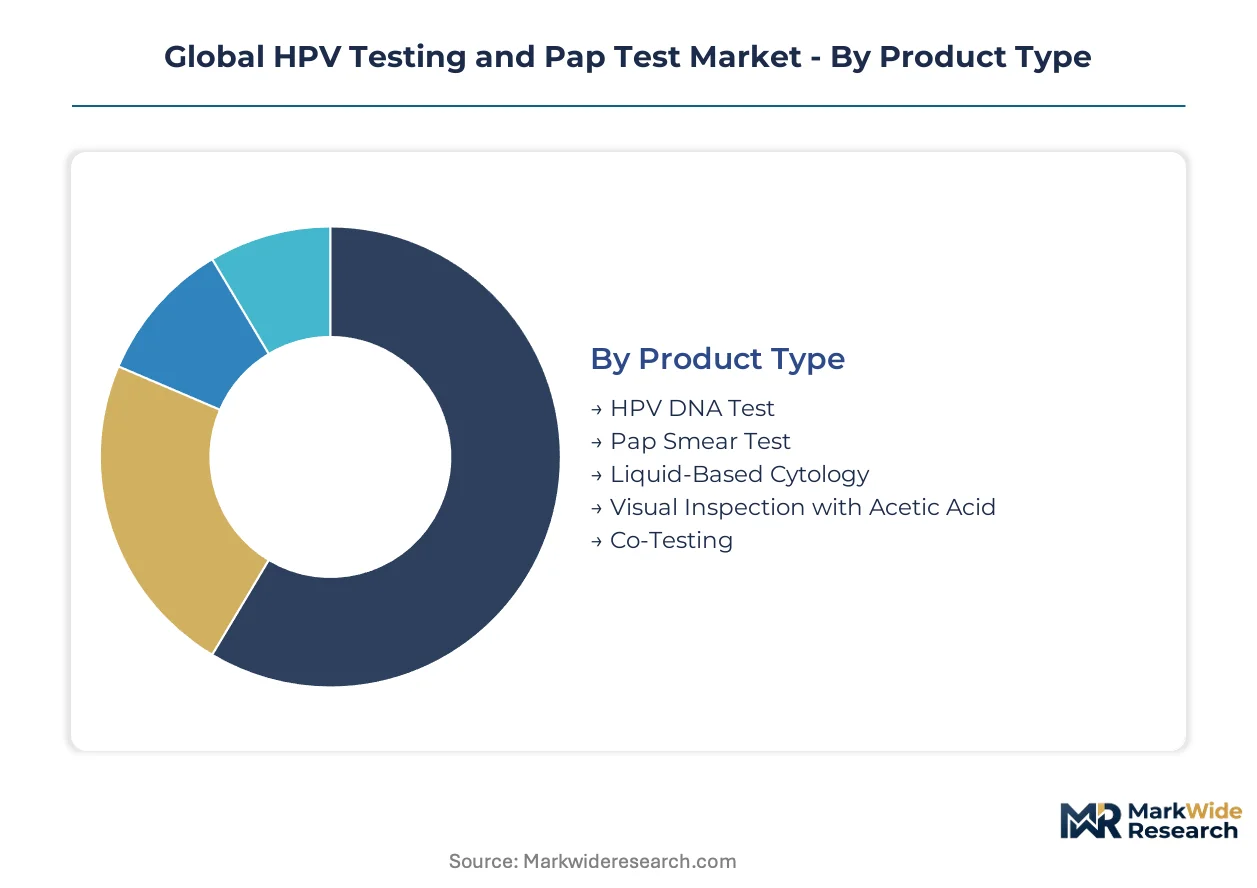
HPV testing and Pap test market segmentation reflects divergent regulatory pathways across molecular and cytology platforms. Product categories align with distinct reimbursement codes and clinical guideline endorsements that determine procurement authority.
Product Type:
FDA premarket notification and EMA In Vitro Diagnostic Regulation create divergent commercialization timelines for molecular versus cytology platforms.
- HPV DNA Test:PCR-based nucleic acid detection targets high-risk genotypes with analytical sensitivity exceeding cytology. WHO elimination strategy directs public procurement toward DNA-first protocols in Brazil and India where ANVISA and CDSCO have accelerated molecular assay approvals.
- Pap Smear Test:Conventional exfoliative cytology requires manual microscopy at 200-400x magnification. Cost-constrained health systems in parts of Africa and Southeast Asia continue deploying this method, constraining molecular conversion timelines.
- Liquid-Based Cytology:Preservative medium enables automated slide preparation and digital imaging.
- Visual Inspection with Acetic Acid:Low-resource screening alternative without laboratory infrastructure requirements.
- Co-Testing:Simultaneous HPV DNA and cytology evaluation endorsed for women over thirty in US and German screening programs.
Established volume favors Pap Smear Test; emerging adoption favors HPV DNA Test.
Technology:
Capital intensity and reagent annuity structures differentiate margin profiles across detection methodologies.
- PCR Amplification:Real-time polymerase chain reaction delivers quantitative viral load measurement with genotype-specific probe chemistry. Reference laboratories in Germany and the United States anchor molecular workflows around this technology due to reimbursement alignment with high-risk HPV 16/18 detection.
- Automated Cytology:Image analysis algorithms classify cellular morphology without continuous pathologist review. Japan's PMDA and South Korea's MFDS are establishing validation frameworks for machine learning-assisted diagnostics, reducing workforce bottlenecks.
- Chemiluminescence:Signal amplification for antibody-based detection in integrated instrument platforms.
- Hybrid Capture:RNA probe hybridization with antibody-mediated signal detection.
- Immunocytochemistry:Protein-level biomarker visualization for lesion triage.
- Fluorescence In Situ Hybridization:Chromosomal aberration detection for integration site mapping.
Platform switching costs favor PCR Amplification; AI-augmented validation favors Automated Cytology.
Application:
Screening intensity and reimbursement frequency vary by clinical indication and patient risk stratification.
- Cervical Cancer Screening:Population-scale prevention programs target asymptomatic women at defined intervals. Brazil's ANVISA-expanded reimbursement redirects public health procurement toward molecular platforms in national screening campaigns.
- Precancerous Lesion Detection:Triage of abnormal cytology results through colposcopy referral algorithms. Extended genotyping panels beyond HPV 16/18 support risk stratification that guides intervention intensity in US integrated delivery networks.
- Infection Monitoring:Viral persistence tracking in high-risk patient cohorts.
- Post-Treatment Follow-Up:Surveillance after excisional or ablative therapy.
- Risk Assessment:Individualized screening interval determination based on combined biomarker profiles.
Population coverage favors Cervical Cancer Screening; margin expansion favors Precancerous Lesion Detection.
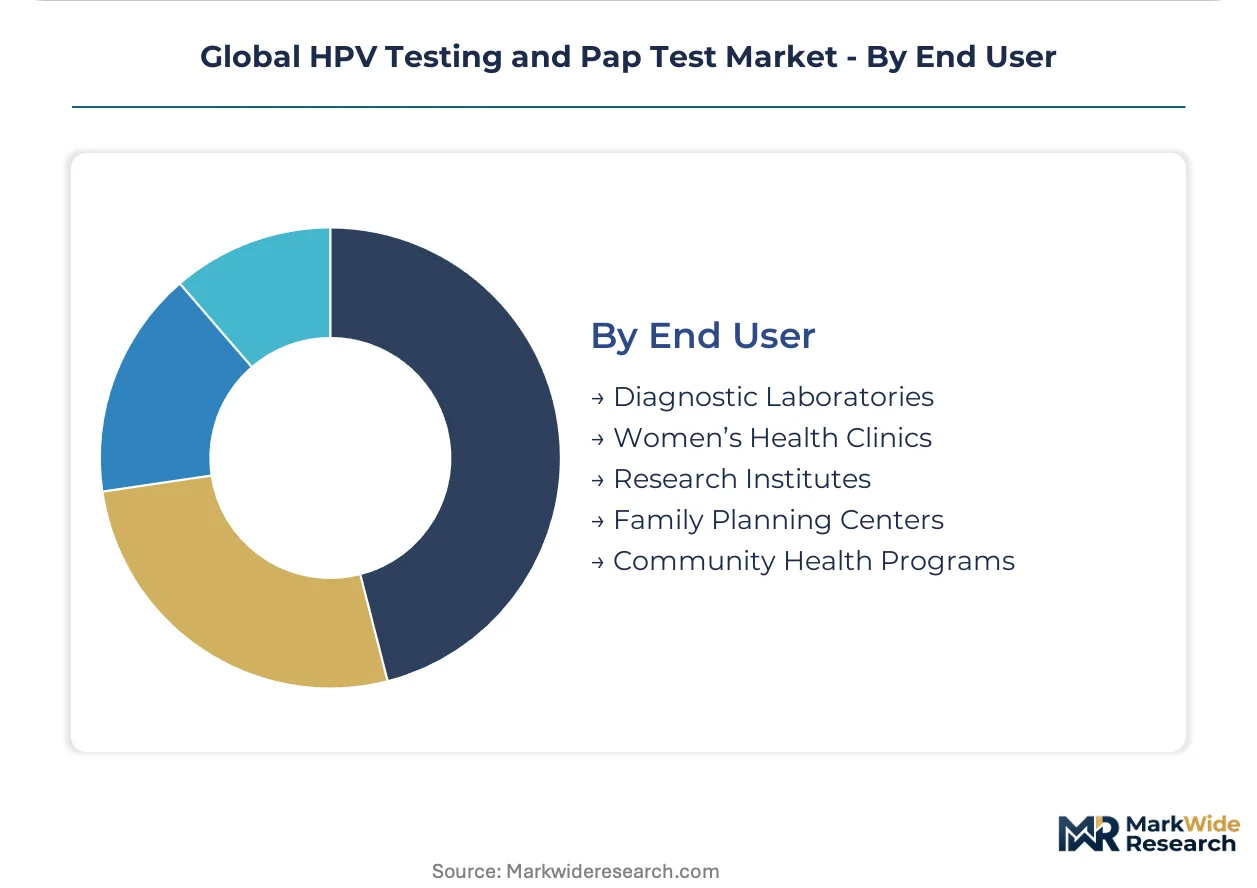
End User:
Procurement authority and testing volume concentrate in centralized laboratory networks versus decentralized point-of-care deployment.
- Diagnostic Laboratories:High-throughput processing with automated specimen handling and laboratory information system integration. US laboratories face HL7 FHIR mapping requirements to legacy cytology reporting modules, extending implementation timelines for hospital networks.
- Women's Health Clinics:Specimen collection with referral to external processing facilities. Self-sampling vaginal collection kits are expanding access beyond clinic-dependent populations in rural India where CDSCO pathways accelerate approvals.
- Research Institutes:Next-generation sequencing adoption for HPV integration site profiling.
- Family Planning Centers:Preventive care integration with contraceptive services.
- Community Health Programs:Decentralized screening models with point-of-care molecular testing.
Revenue concentration favors Diagnostic Laboratories; access expansion favors Community Health Programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic laboratories in the United States, Germany, Brazil, Japan, and India concentrate procurement authority for HPV testing platforms, with each market exhibiting distinct regulatory pathways and infrastructure maturity.
United States
Co-testing protocols are expanding across integrated delivery networks as the FDA tightens premarket notification requirements for molecular screening devices. Laboratories face HL7 FHIR mapping challenges when integrating molecular test results with legacy cytology reporting modules. Boston and San Francisco anchor reference laboratory clusters where next-generation sequencing adoption is compressing screening-to-treatment timelines.
Germany
EMA-aligned national screening registries are accelerating liquid-based cytology conversions while demanding expanded clinical evidence for higher-risk assay reclassifications. Bavaria and North Rhine-Westphalia host Europe's densest concentrations of automated cytology platforms locked into reagent annuity contracts. The country's post-market surveillance infrastructure creates competitive moats for manufacturers with established European trial networks.
Brazil
ANVISA's expanded reimbursement for HPV DNA testing is redirecting public health procurement toward molecular platforms in national screening campaigns. Self-sampling vaginal collection kits are expanding access beyond clinic-dependent populations in rural Minas Gerais and Bahia. São Paulo anchors the country's diagnostic laboratory concentration where subscription-based reagent contracts are displacing per-test purchasing.
Japan
PMDA validation frameworks for machine learning-assisted diagnostics are reducing cytotechnologist workforce bottlenecks in automated cytology review. Tokyo and Osaka metropolitan areas concentrate the country's imaging analysis algorithm development. Extended genotyping panels beyond HPV 16/18 are supporting risk stratification algorithms that guide colposcopy referral intensity.
India
CDSCO pathways are accelerating molecular assay approvals as WHO elimination strategy directs procurement standards for low-resource screening programs. Maharashtra and Karnataka host decentralized community health programs deploying point-of-care molecular testing in pharmacy chains. Cost-constrained systems in northern states continue manual screening persistence, constraining molecular conversion timelines.
Global HPV Testing and Pap Test Market Competitive Landscape
Player mix skews toward diversified diagnostic conglomerates with installed base leverage, creating tiered competition between molecular platform specialists and cytology incumbents. Consolidation pressure favors manufacturers with robust post-market surveillance infrastructure capable of generating EMA-mandated real-world evidence. Three archetypes dominate: instrument-reagent integrators, PCR amplification system anchors, and AI-augmented cytology developers. Competitive moves center on multi-year subscription contracting and geographic licensing partnerships.
Among US-based diversified diagnostics, Hologic, Inc. and Abbott Laboratories exemplify instrument-reagent integration strategies that reduce per-test operational complexity. QIAGEN anchors the PCR amplification tier through reference laboratory workflow dominance. These three entities represent distinct competitive vectors: installed base cytology platform leverage, integrated architecture simplicity, and molecular workflow anchoring respectively.
| Leading Market Players |
|---|
| Hologic, Inc. |
| QIAGEN |
| Abbott Laboratories |
| Becton, Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| Quest Diagnostics Incorporated |
| Seegene Inc. |
| Arbor Vita Corporation |
| Femasys Inc. |
| Others |
Supply & Pricing Matrix
FDA premarket notification pathways and EMA's In Vitro Diagnostic Regulation reclassification simultaneously gate supply qualification and stratify price tiers across molecular and cytology platforms. Manufacturers must generate expanded clinical evidence to access premium reimbursement codes, while laboratories face switching costs that lock in reagent annuity streams and compress margin flexibility.
Pricing Analysis
Multi-year subscription contracts with annual indexation to laboratory throughput volumes dominate procurement between diagnostic manufacturers and integrated delivery networks. Three-tier pricing structure across premium automated platforms, standard PCR systems, and economy manual kits reflects FDA tier certification and service bundling intensity. Pricing pressure stems from Brazil's ANVISA-expanded reimbursement redirecting public budgets toward molecular platforms at contracted rates. Community health programs exhibit highest price sensitivity due to WHO-directed procurement standards, while reference laboratories in Germany and the United States absorb premium positioning through locked reagent contracts.
Supply Chain Analysis
Isothermal amplification cartridge production concentrates in the United States, Germany, and China, creating single-source vulnerability for point-of-care molecular testing expansion. Supply chains draw from specialized polymerase enzyme fermentation, precision injection-molded consumables, and rare-earth fluorescence probe chemistry. Tariff exposure runs through Chinese-sourced optical components and German precision manufacturing equipment. Distribution runs through centralized laboratory networks in São Paulo, Tokyo, and Boston, with decentralized pharmacy chain channels emerging in rural India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are inflecting toward ecosystem lock-in as HL7 FHIR interoperability requirements force laboratory information system consolidation around dominant instrument-reagent architectures.
For Market Incumbents: Compound installed base leverage through backward integration into specimen collection consumables and predictive maintenance software layers. Defend against point-of-care molecular entrants by embedding AI-augmented cytology algorithms that raise switching costs. Prioritize certification investment in Japan's PMDA and South Korea's MFDS validation frameworks to capture workforce-constrained markets. For New Entrants and Emerging Players: Self-sampling kit distribution gaps in rural Brazil and northern India represent underserved channels where incumbents maintain weak direct presence. Pharmacy chain partnerships offer the most penetrable go-to-market angle for cartridge-based isothermal systems, bypassing capital-intensive reference laboratory sales cycles entirely. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across point-of-care molecular sub-segments as semiconductor manufacturing scales drive cartridge cost curves. Long-term viability favors manufacturers with post-market surveillance infrastructure capable of EMA-mandated real-world evidence generation. Watch for CDSCO and ANVISA approval velocity as inflection indicators for emerging market molecular conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| EMA Post-Market Surveillance Infrastructure Buildout | Real-world evidence generation capabilities now determine CE marking continuity for legacy HPV assays. |
| Self-Sampling Kit Regulatory Pathway Expansion | ANVISA and CDSCO accelerated approvals in Brazil and India unlock rural screening access beyond clinic infrastructure. |
| AI-Augmented Cytology Algorithm Validation | PMDA and MFDS frameworks in Japan and South Korea reduce pathologist workforce bottlenecks in automated review. |
| HL7 FHIR Laboratory Information System Integration | Interoperability compliance extends implementation timelines but locks hospital networks into platform ecosystems. |
| Extended Genotyping Panel Development | Beyond HPV 16/18 detection supports risk stratification algorithms guiding colposcopy referral intensity in US networks. |
Research Methodology
Operator-level perspectives from diagnostic laboratory directors, biomedical equipment procurement managers, GPO contracts specialists, and regulatory affairs leads anchored the qualitative base. Secondary validation drew from FDA 510(k) premarket notification databases, EMA In Vitro Diagnostic Regulation guidance documents, WHO cervical cancer elimination strategy procurement standards, and ANVISA reimbursement bulletins. Bottom-up instrument placement modeling and top-down public health budget allocation analysis were triangulated against manufacturer reagent revenue disclosures.
Sensitivity analysis across high, base, and low scenarios tested molecular conversion rate assumptions and cytology platform retirement timelines over the projection horizon. Segmentation dimensions modeled include product type, detection technology, clinical application, end-user facility class, and national regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to historical platform adoption patterns, with inputs from laboratory automation capex cycles and screening program guideline revision schedules.
Forecasts assume regulatory continuity in FDA premarket notification pathways and EMA MDR implementation timelines; material policy shifts would require re-modeling. Specific risk factors include WHO funding volatility for low-income country programs, cytotechnologist training pipeline contraction in the United States and United Kingdom, and reimbursement code fragmentation across US Medicare and Medicaid jurisdictions. Practitioners should keep alternative scenarios live as EMA post-market surveillance requirements and CDSCO approval velocity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Blood Testing Market
Testing Services
Nanoparticle Drug Delivery Size and Zeta Potential Measurement Instruments Market
Testing Services
Influenza Home Testing Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Global Rapid Test Market
Testing Services
Monkeypox Testing Market
Testing Services
Fecal Pancreatic Elastase Testing Market
Testing Services
Sterilization Monitoring Technologies Market
Testing Services
Genetic Toxicology Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Global Cholesterol Testing Products and Services Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Hemotransmissive Infections Testing Market
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
North America Endotoxin and Pyrogen Testing Market