
 Food Cold Chain Market | 2026-2036
Food Cold Chain Market Size, Share, and Industry Trends Forecast 2026-2036
Food Cold Chain Market Analysis
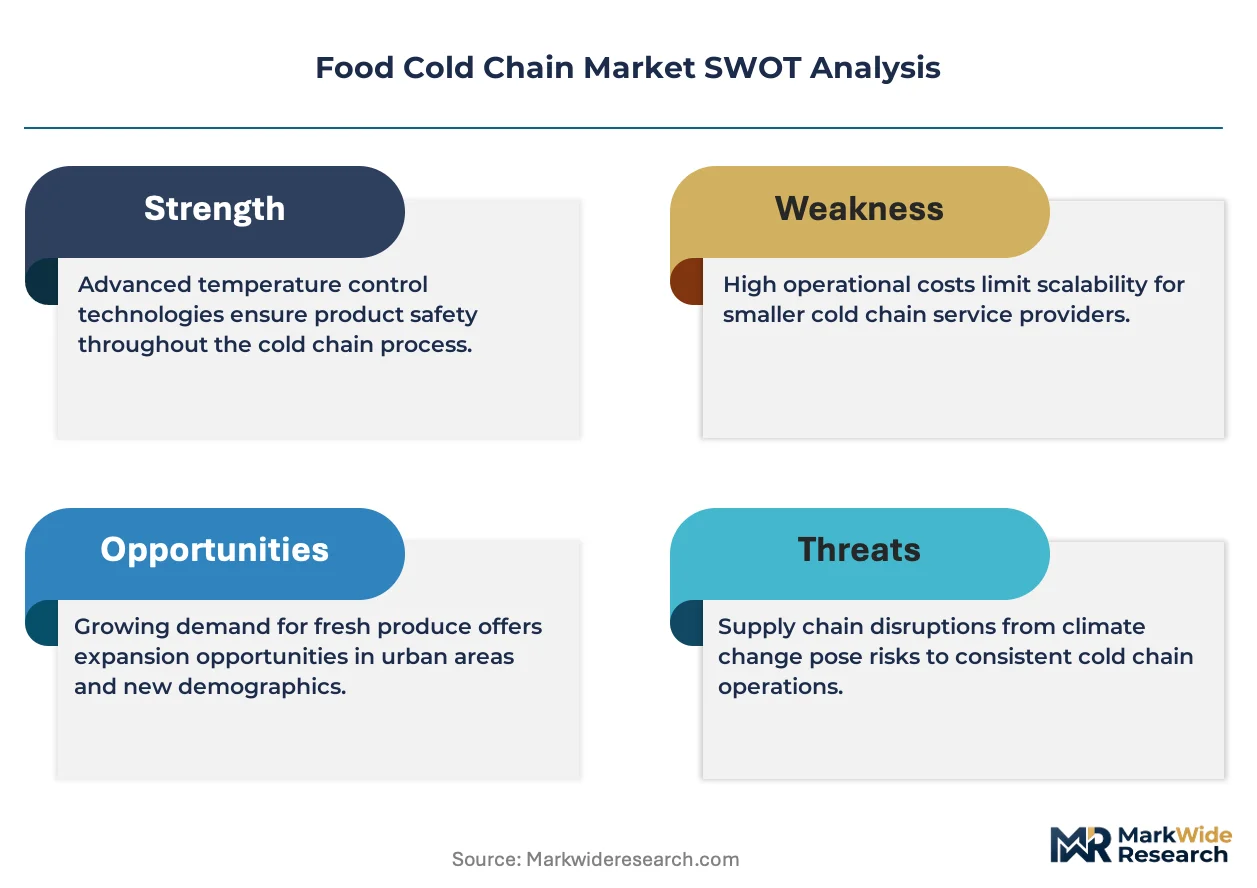
Refrigeration technician availability is collapsing across North America and Europe, constraining warehouse expansion timelines and forcing automation investments. Americold Logistics leverages automated storage and retrieval systems to sustain throughput across its US network. Lineage Logistics anchors its competitive position through AI-driven predictive maintenance platforms that reduce downtime. AGRO Merchants Group specializes in port-adjacent cold storage, controlling access corridors for Latin American produce imports.
The food cold chain encompasses temperature-controlled infrastructure maintaining perishable goods between 0°C and -25°C through refrigerated transport, warehouse storage, and real-time telemetry systems that prevent thermal excursions and microbial proliferation. Frozen foods command the largest product segment by volume, though seafood and dairy products carry higher margin density due to stricter handling protocols and shorter shelf windows. Refrigerated trucks dominate technology deployment in last-mile networks, while cold storage facilities concentrate capital investment near urban consumption clusters and export gateways.
The EPA SNAP program and EU F-Gas Regulation are phasing down hydrofluorocarbon refrigerants, compelling fleet retrofits and warehouse equipment replacement across both jurisdictions. FDA Food Safety Modernization Act traceability mandates are reshaping temperature monitoring requirements, pushing distributors toward integrated digital logging systems. Stakeholders must weigh refrigerant transition timelines against capital replacement cycles as regulatory deadlines tighten compliance windows.
Market Dynamics
The food cold chain sector confronts a structural technician shortage across developed economies, forcing accelerated automation deployment and reshaping competitive economics around labor substitution rather than capacity expansion alone.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon refrigerants is mandating fleet retrofits and warehouse equipment replacement, creating sustained demand for next-generation cooling infrastructure across member states.
- Seafood export corridors:India's dairy and seafood sectors require expanded refrigerated capacity to meet international cold chain standards, driving port-adjacent storage investment and specialized transport networks.
- Pharmaceutical-grade protocols:Restaurant chains and meal-kit providers are adopting temperature precision standards previously reserved for biologics, elevating equipment specifications and service margins.
Market Restraints
- Copper and aluminum input volatility:Refrigeration equipment manufacturing depends on these commodities, with price swings compressing margin predictability for original equipment manufacturers.
- Specialized technician concentration:North America and Europe face collapsing availability of certified refrigeration mechanics, constraining installation and maintenance throughput regardless of capital availability.
- Natural refrigerant safety codes:Ammonia and CO₂ systems face stricter occupancy and ventilation requirements under OSHA and national fire codes, limiting retrofit feasibility in dense urban facilities.
Strategic Opportunities
- India cold storage deficit:The country's horticulture and dairy sectors operate with substantial post-harvest losses, creating white space for integrated pack-house-to-port temperature-controlled infrastructure.
- FDA Food Safety Modernization Act traceability:Mandated digital logging is pushing distributors toward integrated telemetry platforms, opening subscription revenue models for monitoring-as-a-service providers.
- AI-predictive maintenance convergence:Machine learning platforms paired with IoT sensor networks enable downtime prevention, shifting service relationships from reactive repair to uptime guarantees.
Industry Challenges
- Refrigerant transition timeline compression:The EPA SNAP program deadlines force capital replacement cycles that misalign with typical equipment depreciation schedules, straining fleet operator balance sheets.
- Legacy warehouse management system integration:Automated storage and retrieval systems require API connectivity with decades-old inventory platforms, extending deployment timelines and inflating implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Cold Chain Market |
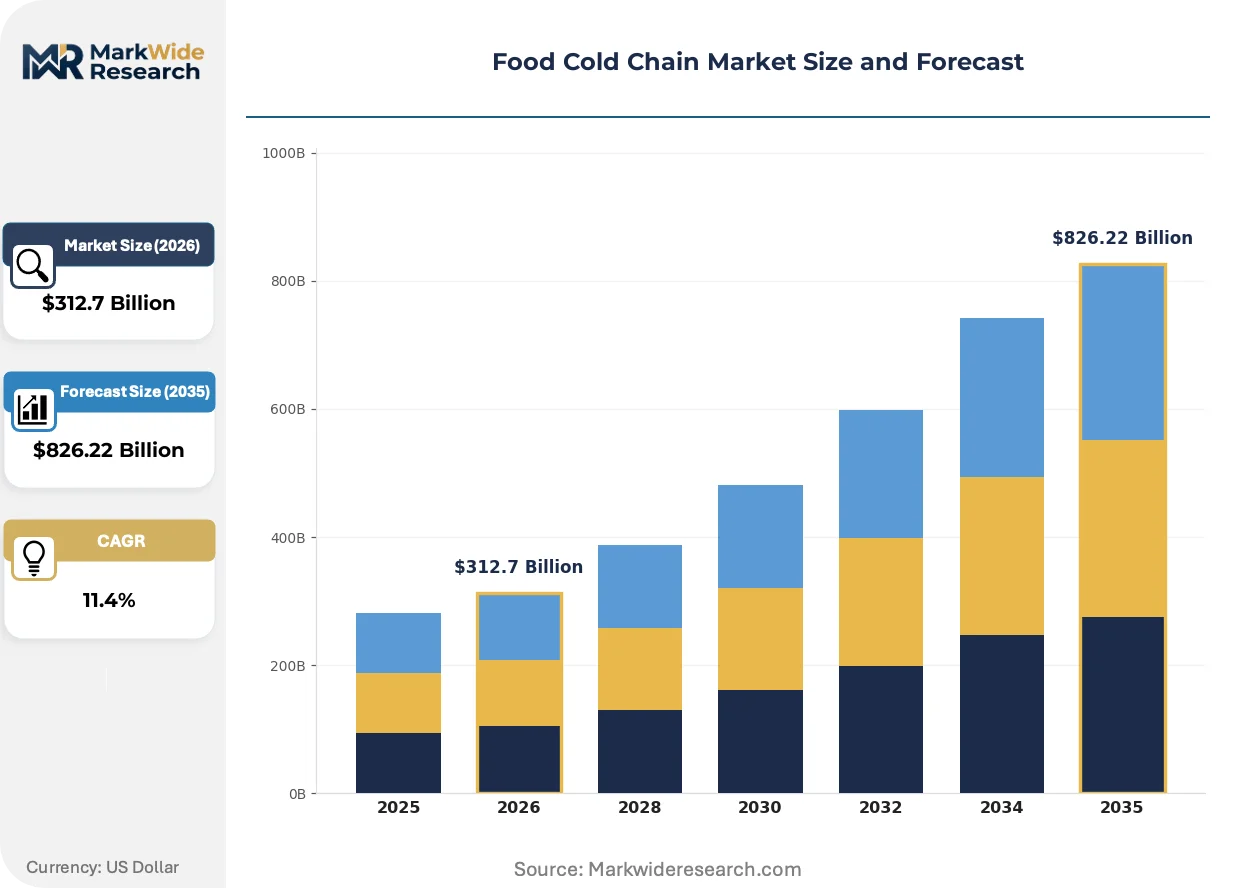
| Market Size in 2026 | $312.7 Billion |
| Market Size in 2035 | $826.22 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Frozen Foods, Dairy Products, Fresh Fruits, Seafood Technology: Refrigerated Trucks, Cold Storage Facilities, Temperature Monitoring, Cryogenic Systems End User: Supermarkets, Restaurants, Food Distributors, Wholesalers Service Type: Transportation, Storage, Packaging, Monitoring Services |
| Companies Covered | Americold Logistics, Lineage Logistics, AGRO Merchants Group, Burris Logistics, Henningsen Cold Storage, United States Cold Storage, Nichirei Corporation, Kloosterboer Group, Preferred Freezer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Cold Chain Market Emerging Trajectories
Digital telemetry and predictive systems are displacing reactive temperature monitoring, while regulatory refrigerant transitions force hardware refresh cycles that favor integrated platform providers over point-solution vendors.
IoT-enabled cold chain monitoring is fragmenting the legacy data logger market. Wireless sensors now transmit real-time temperature, humidity, and location data to cloud dashboards, enabling excursion alerts before product compromise. Small and mid-sized distributors are adopting these platforms fastest, bypassing capital-intensive wired infrastructure. The technology is fragmenting vendor relationships as shippers demand end-to-end visibility spanning multiple handler networks rather than siloed facility-level reporting.
The EU F-Gas Regulation is accelerating natural refrigerant adoption across European cold storage. The phasedown schedule mandates HFC reduction quotas that tighten through 2030, rendering conventional systems economically unviable for new construction. Operators in Germany, the Netherlands, and Denmark are retrofitting ammonia and CO₂ systems most aggressively. Facility operators are responding by consolidating into fewer, larger automated warehouses to amortize transition costs across greater throughput volume.
Direct-to-consumer frozen fulfillment is compressing last-mile delivery windows. Meal-kit subscribers and specialty frozen retailers now expect delivery within 24-48 hours with intact temperature documentation, displacing traditional wholesale distribution through grocery intermediaries. This pattern concentrates demand in suburban fulfillment zones with proximity to both cold storage and parcel carrier hubs. The shift is most visible in the United States and United Kingdom, where subscription frozen food services have achieved household penetration rates that justify dedicated refrigerated last-mile fleets.
Food Cold Chain Market Segmentation
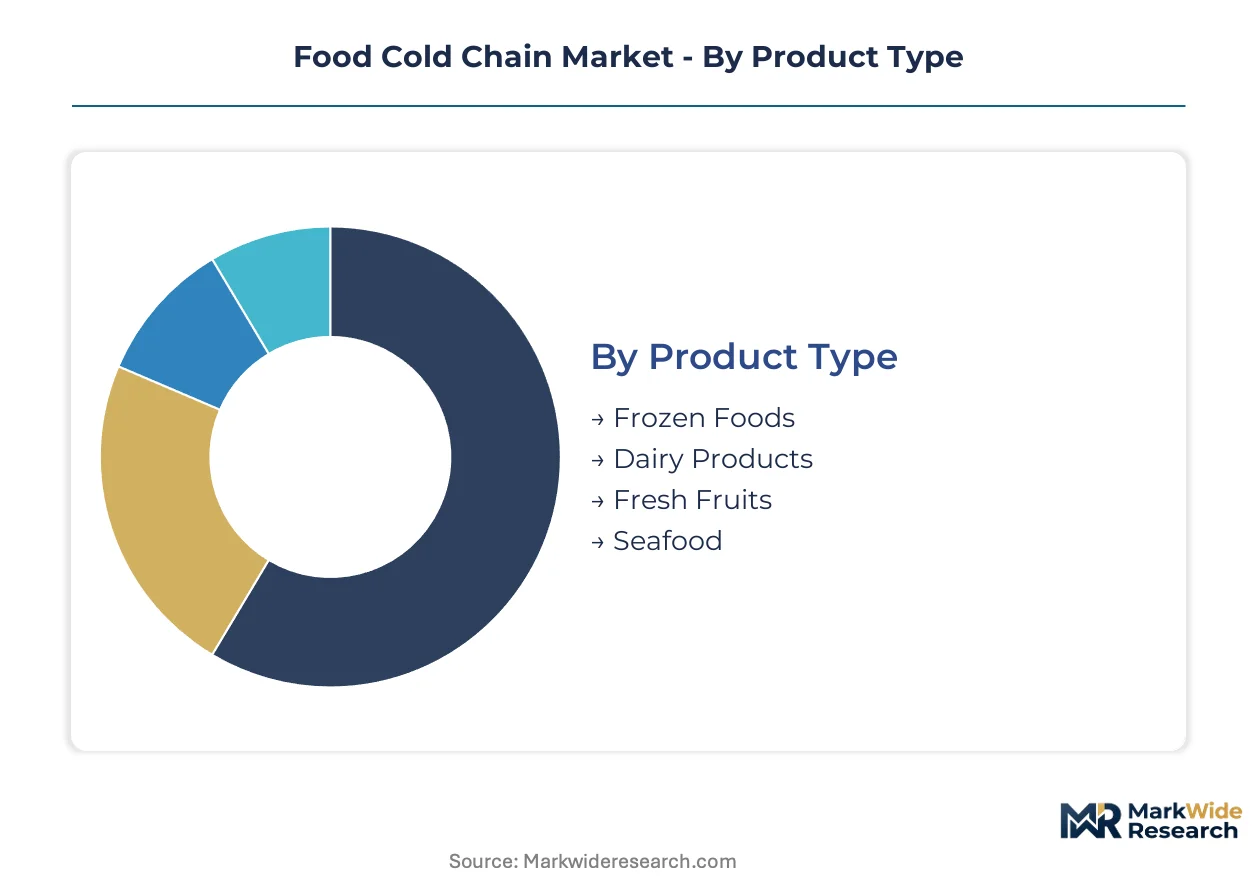
Temperature precision requirements vary dramatically across product categories, forcing infrastructure providers to maintain parallel handling protocols rather than standardized systems. Equipment specifications and service margins diverge based on thermal sensitivity thresholds and regulatory exposure, creating distinct competitive arenas within the broader cold chain ecosystem.
Product Type:
Frozen foods face the strongest substitution pressure from ambient-stable alternatives, while dairy and seafood segments defend their cold chain dependency through irreplaceable freshness requirements.
- Frozen Foods:Processed items maintained at -18°C to -25°C through continuous mechanical refrigeration. Demand concentrates in US and UK suburban fulfillment zones where direct-to-consumer frozen delivery compresses last-mile windows to 24-48 hours.
- Dairy Products:Fluid milk, cheese, and yogurt requiring 0°C to 4°C maintenance with strict FSSAI and FDA compliance on pathogen suppression. India's expanding dairy export corridors drive specialized refrigerated capacity near Mumbai and Chennai ports.
- Fresh Fruits:Horticultural products with respiration-dependent cooling curves and ethylene management protocols.
- Seafood:High-value catch requiring rapid chilling to 0°C and frozen preservation for export-grade tuna and shrimp.
Frozen foods retains volume leadership; seafood holds the steepest expansion curve.
Technology:
Capital deployment intensity separates segments, with infrastructure-heavy categories demanding decade-long amortization against fleet-based alternatives.
- Refrigerated Trucks:Diesel-electric or cryogenic-powered mobile units dominating last-mile networks. EPA SNAP refrigerant mandates force fleet retrofits across US interstate corridors, accelerating natural refrigerant adoption in new vehicle purchases.
- Cold Storage Facilities:Fixed-site ammonia or CO₂-based warehouses with automated storage and retrieval systems. Germany, the Netherlands, and Denmark retrofit most aggressively under EU F-Gas Regulation phasedown schedules.
- Temperature Monitoring:IoT-enabled wireless sensors displacing legacy wired data loggers.
- Cryogenic Systems:Liquid nitrogen or CO₂ injection for ultra-rapid chilling applications.
Cold storage facilities anchor capital investment; refrigerated trucks capture the greatest deployment velocity.
End User:
Traceability liability exposure creates sharp segmentation, with regulatory-facing buyers demanding integrated digital logging versus price-sensitive intermediaries.
- Supermarkets:Multi-temperature distribution centers requiring simultaneous frozen, chilled, and fresh handling. FDA Food Safety Modernization Act mandates push US grocers toward telemetry-integrated supplier networks.
- Restaurants:Quick-service and casual dining chains adopting pharmaceutical-grade temperature precision. Meal-kit penetration in UK and US households elevates equipment specifications for specialty frozen ingredient delivery.
- Food Distributors:Third-party logistics providers managing multi-handler visibility.
- Wholesalers:Volume-focused intermediaries with lower compliance exposure.
Supermarkets dominate procurement scale; restaurants are climbing the fastest on precision requirements.
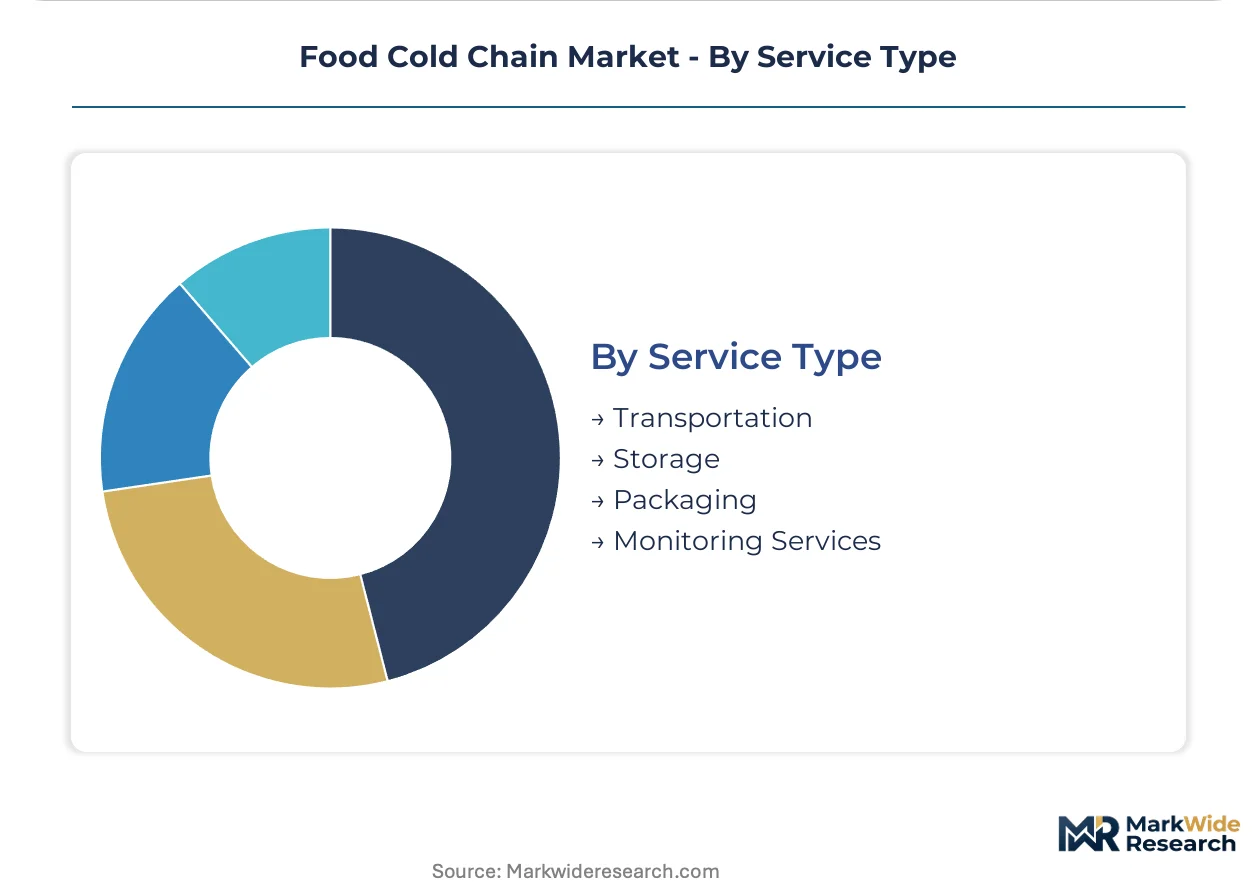
Service Type:
Margin structure varies by asset ownership model, with capital-light monitoring services expanding faster than fixed infrastructure plays.
- Transportation:Refrigerated trucking and intermodal services spanning port-to-warehouse and last-mile legs. India's seafood and dairy export growth drives specialized reefer container demand at Jawaharlal Nehru Port and Visakhapatnam.
- Storage:Warehouse-based inventory holding with temperature zone stratification. Technician shortages across North America constrain expansion timelines regardless of capital availability.
- Packaging:Insulated containers and phase-change materials for temporary thermal protection.
- Monitoring Services:Subscription-based telemetry platforms offering real-time excursion alerts.
Transportation commands the largest revenue pool; monitoring services gain share fastest on recurring revenue models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys cold chain infrastructure primarily for export-grade dairy and seafood, while the United States concentrates capital in suburban fulfillment zones serving direct-to-consumer frozen delivery. Germany and the Netherlands retrofit ammonia systems under regulatory pressure. Japan maintains pharmaceutical-grade precision for domestic food distribution.
United States
Direct-to-consumer frozen fulfillment compresses last-mile delivery windows to 24-48 hours, driving refrigerated fleet investment near parcel carrier hubs. The FDA Food Safety Modernization Act mandates digital traceability for temperature-sensitive shipments. Chicago and Dallas anchor the largest automated cold storage clusters, where Americold Logistics deploys retrieval systems to offset technician shortages.
Germany
EU F-Gas Regulation phasedown quotas render hydrofluorocarbon systems economically unviable for new warehouse construction. Operators retrofit ammonia and CO₂ infrastructure most aggressively here. The Port of Hamburg concentrates specialized reefer container handling for Eastern European produce distribution.
India
Dairy and seafood export corridors require expanded refrigerated capacity to meet international cold chain standards. FSSAI compliance protocols on pathogen suppression elevate equipment specifications for fluid milk handling. Jawaharlal Nehru Port and Visakhapatnam drive specialized reefer demand for shrimp and tuna shipments.
Netherlands
Natural refrigerant adoption accelerates under tightening HFC reduction schedules through 2030. The country consolidates into fewer, larger automated warehouses to amortize transition costs. Rotterdam's port-adjacent cold storage controls access corridors for Latin American produce imports entering European distribution networks.
Japan
Domestic food distribution maintains pharmaceutical-grade temperature precision standards previously reserved for biologics. METI efficiency regulations push equipment refresh cycles toward integrated telemetry platforms. Tokyo-Osaka corridor demand concentrates on multi-temperature handling for convenience store supply chains.
Food Cold Chain Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale-driven operators controlling port-adjacent corridors while regional players defend niche temperature zones. The structure rewards asset-heavy balance sheets capable of absorbing refrigerant transition costs and automation capex. Two archetypes dominate: integrated network operators with national footprint coverage, and port-centric specialists capturing import-export arbitrage. Competitive moves concentrate on automated warehouse deployment and predictive maintenance platform development.
Within the integrated network tier, Americold Logistics and Lineage Logistics exemplify scale-driven automation strategies, while AGRO Merchants Group occupies a position as a port-centric specialist. These three entities represent divergent capital deployment models: national refrigerated warehouse networks, AI-driven predictive maintenance platforms, and corridor-control positioning for produce import handling.
| Leading Market Players |
|---|
| Americold Logistics |
| Lineage Logistics |
| AGRO Merchants Group |
| Burris Logistics |
| Henningsen Cold Storage |
| United States Cold Storage |
| Nichirei Corporation |
| Kloosterboer Group |
| Preferred Freezer |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with cold storage operators lock in refrigerated pallet positions and freeze price visibility for food distributors navigating EPA SNAP refrigerant transition timelines. These agreements tether buyer procurement to specific facility locations while insulating against spot-rate volatility during peak harvest windows.
Pricing Analysis
Contract-based long-term offtake dominates cold storage procurement, with price differentiation resting on certification grade and geographic delivery cost. FDA Food Safety Modernization Act traceability tiers command premium positioning against standard handling protocols. Pricing pressure stems from copper and aluminum input volatility compressing equipment manufacturer margins. Small regional distributors exhibit highest price sensitivity; pharmaceutical-grade meal-kit providers show lowest.
Supply Chain Analysis
China and the United States anchor refrigeration equipment manufacturing, while India and Vietnam concentrate insulated packaging production. Supply chains draw from copper tubing, aluminum coil, and compressor assemblies as critical inputs. Single-source vulnerability runs through Taiwanese semiconductor components controlling IoT sensor networks. Distribution runs through port-adjacent cold storage clusters feeding last-mile refrigerated trucking networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry platform interoperability is shifting competitive advantage toward integrated data-layer providers, as FDA traceability mandates force API connectivity across fragmented handler networks.
For Market Incumbents: Shield automated warehouse investments through ammonia retrofit consolidation under EU F-Gas Regulation deadlines. Prioritize technician training partnerships with community colleges to offset labor scarcity constraining expansion timelines. Defend corridor control at Jawaharlal Nehru Port and Rotterdam against emerging port-centric specialists. For New Entrants and Emerging Players: Differentiate on AI-predictive maintenance subscription models that convert reactive repair relationships into uptime guarantees. Target India's horticulture post-harvest loss corridor with pack-house-to-port integrated infrastructure. Pursue white-label telemetry partnerships with mid-sized distributors bypassing capital-intensive wired systems. For Investors and Strategic Acquirers: Port-centric cold storage specialists with Latin American produce corridor access represent the most defensible acquisition archetype. Long-term viability hinges on natural refrigerant transition completion and automation deployment density. Monitor EPA SNAP enforcement acceleration as inflection signal for stranded HFC asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Warehouse Deployment | Americold Logistics offsets technician shortages through retrieval systems sustaining throughput across US networks. |
| AI-Predictive Maintenance Platform | Lineage Logistics reduces downtime through machine learning models paired with IoT sensor networks. |
| Natural Refrigerant Retrofit | German and Dutch operators consolidate into fewer, larger facilities to amortize EU F-Gas Regulation transition costs. |
| Port-Adjacent Corridor Control | AGRO Merchants Group captures Latin American produce import arbitrage through specialized reefer handling. |
| Telemetry-as-a-Service Launch | Wireless sensor platforms fragment legacy data logger markets among small and mid-sized distributors. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs trade databases, and EPA regulatory dockets to validate market sizing and competitive positioning claims. Interviews with cold storage facility operators, refrigerated fleet managers, refrigeration equipment procurement leads, and food safety compliance officers informed operational constraints and technology adoption patterns. Bottom-up capacity utilization data triangulates against top-down trade flow analysis across dairy, seafood, and frozen food corridors.
Segmentation dimensions modeled span product temperature sensitivity, equipment technology type, end-user traceability liability exposure, and service asset ownership structure across the projection horizon. CAGRs derive from installed base replacement cycles, regulatory deadline compression effects, and export corridor growth trajectories. Forecast inputs incorporate EU F-Gas Regulation phasedown schedules and FDA Food Safety Modernization Act implementation timelines as structural demand shapers.
Material uncertainties — refrigerant transition cost overruns, technician availability collapses, and copper price spikes — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and automation deployment feasibility. Recalibration cycles align with material shifts in EPA SNAP rulemaking and EU HFC quota allocations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cold Chain Packaging
Cryogenic Boxes Market
Cold Chain Packaging
Cryogenic Capsules Market
Cold Chain Packaging
North America Passive Temperature Controlled Packaging Market
Cold Chain Packaging
Europe Healthcare Cold Chain Logistics Market
Cold Chain Packaging
Insulated Coolers Market
Cold Chain Packaging
Cold Chain Equipment Market
Cold Chain Packaging
Cold Chain Integrity and Shock Monitoring Test Devices Market
Cold Chain Packaging
North America Food Cold Chain Logistics Market
Cold Chain Packaging
Cold Chain Temperature Monitoring Market
Cold Chain Packaging
Cold Storage Insulated Market
Cold Chain Packaging
Ice Boxes Market
Cold Chain Packaging
Latin America Pharmaceutical Cold Chain Logistics Market
Cold Chain Packaging
Biopharma Cold Chain Packaging Market
Cold Chain Packaging
Europe Cold Chain Tracking and Monitoring Market
Cold Chain Packaging
China Cold Chain Market
Cold Chain Packaging
Cold Chain Packaging Market