
 Biomass Molding Fuel Market | 2026-2036
Biomass Molding Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
Biomass Molding Fuel Market Intelligence
The EU Green Deal is decoupling carbon-intensive fuel economics from biomass supply contracts across European power markets. Enviva Holdings leverages transatlantic shipping infrastructure to sustain pellet deliveries to Drax Group's converted generating stations. RWE AG anchors continental demand through industrial heat contracts, while Green Circle Bio Energy differentiates via southeastern US feedstock proximity.
Biomass molding fuel comprises densified organic material—typically compressed wood residues or agricultural waste into standardized pellets, briquettes, or logs—with calorific values ranging from 4.5 to 5.5 kWh per kilogram depending on feedstock and compression ratio. Pellet formats dominate industrial procurement due to automated handling compatibility, while briquette demand concentrates in residential heating across Central European markets. Wood residues anchor feedstock supply through sawmill waste streams, though energy crops represent the fastest-expanding input category as dedicated cultivation spreads.
EPA emissions standards in the United States, EU F-Gas Regulation phase-down schedules, and Japan's METI biomass feed-in tariff collectively shape product certification requirements and cross-border trade access. EMA sustainability criteria and REACH chemical compliance further constrain feedstock sourcing for European industrial buyers. Stakeholders must monitor regulatory tightening on lifecycle carbon accounting, as border-adjusted sustainability verification threatens to reshape competitive positioning among feedstock suppliers and fuel processors.
Market Dynamics
EU coal phase-out mandates under the Green Deal are forcing power utilities into accelerated fuel-switching timelines, compressing procurement cycles for densified biomass and reshaping transatlantic supply contract structures.
Growth Catalysts
- EU F-Gas Regulation phase-down:Industrial boiler operators face escalating carbon costs that make biomass firing systems economically superior to natural gas alternatives in German and Polish manufacturing corridors.
- Wood pellet automated handling:Power generation utilities prioritize pellet formats compatible with existing coal-handling infrastructure, reducing conversion capital requirements for Drax Group and similar operators.
- Japan METI biomass feed-in tariff:Guaranteed power purchase agreements spanning 20 years attract project finance for dedicated pellet import terminals in Kansai and Kyushu industrial zones.
Market Restraints
- Feedstock cost volatility:Sawmill residue prices fluctuate with North American housing construction cycles, squeezing processor margins when lumber demand spikes.
- Southeastern US supply concentration:Green Circle Bio Energy and Enviva Holdings control majority Atlantic port capacity, creating single-source risk for European buyers.
- Energy crop cultivation lag:Dedicated biomass crops require 3-5 year establishment periods before commercial harvest, limiting near-term feedstock diversification.
Strategic Opportunities
- Italian district heating expansion:Municipal utilities in Lombardy and Veneto seek briquette suppliers for residential heat networks underserved by natural gas infrastructure.
- Carbon border adjustment mechanism:EU CBAM verification requirements favor certified sustainable biomass over uncertified alternatives, rewarding early compliance investments.
- Torrefaction-plant co-location:Combining torrefaction units with existing pellet mills enables hydrophobic fuel production with 25% higher energy density for maritime shipping.
Industry Challenges
- Sustainability certification backlog:EMA and SBP scheme auditors face 6-9 month queue times, delaying contract execution for new market entrants.
- Legacy coal boiler retrofit complexity:Polish and Czech power stations require customized burner modifications and fuel-handling system overhauls that extend commissioning timelines.
- Moisture content standardization gaps:Inconsistent ISO 17225 enforcement across Baltic and Black Sea ports creates quality disputes and rejection penalties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biomass Molding Fuel Market |
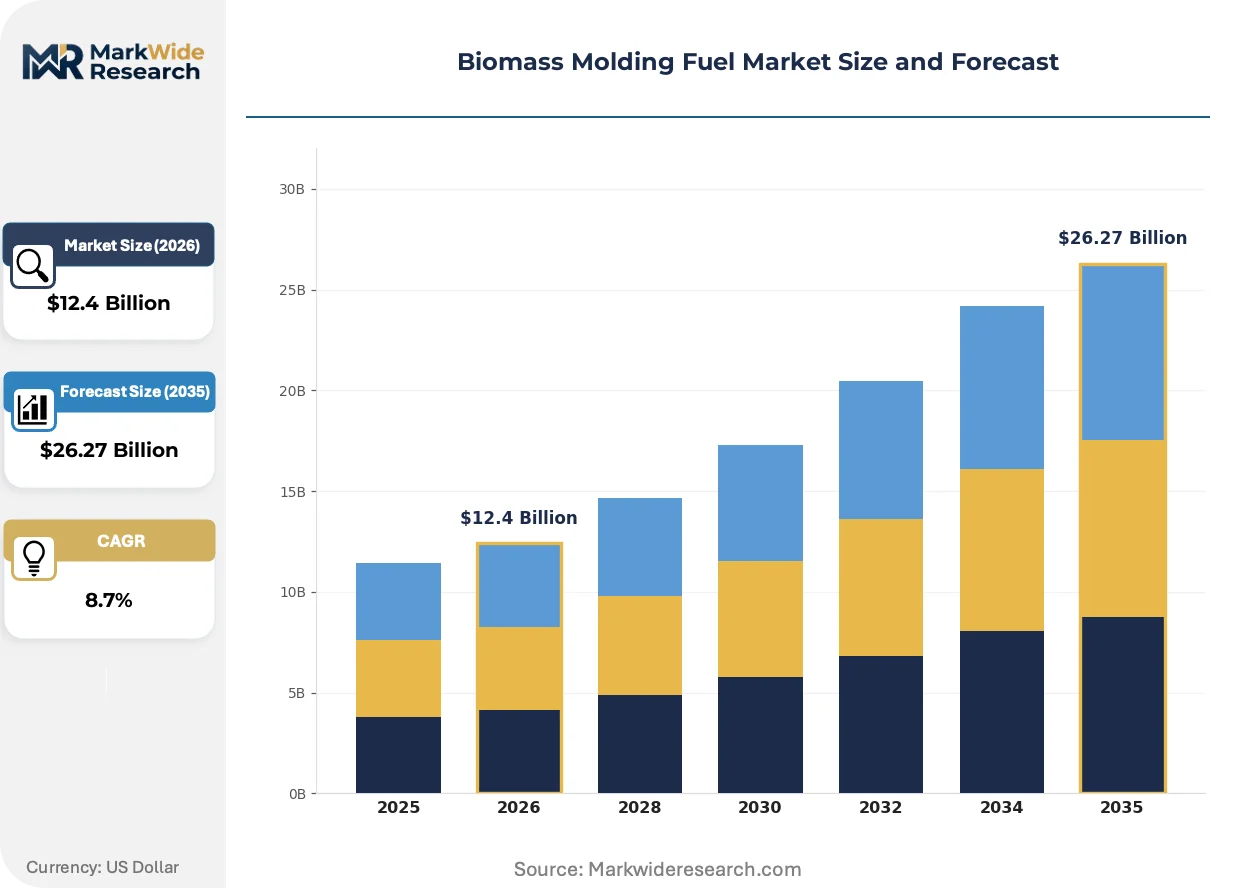
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Briquettes, Logs, Pinches Feedstock: Wood Residues, Agricultural Waste, Energy Crops, Others End User: Residential Heating, Industrial Applications, Power Generation, Commercial Use Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Distributors |
| Companies Covered | Enviva Holdings, Drax Group, Green Circle Bio Energy, Pinnacle Renewable Energy, Pacific BioEnergy, RWE AG, Fram Renewable, Billington Bioenergy, Austrian Bioenergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biomass Molding Fuel Market Strategic Shifts & Innovations
Torrefaction technology is moving from pilot demonstration to commercial scale, while regulatory carbon accounting tightens and procurement models favor long-term offtake over spot purchasing.
Steam explosion pretreatment is integrating lignocellulosic agricultural residues into pellet feedstock streams previously limited to wood waste. Danish district heating cooperatives are adopting this processed straw input to meet renewable heat mandates. The technology is integrating formerly non-combustible materials into standardized fuel specifications, expanding addressable feedstock pools beyond traditional sawmill channels.
EU Green Deal lifecycle carbon accounting rules now require transport emissions disclosure for biomass imports. Industrial buyers must document shipborne carbon from US Gulf and Baltic ports to receiving terminals. German utilities are responding by negotiating dedicated vessel charters and rail-last-mile contracts to minimize reported supply chain emissions.
Power purchase agreements are displacing annual procurement tenders as the dominant contracting mechanism. Drax Group and RWE AG now structure 10-15 year pellet supply contracts with price escalation clauses tied to EU carbon allowance markets. This shift concentrates procurement authority among integrated generators with balance-sheet capacity to underwrite long-dated fuel commitments.
Biomass Molding Fuel Market Segmentation
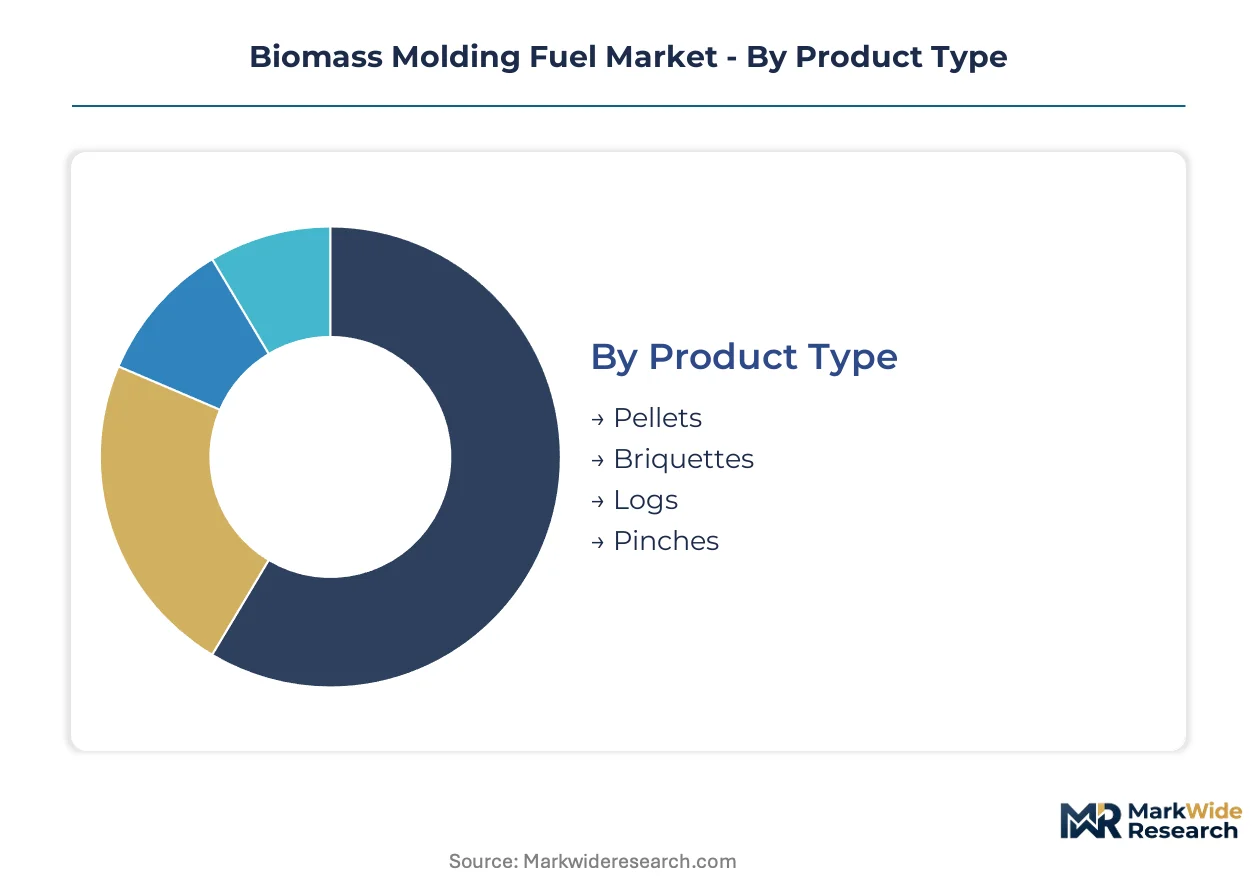
Segmentation in biomass molding fuel reveals how physical form, feedstock origin, and delivery channel each command distinct margin structures and procurement protocols. Understanding these divides exposes where capital efficiency concentrates versus where operational complexity inflates costs.
Product Type:
Pellets capture volume leadership through automated handling compatibility, while briquettes and logs occupy premium niches requiring manual or semi-automated feed systems.
- Pellets:Cylindrical densified fuel with 6-8mm diameter and standardized 15-30mm length, optimized for pneumatic conveying and automated combustion control. Drax Group and RWE AG procurement concentrates demand in this format for converted coal stations. The ISO 17225-2 specification governs quality, with moisture content below 10% enabling long-distance maritime shipment without degradation.
- Briquettes:Block-form fuel produced under higher compression ratios, typically 50-100mm diameter, suited to residential stoves and small commercial boilers. Demand clusters in Italian district heating networks and Central European municipal heat cooperatives where manual loading remains economically viable.
- Logs:Split or whole wood pieces for traditional fireplace and stove combustion, retaining natural density without mechanical compression. German and Austrian alpine regions sustain this segment through cultural heating practices and tourism accommodation.
- Pinches:Small-format compressed fragments for specialized industrial burners requiring rapid ignition characteristics. Japanese METI-subsidized biomass power plants represent the primary offtake channel.
Mature deployment sits with pellets. Newer deployment is concentrated in pinches.
Feedstock:
Cost tier differentiation separates residue-based inputs from cultivated energy crops, with agricultural waste occupying a volatile middle position.
- Wood Residues:Sawmill chips, sawdust, and bark from lumber processing, currently anchoring supply through established collection infrastructure. North American housing construction cycles directly impact availability and pricing, creating margin squeeze during building booms.
- Agricultural Waste:Straw, rice husks, and corn stover requiring steam explosion or torrefaction pretreatment to achieve combustion stability. Danish district heating cooperatives are adopting this processed straw input to meet renewable heat mandates.
- Energy Crops:Dedicated cultivation of miscanthus, switchgrass, or short-rotation coppice willow, representing the steepest expansion trajectory as arable land repurposing accelerates. Establishment requires 3-5 year lead times before commercial harvest.
- Others:Food processing byproducts, paper mill sludge, and construction wood waste diverted from landfill streams. EU waste hierarchy regulations are expanding permissible feedstock categories.
Established supply chains favor wood residues. Capital deployment is accelerating into energy crops.
End User:
Application scale determines procurement sophistication, from individual household purchasing to utility-grade long-term offtake contracting.
- Residential Heating:Individual household consumption through stove and small boiler systems, typically purchasing 1-2 ton annual quantities. Italian and Polish markets concentrate demand where natural gas infrastructure remains underdeveloped.
- Industrial Applications:Manufacturing process heat for food processing, textile dyeing, and chemical production. German industrial corridors in North Rhine-Westphalia and Bavaria anchor demand as EU F-Gas Regulation carbon costs escalate.
- Power Generation:Utility-scale electricity production through dedicated biomass plants or coal-to-biomass conversions. UK and Japanese markets structure 10-15 year supply contracts with price escalation clauses tied to carbon allowance markets.
- Commercial Use:Hotels, hospitals, and educational institutions operating medium-capacity boilers. Procurement often runs through energy service companies rather than direct fuel purchasing.
Contract maturity sits with power generation. Procurement innovation is concentrated in commercial use.
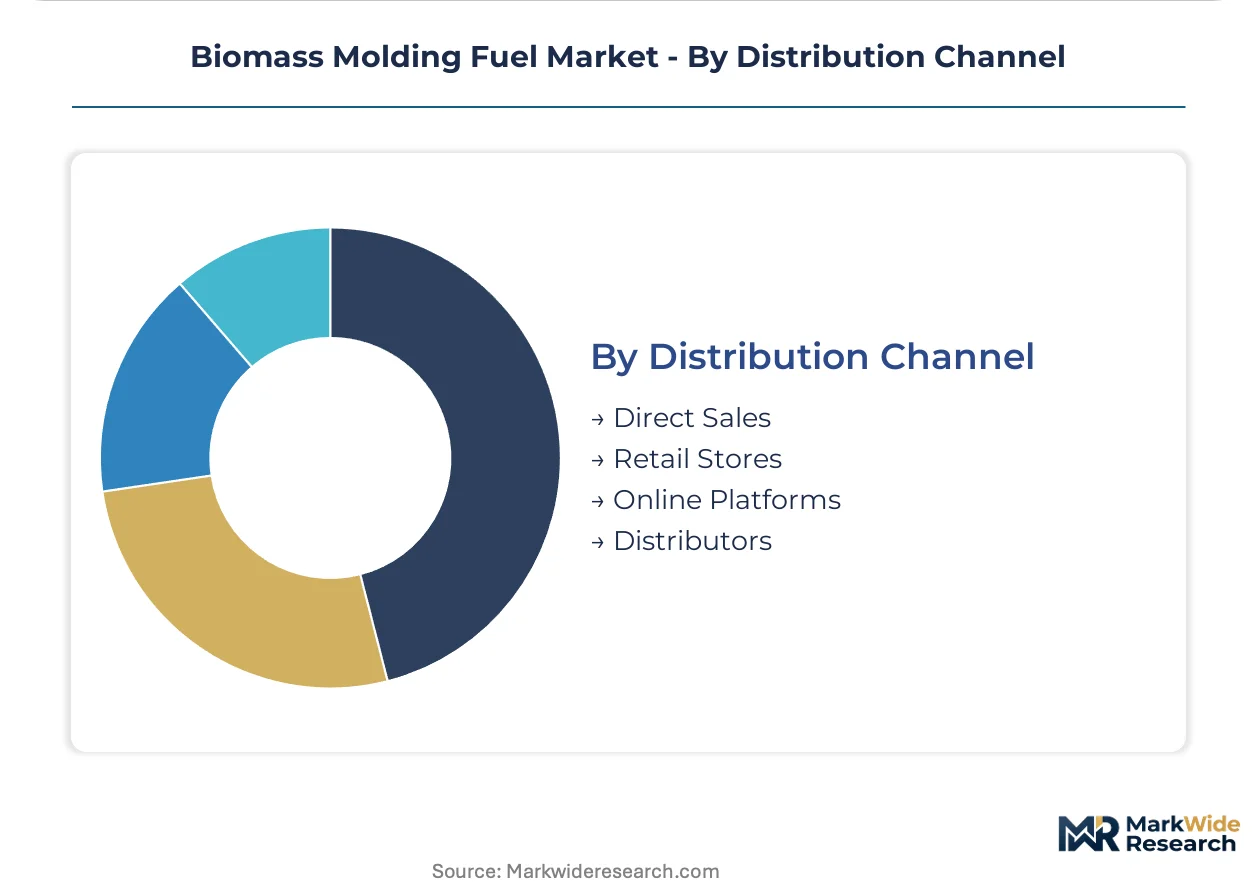
Distribution Channel:
Customer type and purchase scale dictate channel selection, with direct sales capturing bulk utility contracts while fragmented residential demand flows through retail intermediation.
- Direct Sales:Producer-to-consumer contracts for volumes exceeding 1,000 tons annually, eliminating intermediary margins. Drax Group and RWE AG procurement teams negotiate these arrangements directly with Enviva Holdings and Green Circle Bio Energy.
- Retail Stores:Agricultural supply cooperatives and building material chains serving residential and small commercial buyers. German Raiffeisen and French Terrena cooperatives dominate this channel in their respective markets.
- Online Platforms:Digital marketplaces emerging for spot purchasing and price discovery, particularly in Nordic markets with high digital infrastructure penetration. Quality verification remains a friction point.
- Distributors:Regional wholesalers consolidating fragmented demand and managing last-mile logistics. Baltic and Black Sea port operators increasingly integrate distribution with bulk handling infrastructure.
Volume concentration sits with direct sales. Platform development is accelerating in online channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Southeastern US special economic zones concentrating pellet export infrastructure anchor transatlantic supply chains, while EU border carbon adjustments reshape procurement geography across industrial heating corridors.
Germany
Industrial boiler conversions in North Rhine-Westphalia and Bavaria drive densified fuel procurement as EU F-Gas Regulation carbon costs escalate. The national climate protection program mandates 65% renewable heat by 2030. Munich and Stuttgart manufacturing clusters now structure 10-year briquette supply contracts for process heat applications.
United States
Southeastern timber belts and Atlantic port infrastructure concentrate wood pellet production capacity under EPA emissions compliance frameworks. The Inflation Reduction Act bioenergy tax credits sustain export-oriented facility investments. Georgia and Alabama coastal terminals now supply converted UK power stations through dedicated vessel charters.
Japan
Utility-scale biomass power development in Kansai and Kyushu industrial zones accelerates pellet import terminal construction under METI feed-in tariff guarantees. The 20-year power purchase agreements attract project finance for dedicated handling infrastructure. Osaka Bay and Kitakyushu port operators now integrate storage with rail-last-mile distribution networks.
Poland
Coal-dependent district heating systems in Silesia and Masovia face accelerated fuel-switching timelines under EU Green Deal phase-out mandates. The national energy policy prioritizes biomass conversion for municipal heat networks. Warsaw and Łódź utilities now negotiate long-term pellet contracts to replace lignite-fired boiler capacity.
Italy
Natural gas infrastructure gaps in Lombardy and Veneto sustain briquette demand for residential heating cooperatives under EU renewable energy directive compliance. The national green recovery plan funds municipal heat network expansion. Alpine tourism accommodation clusters in South Tyrol now specify certified sustainable fuel for district heating systems.
Biomass Molding Fuel Market Key Industry Players
Southeastern US producers anchor one tier; European utilities and integrated generators hold procurement authority through long-dated offtake structures. The market exhibits tiered concentration with transatlantic shipping infrastructure controlling access to premium demand pockets. Three archetypes dominate: port-proximate pellet exporters, utility-captive supply arrangements, and agricultural residue processors. Capacity expansion and sustainability certification investments constitute the dominant competitive vectors as border-adjusted carbon accounting tightens.
Within the port-proximate exporter tier, Enviva Holdings and Green Circle Bio Energy represent the infrastructure-anchored archetype controlling Atlantic terminal capacity. Drax Group occupies a position exemplifying the utility-integrated procurement model structuring decade-long supply commitments. These named entities illustrate how geographic concentration in feedstock basins and shipping infrastructure shapes competitive positioning without requiring operational specificity about individual facilities.
| Leading Market Players |
|---|
| Enviva Holdings |
| Drax Group |
| Green Circle Bio Energy |
| Pinnacle Renewable Energy |
| Pacific BioEnergy |
| RWE AG |
| Fram Renewable |
| Billington Bioenergy |
| Austrian Bioenergy |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between SBP-certified premium pellets and uncertified commodity grades manifests in both contract pricing premiums and supply chain routing decisions. Industrial buyers in Germany and Japan pay escalation-adjusted rates for verified sustainable supply chains while spot-market procurement concentrates in Baltic port arbitrage.
Pricing Analysis
Short-lead-time procurement commands premium pricing as utilities facing accelerated coal phase-out timelines absorb rush-delivery surcharges. Contract-based long-term offtake dominates, with price differentiation driven by SBP certification tier and volume scale commitments. Cost compression in commodity-grade spot markets is intensifying because sawmill residue availability fluctuates with North American housing cycles. Municipal district heating cooperatives exhibit highest price sensitivity, while integrated power generators with balance-sheet capacity show lowest sensitivity due to carbon-allowance-hedged procurement.
Supply Chain Analysis
Maritime freight costs from US Gulf and Atlantic ports to European terminals constitute 15-25% of delivered fuel cost, compressing processor margins during vessel charter spikes. Supply concentrates in the United States, Canada, and Baltic states, with raw material dependencies on sawmill residues, agricultural straw, and emerging energy crop cultivation. Single-source vulnerability runs through southeastern US port capacity controlled by dominant exporters. Distribution runs through direct sales for utility volumes exceeding 1,000 tons annually, while fragmented residential demand flows through agricultural cooperative retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Torrefaction technology is displacing conventional pellet production as the industry transitions toward hydrophobic, higher-density fuel formats. Legacy coal-handling infrastructure retrofits face compressed commissioning timelines under EU Green Deal mandates.
For Market Incumbents: Extend sustainability certification coverage to capture EU CBAM-compliant premium pricing before verification backlogs widen. Secure backward integration into dedicated energy crop cultivation to reduce sawmill residue price volatility exposure. Enviva Holdings and Green Circle Bio Energy demonstrate how Atlantic port capacity control creates defensive moats against new export-oriented entrants.
For New Entrants and Emerging Players: Enter via Italian district heating cooperatives in Lombardy and Veneto where natural gas infrastructure gaps sustain briquette demand underserved by transatlantic pellet suppliers. Agricultural residue processing using steam explosion pretreatment offers lowest capital barriers compared to greenfield pellet mill construction. Partner with Danish district heating networks to validate processed straw fuel specifications before scaling.
For Investors and Strategic Acquirers: Re-rating potential sits with torrefaction-plant operators given EU lifecycle carbon accounting rules that reward hydrophobic fuel with 25% higher energy density and reduced maritime shipping emissions. Long-term viability favors integrated generators with captive offtake structures and balance-sheet capacity to underwrite decade-long supply commitments. Watch for sustainability certification queue times compressing below six months as an inflection signal for new entrant viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Torrefaction Capacity Buildout | Enables hydrophobic fuel production meeting EU maritime shipping efficiency standards. |
| Long-term Supply Agreement | Drax Group and RWE AG structure 10-15 year contracts with carbon-allowance price escalation clauses. |
| Backward Integration into Energy Crops | Reduces sawmill residue price volatility exposure through dedicated miscanthus and switchgrass cultivation. |
| Green Certification Program | SBP and EMA scheme compliance unlocks EU CBAM-advantaged procurement from industrial buyers. |
| Joint Venture with Port Operators | Osaka Bay and Kitakyushu terminals integrate storage with rail-last-mile distribution under METI tariff guarantees. |
Research Approach
Trade databases, customs records, and EIA biomass fuel reports formed the secondary backbone, cross-referenced with primary interviews involving utility procurement officers, pellet mill operations managers, district heating cooperative directors, and sustainability certification auditors. Bottom-up capacity assessments across US Gulf and Atlantic port facilities combined with top-down demand modeling from EU Green Deal implementation timelines. Triangulation validated volume and price assumptions against FERC filings and IEA bioenergy statistics.
Historical trendline analysis of wood pellet export volumes from Georgia and Alabama terminals established baseline growth patterns across the projection horizon. Segmentation modeling incorporated fuel format, feedstock origin, end-use application, and distribution channel dimensions. CAGRs derived from regression analysis of contract pricing escalation clauses tied to EU carbon allowance markets, with torrefaction adoption curves and energy crop cultivation lag periods as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU CBAM enforcement delays or North American housing construction boom-bust cycles. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Europe Biogas Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Biopower Market
Bioenergy
Biogas Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Organic Biogas Market
Bioenergy
Bioenergy Market
Bioenergy
Biopellets Energy Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Bio CHP Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Europe Bioenergy Market