
 Biopower Market | 2026-2036
Biopower Market Size, Share, and Industry Trends Forecast 2026-2036
Biopower Market Analysis
Advanced thermal gasification is narrowing the efficiency gap between biomass combustion and combined-cycle natural gas plants. Enviva leverages its pellet supply chain to anchor feedstock security for utility offtakers. Drax Biomass sustains vertical integration from forestry residue collection to port logistics. RWE Innogy dominates utility-scale biomass retrofit projects across European coal-to-biomass conversions.
Biopower denotes electricity generation from organic feedstocks through combustion, gasification, or anaerobic digestion processes, typically operating at 20-40% net electrical efficiency depending on technology configuration and feedstock moisture content. The technology serves baseload renewable power, grid stabilization, and waste-to-energy applications for industrial and municipal offtakers. Biomass power retains the largest installed base among technology segments, though thermal gasification represents the fastest-expanding margin pool due to higher conversion efficiencies and syngas co-production potential. Agricultural residues and forestry residues together constitute the dominant feedstock mix, with energy crops gaining traction where land-use regulations permit dedicated cultivation.
The EU Green Deal and F-Gas Regulation shape feedstock eligibility and carbon accounting methodologies for European operators, while the EPA's Renewable Fuel Standard and state-level renewable portfolio standards in the US mandate biomass-derived power quotas. Japan's METI feed-in tariff system and Brazil's PROINFA program direct national procurement toward bagasse and forestry residue combustion. Stakeholders must monitor evolving lifecycle carbon intensity thresholds, as regulatory bodies on three continents are tightening the boundary between countable renewable generation and fossil-coupled bioenergy.
Market Dynamics
The EU Green Deal's tightening lifecycle carbon intensity thresholds are forcing operators to revalidate feedstock eligibility, while anaerobic digestion capacity expansion across Scandinavian municipal utilities concentrates supply-side investment in waste-to-energy infrastructure.
Growth Catalysts
- EU Green Deal renewable targets:Binding national quotas under the F-Gas Regulation and RED III directive mandate biomass-derived power procurement, tightening feedstock certification standards across member states.
- Japan METI feed-in tariff:Guaranteed long-term power purchase agreements for bagasse and forestry residue combustion anchor project finance for utility-scale installations.
- Anaerobic digestion scale-up:Municipal utilities across Sweden, Denmark, and Norway are expanding organic waste processing capacity to capture methane for grid injection and combined heat and power output.
Market Restraints
- Feedstock cost volatility:Agricultural residue prices fluctuate with grain harvest cycles and competing animal feed demand, compressing plant operating margins during poor growing seasons.
- Supply concentration risk:Forestry residue collection and pellet production clusters in the US Southeast and Baltic states, exposing European and Asian offtakers to shipping rate spikes and port congestion.
- Technical limitation:Biomass combustion systems face 25-35% net electrical efficiency ceilings versus 50%+ for combined-cycle natural gas, limiting dispatch competitiveness in merit-order electricity markets.
Strategic Opportunities
- Brazil PROINFA program expansion:Dedicated cultivation of energy crops on degraded pastureland offers feedstock security for bagasse cogeneration projects beyond existing sugarcane milling infrastructure.
- Thermal gasification convergence:Integration of biomass gasification with Fischer-Tropsch synthesis and carbon capture enables renewable hydrogen and biofuel co-production from single feedstock streams.
- Corporate renewable procurement:Industrial offtakers in Germany and Japan are signing direct power purchase agreements for baseload biopower to meet science-based emissions targets.
Industry Challenges
- Certification timeline compression:Operators must complete EU-recognized sustainability certification under revised RED III criteria before existing feedstock contracts expire, straining audit capacity.
- Gasification engineering talent scarcity:Specialized skills in syngas cleanup, tar cracking, and pressurized reactor design command premium compensation, constraining project execution timelines.
- Legacy coal plant retrofit complexity:Biomass conversion of existing pulverized coal units requires boiler derating, fuel handling system replacement, and particulate emission control upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopower Market |
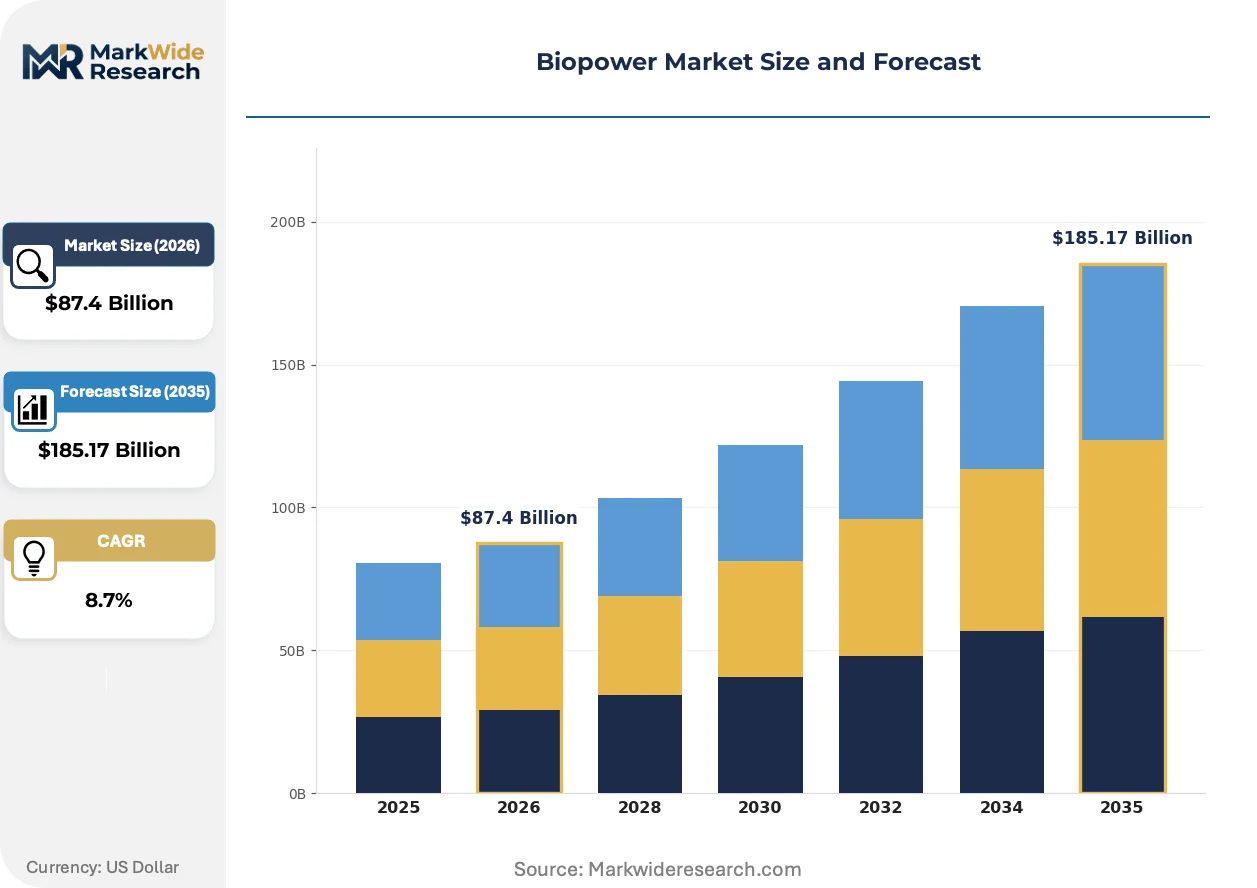
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Anaerobic Digestion, Biomass Power, Landfill Gas, Thermal Gasification Feedstock Type: Agricultural Residues, Energy Crops, Forestry Residues, Organic Waste End User: Commercial, Industrial, Municipal, Residential Service Type: Consulting, Installation, Operation, Maintenance |
| Companies Covered | Pacific BioEnergy, Lignetics, Enviva, Vyborgskaya Cellulose, Drax Biomass, Pinnacle Renewable Energy Group, RWE Innogy, E-pellets, Graanul Invest Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopower Market Emerging Trajectories
Advanced thermal conversion technologies and evolving carbon accounting methodologies are compressing technology lifecycles and redrawing competitive boundaries between combustion, gasification, and anaerobic digestion pathways.
Fluidized bed gasification with integrated tar reforming is rendering obsolete fixed-bed downdraft systems for distributed power applications. Industrial clusters in Germany and the Netherlands are deploying pressurized oxygen-blown units at 10-50 MW scale. The technology enables 40%+ cold gas efficiency and polygeneration of heat, power, and biochar, collapsing the historical efficiency gap with centralized combustion plants.
The EU's F-Gas Regulation and delegated acts under RED III are reclassifying certain forestry-derived feedstocks based on indirect land-use change risk. Project developers must now submit granular supply chain documentation to national regulatory authorities. This is diverting investment toward agricultural residues and purpose-grown energy crops with lower certification burden, particularly in Poland and Romania.
Utility offtakers are unbundling long-term service contracts from equipment supply, demanding performance guarantees on availability and heat rate rather than capital expenditure coverage. Independent service providers with specialized combustion expertise are capturing aftermarket revenue streams previously held by original equipment manufacturers. This shift is most pronounced in Germany's coal-to-biomass retrofit fleet and Japan's independent power producer segment.
Biopower Market Segmentation
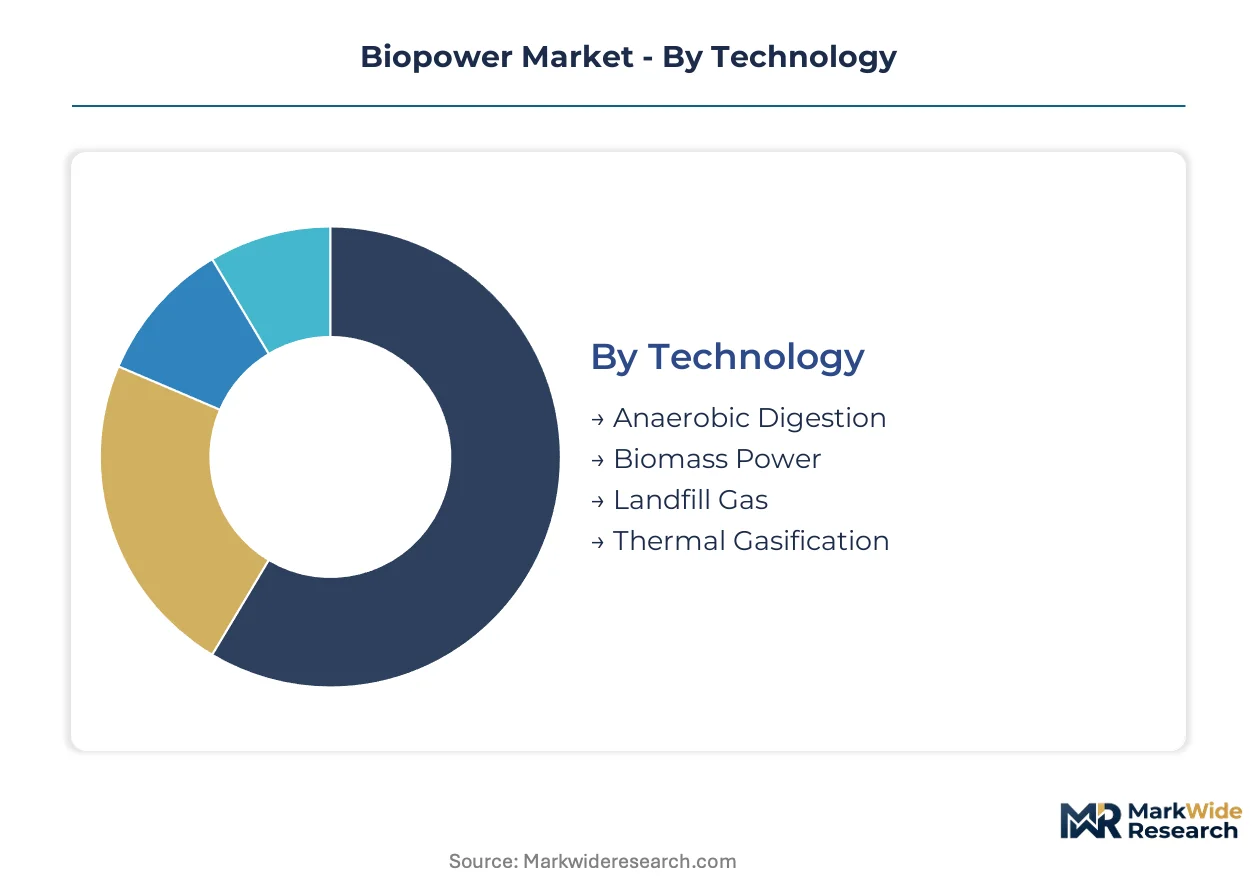
Biopower market segmentation reveals how technology maturity, feedstock availability, and offtaker contracting structures fragment investment returns across the value chain. Understanding these dimensions clarifies where capital deployment concentrates versus where regulatory arbitrage opportunities emerge.
Technology:
Mature combustion platforms dominate installed capacity, while emerging conversion pathways command premium valuations for efficiency gains and polygeneration potential.
- Biomass Power:Direct combustion of solid biomass in grate, fluidized bed, or pulverized fuel configurations delivers 20-40% net electrical efficiency. Utility-scale retrofits of coal plants in Germany, Japan, and the UK anchor demand, though efficiency ceilings limit merit-order competitiveness against combined-cycle gas.
- Thermal Gasification:Partial oxidation of biomass at high temperatures produces syngas for power generation, biofuel synthesis, or hydrogen production. Pressurized oxygen-blown units in Germany and the Netherlands achieve 40%+ cold gas efficiency and enable polygeneration, attracting project finance for industrial cluster integration.
- Anaerobic Digestion:Microbial decomposition of organic waste in oxygen-free environments yields biogas for combined heat and power or grid injection. Scandinavian municipal utilities are scaling capacity to process food waste and agricultural slurry under EU landfill diversion mandates.
- Landfill Gas:Methane capture from decomposing municipal solid waste powers reciprocating engines or feeds directly into distribution networks. Projects cluster near urban waste streams with long-term tipping fee structures.
Biomass Power retains volume leadership; Thermal Gasification holds the steepest expansion curve.
Feedstock Type:
Supply concentration and certification burden split feedstock economics between residue streams with established collection infrastructure and purpose-grown alternatives with higher regulatory scrutiny.
- Forestry Residues:Bark, sawdust, and logging slash from commercial timber operations constitute the dominant pelletized feedstock. The US Southeast and Baltic states concentrate production, exposing European and Asian offtakers to shipping rate volatility and port congestion risks.
- Agricultural Residues:Straw, corn stover, and rice husks offer lower certification burden under EU RED III indirect land-use change criteria. Polish and Romanian project developers are pivoting toward these streams as forestry documentation requirements tighten.
- Energy Crops:Dedicated cultivation of miscanthus, switchgrass, or short-rotation coppice on degraded land offers supply security. Brazil's PROINFA program is expanding cultivation on former pastureland to feed bagasse cogeneration beyond existing sugarcane milling infrastructure.
- Organic Waste:Source-separated food waste, sewage sludge, and agricultural manure feed anaerobic digestion systems. Swedish, Danish, and Norwegian municipal utilities are capturing methane for grid injection under national biogas targets.
Forestry Residues anchor current procurement volumes; Agricultural Residues are climbing the fastest as certification complexity reshapes feedstock strategy.
End User:
Contracting sophistication and offtake duration vary sharply across customer types, with industrial buyers demanding performance guarantees and municipal procurements prioritizing waste diversion outcomes.
- Industrial:Pulp and paper mills, cement producers, and chemical manufacturers deploy cogeneration for process heat and power self-supply. German and Japanese industrial offtakers are signing direct power purchase agreements for baseload biopower to meet science-based emissions targets.
- Municipal:Cities and regional utilities procure waste-to-energy capacity under long-term service concessions. Scandinavian operators bundle district heating with electricity sales to maximize asset utilization.
- Commercial:Retail chains, hospitals, and universities install smaller-scale anaerobic digestion or biomass boilers for scope 1 emissions reduction. Projects typically rely on third-party ownership structures to bypass capital constraints.
- Residential:Individual households or housing cooperatives deploy pellet stoves and small-scale gasification for heating. This segment remains marginal in utility-scale market analysis.
Industrial offtakers command the deepest project pipelines; Municipal procurement is gaining share fastest as landfill diversion mandates tighten across Europe.
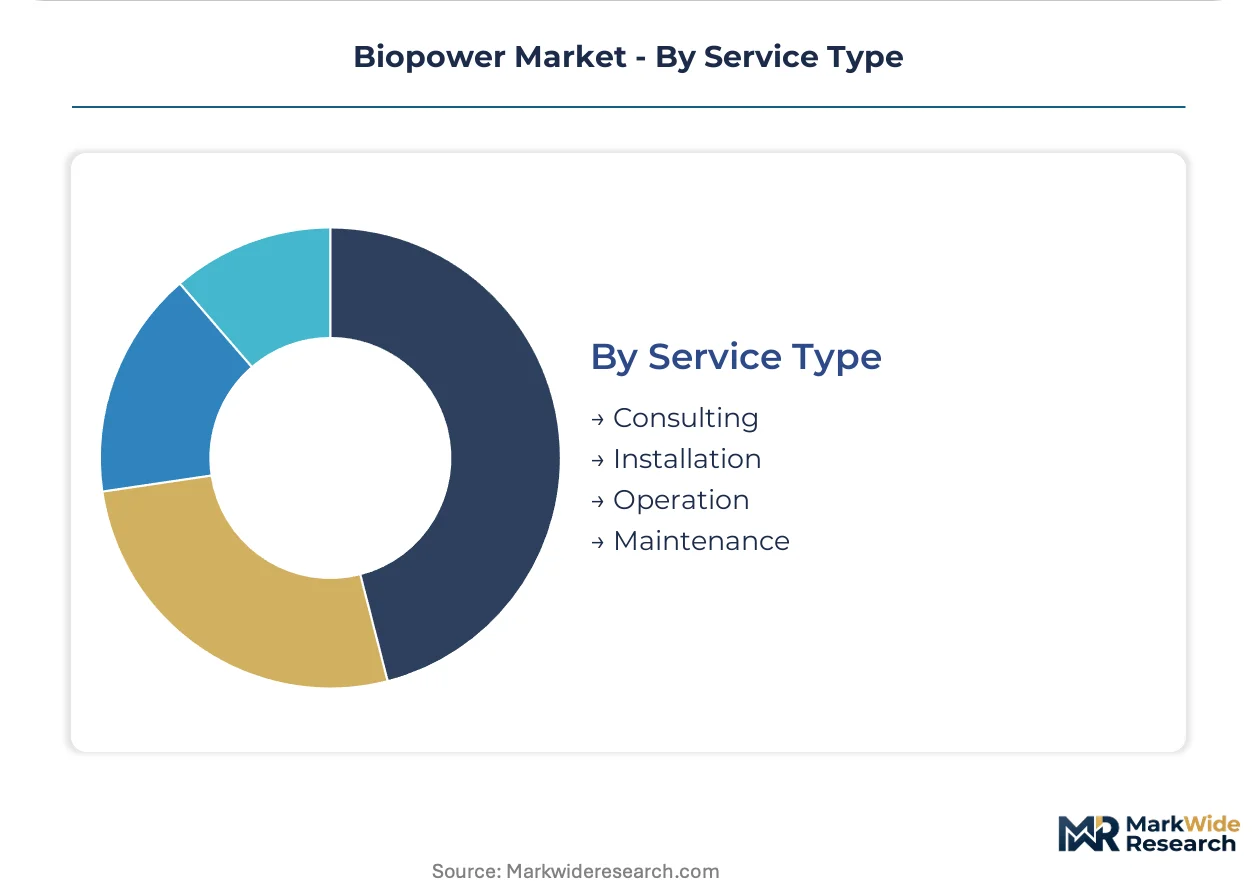
Service Type:
Value capture is migrating from equipment supply toward performance-based service contracts as utility offtakers unbundle long-term agreements from capital expenditure coverage.
- Operation:Day-to-day plant management, fuel procurement optimization, and dispatch scheduling against power markets. Independent service providers with specialized combustion expertise are capturing aftermarket revenue previously held by original equipment manufacturers in Germany's coal-to-biomass retrofit fleet.
- Maintenance:Scheduled overhauls, refractory replacement, and emission control system upgrades. Long-term service agreements now emphasize availability guarantees and heat rate performance rather than parts-and-labor coverage.
- Installation:Engineering, procurement, and construction of greenfield plants or coal-to-biomass conversions. Boiler derating, fuel handling system replacement, and particulate control upgrades dominate retrofit scope.
- Consulting:Feedstock sustainability certification, regulatory compliance strategy, and project finance structuring. EU-recognized audit capacity is strained as operators rush to complete RED III recertification before existing contracts expire.
Operation services generate the most recurring revenue; Maintenance contracting is expanding most quickly as performance guarantees reshape service economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial offtakers and Japanese utilities anchor procurement demand for utility-scale biomass installations, while Scandinavian municipal operators concentrate anaerobic digestion investment and Brazilian agro-industrial complexes drive bagasse cogeneration expansion.
Germany
RWE Innogy and utility operators drive coal-to-biomass retrofit demand across the industrial Ruhr corridor. The EU Green Deal's RED III directive mandates revised sustainability certification for forestry-derived feedstocks. Hamburg and Berlin municipal utilities are expanding district heating integration with biomass cogeneration plants.
Japan
Independent power producers and pulp mills procure baseload biopower under long-term contracting structures. METI's feed-in tariff system guarantees power purchase agreements for bagasse and forestry residue combustion projects. Kyushu and Tohoku industrial clusters host the densest concentration of operational biomass plants.
Brazil
Sugarcane milling complexes and independent energy producers scale bagasse cogeneration beyond existing processing infrastructure. The PROINFA program directs national procurement toward agricultural residue combustion and dedicated energy crop cultivation. São Paulo and Minas Gerais states concentrate new capacity development on degraded pastureland.
Sweden
Municipal utilities and district heating operators expand organic waste processing capacity under landfill diversion mandates. The EU F-Gas Regulation shapes feedstock eligibility criteria for biogas grid injection projects. Stockholm and Gothenburg metropolitan regions are scaling anaerobic digestion facilities for combined heat and power output.
United States
Southeastern utilities and industrial pellet offtakers anchor demand for wood biomass power generation. The EPA's Renewable Fuel Standard and state-level renewable portfolio standards mandate biomass-derived power quotas in regulated markets. Georgia and Alabama forestry clusters supply pelletized feedstock to European and Asian export markets.
Biopower Market Vendor Landscape
Channel-controlling players compete with product-specialist players across feedstock logistics, conversion technology, and utility offtake contracting. The market structure concentrates around pellet supply chain operators, utility-scale project developers, and regional anaerobic digestion specialists. Three archetypes dominate: vertically integrated feedstock-to-power operators, independent power producers with captive fuel arrangements, and technology-agnostic service providers. Capacity expansion and strategic partnerships represent the primary competitive moves, with operators securing long-term feedstock contracts to anchor project finance.
Among North American pellet producers, Enviva and Drax Biomass exemplify the integrated supply chain archetype, anchoring feedstock security through upstream forestry relationships and port logistics control. RWE Innogy occupies a position within the European utility-scale developer tier, representing the coal-to-biomass retrofit specialist model across German and UK installations.
| Leading Market Players |
|---|
| Pacific BioEnergy |
| Lignetics |
| Enviva |
| Vyborgskaya Cellulose |
| Drax Biomass |
| Pinnacle Renewable Energy Group |
| RWE Innogy |
| E-pellets |
| Graanul Invest Group |
| Others |
Supply Flow & Price Mechanics
Trans-Atlantic pellet freight corridors from the US Southeast to European utility terminals impose cost volatility that cascades through contract indexation clauses and sharpens price differentiation between certified and uncertified feedstock tiers.
Pricing Analysis
Cost-plus contracts with Rotterdam pellet price indexation dominate long-term utility offtake agreements. Pricing stratifies across FSC-certified premium grades, standard ENplus-A1 tiers, and economy-grade industrial pellets with relaxed moisture specifications. Cost compression in the economy tier is intensifying because Baltic producers are absorbing shipping rate spikes to maintain European market share. Industrial cogeneration operators in Germany and Japan exhibit the highest price sensitivity, while Scandinavian municipal utilities prioritize waste diversion outcomes over unit economics.
Supply Chain Analysis
EU F-Gas Regulation restrictions on fluorinated greenhouse gas equipment constrain technology flows to biomass conversion projects. Feedstock procurement draws from the US Southeast, Baltic states, and Brazil's São Paulo corridor. Forestry residue collection, pellet densification, and port logistics constitute the critical input chain. Single-source vulnerability concentrates around Georgia and Alabama pellet terminals serving trans-Atlantic routes. Distribution runs through long-term offtake contracts with utility buyers rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Project execution timelines are stretching because specialized engineering talent in pressurized gasification reactor design commands scarcity premiums across three continents.
For Market Incumbents: Harden feedstock security through backward integration into forestry residue collection networks in the US Southeast and Baltic states. Accelerate RED III sustainability certification completion ahead of contract renewal cycles to preempt regulatory disqualification. Defend against thermal gasification entrants by locking industrial cluster offtakers into long-term heat-and-power service agreements with availability guarantees. For New Entrants and Emerging Players: Anaerobic digestion capacity gaps in Poland and Romania offer the most penetrable white-space opportunity under EU landfill diversion mandates. Target municipal utility procurement in secondary Scandinavian cities where incumbent service providers lack localized biogas grid injection expertise. Lead with turnkey engineering-procurement-construction packages that bundle feedstock pre-treatment with plant commissioning to bypass incumbent equipment-only positioning. For Investors and Strategic Acquirers: Independent service providers with specialized combustion expertise and captive utility relationships represent the highest-conviction acquisition archetype. Long-term viability hinges on differentiation from original equipment manufacturer service arms through performance-based contracting rather than parts-and-labor coverage. Watch for inflection when EU member states publish delegated act implementation timelines for revised RED III indirect land-use change criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Certification Program | Secures EU-recognized RED III compliance ahead of delegated act enforcement deadlines. |
| Gasification Technology Licensing | Enables industrial cluster polygeneration with 40% cold gas efficiency in German deployments. |
| Long-term Power Purchase Agreement | Anchors project finance for utility-scale installations under Japan METI feed-in tariff structures. |
| Coal-to-Biomass Retrofit Capacity | Captures German and UK utility procurement under EU Green Deal coal phase-out mandates. |
| Anaerobic Digestion Scale-Up | Positions for Swedish and Danish municipal organic waste processing concession awards. |
Methodological Framework
Desk research of EIA biomass generation databases, IEA renewable energy outlooks, and EU regulatory delegated acts preceded structured interviews with utility planning officers, IPP project developers, EPC contractors, and fuel supply specialists. Primary fieldwork captured operational data from German coal-to-biomass retrofit installations and Scandinavian anaerobic digestion facilities. Secondary validation drew from FERC interconnection filings, national biogas registry statistics, and customs trade data on pellet exports. Bottom-up capacity build-up and top-down regulatory mandate analysis were triangulated against disclosed project pipelines.
Assumptions held fixed include EU Green Deal renewable target enforcement, Japan METI feed-in tariff continuity, and current EU-recognized sustainability certification standards. The analytical framework modeled technology segmentation, feedstock type, end-user contracting structure, and regional regulatory framework across the projection horizon. CAGRs were derived from installed capacity growth trajectories, capacity factor assumptions, and feedstock cost evolution curves. Industry-specific inputs encompassed pellet export price indices, anaerobic digestion feedstock tipping fees, and gasification engineering procurement cost benchmarks.
Macroeconomic conditions sit as an overlay; deviation in freight rates, carbon credit pricing, or construction cost inflation would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement timing and technology cost learning curves. Material shifts in EU delegated act implementation scope or Japan feed-in tariff revision would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Europe Biogas Market
Bioenergy
Biogas Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Biopellets Energy Market
Bioenergy
Bio CHP Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Organic Biogas Market
Bioenergy
Bioenergy Market