
 Biogas Market | 2026-2036
Biogas Market Size, Share, and Industry Trends Forecast 2026-2036
Biogas Market Analysis
Utility offtake agreements is reconfiguring how biogas developers secure long-term revenue. Engie SA leverages its European gas grid access to aggregate distributed biogas production into pipeline-quality biomethane streams. Wartsila Corporation anchors its position through modular gas engine technology that converts raw biogas directly into baseload electricity. Greenlane Renewables Inc specializes in membrane upgrading systems that strip CO2 from biogas to meet vehicle fuel specifications.
Biogas comprises methane, carbon dioxide, and trace gases produced through anaerobic digestion of organic matter at mesophilic or thermophilic temperatures, typically yielding 50-70% methane content suitable for energy recovery. Agricultural residues dominate feedstock supply chains where existing manure collection infrastructure lowers feedstock logistics costs. Anaerobic digestion technology leads installed capacity but thermal gasification is gaining traction for lignocellulosic feedstocks that resist bacterial breakdown. Electricity generation remains the largest application segment though vehicle fuel commands premium pricing where renewable natural gas standards apply.
The EU Green Deal and F-Gas Regulation shape European biogas demand by mandating progressive reductions in fossil-derived heating fuels. EPA renewable fuel standards in the United States create compliance value for landfill gas recovery projects that qualify for cellulosic biofuel credits. India's PLI scheme for compressed biogas plants directs capital toward agricultural residue aggregation hubs. Stakeholders must monitor how carbon border adjustment mechanisms redefine the competitive position of biogas against electrolytic hydrogen in industrial heat applications.
Market Dynamics
The EU Green Deal and F-Gas Regulation are compressing project timelines for biogas developers as emission benchmarks tighten across heating fuel supply chains. Feedstock logistics costs now determine plant economics more than conversion technology selection.
Growth Catalysts
- EU Green Deal mandates:The framework mandates progressive reductions in fossil-derived heating fuels, pulling upgraded biomethane into grid injection contracts across Germany, Denmark, and the Netherlands.
- Agricultural residue aggregation:Existing manure collection infrastructure in dairy-intensive regions lowers feedstock logistics costs below lignocellulosic alternatives.
- Membrane upgrading systems:These systems strip CO2 from raw biogas to meet vehicle fuel specifications, opening premium pricing in renewable natural gas markets.
Market Restraints
- Feedstock supply concentration:Agricultural residue availability clusters in specific watersheds and farming regions, creating geographic supply risk for project developers.
- Electrolytic hydrogen substitution:Industrial heat applications face competitive pressure from electrolytic hydrogen where carbon border adjustment mechanisms favor molecular alternatives.
- Anaerobic digestion technical limits:Mesophilic and thermophilic bacterial processes cannot break down lignocellulosic feedstocks, restricting feedstock flexibility.
Strategic Opportunities
- India's PLI scheme:The production-linked incentive directs capital toward agricultural residue aggregation hubs for compressed biogas plants in Punjab and Haryana.
- Thermal gasification convergence:Gasification technology paired with anaerobic digestion expands addressable feedstocks to woody biomass and energy crops.
- Vehicle fuel certification:Renewable natural gas standards in California and Oregon create compliance value that commands premium pricing over electricity generation.
Industry Challenges
- Grid interconnection timelines:Biomethane injection into natural gas distribution networks requires utility coordination that extends project commissioning schedules.
- Digestate management protocols:Post-digestion organic matter handling must meet national fertilizer regulations, adding operational complexity and transport costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biogas Market |
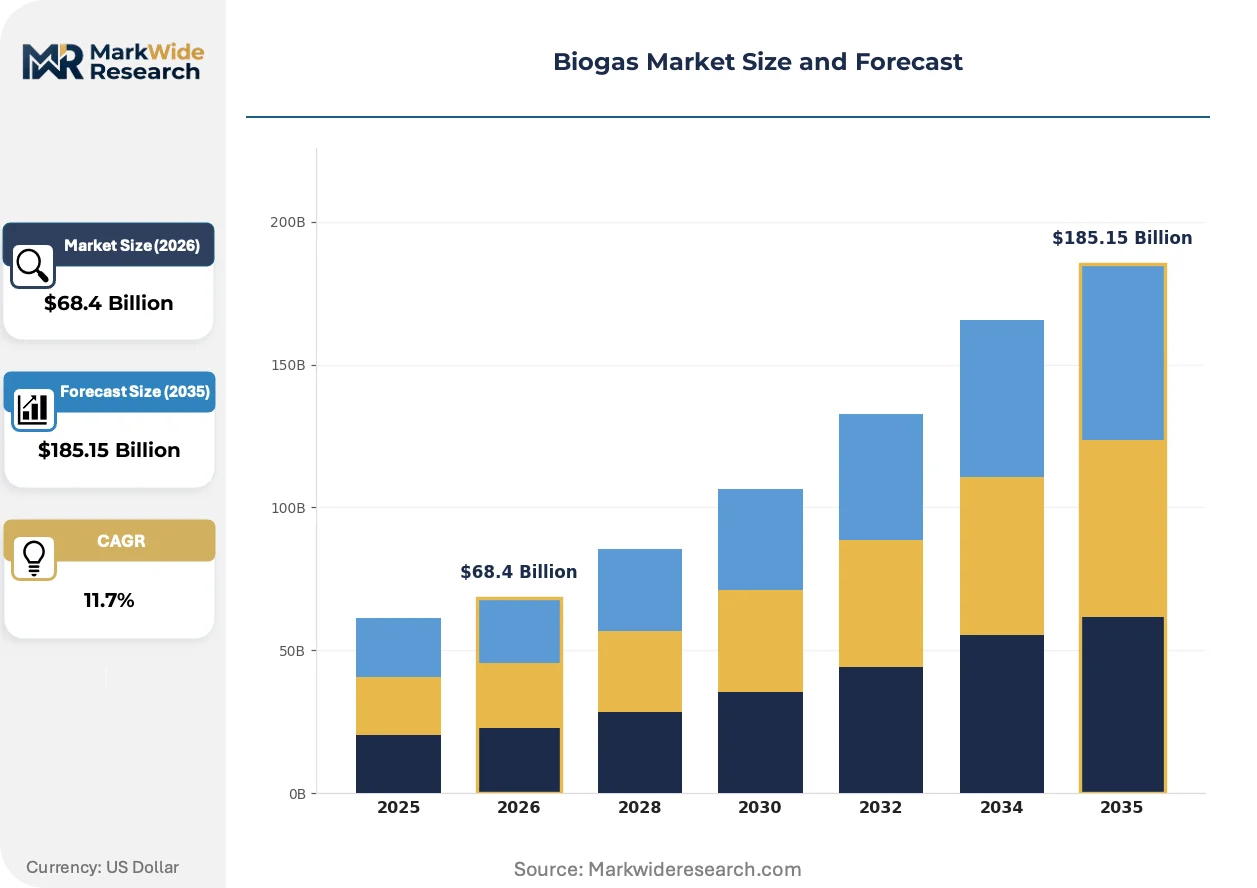
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $185.15 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Agricultural Residues, Food Waste, Manure, Energy Crops Technology: An anaerobic digestion, Landfill Gas Recovery, Thermal Gasification, Fermentation Application: Electricity Generation, Vehicle Fuel, Heating, Industrial Processes End User: Utilities, Agricultural Sector, Food Processing Industry, Transportation |
| Companies Covered | Engie SA, Bright Renewables BV, EnviTec Biogas AG, Air Liquide, Wartsila Corporation, PlanET Biogas Group, WELTEC BIOPOWER GmbH, Greenlane Renewables Inc, Hitachi Zosen Inova AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biogas Market Emerging Trajectories
Technology convergence between anaerobic digestion and thermal conversion processes is expanding addressable feedstock pools beyond traditional agricultural residues. Regulatory frameworks are accelerating the shift from electricity generation toward pipeline-quality biomethane production.
Membrane upgrading technology is hybridizing biogas purification workflows by combining selective permeability with pressure swing adsorption in single-unit configurations. Industrial gas utilities in Germany and the Netherlands are deploying these systems at scale to meet grid injection specifications. The technology is compressing capital costs for medium-scale plants that previously required multiple standalone upgrading stages.
The F-Gas Regulation is mandating progressive phase-down of hydrofluorocarbon use in heating and cooling equipment, indirectly tightening emission benchmarks for fossil-derived thermal energy. This regulatory pressure is redirecting utility procurement toward certified biomethane streams that qualify for renewable heating credits. Project developers in Denmark and Sweden are responding by prioritizing upgrading capacity over raw biogas electricity generation.
Long-term offtake contracting is displacing spot market sales as the dominant revenue model for biogas producers. Power utilities and industrial gas buyers are locking in ten-to-fifteen-year supply agreements to secure renewable fuel volumes for compliance reporting. This shift is most visible in Germany, where Engie SA and regional municipal utilities are aggregating distributed production through pipeline access contracts.
Biogas Market Segmentation
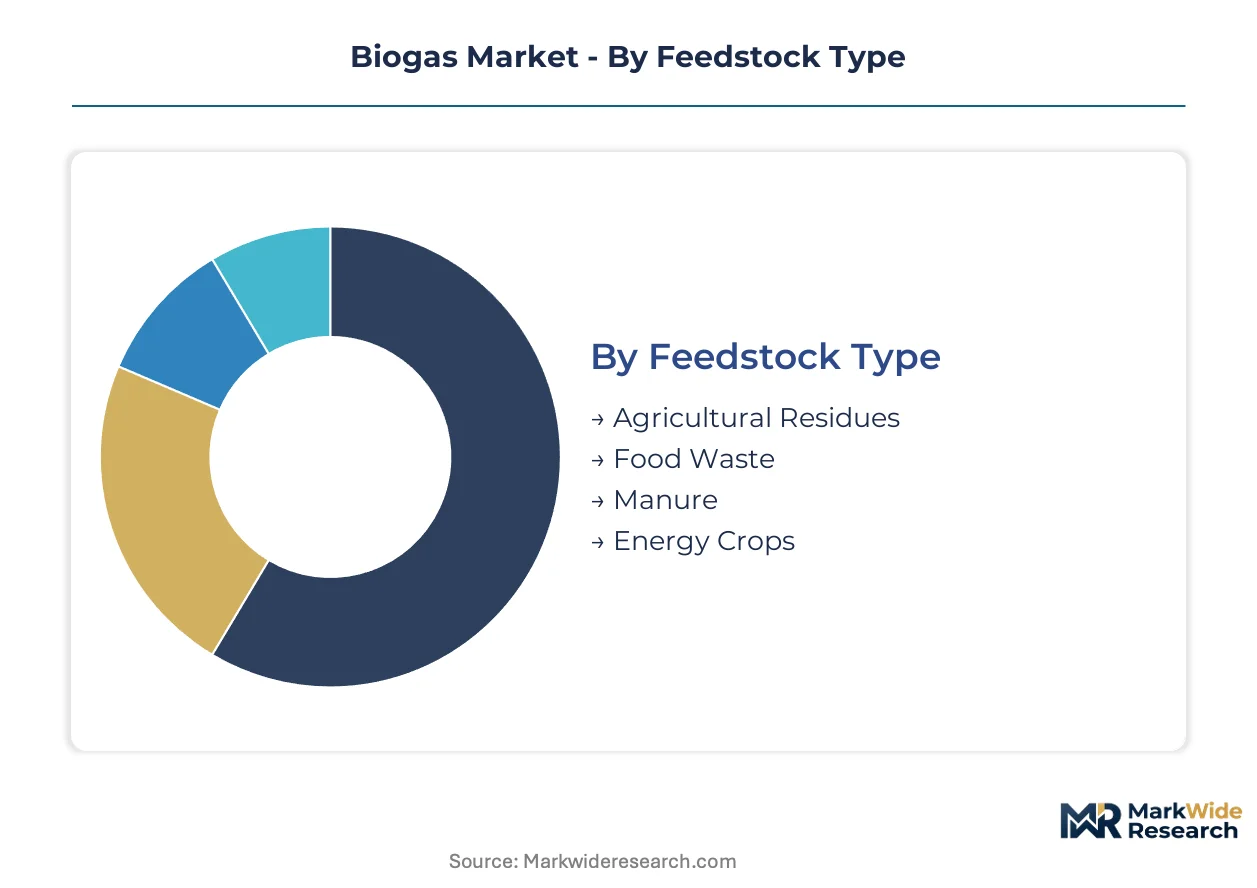
Biogas market segmentation reveals how feedstock availability, conversion technology economics, and end-use pricing premiums reshape competitive strategy. Developers must align technology selection with local feedstock logistics and offtake contract structures to secure project returns.
Feedstock Type:
Use-case spectrum spans distributed agricultural operations to centralized urban waste streams, each imposing distinct collection cost structures on plant economics.
- Agricultural Residues:Crop straw, husks, and harvest remnants deliver 50-70% methane yields through anaerobic digestion. Demand concentrates in Germany and Denmark where the EU Green Deal tightens emission benchmarks for district heating networks, pulling these feedstocks into biomethane upgrading facilities.
- Manure:Dairy and livestock operations generate steady, high-moisture organic streams ideal for continuous digester operation. Existing collection infrastructure in the Netherlands and northern Germany lowers logistics costs below lignocellulosic alternatives, anchoring regional production clusters.
- Food Waste:Municipal and commercial organic refuse offers higher energy density per ton but requires source-segregation infrastructure.
- Energy Crops:Dedicated cultivation of maize, sorghum, or miscanthus for biogas feedstock faces land-use competition from food production.
The dominant share belongs to Agricultural Residues, while Food Waste is closing the gap fastest as urban collection systems mature.
Technology:
Cost tier differentiation separates proven bacterial processes from emerging thermochemical routes that unlock lignocellulosic feedstocks.
- Anaerobic Digestion:Mesophilic and thermophilic bacterial breakdown of organic matter at 35-55°C yields 50-70% methane content. Germany's F-Gas Regulation and feed-in tariff structures continue reshaping project economics for this mature technology.
- Thermal Gasification:High-temperature partial oxidation converts woody biomass and energy crops into syngas for methanation. India's PLI scheme for compressed biogas plants directs capital toward agricultural residue hubs where gasification expands addressable feedstocks beyond bacterial limits.
- Landfill Gas Recovery:Collection and upgrading of methane from decomposing municipal waste.
- Fermentation:Biochemical conversion pathways for sugar-rich feedstocks.
Anaerobic Digestion retains the dominant share, though Thermal Gasification is expanding most quickly where lignocellulosic resources dominate local supply.
Application:
Margin structure varies sharply across energy outputs, with vehicle fuel certification commanding substantial premiums over electricity generation.
- Electricity Generation:Baseload power from gas engines or turbines remains the largest installed base. Wartsila Corporation anchors this segment through modular gas engine technology that converts raw biogas directly into grid-stabilizing output.
- Vehicle Fuel:Pipeline-quality biomethane meeting renewable natural gas standards accesses California LCFS and Oregon CFP compliance markets. Greenlane Renewables Inc specializes in membrane upgrading systems that strip CO2 to meet these stringent vehicle fuel specifications.
- Heating:Direct combustion or district heat supply from biogas or upgraded biomethane.
- Industrial Processes:Process heat and combined heat-and-power in food processing and manufacturing.
Electricity Generation holds the dominant share, while Vehicle Fuel is gaining share fastest as renewable natural gas standards proliferate.
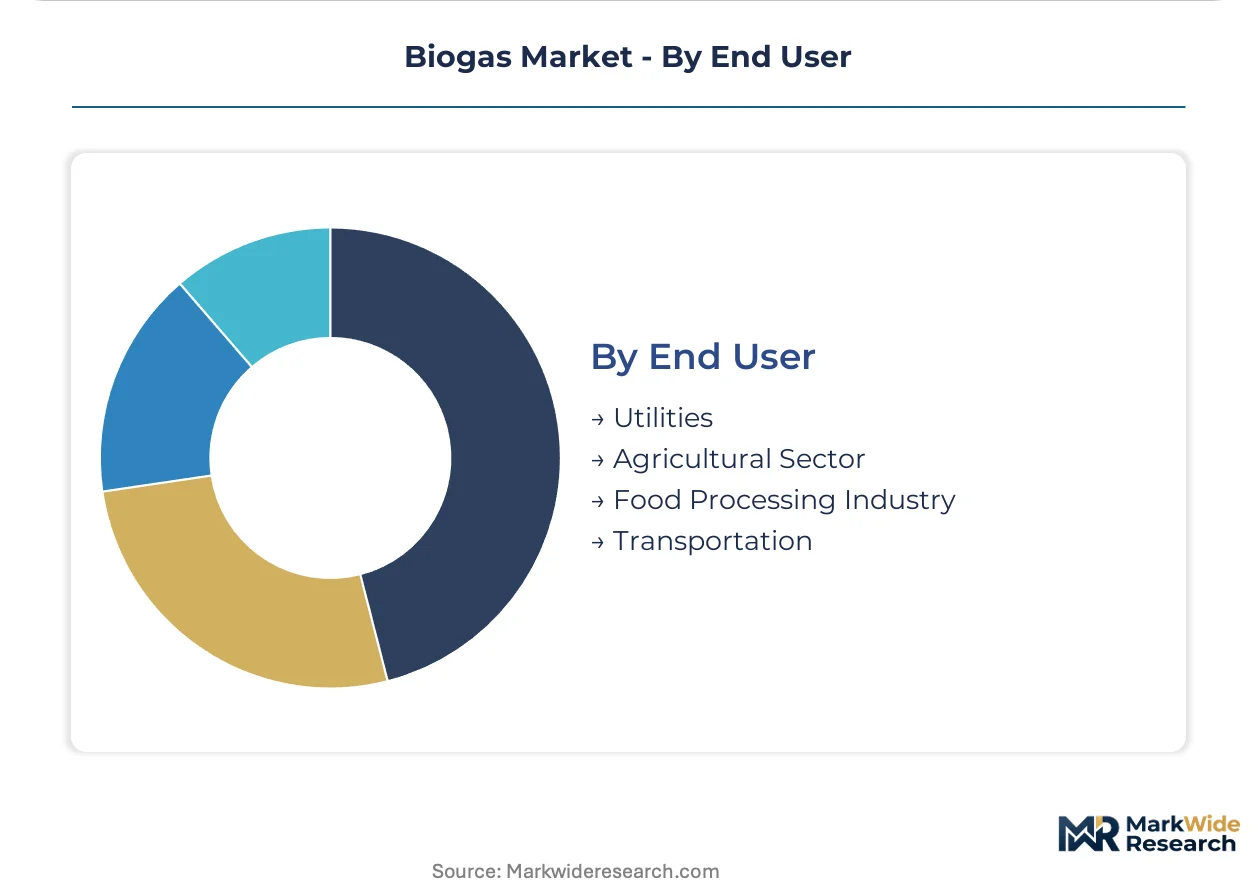
End User:
Customer type determines contract duration, price indexation, and carbon credit eligibility in ways that reshape developer financing structures.
- Utilities:Power and gas distribution companies procure biomethane through ten-to-fifteen-year offtake agreements. Engie SA leverages European gas grid access to aggregate distributed production into pipeline-quality streams for compliance reporting.
- Agricultural Sector:On-farm digesters serve dual purposes of waste management and energy self-supply. Manure collection infrastructure in dairy-intensive regions creates captive feedstock advantages for farm-scale operations.
- Food Processing Industry:Wastewater treatment and organic byproduct valorization within processing facilities.
- Transportation:Fleet operators and fuel retailers sourcing certified renewable natural gas for vehicle compliance.
Utilities command the dominant share, while Transportation is climbing the fastest as fleet decarbonization targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal and national production-linked incentives are reconfiguring biogas deployment patterns across major economies. Feedstock logistics infrastructure and grid interconnection capacity now determine regional competitive positioning more than conversion technology maturity.
Germany
Agricultural residue aggregation and dairy manure collection networks anchor project economics in Lower Saxony and Bavaria. The F-Gas Regulation and renewable heating mandates under the EU Green Deal compress commissioning timelines for biomethane upgrading facilities. The North German Plain hosts dense clusters of anaerobic digestion plants supplying pipeline-quality gas to municipal utilities.
United States
Landfill gas recovery projects in California and Texas access premium renewable fuel credits under EPA renewable fuel standards. The state's Low Carbon Fuel Standard creates compliance value for upgraded biomethane directed toward vehicle fuel markets. Industrial gas offtakers in the Central Valley lock in long-term supply agreements with agricultural biogas producers.
India
The PLI scheme for compressed biogas plants directs capital toward agricultural residue aggregation hubs in Punjab and Haryana. State-level mandates for municipal organic waste processing accelerate project development in peri-urban corridors. Gujarat and Maharashtra host emerging clusters where thermal gasification expands feedstock flexibility beyond bacterial digestion limits.
Denmark
District heating network decarbonization targets pull upgraded biomethane into grid injection contracts across Jutland and Zealand. National biogas feed-in tariffs reshape project economics toward pipeline-quality production rather than electricity generation. The central agricultural belt concentrates manure-based digester capacity serving regional energy cooperatives.
Netherlands
Existing dairy manure collection infrastructure in Friesland and Gelderland lowers logistics costs below lignocellulosic alternatives. The EU Green Deal tightens emission benchmarks for industrial heat users, redirecting procurement toward certified biomethane streams. Gasunie grid access contracts enable distributed producers to aggregate output into pipeline-quality supply.
Biogas Market Vendor Landscape
On the supply side, the industry is consolidating around integrated technology providers and specialized upgrading equipment fabricators. The vendor base separates into three strategic archetypes: European gas utilities leveraging grid infrastructure, modular equipment specialists, and membrane purification technology developers. Competitive dynamics center on long-term offtake contracting and geographic expansion through licensing partnerships rather than pure capacity races.
Among European-integrated operators, Engie SA exemplifies the utility-archetype position through gas grid access aggregation. Wartsila Corporation and Greenlane Renewables Inc represent contrasting specialization vectors—modular power generation equipment versus membrane upgrading systems—each anchoring distinct value-chain positions. These three entities illustrate how technology focus and infrastructure control define competitive segmentation.
| Leading Market Players |
|---|
| Engie SA |
| Bright Renewables BV |
| EnviTec Biogas AG |
| Air Liquide |
| Wartsila Corporation |
| PlanET Biogas Group |
| WELTEC BIOPOWER GmbH |
| Greenlane Renewables Inc |
| Hitachi Zosen Inova AG |
| Others |
Supply Flow & Price Mechanics
German dairy manure collection networks concentrate feedstock supply in Lower Saxony and Bavaria, anchoring margin pools with utilities holding long-term offtake contracts rather than spot-market traders. The EU Green Deal's renewable heating mandates compress pricing differentials between raw biogas and pipeline-quality biomethane, redirecting developer investment toward upgrading capacity.
Pricing Analysis
Volume-discount tiering structures dominate utility procurement, with ten-to-fifteen-year offtake agreements commanding lower per-unit rates than spot sales to industrial heat users. Price differentiation rests on certification grade — renewable natural gas standards in California and Oregon access premium LCFS credits unavailable to electricity-only output. Cost compression in standard-grade biomethane is intensifying because membrane upgrading technology compresses capital costs for medium-scale plants. Agricultural cooperatives show highest price sensitivity due to captive feedstock advantages, while municipal utilities demonstrate lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Contract-manufacturing concentration for upgrading equipment sits with Bright Renewables BV and Greenlane Renewables Inc in the Netherlands and Canada, while Wartsila Corporation anchors modular gas engine fabrication in Finland. Geographic supply concentration clusters in Germany, Denmark, and India where national incentive schemes direct capital deployment. Raw material dependencies include stainless steel digester vessels, specialized membrane polymers, and gas engine components. Single-source vulnerability runs through European gas grid interconnection capacity for biomethane injection. Distribution runs through utility aggregation contracts that pool distributed production into pipeline-quality streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biogas market constitutes a high-growth disruption as the EU Green Deal and F-Gas Regulation mandate progressive phase-down of fossil-derived heating fuels, creating structural demand inflection for certified biomethane.
For Market Incumbents: Insulate margin position by deepening backward integration into agricultural residue aggregation infrastructure in Germany's North German Plain, locking in feedstock supply before India's PLI scheme redirects global capital toward Punjab and Haryana. Prioritize membrane upgrading capacity investments over raw biogas electricity generation as renewable natural gas standards proliferate across California and Oregon. For New Entrants and Emerging Players: Establish a beachhead in thermal gasification technology for lignocellulosic feedstocks that resist bacterial breakdown, targeting India's agricultural residue hubs where anaerobic digestion technical limits create white-space opportunity. Penetrate the vehicle fuel certification segment through modular upgrading systems that strip CO2 to meet stringent RNG specifications, leveraging licensing partnerships with European gas utilities rather than competing for grid access directly. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional biogas developers holding ten-year German feed-in tariff contracts nearing expiration. Long-term viability over a five-to-ten year window hinges on successful contract renegotiation toward pipeline-quality biomethane pricing. Target acquisition archetypes: mid-scale operators with existing manure collection infrastructure and unutilized upgrading capacity. Monitor carbon border adjustment mechanism implementation as the critical inflection signal for industrial heat application competitiveness against electrolytic hydrogen.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Upgrading Capacity Buildout | Greenlane Renewables Inc deploys selective permeability systems that compress capital costs for medium-scale German plants. |
| Long-term Biomethane Offtake Agreement | Engie SA aggregates distributed production through European gas grid access contracts spanning ten-to-fifteen years. |
| Agricultural Residue Aggregation Hub Development | India's PLI scheme directs capital toward Punjab and Haryana hubs where thermal gasification expands feedstock flexibility. |
| Renewable Natural Gas Certification Program | California LCFS and Oregon CFP compliance markets create premium pricing for vehicle fuel-grade biomethane output. |
| Modular Gas Engine Technology Licensing | Wartsila Corporation anchors electricity generation segment through baseload power systems for raw biogas conversion. |
Methodological Framework
Cross-validation between EIA project development databases and IEA renewable energy reports anchors the qualitative findings on technology deployment patterns. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and agricultural cooperative managers combined with secondary validation from FERC filings, EPA renewable fuel standard dockets, and EU Green Deal implementation documents. Bottom-up plant-level capacity aggregation and top-down national incentive scheme analysis triangulate market sizing.
Calibration against historical commissioning timelines and tariff regime changes shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include feedstock type, conversion technology, application output, and end-user contract structure. CAGRs derive from regression analysis of installed capacity growth correlated with regulatory incentive trajectories. Industry-specific forecast inputs incorporate EU F-Gas Regulation phase-down schedules and India's PLI scheme disbursement patterns.
Stress conditions across feedstock price volatility, interconnection queue delays, and electrolytic hydrogen cost curves were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on policy continuity and technology cost trajectories. Quarterly review of carbon border adjustment mechanism proposals and national biogas tariff renegotiations is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Biomass Wood Chip Market
Bioenergy
Europe Biogas Market
Bioenergy
Biopellets Energy Market
Bioenergy
Biopower Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Bio CHP Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Organic Biogas Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Bioenergy Market