
 Biopellets Energy Market | 2026-2036
Biopellets Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Biopellets Energy Market Outlook
Aftermarket fuel supply contracts is rewriting margin allocation across the biopellets value chain, shifting returns from equipment makers toward long-term offtake operators. Enviva leverages its transatlantic export terminal network to sustain supply security for European utilities. Mitsubishi Corporation anchors its position through integrated biomass procurement and power generation assets in Japan. Pinnacle Renewable Energy specializes in industrial-grade pellet specifications that dominate Pacific Rim industrial heating demand.
Biopellets energy denotes densified solid fuel manufactured from compressed organic matter, typically exhibiting moisture content below 10% and bulk density exceeding 600 kg per cubic meter, serving as a direct combustion substitute for coal in thermal applications. Wood pellets command the largest production volume owing to established supply chains from sawmill residues and forest thinning operations. Power generation applications attract the fastest capacity additions as existing coal units retrofit for biomass co-firing to comply with emissions regulations. Residential heating remains a mature, seasonally cyclical segment concentrated in Northern European markets with established stove and boiler infrastructure.
The EU Green Deal and Renewable Energy Directive shape product certification requirements through sustainability criteria governing feedstock sourcing and lifecycle emissions accounting. EPA standards in the United States govern particulate emissions from residential wood heaters, while Japan's FIT mechanism steers utility procurement toward imported biopellets meeting strict chlorine and ash thresholds. Stakeholders must monitor evolving sustainability certification schemes and carbon border adjustment mechanisms that will determine feedstock eligibility and market access across major demand centers.
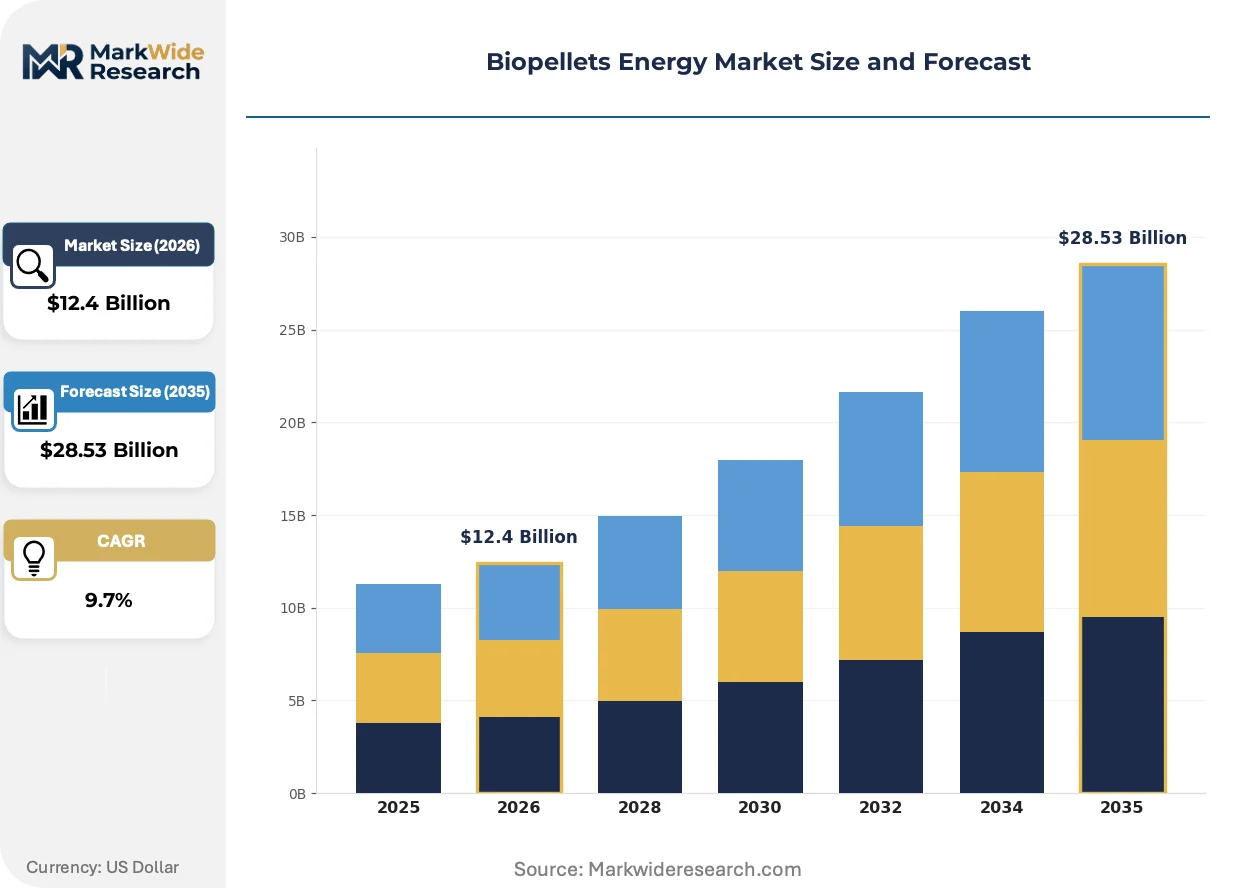
Market Dynamics
Coal plant retrofit economics are compressing project timelines across European utilities, as biomass co-firing offers faster compliance pathways than nuclear or offshore wind construction. This structural pull is reallocating capital from greenfield generation toward feedstock security and handling infrastructure.
Growth Catalysts
- EU Green Deal phase-out mandates:Germany's coal exit law and similar Scandinavian statutes are forcing thermal operators toward certified biomass feedstock. Utility procurement desks now prioritize long-term pellet contracts over spot market exposure.
- Industrial heat demand:District heating networks in Copenhagen and Stockholm are expanding pellet-fired capacity to displace natural gas in combined heat and power configurations. Municipal operators value the dispatchability biomass provides versus intermittent alternatives.
- Feedstock densification technology:Advanced torrefaction processes are raising pellet energy density above standard specifications, reducing shipping costs for transatlantic supply chains. Japanese utilities specify these upgraded pellets for co-firing at coastal power stations.
Market Restraints
- Sawmill residue supply concentration:Pellet production clusters in the US Southeast and British Columbia depend on fiber flows from lumber operations. Housing construction downturns directly constrain feedstock availability and pricing stability.
- Chlorine and ash thresholds:Japan's FIT mechanism enforces strict contamination limits that disqualify agricultural residue pellets. Compliance requires costly washing and sorting infrastructure at export terminals.
- Natural gas price volatility:European industrial heat consumers retain dual-fuel capability, switching back to gas when hub prices collapse. This demand elasticity undermines pellet offtake predictability for producers.
Strategic Opportunities
- South Korean renewable portfolio standards:Kepco's biomass procurement targets under RPS mandates create import demand beyond existing Japanese and European absorption. Local developers lack established supply relationships, opening terminal access for integrated traders.
- Agricultural residue valorization:Straw and rice husk pelletization in India and Southeast Asia remains technically immature. Equipment suppliers who adapt dies and cooling systems for high-silica feedstocks capture first-mover positioning.
- Carbon border adjustment alignment:The EU CBAM's phased implementation rewards pellet supply chains with documented lifecycle emissions below fossil benchmarks. Certification bodies accredited under ENplus or SBP standards gain gatekeeper influence over market access.
Industry Challenges
- Biomass sustainability auditing capacity:Third-party verification of chain-of-custody documentation lags behind certification demand. Qualified auditors command premium rates, extending compliance timelines for new market entrants.
- Port handling infrastructure retrofit:Bulk pellet discharge requires enclosed conveyor systems distinct from coal or grain handling. European terminals face capex commitments to prevent dust emissions and moisture absorption during storage.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopellets Energy Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $28.53 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Pellets, Agricultural Residue Pellets, Biomass Pellets, Other Feedstock Pellets Application: Residential Heating, Industrial Heating, Power Generation, Biomass Co-firing End User: Power Plants, Heating Facilities, Industrial Manufacturers, Residential Consumers Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesale Distributors |
| Companies Covered | Enviva, Mitsubishi Corporation, Weyerhaeuser Company, Abellon Clean Energy, Biomass Secure Power, Curran Renewable, Pinnacle Renewable Energy, Orsted, Pacific BioEnergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopellets Energy Market Strategic Shifts
Torrefaction and steam explosion processes are upgrading pellet combustion characteristics, while digital tracking systems reshape how sustainability credentials traverse complex supply chains. These developments are compressing the gap between laboratory specifications and field performance.
Torrefaction technology is hybridizing conventional wood pellet production with mild pyrolysis treatment that elevates fixed carbon content and hydrophobicity. Danish district heating operators are piloting these black pellets at 50% co-firing rates without derating boiler output. The process is hybridizing product categories, blurring distinctions between biomass and upgraded solid fuel classifications in procurement specifications.
EU Green Deal sustainability criteria are mandating feedstock traceability through geolocation verification and mass balance accounting. Pellet producers must document that forest biomass derives from regeneration-compliant harvesting, not high-carbon-stock primary forests. German utilities have advanced their compliance timelines ahead of statutory deadlines to secure preferred supplier status under national coal phase-out auctions.
Long-term offtake contracting is displacing spot market liquidity as the dominant transaction mode for utility-scale volumes. European power generators now seek 10-15 year supply agreements with built-in price escalation clauses indexed to coal and carbon futures. This preference shift concentrates procurement influence among integrated traders with captive terminal capacity rather than standalone producers.
Biopellets Energy Market Segmentation
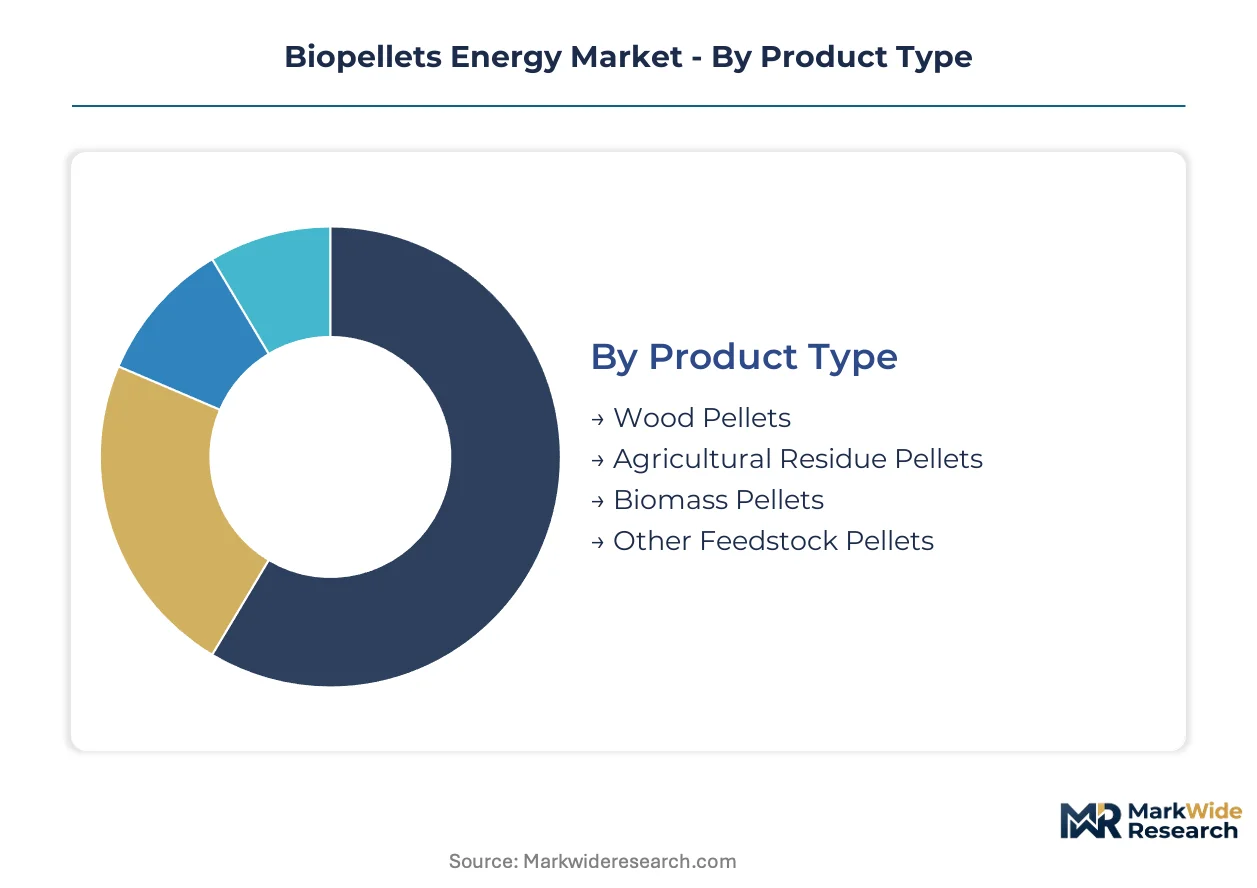
Segmentation in the biopellets market reveals distinct procurement cycles and margin profiles across product grades and customer types. Understanding these structural differences enables suppliers to align production capacity with contract duration and certification requirements.
Product Type:
Wood pellets turn inventory fastest through established sawmill residue supply chains, while agricultural residue pellets face longer qualification timelines due to contamination testing protocols.
- Wood Pellets:Manufactured from compressed sawmill residues and forest thinning operations with moisture content below 10% and bulk density exceeding 600 kg per cubic meter. Demand concentrates in German and Scandinavian district heating networks where EU Green Deal phase-out mandates enforce certified biomass procurement. Long-term utility contracts now dominate volume allocation.
- Agricultural Residue Pellets:Produced from straw, rice husk, and other crop residues requiring adapted densification equipment for high-silica feedstocks. Japanese FIT mechanism enforcement of strict chlorine and ash thresholds blocks most current supply, forcing costly washing infrastructure investments at export terminals.
- Biomass Pellets:Blend wood and agricultural fibers for intermediate combustion characteristics.
- Other Feedstock Pellets:Include energy crops and dedicated biomass plantations with limited commercial scale.
Wood pellets anchors the volume base while agricultural residue pellets gains share at the steepest rate.
Application:
Cost tier differentiation separates premium torrefied products for utility co-firing from standard grades serving residential heating markets.
- Residential Heating:Mature, seasonally cyclical segment concentrated in Northern European markets with established stove and boiler infrastructure. Copenhagen and Stockholm municipal operators value dispatchability versus intermittent alternatives.
- Industrial Heating:District heating networks expanding pellet-fired capacity to displace natural gas in combined heat and power configurations. EU carbon border adjustment mechanisms reward documented lifecycle emissions below fossil benchmarks.
- Power Generation:Existing coal units retrofit for biomass co-firing to comply with emissions regulations, attracting fastest capacity additions. Torrefaction processes elevate energy density above standard specifications, reducing shipping costs for transatlantic supply chains.
- Biomass Co-firing:Retrofit installations at coastal power stations in Japan specify upgraded pellets meeting strict contamination limits.
Residential heating commands the widest installed base while power generation climbs the fastest.
End User:
Customer type determines contract structure, with utilities demanding decade-long offtake agreements and residential buyers purchasing through seasonal retail channels.
- Power Plants:European generators seek 10-15 year supply agreements with price escalation clauses indexed to coal and carbon futures. Procurement concentrates among integrated traders with captive terminal capacity rather than standalone producers.
- Heating Facilities:Municipal district heating operators in Germany and Scandinavia prioritize dispatchability and supply security over spot price minimization.
- Industrial Manufacturers:Retain dual-fuel capability, switching between pellets and natural gas based on hub price differentials.
- Residential Consumers:Purchase through established stove and boiler infrastructure concentrated in Northern European markets with pronounced seasonal demand patterns.
Power plants dominate contract value while heating facilities expand most quickly.
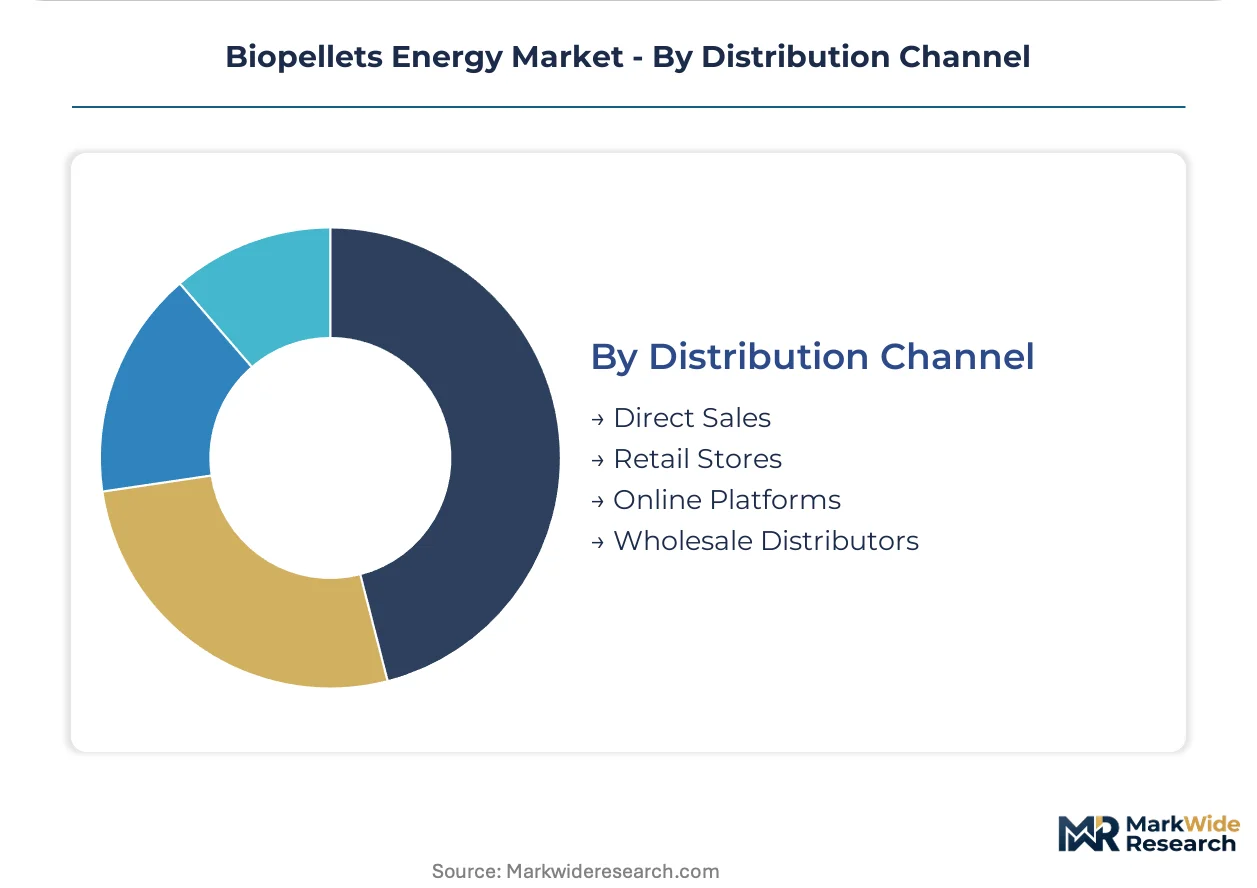
Distribution Channel:
Supply concentration favors direct sales to large utilities, while fragmented residential demand flows through wholesale and retail intermediaries.
- Direct Sales:Long-term offtake contracting displaces spot market liquidity as the dominant transaction mode for utility-scale volumes. Enviva leverages transatlantic export terminal network to sustain supply security.
- Retail Stores:Serve residential heating segment with bagged pellet products through established Northern European stove and boiler supply chains.
- Online Platforms:Emerging channel for residential consumers seeking transparent pricing and delivery scheduling.
- Wholesale Distributors:Aggregate fragmented industrial heat demand across smaller manufacturing facilities lacking direct procurement scale.
Direct sales capture the largest contract values while wholesale distributors reach the broadest customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial heat buyers in Germany and Scandinavia lock in long-term pellet contracts regardless of natural gas price swings, while Japanese utilities enforce strict contamination thresholds that disqualify marginal suppliers. Price elasticity thus fragments sharply across demand centers.
Germany
Coal phase-out auctions under the Kohleausstiegsgesetz compress retrofit timelines for lignite-fired stations. The Bundesnetzagentur monitors biomass co-firing compliance through emissions trading scheme verification. The Rhein-Ruhr industrial corridor hosts multiple district heating conversions from coal to pellet-fired CHP configurations.
Japan
Coastal power stations specify torrefied pellets for 50% co-firing rates without boiler derating. METI's FIT mechanism enforces chlorine and ash thresholds that block agricultural residue imports. The Keihin industrial zone around Tokyo Bay concentrates biomass handling infrastructure investments for transatlantic supply security.
United States
Sawmill residue flows from Southeast lumber operations feed transatlantic export terminal networks. EPA particulate standards govern residential wood heater emissions without restricting industrial utility procurement. The Virginia-North Carolina border region clusters pellet production capacity proximate to Atlantic port facilities.
Sweden
Municipal district heating operators in Stockholm prioritize dispatchable pellet capacity over intermittent alternatives. The EU Green Deal's sustainability criteria mandate geolocation verification for forest biomass chain-of-custody documentation. The Mälaren Lake region integrates pellet storage silos with existing CHP plant infrastructure.
South Korea
Kepco's renewable portfolio standard targets create import demand beyond Japanese and European absorption capacity. The country's national energy regulator certifies biomass eligibility under RPS compliance accounting. The Yeosu industrial complex on the southern coast develops pellet-receiving terminal capacity for utility procurement.
Biopellets Energy Market Competitive Environment
Capability concentration sits with integrated traders commanding captive terminal networks; scale advantage sits with standalone producers locked into sawmill residue catchment areas. The vendor base stratifies across three tiers: transatlantic logistics operators, regional fiber aggregators, and equipment-integrated technology licensors. Dominant competitive moves include backward integration into port handling infrastructure and long-term offtake contracting that displaces spot market liquidity.
Among North American fiber aggregators, Enviva and Pinnacle Renewable Energy exemplify the integrated trader archetype, while Mitsubishi Corporation represents the diversified conglomerate model with procurement-generation asset pairing. These three anchors illustrate how supply security guarantees and sustainability certification capacity determine procurement influence under EU Green Deal and Japanese FIT compliance frameworks.
| Leading Market Players |
|---|
| Enviva |
| Mitsubishi Corporation |
| Weyerhaeuser Company |
| Abellon Clean Energy |
| Biomass Secure Power |
| Curran Renewable |
| Pinnacle Renewable Energy |
| Orsted |
| Pacific BioEnergy |
| Others |
Value Chain & Pricing Dynamics
Transatlantic bulk freight corridors from the US Southeast to Rotterdam and Hamburg anchor cost dynamics that simultaneously concentrate supply around sawmill residue catchments and stratify downstream pricing across certification tiers. Long-term offtake contracts now override spot market liquidity, transferring margin capture from producers to terminal operators who control discharge infrastructure and sustainability verification capacity.
Pricing Analysis
Aftermarket fuel supply contracts drive lifetime value through embedded handling and certification services rather than commodity margin alone. Three-tier pricing structure across premium torrefied, standard ENplus-certified, and economy-grade residential pellets separates utility co-firing procurement from district heating and bagged retail channels. Cost compression in standard-grade supply is intensifying because sawmill residue competition from particleboard manufacturers tightens fiber availability. Industrial heat buyers exhibit lowest price sensitivity due to coal phase-out compliance deadlines, while residential consumers retain seasonal switching elasticity toward natural gas.
Supply Chain Analysis
EU sustainability certification requirements under the Renewable Energy Directive restrict feedstock flows from high-carbon-stock primary forests, limiting eligible supply origins. Production gravity centers on the US Southeast, British Columbia, and the Baltic states, drawing from lumber operation residues and managed forest thinning programs. Raw material dependencies rest on sawmill chip flows, forest harvest residues, and increasingly torrefaction upgrade services. Single-source vulnerability concentrates around the Virginia-North Carolina border production cluster where Atlantic terminal access dominates export capacity. Distribution runs through integrated traders with captive port infrastructure rather than fragmented wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs this market as sustainability certification bodies and terminal operators capture gatekeeper rents previously accruing to fuel producers. Interoperability between ENplus, SBP, and Japan's FIT compliance frameworks determines supplier access across demand centers.
For Market Incumbents: Pre-empt margin erosion by securing backward control over port discharge infrastructure at Rotterdam, Hamburg, and Tokyo Bay. Lock in decade-long offtake agreements with built-in price escalation clauses indexed to carbon futures before new terminal capacity dilutes procurement concentration. Certification investment in dual ENplus-SBP accreditation defends position against emerging traders lacking audit capacity.
For New Entrants and Emerging Players: South Korean RPS compliance markets offer the most penetrable geography as Kepco procurement targets outpace established Japanese and European absorption. Agricultural residue pelletization in India and Southeast Asia remains technically immature, creating equipment-adaptation opportunities for high-silica feedstocks. Partner with European utilities seeking supply diversification beyond transatlantic dependence as the go-to-market angle.
For Investors and Strategic Acquirers: Integrated terminal operators with sustainability certification capacity represent the priority acquisition archetype as gatekeeper economics displace production-scale advantages. Long-term viability across the analysis window hinges on carbon border adjustment alignment and documented lifecycle emissions below fossil benchmarks. Watch for EU CBAM implementation pace as the inflection signal determining feedstock eligibility and market access fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Infrastructure Expansion | Captive discharge capacity at Rotterdam and Hamburg secures EU utility procurement influence under coal phase-out mandates. |
| Torrefaction Technology Licensing | Danish district heating pilots demonstrate 50% co-firing rates without boiler derating, elevating pellet energy density premiums. |
| Dual Certification Program | ENplus-SBP accreditation opens simultaneous access to German district heating and Japanese FIT-compliant utility markets. |
| Agricultural Residue Adaptation | Equipment modifications for high-silica straw and rice husk feedstocks capture first-mover positioning in South Asian supply development. |
| Long-term Offtake Contracting | 10-15 year agreements with price escalation clauses indexed to carbon futures transfer margin from producers to terminal operators. |
Study Parameters
The analysis maps wood pellet, agricultural residue pellet, and torrefied product sub-sectors, each validated through utility procurement officers, terminal operators, sustainability certification auditors, and densification equipment manufacturers. Primary interviews with biomass supply specialists and power generation planners combined with secondary validation from EIA trade data, IEA bioenergy reports, EU-ETS emissions verification records, and FERC export terminal filings. Bottom-up production capacity modeling and top-down demand aggregation from national renewable energy targets provided cross-check triangulation.
Assumptions held fixed include current EU Green Deal phase-out timelines, Japanese FIT contamination thresholds, and existing transatlantic freight rate structures; variables tested across the projection horizon encompass natural gas price volatility, housing construction cycles affecting sawmill residue flows, and South Korean RPS target acceleration. Segmentation dimensions modeled cover product grade tier, application category, end-user contract structure, and regional regulatory framework. CAGRs derived from production capacity buildout schedules against demand absorption curves, with torrefaction adoption rates and carbon border adjustment stringency as key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive terminal capacity expansion by integrated traders or sudden feedstock origin rule changes by the European Commission would shift outcomes. Material shifts in EU CBAM implementation pace, Japanese FIT chlorine threshold enforcement, or South Korean RPS compliance accounting would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Biopower Market
Bioenergy
Organic Biogas Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Bioenergy Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Europe Biogas Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Bio CHP Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Biogas Market
Bioenergy
Biomass Wood Chip Market