
 Micro-Scale Biogas Plant Market | 2026-2036
Micro-Scale Biogas Plant Market Size, Share, and Industry Trends Forecast 2026-2036
Micro-Scale Biogas Plant Market Foresight
Smallholder cooperatives is collapsing as the dominant buyer archetype while commercial farms and food processors gain procurement share. HomeBiogas leverages direct-to-consumer channels across Southeast Asian markets. Agrinz Technologies GmbH anchors Central European project development with turnkey fixed-dome installations. 2G Energy GmbH competes on combined heat and power integration for sub-megawatt biogas streams.
A micro-scale biogas plant converts organic feedstock through anaerobic digestion into methane-rich biogas and digestate fertilizer, typically operating at electrical outputs below 500 kW with hydraulic retention times of 20 to 40 days. Fixed dome digesters dominate rural installations where capital constraints favor masonry construction over steel vessels. Wet fermentation leads technology adoption where manure and food waste supply liquid feedstock profiles. Containerized installations are capturing margin pools in remote commercial sites by cutting civil works and commissioning timelines.
Germany's Federal Network Agency administers EEG tariff tiers that structure revenue certainty for sub-500kW plants, while EU F-Gas Regulation shapes biogas upgrading equipment standards for grid injection. India's MNRE and state nodal agencies channel subsidy capital toward fixed-dome household units under the National Biogas and Manure Management Programme. Stakeholders must weigh feedstock contract duration against tariff reauthorization cycles when sizing project finance.
Market Dynamics
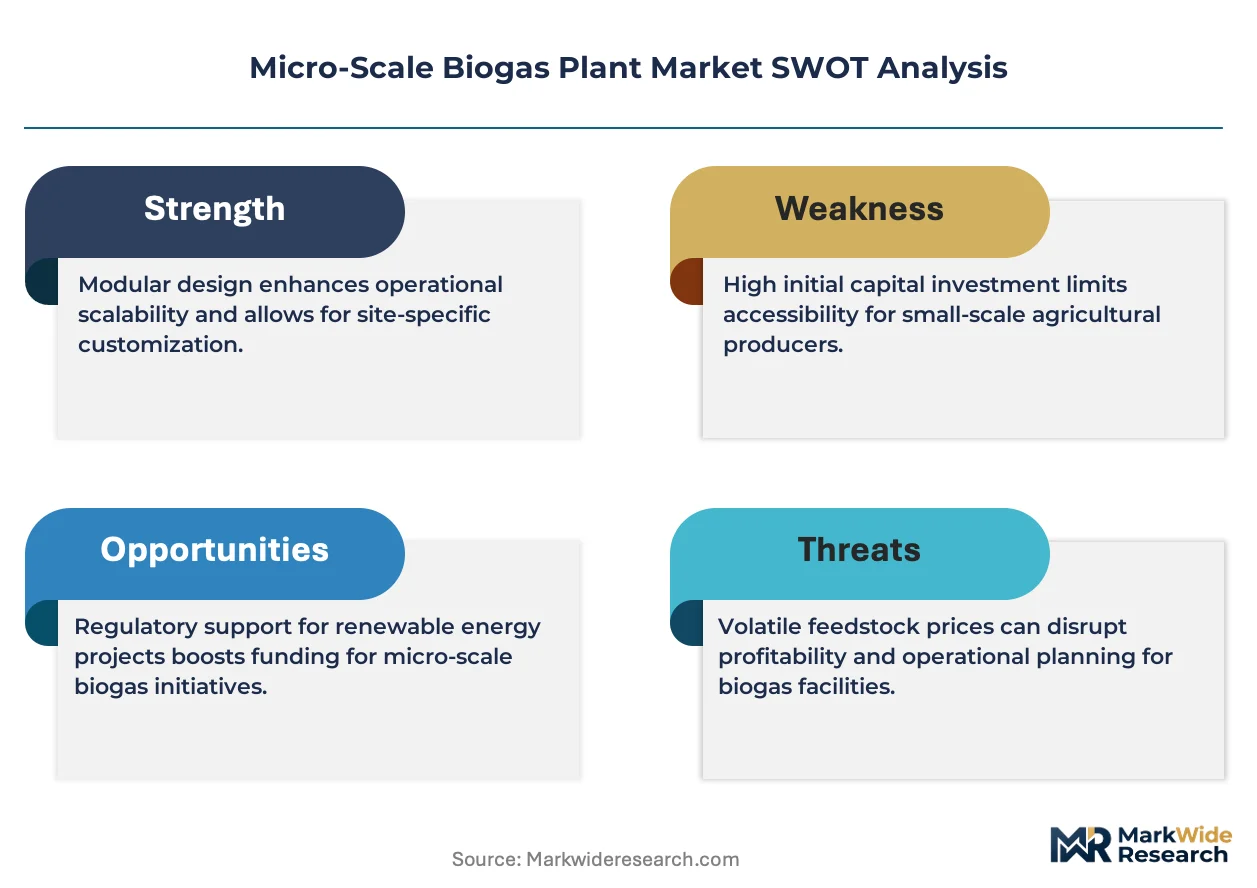
The collapse of smallholder cooperatives as the dominant buyer archetype is forcing technology suppliers to restructure their go-to-market models around commercial farms and food processors with higher throughput requirements and capital access.
Growth Catalysts
- Germany's EEG tariff tiers:The Federal Network Agency's sub-500kW preferential rates create revenue certainty that unlocks project finance for on-farm digestion capacity in Bavaria and other dairy-intensive regions.
- Containerized system design:Prefabricated plug-and-play units cut civil works and commissioning timelines, drawing development finance to remote commercial sites in Kenya's Rift Valley where infrastructure constraints previously blocked deployment.
- EU F-Gas Regulation:Equipment standards for biogas upgrading compress technology costs for grid injection, expanding the addressable market beyond captive heat use into revenue-generating biomethane sales.
Market Restraints
- Feedstock supply volatility:Seasonal manure availability and inconsistent food waste streams from hospitality and retail sectors force operators to overbuild buffer storage or accept reduced plant load factors.
- Steel and polymer input costs:Floating-dome and membrane digesters face margin pressure from commodity price swings in stainless steel and EPDM rubber, materials concentrated in Chinese and German supplier bases.
- Grid interconnection queues:Distribution network operators in high-penetration biogas regions impose technical studies and upgrade cost allocations that extend project timelines beyond feed-in tariff windows.
Strategic Opportunities
- India's National Biogas and Manure Management Programme:MNRE and state nodal agency subsidies for fixed-dome household units create a channel for technology licensors to monetize design IP through local fabrication partnerships.
- Combined heat and power convergence:Integration of sub-megawatt biogas streams with thermal storage and industrial heat off-takers unlocks higher value capture than electricity-only configurations.
- Direct-to-consumer channels in Southeast Asia:HomeBiogas-style compact units for urban households with organic waste access represent an underpenetrated segment bypassing traditional agricultural distributor networks.
Industry Challenges
- Anaerobic digestion microbiology expertise:Process optimization and troubleshooting hydraulic retention times require specialized knowledge scarce in rural installer networks, creating performance gaps between designed and actual biogas yields.
- Digestate certification timelines:Pathogen reduction standards and heavy metal testing for fertilizer market access vary across German Länder and EU member states, complicating equipment specification and sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro-Scale Biogas Plant Market |
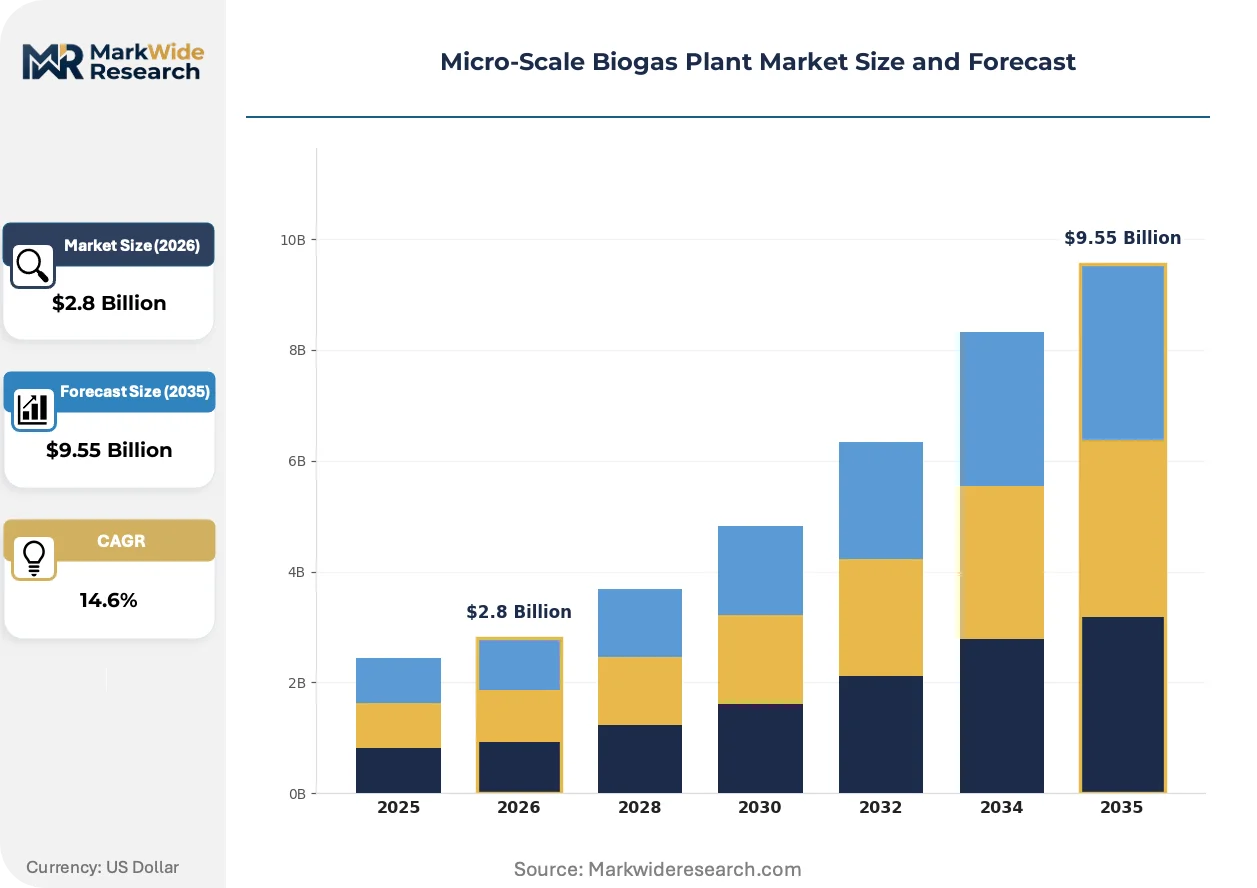
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Dome, Floating Drum, Plug Flow, Batch Type Technology: Dry Fermentation, Wet Fermentation, Anaerobic Digestion, Biogas Upgrading End User: Agriculture, Food Processing, Waste Management, Residential Installation: On-site, Off-site, Containerized, Modular |
| Companies Covered | HomeBiogas, Agrinz Technologies GmbH, 2G Energy AG, BioConstruct GmbH, Naskeo Environnement, AEV Energy GmbH, Schmack Biogas Srl, Bioenergy DevCo, MT-Energie GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro-Scale Biogas Plant Market Shifts & Advancements
Modular system architectures are displacing fixed civil structures across the micro-scale segment, enabling rapid redeployment and reducing site-specific engineering costs that previously consumed 30-40% of project budgets.
Membrane-based biogas upgrading is decomposing the cost barrier between on-farm production and grid injection. Dairy cooperatives in Lower Saxony and Baden-Württemberg are piloting containerized upgrading skids at 150-400 kW scale. This technology is compressing the minimum viable plant size for biomethane revenue by eliminating the capital intensity of pressure swing adsorption or water scrubbing systems.
The EU F-Gas Regulation's phase-down of fluorinated greenhouse gases is tightening equipment specifications for compressors and heat exchangers used in biogas upgrading. Manufacturers are accelerating R&D into magnetic bearing compressors and ammonia-based refrigeration cycles. Sub-500kW plant operators in Denmark and the Netherlands face the steepest compliance curves due to earlier biomethane adoption and denser installed bases.
Food processors are consolidating biogas procurement under centralized sustainability departments rather than site-level engineering teams. This shift compresses vendor evaluation cycles and elevates lifecycle cost modeling over upfront capital expenditure in supplier selection. German meatpacking and dairy processing conglomerates are most advanced in this transition, with multi-site framework agreements replacing individual plant procurements.
Micro-Scale Biogas Plant Market Segmentation
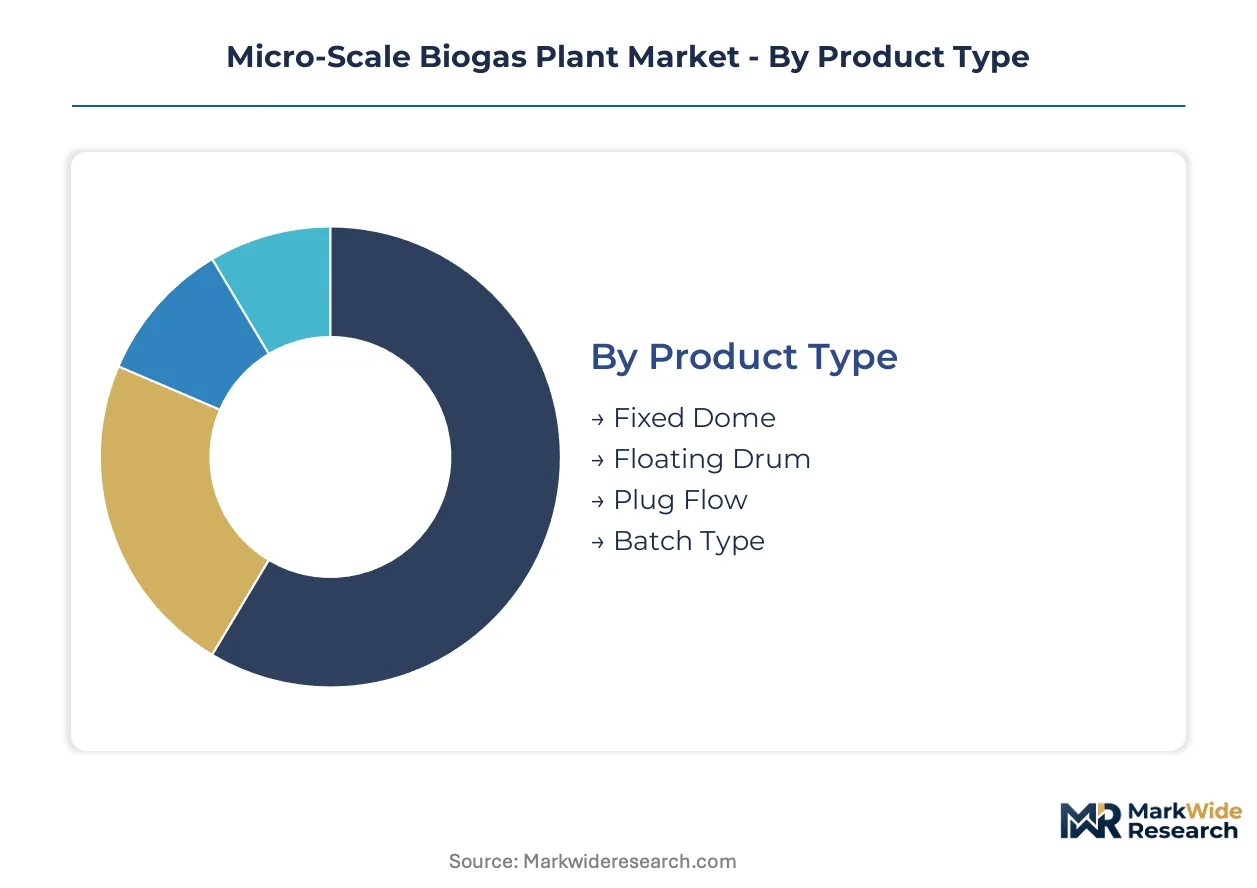
Micro-scale biogas plant segmentation reveals how regulatory frameworks, feedstock profiles, and capital constraints reshape procurement patterns across customer archetypes. Technology suppliers must align product configurations with specific tariff eligibility, microbiology requirements, and site infrastructure to capture margin pools.
Product Type:
Germany's EEG tariff tiers and India's MNRE subsidy schemes create divergent equipment specifications that favor masonry construction in rural subsidy markets and steel vessels where grid injection revenue justifies higher capital intensity.
- Fixed Dome:Masonry construction with integrated gas storage eliminates steel costs and suits capital-constrained rural deployments. Bavarian dairy cooperatives and Indian smallholders under the National Biogas and Manure Management Programme dominate procurement, driven by subsidy eligibility and 20-30 year structural lifespans.
- Floating Drum:Separate gas holder in mild steel or fiberglass enables visible storage monitoring and easier maintenance access. Demand concentrates in Kenya's Rift Valley and Southeast Asian commercial farms where development finance requires proven operational transparency and shorter payback demonstration.
- Plug Flow:Horizontal reactor geometry handles high-solids feedstock with minimal mixing energy.
- Batch Type:Sequential loading suits seasonal agricultural waste streams with intermittent availability.
Fixed Dome handles the majority of throughput; Floating Drum is expanding most quickly on share.
Technology:
Feedstock moisture content and total solids percentage dictate reactor selection, with liquid manure streams favoring wet systems and stackable organics requiring dry fermentation protocols.
- Wet Fermentation:Continuous stirred-tank reactors operate at 10-15% total solids with hydraulic retention times of 20-40 days. Dairy operations in Lower Saxony and Baden-Württemberg anchor demand, leveraging consistent manure supply and EEG tariff certainty for sub-500kW installations.
- Biogas Upgrading:Membrane-based and pressure swing adsorption systems strip CO2 and impurities for grid-injection biomethane. EU F-Gas Regulation compliance costs are compressing technology margins in Denmark and the Netherlands, where dense installed bases face steepest fluorinated gas phase-down curves.
- Dry Fermentation:Batch or garage-style systems process 25-40% total solids without wastewater discharge.
- Anaerobic Digestion:Umbrella term covering all oxygen-excluded microbial decomposition processes.
Wet Fermentation commands the largest installed base; Biogas Upgrading shows the steepest expansion trajectory.
End User:
Procurement authority is migrating from site-level engineering to centralized sustainability departments, compressing vendor evaluation cycles and elevating lifecycle cost modeling.
- Agriculture:Dairy cooperatives and livestock operations with captive manure supply dominate capacity additions. German meatpacking conglomerates are consolidating multi-site framework agreements, replacing individual plant procurements with standardized equipment specifications.
- Food Processing:Slaughterhouses, breweries, and vegetable processors generate homogeneous organic waste streams with predictable energy content. German dairy processing groups lead this transition, embedding biogas into Scope 1 emissions reduction targets.
- Waste Management:Municipal and commercial collection intermediaries aggregate heterogeneous feedstock.
- Residential:Urban households with organic waste access represent an underpenetrated channel bypassing agricultural distributor networks.
Agriculture maintains the deepest deployment footprint; Food Processing is climbing the fastest on procurement share.
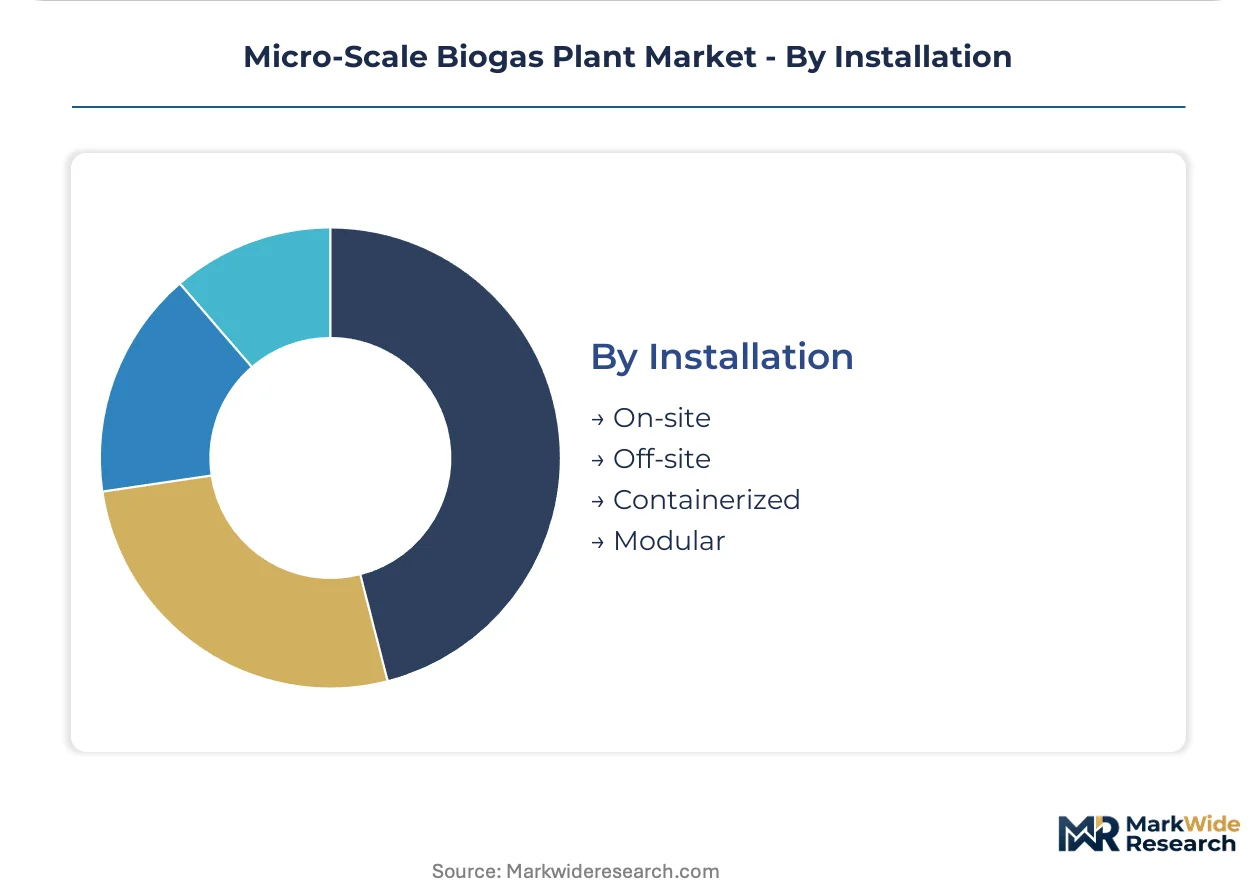
Installation:
Civil works intensity and commissioning timelines determine project finance accessibility, with prefabrication unlocking remote commercial sites previously blocked by infrastructure constraints.
- Containerized:Factory-built skids with integrated controls cut site construction to 2-4 weeks. Kenya's Rift Valley and remote Indonesian palm oil estates are drawing development finance to these configurations, where road access and skilled labor scarcity previously stalled fixed-structure projects.
- Modular:Scalable unit replication enables phased capacity expansion matched to feedstock supply growth. Southeast Asian urban deployment and European farm cluster models favor this approach, allowing operators to validate yields before committing full capital.
- On-site:Permanent civil construction integrated with existing farm or plant infrastructure.
- Off-site:Centralized digestion facilities accepting trucked feedstock from multiple generators.
On-site retains the largest cumulative capacity; Containerized is gaining share fastest where infrastructure gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German technology suppliers export containerized digestion systems to Kenyan commercial farms and Southeast Asian food processors, while Indian fabricators ship fixed-dome units across South Asian subsidy markets. Trade corridors concentrate equipment flows from established manufacturing bases in Central Europe and East Asia toward emerging deployment zones in Sub-Saharan Africa and South Asia.
Germany
Bavarian dairy cooperatives expand on-farm digestion capacity with sub-500kW installations. The Federal Network Agency administers EEG tariff tiers that structure revenue certainty for these plants. Lower Saxony and Baden-Württemberg host pilot containerized upgrading skids at 150-400 kW scale for biomethane grid injection.
India
State nodal agencies channel subsidy capital toward fixed-dome household units under MNRE's National Biogas and Manure Management Programme. The Central Electricity Authority coordinates rural electrification linkages for village-scale plants. Gujarat and Maharashtra concentrate manufacturing partnerships where technology licensors monetize design IP through local fabricators.
Kenya
Development finance flows to containerized systems in the Rift Valley where road access and skilled labor scarcity previously blocked fixed-structure projects. The country's energy regulator issues standardized power purchase agreements for sub-megawatt renewable generators. Commercial farms around Nakuru and Eldoret anchor demand for plug-and-play units with rapid commissioning timelines.
Denmark
Dense installed bases of sub-500kW plants face steep EU F-Gas Regulation compliance curves for biogas upgrading equipment. The Danish Energy Agency enforces fluorinated gas phase-down schedules that accelerate compressor and heat exchanger replacement cycles. Jutland's agricultural cooperatives pilot magnetic bearing compressors and ammonia-based refrigeration cycles.
Indonesia
Remote palm oil estates draw containerized installations that cut civil works requirements on sites with limited infrastructure. The Ministry of Energy and Mineral Resources issues permits for captive power generation from agricultural waste streams. Sumatra and Kalimantan processing clusters represent underpenetrated segments for modular system architectures.
Micro-Scale Biogas Plant Market Competitive Landscape
Listed leaders compete with private specialists across technology integration depth and geographic coverage breadth. The vendor base spans three tiers: multinational energy conglomerates with combined heat and power portfolios, regional turnkey developers anchored in subsidy-driven European markets, and compact system specialists pursuing direct-to-consumer channels in emerging economies. Strategic moves concentrate on technology licensing partnerships for local fabrication and modular platform replication to compress commissioning timelines.
Among German-based system integrators, 2G Energy AG and Agrinz Technologies GmbH exemplify divergent positioning archetypes. HomeBiogas occupies a distinct tier as a direct-to-consumer specialist. These three anchors illustrate how competitive positioning fragments across project-scale engineering, regional turnkey deployment, and compact household units rather than consolidating around unified technology standards or captive distribution networks.
| Leading Market Players |
|---|
| HomeBiogas |
| Agrinz Technologies GmbH |
| 2G Energy AG |
| BioConstruct GmbH |
| Naskeo Environnement |
| AEV Energy GmbH |
| Schmack Biogas Srl |
| Bioenergy DevCo |
| MT-Energie GmbH |
| Others |
Supply & Pricing Matrix
EU F-Gas Regulation certification tiers gate both equipment supplier qualification and price differentiation simultaneously, compressing margins for non-compliant compressor manufacturers while creating premium capture opportunities for ammonia-cycle technology providers serving Danish and Dutch biomethane operators.
Pricing Analysis
Prior-generation fixed-dome masonry systems trade at material-cost-plus benchmarks, current-generation containerized steel vessels command project-finance premiums, and next-generation membrane-upgrading skids extract biomethane revenue shares. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for grid-injection eligibility and after-sales service bundling. Pricing pressure stems from Chinese stainless steel input volatility and EPDM rubber supply constraints. Smallholder cooperatives under India's MNRE subsidy scheme exhibit highest price sensitivity, while German dairy processors with consolidated sustainability procurement show lowest.
Supply Chain Analysis
Inventory lead times for membrane upgrading components stretch 16-24 weeks against 6-10 weeks for standard digestion vessels, compressing working capital for project developers. Manufacturing concentrates in Germany, China, and India. Stainless steel reactor vessels, EPDM gas-holder membranes, and magnetic-bearing compressors constitute critical input dependencies. Single-source vulnerability runs through German precision compressor suppliers. Distribution runs through regional EPC contractors with local fabrication partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer archetype fragmentation—collapsing smallholder cooperatives against ascending commercial farms and food processors—creates addressable niches for differentiated technology configurations and go-to-market models.
For Market Incumbents: Fortify position through backward integration into stainless steel vessel manufacturing and captive membrane upgrading technology development. Containerized system specialists from Kenya's Rift Valley and Southeast Asian channels represent emerging competitive threats requiring pre-emptive certification investment in EU F-Gas Regulation compliance tiers.
For New Entrants and Emerging Players: Anchor in India's fixed-dome household segment under MNRE subsidy channels, where local fabrication partnerships monetize design IP without capital-intensive manufacturing scale. Direct-to-consumer urban household units across Southeast Asian markets offer parallel white-space with HomeBiogas-proven demand validation and distributor-bypass economics.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized system architectures, enabling asset-light platform replication. Long-term viability favors technology licensors with modular IP and regional fabrication networks over steel-heavy vessel manufacturers. Watch German Federal Network Agency EEG tariff reauthorization cycles as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | MNRE subsidy access in India requires local fabrication alliances with Gujarat and Maharashtra manufacturers. |
| Containerized Platform Replication | Kenya's Rift Valley development finance flows to rapid-commissioning units cutting civil works timelines. |
| Backward Integration into Membranes | EU F-Gas Regulation compliance compresses third-party compressor margins for Danish upgrading operators. |
| Biomethane Grid Injection Certification | German EEG tariff tiers structure revenue certainty for sub-500kW plants in Bavarian dairy cooperatives. |
| Direct-to-Consumer Channel Buildout | Southeast Asian urban households bypass agricultural distributor networks with compact household units. |
Research Methodology
A standing panel of biogas project developers, dairy cooperative energy officers, MNRE state nodal agency administrators, containerized system EPC contractors, and biogas upgrading equipment procurement managers provided ongoing calibration. Primary interview intelligence combined with secondary validation from EEG tariff filings at Bundesnetzagentur, MNRE subsidy disbursement records, Kenya Energy Regulatory Authority standardized PPA documentation, and EU F-Gas Regulation compliance registries. Bottom-up installation capacity tracking triangulated against top-down feedstock availability modeling.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include digester product type, fermentation technology, end-user industry, and installation configuration against regional regulatory framework clusters. CAGRs derived from segment-level capacity buildout trajectories and tariff reauthorization cycle assumptions. Forecast inputs incorporated EEG tariff tier stability probability and MNRE subsidy allocation continuity.
Decision-makers should treat outputs as directional under sustained EEG sub-500kW preferential rates and MNRE fixed-dome subsidy continuity; material deviation in either would warrant model refresh. Specific risk factors include German feed-in tariff reauthorization delays, Indian state-level subsidy allocation volatility, and EU F-Gas Regulation phase-down acceleration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Biogas Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Biopower Market
Bioenergy
Biopellets Energy Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Bioenergy Market
Bioenergy
Organic Biogas Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Europe Biogas Market
Bioenergy
Bio CHP Market
Bioenergy
Biomass Wood Chip Market