
 Global Biomass Briquette Market | 2026-2036
Global Biomass Briquette Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biomass Briquette Market Foresight
Multi-source feedstock procurement is expanding across the biomass briquette industry as producers hedge against seasonal agricultural residue shortages. Enviva leverages its port-terminal network to sustain transatlantic supply chains for utility-grade wood briquettes. Drax Group anchors its procurement strategy around dedicated pellet and briquette offtake contracts with North American forest products suppliers. ECOSTAN Biofuel differentiates through integrated drying and densification equipment that controls upstream processing costs for small-scale operators.
Biomass briquettes are compressed blocks of organic material, typically densified to 1,000–1,400 kg/m³ through mechanical extrusion or piston pressing, and serve as standardized solid fuel for controlled-combustion systems. Their primary purpose is to convert low-bulk-density agricultural and forestry residues into transportable, uniform fuel with predictable calorific values and moisture content below 10 percent. Wood briquettes occupy the dominant share of industrial offtake due to consistent combustion properties and established supply chains from managed forestry. Agricultural residue briquettes represent the fastest-expanding product category as rice husk and straw densification spreads across South and Southeast Asian processing clusters. Sawdust briquettes concentrate margin pools in regions with captive sawmill waste streams, particularly where furniture and construction panel manufacturing generates predictable feedstock flows.
The EU Green Deal and F-Gas Regulation are tightening emission thresholds for solid biomass combustion, forcing briquette producers toward certified sustainable sourcing under ECHA-aligned frameworks. India's MNRE biomass mission and BIS fuel quality standards are mandating calorific minimums and ash-content ceilings for industrial briquette supply to power and thermal applications. Stakeholders must monitor how carbon-border adjustment mechanisms and feedstock traceability requirements reshape sourcing economics and certification burdens across export markets.
Market Dynamics
The EU Green Deal's tightening emission thresholds for solid biomass combustion are forcing producers toward certified sustainable sourcing under ECHA-aligned frameworks, compressing margins for uncertified suppliers while rewarding traceable supply chains.
Growth Catalysts
- Renewable heat mandates:The EU Green Deal mandates emission reductions across industrial thermal applications, pulling power generation utilities in Germany toward wood briquette baseload substitution.
- Indonesia's industrial estates:Captive boiler demand from food processing clusters concentrates procurement of palm kernel shell briquettes for thermal energy self-sufficiency.
- BIS fuel quality standards:India's MNRE biomass mission mandates calorific minimums and ash-content ceilings, standardizing industrial briquette supply to power and thermal sectors.
Market Restraints
- Seasonal agricultural residue shortages:Rice husk and straw availability fluctuates with harvest cycles, forcing producers to maintain costly multi-source feedstock buffers.
- Carbon-border adjustment exposure:Emerging EU CBAM mechanisms threaten export economics for uncertified Asian producers lacking ECHA-aligned traceability systems.
- Natural gas price volatility:Fossil fuel price swings distort briquette competitiveness in dual-fuel industrial boilers, particularly in European district heating networks.
Strategic Opportunities
- Vietnam's underpenetrated industrial zones:Food and textile manufacturing clusters lack dedicated briquette supply infrastructure, creating first-mover positioning for integrated producers.
- Carbon credit monetization:Verified emission reduction frameworks under ISO 14064 enable premium pricing for briquettes displacing coal in captive power applications.
- Smart densification systems:Integration of IoT-enabled moisture control with mechanical piston pressing is reducing upstream processing losses for small-scale operators.
Industry Challenges
- Certification timeline compression:ECHA-aligned sustainable sourcing audits require 12-18 month validation cycles, delaying market access for new export entrants.
- Feedstock quality heterogeneity:Variable lignin content across rice husk, straw, and sawdust streams complicates combustion calibration for utility offtakers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biomass Briquette Market |
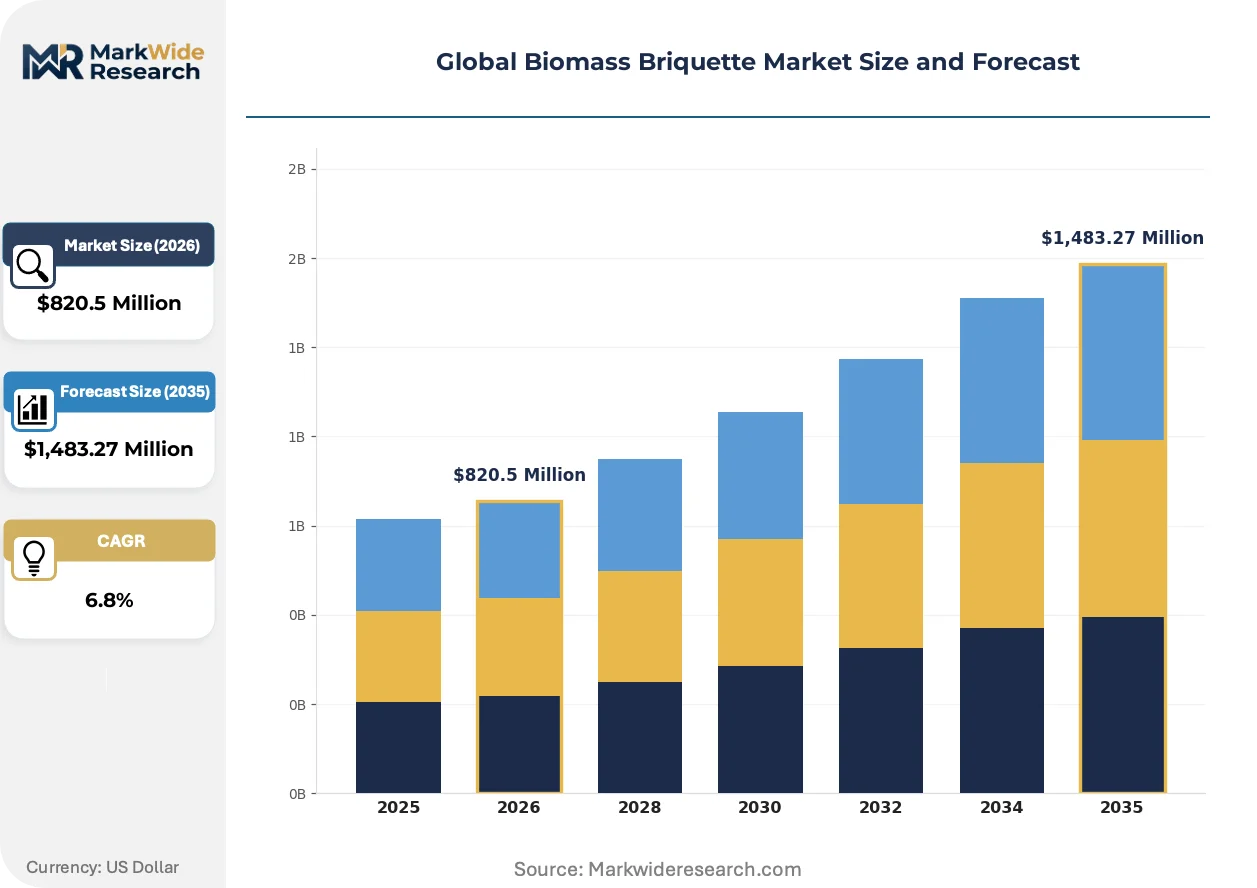
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $1,483.27 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wood Briquettes, Agricultural Residue Briquettes, Sawdust Briquettes, Grass Briquettes, Coconut Shell Briquettes Application: Power Generation, Industrial Heating, Domestic Cooking, Commercial Heating, Agricultural Drying End User: Manufacturers, Food Processing Units, Energy Plants, Hospitality Sector, Residential Consumers Distribution Channel: Direct Sales, Online Platforms, Dealers & Distributors, Retail Outlets, Industrial Suppliers |
| Companies Covered | Premium Pellet Ltd., Biomass Secure Power Inc., Enviva, RUF US, Inc, ECOSTAN Biofuel, Drax Group, BIOMAC Energy Ltd, Lignetics, Inc., Pinnacle Renewable Energy Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biomass Briquette Market Shifts & Advancements
Mechanical densification technologies and digital traceability systems are compressing supply chain opacity while enabling smaller producers to access utility-grade procurement channels previously reserved for integrated forest products suppliers.
Modular containerized briquetting units are decentralizing production economics by enabling feedstock processing at agricultural collection points rather than centralized mills. Rice mill cooperatives in South India are deploying these systems to eliminate double-handling costs. This distributed model is decentralizing margin capture toward farm-gate operators and reducing transport losses for high-moisture residues.
REACH-aligned chemical safety assessments are tightening substance restrictions in briquette binding agents and combustion additives. Producers reformulating with lignin-based natural binders face reformulation costs but gain EU market access. Wood briquette categories face the steepest compliance burden due to established export volumes into German and Dutch district heating networks.
Industrial buyers are consolidating supplier relationships around multi-year offtake contracts with embedded sustainability certification requirements. Food processing clusters in Indonesia are replacing spot-market procurement with dedicated supply agreements. This concentration is visible most acutely in Java's integrated industrial estates where captive boiler operators demand guaranteed calorific consistency.
Global Biomass Briquette Market Segmentation
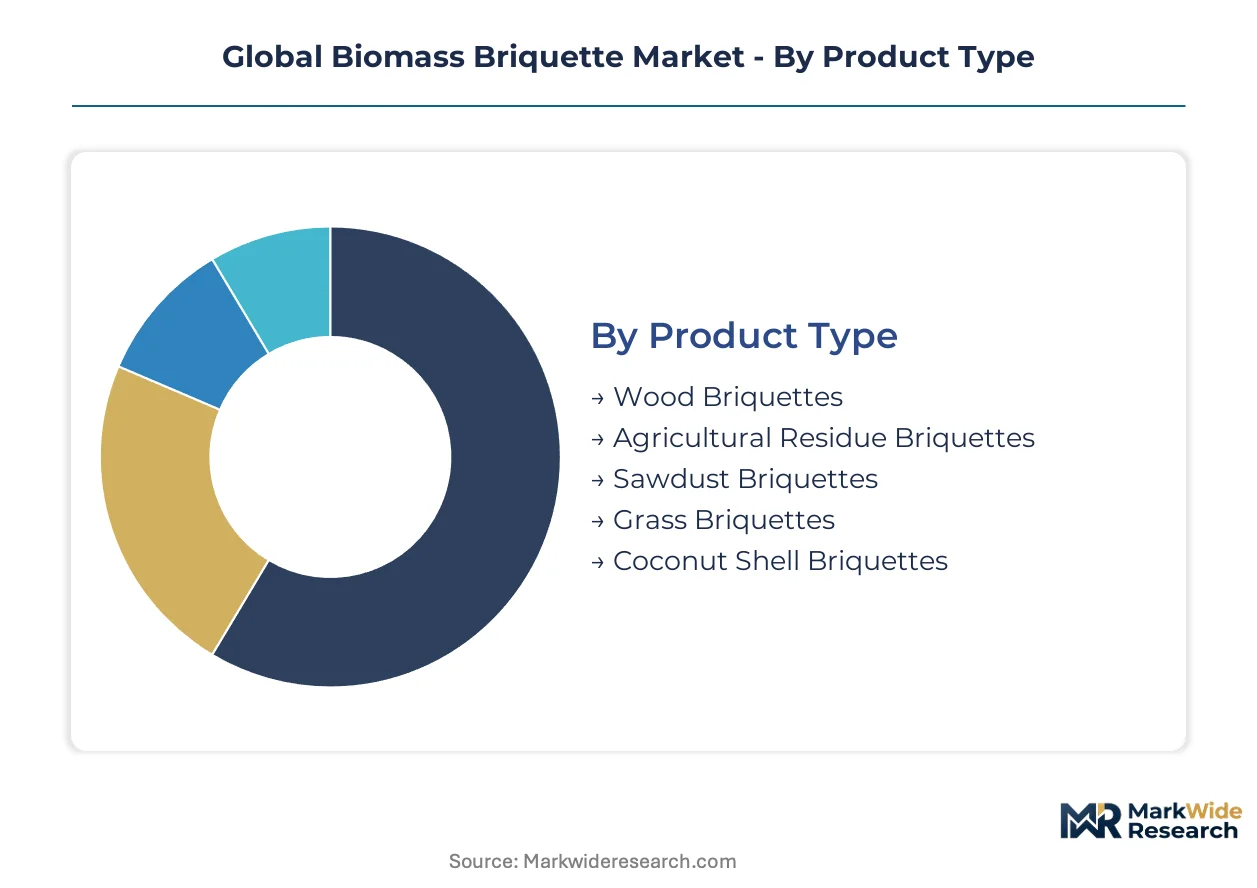
Segmentation in biomass briquettes exposes divergent certification burdens across product categories, with wood-derived fuels facing ECHA-aligned sustainability audits while agricultural residues navigate BIS calorific mandates in India. Application-based segmentation reveals how power generation utilities demand ISO-compliant traceability systems that domestic cooking segments rarely require.
Product Type:
Wood briquettes carry the heaviest ECHA-aligned certification burden due to established export volumes into German and Dutch district heating networks, while agricultural residue categories face variable BIS standards across South Asian markets.
- Wood Briquettes:Densified blocks from managed forestry residues achieve 1,000–1,400 kg/m³ through mechanical extrusion, delivering sub-10% moisture content. German power generation utilities anchor procurement of utility-grade volumes under EU Green Deal emission thresholds, compressing margins for uncertified suppliers.
- Agricultural Residue Briquettes:Rice husk and straw densification spreads across South and Southeast Asian processing clusters, with India's MNRE biomass mission mandating calorific minimums and ash-content ceilings. Indonesia's food processing estates concentrate demand for palm kernel shell derivatives in captive boiler applications.
- Sawdust Briquettes:Captive sawmill waste streams in furniture and construction panel manufacturing regions generate predictable feedstock flows with concentrated margin pools.
- Grass Briquettes:Seasonal availability constraints limit commercial scale, with scattered demand from rural heating cooperatives in Central European markets.
- Coconut Shell Briquettes:South Indian and Sri Lankan processors leverage shell carbonization byproducts for industrial thermal applications requiring high fixed-carbon content.
Wood briquettes sit at the top of the volume ranking, with agricultural residue briquettes climbing the fastest.
Application:
Cost tier differentiation separates premium-certified power generation supply from economy-grade domestic cooking segments, with industrial heating occupying the mid-tier certification zone.
- Power Generation:Baseload fuel substitution in German utilities demands ECHA-aligned traceability and ISO 14064 carbon credit frameworks, enabling premium pricing for coal displacement.
- Industrial Heating:Captive boilers in Indonesia's integrated industrial estates require guaranteed calorific consistency, driving multi-year offtake contracts with embedded sustainability requirements.
- Domestic Cooking:Rural South Asian markets prioritize cost over certification, with minimal regulatory burden beyond basic BIS fuel quality standards.
- Commercial Heating:European district heating networks source certified wood briquettes under EU Green Deal renewable heat mandates.
- Agricultural Drying:Rice mill cooperatives in South India deploy modular containerized briquetting units for thermal energy self-sufficiency.
Power generation commands the highest certification investment per tonne, with industrial heating showing the steepest contract concentration.
End User:
Customer type determines procurement sophistication, with energy plants and food processing units demanding traceable supply chains that residential consumers rarely enforce.
- Manufacturers:Industrial thermal users in Vietnam's underpenetrated food and textile zones lack dedicated briquette infrastructure, creating positioning opportunities for integrated producers.
- Food Processing Units:Java's integrated industrial estates replace spot-market procurement with dedicated supply agreements requiring guaranteed calorific consistency.
- Energy Plants:Drax Group anchors procurement around pellet and briquette offtake contracts with North American forest products suppliers.
- Hospitality Sector:Commercial heating demand in European hospitality clusters prioritizes certified wood briquettes for emission compliance.
- Residential Consumers:Price-sensitive rural markets in South Asia drive demand for uncertified agricultural residue briquettes.
Energy plants lead procurement volume, with food processing units expanding most quickly.
Distribution Channel:
Supply concentration varies sharply by channel, with direct sales capturing utility-grade volumes and online platforms fragmenting retail access.
- Direct Sales:Multi-year offtake contracts with embedded sustainability certification requirements dominate utility and industrial procurement, particularly in German power generation.
- Online Platforms:E-commerce penetration remains limited to premium-certified segments in European markets, with minimal traction in bulk industrial supply.
- Dealers & Distributors:Regional networks aggregate small-scale producer output across South Asian agricultural residue markets.
- Retail Outlets:Urban European channels stock certified wood briquettes for commercial and residential heating segments.
- Industrial Suppliers:Integrated port-terminal networks like Enviva's sustain transatlantic supply chains for utility-grade volumes.
Direct sales capture the largest contract value, with industrial suppliers gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German power generation utilities anchor the largest procurement volumes for utility-grade wood briquettes, with EU Green Deal renewable heat mandates tightening emission thresholds across industrial thermal applications. The analysis spans five countries where feedstock availability, regulatory frameworks, and industrial demand patterns create distinct market configurations.
Germany
Baseload fuel substitution in district heating networks and power generation utilities drives wood briquette procurement, with ECHA-aligned sustainability certification mandatory for export-grade supply. The EU Green Deal's F-Gas Regulation and renewable heat mandates compress margins for uncertified suppliers. The Ruhr industrial corridor and Bavarian manufacturing clusters concentrate demand from captive boiler operators seeking emission-compliant thermal fuel.
Indonesia
Palm kernel shell briquettes feed captive boilers at food processing estates seeking thermal energy self-sufficiency, with demand concentrating in Java's integrated industrial zones. The country's national energy regulator enforces emission standards for industrial biomass combustion. Surabaya and Jakarta's manufacturing corridors are replacing spot-market procurement with multi-year offtake contracts requiring guaranteed calorific consistency.
India
Rice husk and straw densification spreads across South Asian processing clusters, with MNRE biomass mission mandates enforcing BIS fuel quality standards for calorific minimums and ash-content ceilings. Tamil Nadu and Punjab's rice mill cooperatives deploy modular containerized briquetting units to eliminate double-handling costs and achieve thermal energy self-sufficiency for agricultural drying operations.
United States
Transatlantic supply chains for utility-grade wood briquettes sustain through integrated port-terminal networks, with EPA emission standards governing industrial biomass combustion. The Southeast's managed forestry regions and Pacific Northwest sawmill clusters generate predictable feedstock flows. Drax Group anchors procurement around dedicated pellet and briquette offtake contracts with North American forest products suppliers.
Vietnam
Food and textile manufacturing clusters lack dedicated briquette supply infrastructure, creating first-mover positioning for integrated producers targeting captive boiler applications. The country's national standards body implements fuel quality specifications for industrial biomass supply. Ho Chi Minh City's industrial zones and Hanoi's manufacturing corridors present underpenetrated demand from thermal energy users seeking alternatives to volatile natural gas pricing.
Global Biomass Briquette Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular containerized systems and farm-gate densification models. The market structures around integrated forest products suppliers with captive feedstock access, equipment manufacturers selling upstream processing technology, and regional aggregators consolidating small-scale agricultural residue output. Three archetypes dominate: transatlantic utility-grade suppliers with port-terminal networks, Asian agricultural residue processors with cooperative feedstock arrangements, and European equipment specialists controlling densification technology. Competitive moves concentrate on multi-year offtake contracting with embedded certification requirements and backward integration into managed forestry or agricultural collection networks.
Within the integrated supplier tier, Enviva and Drax Group represent transatlantic utility-grade archetypes with established procurement channels into European district heating networks. ECOSTAN Biofuel exemplifies the equipment-integrated model, occupying a position among upstream technology providers serving small-scale operators. These three anchors illustrate how feedstock control, certification systems, and processing technology separate competitive positions across the value chain.
| Leading Market Players |
|---|
| Premium Pellet Ltd. |
| Biomass Secure Power Inc. |
| Enviva |
| RUF US, Inc |
| ECOSTAN Biofuel |
| Drax Group |
| BIOMAC Energy Ltd |
| Lignetics, Inc. |
| Pinnacle Renewable Energy Inc. |
| Others |
Supply & Pricing Matrix
Mechanical densification technology adoption is compressing production costs for small-scale operators while simultaneously fragmenting supply concentration toward farm-gate processing nodes. This shift redistributes margin capture away from centralized mill operators and enables agricultural cooperatives to command pricing power previously reserved for integrated forest products suppliers.
Pricing Analysis
Input-cost pass-through from feedstock procurement dominates pricing dynamics, with seasonal rice husk and straw shortages forcing producers to absorb buffer stock carrying costs. Three-tier pricing structure across premium-certified, standard-industrial, and economy-domestic levels separates power generation utilities from food processing estates from rural cooking markets. Pricing pressure stems from EU CBAM exposure threatening export economics for uncertified Asian producers. Residential consumers in South Asian markets exhibit highest price sensitivity, while German district heating networks accept certified premiums.
Supply Chain Analysis
Regional distribution centers in Germany, Indonesia, and India anchor hub-and-spoke patterns for utility-grade and industrial volumes. Raw material flows draw from managed forestry residues in North America, palm kernel shell streams in Southeast Asia, and rice husk cooperatives in South India. Single-source vulnerability concentrates in transatlantic shipping lanes serving European power generation. Distribution runs through direct sales channels for multi-year offtake contracts and industrial supplier networks for bulk utility procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Green Deal's renewable heat mandates compound demand growth by mandating emission reductions across industrial thermal applications, creating regulatory tailwinds for certified biomass fuel suppliers.
For Market Incumbents: Deepen backward integration into managed forestry and agricultural collection networks to secure feedstock buffers against seasonal shortages. Lock in multi-year offtake contracts with embedded ECHA-aligned certification requirements before CBAM mechanisms fully activate. Prioritize certification investment as the defensive lever against margin compression from uncertified competitors. For New Entrants and Emerging Players: Rice mill cooperatives represent the most penetrable channel partner type for modular containerized briquetting deployment. Target Vietnam's underpenetrated food and textile manufacturing clusters where captive boiler infrastructure remains undeveloped. Pursue farm-gate densification partnerships as the go-to-market angle, eliminating double-handling costs for high-moisture residues. For Investors and Strategic Acquirers: Valuations sit cheapest among equipment-integrated upstream technology providers serving small-scale operators. Long-term viability frames around carbon credit monetization and ISO 14064 framework adoption across the projection horizon. Acquisition target archetype: Asian agricultural residue processors with cooperative feedstock arrangements and latent certification capacity. Watch CBAM implementation pace as the inflection signal for export market access restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Networks | Enviva's port-terminal network demonstrates how captive supply secures transatlantic utility contracts. |
| ECHA-Aligned Certification Investment | Drax Group's dedicated offtake contracts require traceable sourcing under EU Green Deal thresholds. |
| Modular Containerized Deployment | Tamil Nadu rice mill cooperatives eliminate double-handling costs through distributed farm-gate processing. |
| Multi-Year Offtake Contracting | Java's industrial estates replace spot procurement with guaranteed calorific consistency agreements. |
| Carbon Credit Monetization | ISO 14064 frameworks enable premium pricing for coal displacement in captive power applications. |
Research Methodology
Direct dialogue with briquette plant managers, utility procurement officers at German power generation firms, agricultural cooperative leaders in South India, and EPC contractors specializing in biomass boiler installations grounded qualitative insights. Secondary validation drew from EU ECHA sustainability framework documentation, EPA emission standard filings, BIS fuel quality specifications, and customs trade data for biomass fuel shipments. Bottom-up feedstock flow modeling and top-down demand aggregation from industrial estate energy consumption data provided triangulation.
Bottom-up volume modeling tracked densification capacity deployment across five product categories and five end-use applications, while top-down validation calibrated against national renewable heat mandate targets. Segmentation dimensions spanned feedstock source, combustion application, certification tier, and regional regulatory cluster. CAGRs derived from compound growth trajectory analysis against baseline market sizing. Industry-specific forecast inputs incorporated EU CBAM phase-in schedules and MNRE biomass mission implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon-border adjustment mechanism coverage expansion and feedstock traceability system adoption rates. Outputs reflect documented assumptions regarding regulatory enforcement continuity and industrial energy demand patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Europe Bioenergy Market
Bioenergy
Biopellets Energy Market
Bioenergy
Organic Biogas Market
Bioenergy
Bio CHP Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Biopower Market
Bioenergy
Europe Biogas Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Biogas Market
Bioenergy
Bioenergy Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Biomass Wood Chip Market