
 Bio CHP Market | 2026-2036
Bio CHP Market Size, Share, and Industry Trends Forecast 2026-2036
Bio CHP Market Intelligence
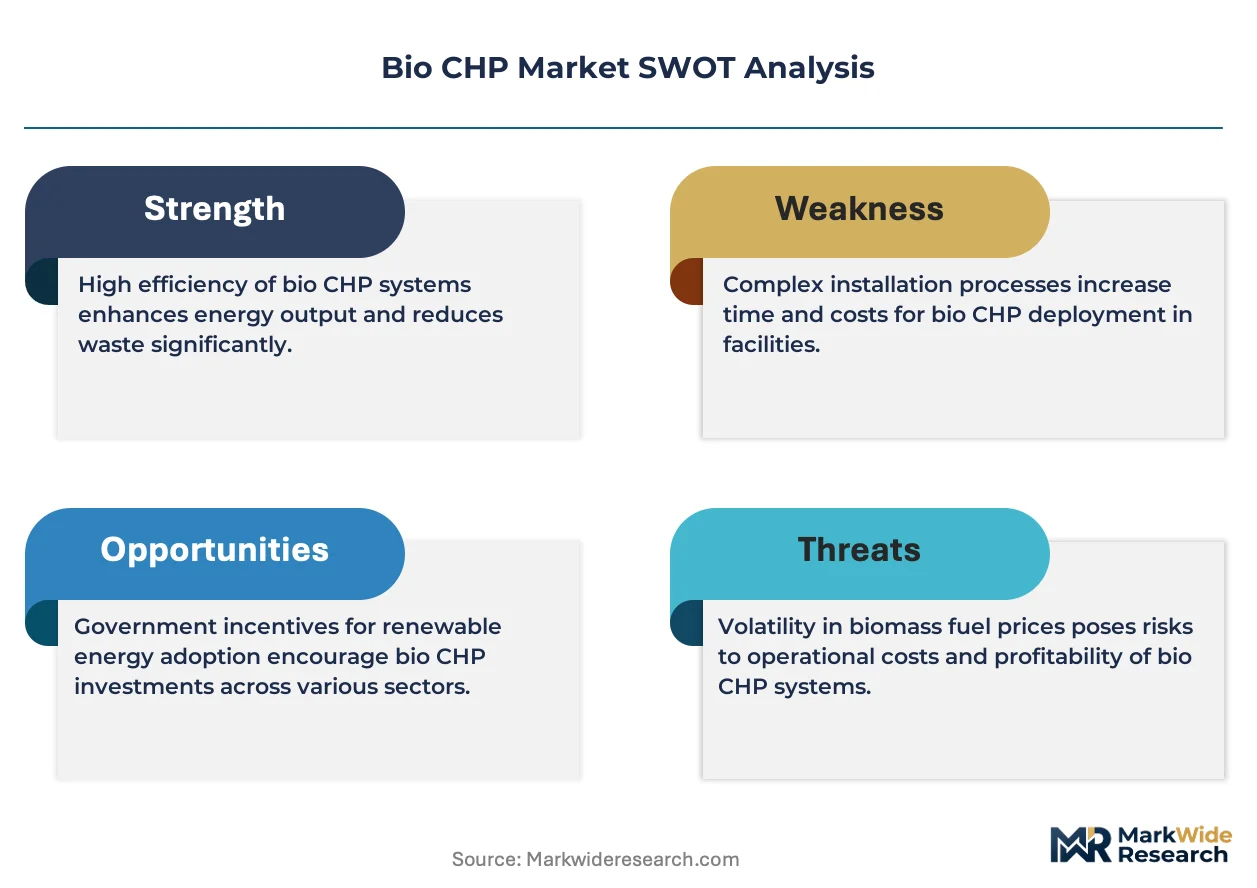
A shortage of certified biomass boiler technicians is redrawing deployment timelines across the Bio CHP sector. GE Vernova leverages its gas turbine heritage to anchor large-scale biogas projects in North America. 2G Energy AG specializes in modular gas engine CHP units that dominate agricultural waste-to-energy applications in Europe.
Bio combined heat and power denotes integrated systems that generate electricity and useful thermal energy from organic feedstocks through combustion, gasification, or anaerobic digestion, typically achieving total efficiency above 80 percent. Gas engines lead installed capacity due to maturity and fuel flexibility, while organic Rankine cycle systems represent the fastest-expanding product category for low-grade waste heat recovery. District heating captures the dominant application share in Nordic markets, whereas industrial manufacturing applications concentrate margin pools through long-term power purchase agreements.
The EU Green Deal and F-Gas Regulation shape equipment specifications and refrigerant choices across European installations, while the EPA's renewable fuel standards influence biogas qualification in the United States. Germany's Federal Emission Control Act mandates minimum efficiency thresholds that filter out subscale project developers. Stakeholders must monitor feedstock price volatility and evolving carbon border mechanisms to calibrate capacity expansion decisions.
Market Dynamics
The EU Green Deal's renewable heat mandates are compressing deployment timelines across European Bio CHP installations, forcing developers to secure certified biomass technicians and upgrade legacy equipment before subsidy windows close.
Growth Catalysts
- EU Green Deal renewable heat targets:Member states must quadruple renewable heating by 2030, accelerating district heating network procurement of biogas-fueled CHP systems in Germany, Denmark, and Sweden.
- Agricultural waste valorization:Dairy and poultry operations in Northern Europe are installing modular gas engine units to convert manure and silage into baseload power and process heat.
- Organic Rankine cycle maturation:Low-grade waste heat recovery from industrial processes is expanding addressable market for sub-megawatt installations previously excluded from project economics.
Market Restraints
- Certified technician scarcity:Germany's Federal Emission Control Act mandates qualified personnel for all biomass boiler maintenance, but training pipeline output lags installation growth by approximately 40 percent.
- Feedstock price volatility:Wood pellet and agricultural residue costs fluctuate with harvest yields and competing industrial demand, eroding power purchase agreement margins for independent power producers.
- Grid interconnection queues:Utility-scale biogas projects face 18-36 month delays for distribution network upgrades in saturated renewable zones of Denmark and Southern Sweden.
Strategic Opportunities
- Industrial cluster heat networks:Chemical and food processing parks in the Netherlands and Belgium are tendering centralized bio-CHP to replace aging natural gas boilers under carbon reduction commitments.
- Carbon border adjustment alignment:Export-oriented manufacturers in Germany are installing on-site bio-CHP to document Scope 1-2 emissions reductions and preserve EU market access for energy-intensive goods.
- Biogas upgrading integration:Co-located biomethane injection and power generation assets allow developers to arbitrage between wholesale electricity and renewable natural gas certificate markets.
Industry Challenges
- Gas engine maintenance specialization:Agricultural cooperatives lack in-house expertise for scheduled overhauls of Jenbacher and MWM engines, forcing reliance on OEM service contracts with 6-8 week lead times.
- F-Gas refrigerant compliance:The EU F-Gas Regulation is phasing down high-GWP working fluids in organic Rankine cycle systems, requiring engineering retrofits or equipment replacement for installed base.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio CHP Market |
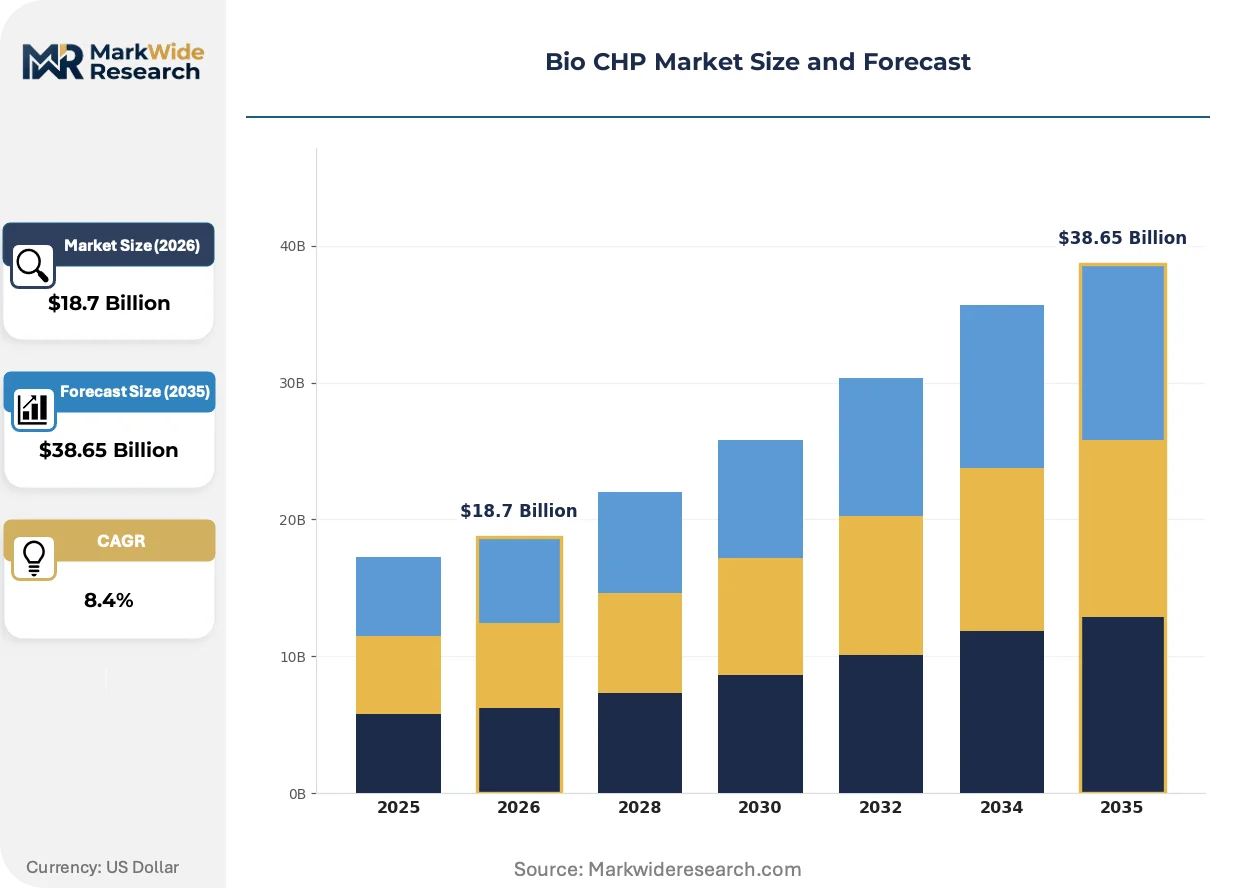
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gas Engines, Steam Turbines, Organic Rankine Cycle, Microturbines, Fuel Cells Fuel Type: Biogas, Biomass, Bioethanol, Biodiesel, Landfill Gas, Agricultural Waste Application: District Heating, Combined Cooling Heating Power, Industrial Manufacturing, Greenhouses, Commercial Buildings End User: Food Processing Units, Chemicals Production, Data Centers, Educational Institutions, Hospitality Venues |
| Companies Covered | Fleetsolve, GE Vernova, 2G Energy AG, Mitsubishi Heavy Industries, Veolia, Wärtsilä, Siemens Energy, H3CHP, Enexor BioEnergy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio CHP Market Strategic Shifts & Innovations
Equipment specifications across the Bio CHP sector are tightening around efficiency thresholds and refrigerant chemistry, while procurement patterns shift toward bundled energy service contracts that transfer operational risk from facility owners to technology providers.
Organic Rankine cycle systems using siloxane-based working fluids are supplanting traditional steam turbines in low-temperature waste heat applications below 300°C. Pulp and paper mills in Finland and Sweden are retrofitting ORC modules onto lime kiln exhaust streams. This technology is supplanting capital-intensive steam bottoming cycles and opening sub-5 MW projects to smaller industrial operators previously priced out of CHP economics.
The EU F-Gas Regulation's phasedown schedule is forcing refrigerant transitions across ORC and heat pump-integrated CHP installations. Equipment manufacturers must recertify systems using hydrofluoroolefin blends or natural refrigerants before 2027. German and Danish project developers are front-loading procurement decisions to secure grandfathered equipment or lock in engineering resources for compliant redesigns.
Energy-as-a-service contracts now dominate municipal and industrial procurement for bio-CHP above 2 MW electrical output. Facility owners transfer fuel supply, maintenance, and performance risk to specialized operators in exchange for fixed thermal and power tariffs. This model concentrates most visibly in Netherlands district heating concessions and German chemical park energy supply tenders.
Bio CHP Market Segmentation
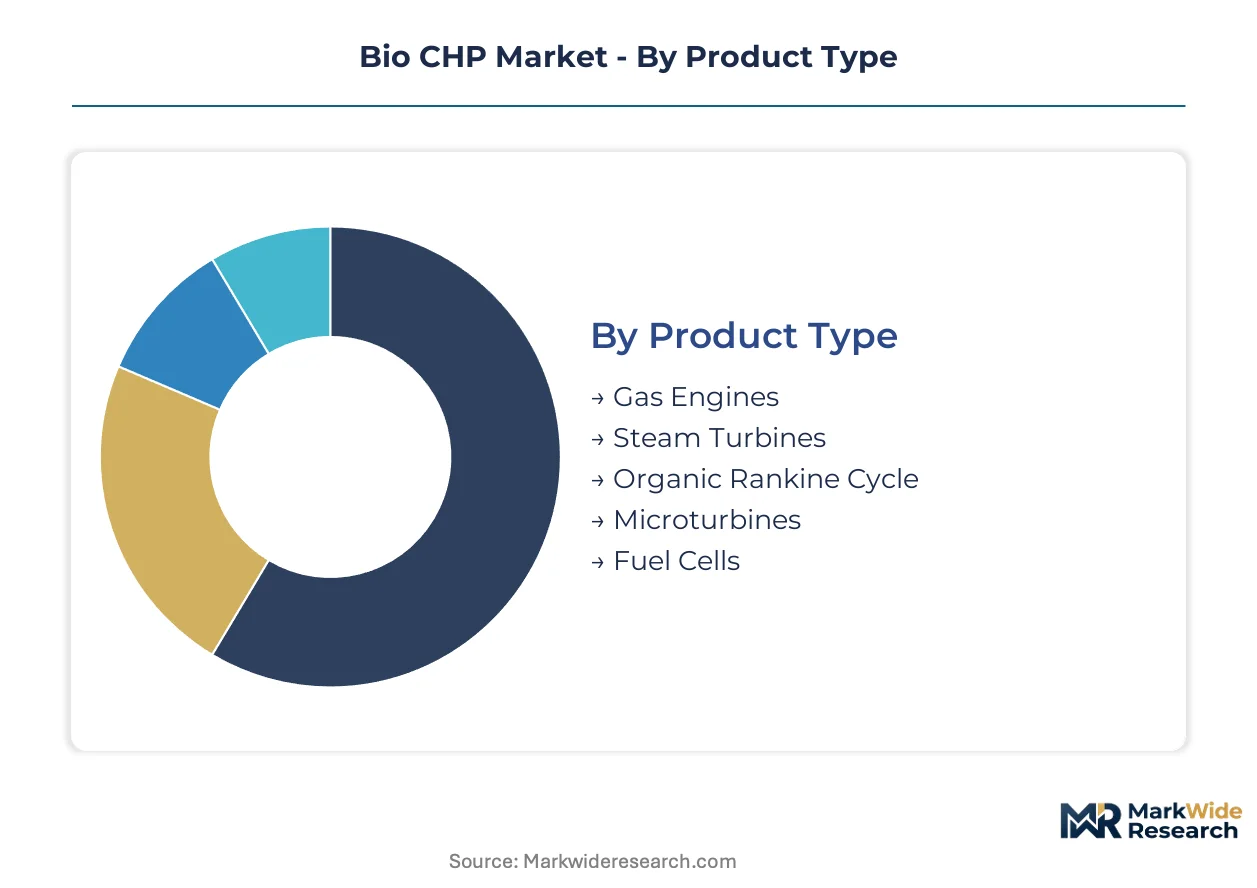
Technology choice in Bio CHP determines fuel flexibility, efficiency curves, and maintenance burden. Procurement channels diverge sharply across segments—OEM direct sales dominate large gas engine projects, while EPC contractors and energy service companies control sub-megawatt organic Rankine cycle deployments.
Product Type:
Channel mix splits by project scale and complexity. Gas engines and steam turbines flow through established OEM-direct relationships with utilities and industrial offtakers. Organic Rankine cycle and microturbine segments rely more heavily on specialized EPC integrators and energy-as-a-service providers who bundle equipment with long-term operation contracts.
- Gas Engines:Mature reciprocating engine technology achieves electrical efficiencies above 40 percent with biogas and landfill gas. Demand concentrates in German and Danish agricultural cooperatives converting manure and silage to baseload power under feed-in tariff programs. Maintenance specialization requirements and OEM service contract dependency shape procurement economics.
- Organic Rankine Cycle:Siloxane-based working fluid systems recover low-grade waste heat below 300°C without steam infrastructure. Finnish and Swedish pulp mills retrofit ORC modules onto lime kiln exhaust, opening sub-5 MW projects to smaller industrial operators previously excluded from CHP economics. F-Gas Regulation refrigerant phase-downs are forcing engineering recertification timelines.
- Steam Turbines:Capital-intensive systems suit high-temperature, high-pressure applications in large-scale biomass combustion plants.
- Microturbines:Compact radial flow designs serve distributed commercial and small industrial loads with lower maintenance requirements than reciprocating engines.
- Fuel Cells:Solid oxide and molten carbonate technologies achieve highest electrical efficiency but face cost barriers and fuel purity requirements.
Gas engines dominate installed base across European agricultural and district heating applications. Organic Rankine cycle is where expansion concentrates, climbing the fastest as industrial waste heat recovery economics improve.
Fuel Type:
Margin structure varies by feedstock procurement risk and preprocessing intensity. Biogas and landfill gas projects command premium valuations for predictable supply contracts, while solid biomass and agricultural waste segments expose developers to harvest volatility and competing industrial demand.
- Biogas:Anaerobic digestion of agricultural residues, food waste, and sewage sludge produces methane-rich fuel with consistent heating value. German and Danish operators leverage guaranteed feed-in tariffs and biomethane upgrading co-location to arbitrage between power and renewable natural gas certificate markets. Substrate availability and digester biology management constrain scale-up.
- Biomass:Wood chips, pellets, and agricultural residues require combustion or gasification infrastructure with higher capital intensity than biogas systems. Swedish and Finnish district heating networks anchor procurement through long-term supply agreements with forestry cooperatives. Carbon border adjustment documentation requirements are tightening sustainability certification standards.
- Bioethanol:Distillery residues and purpose-grown crops serve specialized applications with established fuel logistics.
- Biodiesel:Glycerin byproduct and oilseed residues offer niche opportunities in integrated biofuel-processing facilities.
- Landfill Gas:Captured methane from decomposing waste provides low-cost fuel with negative carbon intensity credentials.
- Agricultural Waste:Manure, poultry litter, and crop residues concentrate supply seasonally and geographically.
Biogas dominates revenue concentration in new European installations. Agricultural waste is where technology providers are deepening integration into upstream feedstock aggregation.
Application:
Customer acquisition cost and contract structure diverge by application type. District heating concessions and industrial manufacturing sites support long-term power purchase agreements, while commercial building and greenhouse segments favor shorter-term energy service contracts with performance guarantees.
- District Heating:Centralized heat networks in Denmark, Sweden, and the Netherlands procure multi-megawatt bio-CHP through 20-30 year concession tenders. Baseload thermal output and seasonal storage integration create high switching costs and incumbent advantages. EU Green Deal renewable heat mandates are compressing procurement timelines.
- Industrial Manufacturing:Chemical, food processing, and pulp and paper facilities install on-site generation to document Scope 1-2 emissions reductions and preserve EU market access under carbon border adjustment mechanisms. German chemical parks tender centralized bio-CHP to replace aging natural gas boilers.
- Combined Cooling Heating Power:Trigeneration configurations serve air conditioning loads in Southern European commercial and institutional buildings.
- Greenhouses:Horticulture operations in the Netherlands and Belgium consume both heat and carbon dioxide from biogas combustion.
- Commercial Buildings:Hotels, hospitals, and retail centers favor sub-megawatt modular systems with rapid deployment.
District heating captures the dominant share of megawatt-scale project finance. Industrial manufacturing is where margin pools concentrate through long-term offtake structures.
End User:
Technical sophistication and in-house engineering capacity shape vendor selection across end user categories. Chemicals production and data center operators demand high availability guarantees, while educational institutions and hospitality venues prioritize operational simplicity and transferred risk.
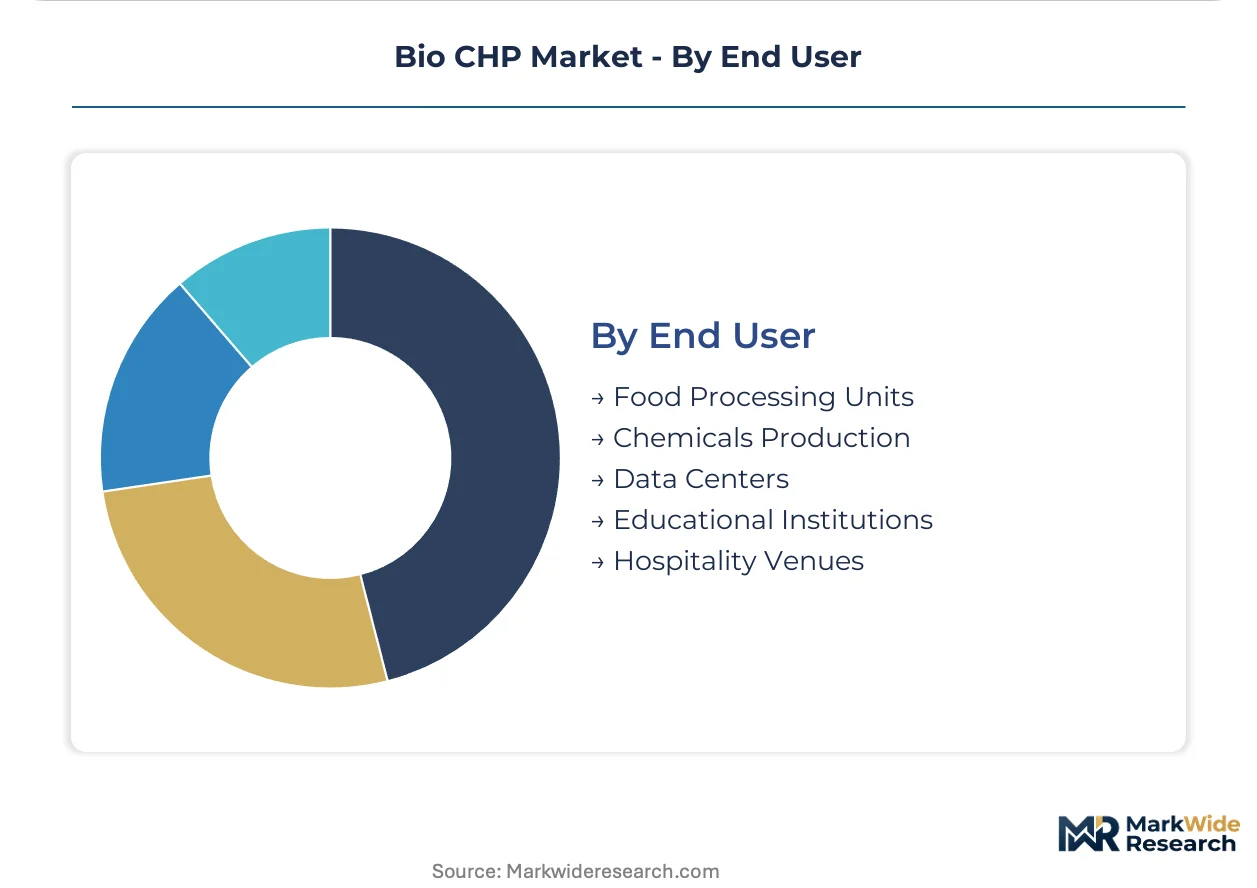
- Food Processing Units:Dairy, meat, and beverage facilities generate organic waste streams suitable for on-site anaerobic digestion with heat recovery for pasteurization and cleaning processes. German and Dutch cooperatives deploy modular gas engine CHP to convert waste liabilities into energy assets.
- Chemicals Production:Energy-intensive processes require reliable steam and power supply with documented carbon intensity for product certification. German chemical parks in Ludwigshafen and Leverkusen tender bio-CHP integration into existing utility infrastructure.
- Data Centers:Baseload power reliability and waste heat reuse for cooling drive interest in biogas-fueled systems with grid backup.
- Educational Institutions:University campuses and research facilities prioritize sustainability visibility and student engagement.
- Hospitality Venues:Hotels and resorts value energy cost predictability and green marketing credentials.
Food processing units anchor demand for sub-megawatt modular systems. Chemicals production is where equipment specifications tighten around efficiency thresholds and emissions documentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys biogas-fueled systems primarily through agricultural cooperatives, while Denmark and Sweden concentrate district heating networks at scale. This consumption-mix differential separates decentralized farm-based generation from centralized municipal procurement.
Germany
Agricultural cooperatives in Lower Saxony and Bavaria drive demand for modular gas engine units converting manure to baseload power. The Federal Emission Control Act mandates qualified technician certification for all biomass boiler maintenance, tightening deployment timelines. Ludwigshafen and Leverkusen chemical parks tender centralized bio-CHP integration to replace aging natural gas infrastructure.
Denmark
District heating networks in Copenhagen and Aarhus procure multi-megawatt biogas systems through long-term concession tenders. EU Green Deal renewable heat targets compress procurement windows before subsidy closures. Grid interconnection queues in saturated renewable zones extend project timelines by 18-36 months.
Sweden
Forestry cooperatives supply wood chip feedstock to district heating networks in Stockholm and Gothenburg under long-term agreements. Carbon border adjustment documentation requirements tighten sustainability certification standards. Pulp and paper mills in Finland and Sweden retrofit organic Rankine cycle modules onto lime kiln exhaust streams.
Netherlands
Chemical and food processing parks in Rotterdam and Eindhoven tender centralized bio-CHP under carbon reduction commitments. Energy-as-a-service contracts dominate municipal procurement above 2 MW electrical output. Greenhouse horticulture operations consume both heat and carbon dioxide from biogas combustion.
United States
Landfill gas capture projects in California and Texas leverage EPA renewable fuel standards for biogas qualification. Dairy operations in Wisconsin and New York install anaerobic digestion with heat recovery. GE Vernova anchors large-scale biogas projects through gas turbine heritage and utility relationships.
Bio CHP Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Bio CHP equipment market. Tier-one participants combine manufacturing scale with service network density across multiple geographies. Specialist competitors concentrate on modular gas engines or organic Rankine cycle subsystems for specific fuel types. Dominant competitive moves include strategic partnerships for feedstock aggregation and technology licensing for refrigerant-compliant system redesigns.
Within the integrated infrastructure tier, GE Vernova and Siemens Energy occupy positions spanning gas turbine and engine technologies across North American and European deployments. 2G Energy AG exemplifies the modular specialist archetype, anchoring agricultural waste-to-energy applications through German-engineered gas engine CHP units. Mitsubishi Heavy Industries represents the diversified industrial conglomerate model with cross-sector energy equipment capabilities.
| Leading Market Players |
|---|
| Fleetsolve |
| GE Vernova |
| 2G Energy AG |
| Mitsubishi Heavy Industries |
| Veolia |
| Wärtsilä |
| Siemens Energy |
| H3CHP |
| Enexor BioEnergy |
| Others |
Cost & Logistics Intelligence
Capacity utilization at German and Danish gas engine manufacturing facilities shapes both supply concentration and price floors across the Bio CHP equipment market. OEMs with dedicated service networks command premium positioning for long-term maintenance contracts, while modular system providers compete on deployment speed and feedstock flexibility.
Pricing Analysis
Long-term offtake contracts dominate megawatt-scale district heating procurements in Denmark and Sweden, insulating developers from feedstock volatility through fixed thermal tariffs. Price differentiation separates premium OEM service bundles from standard equipment-only sales, with certified technician availability driving the spread. Cost compression in sub-megawatt agricultural installations is intensifying as cooperatives compare energy-as-a-service alternatives. Agricultural cooperatives in Germany exhibit highest price sensitivity due to thin operating margins, while Dutch chemical parks prioritize availability guarantees over unit economics.
Supply Chain Analysis
Inventory buffers for Jenbacher and MWM engine components extend lead times for scheduled overhauls, forcing agricultural operators into costly OEM service dependencies. Manufacturing concentrates in Germany, Denmark, and Finland for core combustion and ORC equipment. Siloxane-based working fluids and specialized refractory materials for high-temperature biomass boilers draw from concentrated chemical suppliers. Single-source vulnerability for F-Gas-compliant refrigerant formulations poses recertification risks ahead of EU phase-down deadlines. Distribution runs through EPC integrators for sub-megawatt projects and direct OEM relationships for utility-scale deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The shortage of certified biomass boiler technicians across Northern Europe creates a structural bottleneck that favors equipment providers with captive training pipelines and service network density.
For Market Incumbents: Shield installed base relationships by embedding multi-year service contracts before F-Gas recertification deadlines force equipment turnover. Acquire specialized ORC engineering capabilities to capture industrial waste heat retrofit demand in Finnish and Swedish pulp mills. The EU Green Deal's compressed procurement timelines threaten margin pressure from rushed deployment schedules. For New Entrants and Emerging Players: Aftermarket maintenance capacity gaps in German agricultural cooperatives offer white-space entry points for independent service providers with rapid-response capabilities. Target Netherlands greenhouse horticulture clusters seeking bundled heat and carbon dioxide supply contracts. Energy-as-a-service contract structures lower customer acquisition barriers by transferring operational risk from capital-constrained facility owners. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular gas engine specialists with proven agricultural feedstock integration over unproven fuel cell architectures. Long-term viability rests on feedstock aggregation capabilities and regulatory compliance infrastructure rather than pure equipment manufacturing scale. Watch biomethane certificate price spreads as the inflection signal for power-versus-gas market arbitrage strategies.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Pipeline Investment | Addresses Germany's Federal Emission Control Act compliance bottleneck and accelerates deployment timelines. |
| F-Gas Compliant Refrigerant Recertification | Preserves ORC system market access under EU phasedown schedules for siloxane alternatives. |
| Feedstock Aggregation Partnerships | Secures predictable biogas supply contracts for agricultural cooperative installations in Lower Saxony. |
| Energy-as-a-Service Contract Expansion | Captures Dutch chemical park tenders seeking transferred operational risk under carbon reduction commitments. |
| Industrial Waste Heat Retrofit Integration | Opens sub-5 MW ORC deployments for Finnish pulp mills previously excluded from CHP economics. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews across the Bio CHP value chain. EPC contractors, agricultural cooperative energy managers, district heating procurement officers, and OEM service directors provided operational perspective. Secondary validation drew from EU Green Deal implementation documents, EPA renewable fuel standard filings, F-Gas Regulation compliance databases, and national feed-in tariff registries. Bottom-up project pipeline analysis and top-down equipment shipment triangulation anchored market sizing.
Across the analysis window, forecasts model technology adoption by fuel source, generation capacity tier, and application segment. CAGRs derive from installation growth trajectories, equipment replacement cycles, and regulatory deadline clustering. Feedstock price volatility indices and grid interconnection queue lengths inform scenario-weighted projections. Segmentation incorporates project scale, end-user technical sophistication, and regional subsidy regime differentiation.
Forecasts assume regulatory continuity in EU member state renewable heat mandates and EPA biogas qualification standards; material policy shifts would require re-modeling subsidy dependency and feed-in tariff economics. Carbon border adjustment implementation intensity and F-Gas refrigerant availability represent key revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Biopower Market
Bioenergy
Europe Biogas Market
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Biogas Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Organic Biogas Market
Bioenergy
Biomass Solid Fuel Market
Bioenergy
Biopellets Energy Market
Bioenergy
Bioenergy Market