
 Bioenergy Market | 2026-2036
Bioenergy Market Size, Share, and Industry Trends Forecast 2026-2036
Bioenergy Market Intelligence
The industrial energy segment's reliance on bioenergy is pivoting from co-firing in coal plants to developing dedicated biomass power facilities. Drax Biomass leads in large-scale power generation conversions from coal to biomass. Valero Energy Corporation specializes in the production of bioethanol for transportation fuels. Meanwhile, Enviva operates a significant network focused on the production and export of wood pellets to international utilities in Europe and Asia.
Bioenergy is renewable energy derived from organic materials, collectively known as biomass. Conversion technologies include direct combustion, anaerobic digestion, and gasification to release the stored chemical energy for use. Its primary purpose is to produce electricity, process heat for industrial applications, and create liquid transportation fuels. Solid biomass in the form of wood pellets commands the power generation application, while bioethanol remains the principal product for the transportation fuel segment.
Regulatory frameworks like the US EPA's Renewable Fuel Standard and the EU's Renewable Energy Directive create mandatory demand for biofuels. In Brazil, the RenovaBio program incentivizes efficiency and carbon intensity reduction in biofuel production. These policies directly shape market access and define sustainability criteria for eligible feedstocks. Consequently, securing a verifiable and sustainable feedstock supply chain remains the central strategic challenge for all producers.
Market Dynamics
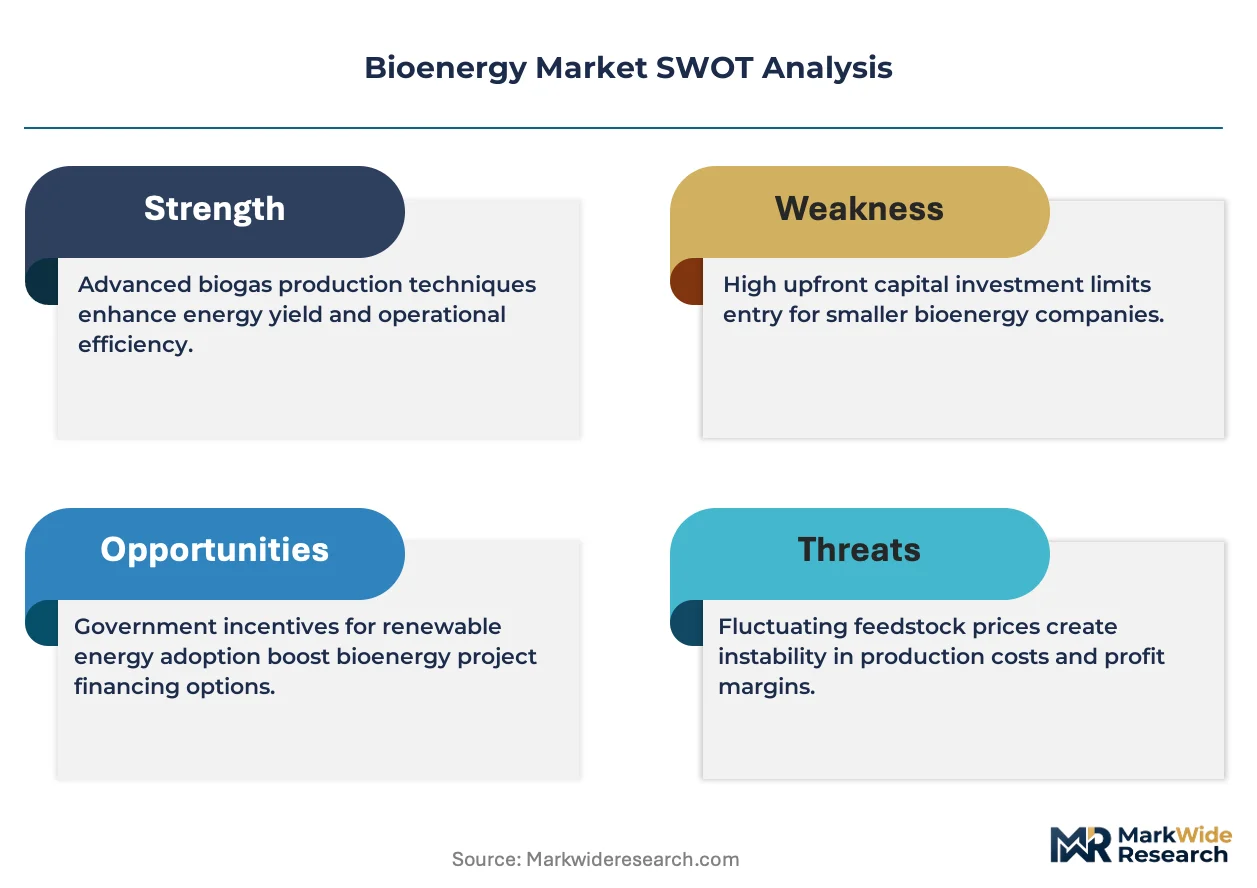
The central tension in the bioenergy market is the policy-driven acceleration of demand, particularly for transportation biofuels, against the structural limitations and sustainability challenges of securing large-scale, verifiable feedstock supply chains.
Growth Catalysts
- Regulatory Mandates:Frameworks like the EU Green Deal create binding targets for renewable energy, compelling the integration of biofuels into energy grids.
- Feedstock Diversification:Advanced technologies unlock non-food feedstocks, expanding the resource base and mitigating competition with food production.
- Transportation Demand:Rising biofuel blending mandates, especially in Brazil, provide a large-scale offtake market for bioethanol and biodiesel.
Market Restraints
- Feedstock Cost Volatility:Prices for inputs like corn and wood pellets fluctuate with weather and competing demand, impacting producer margins.
- High Capital Expenditure:Building dedicated biomass power plants and biorefineries requires substantial upfront investment, limiting market entry.
- Land Use Competition:Sourcing energy crops competes with land for food production, raising sustainability concerns that restrict project approvals.
Strategic Opportunities
- Advanced Biofuels:Developing drop-in fuels like sustainable aviation fuel (SAF) opens high-value markets with fewer infrastructure constraints than ethanol.
- Waste-to-Energy Growth:Using municipal solid waste as feedstock offers growth potential in densely populated regions of Asia.
- Biorefinery Co-products:Producing high-value bio-based chemicals alongside fuels enhances the economic viability of integrated biorefinery operations.
Industry Challenges
- Complex Logistics:Managing the collection and transport of dispersed, low-density biomass feedstocks presents significant operational and cost hurdles.
- Regulatory Compliance:Verifying feedstock sustainability to meet complex criteria, like those in the EU's Renewable Energy Directive, is costly and time-consuming.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioenergy Market |
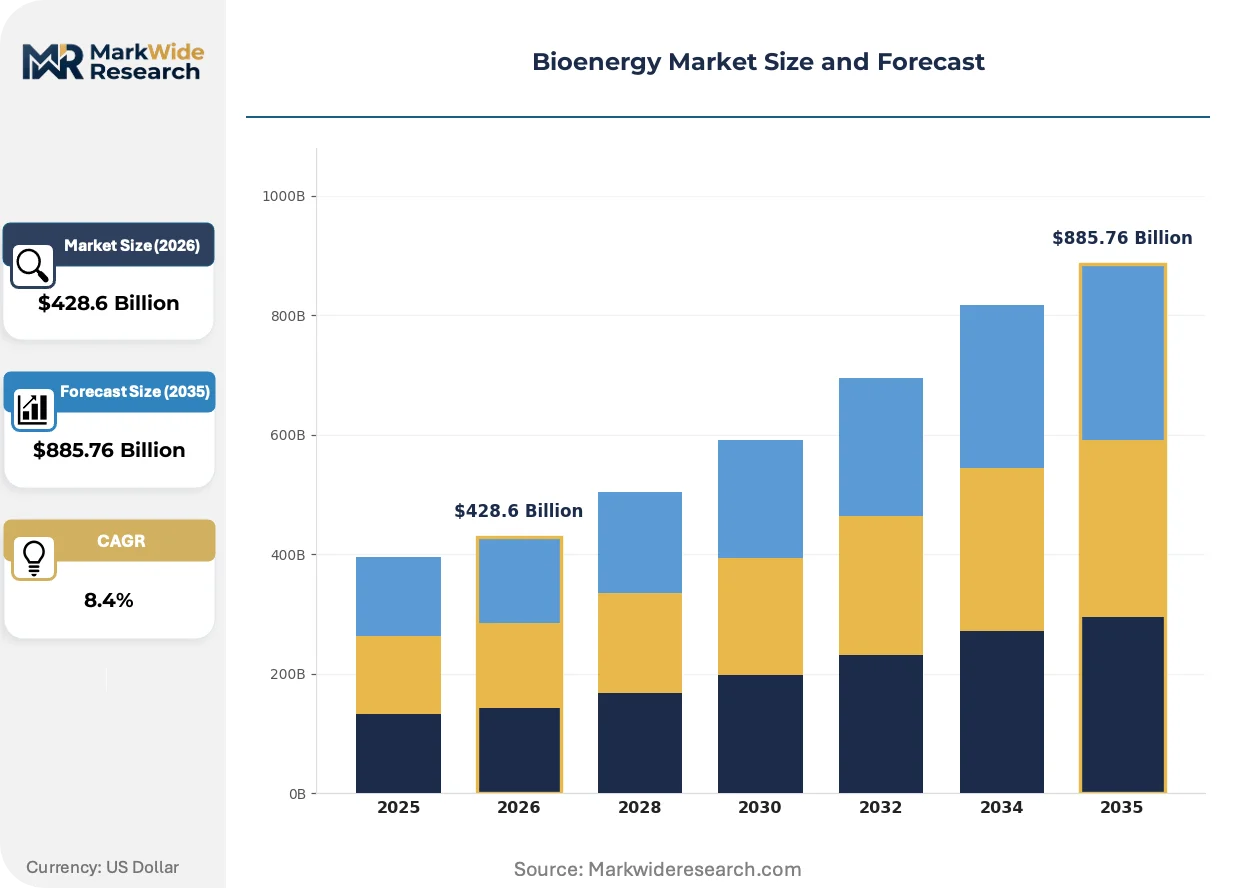
| Market Size in 2026 | $428.6 Billion |
| Market Size in 2035 | $885.76 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bioethanol, Biodiesel, Biogas, Solid Biomass, Biohydrogen Feedstock: Energy Crops, Agricultural Residues, Wood Pellets, Animal Waste, Algae Application: Power Generation, Residential Heating, Transportation Fuel, Industrial Energy, Cooking Fuel End User: Energy Providers, Commercial Establishments, Transportation Sector, Agricultural Sector, Manufacturing Plants |
| Companies Covered | Pinnacle Renewable Energy Group, Pacific BioEnergy, Enviva, POET, RWE Innogy, Drax Biomass, Lignetics, Valero Energy Corporation, Graanul Invest Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioenergy Market Strategic Shifts & Innovations
Technology pathways are diversifying beyond conventional biofuels, while regulatory frameworks are tightening sustainability requirements. This dual pressure is forcing producers to innovate in both feedstock sourcing and conversion efficiency to maintain market access and profitability.
Second-generation biofuel technology enables the conversion of non-food biomass, like agricultural residues and wood waste, into liquid fuels. The aviation and marine industries are increasingly adopting these advanced fuels to meet decarbonization targets. This technology, initially focused on road transport, is expanding into hard-to-abate sectors, creating demand for sustainable aviation fuel (SAF) and renewable diesel.
Brazil's RenovaBio program establishes a carbon intensity-based market for biofuels. It rewards producers with tradable decarbonization credits (CBIOs) for efficiency improvements and lower lifecycle emissions, from farm to fuel pump. This policy directly impacts ethanol and biodiesel producers, who now invest in precision agriculture and energy-efficient processing to maximize their credit generation.
Corporate buyers are shifting procurement towards direct, long-term power purchase agreements (PPAs) for biomass-generated electricity. This model allows large industrial and technology companies to bypass traditional utility contracts, locking in green energy supplies to meet internal ESG goals. The trend is most prominent in North America and Europe, driven by corporate carbon neutrality pledges.
Bioenergy Market Segmentation
The Bioenergy Market's diverse landscape necessitates a granular segmentation to understand specific demand drivers, technological pathways, and investment priorities. This analysis delineates the market by fuel type, feedstock source, application, and end-user, highlighting areas of concentrated value and strategic growth within the renewable energy sector.
Type:
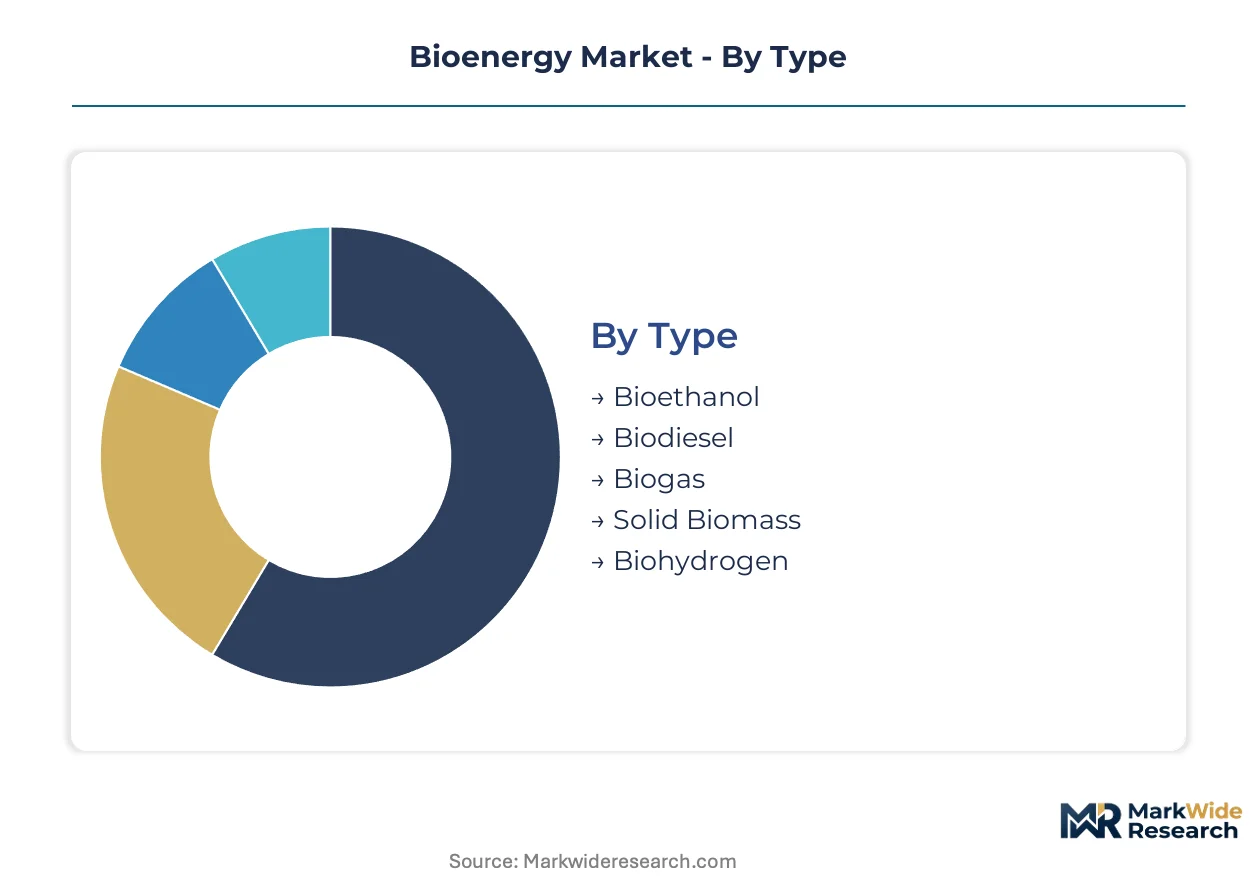
The capital intensity of bioenergy production varies significantly across different fuel types, influencing investment decisions and market entry barriers.
- Bioethanol:This alcohol fuel is produced primarily through the fermentation of biomass sugars, serving as a key component in transportation fuels. Demand concentrates in Brazil, driven by its long-standing flexible-fuel vehicle fleet and supportive government policies like RenovaBio.
- Solid Biomass:Comprising materials like wood pellets, agricultural residues, and dedicated energy crops, solid biomass is densified for efficient transport and combustion. Its demand is significant in large-scale power generation, particularly in Europe and Asia, where utilities convert coal plants to biomass or build dedicated facilities.
- Biodiesel:Produced from vegetable oils or animal fats through transesterification, biodiesel serves as a renewable diesel substitute.
- Biogas:This methane-rich gas results from the anaerobic digestion of organic matter, providing renewable electricity and heat.
- Biohydrogen:Hydrogen derived from biomass via gasification or fermentation offers a clean energy carrier for fuel cells and industrial processes.
Most installed capacity flows through Solid Biomass. Expansion is steepest in Bioethanol.
Feedstock:
Supply concentration heavily influences feedstock availability and pricing stability within the bioenergy sector.
- Wood Pellets:These are standardized, densified biomass products primarily sourced from wood waste and sustainable forestry. Global demand comes from international utilities in Europe and Asia seeking a consistent, transportable fuel for power generation.
- Agricultural Residues:This category includes crop stalks, husks, and bagasse, which are by-products of agricultural production. These residues are increasingly utilized for second-generation biofuels and biorefinery operations, mitigating competition with food production.
- Energy Crops:Dedicated non-food crops like switchgrass and miscanthus are cultivated specifically for their high energy content.
- Animal Waste:Manure and other animal by-products are processed through anaerobic digestion to produce biogas.
- Algae:Microalgae and macroalgae offer a fast-growing, non-land-intensive source for advanced biofuels and biochemicals.
Wood Pellets currently hold the largest share of procured biomass. Algae-based feedstocks are gaining share fastest.
Application:
The volume of bioenergy consumed varies considerably across different application segments, reflecting diverse energy needs and infrastructure.
- Transportation Fuel:This segment encompasses liquid biofuels such as bioethanol, biodiesel, and sustainable aviation fuel (SAF), used in road, air, and marine transport. Demand is propelled by rising biofuel blending mandates in regions like Brazil and the EU, alongside aviation industry decarbonization targets.
- Power Generation:Bioenergy is converted into electricity through combustion of solid biomass, gasification, or biogas engines. Corporate buyers are increasingly entering direct, long-term power purchase agreements (PPAs) for biomass-generated electricity, especially in North America and Europe.
- Residential Heating:Bioenergy provides heat for homes, primarily through wood pellets, briquettes, and biogas in specific regional markets.
- Industrial Energy:Manufacturing plants utilize bioenergy for process heat, steam generation, and industrial power applications.
- Cooking Fuel:Biomass briquettes and biogas systems offer cleaner cooking solutions, particularly in developing economies.
Transportation Fuel generates the highest revenue. Power Generation exhibits the steepest expansion trajectory.
End User:
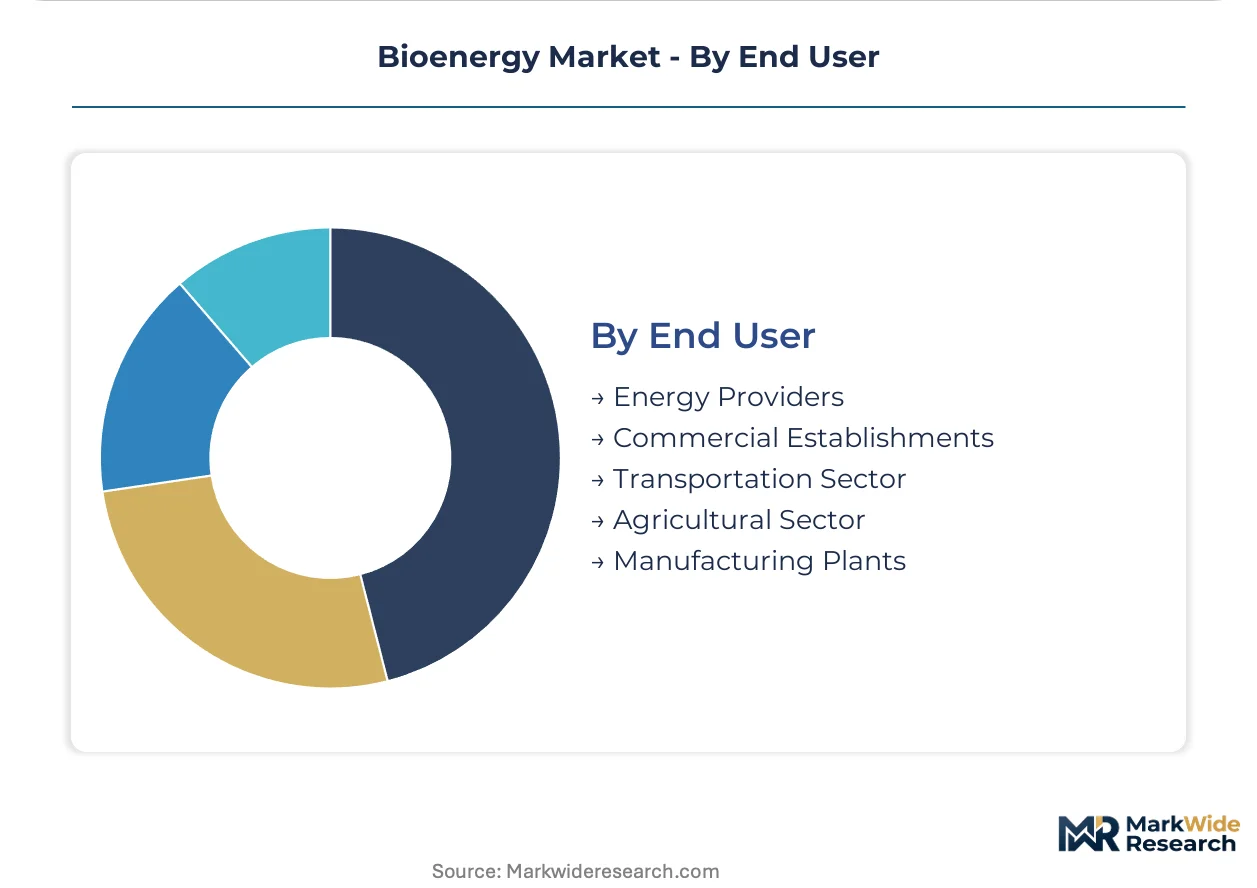
Customer type significantly dictates procurement patterns and long-term contract structures within the bioenergy market.
- Energy Providers:This segment includes utilities and independent power producers that operate large-scale biomass power plants or co-fire biomass with other fuels. These entities seek stable, long-term feedstock contracts to meet renewable portfolio standards and decarbonization goals.
- Transportation Sector:Airlines, shipping companies, and road vehicle fleet operators consume biofuels to meet regulatory mandates and internal sustainability targets. The sector focuses on advanced biofuels like SAF and renewable diesel to reduce carbon intensity.
- Commercial Establishments:Businesses and institutions procure bioenergy for on-site heat and power generation, supporting their ESG objectives.
- Agricultural Sector:Farms and agribusinesses integrate bioenergy solutions for waste management and captive energy generation.
- Manufacturing Plants:Industrial facilities, particularly in sectors like pulp and paper, use bioenergy for process heat and steam.
Energy Providers represent the largest consumer base. The Transportation Sector is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences bioenergy market dynamics, as producers seek regions balancing strong demand with favorable compliance costs. Countries with robust renewable energy mandates attract significant investment, often offsetting complex feedstock verification requirements. This strategic migration optimizes production and distribution channels for biofuels and biomass.
Brazil
Brazil's transportation sector drives substantial bioethanol demand for its extensive flexible-fuel vehicle fleet. The RenovaBio program incentivizes biofuel producers for carbon intensity reductions through tradable credits. São Paulo's sugarcane industry remains a global hub for efficient ethanol production and processing.
United States
United States demand for biofuels stems from stringent blending mandates and corporate sustainability pledges. The US EPA's Renewable Fuel Standard creates a mandatory market for ethanol and advanced biofuels. The Midwest corn belt anchors significant bioethanol production capacity and innovation.
Germany
German renewable electricity targets and industrial heat requirements fuel biomass consumption. The EU Green Deal provides a strong regulatory push for sustainable energy sources across the nation. Northern Germany's port cities facilitate substantial wood pellet imports for power generation.
Japan
Japanese power generation relies on imported solid biomass to meet decarbonization commitments. Feed-in tariff schemes have supported the conversion of coal-fired plants to co-firing or dedicated biomass facilities. Coastal power plants in regions like Kyushu are actively transitioning towards biomass-fueled operations.
Bioenergy Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the bioenergy market. The market exhibits a tiered structure, with large integrated energy companies alongside specialized biomass producers. Strategic archetypes include feedstock aggregators, biofuel refiners, and dedicated biomass power generators. Companies often pursue geographic expansion and portfolio diversification to mitigate feedstock volatility.
Specialists in various bioenergy value chains include Enviva, Drax Biomass, and Valero Energy Corporation. Enviva exemplifies a global leader in wood pellet production and export, serving international utilities in Europe and Asia. Drax Biomass represents a major player in large-scale power generation conversions from coal to biomass. Valero Energy Corporation occupies a significant position in the production of bioethanol for transportation fuels, anchoring the biofuel refining archetype. These entities collectively demonstrate the diverse operational models driving the market.
| Leading Market Players |
|---|
| Pinnacle Renewable Energy Group |
| Pacific BioEnergy |
| Enviva |
| POET |
| RWE Innogy |
| Drax Biomass |
| Lignetics |
| Valero Energy Corporation |
| Graanul Invest Group |
| Others |
Cost & Logistics Intelligence
Private-equity-backed specialists in bioenergy production often influence supply behavior and pricing discipline. Their investment decisions frequently prioritize economies of scale in feedstock processing and market access. This structure impacts the availability and cost of bioenergy products across various end-use sectors.
Pricing Analysis
Direct-to-end-user discounts shape bioenergy pricing, especially for large corporate buyers. The dominant pricing model involves contract-based long-term offtake agreements for solid biomass and advanced biofuels. Price differentiation stems from feedstock sustainability certification levels and the high geographic delivery cost of densified biomass. Pricing pressure intensifies due to feedstock cost volatility, impacting producer margins. Energy providers, driven by renewable portfolio standards, exhibit lower price sensitivity compared to the transportation sector, which faces consumer fuel price scrutiny.
Supply Chain Analysis
Dual-sourcing requirements for sustainable feedstocks mitigate supply risks for bioenergy producers. Geographic supply concentrates wood pellets from North America to Europe and Asia, while bioethanol production centers in Brazil and the United States. Raw material dependencies include wood waste, agricultural residues, corn, and sugarcane. Complex logistics for collecting and transporting dispersed, low-density biomass present a significant operational risk. Distribution runs through specialized logistics networks for solid biomass and established fuel infrastructure for liquid biofuels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bioenergy market functions as a stable compounder, driven by binding regulatory mandates for renewable energy integration. Long-term policy frameworks ensure sustained demand across multiple application segments.
For Market Incumbents: Acquire advanced biorefinery technology to diversify conversion capabilities beyond existing assets. Incumbents must secure long-term, verifiable feedstock supply contracts to mitigate feedstock cost volatility and tightening regulatory sustainability criteria. Investing in vertical integration into feedstock cultivation or waste processing ensures supply chain resilience. This strategy defends against margin erosion from input price fluctuations.
For New Entrants and Emerging Players: Digital platforms for feedstock traceability and carbon intensity verification offer a market entry route for new players. Target waste-to-energy growth in densely populated regions of Asia, leveraging municipal solid waste as a sustainable feedstock. Focus on producing high-value biorefinery co-products alongside fuels to enhance economic viability. A go-to-market angle emphasizing verifiable lifecycle emissions reductions can attract corporate buyers.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized biomass logistics and pre-processing firms. The long-term viability of bioenergy is underpinned by global decarbonization targets and sustained regulatory support for renewables. Target acquisition archetypes include advanced biofuel technology developers and companies with verifiable sustainable feedstock access. The expansion of sustainable aviation fuel (SAF) mandates represents a crucial inflection indicator for future growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout for Dedicated Facilities | Drax Biomass expands large-scale power generation conversions from coal to biomass, reducing carbon emissions. |
| Long-term Power Purchase Agreements | Corporate buyers secure green energy supplies to meet internal ESG goals in North America and Europe. |
| Advanced Biofuel Technology Licensing | Second-generation biofuel conversion of non-food biomass expands resource base for transportation fuels. |
| Vertical Integration into Sustainable Feedstock | Enviva ensures verifiable wood pellet supply chains for international utilities in Europe and Asia. |
| Carbon Intensity Certification Programs | Brazil's RenovaBio incentivizes efficiency improvements and lower lifecycle emissions for ethanol producers. |
Research Approach
Coverage spans Brazil, the United States, Germany, and Japan, with primary inputs from each key geography. This study integrates insights from interviews with bioenergy producers, utility procurement managers, biofuel refiners, and agricultural feedstock suppliers. Secondary validation draws from regulatory documents, such as the US EPA's Renewable Fuel Standard and the EU's Renewable Energy Directive, alongside industry association reports. A bottom-up and top-down triangulation approach ensures data consistency.
Granularity levels for the forecast model segment the market by fuel type, feedstock source, application, end-user, and regional policy frameworks. The analytical framework projects growth across the analysis window, deriving CAGRs from historical market trends and industry expert projections. Key industry-specific inputs include biofuel blending mandates in Brazil and the EU, along with corporate power purchase agreement commitments.
The model assumes a particular technology adoption path; alternative pathways for advanced biofuels or waste-to-energy would alter the outlook. Forecasts reflect assumptions regarding feedstock availability, policy stability, and capital expenditure requirements. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bioenergy
Micro-Scale Biogas Plant Market
Bioenergy
Biomass Molding Fuel Market
Bioenergy
Biomass Wood Chip Market
Bioenergy
Organic Biogas Market
Bioenergy
Biopellets Energy Market
Bioenergy
Biogas Market
Bioenergy
Europe Bioenergy Market
Bioenergy
Biopower Market
Bioenergy
Europe Biogas Market
Bioenergy
Bio CHP Market
Bioenergy
Global Biomass Briquette Market
Bioenergy
Biomass Solid Fuel Market