
 Theranostics Market | 2026-2036
Theranostics Market Size, Share, and Industry Trends Forecast 2026-2036
Theranostics Market Intelligence
ISO 13485 certification is reorganizing competitive access in theranostics manufacturing, forcing contract developers to upgrade quality management systems before supplying radiolabeled compounds to commercial partners. GE Healthcare leverages its cyclotron network and PET tracer infrastructure to dominate North American supply. Siemens Healthineers anchors its position through integrated molecular imaging hardware and AI-enhanced dosimetry software. Thermo Fisher Scientific competes via specialized isotope production capabilities and cold kit formulation expertise.
Theranostics pairs diagnostic imaging with targeted radionuclide therapy using matched biomolecular carriers, typically radiolabeled antibodies or small molecules that bind tumor-specific antigens for simultaneous visualization and treatment. The approach requires precise coordination between tracer chemistry, companion imaging, and personalized dosing protocols to deliver therapeutic radiation while sparing healthy tissue. Molecular imaging and next-generation sequencing segments lead current revenue as PSMA PET and circulating tumor DNA profiling become standard in prostate and lung cancer pathways. Imaging agents represent the fastest-growing product category as novel radioisotopes expand beyond lutetium-177 into actinium-225 and terbium-161 candidates.
FDA oversight of radiopharmaceuticals under 21 CFR Part 312 and Part 361 shapes clinical trial design and manufacturing scale-up requirements for theranostics developers. EMA's centralized marketing authorization process for advanced therapy medicinal products creates parallel compliance obligations for companies seeking European market access. Stakeholders must monitor evolving reimbursement decisions from CMS and national health technology assessment bodies, as payment policy rather than clinical evidence increasingly determines which theranostic pairings achieve routine adoption.
Market Dynamics
ISO 13485 certification requirements are forcing contract manufacturers to rebuild quality management systems before supplying radiolabeled compounds, concentrating production among firms with cyclotron networks and cold kit formulation capabilities.
Growth Catalysts
- FDA's streamlined 21 CFR Part 312 framework:The FDA's radiopharmaceutical companion diagnostic pathway compresses clinical trial timelines and accelerates commercialization for matched imaging-therapy pairs.
- Academic medical center expansion:Oncology departments at major university hospitals are building dedicated theranostics programs as CMS reimbursement pathways mature for PSMA PET and lutetium-177 therapy.
- Actinium-225 production scaling:Novel alpha-emitter isotope supply is expanding beyond lutetium-177, enabling next-generation radiolabeled antibodies for resistant metastatic disease.
Market Restraints
- Cyclotron network concentration:Production of fluorine-18 and carbon-11 tracers clusters around major metropolitan proton therapy hubs, creating geographic supply vulnerability for rural and mid-market healthcare systems.
- Short half-life logistics:Technetium-99m and gallium-68 isotopes require just-in-time delivery infrastructure that limits distribution radius and raises per-dose logistics costs.
- EMA centralized authorization complexity:The European Medicines Agency's advanced therapy medicinal product pathway imposes parallel compliance obligations that delay European market entry for US-developed radiopharmaceuticals.
Strategic Opportunities
- India's CDSCO pathway acceleration:India's pharmaceutical regulator is streamlining radiopharmaceutical import and manufacturing licensing, opening access to a large oncology patient population with limited domestic isotope production.
- AI-enhanced dosimetry integration:Machine learning algorithms for personalized radiation dose calculation are converging with molecular imaging hardware to enable precision dosing protocols that differentiate service offerings.
- Community oncology infusion:Radiopharmaceutical therapy administration is migrating from academic centers to regional cancer networks, creating channel expansion opportunity for cold kit and isotope suppliers.
Industry Challenges
- Radiochemist talent scarcity:The specialized skill set combining radiochemistry, GMP manufacturing, and radiation safety is concentrated among a small cohort of trained professionals, constraining production scale-up.
- Legacy EHR integration friction:Theranostics workflows require seamless coordination between nuclear medicine, radiation oncology, and medical oncology departments, but hospital information systems lack interoperable ordering and scheduling modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Theranostics Market |
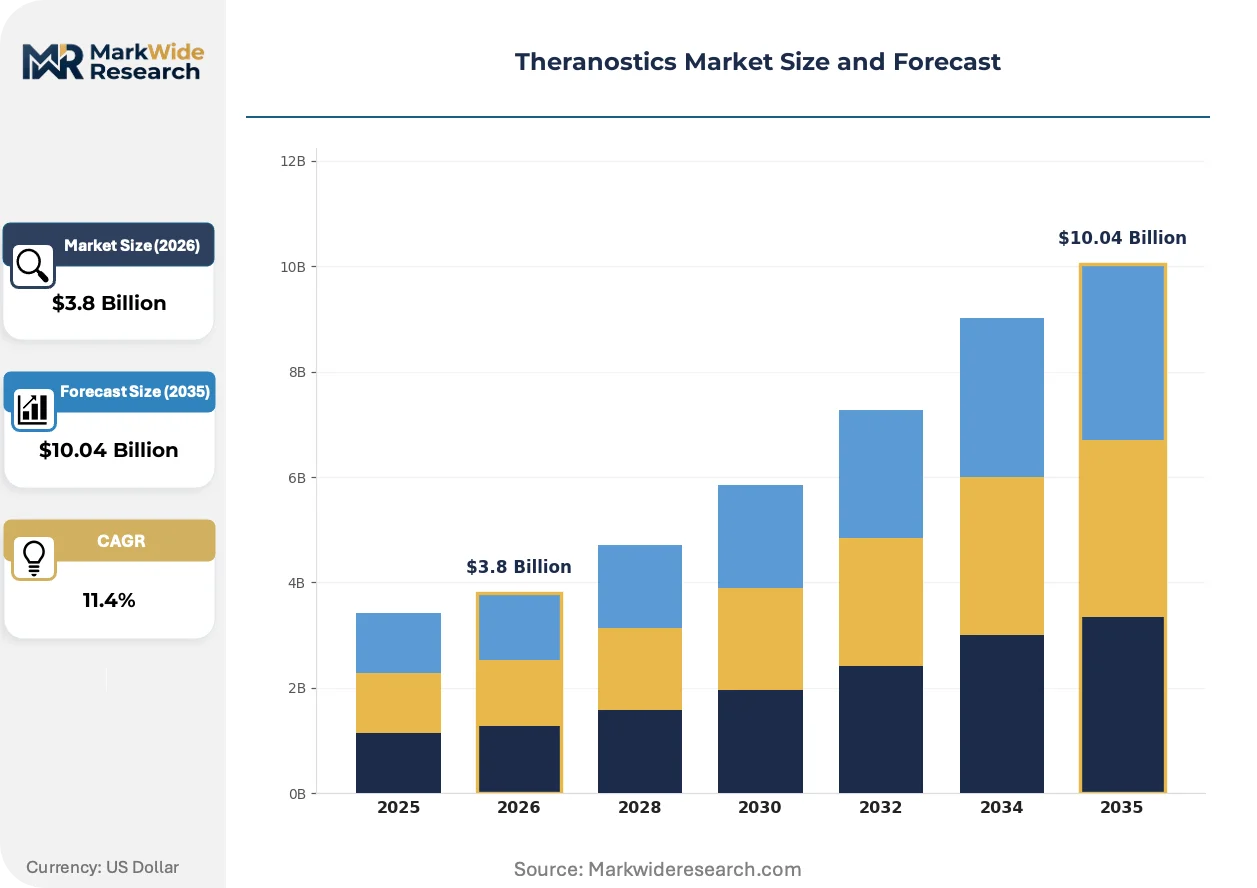
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: In Vitro Diagnostics, Biomarkers, Imaging Agents, Therapeutic Drugs Technology: Molecular Imaging, PCR, Next-Generation Sequencing, CRISPR End User: Hospitals, Laboratories, Research Institutions, Clinics Application: Cancer Diagnosis, Cardiovascular Care, Infectious Disease Testing, Neurology |
| Companies Covered | GE Healthcare, Siemens Healthineers, Roche Diagnostics, Thermo Fisher Scientific, Bayer AG, Novartis AG, Advanced Accelerator Applications, Cardinal Health, Telix Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Theranostics Market Strategic Shifts & Innovations
Alpha-emitter radiopharmaceuticals and AI-driven dosimetry are fragmenting the theranostics technology base, while reimbursement policy and procurement models reshape how matched diagnostic-therapy pairs reach patients.
Actinium-225 and terbium-161 radiolabeling chemistry is fragmenting the therapeutic isotope landscape beyond established lutetium-177 protocols. Academic medical centers in Germany and the United States are adopting these alpha-emitters for resistant prostate and neuroendocrine malignancies. The shift is compressing market share concentration among isotope suppliers with specialized production reactors and radiochemistry expertise.
REACH regulation amendments on radiopharmaceutical precursor chemicals are tightening supply chain documentation requirements for European manufacturers. The European Chemicals Agency's expanded substance registration obligations are forcing reformulation of cold kit components and tracer synthesis modules. German and Swiss contract developers are responding by consolidating precursor sourcing through vertically integrated radiochemistry facilities.
Hospital procurement departments are unbundling molecular imaging hardware from radiopharmaceutical supply contracts, reversing decade-long bundled leasing arrangements. Independent cyclotron operators and radiopharmacy networks are winning standalone supply agreements with community health systems. This pattern is most visible in the United States, where regional cancer networks seek flexibility to switch isotope suppliers based on half-life availability and dose pricing.
Theranostics Market Segmentation
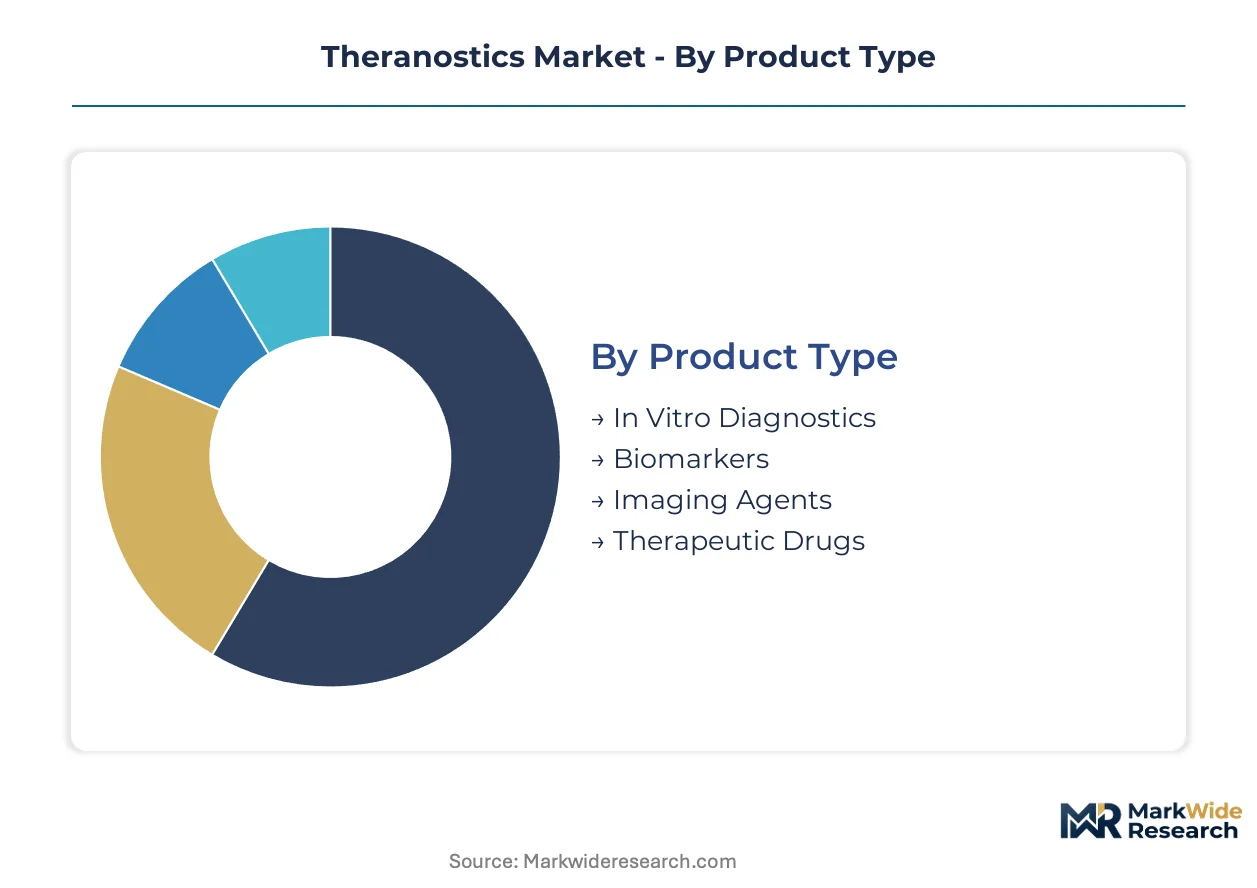
Theranostics segmentation reveals distinct channel economics. Imaging agents flow through cyclotron networks and radiopharmacy chains. Biomarkers and sequencing services route through centralized laboratory contracts. Hospital procurement departments now unbundle hardware from isotope supply, reshaping how each segment reaches clinical decision-makers.
Product Type:
Channel mix varies sharply by product chemistry. Cold kit formulations and isotope-labeled compounds follow different distribution footprints.
- Imaging Agents:Radiolabeled small molecules and antibodies for PET and SPECT visualization require just-in-time cyclotron production. Demand clusters around academic medical centers with in-house PET infrastructure and regional radiopharmacy networks serving community oncology practices.
- Therapeutic Drugs:Lutetium-177 and actinium-225 radiolabeled antibodies deliver targeted radionuclide therapy. Administration concentrates at proton therapy centers and specialized nuclear medicine departments as CMS reimbursement pathways mature for PSMA-targeted therapy.
- Biomarkers:Circulating tumor DNA and protein assays enable patient stratification for theranostic pairing. Commercial reference laboratories process these through high-throughput sequencing platforms.
- In Vitro Diagnostics:Companion diagnostic kits for FDA-approved radiopharmaceuticals ship through diagnostic distributors to hospital central laboratories.
Imaging agents dominate installed base. Therapeutic drugs are where expansion concentrates.
Technology:
Cost tier separates capital-intensive hardware from consumable-driven testing modalities.
- Next-Generation Sequencing:Tumor mutational profiling and circulating DNA analysis identify molecular targets for theranostic selection. Major cancer centers deploy these platforms to match patients to PSMA, SSTR2, or other targetable antigens.
- Molecular Imaging:PET and SPECT hardware with integrated AI dosimetry software commands premium capital budgets. Siemens Healthineers and GE Healthcare anchor this tier through bundled hardware-software contracts.
- PCR:Targeted amplification supports companion diagnostic workflows for infectious disease and oncology applications. Lower capital requirements enable placement at mid-tier hospitals.
- CRISPR:Gene editing tools for research-stage theranostic target validation remain confined to academic and pharmaceutical research settings.
Molecular imaging captures the highest per-procedure revenue. Next-generation sequencing is climbing the fastest.
End User:
Customer type determines purchasing authority and contract structure.
- Hospitals:Integrated delivery networks with proton therapy and nuclear medicine departments control the largest theranostic volumes. Supply contracts now separate cyclotron access from imaging hardware leasing.
- Laboratories:Commercial reference labs and hospital outreach programs process biomarker testing and sequencing services under capitated or per-test pricing.
- Research Institutions:Academic medical centers develop novel radiolabeled compounds under FDA 21 CFR Part 312 IND protocols, bridging to commercial manufacturing.
- Clinics:Community oncology practices increasingly administer lutetium-177 therapy through satellite infusion centers, requiring cold kit logistics and radiation safety infrastructure.
Hospitals anchor current revenue. Clinics represent the steepest expansion trajectory.
Application:
Application maturity follows regulatory approval sequencing and reimbursement coverage.
- Cancer Diagnosis:PSMA PET for prostate cancer staging and SSTR2 imaging for neuroendocrine tumors constitute the reimbursed core. FDA-approved companion diagnostics pair imaging with lutetium-177 therapy.
- Cardiovascular Care:Amyloid PET tracers for cardiac amyloidosis represent an emerging reimbursable indication, with expansion into sarcoidosis imaging.
- Neurology:Tau and amyloid PET for Alzheimer's disease progression monitoring remains research-funded, pending CMS national coverage determination.
- Infectious Disease Testing:FDG-PET for device-related infection localization serves niche surgical planning applications.
Cancer diagnosis dominates procedure volume. Cardiovascular care is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement pathway maturation at CMS is accelerating theranostics infrastructure investment across multiple geographies. Academic medical centers in Germany, the United States, Japan, and Switzerland are expanding cyclotron networks and radiochemistry facilities to capture emerging PSMA-targeted therapy volumes.
United States
Prostate cancer mortality reduction targets are driving demand for PSMA PET and lutetium-177 therapy pairing at academic medical centers. FDA's 21 CFR Part 312 framework compresses IND timelines for radiopharmaceutical developers. Cyclotron networks cluster around Houston, Boston, and Cleveland metropolitan hubs where proton therapy centers anchor integrated theranostics programs.
Germany
Neuroendocrine tumor incidence rates and established SSTR2 imaging protocols sustain high theranostics procedure density. EMA centralized marketing authorization for advanced therapy medicinal products shapes German hospital procurement of radiolabeled compounds. Munich and Heidelberg academic centers pioneer actinium-225 alpha-emitter protocols for resistant metastatic disease.
Switzerland
Swissmedic's streamlined radiopharmaceutical licensing attracts European headquarters for isotope suppliers and contract developers. Basel and Zurich house concentrated radiochemistry expertise serving cross-border supply to German and French hospital networks. Paul Scherrer Institute reactor production anchors domestic actinium-225 supply for clinical trials.
Japan
Aging demographics and prostate cancer screening expansion are building demand for molecular imaging infrastructure. PMDA's conditional early approval system for radiopharmaceuticals accelerates commercialization timelines for novel tracer candidates. Tokyo and Osaka metropolitan areas concentrate cyclotron installations at university hospitals with integrated nuclear medicine departments.
India
Oncology patient volume and limited domestic isotope production create import dependency for fluorine-18 and gallium-68 tracers. CDSCO's streamlined radiopharmaceutical manufacturing licensing is opening contract development opportunities for multinational suppliers. Mumbai and Hyderabad hospital networks are building captive radiopharmacy capabilities to reduce cold kit logistics costs.
Theranostics Market Key Industry Players
Listed leaders compete with private specialists across cyclotron network scale and radiochemistry service breadth. The vendor base separates into three tiers: integrated imaging hardware suppliers with captive isotope production, standalone radiopharmacy networks serving community oncology, and contract manufacturers specializing in cold kit formulation. Dominant competitive moves include cyclotron network expansion through regional partnerships and backward integration into isotope production reactors to secure alpha-emitter supply.
Within the integrated hardware tier, GE Healthcare and Siemens Healthineers exemplify archetypes combining molecular imaging equipment with AI-enhanced dosimetry software. Thermo Fisher Scientific occupies a position representing specialized isotope production and cold kit formulation capabilities for commercial radiopharmaceutical partners. These three anchors illustrate how competitive positioning depends on control over production infrastructure rather than product differentiation alone.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Roche Diagnostics |
| Thermo Fisher Scientific |
| Bayer AG |
| Novartis AG |
| Advanced Accelerator Applications |
| Cardinal Health |
| Telix Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Actinium-225 substitution for lutetium-177 in resistant metastatic prostate protocols is redrawing supply geography toward reactor-equipped facilities in Germany and Switzerland while compressing pricing economics for beta-emitter manufacturers facing reimbursement pressure from alpha-emitter premium positioning.
Pricing Analysis
Certification level creates the primary spread between GMP-grade radiopharmaceuticals and research-use compounds. Three-tier pricing structure across FDA-approved, CE-marked, and non-certified isotope grades separates academic medical center procurement from community oncology budgets. Cost compression in technetium-99m and fluorine-18 tracer production is intensifying because cyclotron network overbuild around Houston and Cleveland metropolitan hubs concentrates supply-side competition. Community oncology practices exhibit highest price sensitivity due to thin cold kit logistics margins, while proton therapy centers at academic medical centers absorb premium pricing for actinium-225 alpha-emitter therapy.
Supply Chain Analysis
Germany and Switzerland anchor European radiopharmaceutical production through Paul Scherrer Institute reactor output and Basel radiochemistry expertise. Domestic supply draws from specialized isotope production reactors, cold kit precursor chemicals, and gallium-68 generator systems. Single-source vulnerability concentrates in actinium-225 supply where only three production reactors globally meet clinical-grade specifications. Distribution runs through just-in-time radiopharmacy networks serving metropolitan proton therapy centers with four-hour delivery windows for short half-life isotopes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among integrated delivery networks unbundling hardware leasing from isotope supply contracts, fragmenting vendor lock-in that previously protected incumbent margins.
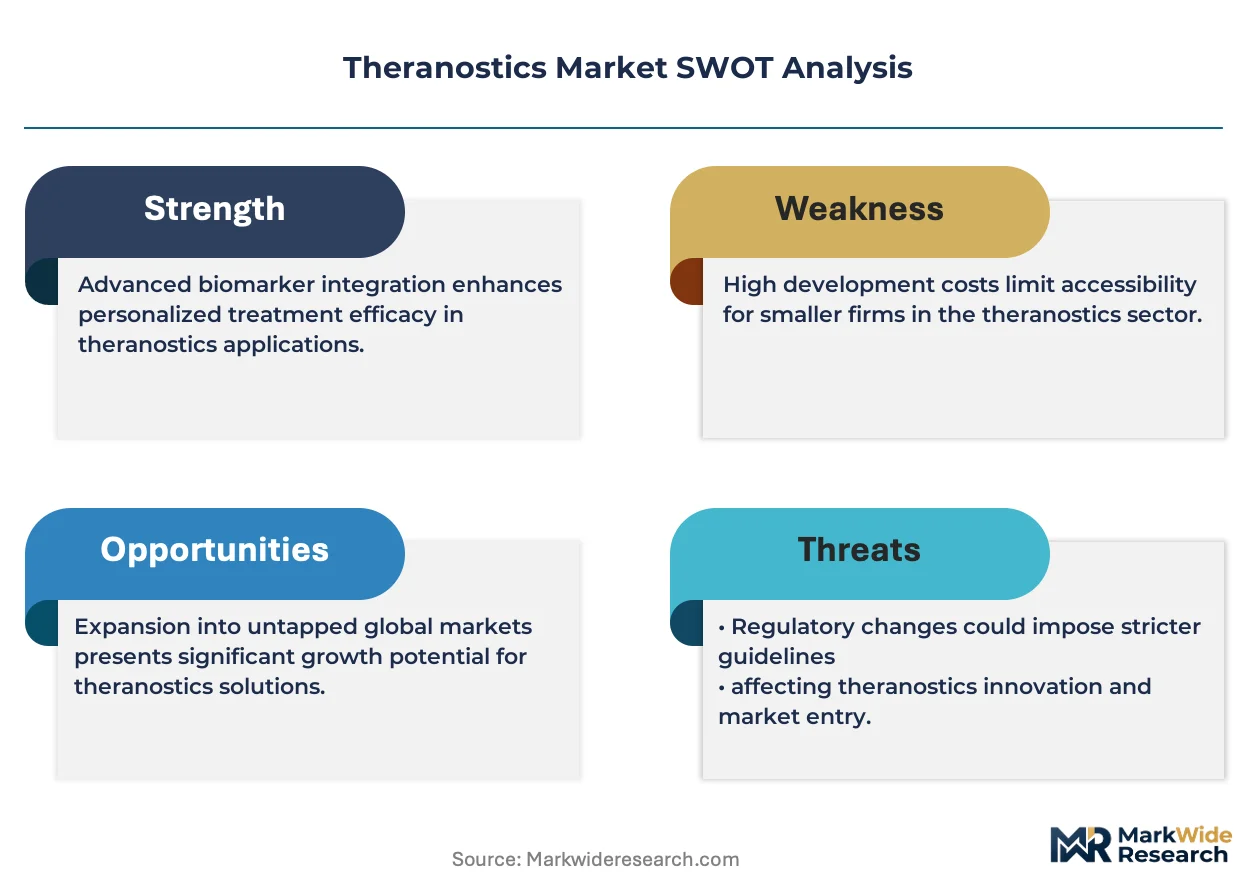
For Market Incumbents: Consolidate cyclotron network access through regional partnerships with academic medical centers before independent radiopharmacy operators capture community oncology volume. Backward integration into alpha-emitter reactor production secures supply leverage against emerging isotope suppliers. ISO 13485 certification investment defends contract manufacturing relationships as FDA quality system enforcement tightens. For New Entrants and Emerging Players: Lead with AI-enhanced dosimetry software partnerships that differentiate service offerings without requiring captive cyclotron infrastructure. India's CDSCO streamlined licensing pathway offers the most penetrable geography for import-dependent isotope supply. Community oncology infusion centers present white-space channel expansion for cold kit logistics specialists. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed radiopharmacy networks consolidating regional cyclotron access. Long-term viability hinges on reimbursement pathway maturation at CMS for PSMA-targeted therapy pairing. Watch FDA 21 CFR Part 312 IND approval velocity as inflection indicator for manufacturing scale-up timing.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Regional partnerships with Houston and Cleveland proton therapy centers secure captive isotope demand. |
| Alpha-Emitter Reactor Investment | Paul Scherrer Institute reactor capacity anchors European actinium-225 supply for resistant metastatic protocols. |
| AI Dosimetry Software Integration | Siemens Healthineers and GE Healthcare bundle machine learning algorithms with molecular imaging hardware. |
| ISO 13485 Certification Pathway | Contract manufacturers upgrade quality systems to supply commercial radiopharmaceutical partners under FDA enforcement. |
| Community Oncology Channel Development | Cold kit logistics networks enable lutetium-177 therapy administration outside academic medical centers. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR Part 312 IND filings, EMA centralized marketing authorization submissions, CMS reimbursement determinations, and hospital procurement databases. Radiochemistry executives, nuclear medicine department chairs, GPO contracts managers, and regulatory affairs leads at radiopharmaceutical developers provided structured interviews. Bottom-up isotope production volume estimates triangulate against top-down therapeutic procedure forecasts across the analysis window.
Segmentation dimensions modeled include product type, technology platform, end-user category, and application indication throughout the forecast period. CAGRs derive from procedure volume projections weighted by reimbursement pathway maturation timing. Forecast inputs incorporate cyclotron network expansion timelines, alpha-emitter production reactor capacity, and AI dosimetry software adoption curves.
The analysis sits within stated boundaries; outcomes outside CMS national coverage determination timelines or EMA advanced therapy medicinal product authorization pathways would require recalibration. Forecasts reflect assumptions on reimbursement policy stability, isotope supply chain security, and radiochemist workforce availability. Recalibration cycles align with material shifts in FDA radiopharmaceutical approval velocity and CMS payment policy updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
US Generic Injectables Market
Biopharmaceuticals
Global Oncology/Cancer Drugs Market
Biopharmaceuticals
Global Human Recombinant Insulin Market
Biopharmaceuticals
North America HIV Drugs Market
Biopharmaceuticals
US Generic Drug Market
Biopharmaceuticals
Phenylketonuria (PKU) Market
Biopharmaceuticals
Antibody Discovery Market
Biopharmaceuticals
Thailand Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
BRAF Kinase Inhibitors Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market