
 Global Carcinoembryonic Antigen (CEA) Market | 2026-2036
Global Carcinoembryonic Antigen (CEA) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carcinoembryonic Antigen (CEA) Market Intelligence
Hospital procurement consolidation across integrated delivery networks is recalibrating vendor selection criteria for CEA testing platforms. Siemens Healthineers leverages its installed base of immunoassay analyzers to sustain long-term service contracts. Roche Diagnostics differentiates through centralized laboratory automation that anchors high-throughput oncology workflows in major health systems.
Carcinoembryonic antigen is a glycoprotein with a molecular weight of approximately 180 kDa, produced during fetal development and re-expressed in epithelial malignancies, particularly colorectal adenocarcinoma, where serum quantification supports staging and post-surgical surveillance. The primary commercial purpose centers on immunoassay-based detection in clinical laboratories to monitor tumor burden and treatment response. Test kits and reagents command the largest revenue share within product type segments, while molecular diagnostics represents the fastest-expanding technology category as laboratories integrate PCR-based reflex testing. Hospitals dominate end-user demand, though diagnostic centers are capturing incremental volume through outpatient oncology monitoring programs.
FDA oversight of in vitro diagnostics under the IVDR transition timeline shapes product registration requirements for US market entry, while EMA's companion diagnostic guidelines influence CEA assay validation standards across European member states. Japan's PMDA enforces stringent analytical performance criteria that filter non-compliant imports from the Japanese clinical laboratory market. Stakeholders must monitor evolving regulatory harmonization between FDA and IVDR frameworks to anticipate compliance cost structures and timeline risks for new assay introductions.
Market Dynamics
Integrated delivery networks in the United States and Germany are consolidating laboratory procurement decisions, forcing CEA assay vendors to restructure pricing and service models around multi-year enterprise contracts rather than transactional reagent sales.
Growth Catalysts
- IVDR Transition Timeline:The European Union's In Vitro Diagnostic Regulation mandates recertification of legacy CEA assays by 2028, creating replacement demand for next-generation platforms with enhanced analytical sensitivity.
- Outpatient Oncology Monitoring:Diagnostic centers in Japan are expanding CEA testing capacity to capture post-surgical surveillance volumes shifting from inpatient settings.
- PCR-Based Reflex Testing:Molecular diagnostics laboratories are integrating CEA quantification with circulating tumor DNA analysis to reduce time-to-treatment decisions in colorectal cancer management.
Market Restraints
- Reagent Supply Concentration:Production of high-purity monoclonal antibodies for CEA immunoassays concentrates among contract manufacturers in Switzerland and the United States, exposing vendors to single-source risk.
- Analytical Specificity Limitations:Cross-reactivity with non-malignant conditions including smoking-related inflammation and benign liver disease generates false-positive rates that limit screening application expansion.
- PMDA Import Filters:Japan's Pharmaceuticals and Medical Devices Agency enforces stringent lot-release testing requirements that extend registration timelines for foreign CEA kit manufacturers by 18-24 months.
Strategic Opportunities
- India's Diagnostic Infrastructure Buildout:The country's PLI scheme for medical device manufacturing incentivizes domestic CEA assay production to serve underserved oncology screening populations in tier-2 and tier-3 cities.
- Liquid Biopsy Convergence:CEA quantification is converging with next-generation sequencing panels to create composite biomarker signatures for minimal residual disease monitoring in post-operative colorectal patients.
- Point-of-Care Expansion:Ambulatory surgery centers in Germany are piloting rapid CEA testing protocols to enable same-day treatment adjustment decisions without central laboratory turnaround delays.
Industry Challenges
- IVDR Technical Documentation Burden:The European regulation's expanded clinical evidence requirements for class C devices demand retrospective studies that compress R&D budgets and extend development cycles.
- Laboratory Information System Integration:Health systems in the United States require bidirectional HL7 connectivity for CEA results that legacy immunoassay platforms lack without expensive middleware upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carcinoembryonic Antigen (CEA) Market |
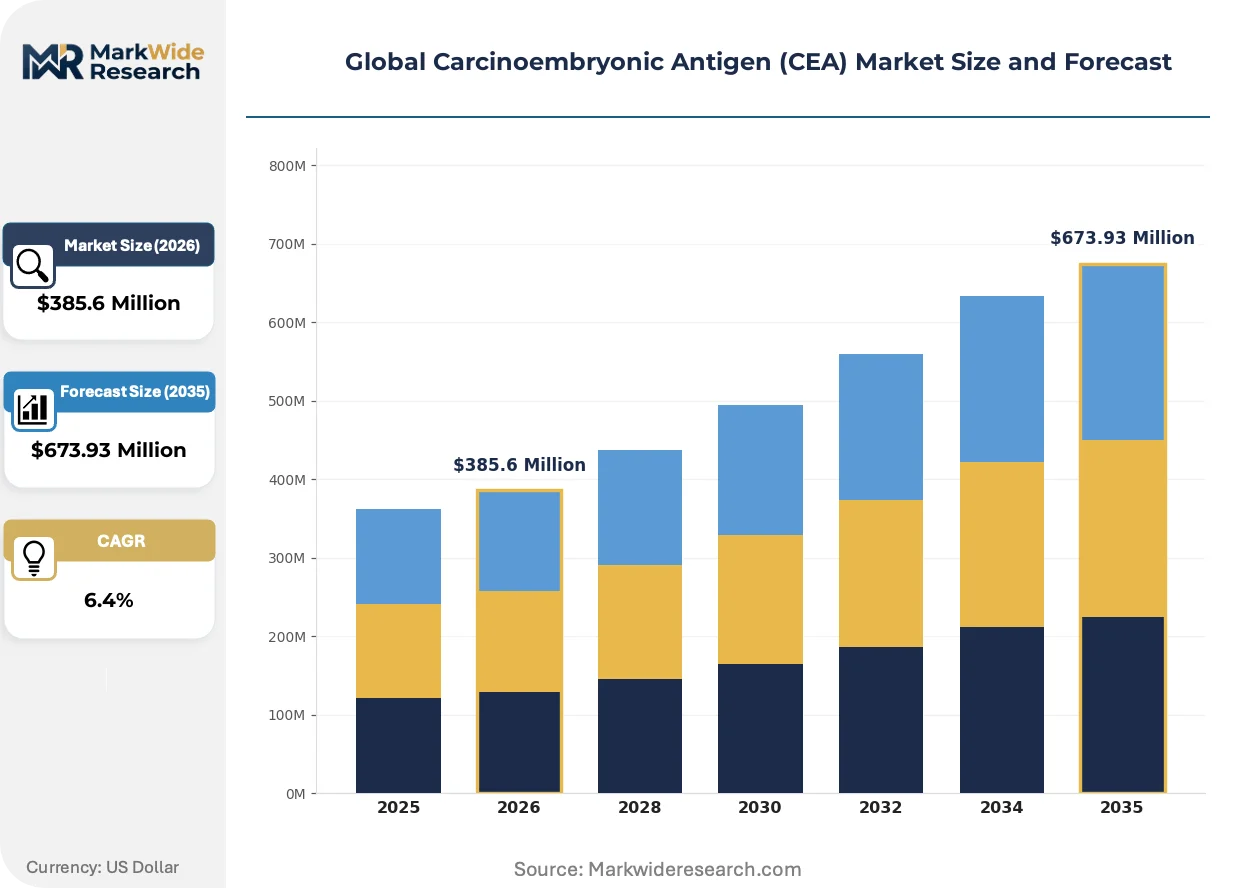
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Test Kits, Reagents, Analyzers, Calibration Tools Application: Oncology, Diagnosis, Monitoring, Research End User: Hospitals, Laboratories, Clinics, Diagnostic Centers Technology: ELISA, Immunohistochemistry, Molecular Diagnostics, Rapid Tests |
| Companies Covered | Siemens Healthineers, Bio-Techne Corporation, F. Hoffmann-La Roche (Roche Diagnostics), Quest Diagnostics, Merck KGaA, Abbott Laboratories, Danaher Corporation (Beckman Coulter), Tosoh Corporation, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carcinoembryonic Antigen (CEA) Market Strategic Shifts & Innovations
Automation architecture and regulatory harmonization are compressing competitive differentiation in CEA testing, while procurement centralization is redistributing vendor relationships toward enterprise-scale service partnerships.
Multiplex immunoassay platforms are converging with chemiluminescence detection to enable simultaneous quantification of CEA, CA 19-9, and CA 72-4 from single serum samples. Academic medical centers in the United States are adopting these consolidated panels to reduce sample volume requirements in pediatric and geriatric oncology populations. This convergence is compressing the addressable market for standalone CEA reagents while expanding total accessible revenue per test event.
REACH compliance obligations for hazardous substance documentation now extend to diagnostic reagent components imported into the European Union, affecting antibody conjugate formulations and preservative systems. Manufacturers are reformulating CEA assay diluents to eliminate classified substances ahead of 2026 registration deadlines. German and French reference laboratories are prioritizing suppliers with verified supply chain transparency to preempt audit findings.
Centralized procurement through group purchasing organizations is displacing hospital-level reagent selection autonomy in the United States. Oncology-focused GPOs are consolidating CEA testing contracts with vendors offering integrated analyzer placement and consumable bundling. This concentration is most visible in the southeastern United States, where regional health systems have consolidated laboratory management under shared service organizations.
Global Carcinoembryonic Antigen (CEA) Market Segmentation
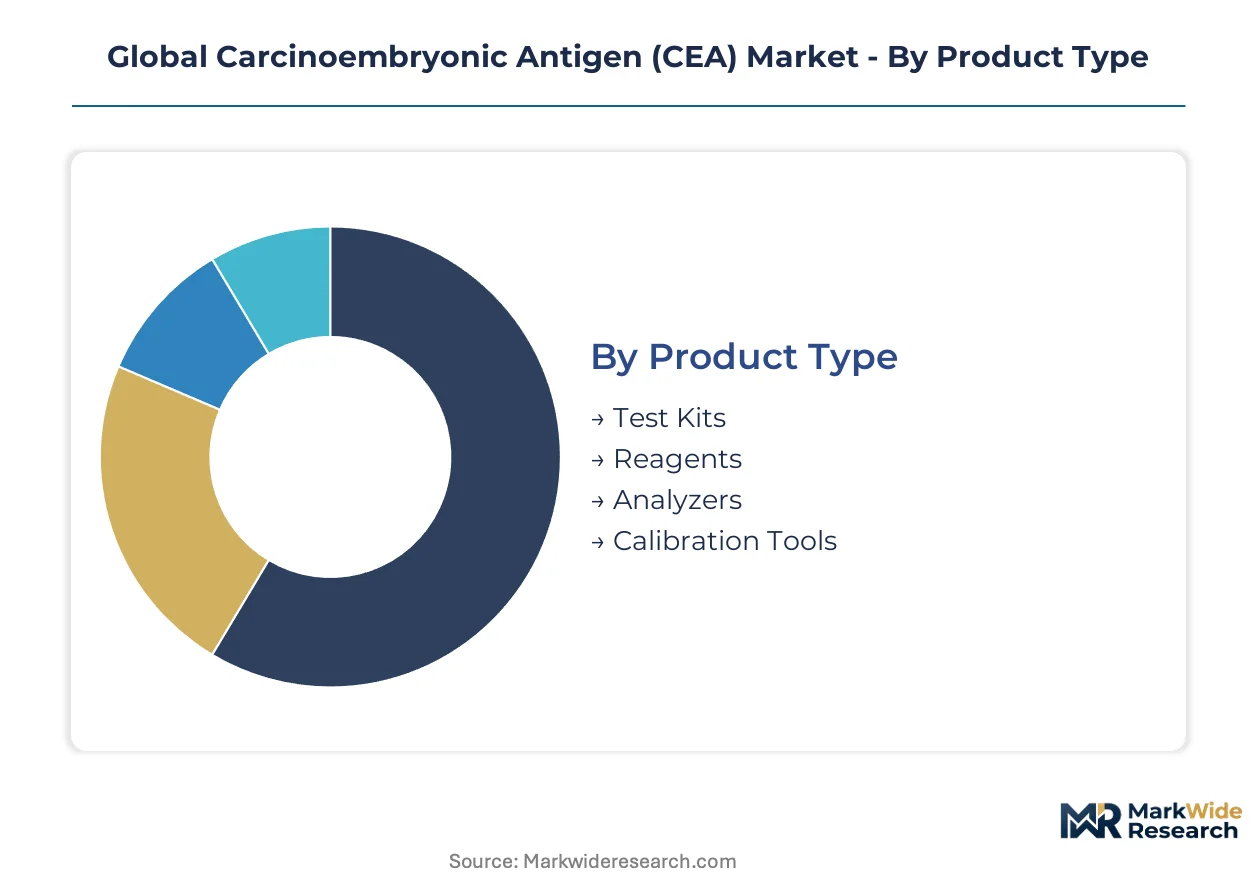
CEA testing configurations vary sharply by clinical setting and analytical requirement. Procurement patterns diverge across product categories, with consumables dominating recurring revenue while capital equipment anchors long-term vendor relationships.
Product Type:
Antibody specificity and reagent stability define competitive positioning within each tier.
- Test Kits:Pre-configured immunoassay panels with standardized calibrator ranges support high-throughput hospital laboratories. Siemens Healthineers and Roche Diagnostics compete for multi-year kit supply contracts across integrated delivery networks in the United States and Germany.
- Reagents:Monoclonal antibody conjugates and enzyme substrates constitute the highest-margin consumable category. Swiss contract manufacturers concentrate production of high-purity antibodies, exposing vendors to single-source supply risk.
- Analyzers:Automated chemiluminescence platforms require capital investment but lock in reagent purchasing through closed-system architectures. Japanese diagnostic centers prioritize analyzers with PMDA-validated traceability protocols.
- Calibration Tools:Certified reference materials and control sera ensure inter-laboratory result harmonization. EMA companion diagnostic guidelines are tightening validation requirements for calibrator lots entering European member states.
Test kits lead on scale; molecular diagnostic reagents lead on momentum.
Application:
Clinical utility varies by disease stage and treatment phase.
- Oncology:Serum CEA quantification guides staging decisions and chemotherapy response assessment in colorectal adenocarcinoma. Post-surgical surveillance protocols in Japan and Germany drive standardized testing intervals.
- Diagnosis:Adjunctive use alongside imaging and histopathology reduces false-negative rates in suspected malignancy. Limitations persist due to cross-reactivity with smoking-related inflammation and benign hepatic conditions.
- Monitoring:Serial measurement tracks minimal residual disease and early recurrence. Outpatient diagnostic centers in the United States are capturing volumes shifting from inpatient settings.
- Research:Biomarker discovery applications employ CEA as a reference analyte in multiplex assay development. Academic medical centers prioritize suppliers with documented antibody clone provenance.
Oncology commands installed base; research applications are climbing the fastest.
End User:
Facility type determines throughput requirements and connectivity specifications.
- Hospitals:Central laboratories process thousands of CEA determinations monthly, requiring bidirectional HL7 integration with electronic health records. Legacy immunoassay platforms face expensive middleware upgrades to meet interoperability mandates.
- Laboratories:Independent reference labs compete on turnaround time and specialized oncology panels. Consolidation among United States group purchasing organizations is compressing vendor margins.
- Clinics:Limited test volumes favor send-out arrangements rather than on-site analyzer placement. Point-of-care pilot programs in German ambulatory surgery centers may shift this dynamic.
- Diagnostic Centers:Dedicated oncology monitoring facilities in Japan are expanding capacity to capture post-surgical surveillance volumes. PMDA lot-release testing requirements filter non-compliant imports.
Hospitals anchor procurement volume; diagnostic centers show steepest expansion trajectory.
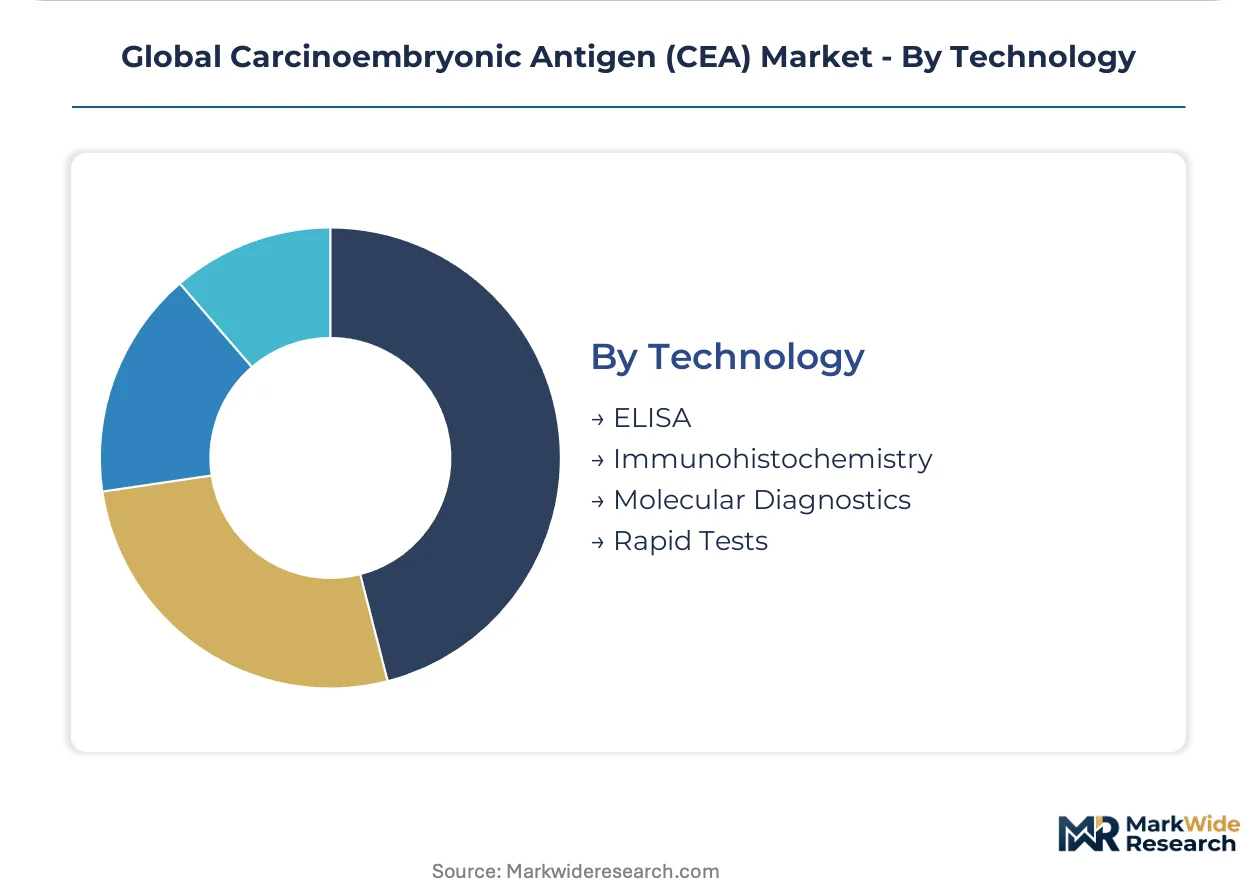
Technology:
Detection chemistry and platform architecture determine sensitivity specifications.
- ELISA:Enzyme-linked immunosorbent assays remain the workhorse methodology in resource-constrained settings. India's PLI scheme for medical device manufacturing is incentivizing domestic ELISA kit production.
- Immunohistochemistry:Tissue-based CEA detection supports primary tumor characterization and metastasis confirmation. Pathology laboratories require antibody clones with verified lot-to-lot consistency.
- Molecular Diagnostics:PCR-based reflex testing integrates CEA quantification with circulating tumor DNA analysis. This convergence is gaining share fastest in academic medical centers seeking composite biomarker signatures.
- Rapid Tests:Lateral flow formats enable same-day result delivery in ambulatory settings. Analytical sensitivity limitations restrict application to screening rather than quantitative monitoring.
ELISA maintains broadest installed base; molecular diagnostics platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's hospital laboratories process higher CEA testing volumes per capita than Japan's diagnostic centers, though Tokyo's outpatient monitoring facilities are expanding faster than Berlin's central lab networks.
United States
Integrated delivery networks in Texas and Florida are consolidating oncology laboratory procurement under single vendor contracts. FDA's IVDR alignment initiatives are compressing compliance timelines for CEA assay registrants. The southeastern hospital cluster spanning Georgia and the Carolinas is migrating to automated chemiluminescence platforms.
Germany
Ambulatory surgery centers in Bavaria are piloting rapid CEA protocols for same-day treatment adjustments. EMA companion diagnostic guidelines are tightening calibrator validation requirements for assays entering European member states. The Baden-Württemberg medical technology corridor is hosting reformulation efforts to eliminate REACH-classified substances from reagent diluents.
Japan
Post-surgical surveillance volumes are shifting from Tokyo university hospitals to dedicated diagnostic centers in Osaka and Nagoya. PMDA enforces lot-release testing that extends foreign kit registration timelines by 18-24 months. The Kansai region's oncology monitoring facilities are capturing incremental CEA testing capacity from inpatient settings.
India
Tier-2 cities in Maharashtra and Gujarat are building diagnostic infrastructure to serve underserved oncology screening populations. The PLI scheme for medical device manufacturing is incentivizing domestic ELISA kit production. The Karnataka medical device cluster in Bangalore is attracting contract manufacturing investment for antibody conjugate formulations.
Switzerland
Contract manufacturers in Basel and Zurich concentrate production of high-purity monoclonal antibodies for CEA immunoassays. Swissmedic maintains stringent analytical performance criteria that filter non-compliant imports. The country's antibody production facilities are expanding capacity to address single-source supply risks flagged by downstream assay vendors.
Global Carcinoembryonic Antigen (CEA) Market Key Industry Players
United States producers anchor one tier; German and Swiss specialists hold differentiated positions in reagent-grade antibody supply. The vendor base stratifies across three layers: diversified diagnostics conglomerates with installed analyzer bases, precision reagent specialists controlling antibody supply chains, and regional kit assemblers serving price-sensitive markets. Strategic archetypes include platform-integrated service providers, upstream antibody specialists, and automated system bundlers. Competitive moves center on multi-year enterprise contract capture and backward integration into antibody production.
Among diversified diagnostics conglomerates, Siemens Healthineers and Roche Diagnostics exemplify platform-integrated service providers that leverage installed immunoassay analyzer bases to secure long-term reagent supply contracts. Danaher Corporation occupies a position within the precision instrumentation tier through its Beckman Coulter subsidiary. These three anchors represent distinct competitive vectors: Siemens Healthineers emphasizes service contract retention across integrated delivery networks, Roche Diagnostics anchors high-throughput laboratory automation, and Danaher Corporation exemplifies consolidation-driven portfolio breadth in clinical diagnostics.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Bio-Techne Corporation |
| F. Hoffmann-La Roche (Roche Diagnostics) |
| Quest Diagnostics |
| Merck KGaA |
| Abbott Laboratories |
| Danaher Corporation (Beckman Coulter) |
| Tosoh Corporation |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
PCR-based reflex testing convergence is compressing standalone CEA reagent margins while simultaneously concentrating procurement power among integrated delivery networks in the United States and Germany. This dual shift forces vendors to absorb cost pressures from monoclonal antibody supply constraints while negotiating multi-year enterprise contracts that lock in pricing trajectories.
Pricing Analysis
Capacity additions in India's ELISA manufacturing base are reshaping price floors for economy-tier test kits while premium chemiluminescence platforms sustain value capture through closed-system reagent bundling. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated assays from CE-marked alternatives and domestically produced kits. Cost compression in the standard tier intensifies because Indian PLI-subsidized production is flooding tier-2 city markets. Diagnostic centers in Japan exhibit lowest price sensitivity due to PMDA-mandated quality premiums, while Indian clinics drive hardest bargain on per-test economics.
Supply Chain Analysis
High-purity monoclonal antibody production rests on Swiss contract manufacturers in Basel and Zurich, with secondary concentration among United States bioprocessing facilities. CEA immunoassay vendors draw from recombinant antibody cell lines, enzyme substrate conjugates, and certified reference sera as critical inputs. Single-source vulnerability dominates risk profile because Swiss facilities supply multiple competing assay vendors simultaneously. Distribution runs through regional diagnostic distributors in Europe, direct hospital contracts in North America, and government procurement channels in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where post-surgical surveillance protocols in Japan and Germany are shifting demand toward premium-tier platforms with PMDA-validated traceability.
For Market Incumbents: Deepen backward integration into monoclonal antibody production to neutralize Swiss supply concentration risk. Lock in multi-year service contracts across southeastern United States integrated delivery networks before Indian ELISA producers achieve FDA registration. Molecular diagnostics substitution represents the primary threat to standalone CEA reagent volumes. For New Entrants and Emerging Players: The premium-economy price gap in Indian tier-2 cities creates white-space opportunity for domestically manufactured ELISA kits with CDSCO registration. Target Maharashtra and Gujarat diagnostic infrastructure buildout where PLI subsidies compress capital requirements. Pursue GPO bypass strategy selling direct to emerging diagnostic center chains. For Investors and Strategic Acquirers: Valuations sit cheapest among precision reagent specialists controlling antibody clone libraries without captive analyzer platforms. Five-to-ten year viability hinges on convergence with liquid biopsy workflows. Acquisition target archetype: Swiss or United States-based contract manufacturers with documented CEA antibody provenance. Watch PMDA registration timeline acceleration as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Technical Documentation Completion | EMA recertification deadlines force legacy assay portfolio overhaul across European reference laboratories. |
| Monoclonal Antibody Production Backward Integration | Captive supply of high-purity antibodies neutralizes Swiss single-source vulnerability for assay vendors. |
| Diagnostic Center Partnership Expansion | Osaka and Nagoya outpatient facilities capture post-surgical surveillance volumes from Tokyo university hospitals. |
| Multiplex Immunoassay Platform Development | Simultaneous CEA-CA 19-9-CA 72-4 quantification reduces sample volume requirements in pediatric oncology. |
| HL7 Bidirectional Connectivity Upgrade | Middleware integration meets United States hospital electronic health record interoperability mandates. |
Research Approach
Bottom-up hospital laboratory modeling reconciled against top-down immunoassay reagent tracking forms the analytical core of this study. Primary interviews with hospital procurement managers, GPO contracts directors, biomedical engineers, and regulatory affairs leads at IVD manufacturers were validated against secondary sources including FDA 510(k) filings, EMA companion diagnostic guidelines, PMDA lot-release databases, and hospital procurement contract repositories. Triangulation across these inputs ensures segmentation integrity.
Input-output matrices connect CEA test volume assumptions to reagent consumption rates across ELISA, chemiluminescence, and molecular diagnostic platforms. Segmentation dimensions modeled include product type tier, application clinical utility, end-user facility category, and detection technology chemistry. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window. Forecast inputs incorporate IVDR transition compliance timelines and India's PLI scheme capacity buildout trajectories.
Caveats apply where PMDA registration timeline extensions or IVDR technical documentation rejections could materially shift the outlook. Forecasts reflect assumptions regarding regulatory harmonization progress and antibody supply chain stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Atipamezole Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Mammalian Derived Proteins Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
HIV Market
Biopharmaceuticals
Polyclonal Antibodies Market
Biopharmaceuticals
North Africa Generic Drug Market
Biopharmaceuticals
Global Thrombin Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Canada Generic Drug Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
United Kingdom Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Hemophilia B Market
Biopharmaceuticals
Global Immuno Oncology Assays Market