
 United Kingdom Insulin Drugs and Delivery Devices Market | 2026-2036
United Kingdom Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Insulin Drugs and Delivery Devices Market Analytics
Specialist diabetes nurse capacity is rotating toward community-based care models, stretching hospital-based delivery while expanding home administration training. Novo Nordisk leverages its integrated insulin and pen-needle portfolio to sustain formulary positioning across NHS integrated care boards. Sanofi anchors its presence through basal insulin analogues that compete on total cost-of-treatment metrics within NICE appraisals.
Insulin drugs and delivery devices comprise biologically active peptide formulations for glycemic control paired with mechanical or electronic systems for parenteral administration, typically requiring refrigeration at two to eight degrees Celsius and subcutaneous injection via precision-calibrated dosing mechanisms. The primary purpose is maintaining euglycemia in patients with absolute or relative insulin deficiency. Insulin pens occupy the largest volume position due to NHS preference for reusable and disposable pen systems that reduce dosing error rates. Continuous glucose monitors represent the fastest-expanding segment as real-time data integration with insulin pumps advances closed-loop therapy adoption.
MHRA regulates device safety and performance standards independently from EMA frameworks post-Brexit, while NICE technology appraisals determine reimbursement eligibility and prescribing guidelines for insulin therapies across the four UK nations. NHS England's Diabetes Transformation Programme shapes procurement centralization and care pathway redesign. Stakeholders must monitor MHRA recognition route convergence with FDA and TGA standards as divergence risk affects future device registration strategies.
Market Dynamics
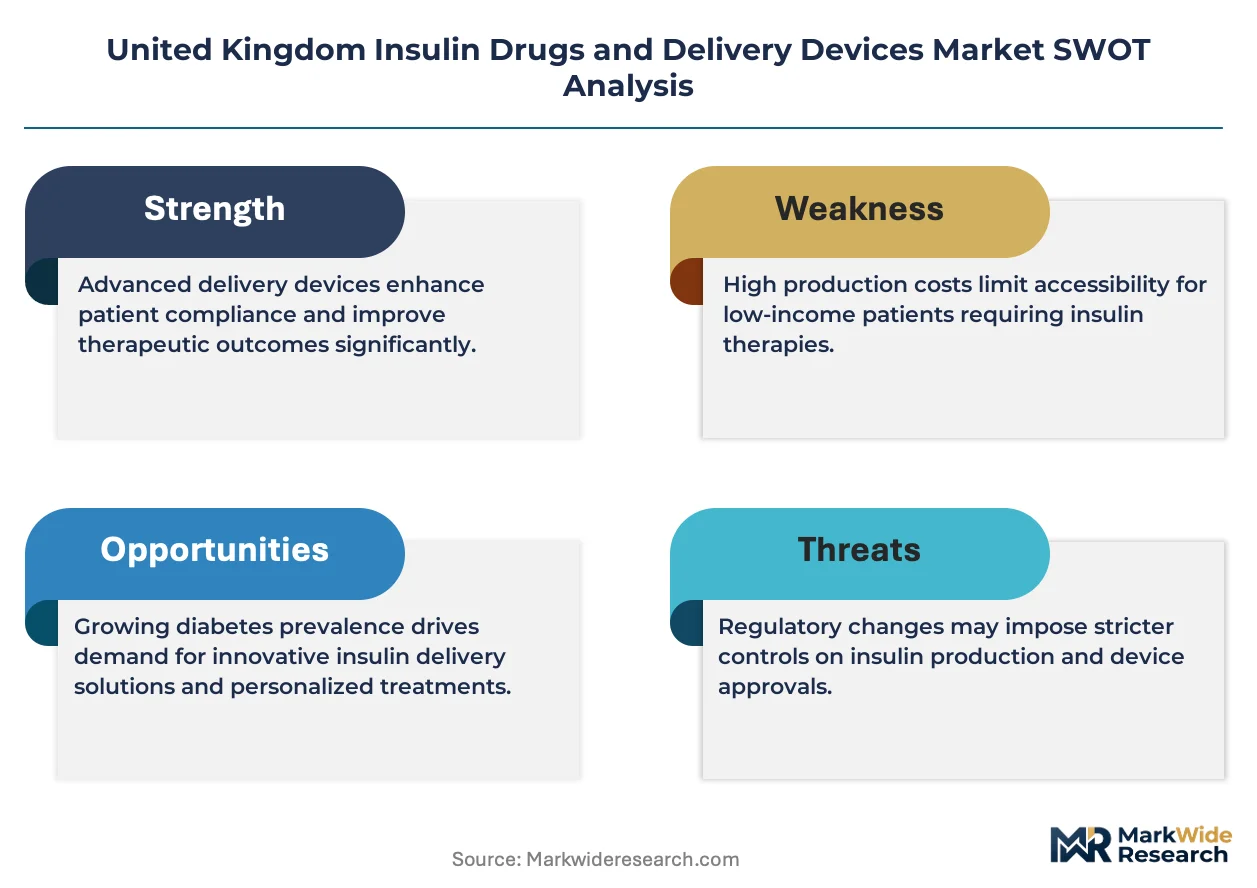
NHS England's Diabetes Transformation Programme is consolidating procurement authority into integrated care boards, compressing vendor margins while expanding community-based insulin administration pathways.
Growth Catalysts
- ICB Centralisation:NHS England's integrated care boards aggregate hospital and community procurement volumes, creating formulary leverage for preferred insulin delivery systems.
- MHRA Recognition Route Convergence:The UK's post-Brexit regulatory alignment with FDA and TGA standards accelerates device registration timelines for manufacturers holding parallel approvals.
- Homecare Expansion:Specialist diabetes nurse redeployment toward community settings drives demand for patient-administered pen systems and remote monitoring infrastructure.
Market Restraints
- Reimbursement Compression:NICE technology appraisals impose total cost-of-treatment ceilings that constrain premium insulin analogue pricing within NHS formularies.
- Cold Chain Fragility:Two-to-eight-degree Celsius storage requirements for biological insulin formulations create distribution vulnerability during last-mile delivery to dispersed community pharmacies.
- Pen-Needle Waste Regulation:Sharps disposal compliance costs escalate as local authorities enforce stricter healthcare waste segregation standards.
Strategic Opportunities
- Closed-Loop Integration:Continuous glucose monitor data streams converging with algorithm-driven insulin pumps enable automated glycemic control for Type 1 diabetes patients.
- Scotland and Wales Penetration:Devolved health authorities in Edinburgh and Cardiff operate distinct procurement frameworks with less consolidated vendor relationships than England's ICBs.
- Digital Therapeutics Bundling:MHRA's software-as-medical-device pathway permits insulin dose optimisation apps to qualify for NHS reimbursement alongside hardware systems.
Industry Challenges
- Specialist Nurse Capacity:Community care model expansion stretches hospital-based diabetes specialist nurse availability for complex insulin initiation protocols.
- Legacy Device Interoperability:Closed-loop system adoption requires integration with existing pen-needle and pump infrastructures that lack standardised data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Insulin Drugs and Delivery Devices Market |
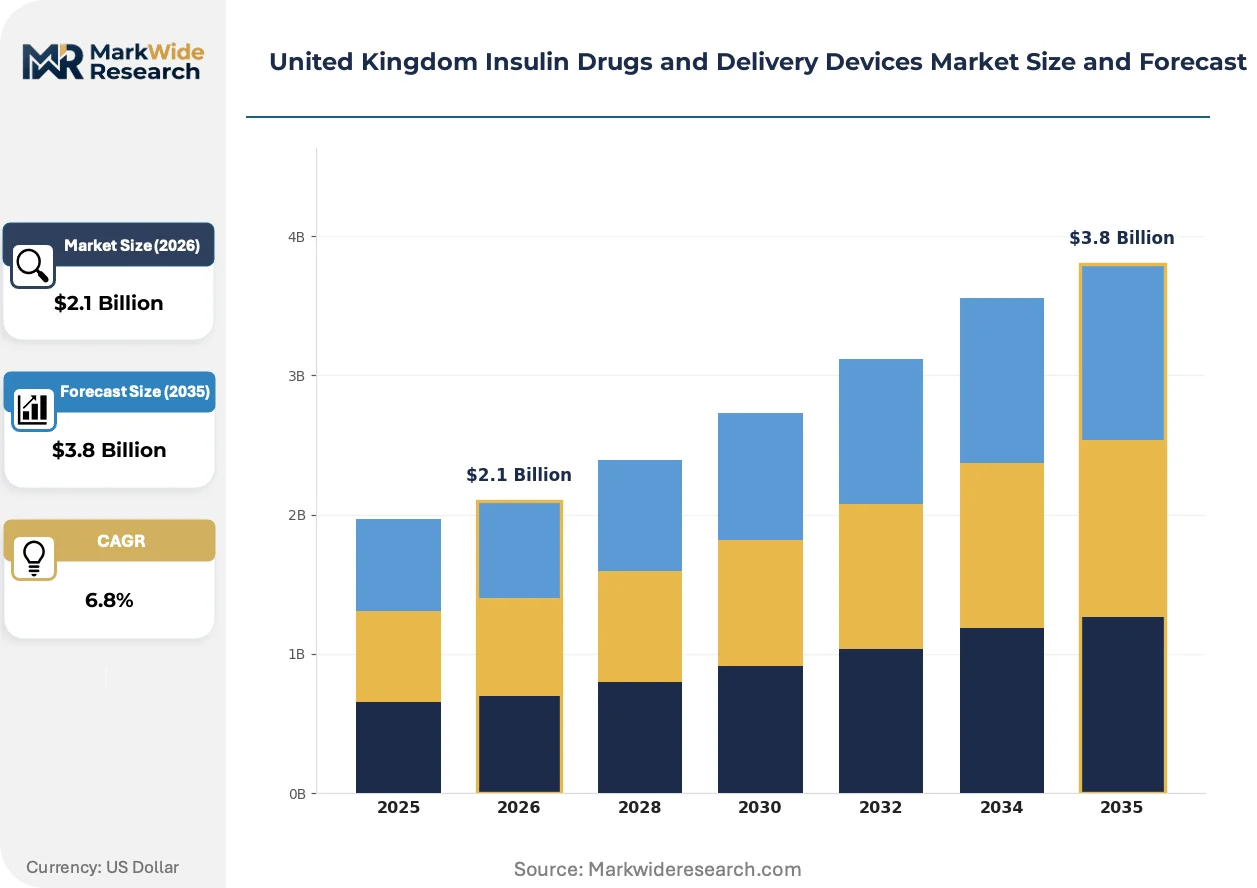
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Insulin Pens, Insulin Pumps, Continuous Glucose Monitors Delivery Mode: Subcutaneous, Intravenous, Inhalation, Transdermal Therapy Area: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Prediabetes End User: Hospitals, Clinics, Homecare, Pharmacists |
| Companies Covered | Novo Nordisk, Sanofi, Eli Lilly and Company, Medtronic, Ypsomed, Biocon, Becton Dickinson, Julphar, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Insulin Drugs and Delivery Devices Market Evolving Landscape
Real-time glycemic data integration is displacing episodic glucose monitoring across NHS pathways, while regulatory divergence post-Brexit forces manufacturers to maintain parallel conformity assessment procedures.
Closed-loop artificial pancreas systems are fragmenting the traditional separation between glucose sensing and insulin delivery. Paediatric endocrinology units within England's metropolitan hospital trusts adopt these systems at the fastest pace. The technology is fragmenting market share between integrated platform vendors and component specialists competing on interoperability claims.
MHRA's independent device regulation post-Brexit extends approval timelines for novel delivery mechanisms lacking prior EMA clearance. Manufacturers now maintain dual technical documentation sets to satisfy UK and EU conformity routes simultaneously. Insulin pump innovators with existing FDA approvals leverage MHRA's recognition route to compress UK market entry schedules.
Hospital trusts are unbundling insulin delivery device procurement from glucose monitoring supply contracts. Community pharmacy networks capture increasing device dispensing volume as homecare pathways expand. This pattern concentrates in England's former sustainability and transformation partnership regions where ICB consolidation is most advanced.
United Kingdom Insulin Drugs and Delivery Devices Market Segmentation
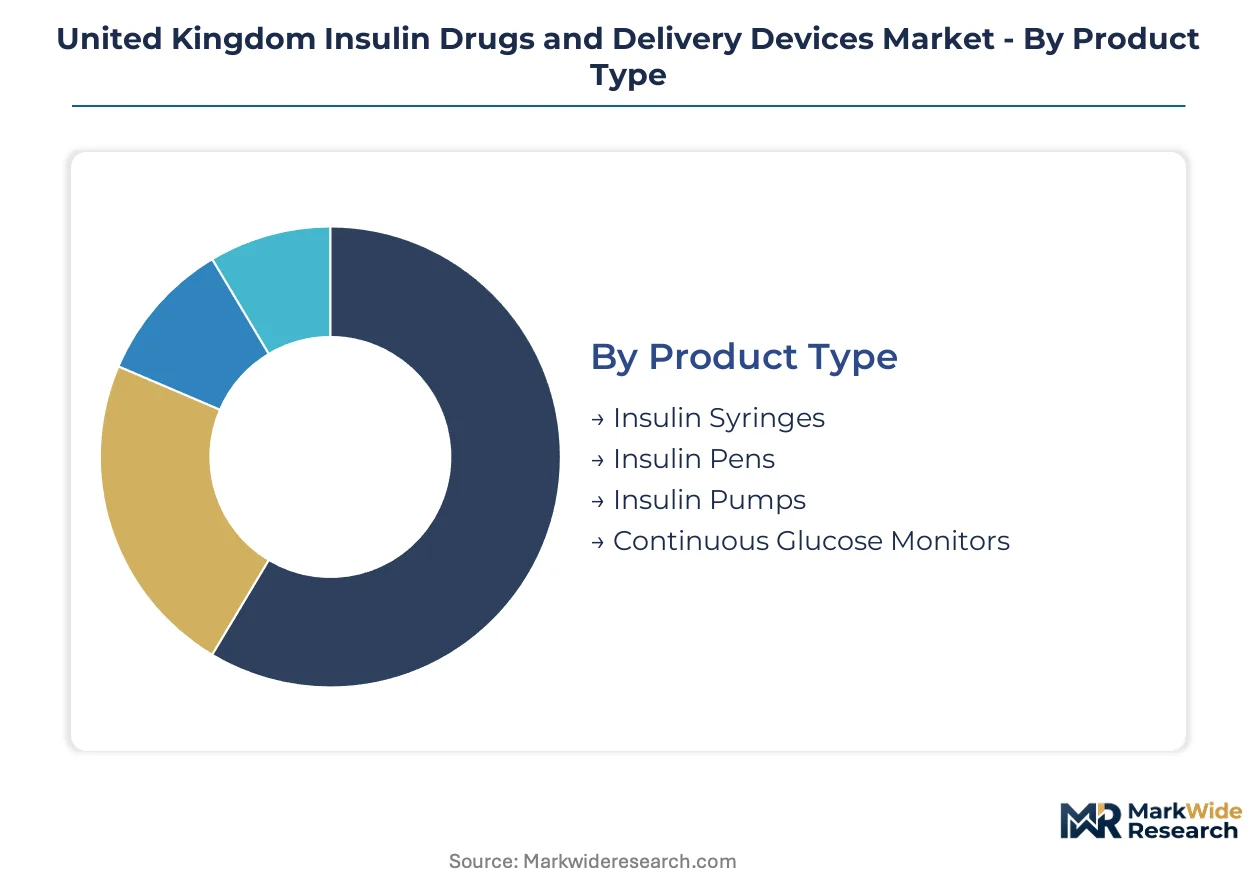
Segmentation in the United Kingdom insulin market reveals how NHS procurement centralisation and care pathway redesign favour specific device formats over others. Substitution pressure between traditional injection systems and sensor-augmented pump therapy is intensifying as integrated care boards consolidate formularies.
Product Type:
Substitution pressure is strongest against legacy syringe systems as NHS trusts prioritise precision dosing and reduced error rates in their procurement specifications.
- Insulin Syringes:Conventional glass-barrel syringes with fixed or detachable needles calibrated for unit-specific dosing. Demand concentrates in England's smaller community pharmacies serving elderly populations with established injection routines, though NHS England's formulary shifts are compressing volumes.
- Insulin Pens:Reusable and disposable pen systems incorporating dose-memory functions and half-unit increments. Metropolitan hospital trusts in Greater Manchester and West Midlands are standardising on pen-based protocols to reduce medication errors during inpatient insulin administration.
- Insulin Pumps:Battery-powered devices delivering continuous subcutaneous insulin infusion with programmable basal rates. Specialist diabetes centres in London and Birmingham are expanding pump initiation capacity for Type 1 cohorts.
- Continuous Glucose Monitors:Sensor-based systems transmitting interstitial glucose data to receivers or smartphones. Scotland's NHS boards are deploying these at scale for paediatric patients, creating procurement templates England's ICBs are adopting.
Insulin pens retain volume leadership; continuous glucose monitors hold the steepest expansion curve.
Delivery Mode:
Cost tier stratification is pronounced across delivery modes, with subcutaneous dominating NHS expenditure while inhalation and transdermal formats target premium self-pay segments.
- Subcutaneous:Injection into adipose tissue via pen, syringe, or pump cannula, the established standard for all insulin analogues. NHS homecare expansion is driving demand for patient-administered subcutaneous systems with simplified training protocols.
- Intravenous:Direct vascular infusion restricted to perioperative and critical care settings. England's tertiary hospital trusts maintain intravenous insulin protocols for diabetic ketoacidosis management.
- Inhalation:Pulmonary delivery of powdered human insulin via breath-activated devices. Private diabetes clinics in London and Harley Street medical district represent the primary demand concentration given NICE reimbursement constraints.
- Transdermal:Microneedle patches and iontophoretic systems in early commercialisation. MHRA's software-as-medical-device pathway is enabling digital therapeutic bundling with transdermal platforms.
Subcutaneous delivery commands the expenditure base; transdermal formats are climbing the fastest despite regulatory headwinds.
Therapy Area:
Application urgency varies sharply across therapy areas, with Type 1 diabetes mandating immediate insulin initiation while Type 2 progression allows oral agent sequencing.
- Type 1 Diabetes:Absolute insulin deficiency requiring exogenous replacement from diagnosis. Paediatric endocrinology units in Birmingham Children's Hospital and Great Ormond Street are adopting closed-loop systems for this cohort.
- Type 2 Diabetes:Progressive insulin resistance with relative deficiency, typically requiring insulin only after oral therapy failure. NHS England's Diabetes Transformation Programme is accelerating insulin initiation in primary care for this largest patient segment.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring tight glycemic targets. Maternity units across England's former sustainability and transformation partnership regions are standardising insulin pen protocols.
- Prediabetes:Elevated glucose below diabetes threshold, rarely requiring insulin. Community pharmacy screening programmes in Wales are identifying conversion risks for early intervention.
Type 2 diabetes generates the patient volume base; Type 1 diabetes shows the steepest technology adoption trajectory.
End User:
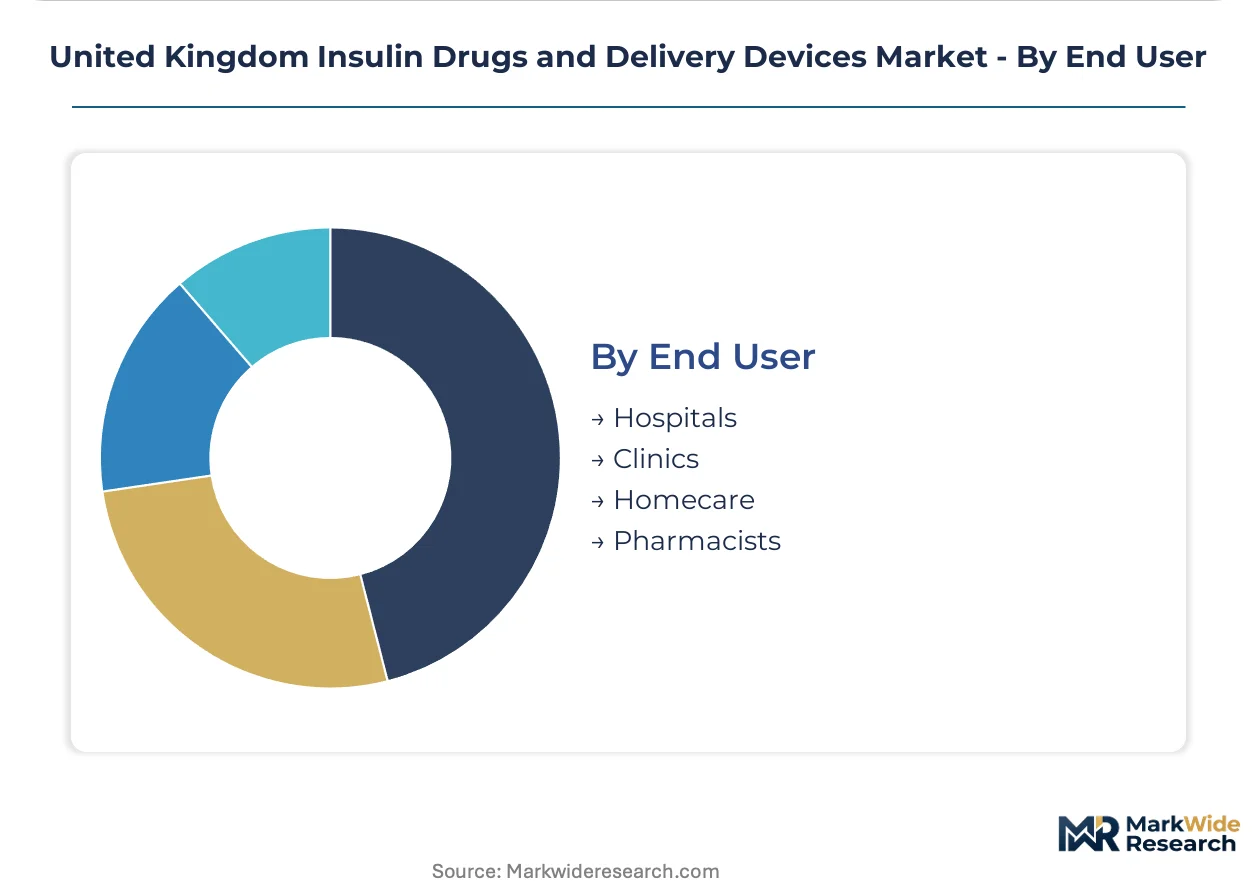
Customer type fragmentation is narrowing as NHS England consolidates procurement authority into integrated care boards, compressing the distinction between hospital and community acquisition channels.
- Hospitals:Acute trusts managing inpatient glycemic control and complex insulin initiation. England's metropolitan hospital trusts are unbundling device procurement from glucose monitoring contracts.
- Clinics:Outpatient specialist diabetes services and primary care networks. Scotland's regional health boards are deploying community clinic-based insulin optimisation programmes.
- Homecare:Patient-administered therapy with remote specialist nurse oversight. Specialist diabetes nurse redeployment from hospitals to community settings is expanding homecare device dispensing.
- Pharmacists:Community pharmacies handling device supply and injection training. Wales and Northern Ireland operate distinct pharmacy-led insulin supply frameworks separate from England's ICB consolidation.
Homecare channels are gaining share fastest; hospital procurement retains the largest contract value concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's integrated care boards command stronger formulary leverage than Scotland's devolved procurement frameworks, creating pricing-power asymmetry across the UK's four nations. NHS England's Diabetes Transformation Programme consolidates purchasing authority while Edinburgh and Cardiff operate distinct vendor relationships. The analysis examines sub-regional dynamics within England, Scotland, Wales, and Northern Ireland.
London and the Southeast
Metropolitan hospital trusts in Greater London and the Thames Valley generate concentrated demand for closed-loop insulin systems and continuous glucose monitors. NHS England's specialised commissioning hub at NHS England London coordinates procurement for complex diabetes technologies across 40 acute trusts. Paediatric endocrinology units at Great Ormond Street Hospital and Evelina London Children's Hospital are adopting sensor-augmented pump therapy at scale.
Midlands and North England
Former sustainability and transformation partnership regions in West Midlands and Greater Manchester are standardising pen-based insulin protocols to reduce medication errors during inpatient care. NHS England's Midlands and North West integrated care boards aggregate community pharmacy dispensing volumes for homecare device distribution. Birmingham Children's Hospital anchors specialist pump initiation capacity for the region's Type 1 diabetes cohort.
Scotland
NHS Scotland's national procurement framework deploys continuous glucose monitors at scale for paediatric patients, creating template contracts England's ICBs subsequently adopt. Health boards in Edinburgh and Glasgow operate less consolidated vendor relationships than England's ICBs, preserving niche supplier access. Scotland's distinct technology appraisal process through the Scottish Medicines Consortium evaluates insulin therapies on quality-adjusted life year metrics that diverge from NICE methodologies.
Wales and Northern Ireland
Community pharmacy networks in Wales handle device supply and injection training through pharmacy-led frameworks separate from England's ICB consolidation. Northern Ireland's Health and Social Care Board coordinates cross-border procurement with Republic of Ireland health services for certain diabetes technologies. Belfast's regional specialist centre manages complex insulin initiation for the province's dispersed rural population.
United Kingdom Insulin Drugs and Delivery Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the UK insulin market. Integrated platform vendors with closed-loop capabilities command premium positioning within NHS specialist commissioning, while pen-needle and basal insulin specialists compete on total cost-of-treatment metrics in primary care formularies. The market structure separates into three strategic archetypes: full-stack diabetes technology integrators, analogue insulin portfolio players, and device component specialists. Dominant competitive moves include formulary bundling of hardware and consumables and geographic targeting of devolved procurement frameworks outside England's ICB consolidation.
Among the integrated platform vendors, Novo Nordisk and Medtronic exemplify contrasting approaches to NHS market access. Novo Nordisk occupies a position spanning biologic insulin production and precision delivery devices, while Medtronic anchors the algorithm-driven pump segment. Sanofi represents the analogue insulin portfolio archetype, competing within NICE appraisals on long-acting formulations. These three companies illustrate how technology depth versus therapeutic breadth shapes competitive positioning under NHS procurement centralisation.
| Leading Market Players |
|---|
| Novo Nordisk |
| Sanofi |
| Eli Lilly and Company |
| Medtronic |
| Ypsomed |
| Biocon |
| Becton Dickinson |
| Julphar |
| Abbott Laboratories |
| Others |
Value Network & Pricing Analysis
Pen-needle substitution for traditional syringe systems simultaneously concentrates manufacturing in Denmark and Switzerland while compressing margin structures across England's integrated care boards. This input shift forces suppliers to absorb cold-chain logistics costs that previously distributed across fragmented procurement channels.
Pricing Analysis
Geographic price spreads between London's specialist commissioning hubs and Northern England's consolidated ICBs reach three-to-one ratios for identical pump configurations. Three-tier pricing structure across premium closed-loop systems, standard sensor-augmented pumps, and economy pen-needle bundles dominates NHS formularies. Cost compression in the standard tier is intensifying because NICE total cost-of-treatment ceilings harden annually. Community pharmacies serving homecare pathways exhibit highest price sensitivity; specialist paediatric centres demonstrate lowest.
Supply Chain Analysis
Denmark and Switzerland anchor precision pen-needle manufacturing while Ireland and Singapore host biologic insulin fill-finish operations. Active pharmaceutical ingredients draw from recombinant DNA fermentation processes resting on yeast cell banks and chromatography resins. Single-source vulnerability concentrates in temperature-controlled last-mile distribution to dispersed community pharmacies. Distribution runs through NHS Supply Chain central warehouses into ICB-managed regional hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through NHS England's ICB consolidation, compressing vendor margins while elevating formulary leverage for integrated platform suppliers.
For Market Incumbents: Compound formulary positioning by bundling continuous glucose monitors with insulin pump consumables under single-contract NHS frameworks. Deepen backward integration into pen-needle manufacturing to defend against emerging low-cost Asian suppliers. Prioritise MHRA recognition route alignment with FDA standards to compress approval timelines for next-generation closed-loop algorithms. For New Entrants and Emerging Players: Remote patient monitoring infrastructure represents the most penetrable service-layer gap where incumbents under-serve rural Scottish health boards and Northern Irish dispersed populations. Target Wales's pharmacy-led supply frameworks that operate outside England's ICB consolidation. Deploy direct specialist nurse training partnerships as the primary go-to-market angle rather than hospital procurement channels. For Investors and Strategic Acquirers: Capital is best deployed toward algorithm-driven pump specialists with existing FDA clearances and MHRA recognition pathway documentation. Long-term viability hinges on platform interoperability rather than closed-loop exclusivity. Watch Scotland's national procurement framework adoption rates as the inflection indicator for England's ICB template migration.| Strategic Initiative | Industry Significance |
|---|---|
| MHRA Recognition Route Alignment | Accelerates device registration for manufacturers holding parallel FDA and TGA approvals. |
| Closed-Loop System Integration | Positions vendors for NHS specialist commissioning hub contracts in Greater London. |
| Community Nurse Training Partnerships | Captures homecare pathway volume as specialist diabetes nurses redeploy from hospitals. |
| Digital Therapeutic Bundling | Qualifies insulin dose optimisation apps for NHS reimbursement alongside hardware systems. |
| Devolved Procurement Targeting | Exploits less consolidated vendor relationships in Scotland and Wales outside England's ICBs. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of MHRA device registration databases, NICE technology appraisal documentation, and NHS England procurement contract notices. Interviews with integrated care board pharmacy leads, specialist diabetes nurse consultants, hospital biomedical engineers, and medical device regulatory affairs directors informed demand-side assumptions. Secondary validation drew from ClinicalTrials.gov entries, NHS Supply Chain tender awards, and MHRA post-market surveillance reports. Bottom-up volume estimates triangulated against top-down NHS expenditure data.
Segmentation dimensions modeled include insulin delivery format, administration route, diabetes type, and care setting across the projection horizon. CAGRs derived from regression analysis of historical procurement volumes against ICB consolidation timelines and technology substitution curves. Forecast inputs incorporated NICE appraisal decision schedules and MHRA recognition route adoption rates for parallel-approved devices.
Underlying assumptions cover stable NHS funding allocations and continued ICB procurement centralisation, with deviation risk concentrated in regulatory divergence between MHRA and FDA standards. Forecasts reflect these conditions without claiming predictive certainty. Recalibration cycles align with material shifts in NICE technology appraisal outcomes and MHRA guidance updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Carcinoembryonic Antigen (CEA) Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Discovery Bioanalysis Market
Biopharmaceuticals
Female Infertility Drugs Market
Biopharmaceuticals
Biopharmaceutical Fermentation Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Next Generation Antibody Therapeutics Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Oligonucleotide API Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Global Biopharmaceuticals Market
Biopharmaceuticals
Peptide Antibiotics Market