
 Global Anti-Tuberculosis Therapeutics Market | 2026-2036
Global Anti-Tuberculosis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Tuberculosis Therapeutics Market Foresight
Short-course oral regimens is narrowing the development focus away from prolonged injectable protocols across the anti-tuberculosis pipeline. Johnson & Johnson Services, Inc. anchors its position through bedaquiline-based combination platforms for multidrug-resistant strains. Lupin Limited leverages vertically integrated API-to-finished-dose manufacturing to sustain cost leadership in first-line generic supply. Otsuka Pharmaceutical Co., Ltd. differentiates through delamanid access programs targeting extensively drug-resistant tuberculosis in limited-resource settings.
Anti-tuberculosis therapeutics comprise pharmaceutical agents targeting Mycobacterium tuberculosis infection, formulated as single agents or fixed-dose combinations typically containing rifamycin derivatives, isoniazid, pyrazinamide, or ethambutol with defined bioequivalence thresholds. These products serve to eradicate active infection, prevent latent reactivation, and reduce transmission in high-prevalence populations. First-line drugs still occupy the largest revenue pool due to standardized national program procurement, though new chemical entities command premium positioning where resistance profiles demand novel mechanisms. Nanoparticle-based formulations represent the fastest-growing delivery segment as manufacturers pursue improved bioavailability and reduced dosing frequency to enhance patient adherence.
FDA, EMA, and WHO prequalification standards collectively determine market access for anti-tuberculosis therapeutics, with stringent bioequivalence and stability requirements shaping regional registration strategies. The EU MDR and WHO PQ pathways create divergent compliance burdens that favor manufacturers with dedicated regulatory affairs capacity across multiple geographies. Stakeholders must monitor how national TB program formularies evolve toward shorter all-oral regimens and whether domestic production incentives in high-burden countries redirect procurement flows away from established multinational suppliers.
Market Dynamics
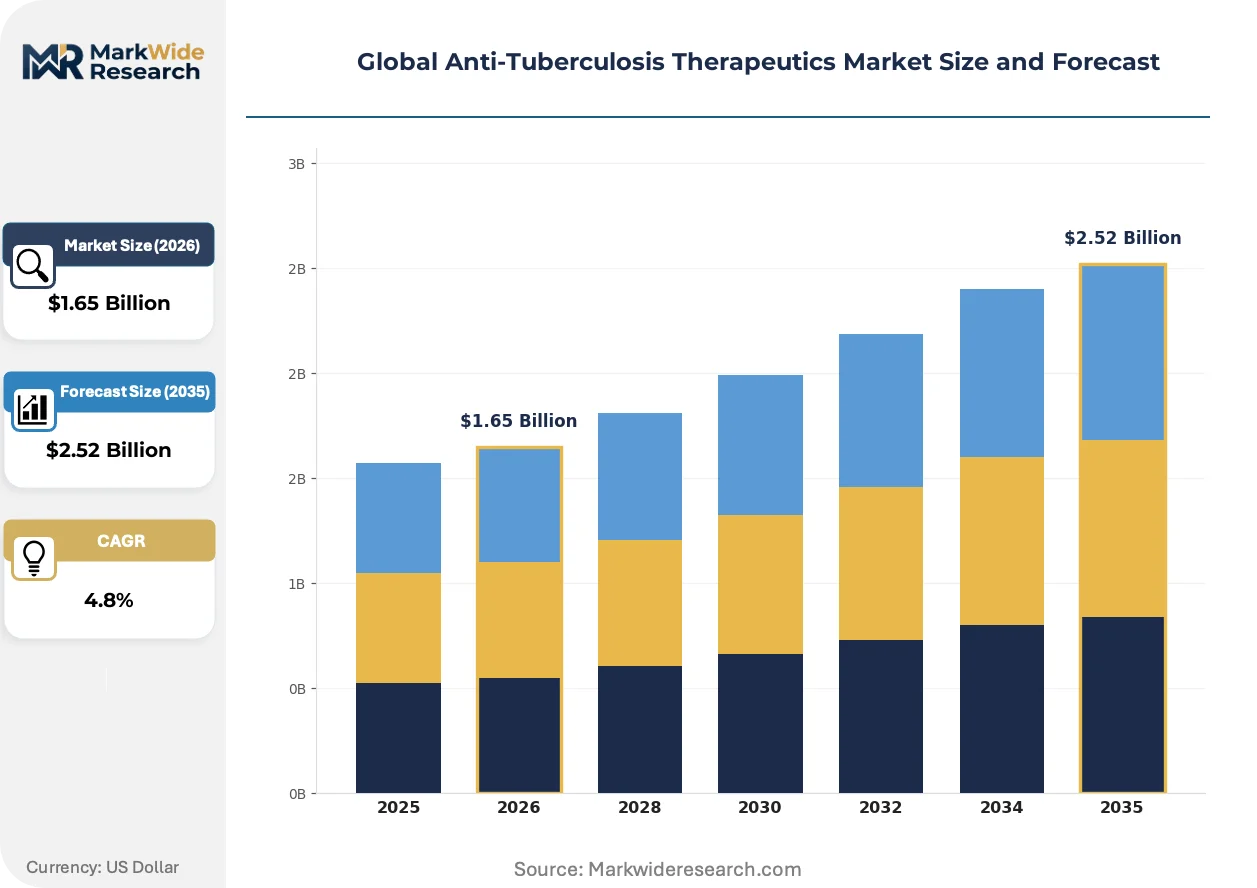
Nanoparticle delivery platforms are compressing dosing frequency requirements while WHO prequalification standards are redirecting manufacturing investment toward differentiated formulations that meet bioequivalence thresholds for high-burden country procurement.
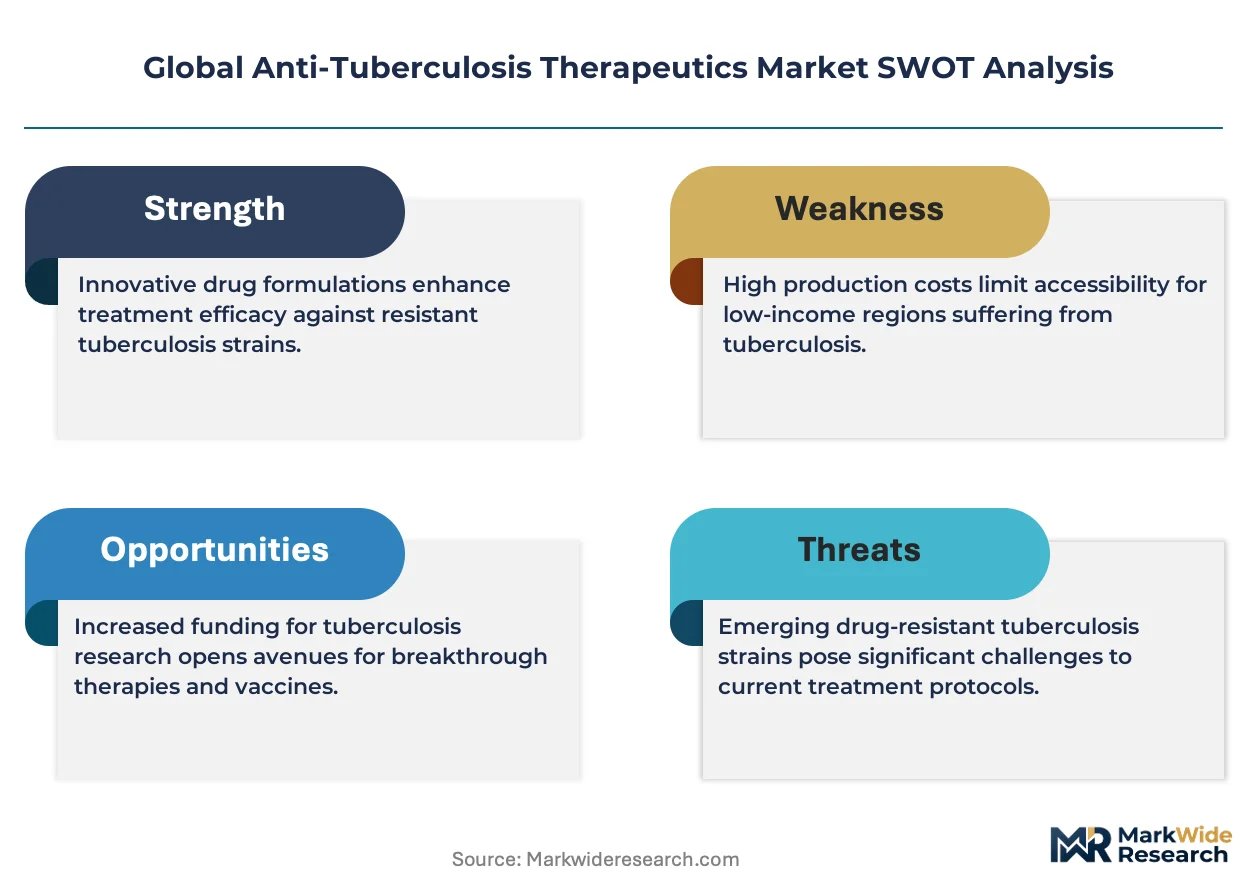
Growth Catalysts
- India's TB Elimination Program:Government volume commitments for domestic suppliers are expanding procurement pipelines for fixed-dose combination therapies across public health centers.
- WHO Prequalification Pathway:Stringent stability requirements are favoring manufacturers with dedicated regulatory affairs capacity, accelerating market access for differentiated formulations.
- Short-Course Oral Regimens:Development focus is narrowing away from prolonged injectable protocols, improving patient adherence and reducing treatment dropout rates in high-prevalence populations.
Market Restraints
- API Supply Concentration:Rifamycin derivative active pharmaceutical ingredients face supply bottlenecks from concentrated manufacturing bases in specific Asian supplier clusters.
- Divergent Compliance Burdens:EU MDR and WHO PQ pathways create incompatible documentation requirements that strain mid-scale manufacturers lacking multi-territory regulatory teams.
- Resistance Surveillance Gaps:Limited laboratory capacity in high-burden settings delays detection of emerging multidrug-resistant strains, complicating formulary planning.
Strategic Opportunities
- Extensively Drug-Resistant TB Access Programs:Limited-resource settings present white space for novel chemical entities targeting resistance profiles where standard regimens fail.
- Domestic Production Incentives:India's PLI scheme for pharmaceuticals is creating captive supply advantages for local manufacturers serving national program procurement.
- Fixed-Dose Combination Innovation:Convergence of nanoparticle engineering with bioequivalence modeling enables reduced pill burden formulations that differentiate tender submissions.
Industry Challenges
- Regulatory Affairs Talent Scarcity:Shortage of specialists capable of navigating simultaneous FDA, EMA, and WHO prequalification submissions delays product registration timelines.
- Stability Validation Capex:Extended shelf-life demonstration for tropical climate conditions requires climate-controlled manufacturing investments that strain facility budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Tuberculosis Therapeutics Market |
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: First-Line Drugs, Second-Line Drugs, Combination Therapy, Adjunctive Treatment, New Chemical Entities Therapy Area: Latent Tuberculosis, Active Pulmonary Tuberculosis, Extrapulmonary Tuberculosis, Multidrug-Resistant TB, Extensively Drug-Resistant TB End User: Hospitals, Specialized TB Clinics, Research Institutes, Public Health Centers, Community Healthcare Facilities Delivery Mode: Oral, Injectable, Inhalation, Fixed-Dose Combinations, Nanoparticle-Based Formulations |
| Companies Covered | Johnson & Johnson Services, Inc., Lupin Limited, Macleods Pharmaceuticals Ltd, Otsuka Pharmaceutical Co., Ltd, AstraZeneca, Novartis AG, Eli Lilly and Company, Sanofi, Sequella, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Tuberculosis Therapeutics Market Shifts & Advancements
Formulation science and procurement mechanics are converging to redefine competitive positioning, with delivery platform innovation and regulatory pathway optimization becoming primary differentiation vectors.
Nanoparticle-based drug delivery systems enhance bioavailability through targeted macrophage uptake and controlled release kinetics. Public health procurement bodies in high-burden countries are prioritizing these formulations in tender evaluations where adherence metrics influence award decisions. Manufacturing investment is migrating from conventional wet-granulation tableting toward spray-dried dispersion and lipid nanoparticle platforms that meet accelerated stability protocols.
WHO prequalification requirements for fixed-dose combinations have tightened bioequivalence demonstration standards for rifamycin-containing products. Manufacturers must now submit multi-region reference product bridging studies that increase dossier preparation costs and extend review timelines. High-volume generic suppliers serving Indian national programs are responding by building dedicated bioanalytical laboratories capable of simultaneous pharmacokinetic study execution.
Centralized national tendering for first-line TB medicines is compressing supplier margins while shifting volume toward vertically integrated manufacturers with captive API production. Distributor networks in high-burden African markets are consolidating as procurement agencies direct purchases through pre-qualified vendor lists with stringent cold-chain documentation requirements. This consolidation is most visible in Kenya and Nigeria, where national TB programs have shifted from fragmented state-level purchasing to federal centralized procurement with unified quality specifications.
Global Anti-Tuberculosis Therapeutics Market Segmentation
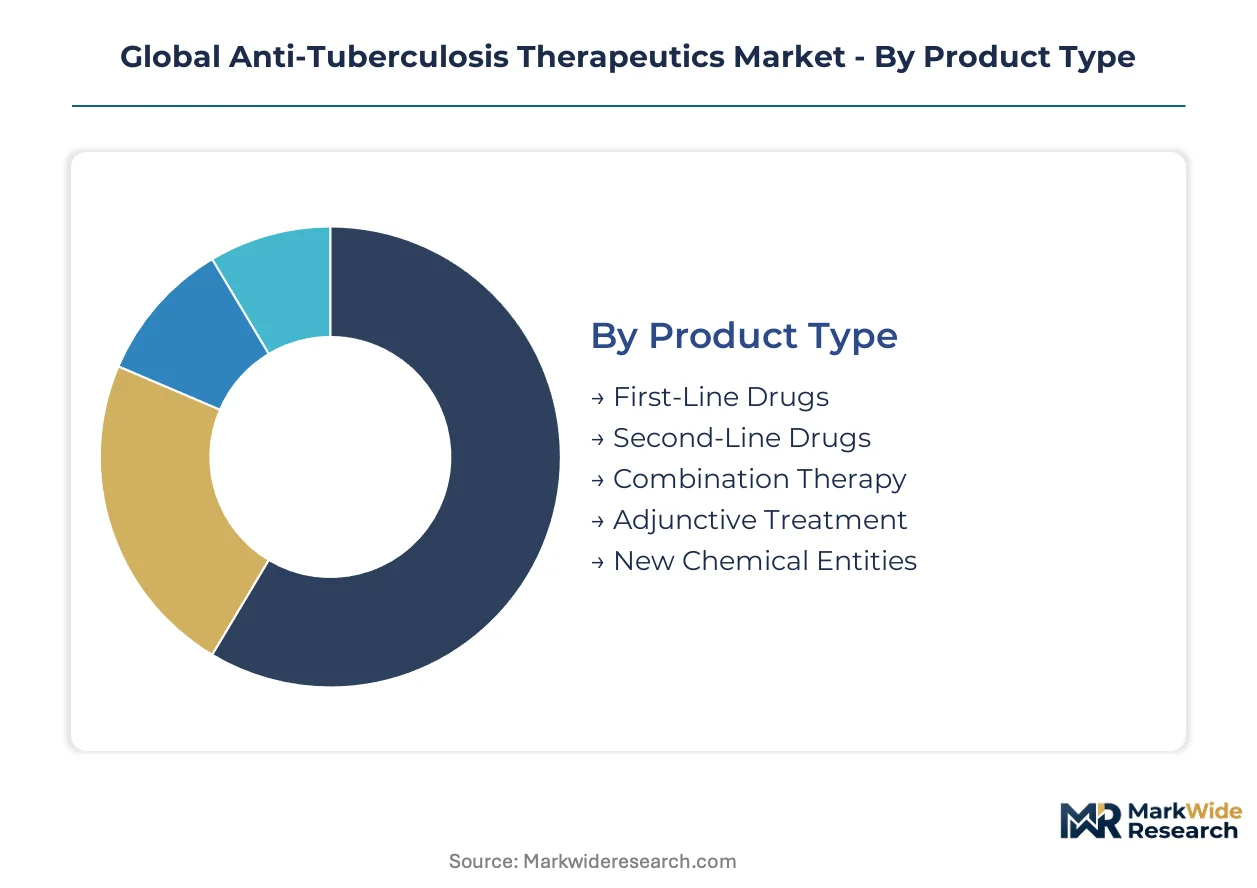
Segmentation in anti-tuberculosis therapeutics reveals how procurement priorities, resistance patterns, and delivery innovation reshape competitive positioning across distinct patient populations and care settings. Understanding these divisions exposes where formulation investments align with public health program requirements.
Product Type:
Fixed-dose combinations and novel chemical entities anchor opposite ends of the use-case spectrum, spanning standardized national program supply to premium resistance-targeted therapies.
- First-Line Drugs:Rifamycin-isoniazid-pyrazinamide-ethambutol regimens constitute the procurement backbone for drug-susceptible tuberculosis. Indian national programs drive volume concentration through domestic supplier tenders with stringent bioequivalence thresholds.
- Second-Line Drugs:Fluoroquinolone-based protocols and injectable aminoglycosides serve multidrug-resistant cases where first-line therapy fails. Supply bottlenecks from concentrated API manufacturing in Asian supplier clusters constrain availability in high-burden African markets.
- Combination Therapy:Pre-formulated multi-agent tablets reduce pill burden and improve adherence metrics in directly observed treatment programs.
- Adjunctive Treatment:Corticosteroid and nutritional support protocols address inflammatory complications and treatment-emergent toxicity.
- New Chemical Entities:Bedaquiline and delamanid derivatives target extensively drug-resistant strains through novel ATP synthase inhibition mechanisms.
Established volume favors first-line supply; emerging adoption favors new chemical entities.
Therapy Area:
Cost tier stratification separates latent infection prophylaxis from resource-intensive resistant disease management.
- Latent Tuberculosis:Isoniazid monotherapy or rifapentine-based short-course regimens prevent reactivation in high-risk contacts. India's TB elimination program expands procurement for household contact chemoprophylaxis.
- Active Pulmonary Tuberculosis:Sputum-positive disease drives the majority of standardized regimen demand through WHO prequalified supply chains.
- Extrapulmonary Tuberculosis:Meningeal, skeletal, and lymphatic presentations require extended therapy durations with enhanced CNS penetration formulations.
- Multidrug-Resistant TB:Rifampicin and isoniazid failure necessitates 18-24 month second-line protocols with intensive toxicity monitoring.
- Extensively Drug-Resistant TB:Fluoroquinolone and aminoglycoside resistance demands novel agent combinations with limited manufacturing scale.
Prevention-focused procurement dominates volume; resistance-targeted therapy commands premium positioning.
End User:
Customer type determines distribution infrastructure requirements from centralized hospital pharmacies to decentralized community networks.
- Hospitals:Tertiary referral centers manage complicated multidrug-resistant cases requiring specialized diagnostics and prolonged inpatient protocols.
- Specialized TB Clinics:Dedicated facilities in Kenya and Nigeria consolidate directly observed therapy programs with federal centralized procurement.
- Research Institutes:Clinical trial sites evaluate novel regimens under FDA and EMA investigational protocols.
- Public Health Centers:Government-operated facilities in Indian states administer first-line therapy through national program formularies.
- Community Healthcare Facilities:Peripheral clinics extend treatment access in rural high-burden districts with simplified adherence support.
Institutional procurement concentrates in public health infrastructure; community penetration expands through decentralized directly observed therapy.
Delivery Mode:
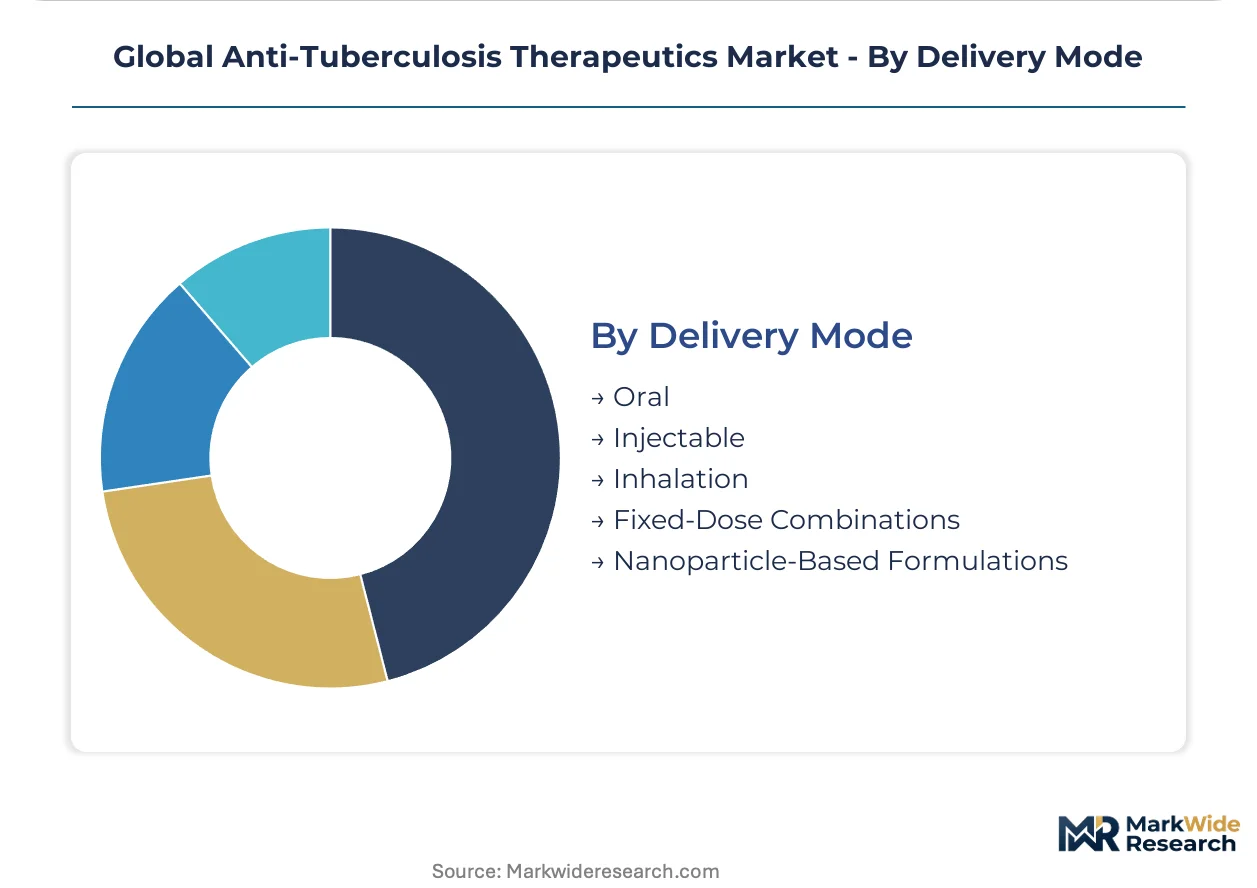
Technology maturity separates conventional oral administration from engineered nanoparticle platforms.
- Oral:Standard tablets and dispersible formulations remain the default for first-line and second-line therapy across all high-burden settings.
- Injectable:Intramuscular aminoglycosides and capreomycin serve multidrug-resistant regimens where oral bioavailability proves inadequate.
- Inhalation:Aerosolized delivery systems target pulmonary cavities with localized drug deposition.
- Fixed-Dose Combinations:Single-tablet rifamycin-isoniazid-pyrazinamide-ethambutol formulations simplify procurement and reduce medication error.
- Nanoparticle-Based Formulations:Lipid nanoparticle and spray-dried dispersion platforms enhance macrophage uptake and enable reduced dosing frequency. WHO prequalification standards now prioritize these formulations where adherence metrics influence tender awards.
Conventional oral delivery sustains volume dominance; nanoparticle engineering gains share fastest in differentiated tender evaluations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public health procurement bodies in high-burden countries drive demand concentration through centralized national tenders and domestic production incentives. India anchors volume commitments through its TB elimination program, while regulatory divergence between WHO prequalification and EU MDR pathways shapes manufacturer access strategies across distinct geographies.
India
India's TB elimination program expands procurement pipelines for fixed-dose combination therapies across state-level public health centers. CDSCO bioequivalence requirements and the PLI scheme for pharmaceuticals create captive supply advantages for domestic manufacturers. Mumbai and Ahmedabad clusters concentrate vertically integrated API-to-finished-dose operations serving national program tenders.
United States
FDA approval pathways for novel chemical entities targeting multidrug-resistant strains attract development-stage investment from specialized biopharmaceutical firms. The President's Emergency Plan for AIDS Relief (PEPFAR) indirectly shapes TB co-infection treatment protocols through integrated procurement mechanisms. Boston and San Francisco research corridors host clinical trial sites evaluating shortened oral regimens under investigational protocols.
South Africa
Extensively drug-resistant TB prevalence drives demand for bedaquiline and delamanid access programs through provincial health department tenders. The South African Health Products Regulatory Authority (SAHPRA) maintains stringent stability requirements for tropical climate conditions. Cape Town and Johannesburg pharmaceutical distribution hubs consolidate cold-chain logistics for second-line therapy supply to specialized TB hospitals.
Brazil
ANVISA registration requirements for fixed-dose combinations prioritize bioequivalence demonstration for rifamycin-containing products in national program formularies. The Unified Health System (SUS) centralizes procurement for first-line therapy through federal purchasing consortia. São Paulo state manufacturers leverage regional API supply relationships to compete in tender evaluations for standardized regimens.
Kenya
Federal centralized procurement has replaced fragmented county-level purchasing for TB medicines, compressing supplier margins toward pre-qualified vendor lists. WHO prequalification standards determine eligibility for Global Fund-financed supply chains reaching peripheral health facilities. Nairobi distribution networks consolidate directly observed therapy program logistics across high-burden districts in the Rift Valley and Western provinces.
Global Anti-Tuberculosis Therapeutics Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement tiers defined by regulatory capacity and manufacturing scale. The vendor base organizes around three strategic archetypes: vertically integrated generic suppliers with captive API production, novel mechanism developers targeting resistance segments, and formulation innovators pursuing nanoparticle delivery differentiation. Dominant competitive moves include backward integration into rifamycin derivative supply and strategic partnerships with national program procurement agencies.
Within the novel mechanism developer tier, Johnson & Johnson Services, Inc. and Otsuka Pharmaceutical Co., Ltd. occupy positions anchored by ATP synthase inhibition platforms for extensively drug-resistant disease management. Lupin Limited exemplifies the vertically integrated archetype through its Mumbai-based operations spanning API synthesis to finished-dose supply for Indian national program tenders. These three entities represent distinct competitive vectors: resistance-targeted premium positioning, domestic cost leadership, and access program structuring for limited-resource settings.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Lupin Limited |
| Macleods Pharmaceuticals Ltd |
| Otsuka Pharmaceutical Co., Ltd |
| AstraZeneca |
| Novartis AG |
| Eli Lilly and Company |
| Sanofi |
| Sequella, Inc. |
| Others |
Supply & Pricing Matrix
Mumbai and Ahmedabad manufacturing clusters concentrate vertically integrated API-to-finished-dose capacity that shapes downstream pricing power for Indian national program tenders. Their captive rifamycin derivative supply insulates domestic manufacturers from raw material volatility while compressing margins for non-integrated foreign suppliers competing on cost.
Pricing Analysis
Cost-plus contracts with API indexation anchor first-line regimen procurement for Indian public health programs. Three-tier pricing structure across novel chemical entities, differentiated formulations, and commodity generics separates bedaquiline access programs from nanoparticle-engineered products and standard fixed-dose combinations. Pricing pressure stems from centralized federal tenders in Kenya and Nigeria that consolidate volume toward pre-qualified vendor lists. National program procurement managers exhibit highest price sensitivity, while specialized TB clinics managing extensively drug-resistant cases prioritize efficacy over cost.
Supply Chain Analysis
Upstream feedstock concentration in Chinese and Indian supplier clusters controls rifamycin derivative availability for global formulation networks. Active pharmaceutical ingredients for isoniazid, pyrazinamide, and ethambutol draw from concentrated Asian manufacturing bases with limited geographic diversification. Single-source vulnerability for capreomycin and aminoglycoside injectables creates supply continuity risk for multidrug-resistant regimens. Distribution runs through Johannesburg and Nairobi cold-chain hubs that consolidate second-line therapy logistics for high-burden African markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Short-course oral regimens and nanoparticle delivery platforms signal early-cycle expansion as procurement bodies prioritize adherence metrics in tender evaluations. India's TB elimination program volume commitments and WHO prequalification pathway acceleration provide structural tailwinds for differentiated formulation developers.
For Market Incumbents: Build regulatory affairs capacity moats by establishing simultaneous FDA, EMA, and WHO prequalification submission capabilities. Invest in climate-controlled manufacturing for tropical stability validation to defend position against mid-scale competitors lacking multi-territory compliance teams. Backward integration into rifamycin API production anchors cost leadership as national programs consolidate procurement.
For New Entrants and Emerging Players: Build out bioanalytical laboratory infrastructure capable of executing multi-region pharmacokinetic bridging studies required for rifamycin-containing fixed-dose combinations. Target extensively drug-resistant TB access programs in limited-resource settings where novel ATP synthase inhibitors command premium positioning. Pursue partnership structures with Indian state-level public health centers to secure volume commitments under PLI scheme incentives.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory compliance burdens and stability validation capex are forcing mid-scale manufacturers toward exit. Acquisition targets should exhibit vertically integrated API production, established WHO prequalification dossiers, and active national program tender relationships. Watch for inflection when India's domestic production incentives redirect procurement flows away from established multinational suppliers toward local manufacturers.
| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Pathway Advancement | Accelerates market access for nanoparticle formulations in Global Fund-financed supply chains. |
| Backward Integration into Rifamycin API | Captive supply secures cost advantage in Indian national program tender competitions. |
| Nanoparticle Platform Licensing Agreement | Spray-dried dispersion technology transfers enhance bioequivalence demonstration capabilities. |
| Domestic Manufacturing Scale-Up | PLI scheme incentives in Mumbai and Ahmedabad clusters strengthen national program positioning. |
| Extensively Drug-Resistant TB Access Program | Bedaquiline and delamanid distribution partnerships penetrate limited-resource African markets. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up volume modeling triangulated against top-down expenditure analysis from national TB program budget disclosures.
Scenario bracketing anchored projections across conservative, baseline, and accelerated adoption paths for nanoparticle delivery platforms. Segmentation dimensions spanned treatment line, dosage form, delivery mode, and regional regulatory cluster. CAGRs derived from patient volume forecasts, pricing trajectory assumptions, and procurement pattern shifts across the analysis window. Resistance surveillance data and formulary evolution timelines informed adoption curve modeling.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese API manufacturers or accelerated PLI scheme disbursements in India would shift outcomes. Cross-checking against WHO Global Tuberculosis Report expenditure benchmarks and national program procurement disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Latin America Human Insulin Drugs Market
Biopharmaceuticals
Global Insulin Glargine Market
Biopharmaceuticals
Human Combinatorial Antibody Libraries (Hucal) Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Typhoid Vaccines Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Anti-Tumor Drugs Market
Biopharmaceuticals
Bioidentical Hormones Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Radiopharmaceutical Theranostics Market
Biopharmaceuticals
Middle East and Africa Plasma Fractionation Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market