
 Biodegradable Plastic Films Market | 2026-2036
Biodegradable Plastic Films Market Size, Share, and Industry Trends Forecast 2026-2036
Biodegradable Plastic Films Market Analytics
Polylactic acid is hardening its position as the dominant feedstock replacing petroleum-based LDPE in flexible packaging applications. BASF SE leverages its integrated biopolymer supply chain to sustain cost advantages across European converting operations. Novamont S.p.A anchors its competitive stance through proprietary Mater-Bi technology that dominates Italian agricultural mulch film deployments. NatureWorks LLC controls North American PLA resin supply for brand owners seeking certified compostable packaging solutions.
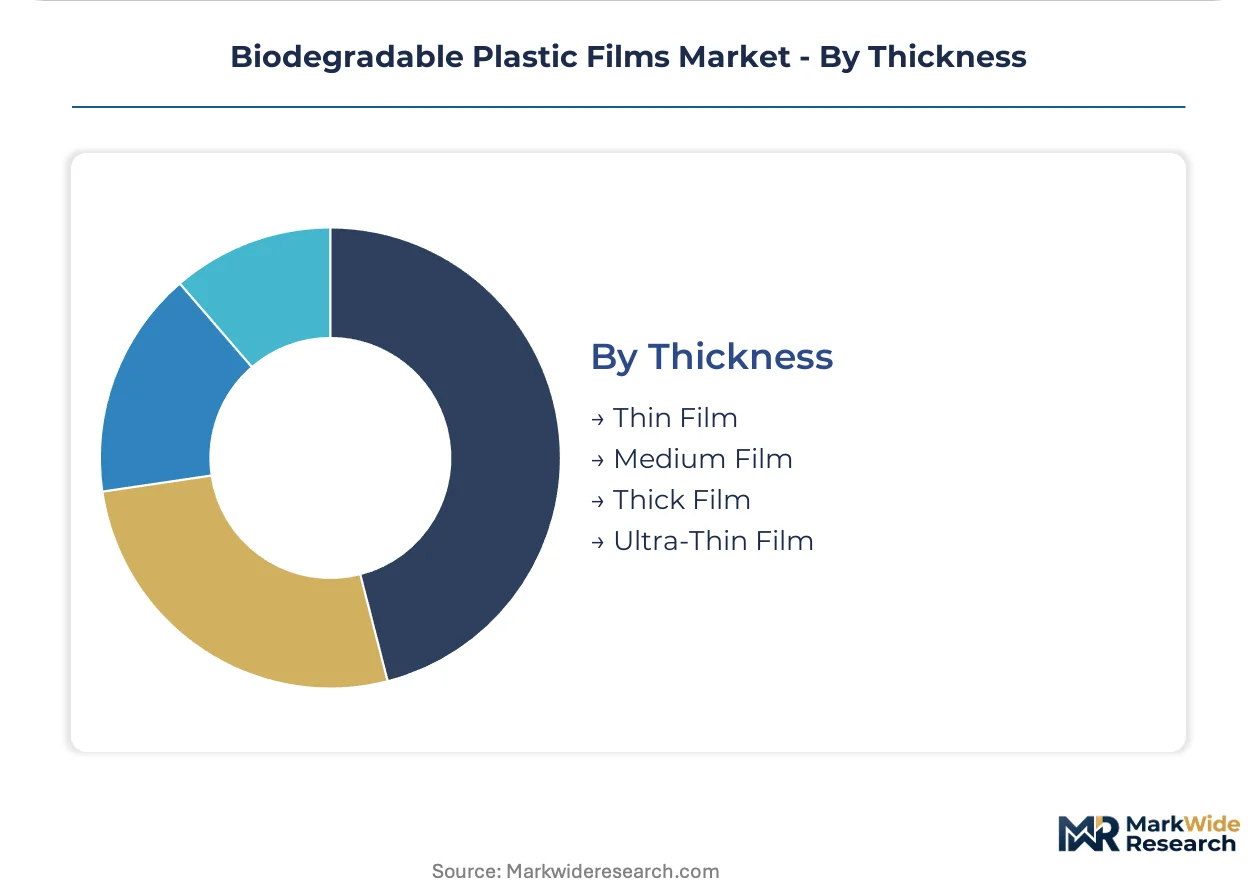
Biodegradable plastic films comprise polymeric sheets engineered to decompose through microbial action under composting or soil-burial conditions, typically achieving mineralization within 180 days per ASTM D6400 or EN 13432 protocols. These films function primarily as barrier layers for moisture and oxygen protection in perishable goods packaging, agricultural cultivation, and disposable food service articles. Starch blends occupy the largest volume position due to raw material abundance and lower unit economics, while PHA formulations represent the fastest-expanding category driven by marine biodegradability credentials that differentiate premium offerings. Thin film gauges command the widest application footprint across food wrapping and produce bags, whereas thick film variants capture concentrated margin pools in agricultural tunnel and mulch applications where UV stability requirements elevate technical barriers.
The European Commission's Packaging and Packaging Waste Regulation together with REACH chemical safety standards and FDA food contact notifications in the United States collectively establish the compliance perimeter for material approvals and market access. France's AGEC anti-waste law and Italy's CONAI packaging consortium impose specific biodegradable content mandates that directly shape procurement specifications for film converters. Stakeholders must monitor evolving certification harmonization between home and industrial composting standards as this divergence determines addressable market boundaries and capital allocation priorities for resin and film production investments.
Market Dynamics
France's AGEC law and Germany's EPR enforcement timelines are compressing converter procurement cycles and forcing rapid feedstock transitions from polyethylene to certified compostable alternatives across European flexible packaging supply chains.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled and biodegradable content thresholds are compelling retail chains to source compostable films for private-label packaging lines.
- Agricultural mulch film:Soil-biodegradable alternatives to polyethylene are capturing share in Italian vegetable cultivation and Spanish greenhouse operations facing microplastic contamination liability.
- PHA marine biodegradability:Ocean-compostable credentials are differentiating premium film offerings for coastal food service and aquaculture packaging applications.
Market Restraints
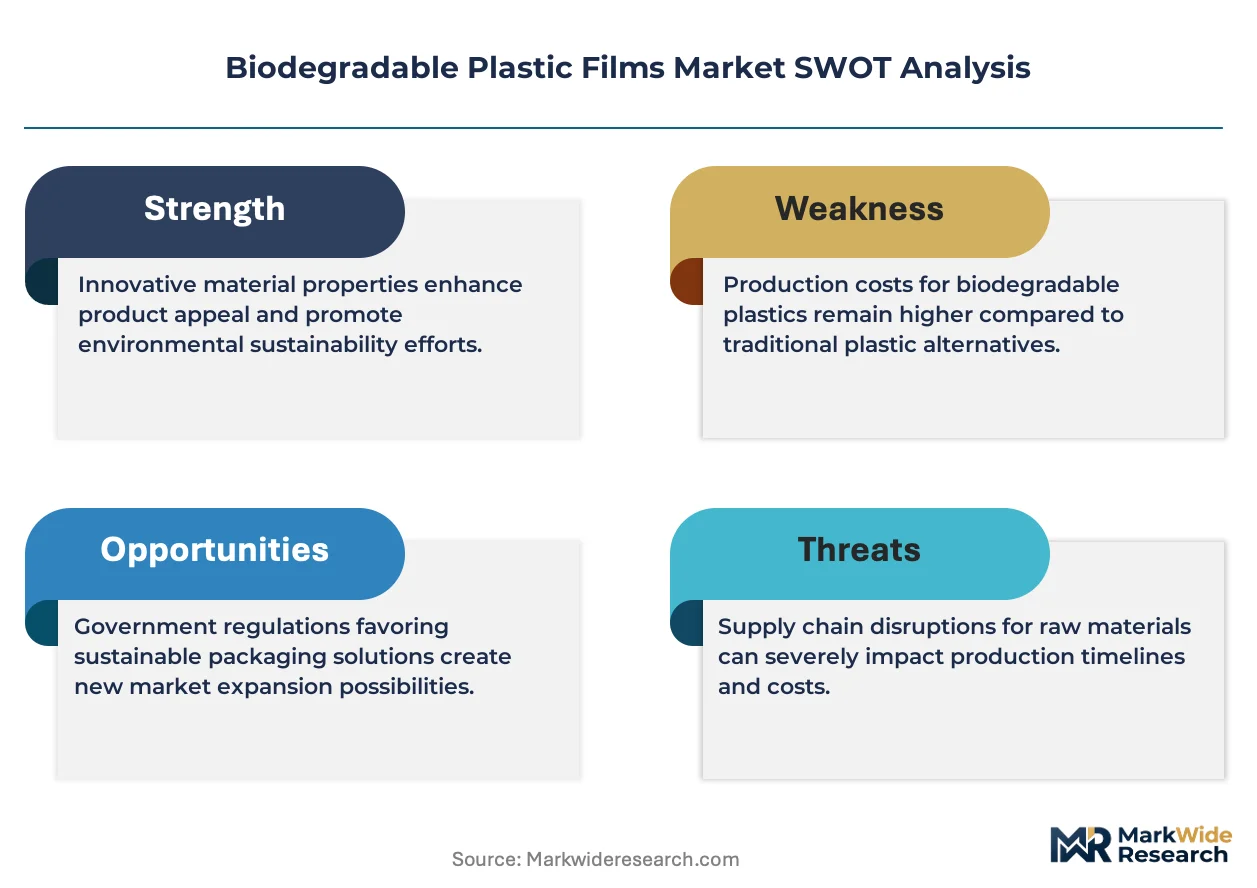
- Feedstock cost volatility:Corn and sugarcane price swings directly compress PLA resin margins and constrain converter pricing flexibility.
- Industrial composting infrastructure gaps:Limited certified composting facility density in Eastern Europe and rural North America restricts addressable market boundaries for home-compostable film claims.
- Performance limitations:Moisture barrier deficiencies in starch-based formulations exclude these films from high-humidity produce applications where polyethylene maintains technical dominance.
Strategic Opportunities
- Italian agricultural sector:CONAI packaging consortium mandates and national plastic tax exemptions are creating concentrated demand pull for soil-biodegradable mulch films in Po Valley tomato and melon cultivation.
- Home composting certification convergence:Harmonization between TÜV Austria OK Compost HOME and BPI home compostable standards would expand addressable market boundaries for retail-branded produce bags.
- Flexible packaging-laminate integration:Combining biodegradable barrier layers with paper substrates is opening premium snack and confectionery applications previously closed to mono-material films.
Industry Challenges
- Composting certification timeline compression:ASTM D6400 and EN 13432 testing protocols require 180-day mineralization validation that extends product development cycles and delays revenue recognition for new film formulations.
- Extrusion equipment reconfiguration:Converters must retrofit blown film lines for lower melt-strength biopolymers, demanding capital allocation that strains mid-tier processors with limited balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodegradable Plastic Films Market |
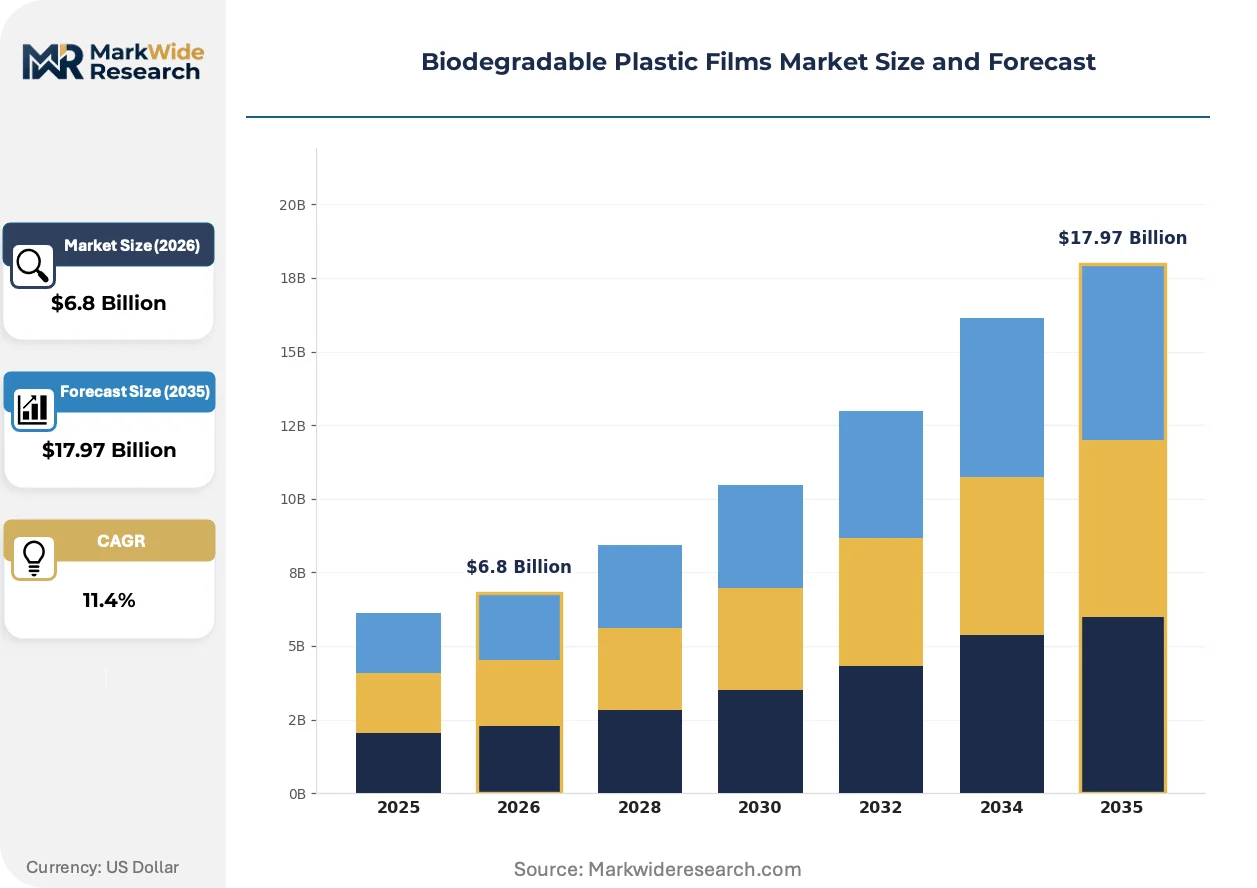
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PLA, PHA, Starch Blends, Cellulose End User: Agriculture, Packaging, Consumer Goods, Food Service Formulation: Compostable, Oxo-Biodegradable, Bio-based, Traditional Thickness: Thin Film, Medium Film, Thick Film, Ultra-Thin Film |
| Companies Covered | BASF SE, Novamont S.p.A, Futamura Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, NatureWorks LLC, Taghleef Industries, Walki Group, TIPA Corp Ltd., Kingfa Sci. & Tech. Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodegradable Plastic Films Market Evolving Landscape
Active innovation fronts span feedstock diversification, processing equipment adaptation, and certification protocol evolution as stakeholders race to meet tightening compliance deadlines while preserving film performance parity with conventional plastics.
Multilayer coextrusion technology is consolidating technical leadership among European converters serving premium food packaging applications. BASF SE and specialized film processors are deploying seven-layer blown film lines that sandwich PHA barrier cores between PLA structural skins, achieving oxygen transmission rates approaching polyethylene benchmarks. This architecture is consolidating market position in German meat and cheese packaging where shelf-life extension commands price premiums.
REACH chemical safety standards are tightening additive migration limits for food-contact films, forcing reformulation of plasticizers and slip agents used in starch-blend compounds. The European Chemicals Agency's 2024 updated restriction proposals target phthalate alternatives common in legacy biodegradable formulations, compelling compounders to validate bio-based citrate esters and epoxidized vegetable oils. Italian converters serving domestic fresh pasta packaging are accelerating compliance timelines to maintain supermarket listing agreements.
Retail procurement consolidation is compressing supplier qualification cycles and elevating certification requirements as a competitive gate. Carrefour and REWE Group are mandating dual certification to both industrial and home composting standards for private-label produce bags, disqualifying single-certified suppliers from tender processes. This behavioral shift is most visible in France and Germany where retail concentration enables procurement standard-setting that ripples through converter tiers.
Biodegradable Plastic Films Market Segmentation
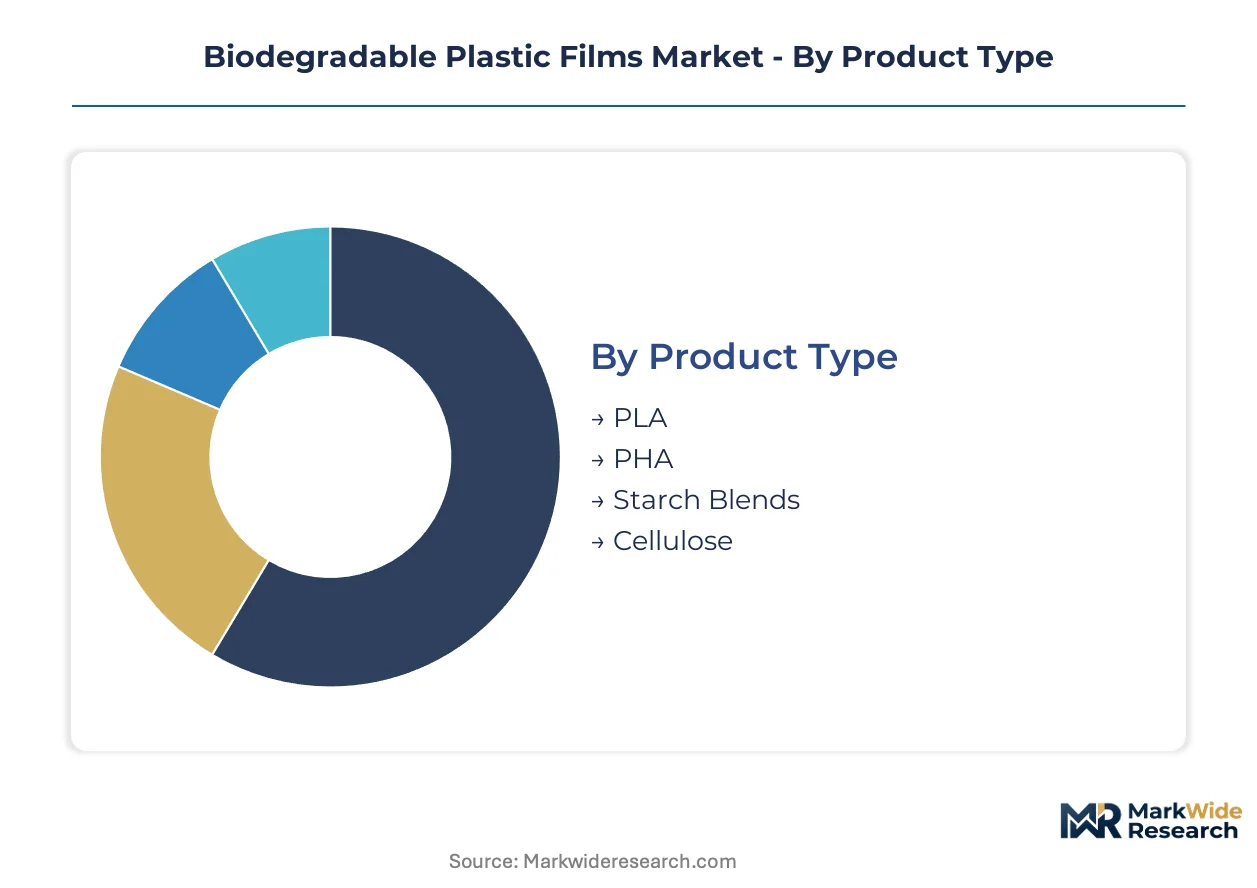
Segmentation in biodegradable plastic films determines certification pathways, equipment requirements, and margin structures. Resin chemistry dictates composting infrastructure compatibility. End-use applications impose divergent performance standards that shape converter specialization.
Product Type:
Certification burdens vary sharply across resin platforms, with ASTM D6400 and EN 13432 compliance timelines stretching longest for novel polymer categories.
- PLA:Polylactic acid delivers the most mature certification pathway, with NatureWorks LLC and TotalEnergies Corbion controlling commercial-scale lactide supply. German retail chains specify PLA for private-label produce bags to meet EU Packaging and Packaging Waste Regulation thresholds.
- PHA:Polyhydroxyalkanoates achieve marine biodegradability certification that PLA cannot match, commanding premium positioning in Italian coastal aquaculture and French offshore food service packaging where ocean disposal liability drives procurement.
- Starch Blends:Mater-Bi technology from Novamont S.p.A dominates Italian agricultural mulch deployments through soil-biodegradability validation.
- Cellulose:Regenerated cellulose films from Eastman Chemical and Futamura Chemical serve high-temperature food contact applications requiring heat-seal integrity.
Starch blends sit at the top of the volume ranking, with PHA climbing the fastest.
End User:
Customer type determines pricing power and contract duration, with agricultural buyers locking in seasonal supply agreements while food service operators pursue spot purchasing flexibility.
- Agriculture:Soil-biodegradable mulch films capture concentrated demand in Italy's Po Valley tomato cultivation and Spain's Almería greenhouse belt, where microplastic contamination liability has accelerated polyethylene displacement.
- Packaging:Flexible barrier layers for fresh pasta and meat applications dominate French and German converter output, with seven-layer coextrusion lines achieving oxygen transmission rates approaching synthetic benchmarks.
- Consumer Goods:Retail-branded produce bags and garment packaging drive volume in urban French and German markets where home composting claims differentiate shelf positioning.
- Food Service:Disposable cutlery wraps and takeout containers face strict single-use plastic bans across French metropolitan areas, compressing procurement cycles toward certified compostable alternatives.
Agriculture commands the deepest contract backlog, with food service expanding most quickly.
Formulation:
Formulation choice locks in addressable market boundaries, with industrial composting certification opening municipal collection systems while home compostable claims target backyard disposal behavior.
- Compostable:ASTM D6400 and EN 13432 certification enables access to industrial composting streams in Germany, France, and the Netherlands, with TÜV Austria and BPI marks serving as procurement gatekeepers for Carrefour and REWE Group tenders.
- Oxo-Biodegradable:Pro-oxidant additive packages face regulatory headwinds under EU Single-Use Plastics Directive restrictions, limiting deployment to non-food contact applications in jurisdictions with less stringent enforcement.
- Bio-based:Renewable carbon content verification through ASTM D6866 appeals to brand owners pursuing Scope 3 emissions reduction without full biodegradability certification.
- Traditional:Conventional polyethylene with biodegradable additives serves transitional applications where performance parity outweighs end-of-life claims.
Compostable formulations hold the broadest certification acceptance, with bio-based gaining share fastest.
Thickness:
Film gauge determines extrusion equipment configuration and resin selection, with thin-gauge lines optimized for high-melt-strength PLA while thick-film production accommodates lower-strength starch blends.
- Thin Film:10-25 micron gauges dominate French retail produce bag applications where downgauging reduces material cost per unit while maintaining tear resistance through multilayer architecture.
- Thick Film:100-200 micron variants capture agricultural tunnel and mulch applications where UV stability requirements extend service life across Italian growing seasons.
- Medium Film:25-75 micron range serves industrial liner and overwrap functions in German meat packaging operations.
- Ultra-Thin Film:Sub-10 micron gauges target high-volume flower wrap and lightweight produce applications with limited durability requirements.
Thin film leads volume production, with thick film capturing the steepest margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhine-Ruhr and Rhine-Main industrial corridors anchor European demand for certified compostable packaging films, with converter clusters in Düsseldorf and Frankfurt serving retail chains under tightening EU Packaging and Packaging Waste Regulation compliance deadlines.
Germany
REWE Group and Aldi Süd procurement mandates are compressing supplier qualification timelines for private-label produce bags. The country's EPR enforcement under Verpackungsgesetz amendments requires converters to document biodegradable content thresholds. Film processors in North Rhine-Westphalia are retrofitting blown film lines for PLA and PHA feedstocks to maintain supermarket listing agreements.
France
Carrefour and Intermarché tender specifications now mandate dual home and industrial composting certification for flexible packaging. AGEC anti-waste law enforcement through Citeo packaging consortium is penalizing polyethylene alternatives in fresh food applications. Converters in Île-de-France and Auvergne-Rhône-Alpes are consolidating multilayer coextrusion capacity to meet oxygen barrier requirements for meat and cheese packaging.
Italy
CONAI packaging consortium mandates and national plastic tax exemptions are creating concentrated demand pull for soil-biodegradable mulch films. Novamont S.p.A's proprietary technology dominates agricultural deployments across the Po Valley tomato and melon cultivation belt. Film converters in Lombardy and Emilia-Romagna are expanding seven-layer lines to serve premium fresh pasta packaging for domestic retail chains.
United States
Whole Foods Market and Kroger procurement standards are elevating BPI certification requirements for private-label produce bags. FDA food contact notifications and state-level single-use plastic bans in California and New York are shaping converter compliance strategies. NatureWorks LLC's Blair, Nebraska lactide facility supplies PLA resin to Midwestern film processors serving brand owners with Scope 3 emissions reduction targets.
Spain
Almería greenhouse operators are accelerating polyethylene displacement in agricultural tunnel and mulch applications due to microplastic contamination liability exposure. The country's national packaging registry is enforcing extended producer responsibility rules that favor certified soil-biodegradable alternatives. Valencia and Murcia-based converters are capturing seasonal contract backlogs from vegetable exporters facing EU import market sustainability audits.
Biodegradable Plastic Films Market Competitive Landscape
Capacity expansion dominates the current landscape as resin producers and film converters race to capture procurement volume from retail chains with 2025-2027 compliance deadlines. The vendor base separates into three tiers: integrated chemical conglomerates with captive biopolymer supply, specialized film processors with certification expertise, and regional converters serving agricultural contract markets. Two strategic archetypes are consolidating position: multilayer coextrusion specialists achieving synthetic-parity barrier performance, and soil-biodegradable formulators capturing agricultural replacement cycles. Competitive moves center on backward integration into lactide and PHA monomer production, plus geographic licensing of composting certification protocols to accelerate market access.
Among European chemical conglomerates, BASF SE anchors the integrated supply chain archetype through its Ludwigshafen biopolymer complex. Novamont S.p.A occupies the specialized agricultural film position via its Mater-Bi technology platform and Italian converter network relationships. NatureWorks LLC represents the regional supply anchor for North American brand owners seeking certified compostable packaging solutions with domestic resin provenance.
| Leading Market Players |
|---|
| BASF SE |
| Novamont S.p.A |
| Futamura Chemical Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| NatureWorks LLC |
| Taghleef Industries |
| Walki Group |
| TIPA Corp Ltd. |
| Kingfa Sci. & Tech. Co. |
| Others |
Value Network & Pricing Analysis
REWE Group and Carrefour dual-certification mandates for private-label produce bags are forcing resin suppliers to absorb certification testing costs while converters face equipment retrofitting expenses, compressing margins across European supply chains and accelerating price stratification by certification tier.
Pricing Analysis
Input-cost pass-through from corn and sugarcane feedstock volatility dominates PLA resin pricing, with compounders adjusting quotations quarterly to preserve lactide conversion margins. Price differentiation hinges on certification grade—dual home and industrial composting certification commands premiums over single-certified alternatives—and volume scale, with agricultural buyers locking annual contracts while food service operators accept spot premiums. Cost compression in starch-blend formulations is intensifying because of REACH additive reformulation requirements. Food service operators exhibit highest price sensitivity due to thin margins and ban-driven forced switching, whereas premium meat packaging buyers absorb cost premiums for barrier performance parity.
Supply Chain Analysis
France's AGEC law and Italy's CONAI packaging consortium mandates are reshaping sourcing patterns toward domestic converter capacity and certified resin provenance. Supply concentrates in Germany, Italy, and the United States, with NatureWorks LLC's Nebraska lactide facility and BASF SE's Ludwigshafen biopolymer complex anchoring regional feedstock security. Raw material dependencies center on corn-derived lactide, sugarcane ethanol, and epoxidized vegetable oil plasticizers. Single-source vulnerability in marine-certified PHA supply creates bottleneck risk for coastal food service applications. Distribution runs through converter-direct relationships with retail procurement consortia, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biodegradable plastic films function as a stable compounder, with EU Packaging and Packaging Waste Regulation compliance deadlines providing predictable demand pull through the projection horizon.
For Market Incumbents: Deploy multilayer coextrusion capacity expansion to defend barrier-performance positioning against emerging PHA specialists. Integrate backward into lactide monomer production to secure margin control amid corn price volatility. Capture Italian agricultural contract renewals before CONAI mandate expansion tightens qualification windows. For New Entrants and Emerging Players: Spain's national packaging registry enforcement opens a window for soil-biodegradable mulch film specialists to capture Almería greenhouse displacement contracts. Target Eastern European industrial composting infrastructure gaps with home-compostable certified offerings. Pursue private-label produce bag tenders through TÜV Austria OK Compost HOME certification as a procurement differentiator. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier converters possessing dual-certification expertise and seven-layer blown film operational capability. Five-to-ten-year viability rests on certification protocol harmonization accelerating addressable market expansion. Monitor BPI and TÜV Austria standard convergence announcements as inflection indicators for retail procurement specification consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lactide Production | Captive supply of PLA feedstock insulates BASF and NatureWorks from corn price volatility. |
| Dual Certification Investment | Combined ASTM D6400 and OK Compost HOME validation unlocks Carrefour and REWE tender eligibility. |
| Seven-Layer Coextrusion Scale-Up | Multilayer barrier architecture achieves oxygen transmission rates matching synthetic benchmarks for meat packaging. |
| Agricultural Film Seasonal Contracting | Po Valley tomato cultivation agreements anchor Novamont's soil-biodegradable volume base. |
| Marine Biodegradability Validation | PHA ocean-compostable credentials differentiate premium offerings for Italian coastal aquaculture. |
Research Methodology
Coverage spans Germany, France, Italy, the United States, and Spain, with primary inputs from each market. The research combines interviews with film converter operations managers, retail procurement leads at Carrefour and REWE, agricultural cooperative supply directors, and biopolymer R&D heads with secondary validation from EU Packaging and Packaging Waste Regulation filings, CONAI and Citeo consortium reports, FDA food contact notifications, and customs trade data for PLA resin flows. Bottom-up volume modeling and top-down regulatory impact assessment provide triangulation.
Granularity-level modeling operates at resin chemistry, end-use application, formulation type, and film thickness dimensions across the analysis window. CAGRs derive from segment-level volume build-ups incorporating compliance deadline phasing and substitution elasticity assumptions. Industry-specific forecast inputs include composting facility density projections by country and retail private-label packaging conversion timelines.
Revisions become necessary when EU certification harmonization agreements materialize or when REACH additive restrictions expand beyond phthalate alternatives. Forecasts reflect documented assumptions on regulatory enforcement intensity and agricultural polyethylene displacement rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Barrier Films
Global Micro-Perforated Films Market
Packaging Barrier Films
Antimicrobial Packaging Market
Packaging Barrier Films
High Barrier Lidding Film Market
Packaging Barrier Films
LDPE and LLDPE Sealant Web Films Market
Packaging Barrier Films
Child-Resistant Foil Packaging Market
Packaging Barrier Films
USA Stretch Hood Films Market
Packaging Barrier Films
Global Metalized Barrier Films Market
Packaging Barrier Films
Food Packaging Migration and Barrier Performance Test Instruments Market
Packaging Barrier Films
Biobased Anti-Blocking Agents for Flexible Packaging Films Market
Packaging Barrier Films
Holographic Transfer Film Market
Packaging Barrier Films
72 Inch Paint Protection Film Market
Packaging Barrier Films
Moisture-Resistant Packaging Market
Packaging Barrier Films
Barrier Bags Market
Packaging Barrier Films
Static-Free Packaging Films Market
Packaging Barrier Films
Cryogenic Insulation Films Market
Packaging Barrier Films
Oil Resistant Packaging Market