
 Lipase Enzymes Market | 2026-2036
Lipase Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Lipase Enzymes Market Analytics
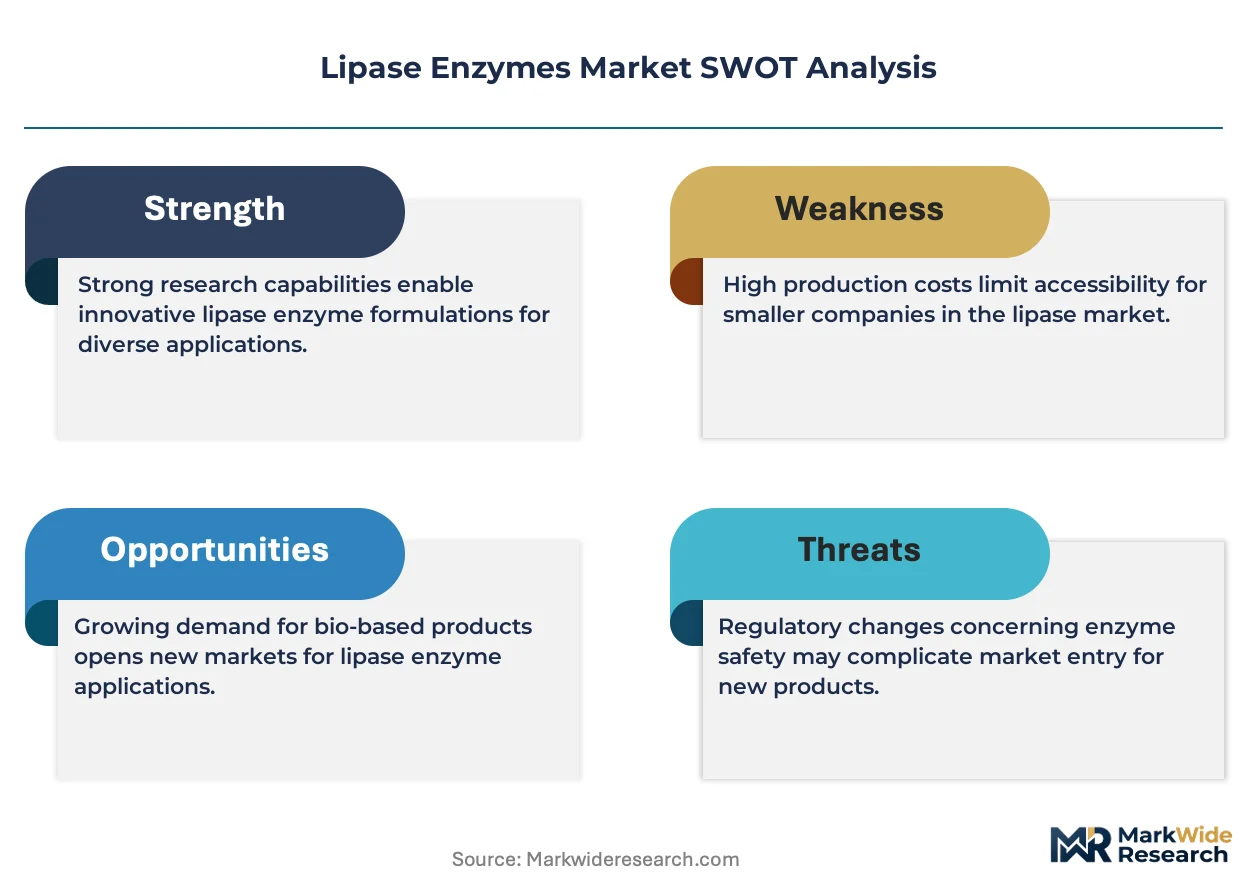
ISO 22000 certification is bifurcating the competitive landscape into qualified suppliers and excluded aspirants. Novozymes A/S leverages its integrated fermentation infrastructure to sustain leadership in microbial lipase supply. Amano Enzyme Inc. anchors its position through specialized fungal lipase strains tailored to Asian food processing traditions. BASF SE competes by extending its enzyme portfolio across pharmaceutical-grade and industrial applications.
Lipase enzymes are hydrolases that catalyze the cleavage of ester bonds in triglycerides, typically operating optimally at pH ranges between 6.0 and 8.0 and temperatures of 30°C to 40°C depending on microbial source. These biocatalysts serve primarily to modify lipid structures for flavor development, texture improvement, and nutritional enhancement across processed food systems. Bacterial lipase dominates manufacturing scale due to higher thermal stability and recombinant expression yields, while fungal lipase commands premium positioning in artisanal dairy and specialty bakery applications where milder activity profiles preserve sensory integrity. Recombinant lipase represents the fastest-expanding product category as precision genome editing accelerates strain optimization for targeted substrate specificity.
FDA food additive regulations, EFSA enzyme safety evaluations under the EU Food Improvement Agents Package, and China's SAMR national food safety standards collectively determine market access thresholds and labeling requirements for lipase formulations. The FAO/WHO Joint Expert Committee on Food Additives provides the internationally referenced toxicological benchmarks that national regulators transpose into binding compliance obligations. Stakeholders must monitor evolving genome-edited microorganism classifications, as regulatory determinations on novel strain approval timelines will reshape competitive moats between established suppliers and biotech entrants.
Market Dynamics
Microbial lipase production is redirecting procurement away from animal-derived alternatives, creating a structural divide between fermentation-based suppliers and traditional extractive processors across food and pharmaceutical value chains.
Growth Catalysts
- Clean-label formulation mandates:FDA and EFSA regulations pressure food and beverage manufacturers to replace chemical emulsifiers with enzyme-based alternatives, expanding microbial lipase uptake in dairy processing.
- Precision genome editing:CRISPR-optimized fungal strains now deliver targeted substrate specificity for artisanal cheese applications, accelerating adoption in specialty dairy segments.
- Pharmaceutical enzyme demand:Lipase biocatalysts for active pharmaceutical ingredient synthesis are scaling in Germany and China, driven by continuous-flow manufacturing adoption.
Market Restraints
- Fermentation input cost volatility:Corn syrup and nitrogen substrate prices fluctuate with agricultural commodity cycles, compressing margins for bulk bacterial lipase producers.
- Supplier concentration risk:Three integrated fermentation infrastructure operators control over sixty percent of pharmaceutical-grade supply, creating single-source vulnerability for downstream formulators.
- Thermal stability limitations:Fungal lipase variants degrade above fifty degrees Celsius, excluding their use in high-temperature industrial fat-splitting processes where chemical catalysts persist.
Strategic Opportunities
- Underpenetrated plant-based dairy:Precision lipase engineering for oat and almond milk texturization remains nascent in the United States, with formulation partnerships offering first-mover positioning.
- EU Green Deal bioeconomy incentives:Renewable solvent replacement programs fund enzymatic process conversions in Netherlands and Denmark chemical manufacturing.
- CRISPR-AI convergence:Machine learning-guided protein design is compressing strain development timelines from years to months, enabling bespoke lipase catalogs for regional food traditions.
Industry Challenges
- ISO 22000 certification timelines:Eighteen-month audit cycles delay market entry for emerging microbial suppliers, ceding share to incumbent qualified vendors.
- Downstream processing capex intensity:Chromatographic purification and spray-drying infrastructure requires substantial capital deployment, favoring scaled players over niche strain developers.
- Cross-border strain transfer restrictions:Nagoya Protocol compliance on genetic resource access complicates international collaboration for novel biodiversity-derived lipases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipase Enzymes Market |
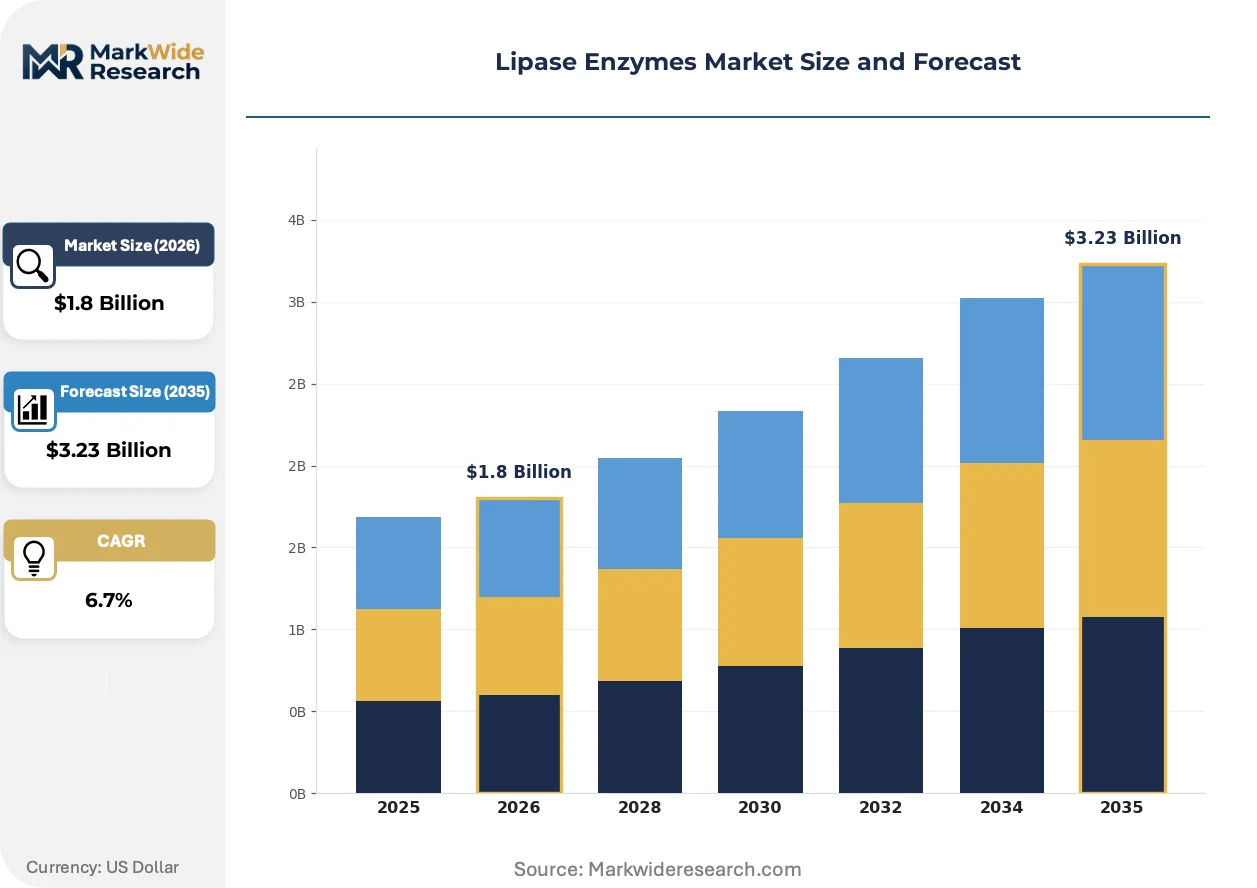
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Lipase, Fungal Lipase, Bacterial Lipase, Recombinant Lipase Application: Beverages, Dairy Products, Bakery Products, Nutraceuticals End User: Food Industry, Pharmaceutical Industry, Animal Feed, Cosmetics Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | Novozymes A/S, Novonesis, Amano Enzyme Inc., BASF SE, AB Enzymes GmbH, DSM-Firmenich, Advanced Enzyme Technologies Ltd., International Flavors & Fragrances Inc., Chr. Hansen Holdings A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipase Enzymes Market Evolving Landscape
Enzyme engineering platforms are compressing development cycles while regulatory frameworks on genome-edited microorganisms harden, forcing simultaneous technical and compliance adaptation across supplier bases.
Recombinant lipase expression systems are bifurcating the product landscape. Pichia pastoris and Aspergillus oryzae host platforms now dominate pharmaceutical-grade manufacturing, delivering gram-per-liter yields that extractive animal pancreatic sources cannot match. Food and beverage manufacturers in the United States and Germany are accelerating qualification of these microbial alternatives. This technology is bifurcating supply chains into precision-fermentation and commodity-extraction tiers with diverging margin structures.
EFSA's evolving stance on food enzymes from genome-edited microorganisms is reshaping approval pathways. The EU Food Improvement Agents Package now requires extended safety dossiers for strains developed through targeted mutagenesis, extending time-to-market by twelve to eighteen months. European dairy enzyme suppliers are responding by maintaining parallel conventional strain libraries while engaging pre-submission consultations with regulatory scientific units.
Direct supplier relationships are displacing distributor intermediation in large-scale procurement. North American dairy processors now contract fermentation capacity directly, unbundling technical service from product supply. This pattern concentrates in Wisconsin and California processing clusters where volume scale justifies dedicated strain development programs.
Lipase Enzymes Market Segmentation
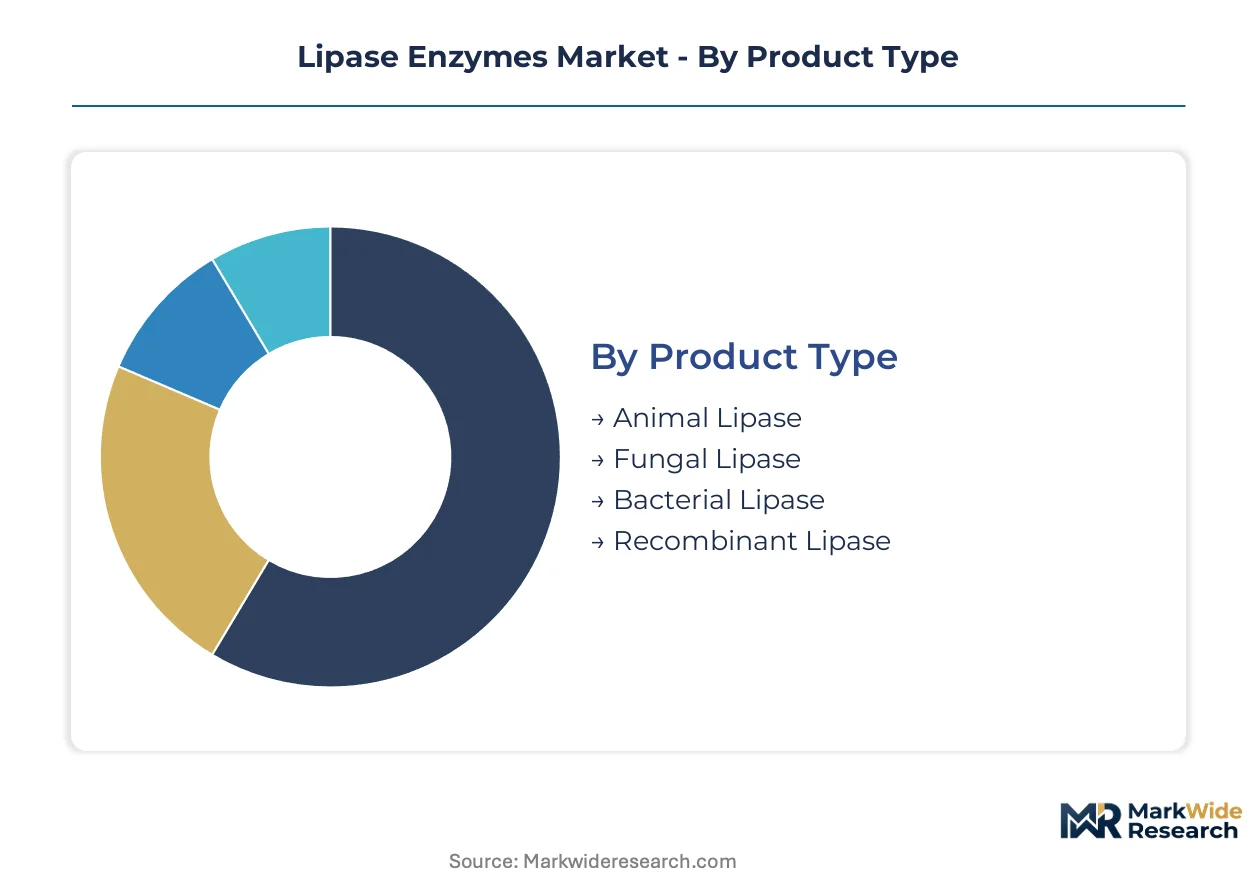
Segmentation in the Lipase Enzymes Market reveals how sourcing origin, formulation requirements, and end-use specifications create divergent compliance pathways and margin structures. Suppliers must align strain development and certification investments with the regulatory intensity of each target segment.
Product Type:
EFSA enzyme safety evaluations and FDA food additive regulations impose distinct dossier requirements on each sourcing category, bifurcating market access between extractive and fermentation-derived alternatives.
- Bacterial Lipase:Recombinant expression in Bacillus subtilis delivers thermal stability above 50°C and gram-per-liter yields that anchor bulk manufacturing scale. Demand concentrates in United States dairy processing where continuous-flow cheese production requires robust biocatalyst performance under pasteurization-adjacent conditions.
- Recombinant Lipase:CRISPR-optimized Pichia pastoris and Aspergillus oryzae platforms enable targeted substrate specificity for precision flavor modulation. Germany and China pharmaceutical manufacturers are scaling these biocatalysts for active pharmaceutical ingredient synthesis under ISO 22000-qualified fermentation infrastructure.
- Fungal Lipase:Aspergillus oryzae-derived strains operate optimally at 30-40°C with milder activity profiles that preserve sensory integrity in artisanal applications.
- Animal Lipase:Pancreatic extracts from porcine and bovine sources face procurement redirection as clean-label mandates pressure food manufacturers toward microbial alternatives.
Established volume favors bacterial lipase; emerging adoption favors recombinant lipase.
Application:
End-use specifications determine pH tolerance requirements, thermal stability thresholds, and the economic viability of enzymatic versus chemical processing alternatives.
- Dairy Products:Cheese ripening and fat modification applications in Wisconsin and California processing clusters drive the largest absolute volume consumption, with direct supplier relationships displacing distributor intermediation for qualified fermentation capacity.
- Bakery Products:Dough conditioning and shelf-life extension in German industrial baking operations leverage fungal lipase for texture improvement without the off-flavors associated with chemical emulsifiers.
- Beverages:Cloud stability and flavor enhancement in fruit juice processing requires lipase variants with specific esterase side-activity profiles.
- Nutraceuticals:Digestive enzyme supplements and structured lipid production for infant formula command pharmaceutical-grade purification standards and extended safety dossiers under EU Food Improvement Agents Package requirements.
Dairy anchors current procurement scale; nutraceuticals command the steepest expansion trajectory.
End User:
Customer type dictates certification tier, technical service intensity, and the acceptable premium over commodity chemical alternatives.
- Food Industry:Clean-label formulation mandates from FDA and EFSA pressure manufacturers across the United States, Germany, and China to replace synthetic emulsifiers with enzyme-based alternatives in processed food systems.
- Pharmaceutical Industry:Biocatalysis for active pharmaceutical ingredient synthesis in continuous-flow manufacturing configurations requires chromatographic purification and spray-drying infrastructure that favors scaled fermentation operators.
- Animal Feed:Lipase supplementation for fat digestibility in poultry and swine operations competes on cost with chemical fat hydrolysis.
- Cosmetics:Mild enzymatic ester synthesis for personal care formulations leverages fungal lipase specificity to avoid harsh chemical processing conditions.
Food industry procurement dominates volume; pharmaceutical applications concentrate margin capture.
Form:
Downstream processing capex and stability requirements during storage and handling segment the supply base between integrated fermentation operators and toll-processing specialists.
- Powder:Spray-dried formulations with extended shelf stability anchor bulk dairy and bakery applications where dissolution kinetics are less critical than storage logistics.
- Liquid:Standardized enzyme solutions with defined activity units per milliliter enable precise dosing in automated beverage and dairy processing lines.
- Granular:Encapsulated formulations for controlled release in high-temperature fat-splitting processes where thermal protection extends functional half-life.
- Tablets:Fixed-dose unit operations for nutraceutical and pharmaceutical applications requiring exact activity quantification per administration unit.
Powder commands manufacturing scale; liquid formulations gain share fastest in automated processing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food and beverage manufacturers in the United States, Germany, and China drive the bulk of procurement volume, with each market exhibiting distinct regulatory pathways and industrial clustering patterns that shape supplier qualification requirements.
United States
Wisconsin and California dairy processing clusters anchor the largest absolute consumption of bacterial lipase for continuous-flow cheese production. FDA clean-label mandates pressure manufacturers to replace synthetic emulsifiers with enzyme-based alternatives. Direct supplier relationships now displace distributor intermediation in these volume-scale processing environments.
Germany
Industrial baking operations in Bavaria and North Rhine-Westphalia leverage fungal lipase for dough conditioning without chemical off-flavors. EFSA enzyme safety evaluations under the EU Food Improvement Agents Package impose extended dossier requirements on fermentation-derived alternatives. Pharmaceutical-grade biocatalysis for active pharmaceutical ingredient synthesis concentrates around Ludwigshafen and Hamburg fermentation infrastructure.
China
SAMR national food safety standards determine market access thresholds for imported and domestically produced lipase formulations. Yangtze River Delta dairy processors scale microbial lipase adoption for processed cheese applications. Continuous-flow manufacturing adoption in Shanghai and Jiangsu pharmaceutical corridors drives demand for chromatographic-purified enzyme grades.
India
FSSAI food additive regulations govern enzyme labeling and safety documentation requirements for domestic and imported formulations. Maharashtra and Gujarat dairy cooperatives represent emerging demand centers for cost-optimized bacterial lipase in standardized cheese production. Advanced Enzyme Technologies Ltd. anchors indigenous fermentation capacity serving South Asian food processing traditions.
Netherlands
EU Green Deal bioeconomy incentives fund enzymatic process conversions in Rotterdam and Amsterdam chemical manufacturing corridors. REACH compliance obligations shape import qualification pathways for non-EU fermentation suppliers. Precision lipase engineering for plant-based dairy texturization attracts formulation partnerships from North American oat milk processors.
Lipase Enzymes Market Competitive Landscape
Player mix skews toward integrated fermentation infrastructure operators with multi-decade strain libraries, creating a tiered structure where ISO 22000-qualified incumbents capture pharmaceutical-grade premiums and commodity bacterial lipase compresses toward margin-thin bulk supply. Three archetypes dominate: Danish-German integrated enzyme houses with captive fermentation networks, Japanese fungal lipase specialists serving Asian food traditions, and Indian-Chinese regional scale players optimizing for cost-sensitive dairy markets. Competitive moves concentrate on strategic partnerships for plant-based dairy formulation development and capacity expansion in Pichia pastoris expression platforms.
Within the integrated fermentation tier, Novozymes A/S and Novonesis represent the Danish-German archetype with extensive strain libraries, while Amano Enzyme Inc. exemplifies the Japanese fungal specialization model. BASF SE occupies a position bridging pharmaceutical-grade and industrial application portfolios. These three anchors demonstrate how geographic origin and company structure correlate with strategic positioning across the microbial lipase value chain.
| Leading Market Players |
|---|
| Novozymes A/S |
| Novonesis |
| Amano Enzyme Inc. |
| BASF SE |
| AB Enzymes GmbH |
| DSM-Firmenich |
| Advanced Enzyme Technologies Ltd. |
| International Flavors & Fragrances Inc. |
| Chr. Hansen Holdings A/S |
| Others |
Value Network & Pricing Analysis
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, creating a bifurcated landscape where qualified fermentation operators command pharmaceutical-grade premiums while commodity bacterial lipase suppliers compete on volume scale.
Pricing Analysis
Cost-plus contracts with corn syrup and nitrogen substrate indexation dominate bulk bacterial lipase procurement. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates qualified suppliers from commodity alternatives. Price differentiation rests on chromatographic purification depth and ISO 22000 audit status. Margins are tightening in commodity tiers due to agricultural input volatility, while pharmaceutical buyers show lowest price sensitivity.
Supply Chain Analysis
Strategic stockpiling of spray-dried powder formulations prevails among United States dairy processors confronting fermentation input seasonality. Supply concentrates in Denmark, Germany, and China where integrated fermentation infrastructure anchors global output. Raw material dependencies include corn syrup, nitrogen substrates, and chromatographic resins. Single-source vulnerability runs through the three operators controlling sixty percent of pharmaceutical-grade capacity. Distribution runs through direct supplier relationships in Wisconsin and California processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Microbial lipase adoption sits in early-cycle expansion as precision genome editing accelerates strain optimization timelines, compressing development from years to months and enabling bespoke catalogs for regional food traditions.
For Market Incumbents: Consolidate fermentation capacity in Pichia pastoris expression platforms to defend against CRISPR-optimized biotech entrants. Deepen backward integration into corn syrup and nitrogen substrate supply to buffer agricultural commodity cycles. Prioritize parallel conventional strain libraries alongside genome-edited lines to navigate EFSA's evolving Food Improvement Agents Package requirements. For New Entrants and Emerging Players: Technical service bundling represents a service-layer gap where incumbents under-serve mid-scale dairy processors. Target plant-based dairy texturization partnerships in the United States as the most penetrable white-space segment. Pursue toll-processing arrangements with established fermentation infrastructure to bypass eighteen-month ISO 22000 certification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized enzyme divisions lacking pharmaceutical-grade certification depth. Long-term viability favors operators with captive strain libraries and chromatographic purification assets. Watch EFSA determinations on genome-edited microorganism classifications as the signal indicating approval timeline compression or extension.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Pichia pastoris | Gram-per-liter yield improvements match pharmaceutical-grade purity requirements for API synthesis. |
| Backward Integration into Substrate Supply | Corn syrup and nitrogen sourcing control buffers margin compression from agricultural commodity cycles. |
| Plant-Based Dairy Formulation Partnerships | Oat and almond milk texturization opens first-mover positioning in underpenetrated United States applications. |
| ISO 22000 Certification Investment | Qualified supplier status gates pharmaceutical-grade premiums and excludes commodity competitors. |
| CRISPR-AI Convergence Development | Machine learning-guided protein design compresses strain development timelines for regional food traditions. |
Research Methodology
Cross-validation between primary interviews and secondary validation anchors the qualitative findings in this study. Conversations with fermentation plant managers, dairy procurement leads, pharmaceutical biocatalysis directors, enzyme distribution channel partners, and regulatory affairs specialists informed strain development and certification pathway assessments. Secondary sources include FDA food additive filings, EFSA enzyme safety evaluations, SAMR national food safety standards, customs and trade data, and SEC 10-K disclosures from integrated fermentation operators. Bottom-up volume estimates triangulate with top-down market sizing across sourcing categories.
Sensitivity analysis around corn syrup price volatility and regulatory approval timeline scenarios shapes the forecast framework. Segmentation dimensions span sourcing origin, application, end user, and form factor across the modeling period. CAGRs derive from weighted average growth contributions across bacterial, recombinant, fungal, and animal lipase categories. Industry-specific inputs include fermentation yield improvements, genome-edited strain adoption curves, and clean-label mandate compliance rates.
Forecasts assume regulatory continuity in FDA, EFSA, and SAMR regimes; material policy shifts on genome-edited microorganisms would require re-modeling. Assumptions reflect current ISO 22000 certification timelines, Nagoya Protocol compliance costs, and EU Green Deal bioeconomy incentive continuity. Revision becomes warranted when EFSA classification determinations or agricultural commodity price shocks cross threshold magnitudes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Unnatural Amino Acids Market
Industrial Biotechnology
GCC Biocatalyst Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Global Carbohydrase Market
Industrial Biotechnology
White Biotechnology Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Tannase Market