
 Fungal Amylase Market | 2026-2036
Fungal Amylase Market Size, Share, and Industry Trends Forecast 2026-2036
Fungal Amylase Market Analysis
Market Context with Strategic Players
Capital intensity divergence between fermentation-scale operators and formulation specialists is redrawing competitive boundaries in fungal amylase supply. Novozymes A/S leverages multi-thousand-liter bioreactor infrastructure to dominate bulk glucoamylase output for ethanol distillers. DSM anchors European enzyme certification pipelines through its food-grade manufacturing network. AB Enzymes competes on tailored alpha-amylase blends for craft brewing segments where batch flexibility commands premium positioning.
Technical Definition and Structural Segments
Fungal amylase denotes a class of extracellular enzymes secreted by filamentous fungi, typically Aspergillus oryzae or Aspergillus niger, that hydrolyze alpha-1,4-glycosidic bonds in starch to yield dextrins, maltose, and glucose units for industrial substrate conversion. These enzymes function optimally at pH 4.5–6.5 and temperatures of 50–60°C, making them indispensable for starch liquefaction in food processing and biofuel fermentation. Glucoamylase captures the largest value pool due to its saccharification role in high-fructose corn syrup and fuel ethanol production, while pullulanase gains traction in debranching applications for premium brewing adjuncts. Powder technology leads volume shipments for shelf-stable distribution, though liquid formulations accelerate in automated bakery and distillery dosing systems where metering precision reduces enzyme waste.
Regulatory Frame and Forward Outlook
The U.S. FDA governs fungal amylase as a food additive under 21 CFR 173.130, while the EU EFSA mandates Novel Food assessments for non-traditional fungal strains, and China's SAMR enforces GB standards for enzyme activity labeling and contaminant thresholds. These frameworks elevate compliance costs for new market entrants but reinforce incumbent positions among certified suppliers. Stakeholders must monitor strain-level regulatory approvals and carbon-intensity benchmarks in biofuel mandates to align R&D pipelines with shifting compliance thresholds.
Market Dynamics
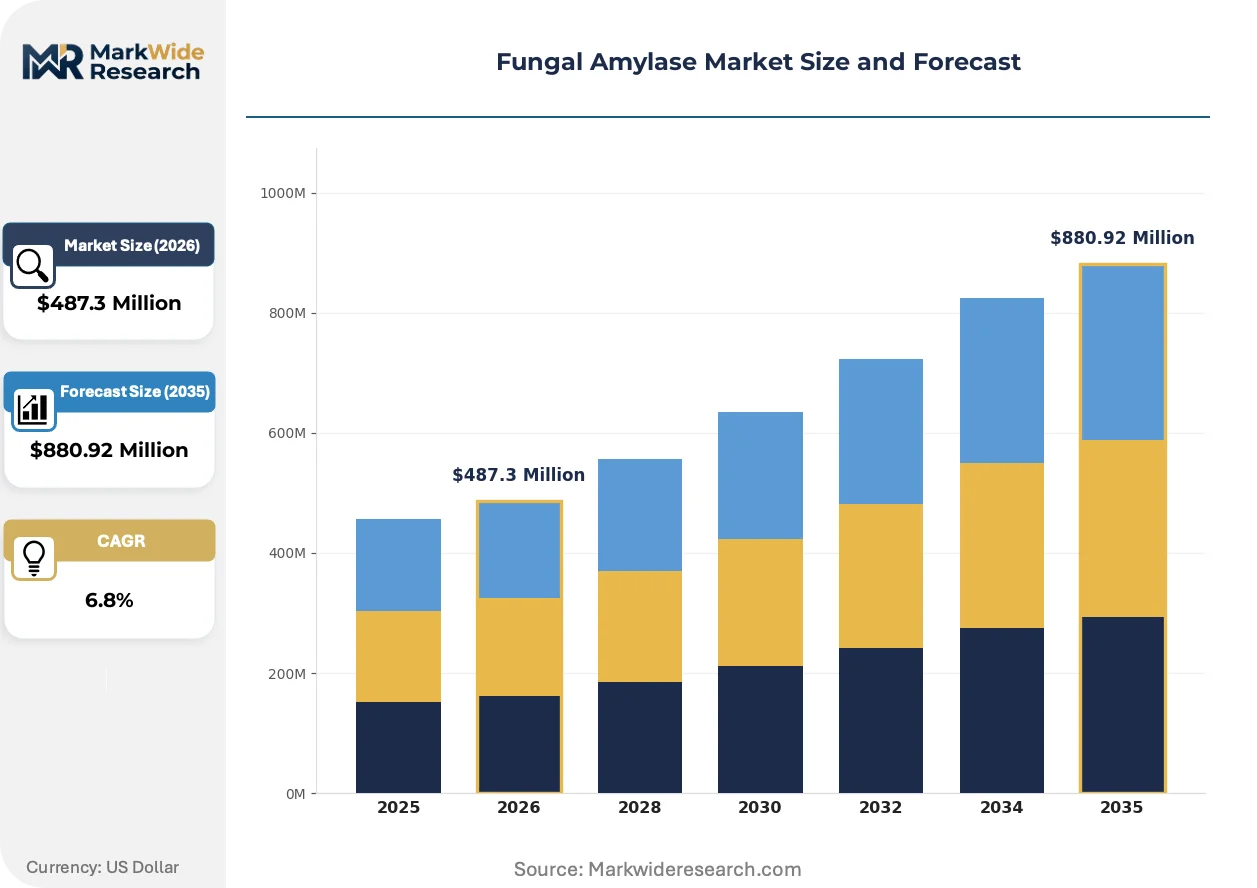
Fermentation-scale capital requirements and strain certification bottlenecks are concentrating supply-side power among multi-thousand-liter bioreactor operators, while Asia-Pacific ethanol mandates and European enzyme safety protocols pull demand in divergent directions.
Growth Catalysts
- India's Ethanol Blending Program:The country's 20% ethanol blending target by 2025 drives glucoamylase consumption at fuel distilleries, with state-run oil marketing companies contracting long-term enzyme supply.
- EFSA Novel Food Pathways:Streamlined safety assessments for modified fungal strains accelerate European food-grade enzyme approvals, reducing time-to-market for next-generation amylase variants.
- Automated Dosing Systems:Liquid enzyme formulations integrate with precision metering infrastructure in large-scale Chinese starch processing corridors, cutting waste and labor costs.
Market Restraints
- Input Cost Volatility:Corn steep liquor and soy protein prices fluctuate with agricultural commodity cycles, squeezing margins for fermentation-based enzyme producers.
- Supply Concentration Risk:Bulk glucoamylase output clusters among operators with captive multi-thousand-liter bioreactor networks in Denmark and the Netherlands, creating single-source vulnerability.
- Regulatory Friction:China's SAMR enforces strict GB standards for enzyme activity labeling and contaminant thresholds, blocking uncertified imports and delaying market entry.
Strategic Opportunities
- Underpenetrated Craft Brewing:Small-batch breweries in Germany and Belgium seek tailored alpha-amylase blends with batch flexibility, commanding premium positioning unavailable to commodity suppliers.
- Dual Carbon Goals:China's national carbon intensity benchmarks for biofuel production incentivize low-carbon enzyme manufacturing processes, rewarding certified green suppliers.
- Precision Fermentation Convergence:Cell-free enzyme production and CRISPR strain engineering combine to reduce fermentation cycle times and unlock novel pH-temperature operating windows.
Industry Challenges
- Strain Certification Timelines:Novel Food assessments under EFSA and GRAS self-affirmation through FDA consume 18-36 months, delaying revenue from engineered fungal variants.
- Bioprocess Engineering Talent Scarcity:Fermentation optimization and downstream purification expertise concentrates among legacy operators, constraining capacity expansion at mid-scale entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fungal Amylase Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alpha-Amylase, Glucoamylase, Pullulanase, Beta-Amylase Application: Baking, Brewing, Distilling, Pharmaceuticals End User: Food Industry, Beverage Manufacturers, Textile Industry, Biofuel Producers Technology: Liquid, Powder, Granular, Others |
| Companies Covered | Novozymes A/S, DSM, AB Enzymes, DuPont, BASF, Amano Enzyme, Chr. Hansen, Sunson, International Flavors & Fragrances Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fungal Amylase Market Emerging Trajectories
Enzyme engineering and regulatory digitization are compressing development cycles while procurement patterns shift toward long-term offtake agreements with certified suppliers.
Precision fermentation platforms using CRISPR-edited Aspergillus strains are fragmenting the traditional trade-off between thermostability and pH tolerance. Craft distilleries in Scotland and Kentucky adopt these variants for simultaneous liquefaction and saccharification, collapsing process steps. The technology is fragmenting equipment vendor relationships as breweries bypass conventional multi-enzyme cocktails.
REACH registration requirements for enzyme concentrates are tightening substance documentation obligations across EU member states. Manufacturers must submit extended safety data sheets for respiratory sensitization endpoints, elevating compliance costs. Food-grade certification pipelines in the Netherlands and Germany absorb the burden through dedicated regulatory affairs teams, while smaller exporters withdraw.
Buyers in fuel ethanol and high-fructose corn syrup sectors are consolidating supplier rosters around dual-source strategies with certified partners. Long-term offtake agreements with fixed-price escalation clauses displace spot market purchasing in the United States and Brazil. This pattern concentrates procurement leverage among integrated agribusinesses with captive trading desks.
Fungal Amylase Market Segmentation
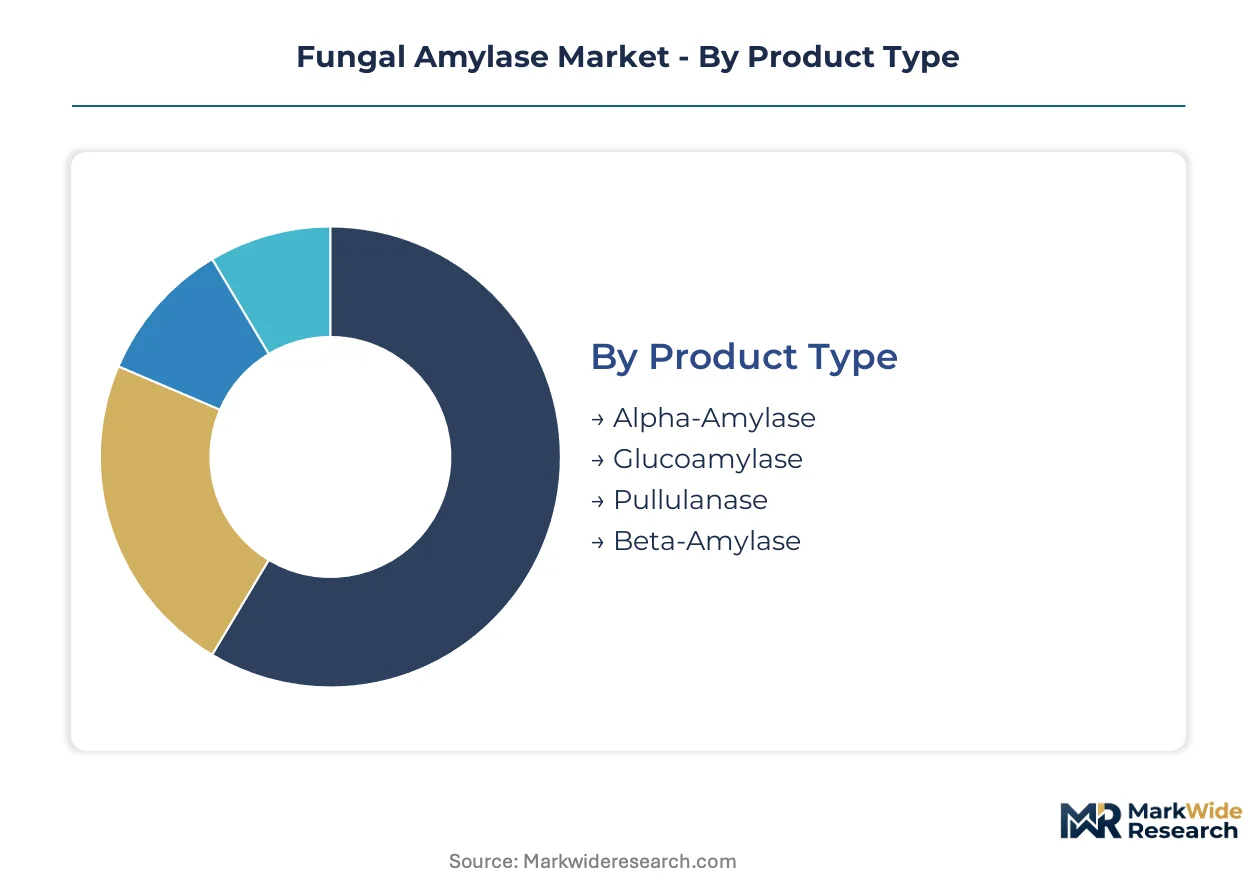
Segmentation in fungal amylase reveals how regulatory frameworks and application-specific performance requirements fragment procurement patterns across end-use verticals. Each dimension carries distinct compliance burdens and technical specifications that reshape supplier selection criteria.
Product Type:
EFSA Novel Food assessments and FDA GRAS pathways apply differential stringency across enzyme classes, with glucoamylase facing streamlined review due to established safety profiles while engineered variants trigger extended strain-level scrutiny.
- Glucoamylase:Catalyzes complete hydrolysis of starch to glucose from non-reducing ends, operating optimally at pH 4.5–5.5. Demand concentrates at Indian ethanol distilleries under the 20% blending mandate, where state-run oil marketing companies lock in multi-year supply contracts. FDA 21 CFR 173.130 provides established regulatory cover for conventional strains.
- Alpha-Amylase:Randomly cleaves internal alpha-1,4-glycosidic bonds to reduce starch viscosity during liquefaction. China's starch processing corridors in Shandong and Jiangsu provinces drive liquid formulation adoption for automated dosing systems that cut enzyme waste. SAMR GB standards enforce strict activity labeling compliance.
- Pullulanase:Debranching enzyme hydrolyzing alpha-1,6 linkages in amylopectin. Premium brewing adjuncts in Belgium and Germany command batch-flexible supply arrangements.
- Beta-Amylase:Exoamylase releasing maltose units from non-reducing ends. Maltose syrup producers in Japan favor METI-certified formulations for traditional confectionery applications.
Established volume favors glucoamylase; emerging adoption favors pullulanase.
Application:
Process temperature and pH windows create incompatible enzyme specifications across downstream industries, forcing suppliers to maintain parallel certification pipelines.
- Baking:Fungal alpha-amylase strengthens dough gluten networks and extends shelf life through controlled starch modification. Automated bakery lines in São Paulo and Mexico City accelerate liquid formulation uptake for precision metering. ANVISA registration requirements shape import compliance costs for Brazilian processors.
- Brewing:Glucoamylase and pullulanase blends enable high-adjunct mashes and light beer production. Craft segments in Scotland and Kentucky adopt CRISPR-edited variants for simultaneous liquefaction-saccharification. REACH respiratory sensitization documentation elevates EU compliance burdens.
- Distilling:Saccharification efficiency directly determines ethanol yield per bushel. Fuel ethanol producers in Iowa and São Paulo consolidate supplier rosters around dual-source certified partners.
- Pharmaceuticals:Excipient-grade enzymes require USP-NF compliance and low-endotoxin certification. CDSCO manufacturing license requirements govern Indian contract manufacturing organization sourcing.
Process standardization favors baking; formulation complexity favors brewing.
End User:
Procurement scale and certification depth diverge sharply between commodity volume buyers and specialty-grade purchasers.
- Food Industry:Starch modification for texturizers and sweeteners demands thermostable variants. High-fructose corn syrup manufacturers in Illinois and Nebraska favor long-term offtake agreements with fixed-price escalation clauses.
- Beverage Manufacturers:Adjunct brewing and fruit juice clarification require pH-tolerant formulations. Japanese beverage conglomerates source through METI-approved enzyme trading houses.
- Textile Industry:Desizing applications for cotton fabric processing consume fungal amylase at lower purity grades. Gujarat and Tamil Nadu textile clusters drive Indian domestic production.
- Biofuel Producers:Carbon-intensity benchmarks in California LCFS and EU RED III incentivize low-carbon enzyme manufacturing process certification. Brazilian sugarcane ethanol mills integrate vertically into fermentation input supply.
Contract duration favors biofuel producers; spot market flexibility favors textile processors.
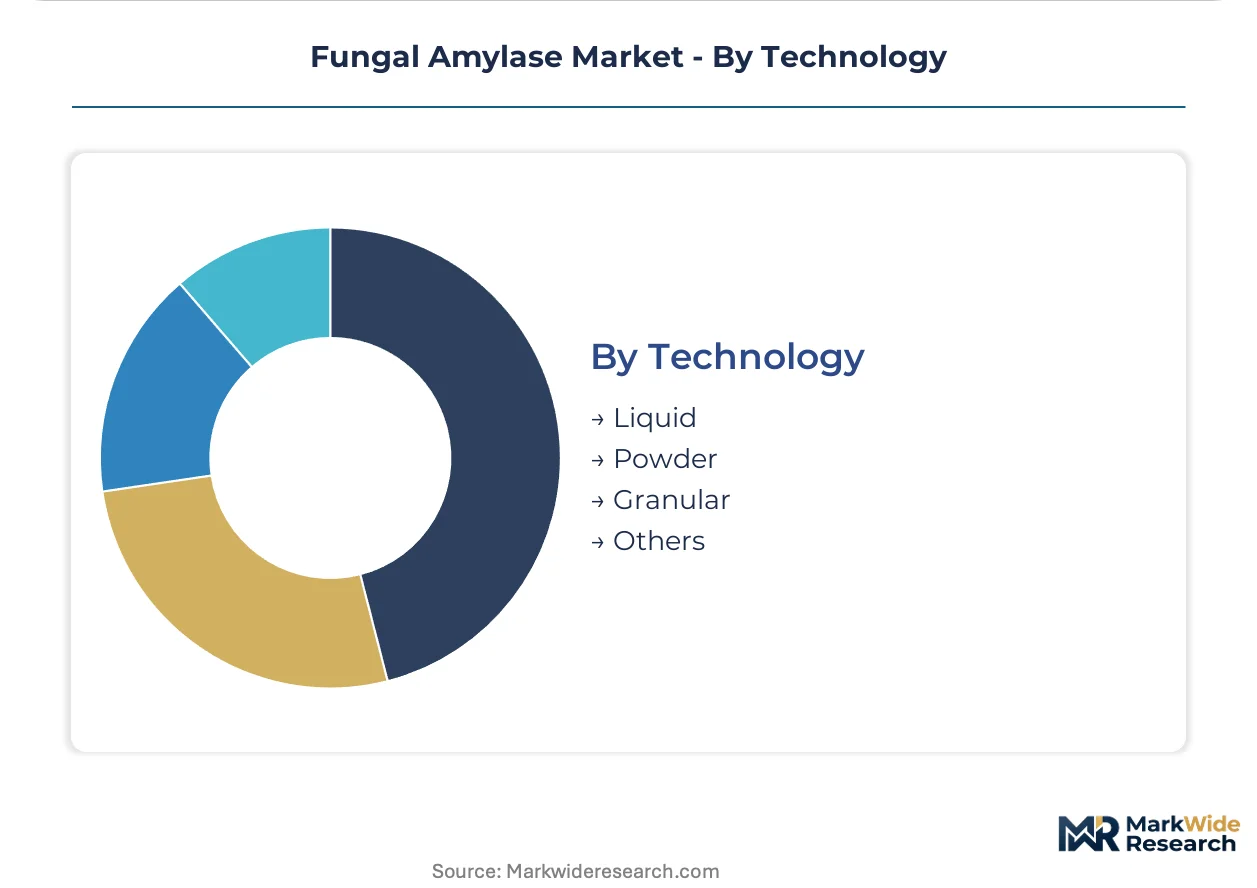
Technology:
Physical formulation determines logistics economics and dosing precision compatibility with customer automation infrastructure.
- Liquid:Standardized activity concentrations enable direct pump injection without reconstitution. Chinese starch corridors and Brazilian distilleries lead automated system integration.
- Powder:Shelf-stable distribution suits remote bakery and textile operations with limited cold chain access. Indian domestic suppliers dominate powder shipments to secondary cities.
- Granular:Dust-free handling properties reduce respiratory exposure compliance costs. German and Dutch food-grade facilities favor granular for dry-mix applications.
- Others:Immobilized and encapsulated variants for continuous reactor systems remain niche. Biocatalysis research programs at TU Delft and MIT explore novel carrier matrices.
Automation compatibility favors liquid; infrastructure adaptability favors powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in fungal amylase track divergent regulatory maturity and fermentation infrastructure density across major economies. Denmark and the Netherlands run structural surpluses in bulk glucoamylase, while India and China absorb inbound shipments amid domestic capacity buildouts.
United States
Fuel ethanol producers in Iowa and Nebraska drive glucoamylase consumption under the Renewable Fuel Standard. FDA 21 CFR 173.130 provides established regulatory cover for conventional strains. The Corn Belt processing corridor consolidates procurement around dual-source certified partners with long-term offtake agreements.
China
Starch processing demand concentrates in Shandong and Jiangsu provinces where automated dosing systems cut enzyme waste. SAMR enforces GB standards for activity labeling and contaminant thresholds that block uncertified imports. Domestic suppliers expand powder production for secondary cities lacking cold chain infrastructure.
India
The 20% ethanol blending target by 2025 pulls glucoamylase volumes toward state-run oil marketing companies. FSSAI and CDSCO govern food-grade and pharmaceutical-grade enzyme certifications respectively. Maharashtra and Gujarat textile clusters sustain parallel demand for lower-purity desizing grades.
Germany
Craft breweries in Bavaria and Baden-Württemberg seek batch-flexible alpha-amylase blends commanding premium positioning. EFSA Novel Food assessments and REACH respiratory sensitization documentation elevate compliance burdens. The Rhine-Ruhr industrial belt hosts dedicated regulatory affairs teams that absorb documentation costs.
Brazil
Sugarcane ethanol mills integrate backward into fermentation input supply to secure enzyme availability. ANVISA registration requirements shape import compliance costs for food-grade formulations. São Paulo and Minas Gerais distilleries lead automated system adoption for liquid enzyme dosing.
Fungal Amylase Market Vendor Landscape
Concentration sits with multi-thousand-liter bioreactor operators who dominate bulk glucoamylase output for fuel ethanol and high-fructose corn syrup verticals. Mid-scale formulation specialists compete on tailored blends for craft brewing and premium baking segments where batch flexibility commands price premiums. The competitive map reveals three archetypes: fermentation-scale infrastructure holders, application-specific blenders, and regulatory certification specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as entrants seek to bypass strain certification bottlenecks.
Within the fermentation-scale tier, Novozymes A/S and DSM exemplify infrastructure-heavy positioning anchored in Danish and Dutch manufacturing networks. AB Enzymes occupies a position among application-specific blenders serving European craft brewing segments. These three entities represent contrasting strategic postures—scale-driven commodity supply, certification-anchored regional dominance, and flexibility-focused specialty positioning—without implying specific market shares or revenue figures.
| Leading Market Players |
|---|
| Novozymes A/S |
| DSM |
| AB Enzymes |
| DuPont |
| BASF |
| Amano Enzyme |
| Chr. Hansen |
| Sunson |
| International Flavors & Fragrances Inc. |
| Others |
Supply Flow & Price Mechanics
EFSA Novel Food assessments and FDA GRAS pathways gate both supplier qualification and price differentiation simultaneously, creating a dual-tier market where certified operators command configured-to-order premiums while uncertified entrants compete on spot-priced commodity grades.
Pricing Analysis
Configured-to-order pricing for strain-certified glucoamylase runs 40-60% above standard bulk grades, with the premium reflecting 18-36 month certification timelines and dedicated regulatory affairs overhead. Contract-based long-term offtake agreements with fixed-price escalation clauses dominate fuel ethanol and high-fructose corn syrup procurement, insulating certified suppliers from agricultural commodity volatility. Price differentiation hinges on certification tier—EFSA-approved food-grade strains command substantial premia over technical-grade alternatives—and volume scale, with multi-thousand-liter bioreactor operators extracting economies unavailable to mid-scale blenders. Cost compression in technical-grade powder formulations is intensifying because Indian and Chinese domestic suppliers expand capacity for textile desizing applications. Craft brewing segments exhibit lowest price sensitivity, prioritizing batch flexibility and tailored alpha-amylase blends over per-kilogram economics.
Supply Chain Analysis
Port congestion on Rotterdam-Singapore lanes and container availability constraints on Asia-Europe routes elevate inbound logistics costs for European formulators sourcing raw enzyme concentrates from Danish and Dutch fermentation hubs. Geographic supply concentration centers on Denmark, the Netherlands, and China, with bulk glucoamylase output clustering among operators with captive multi-thousand-liter bioreactor networks in the first two and starch-processing corridor proximity driving Chinese domestic expansion. Raw material dependencies draw from corn steep liquor, soy protein, and specialized fungal strain banks held under proprietary control. Single-source vulnerability constitutes the dominant structural risk, as strain certification bottlenecks prevent rapid supplier switching. Distribution runs through direct long-term contracts for fuel ethanol and high-fructose corn syrup verticals, with spot-market flexibility surviving only in textile desizing and remote bakery segments lacking cold chain infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bacterial amylase substitution threatens fungal variants in high-temperature industrial applications, forcing incumbents to defend positioning through certification moats and performance differentiation rather than cost alone.
For Market Incumbents: Secure dual-source supply arrangements with state-run oil marketing companies in India and integrated agribusinesses in Brazil to lock in volume commitments before bacterial amylase technical improvements accelerate. Deepen backward integration into proprietary strain banks and CRISPR editing platforms to compress certification timelines and outpace substitute performance convergence. Prioritize regulatory affairs team expansion in the Netherlands and Germany to absorb REACH respiratory sensitization documentation burdens that smaller competitors cannot shoulder. For New Entrants and Emerging Players: Lead with batch-flexible alpha-amylase blends for craft breweries in Bavaria and Kentucky, where incumbent focus on commodity scale leaves white-space for configured-to-order service. Target textile desizing clusters in Gujarat and Tamil Nadu with lower-purity powder grades that bypass food-grade certification barriers entirely. Pursue joint development agreements with precision fermentation platforms to access CRISPR-edited strains without bearing full R&D capitalization. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation infrastructure, favoring platforms with demonstrated strain-engineering capabilities over traditional bioreactor operators. Over the projection horizon, viable acquisition targets combine regulatory certification pipelines with application-specific formulation expertise rather than commodity volume scale. Watch for EFSA streamlined safety assessment announcements as inflection indicators for next-generation amylase variant commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Certification Pipeline Investment | EFSA Novel Food and FDA GRAS approvals compress time-to-revenue for engineered variants. |
| Precision Fermentation Platform Partnership | CRISPR-edited Aspergillus strains unlock novel pH-temperature windows beyond conventional trade-offs. |
| Long-term Offtake Agreement with Fuel Ethanol Producers | Indian state-run oil marketing companies and Brazilian sugarcane mills prioritize supply security over spot pricing. |
| Backward Integration into Raw Strain Supply | Proprietary fungal strain banks reduce dependency on external culture collections and accelerate R&D cycles. |
| Regulatory Affairs Team Expansion in EU | REACH respiratory sensitization documentation and EFSA assessments absorb fixed costs that exclude smaller exporters. |
Methodological Framework
A spread of perspectives from fermentation plant managers, enzyme procurement leads at fuel ethanol distilleries, regulatory affairs directors, and starch processing corridor engineers converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA 21 CFR filings, EFSA Novel Food assessment records, SAMR GB standard documentation, and customs trade data for enzyme concentrate shipments. Bottom-up triangulation across product-grade volume estimates and top-down cross-checks against end-use industry consumption patterns anchored the modeling framework.
Segmentation dimensions modeled span enzyme class, application vertical, end-user procurement scale, and physical formulation technology across the projection horizon. CAGRs derive from fitted growth curves calibrated to ethanol blending mandate trajectories, starch processing automation adoption rates, and craft brewing segment expansion patterns. Industry-specific forecast inputs include state-run oil marketing company contract disclosure patterns and carbon-intensity benchmark evolution under EU RED III and California LCFS frameworks.
Forecasts assume regulatory continuity in EFSA Novel Food pathways, FDA GRAS self-affirmation procedures, and SAMR GB enforcement intensity; material policy shifts would require re-modeling. Strain-level approval delays, agricultural commodity price spikes, or precision fermentation platform technical failures constitute specific risk factors that could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Styrene Monooxygenase Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Glucoamylase Market