
 Global Specialty Enzymes Market | 2026-2036
Global Specialty Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Enzymes Market Foresight
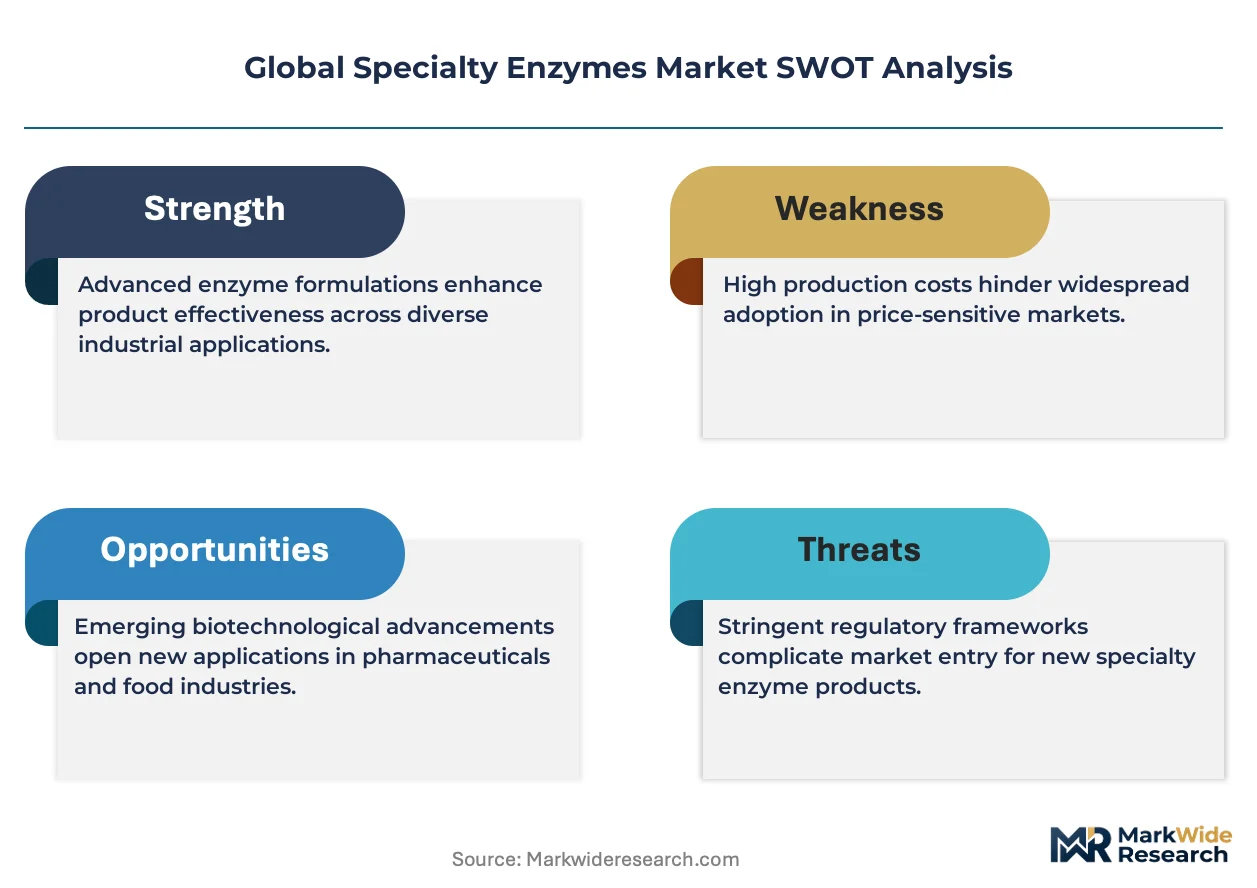
The gap between premium-grade biocatalysts and commodity industrial enzymes is broadening as pharmaceutical applications demand higher specificity and regulatory documentation. Novozymes A/S dominates the commodity detergent enzyme segment through manufacturing scale. Codexis specializes in engineered biocatalysts for pharmaceutical intermediates, commanding differentiated pricing. DSM-Firmenich leverages its nutrition science heritage to anchor positions in food-grade specialty enzymes.
Specialty enzymes are proteins engineered or isolated for targeted catalytic functions under defined pH, temperature, and substrate conditions, typically manufactured through microbial fermentation with subsequent purification and formulation steps. Their primary commercial purpose is to accelerate specific chemical transformations in pharmaceutical synthesis, food processing, and biofuel production with minimal byproduct formation. Protease enzymes lead the product type landscape due to entrenched demand in detergents and leather processing, while lipase variants represent the fastest-expanding category driven by pharmaceutical esterification applications. Encapsulated enzyme formulations capture the strongest margin pools by protecting activity during storage and enabling controlled release in harsh industrial environments.
FDA scrutiny of biocatalytic processes in active pharmaceutical ingredient manufacturing shapes validation requirements for pharmaceutical-grade enzymes. REACH and the EU Green Deal impose substance registration and carbon intensity thresholds on enzyme producers supplying European industrial customers. China's NMPA and GB standards govern food enzyme safety assessments in that market. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate compliance costs and market access barriers.
Market Dynamics
Pharmaceutical biocatalysis is driving a bifurcation between commodity-scale enzyme manufacturing and precision-engineered biocatalysts requiring extensive regulatory documentation. This structural split concentrates margin capture among specialists while squeezing generalist producers.
Growth Catalysts
- EU Green Deal carbon thresholds:European industrial customers now mandate low-carbon enzyme supply chains, redirecting procurement toward fermentation facilities with verified emissions profiles.
- Biocatalysis in API synthesis:Pharmaceutical manufacturers are replacing traditional chemical catalysts with enzymes for chiral intermediate production, demanding higher specificity and batch documentation.
- China's biomanufacturing clusters:Concentrated investment in Tianjin and Suzhou industrial parks is creating integrated enzyme production hubs serving domestic food and pharma sectors.
Market Restraints
- Fermentation input volatility:Corn syrup and nitrogen source costs fluctuate with agricultural commodity cycles, compressing margins for bulk enzyme grades.
- Single-source supplier risk:Purification resin and chromatography media for pharmaceutical-grade enzymes concentrate among German and US specialty chemical vendors.
- Thermal stability ceiling:Natural enzyme variants degrade above 60°C in many industrial processes, limiting substitution for chemical catalysts in high-temperature reactions.
Strategic Opportunities
- India's PLI scheme for biotech:Production-linked incentives for fermentation-based manufacturing are attracting contract enzyme producers to establish local capacity.
- Cell-free enzyme systems:Lyophilized enzyme cascades eliminate live-cell fermentation constraints, opening point-of-use biocatalysis for distributed pharmaceutical synthesis.
- Japan's METI bioeconomy roadmap:National targets for bio-based chemical production are creating mandated demand pull for industrial biocatalysts in polyester and nylon precursors.
Industry Challenges
- Protein engineering talent scarcity:Computational enzyme design requires rare combinations of structural biology and machine learning expertise, constraining R&D throughput.
- Multi-jurisdiction dossier compilation:FDA, EMA, and NMPA each demand distinct stability and purity validation protocols, extending time-to-market for new enzyme products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Enzymes Market |
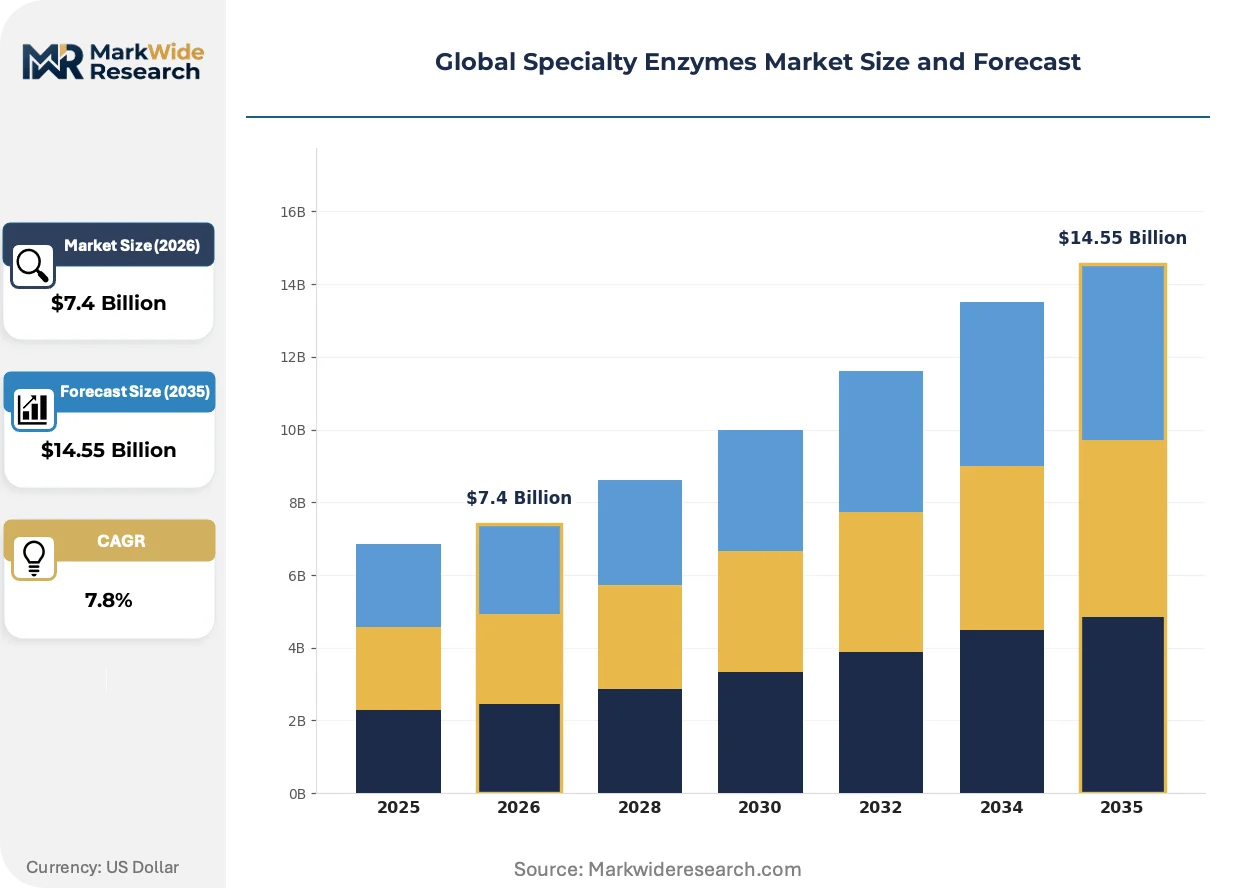
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $14.55 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protease, Lipase, Amylase, Cellulase, Pectinase, Glucose Oxidase Application: Detergents, Textile Processing, Food & Beverages, Bioethanol, Animal Feed, Paper & Pulp End User: Pharmaceutical Manufacturers, Agrochemical Producers, Cosmetic Companies, Biofuel Plants, Food Processors Form: Liquid, Powder, Granular, Encapsulated |
| Companies Covered | BASF SE, International Flavors & Fragrances, DSM-Firmenich, Kerry Group plc, Advanced Enzyme Technologies, Novozymes A/S, Merck KGaA, Codexis, Amano Enzyme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Enzymes Market Shifts & Advancements
Directed evolution platforms and AI-assisted protein design are compressing development cycles for custom biocatalysts. These tools enable rapid optimization of enzyme properties for specific industrial conditions.
Machine learning-guided directed evolution is integrating computational screening with high-throughput laboratory testing to identify enzyme variants with enhanced substrate scope. Pharmaceutical contract manufacturers are adopting these platforms to reduce biocatalyst development from 24 months to under 12 months. This compression is enabling just-in-time enzyme engineering for single-product pharmaceutical campaigns.
REACH substance registration deadlines are forcing enzyme producers to compile extensive toxicological and environmental fate data for commercial formulations. The regulatory burden falls most heavily on multi-product manufacturers with extensive legacy portfolios. Smaller specialists with focused product lines are gaining compliance speed advantages over diversified incumbents.
Long-term supply agreements with fermentation capacity guarantees are displacing spot purchasing for pharmaceutical-grade enzymes. Biopharma CDMOs now contract directly with enzyme houses for dedicated bioreactor slots. This shift is most pronounced in Germany and Switzerland, where API manufacturers seek supply security for multi-year drug programs.
Global Specialty Enzymes Market Segmentation
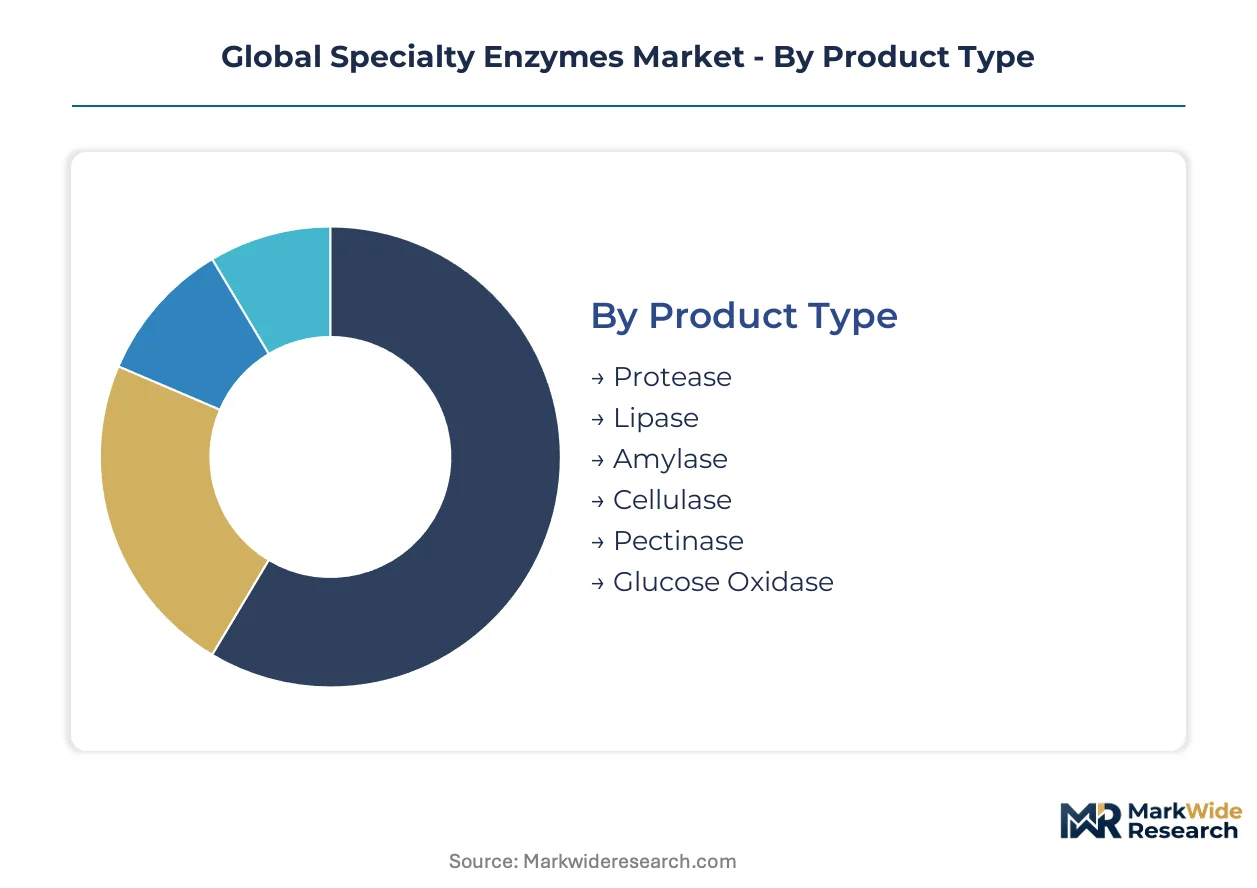
Specialty enzyme markets fragment across technical specifications, regulatory requirements, and end-use performance thresholds. Each segmentation dimension carries distinct margin profiles and supplier qualification barriers that reshape procurement patterns.
Product Type:
Upgrade cycles in industrial biocatalysis are pushing manufacturers toward higher-activity enzyme variants with improved thermal tolerance and substrate specificity.
- Protease:These protein-cleaving enzymes dominate detergent formulations and leather processing applications. Demand concentrates in Germany and the United States where REACH and EPA compliance documentation drives premium-grade procurement. Fermentation scale and purification efficiency determine supplier competitiveness in this mature segment.
- Lipase:Ester-bond hydrolysis enzymes enable pharmaceutical chiral intermediate synthesis and biodiesel production. Pharmaceutical manufacturers in Switzerland and India are expanding lipase adoption for biocatalytic API steps, drawn by regioselectivity advantages over chemical catalysts.
- Amylase:Starch-degrading enzymes serve food processing and bioethanol industries across China and Brazil.
- Cellulase:Cellulose-degrading complexes unlock lignocellulosic biomass conversion for second-generation biofuels.
- Pectinase:Pectin-degrading enzymes clarify fruit juices and wines in Mediterranean food processing clusters.
- Glucose Oxidase:Oxygen-scavenging enzymes preserve food freshness and stabilize dough in bakery applications.
Protease sits at the top of the volume ranking, with lipase climbing the fastest.
Application:
Cost tier differentiation separates commodity enzyme applications from precision biocatalysis segments commanding five-fold price premiums.
- Detergents:Bulk protease and amylase formulations serve mass-market laundry and dishwashing products. Procurement in the United States and Western Europe concentrates among three fermentation houses with verified low-carbon supply chains under EU Green Deal thresholds.
- Food & Beverages:Food-grade enzymes require FSSAI, FDA, or EFSA safety dossiers depending on jurisdiction. Chinese food processors are expanding pectinase and amylase adoption for clarified juices and modified starches, driving regional capacity expansion.
- Textile Processing:Cellulase variants enable bio-polishing and denim finishing with reduced water consumption.
- Bioethanol:Starch-to-sugar conversion enzymes serve first-generation ethanol plants in Brazil and the United States.
- Animal Feed:Phytase and carbohydrase additives improve nutrient digestibility in poultry and swine operations.
- Paper & Pulp:Xylanase and lipase treatments reduce chlorine bleaching requirements in Nordic mills.
Detergents anchor absolute volume, while food and beverages gains share fastest on clean-label formulation trends.
End User:
Customer type determines validation depth, with pharmaceutical and food processors imposing the most stringent supplier audit protocols.
- Pharmaceutical Manufacturers:Biocatalysis adopters require enzyme variants with full regulatory dossiers for API manufacturing. German and Swiss CDMOs are contracting dedicated fermentation capacity for multi-year drug programs, securing supply continuity under EMA and FDA scrutiny.
- Food Processors:Enzyme users demand food-grade certifications and allergen-free documentation. Chinese dairy and bakery sectors are expanding lipase and amylase procurement under NMPA and GB standards enforcement.
- Agrochemical Producers:Biocatalyst users synthesize chiral pesticide intermediates with enzymatic resolution steps.
- Cosmetic Companies:Formulators deploy lipases and proteases for active ingredient extraction and gentle exfoliation.
- Biofuel Plants:Cellulosic ethanol developers test enzyme loading rates against chemical catalyst economics.
Pharmaceutical manufacturers command the highest per-kilogram pricing, with food processors expanding volume most aggressively.
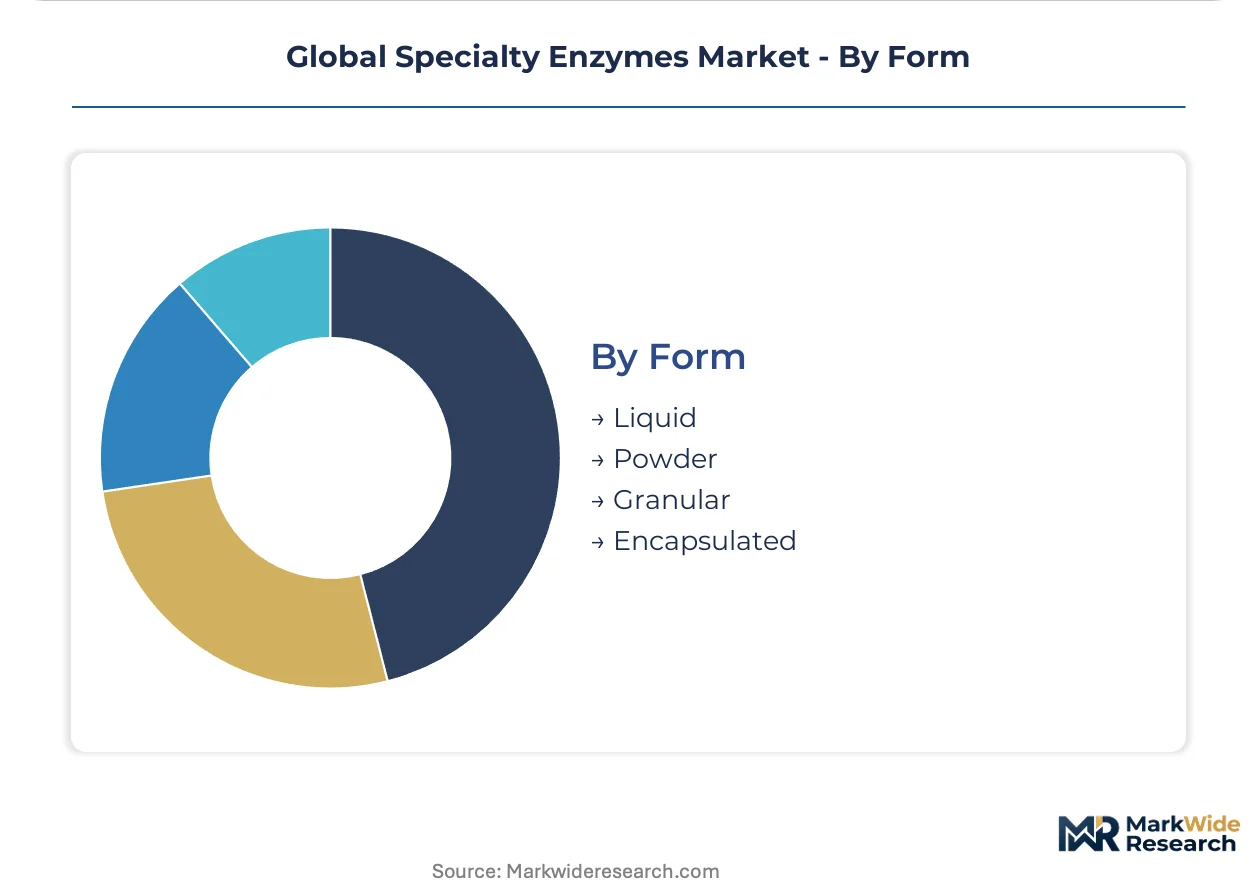
Form:
Margin concentration follows formulation complexity, with encapsulated variants capturing premium pools through extended shelf stability.
- Encapsulated:Protective matrix formulations shield enzyme activity from moisture, oxygen, and temperature extremes. Pharmaceutical biocatalysts in lyophilized or lipid-coated forms enable controlled release in harsh reaction conditions, justifying substantial price premiums over standard grades.
- Liquid:Standard aqueous formulations serve high-volume detergent and textile applications where immediate dissolution matters.
- Powder:Spray-dried preparations offer intermediate stability for food and feed compounding.
- Granular:Agglomerated forms reduce dust exposure in industrial handling environments.
Liquid formulations dominate shipment volumes, with encapsulated forms expanding most quickly in pharmaceutical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein engineering talent pools anchor geographic competitiveness, with fermentation scientists and computational biologists concentrating in established biotech corridors. Regulatory divergence across jurisdictions reshapes where producers site manufacturing assets versus R&D functions.
United States
Pharmaceutical biocatalysis demand from Boston and San Francisco biotech clusters drives enzyme procurement. FDA validation requirements for API manufacturing enzymes impose extensive stability documentation burdens. North Carolina's Research Triangle houses contract fermentation capacity serving multi-year drug programs under dedicated supply agreements.
Germany
REACH substance registration and EU Green Deal carbon thresholds redirect industrial procurement toward verified low-carbon supply chains. EMA scrutiny of biocatalytic processes shapes validation protocols for pharmaceutical-grade enzymes. The Rhine-Ruhr and Bavarian chemical corridors concentrate fermentation infrastructure serving domestic and Swiss pharmaceutical manufacturers.
China
Domestic food processing expansion and biomanufacturing cluster development in Tianjin and Suzhou drive regional capacity investment. NMPA and GB standards enforcement governs food enzyme safety assessments and documentation requirements. Yangtze River Delta industrial parks integrate upstream fermentation with downstream purification for domestic pharma and nutrition sectors.
Switzerland
Swissmedic oversight of biocatalytic API manufacturing attracts enzyme suppliers seeking pharmaceutical-grade certification proximity. Basel and Zurich pharmaceutical CDMOs contract dedicated fermentation capacity for multi-year drug programs. The country's precision manufacturing heritage supports high-purity enzyme formulation capabilities.
India
PLI scheme production-linked incentives for fermentation-based manufacturing attract contract enzyme producers to establish local capacity. CDSCO pharmaceutical regulations and FSSAI food safety standards govern parallel compliance pathways. Hyderabad and Bengaluru biotech corridors develop integrated enzyme production serving domestic and export pharmaceutical markets.
Global Specialty Enzymes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin tiers. The market structure concentrates volume leadership among multi-product fermentation houses while fragmenting precision biocatalyst supply among specialists. Three archetypes dominate: commodity-scale fermentation operators, engineered biocatalyst specialists, and nutrition-science heritage players. M&A activity targets purification technology capabilities, while long-term supply agreements displace spot purchasing for pharmaceutical-grade enzymes.
Within the engineered biocatalyst tier, Codexis occupies a position exemplifying precision enzyme design for pharmaceutical intermediates. Among European heritage conglomerates, BASF SE and DSM-Firmenich represent divergent paths—one anchored in industrial chemical scale, the other in nutrition and food-grade enzyme documentation. Novozymes A/S sits within the commodity fermentation archetype, exemplifying manufacturing scale advantages in detergent and industrial enzyme segments where carbon footprint verification under EU Green Deal thresholds increasingly determines procurement outcomes.
| Leading Market Players |
|---|
| BASF SE |
| International Flavors & Fragrances |
| DSM-Firmenich |
| Kerry Group plc |
| Advanced Enzyme Technologies |
| Novozymes A/S |
| Merck KGaA |
| Codexis |
| Amano Enzyme |
| Others |
Supply & Pricing Matrix
Captive fermentation capacity in Germany and Switzerland anchors supply security for pharmaceutical-grade enzymes while commanding substantial price premiums over spot-market commodity grades. This integration choice concentrates pricing power among houses with dedicated bioreactor slots under EMA-validated protocols, leaving generalist producers exposed to margin compression from agricultural input volatility.
Pricing Analysis
Bundled long-term supply agreements with dedicated fermentation slots and regulatory dossier support command three-to-five-fold premiums over unbundled spot enzyme purchases. Pharmaceutical biocatalysts stratify across premium, standard, and economy tiers based on FDA/EMA validation depth and batch documentation granularity. Cost compression in commodity detergent proteases intensifies as EU Green Deal carbon verification requirements add compliance overhead. Food processors exhibit highest price sensitivity due to clean-label formulation pressures, while pharmaceutical CDMOs prioritize supply continuity over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from Swiss and German pharmaceutical manufacturers require enzyme houses to qualify backup fermentation facilities under identical EMA protocols. Supply concentrates in Denmark, Germany, and China, with downstream purification resins drawing from specialized German and US chemical vendors. Corn syrup and nitrogen feedstock costs fluctuate with agricultural commodity cycles, creating margin vulnerability for bulk grades. Distribution runs through direct long-term contracts rather than distributor networks for pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: India's PLI scheme production-linked incentives offer cost-advantaged fermentation capacity against REACH compliance burdens in Europe.
For Market Incumbents: Hedge fermentation margin exposure by securing multi-year corn syrup supply contracts with agricultural cooperatives in the US Midwest and Brazil. Establish captive purification resin production or backward integration into chromatography media manufacturing to reduce single-source dependency on German specialty chemical vendors. Codexis-style precision biocatalyst specialists threaten commodity-grade incumbents through regioselectivity advantages in pharmaceutical esterification.
For New Entrants and Emerging Players: Contract research organizations in Hyderabad and Bengaluru provide channel access to pharmaceutical CDMOs seeking dedicated fermentation capacity for multi-year drug programs. Target India's domestic food processing expansion under FSSAI enforcement as the most penetrable volume segment. Lead with cell-free lyophilized enzyme cascades to bypass live-cell fermentation capital requirements and enable point-of-use biocatalysis.
For Investors and Strategic Acquirers: Roll-up economics work for regional fermentation houses with verified EU Green Deal carbon profiles because REACH substance registration deadlines force smaller competitors into compliance-driven distress sales. Five-to-ten year viability hinges on purification technology capabilities rather than fermentation scale alone. Watch FDA biocatalytic process validation guidance expansion as the signal for pharmaceutical-grade margin inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Biopharma CDMOs in Basel contract dedicated bioreactor slots under EMA scrutiny. |
| Backward Integration | Enzyme houses acquire chromatography resin production to reduce German vendor dependency. |
| Green Manufacturing Transition | Fermentation facilities verify carbon intensity thresholds under EU Green Deal procurement mandates. |
| Capacity Expansion | Tianjin and Suzhou industrial parks integrate upstream fermentation with downstream purification. |
| Joint Venture | Swiss pharmaceutical CDMOs partner with enzyme houses for multi-year API program supply security. |
Research Methodology
Multiple input streams — fermentation plant managers, pharmaceutical procurement leads at CDMOs, regulatory affairs directors, and food-grade enzyme safety assessors — were reconciled against customs trade data, ECHA REACH registration databases, SEC filings from listed enzyme houses, and FSSAI enforcement circulars. Bottom-up capacity modeling across Denmark, Germany, China, and India was cross-validated with top-down demand estimation from pharmaceutical biocatalysis adoption rates and detergent formulation trends.
Historical capacity utilization patterns were cross-referenced against expert panel inputs on directed evolution platform adoption timelines. Segmentation modeling spanned product type, application, end-user validation depth, and formulation complexity across the projection horizon. CAGRs were derived from fermentation capacity expansion announcements, pharmaceutical pipeline biocatalysis disclosures, and regulatory enforcement trajectory assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH substance registration deadline shifts, FDA biocatalytic process validation guidance evolution, and agricultural commodity input cost trajectories. Deviation in EU Green Deal carbon threshold stringency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Inulinase Market
Industrial Biotechnology
Phospholipase Enzyme Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Pyruvate Synthase Market
Industrial Biotechnology
Esterase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Biocatalyst Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Glucoamylase Market