
 Esterase Market | 2026-2036
Esterase Market Size, Share, and Industry Trends Forecast 2026-2036
Esterase Market Analytics
Pharmaceutical biocatalysis is repositioning esterase demand as drug manufacturers replace traditional chemical routes with enzyme-mediated synthesis. Novozymes A/S leverages its fermentation scale to dominate industrial-grade supply chains. DSM anchors its position through deep specialization in pharmaceutical-grade enzyme formulations. BASF SE competes by extending its reach into custom biocatalysis partnerships with generic API producers.
Esterases constitute a class of hydrolase enzymes that cleave ester bonds into acids and alcohols, typically operating at mild temperatures of 30–50°C and pH ranges of 6.0–8.5 for optimal catalytic efficiency. Their primary industrial purpose centers on selective transformations in pharmaceutical intermediate production, agrochemical synthesis, and food lipid modification. Carboxylesterases command the largest volume share due to their broad substrate scope in prodrug activation, while lipases capture the fastest growth trajectory driven by expanding demand for structured lipids and biodiesel precursors. Pharmaceutical Companies represent the most concentrated end-user margin pool, though Research Laboratories are scaling procurement fastest as CRISPR-enabled enzyme engineering reduces development timelines.
REACH registration requirements and the EU Green Deal sustainability mandates are forcing producers to document biodegradability and reduce solvent intensity in manufacturing processes. FDA's process validation guidelines for enzymatic drug substances are shaping qualification standards that suppliers must meet for North American market access. ISO quality management frameworks further govern batch consistency for clinical-grade esterases. Stakeholders must monitor how regulatory convergence between EMA and FDA on biocatalysis acceptance criteria will reshape supplier qualification burdens and regional sourcing decisions.
Market Dynamics
Pharmaceutical biocatalysis is compressing process development timelines as enzyme-mediated routes displace traditional chemical synthesis, forcing suppliers to reconfigure capacity around clinical-grade fermentation rather than commodity-scale production.
Growth Catalysts
- REACH biodegradability mandates:European chemical manufacturers must document enzymatic process sustainability, pulling esterase demand into green chemistry substitution programs.
- Prodrug activation protocols:Oncology and cardiovascular drug pipelines are embedding esterase-cleavable linkers, concentrating procurement among API specialists.
- Germany's industrial biotechnology corridor:Concentrated fermentation infrastructure around Heidelberg and Jülich is anchoring regional supply security for pharmaceutical-grade enzymes.
Market Restraints
- Fermentation input volatility:Corn syrup and yeast extract price swings compress margin predictability for bulk enzyme producers.
- Single-source substrate risk:Chinese specialty chemical intermediates dominate cofactor and buffer supply chains, creating geographic concentration exposure.
- Thermal stability ceilings:Wild-type esterase variants degrade above 50°C, limiting deployment in high-temperature continuous processing.
Strategic Opportunities
- India's PLI scheme for active pharmaceuticals:Domestic enzyme manufacturing incentives are opening localization pathways for multinational biocatalysis suppliers.
- CRISPR-guided enzyme engineering:Directed evolution platforms are collapsing development cycles for custom substrate specificity.
- Biodiesel precursor refinement:Lipase-class esterases are capturing lipid transesterification demand as renewable fuel mandates tighten.
Industry Challenges
- Fermentation scale-up talent scarcity:Process engineers with GMP biologics experience command premium compensation, constraining mid-tier producer expansion.
- FDA process validation timelines:Enzymatic drug substance qualification requires 18-24 month documentation cycles, freezing supplier switching decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Esterase Market |
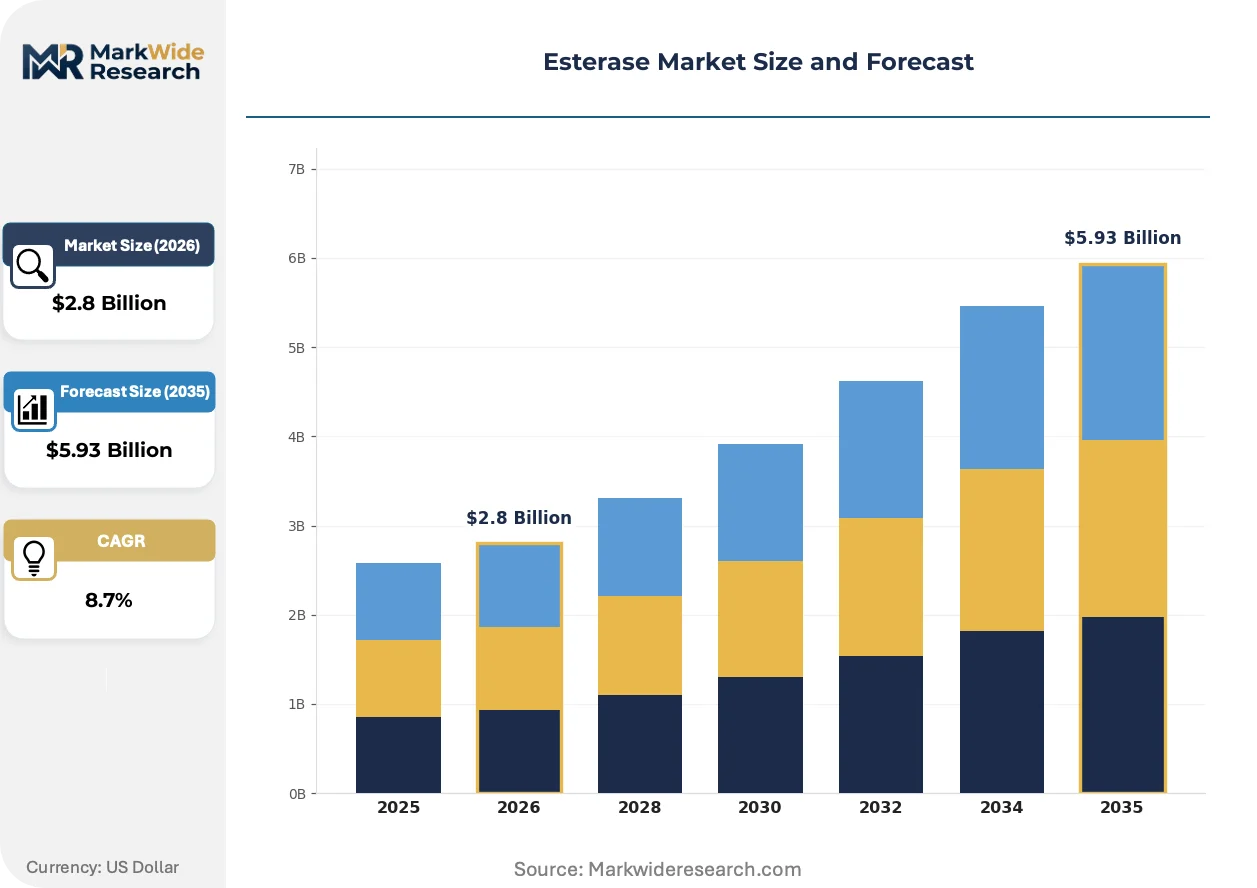
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carboxylesterases, Acetylcholinesterases, Lipases, Pharmaceutical Esterases Application: Pharmaceuticals, Agriculture, Food Industry, Biocatalysis End User: Pharmaceutical Companies, Research Laboratories, Agrochemical Firms, Biotechnology Companies Technology: Enzymatic Technology, Chemical Synthesis, Genetic Engineering, Screening Methods |
| Companies Covered | Novozymes A/S, DSM, DuPont Danisco, BASF SE, Advanced Enzyme Technologies, Creative Enzymes, Specialty Enzymes & Probiotics, Amano Enzyme Inc., AB Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Esterase Market Evolving Landscape
Immobilized enzyme systems are rewriting unit economics for continuous pharmaceutical manufacturing, collapsing batch-to-batch variability while stretching catalyst lifetime across multiple reaction cycles.
Directed evolution platforms are expanding into pharmaceutical intermediate production as Novozymes and DSM deploy high-throughput screening to engineer thermostable variants. Generic API manufacturers in India and China are adopting these tailored biocatalysts to bypass patent-protected chemical routes. The technology is expanding into cost-sensitive therapeutic categories previously reserved for traditional synthesis.
EMA's revised biocatalysis guidance for marketing authorization applications is mandating enzyme source documentation and impurity profiling for drug substances manufactured via enzymatic steps. European generic producers must now maintain dual qualification dossiers for chemical and enzymatic routes. Small-molecule specialists are responding by embedding quality-by-design into early-stage enzyme selection.
Contract development and manufacturing organizations are unbundling enzyme supply from process development services, enabling pharmaceutical sponsors to source biocatalysts independently while retaining IP ownership. This disintermediation is compressing the traditional Novozymes-DSM duopoly in integrated biocatalysis packages. Biotech startups in Boston and Basel are piloting this model for Phase II API manufacturing.
Esterase Market Segmentation
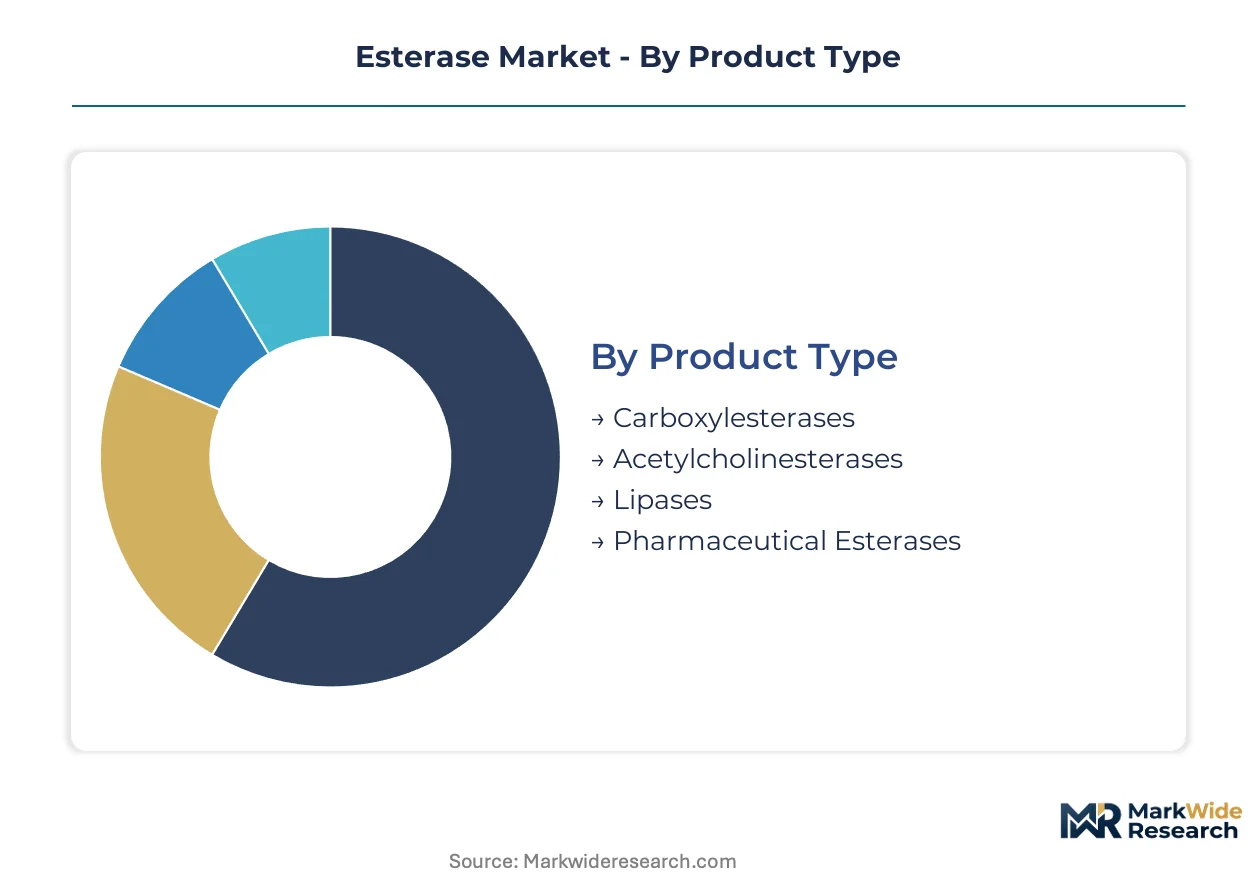
Esterase market segmentation reveals divergent technical requirements across pharmaceutical-grade precision and industrial-scale throughput. Each category maps distinct value capture mechanisms from fermentation capacity to substrate engineering intensity.
Product Type:
Customization intensity varies sharply across this category, from catalog-standard industrial enzymes to patient-specific biocatalyst formulations requiring GMP documentation.
- Carboxylesterases:These enzymes hydrolyze carboxylic acid esters with broad substrate promiscuity, enabling prodrug activation in oncology pipelines. Demand concentrates among API manufacturers in Germany's Rhine-Neckar biotechnology cluster, where REACH biodegradability documentation requirements favor enzymatic routes over solvent-heavy chemical alternatives.
- Lipases:Triglyceride-specific hydrolases operating at oil-water interfaces, structurally distinct from serine esterases through their lid-domain activation mechanism. Food lipid modification in the Netherlands and biodiesel precursor refinement in Spain are pulling capacity expansion, with thermostable variants commanding premium positioning for continuous processing applications.
- Acetylcholinesterases:Neural synapse enzymes with narrow therapeutic relevance, primarily procured for Alzheimer's research protocols and neurotoxicology screening.
- Pharmaceutical Esterases:GMP-grade biocatalysts with documented impurity profiles and host-cell protein clearance validation for regulatory submission.
Most installed capacity flows through Carboxylesterases. Expansion is steepest in Lipases.
Application:
Margin structure across this category inverts conventional volume logic, with kilogram-scale pharmaceutical intermediates outperforming tonnage-scale commodity conversions on per-unit economics.
- Pharmaceuticals:Enzymatic resolution of chiral intermediates and prodrug activation chemistry. EMA biocatalysis guidance is mandating enzyme source documentation for marketing authorization, compressing supplier qualification timelines and favoring established fermentation houses with existing regulatory dossiers.
- Biocatalysis:Process development services and custom enzyme supply for route scouting. Contract manufacturers in Basel and Boston are unbundling catalyst procurement from process development, enabling sponsor IP retention while fragmenting traditional integrated supplier relationships.
- Agriculture:Pesticide intermediate synthesis and crop protection agent manufacturing, with cost pressure favoring wild-type enzymes over engineered variants.
- Food Industry:Lipid transesterification for structured triglycerides and flavor ester production, governed by FSSAI and EFSA purity standards.
Pharmaceuticals anchor revenue concentration. Biocatalysis is climbing the fastest.
End User:
Procurement sophistication separates this category, from commodity catalog buyers to sponsors requiring co-development partnerships and regulatory filing support.
- Pharmaceutical Companies:Integrated biocatalysis programs displacing traditional chemical routes in generic API manufacturing. FDA process validation timelines of 18-24 months freeze supplier switching decisions, entrenching incumbents with existing drug master files.
- Research Laboratories:CRISPR-enabled enzyme engineering is collapsing development cycles, accelerating procurement velocity for screening-grade biocatalysts. Academic consortia around Heidelberg and Jülich are scaling pilot fermentation for prototype variants.
- Agrochemical Firms:Volume-driven procurement with limited tolerance for unit cost premiums, sourcing primarily from Chinese fermentation capacity.
- Biotechnology Companies:Cell therapy and gene therapy developers requiring ancillary enzyme reagents with ancillary process documentation.
Most value capture concentrates in Pharmaceutical Companies. Procurement velocity peaks in Research Laboratories.
Technology:
Capital intensity gradients define this category, from established fermentation infrastructure to high-throughput screening platforms requiring specialized talent.
- Enzymatic Technology:Immobilized enzyme systems and continuous flow biocatalysis are rewriting unit economics, stretching catalyst lifetime across multiple reaction cycles while collapsing batch-to-batch variability for GMP manufacturing.
- Genetic Engineering:Directed evolution platforms deploying high-throughput screening for thermostable variants. Novozymes and DSM are internalizing these capabilities, while generic API manufacturers in India adopt tailored biocatalysts to bypass patent-protected chemical routes.
- Chemical Synthesis:Legacy manufacturing routes facing substitution pressure from REACH solvent reduction mandates and EMA sustainability documentation requirements.
- Screening Methods:Microfluidic and droplet-based selection technologies accelerating variant identification for custom substrate specificity.
Most process validation heritage resides in Enzymatic Technology. Development investment is steepest in Genetic Engineering.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping esterase production geography as manufacturers migrate toward jurisdictions with streamlined biocatalysis approval pathways and concentrated fermentation infrastructure.
Germany
REACH documentation mandates and EU Green Deal sustainability requirements pull pharmaceutical-grade enzyme demand toward enzymatic routes. The country's national chemical regulator enforces biodegradability verification for process chemicals. Heidelberg and Jülich anchor the Rhine-Neckar biotechnology corridor where GMP fermentation capacity concentrates.
United States
FDA process validation timelines of 18-24 months entrench incumbent suppliers with existing drug master files. The agency's guidelines for enzymatic drug substances shape qualification standards that biocatalysis suppliers must meet. Greater Boston hosts contract development organizations unbundling enzyme supply from process development services.
India
Domestic API manufacturing incentives under the PLI scheme open localization pathways for multinational biocatalysis suppliers. CDSCO alignment with FDA enzymatic qualification standards accelerates regulatory convergence. Maharashtra and Gujarat concentrate generic API fermentation infrastructure where tailored biocatalyst adoption is climbing fastest.
China
NMPA oversight of biologics manufacturing and dual carbon goals drive substitution of solvent-heavy chemical routes with enzymatic processes. The Ministry of Ecology and Environment enforces emission reductions that favor biocatalysis. Yangtze River Delta fermentation capacity supplies both domestic pharmaceutical demand and export markets.
Netherlands
EFSA purity standards for food-grade enzymes and REACH solvent reduction mandates concentrate lipid modification demand. The country's national food safety authority governs structured triglyceride production. Eindhoven Region anchors food biotechnology clusters where thermostable lipase variants command premium positioning.
Esterase Market Competitive Landscape
Capacity expansion dominates the current landscape as fermentation houses scale GMP infrastructure to capture pharmaceutical biocatalysis demand. The supplier base stratifies around integrated biocatalysis packages versus unbundled enzyme-only procurement. Three archetypes occupy distinct positions: fermentation-scale incumbents with regulatory dossier depth, contract research specialists offering directed evolution services, and regional API manufacturers backward-integrating into captive enzyme supply. M&A activity and strategic technology licensing represent the dominant competitive vectors as players secure access to CRISPR-enabled engineering platforms.
Among established fermentation houses, Novozymes A/S and DSM exemplify the integrated biocatalysis archetype, anchoring positions through GMP documentation heritage and clinical-grade supply security. BASF SE occupies a position within the chemical-industrial complex, representing the pathway toward custom biocatalysis partnerships. These three entities illustrate how scale, regulatory preparation, and manufacturing scope differentiate competitive positioning in pharmaceutical-grade enzyme supply.
| Leading Market Players |
|---|
| Novozymes A/S |
| DSM |
| DuPont Danisco |
| BASF SE |
| Advanced Enzyme Technologies |
| Creative Enzymes |
| Specialty Enzymes & Probiotics |
| Amano Enzyme Inc. |
| AB Enzymes |
| Others |
Value Network & Pricing Analysis
Corn syrup futures and yeast extract spot markets cascade through esterase manufacturing tiers, compressing margins at commodity-grade suppliers while GMP-certified houses defend pricing power through REACH documentation premiums and FDA drug master file entrenchment.
Pricing Analysis
Distributor markups of 15-25 percent separate catalog industrial enzymes from pharmaceutical-grade formulations with regulatory dossiers. Three-tier pricing structure across GMP-certified, technical-grade, and bulk-industrial levels reflects fermentation scale and documentation depth. Cost compression in technical-grade segments is intensifying because Chinese fermentation capacity expansion floods spot markets. Agrochemical buyers exhibit highest price sensitivity, while oncology API manufacturers absorb premiums for thermostable variants.
Supply Chain Analysis
FDA process validation and REACH biodegradability certification gate entry for pharmaceutical-grade supply, freezing qualification timelines at 18-24 months. Manufacturing concentrates in Denmark, the Netherlands, and Germany for clinical-grade enzymes, while China anchors industrial-scale fermentation. Corn syrup, yeast extract, and specialty cofactors feed from agricultural commodity markets. Single-source vulnerability runs through Chinese specialty chemical intermediates for buffers and cofactors. Distribution runs through integrated biocatalysis packages from Novozymes and DSM, though contract manufacturers increasingly unbundle enzyme-only procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in esterase supply rests on CRISPR-enabled enzyme engineering collapsing development costs and pharmaceutical buyers accepting thermostable-variant premiums for continuous processing.
For Market Incumbents: Extend GMP fermentation capacity around Heidelberg and Jülich to capture EMA biocatalysis guidance demand before qualification timelines freeze supplier switching. Anchor regulatory dossier depth against CRISPR-engineered startup entrants by embedding quality-by-design into early-stage enzyme selection partnerships. Backward integration into corn syrup processing buffers agricultural commodity volatility. For New Entrants and Emerging Players: REACH in Europe opens a window for biodegradable-process documentation specialists to displace solvent-heavy chemical routes in generic API manufacturing. India's PLI scheme for active pharmaceuticals offers the most penetrable geography for localization partnerships with multinational biocatalyst suppliers. CRISPR-guided enzyme engineering services provide a direct go-to-market angle bypassing fermentation scale-up capital requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with directed-evolution platform operators possessing high-throughput screening infrastructure and pharmaceutical customer relationships. Five-to-ten year viability favors acquisition targets with thermostable-variant patent estates and existing FDA drug master files. Watch for EMA-FDA regulatory convergence on biocatalysis acceptance criteria as the inflection signal for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Fermentation Scale-Up | Heidelberg and Jülich capacity expansion captures EMA biocatalysis guidance demand. |
| CRISPR Platform Licensing | Directed evolution technology access collapses custom enzyme development timelines for API manufacturers. |
| Regulatory Dossier Acquisition | FDA drug master file portfolios freeze competitor entry through 18-24 month validation cycles. |
| India PLI Localization | Maharashtra and Gujarat manufacturing incentives open domestic enzyme supply for generic API producers. |
| Continuous Processing Partnerships | Immobilized enzyme system deployment stretches catalyst lifetime across multiple pharmaceutical reaction cycles. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation process engineers, pharmaceutical procurement leads, regulatory affairs specialists at EMA and FDA, and CDSCO alignment officers with secondary validation from FDA drug master file databases, REACH registration records, EMA marketing authorization submissions, and customs trade data for enzyme imports. Bottom-up fermentation capacity modeling and top-down pharmaceutical biocatalysis adoption curves were triangulated against industry association reports.
Segment-weighting applied product type, application, end user, and technology dimensions across the projection horizon, with carboxylesterase and lipase categories, pharmaceutical versus industrial applications, and enzymatic versus genetic engineering technology splits informing value allocation. CAGRs derived from fermentation capacity expansion timelines, regulatory filing velocity, and CRISPR-engineered variant commercialization curves. REACH solvent reduction mandates and FDA process validation timelines served as structural forecast inputs.
Revisions become necessary when EMA-FDA regulatory divergence on biocatalysis acceptance criteria materializes, when CRISPR-engineered variant patent litigation reshapes competitive access, or when Indian PLI scheme incentives accelerate domestic fermentation capacity beyond modeled uptake. A model refresh is warranted upon material change in corn syrup and yeast extract commodity price volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Cellulose Enzyme Market
Industrial Biotechnology
Xylanase Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
United States Biocatalyst Market
Industrial Biotechnology
Biocatalysis and Biocatalysts Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Haematococcus Pluvialis Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
North America Biocatalysts Market
Industrial Biotechnology
China Specialty Enzymes Market
Industrial Biotechnology
Global Specialty Enzymes Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Marine Enzymes Market
Industrial Biotechnology
Unnatural Amino Acids Market