
 Cellulose Enzyme Market | 2026-2036
Cellulose Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Enzyme Market Analytics
Buyer concentration among biofuel producers is repositioning procurement leverage toward large-scale ethanol operators. Novozymes A/S leverages its fermentation technology leadership to dominate commercial cellulase supply contracts. AB Enzymes GmbH anchors European demand through specialized formulations for pulp processing. Sunson Industry Group Co., Ltd competes on manufacturing scale out of Asia-Pacific production bases.
Cellulose enzymes are protein biocatalysts that hydrolyze beta-1,4-glycosidic bonds in cellulose, typically operating optimally at temperatures between 45°C and 65°C depending on the microbial source, and serve primarily to depolymerize lignocellulosic biomass into fermentable sugars or to modify fiber properties in industrial processing. Endoglucanases command the largest product-type volume as the foundational attack enzyme for random cellulose chain cleavage, while cellobiases capture expanding margin pools by eliminating product inhibition in complete cellulose hydrolysis systems. Biofuel Production leads application growth due to cellulosic ethanol mandates, whereas Paper & Pulp represents a mature, specification-intensive segment where enzyme substitution for chemical pulping drives incremental adoption.
EPA renewable fuel standards and the EU Green Deal sustainability criteria shape product qualification pathways for industrial cellulase suppliers seeking market access. BIS certification requirements in India and China's GB standards for feed additives create additional compliance layers for cross-border enzyme shipments. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and certification timelines.
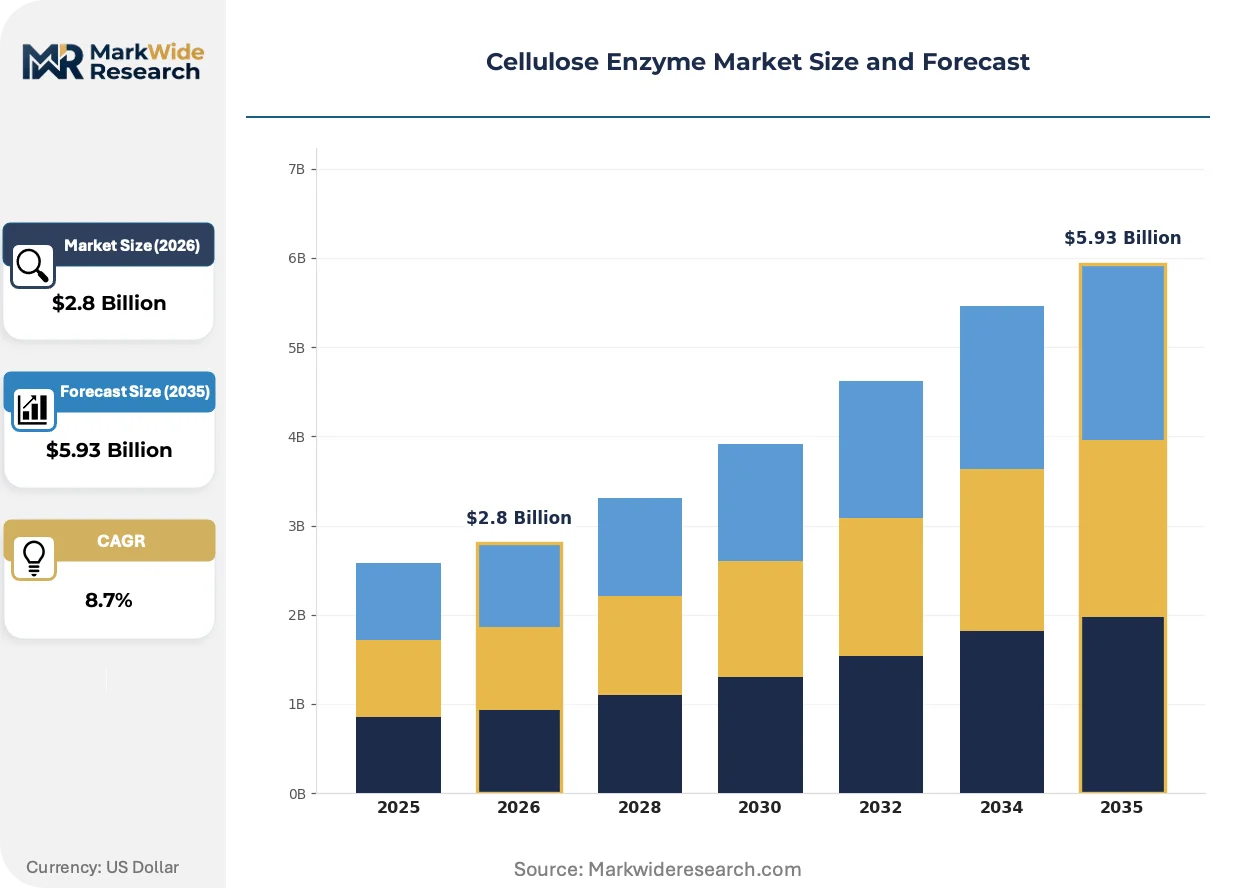
Market Dynamics
Buyer concentration among biofuel producers is concentrating procurement leverage toward large-scale ethanol operators, while REACH compliance and EU Green Deal sustainability criteria reshape product qualification pathways for industrial cellulase suppliers seeking market access.
Growth Catalysts
- Cellulosic Ethanol Mandates:EPA renewable fuel standards in the United States require escalating volumes of advanced biofuels, compelling ethanol producers to secure specialized cellulase formulations for lignocellulosic feedstock conversion.
- Pulp Processing Substitution:Paper and pulp manufacturers are accelerating enzyme substitution for chemical pulping processes, driven by mill-level sustainability targets and effluent reduction requirements.
- Sugarcane Bagasse Infrastructure:Brazil's expanding second-generation ethanol facilities draw specialized cellulase formulations optimized for tropical biomass processing conditions.
Market Restraints
- Fermentation Input Volatility:Industrial enzyme production depends on carbohydrate feedstocks and microbial strain stability, exposing manufacturers to agricultural commodity price swings and contamination risks.
- Supplier Concentration Risk:Commercial cellulase supply contracts cluster among fermentation technology leaders, creating dependency bottlenecks for buyers seeking alternative qualified suppliers.
- Product Inhibition Limitations:Incomplete cellulose hydrolysis systems face cellobiose accumulation constraints that degrade process efficiency without supplemental cellobiase enzyme cocktails.
Strategic Opportunities
- Indian BIS Certification Pathways:Cross-border enzyme shipments into India face expanding BIS certification requirements, creating first-mover advantages for suppliers completing compliance ahead of enforcement escalation.
- Feed Additive GB Standards:China's evolving national standards for feed additive enzymes open formulation opportunities for suppliers adapting cellulase products to animal nutrition specifications.
- Thermostable Enzyme Engineering:Protein engineering converging with synthetic biology enables cellulase variants operating above 65°C, reducing cooling costs in integrated biorefinery configurations.
Industry Challenges
- Reformulation Cost Burden:Regulatory divergence between EPA, REACH, and BIS jurisdictions forces parallel certification tracks, stretching R&D budgets and extending product launch timelines.
- Integration Complexity:Cellulase systems must interface with legacy pretreatment equipment and fermentation vessels, requiring process engineering expertise scarce among mid-scale biofuel operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Enzyme Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoglucanases, Exoglucanases, Cellobiases, Other Enzymes Application: Food & Beverage, Biofuel Production, Textile Industry, Paper & Pulp Deployment: On-premises, Cloud-based, Hybrid, Others End User: Agriculture, Pharmaceuticals, Detergency, Waste Management |
| Companies Covered | AB Enzymes GmbH, BIO-CAT, Inc., Novozymes A/S, Dyadic International Inc., Sunson Industry Group Co., Ltd, Genencor, Amano Enzyme Inc., Advanced Enzyme Technologies Ltd., Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Enzyme Market Evolving Landscape
Enzyme engineering and regulatory harmonization are actively reshaping competitive positioning in industrial biocatalyst supply, with consolidation pressures favoring integrated fermentation technology platforms over standalone formulation specialists.
Consolidated enzyme cocktails combining endoglucanases, exoglucanases, and cellobiases into single-product formats are consolidating procurement decisions for biofuel producers seeking simplified supply relationships. Novozymes A/S and AB Enzymes GmbH have advanced proprietary blend technologies that reduce the number of discrete SKUs required for complete cellulose hydrolysis. This consolidation is compressing margin pools for standalone specialty enzyme suppliers lacking integrated fermentation infrastructure.
REACH authorization requirements and EU Green Deal sustainability criteria are tightening specifications for industrial biocatalysts entering European markets. The European Chemicals Agency is expanding substance evaluation protocols for enzyme preparations, extending registration timelines and reformulation costs for non-compliant suppliers. Cellulosic ethanol facilities in the Netherlands and Finland are prioritizing pre-qualified enzyme sources to avoid production interruptions from regulatory non-conformity.
Long-term offtake agreements are displacing spot-market enzyme purchases among large-scale ethanol operators seeking supply security for multi-year facility deployments. Biofuel producers in Brazil and the United States are negotiating five-to-seven-year cellulase supply contracts with volume commitments and performance guarantees. This contracting pattern is visible most acutely in second-generation ethanol projects where enzyme costs represent a decisive fraction of operating expenditure.
Cellulose Enzyme Market Segmentation
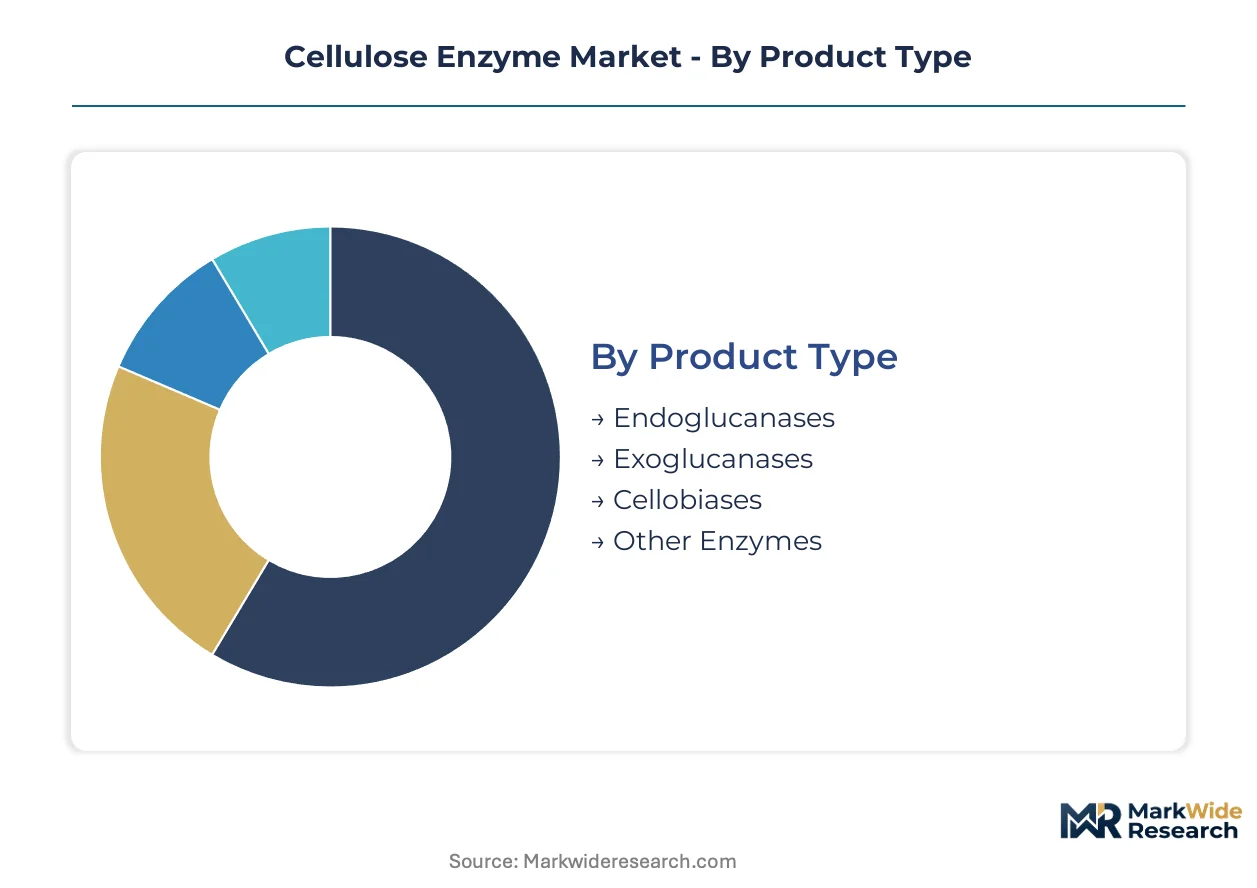
Procurement decisions in the cellulose enzyme market pivot on hydrolysis efficiency requirements and feedstock compatibility. Buyers prioritize enzyme cocktails that minimize cellobiose inhibition while integrating with existing pretreatment infrastructure.
Product Type:
Cost tier determines formulation complexity, with premium multi-enzyme cocktails commanding higher margins than single-component alternatives.
- Endoglucanases:These enzymes randomly cleave internal beta-1,4-glycosidic bonds in cellulose chains, initiating the depolymerization cascade. Demand concentrates among Brazilian sugarcane bagasse processors seeking foundational attack enzymes for tropical biomass. Novozymes A/S dominates supply contracts through fermentation scale advantages.
- Cellobiases:Beta-glucosidases hydrolyze cellobiose into glucose, eliminating product inhibition that stalls complete cellulose conversion. US cellulosic ethanol facilities under EPA renewable fuel standards prioritize these enzymes to maximize fermentable sugar yields. Protein engineering advances are expanding operational temperature ranges above 65°C.
- Exoglucanases:Processive enzymes cleave cellobiose units from cellulose chain ends, working synergistically with endoglucanases.
- Other Enzymes:Auxiliary enzymes including xylanases and lytic polysaccharide monooxygenases address hemicellulose components and crystalline cellulose disruption.
Endoglucanases lead on scale; cellobiases lead on momentum.
Application:
Volume concentration tracks regulatory mandate intensity, with biofuel quotas generating disproportionate procurement activity relative to mature industrial segments.
- Biofuel Production:Cellulosic ethanol facilities deploy cellulase cocktails to convert lignocellulosic feedstocks into fermentable sugars. EPA renewable fuel standards and EU Green Deal sustainability criteria shape enzyme qualification pathways. Long-term offtake agreements spanning five-to-seven years are displacing spot purchases among large-scale operators.
- Paper & Pulp:Mills substitute enzyme-based biopulping for chemical processes to meet effluent reduction targets and mill-level sustainability commitments. REACH authorization requirements and ECHA substance evaluation protocols tighten specifications for European market entry. AB Enzymes GmbH anchors regional supply through specialized formulations.
- Food & Beverage:Cellulases modify fiber properties in fruit juice clarification and bakery applications.
- Textile Industry:Enzymatic stone-washing and bio-polishing of cotton fabrics reduce water and chemical consumption.
Biofuel Production captures the steepest expansion trajectory; Paper & Pulp retains the largest installed base.
Deployment:
Supply concentration favors integrated fermentation platforms over standalone formulation specialists, compressing procurement options for buyers.
- On-premises:Dedicated enzyme production systems at biorefinery sites reduce logistics costs and cold-chain dependencies. Large-scale Brazilian ethanol operators favor captive supply to secure volume commitments for multi-year facility deployments.
- Hybrid:Blended models combine centralized fermentation with on-site formulation and storage. This approach dominates among mid-scale biofuel operators seeking supply security without full vertical integration.
- Cloud-based:Remote monitoring and predictive analytics optimize enzyme dosing rates in real-time.
- Others:Contract manufacturing arrangements and toll production agreements.
On-premises leads on scale; hybrid configurations lead on momentum.
End User:
Customer type dictates performance specifications, with pharmaceutical and agricultural applications imposing divergent purity and stability requirements.
- Agriculture:Feed additive applications leverage cellulases to improve fiber digestibility in ruminant and monogastric nutrition. China's evolving GB standards for feed additive enzymes create formulation opportunities for suppliers adapting products to animal nutrition specifications.
- Pharmaceuticals:High-purity cellulases support drug delivery systems and excipient modification. BIS certification requirements in India impose additional compliance layers for cross-border enzyme shipments into this segment.
- Detergency:Cellulases enhance fabric care and color brightening in laundry formulations.
- Waste Management:Enzymatic hydrolysis accelerates organic waste decomposition and biogas yield improvement.
Agriculture leads on scale; pharmaceuticals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's sugarcane bagasse processing infrastructure draws specialized cellulase formulations, while the United States channels procurement through EPA renewable fuel standards toward cellulosic ethanol expansion.
United States
Cellulosic ethanol facilities under EPA renewable fuel standards drive enzyme procurement for lignocellulosic feedstock conversion. The EPA mandates escalating volumes of advanced biofuels, compelling producers to secure long-term cellulase supply contracts. Iowa and Nebraska host concentrated biorefinery clusters where five-to-seven-year offtake agreements displace spot-market purchases.
Brazil
Sugarcane bagasse processing for second-generation ethanol creates tropical biomass-specific enzyme demand. ANVISA and environmental regulators enforce sustainability criteria for industrial biocatalyst imports. São Paulo state anchors production gravity with integrated ethanol-enzyme facilities scaling operations across the Center-South region.
Germany
Pulp processing substitution accelerates as mills target effluent reduction through enzyme-based biopulping. REACH authorization requirements and ECHA substance evaluation protocols tighten market entry specifications. The Ruhr industrial corridor and Bavarian paper clusters prioritize pre-qualified enzyme sources to avoid regulatory non-conformity interruptions.
China
Feed additive applications expand under evolving GB standards for animal nutrition enzyme specifications. The country's national industrial regulator enforces dual carbon goals that reshape biocatalyst qualification pathways. Shandong Province and the Yangtze River Delta concentrate manufacturing scale for domestic cellulase production.
India
Agricultural residue processing for biofuel and feed applications generates cellulase procurement activity. BIS certification requirements impose compliance layers for cross-border enzyme shipments, creating first-mover advantages for completed registrations. Maharashtra and Gujarat host emerging biorefinery deployments seeking supply security.
Cellulose Enzyme Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the cellulase supply base. Fermentation technology leaders dominate commercial contracts through integrated production platforms, while standalone formulation specialists face margin compression from consolidated enzyme cocktails. Three archetypes structure competition: integrated biotech conglomerates with captive fermentation infrastructure, regional specialists anchoring geographic demand pockets, and contract research organizations licensing engineered strain platforms. M&A activity concentrates procurement leverage among large-scale ethanol operators, while strategic partnerships between enzyme suppliers and pretreatment equipment vendors address integration complexity.
Within the integrated infrastructure tier, Novozymes A/S and AB Enzymes GmbH exemplify archetypes built on fermentation scale and regional formulation specialization respectively. Sunson Industry Group Co., Ltd occupies a position representing Asia-Pacific manufacturing scale advantages. These three anchors illustrate how supply-side concentration channels procurement decisions toward entities controlling upstream microbial strain development and downstream formulation capabilities.
| Leading Market Players |
|---|
| AB Enzymes GmbH |
| BIO-CAT, Inc. |
| Novozymes A/S |
| Dyadic International Inc. |
| Sunson Industry Group Co., Ltd |
| Genencor |
| Amano Enzyme Inc. |
| Advanced Enzyme Technologies Ltd. |
| Koninklijke DSM N.V. |
| Others |
Value Network & Pricing Analysis
Fermentation scientist concentration in Denmark and Germany widens pricing-tier spreads between premium cellulase cocktails and economy-grade alternatives, as labor-cost differentials compound with strain-development complexity to stratify contract values across integrated and standalone suppliers.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard-grade cellulase formulations, compressing margins for regional specialists lacking proprietary strain platforms. Contract-based long-term offtake dominates biofuel procurement, with price differentiation resting on certification grade and volume scale commitments. Cost compression in economy tiers is intensifying because Brazilian ethanol operators are consolidating procurement leverage. Small-scale pulp mills exhibit highest price sensitivity; pharmaceutical-grade buyers show least.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore anchor hub-and-spoke patterns for temperature-sensitive enzyme shipments. Supply concentrates in Denmark, Germany, and China, with fermentation capacity expansion in Shandong Province feeding Asian demand. Raw material dependencies center on carbohydrate feedstocks, microbial strain banks, and sterile filtration systems. Single-source vulnerability from concentrated fermentation technology leaders threatens buyer security. Distribution runs through cold-chain logistics networks with 2-8°C requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in cellulase supply rests on thermostable enzyme engineering reducing cooling costs, while premium-tier shifts toward consolidated multi-enzyme cocktails capture value from simplified procurement relationships.
For Market Incumbents: Anticipate protein engineering disruption from synthetic biology specialists by accelerating in-house strain development programs. Defensive consolidation of pretreatment equipment partnerships addresses integration complexity bottlenecks that stall competitor facility deployments. Backward integration into carbohydrate feedstock sourcing secures margin control against agricultural commodity volatility. For New Entrants and Emerging Players: Direct-to-biorefinery digital platforms offer low-friction entry routes for specialized cellobiase formulations targeting mid-scale Brazilian ethanol operators. White-space concentrates in Indian agricultural residue processing, where BIS certification gaps delay incumbent market entry. Technical service bundling with dosing optimization software differentiates against commodity suppliers. For Investors and Strategic Acquirers: Large-scale ethanol operators are the most active acquirer in this space, seeking captive enzyme supply for multi-year facility deployments. Long-term viability favors integrated fermentation platforms with proprietary strain libraries over standalone formulation specialists. Watch thermostable enzyme patent filings as inflection indicator for next-generation competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Biofuel producers lock in five-to-seven-year cellulase contracts with volume commitments and performance guarantees. |
| Backward Integration | Ethanol operators acquire fermentation capacity to secure supply security for tropical biomass processing facilities. |
| Green Manufacturing Transition | REACH authorization and EU Green Deal criteria reshape biocatalyst qualification pathways for European market access. |
| Joint Venture | Enzyme suppliers partner with pretreatment equipment vendors to address integration complexity in legacy biorefinery configurations. |
| Capacity Expansion | Fermentation scale advantages in Denmark and China consolidate procurement decisions toward integrated technology leaders. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combined with secondary validation. Interviews with fermentation technology directors, biofuel procurement managers, pulp mill sustainability officers, and enzyme formulation scientists anchored demand-side intelligence. Secondary sources included EPA renewable fuel standard filings, ECHA substance evaluation protocols, BIS certification registries, and customs trade data. Bottom-up facility deployment tracking and top-down regulatory mandate analysis provided triangulation.
Granularity-level modeling distinguished product-type performance tiers, application-specific qualification pathways, deployment-mode cost structures, and end-user purity requirements across the projection horizon. CAGRs derived from facility commissioning timelines, regulatory mandate escalation curves, and enzyme cost-per-liter learning effects. Forecast inputs incorporated cellulosic ethanol mandate trajectories and pulp processing substitution rates by regional cluster.
Regulatory enforcement delays, microbial strain contamination events, and feedstock price spikes are the dominant revision risks for cellulase demand projections. Forecasts reflect documented assumptions on mandate compliance timelines and technology adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Biotechnology
Redox Enzymes Market
Industrial Biotechnology
Global Protein Hydrolysis Enzymes Market
Industrial Biotechnology
White Biotech Market
Industrial Biotechnology
Lipase Enzymes Market
Industrial Biotechnology
Bio-Refinery Market
Industrial Biotechnology
Beta-Glucanase Market
Industrial Biotechnology
Protease Enzyme Market
Industrial Biotechnology
Japan Biocatalyst Market
Industrial Biotechnology
Fungal Amylase Market
Industrial Biotechnology
Protease Market
Industrial Biotechnology
Global Enzymes Market
Industrial Biotechnology
Industrial Enzymes Market
Industrial Biotechnology
Tannase Market
Industrial Biotechnology
Americas Enzymes Market
Industrial Biotechnology
Hydrolase Enzymes Market
Industrial Biotechnology
Global Specialty Enzymes Market