
 Bio-Based Phenol Market | 2026-2036
Bio-Based Phenol Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Phenol Market Outlook
Buyer concentration across resin and coatings formulators is rebalancing as mid-sized adhesive producers diversify feedstock sources. Braskem leverages its Brazilian sugarcane-derived aromatics platform to anchor supply security for European distributors. Dow competes through integrated biorefinery partnerships that extend its reach into pharmaceutical-grade phenol derivatives. GreenMantra Technologies specializes in catalytic upcycling of waste polystyrene into renewable phenolic streams, positioning the firm at the intersection of circularity and bio-aromatics.
Bio-based phenol denotes aromatic compounds synthesized from lignocellulosic biomass, agricultural residues, or microbial fermentation pathways rather than benzene-toluene-xylene cracking, typically achieving purity thresholds above 99.5% for industrial resin applications. The substance serves as a direct renewable substitute in bisphenol-A production, phenolic resin curing, and specialty chemical intermediates where petrochemical attribution carries regulatory or brand liability. Phenol and cresol dominate current volume flows, with alkylphenol representing the fastest-expanding category as lubricant additive formulators seek biodegradable alternatives. Fermentation technology leads commercial deployment, though catalytic conversion from lignin is gaining traction among biorefinery operators targeting co-product economics.
EPA bio-preferred procurement standards, EU REACH substance restrictions, and the EU Green Deal industrial emissions framework collectively elevate compliance costs for fossil-derived phenol while creating preferential market access for certified bio-based substitutes. FDA and EMA pharmaceutical excipient guidelines further tighten purity and traceability requirements, favoring producers with documented renewable feedstock chains. Stakeholders must monitor lignin supply scalability and fermentation yield improvements as the decisive variables for cost parity against naphtha-derived aromatics.
Market Dynamics
EU REACH substance restrictions and the EU Green Deal industrial emissions framework are forcing resin manufacturers to requalify supply chains around certified renewable aromatic feedstocks.
Growth Catalysts
- EU Green Deal industrial emissions framework:Chemical clusters in Germany face binding decarbonization timelines that favor bio-based phenol over naphtha-derived alternatives for epoxy curing agents.
- Lignin depolymerization:Biorefinery operators are scaling catalytic conversion pathways that transform forestry residues into high-purity phenolic streams for specialty chemical intermediates.
- Pharmaceutical excipient demand:FDA and EMA traceability requirements for drug formulations are pulling renewable phenol into active pharmaceutical ingredient synthesis.
Market Restraints
- Fermentation feedstock volatility:Brazilian sugarcane pricing swings directly compress margins for first-generation bio-aromatic producers dependent on sucrose-derived benzene substitutes.
- Purification capex thresholds:Achieving 99.5% purity for industrial resin applications requires distillation trains that mid-scale biorefineries cannot finance without offtake guarantees.
- Petrochemical substitution economics:Naphtha-cracked phenol from integrated refineries retains cost advantage in Asian markets lacking carbon border adjustment exposure.
Strategic Opportunities
- Alkylphenol lubricant additives:Biodegradable hydraulic fluid formulators in Scandinavia represent an underpenetrated demand pool for renewable cresol derivatives.
- Catalytic upcycling convergence:Waste polystyrene pyrolysis paired with hydrogenation is opening circular phenol supply chains independent of agricultural land use.
- US bio-preferred procurement:EPA federal purchasing mandates are creating preferential channel access for certified bio-based phenol in coatings for government infrastructure.
Industry Challenges
- Bioprocess engineering talent scarcity:Fermentation scale-up expertise concentrates among a limited pool of specialists with experience in aromatic metabolite recovery.
- REACH registration timelines:Novel bio-based phenol variants face multi-year substance evaluation periods that delay commercial deployment in EU formulated products.
- Lignin supply standardization:Variability in softwood versus hardwood lignin composition complicates catalyst selection and yield optimization across biorefinery sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Phenol Market |
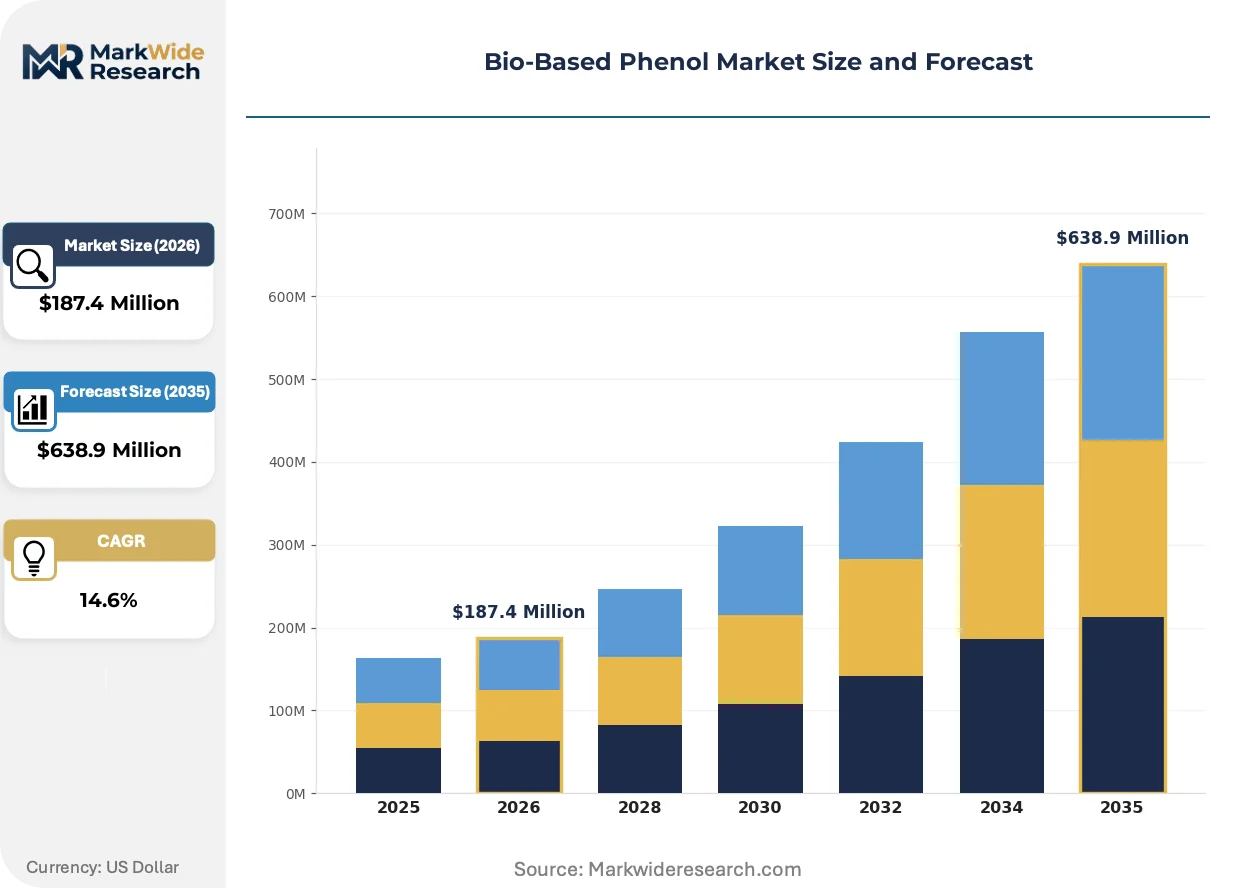
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenol, Cresol, Alkylphenol, Polyphenol Technology: Fermentation, Catalytic Conversion, Biorefinery, Fractionation End User: Plastics, Resins, Adhesives, Coatings Application: Pharmaceuticals, Cosmetics, Agriculture, Food Industry |
| Companies Covered | BioAmber, Ashland, Dow, Arkema Group, Circa Group, Braskem, SABIC, GreenMantra Technologies, BioBased Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Phenol Market Strategic Shifts
Technology maturation in lignin valorization and tightening pharmaceutical purity standards are compressing the viable pathway options for renewable aromatic production.
Catalytic hydrotreatment of lignin-derived pyrolysis oils is consolidating as the dominant thermochemical route for bio-based phenol manufacturing. Specialty resin formulators in the Netherlands and Finland are adopting this technology ahead of commodity chemical producers. The process is consolidating control over feedstock flexibility among biorefinery operators with integrated forestry assets.
REACH authorization requirements for Substances of Very High Concern are tightening traceability mandates across bisphenol-A supply chains. Chemical manufacturers must now document renewable content percentages through mass-balance certification to maintain market access. European epoxy producers are responding by locking in long-term offtake agreements with fermentation-based phenol suppliers.
Brand-owners in consumer electronics and automotive coatings are inserting renewable content clauses into supplier contracts that were previously price-only arrangements. Procurement teams at German and Japanese OEMs now require third-party bio-based certification for phenolic resin components. This contractual evolution is most visible in electric vehicle battery housing applications where carbon footprint disclosure carries regulatory weight.
Bio-Based Phenol Market Segmentation
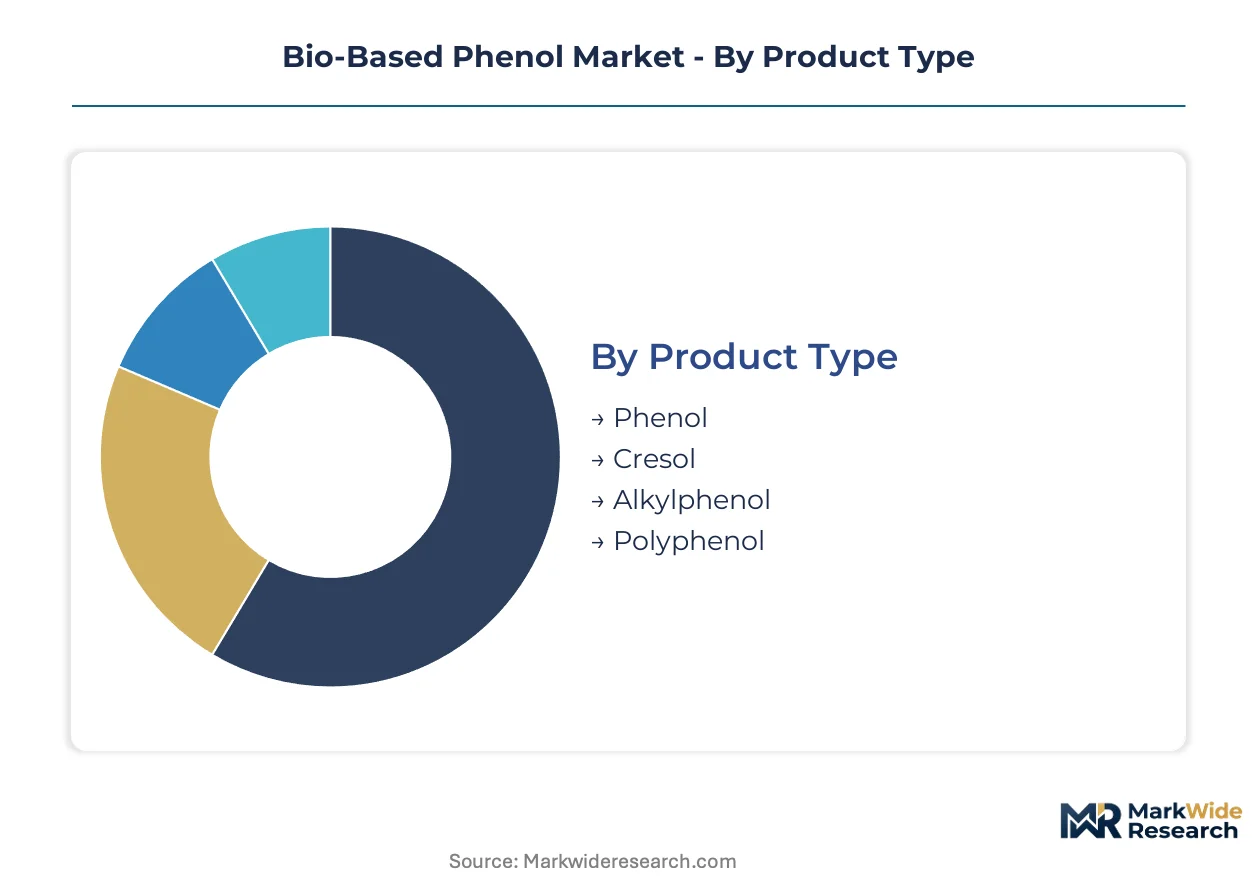
Segmentation in bio-based phenol reveals where capital deployment and regulatory pressure intersect. Product purity thresholds, technology maturity, and end-use certification requirements create divergent investment profiles across the value chain.
Product Type:
Capital intensity peaks with alkylphenol production due to multi-stage hydrogenation and alkylation units required for lubricant-grade specifications.
- Phenol:Achieves 99.5% purity through distillation trains serving epoxy resin formulators. German chemical clusters in Ludwigshafen and Leverkusen anchor procurement volumes as REACH compliance tightens on petrochemical alternatives.
- Alkylphenol:Requires hydrogenation reactors and alkylation catalysts for biodegradable lubricant additive production. Scandinavian hydraulic fluid formulators in Sweden and Finland represent the steepest demand expansion as marine sector regulations tighten.
- Cresol:Three isomer variants (ortho, meta, para) serve disinfectant and antioxidant markets with moderate purification capex.
- Polyphenol:High-molecular-weight extracts target nutraceutical and cosmetic applications with batch processing economics.
Most installed capacity flows through phenol. Expansion is steepest in alkylphenol.
Technology:
Process selection determines feedstock flexibility and co-product revenue potential for biorefinery operators.
- Fermentation:Microbial aromatic metabolite production from sucrose or lignocellulosic sugars dominates commercial deployment. Brazilian sugarcane mills and European wheat straw processors in France and Belgium operate the largest installed bases.
- Catalytic Conversion:Lignin depolymerization with hydrotreatment catalysts yields phenolic streams for specialty chemical intermediates. Finnish and Dutch biorefineries with integrated forestry assets are scaling this pathway fastest.
- Biorefinery:Integrated sugar-to-aromatics platforms co-produce ethanol, biochemicals, and renewable phenol from agricultural residues.
- Fractionation:Pyrolysis oil separation into phenolic fractions serves smaller-scale producers with lower capital barriers.
Fermentation holds the dominant capacity share. Catalytic conversion is climbing the fastest as lignin valorization technology matures.
End User:
Customer concentration and contract structures vary sharply across formulation industries.
- Resins:Phenolic and epoxy curing agents require mass-balance certification for EU automotive and electronics supply chains. German OEM procurement teams now mandate renewable content clauses in multi-year offtake agreements.
- Plastics:Bisphenol-A synthesis for polycarbonate faces pharmaceutical-grade traceability requirements from FDA and EMA guidelines.
- Adhesives:Mid-sized formulators diversify feedstock sources as petrochemical attribution carries brand liability in consumer goods.
- Coatings:Industrial and automotive applications drive specification tightening around carbon footprint disclosure.
Resins command the largest volume flows. Plastics are gaining share fastest on pharmaceutical and electronics demand.
Application:
Regulatory purity mandates and pricing power diverge across end-markets.
- Pharmaceuticals:Active pharmaceutical ingredient synthesis and excipient production demand documented renewable feedstock chains under FDA and EMA traceability protocols. Swiss and German contract manufacturers lead qualification efforts.
- Cosmetics:Natural positioning and preservative applications in premium skincare command margin premiums over industrial grades.
- Agriculture:Pesticide intermediates and biocide formulations face less stringent purity requirements than pharmaceutical applications.
- Food Industry:Antioxidant and packaging applications require food-contact compliance that limits viable supply sources.
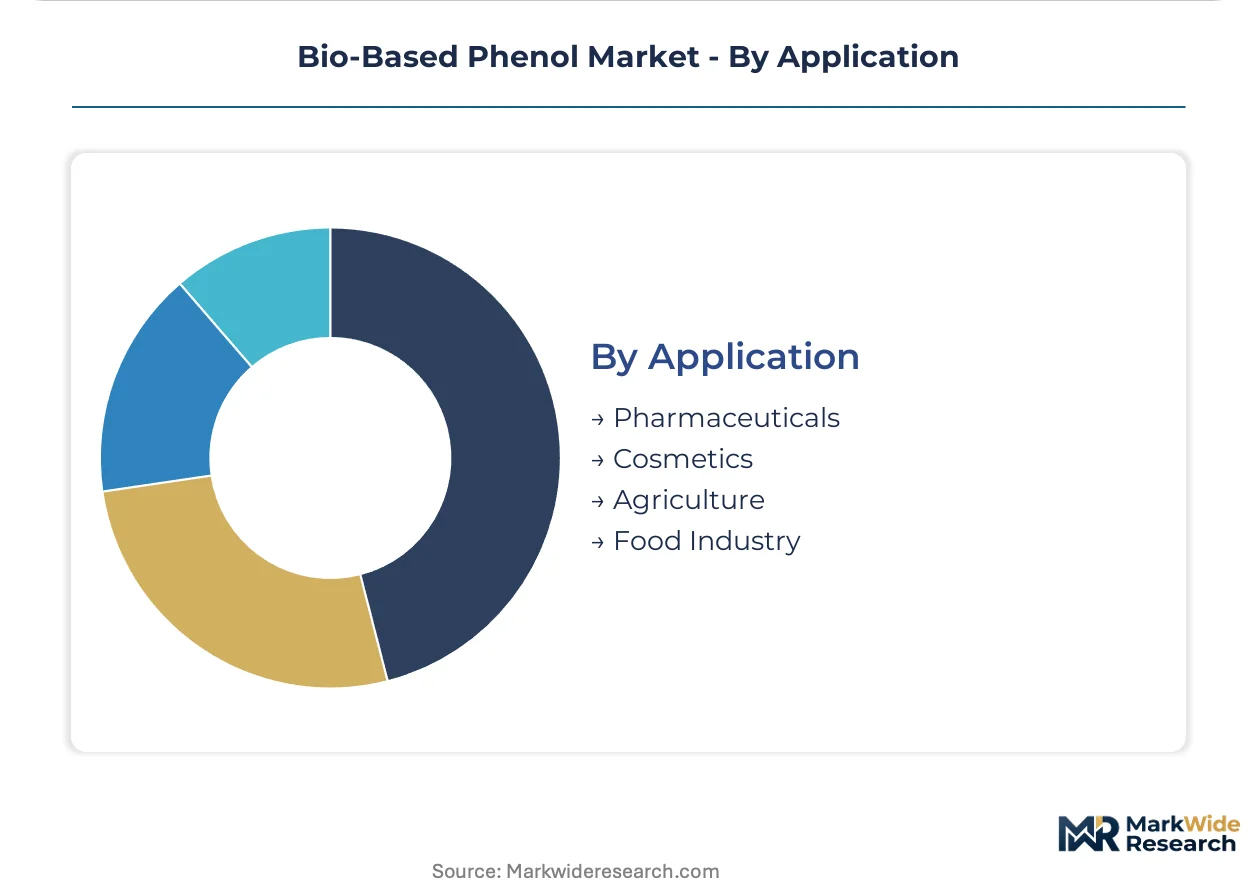
Pharmaceuticals absorb the highest-value volumes. Cosmetics are expanding most quickly on clean-label positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Brazil operate divergent bio-based phenol supply models. German chemical clusters prioritize lignin valorization from integrated forestry assets. Brazilian producers leverage established sugarcane fermentation infrastructure for aromatic metabolite recovery.
Germany
REACH authorization timelines for Substances of Very High Concern drive epoxy resin formulators toward certified renewable feedstocks. The EU Green Deal industrial emissions framework imposes binding decarbonization schedules on Ludwigshafen and Leverkusen chemical parks. Braskem anchors European distribution through long-term offtake agreements with German OEM procurement teams.
United States
EPA bio-preferred procurement standards create preferential channel access for federal infrastructure coatings. GreenMantra Technologies exemplifies the catalytic upcycling archetype with waste polystyrene-to-phenol pathways. Dow maintains integrated biorefinery partnerships extending into pharmaceutical-grade phenol derivatives.
Brazil
Sugarcane pricing volatility directly compresses margins for first-generation bio-aromatic producers. The national biofuel policy framework supports sucrose-derived benzene substitutes through established mill infrastructure. Braskem leverages its domestic sugarcane-derived aromatics platform to supply European resin manufacturers.
Finland
Scandinavian hydraulic fluid formulators in Sweden and Finland represent accelerating demand for biodegradable alkylphenol lubricant additives. National forestry policy incentivizes lignin depolymerization at integrated biorefinery sites. Finnish operators with captive forestry assets are scaling catalytic hydrotreatment faster than commodity chemical producers.
Netherlands
Specialty resin formulators adopt lignin valorization technology ahead of volume chemical producers. The national chemical sector transition program accelerates renewable aromatic qualification. Rotterdam-area biorefineries with pyrolysis oil separation capabilities serve smaller-scale phenolic fraction producers.
Bio-Based Phenol Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology platforms and feedstock strategies. Market structure tilts toward consolidation among fermentation-based producers with integrated agricultural assets, while catalytic conversion remains fragmented among regional biorefinery operators. Three archetypes dominate: Brazilian sugarcane-integrated fermentation platforms, European lignin-valorization biorefineries, and North American waste-to-aromatics upcyclers. Capacity expansion and strategic partnerships constitute the primary competitive moves, with offtake guarantees from German automotive OEMs determining financing access for purification infrastructure.
Among diversified chemical conglomerates, Dow and SABIC occupy positions spanning multiple renewable aromatic value chains. Braskem anchors the sugarcane-integrated fermentation tier with its established Brazilian platform. GreenMantra Technologies exemplifies the waste-to-aromatics specialist archetype through catalytic upcycling approaches. These three companies represent the dominant geographic and technological vectors shaping supply security for European resin formulators.
| Leading Market Players |
|---|
| BioAmber |
| Ashland |
| Dow |
| Arkema Group |
| Circa Group |
| Braskem |
| SABIC |
| GreenMantra Technologies |
| BioBased Technologies |
| Others |
Value Chain & Pricing Dynamics
Premium-mid-economy pricing differentiation between pharmaceutical-grade and industrial resin grades manifests in divergent supply chain configurations across the bio-based phenol value chain. German chemical clusters absorb 99.5% purity material at contracted premiums under REACH-mandated mass-balance certification, while Asian coating formulators source lower-specification phenol through spot markets tethered to naphtha price benchmarks.
Pricing Analysis
Capacity additions in Finland and the Netherlands are reshaping price floors for lignin-derived phenolic streams as biorefinery operators achieve scale economies. Contract-based long-term offtake agreements dominate German automotive procurement, with price differentiation driven by certification tier (ISCC PLUS mass-balance) and volume scale. Cost compression in fermentation-based supply runs through Brazilian sucrose-dependent producers as sugarcane pricing volatility intensifies. Mid-sized adhesive formulators exhibit highest price sensitivity, while Swiss pharmaceutical contract manufacturers absorb premiums for documented renewable feedstock chains.
Supply Chain Analysis
Single-source vulnerability sits with Brazilian sugarcane mills for first-generation fermentation capacity, while European lignin valorization remains fragmented among Finnish and Dutch biorefinery operators. Raw material dependencies center on softwood forestry residues, wheat straw lignocellulosic feedstock, and catalytic hydrotreatment catalysts. Tariff exposure through EU carbon border adjustment mechanisms threatens Asian naphtha-derived phenol imports. Distribution runs through integrated chemical clusters in Ludwigshafen and Leverkusen for German resin formulators, with Rotterdam serving smaller-scale phenolic fraction traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based phenol has entered a late-cycle quality phase where pharmaceutical-grade specifications command structural premiums over industrial resin grades. German and Japanese OEM procurement teams now mandate renewable content clauses that were absent three years ago.
For Market Incumbents: Anticipate margin compression from catalytic upcycling entrants by locking long-term offtake agreements with Scandinavian hydraulic fluid formulators before alkylphenol capacity saturates. Braskem's sugarcane-integrated platform demonstrates how backward integration into agricultural assets defends feedstock security against Brazilian pricing volatility. Certification investment in ISCC PLUS mass-balance documentation represents the critical lever for maintaining EU automotive channel access. For New Entrants and Emerging Players: A 40-60% price-point gap between pharmaceutical-grade and industrial resin tiers opens white-space targeting at mid-purity specifications for European coatings formulators. Underpenetrated demand pools concentrate among biodegradable lubricant additive producers in Sweden and Finland seeking renewable cresol derivatives. Catalytic conversion from lignin offers the most penetrable technology entry point for forestry-integrated biorefinery operators without fermentation scale-up expertise. For Investors and Strategic Acquirers: Consolidation pressure builds where purification capex thresholds exceed mid-scale biorefinery financing capacity without German OEM offtake guarantees. Long-term viability favors acquisition targets with captive forestry assets and demonstrated 99.5% purity distillation capability. The decisive inflection signal to watch is lignin supply standardization progress that enables catalyst selection consistency across softwood and hardwood feedstocks.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | German OEM procurement teams now mandate renewable content clauses in multi-year epoxy resin contracts. |
| Backward Integration | Finnish biorefinery operators with captive forestry assets achieve superior lignin valorization economics. |
| Capacity Expansion | Dutch specialty resin formulators scale catalytic hydrotreatment faster than commodity chemical producers. |
| Green Manufacturing Transition | REACH authorization timelines force requalification around certified renewable aromatic feedstocks. |
| Joint Venture | Integrated sugar-to-aromatics platforms co-produce ethanol and biochemicals alongside renewable phenol. |
Study Parameters
Bottom-up resin and coatings modeling reconciled against top-down biorefinery capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German chemical clusters, procurement leads at automotive OEMs, distribution channel partners in Rotterdam, and technical R&D directors at fermentation operators combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings, and EU ETS emissions disclosures. Triangulation between demand-side qualification timelines and supply-side technology maturation curves ensured segmentation coherence.
Historical trendline analysis of lignin valorization yield improvements and fermentation aromatic metabolite recovery rates informed projection assumptions across the analysis window. Segmentation dimensions modeled include product purity tier, technology pathway, end-use industry, and regional production hub. CAGRs were derived from installed capacity buildout schedules cross-referenced with REACH compliance deadline clustering and FDA pharmaceutical excipient qualification timelines.
Caveats apply where Brazilian sugarcane pricing volatility, lignin supply standardization delays, or REACH substance evaluation timeline extensions could materially shift the outlook. Forecasts reflect documented assumptions about bioprocess engineering talent availability and catalyst performance consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Fatliquoring Agents Market
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Glucosinolates Market
Specialty Chemicals
Catharanthine Market
Specialty Chemicals
2-(2,2,2-Trifluoroethoxy)-1,3,2-Dioxaphospholane-2-Oxide Market
Specialty Chemicals
Fluorotelomers Market
Specialty Chemicals
UV Filters Market
Specialty Chemicals
Specialty Chemicals Market
Specialty Chemicals
Monoaluminum Phosphate Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Global Mandelic Acid Market