
 Cellulose Acetate Phthalate Market | 2026-2036
Cellulose Acetate Phthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Cellulose Acetate Phthalate Market Outlook
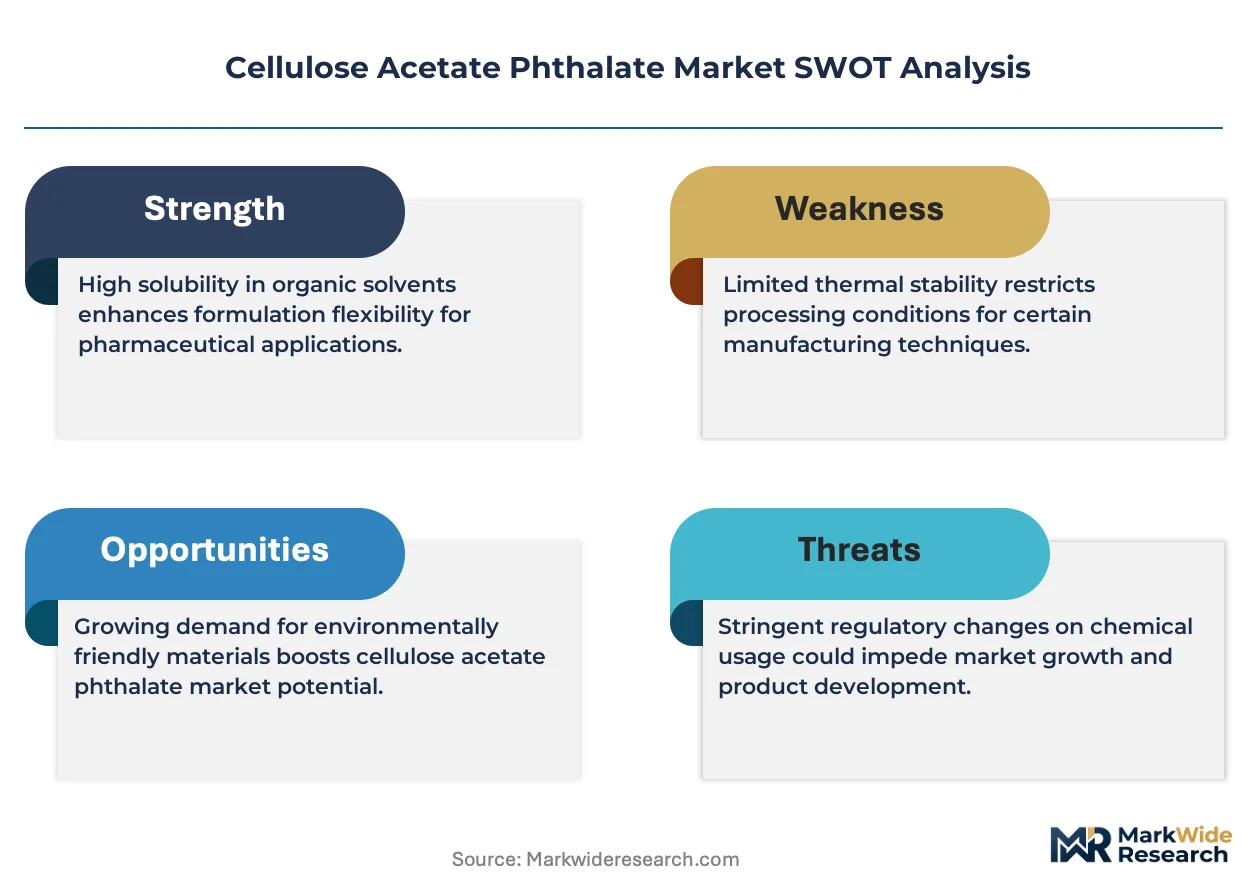
East Asian cellulose acetate supply chains are restructuring around pharmaceutical-grade purification standards. Daicel Corporation leverages its captive acetic acid and cellulose sourcing to sustain margin control across acetate ester derivatives. Eastman Chemical Company anchors North American supply through integrated Kingsport manufacturing, while Solvay SA competes on European regulatory dossier depth for excipient compliance.
Cellulose acetate phthalate is a partially acetylated cellulose polymer esterified with phthalic anhydride, yielding a free carboxyl content of 30-36% that dissolves above pH 5.5 for intestinal targeting in oral drug delivery. The material functions primarily as an enteric coating agent protecting acid-labile APIs from gastric degradation while permitting release in the duodenum. Powder and granule formats dominate current pharmaceutical procurement, with film-grade pellets representing the fastest-expanding margin pool as continuous manufacturing lines displace batch pan coating. Solvent coating technology still occupies the majority of installed capacity, though hot melt extrusion is displacing organic solvent processes under EHS pressure.
FDA's Inactive Ingredient Database and EMA's excipient master file requirements shape formulation selection and supplier qualification timelines for cellulose acetate phthalate. REACH phthalate restrictions and USP-NF monograph updates on residual solvents enforce continuous analytical investment across producer labs. Stakeholders must monitor evolving regulatory divergence between FDA dissolution acceptance criteria and EMA's evolving quality-by-design expectations for modified-release coatings.
Market Dynamics
Continuous manufacturing adoption across oral solid dosage production is compressing batch cycle times and forcing enteric coating polymer suppliers to deliver pelletized, flow-ready formats that integrate directly into twin-screw extrusion lines.
Growth Catalysts
- Delayed-release dissolution guidance:FDA's updated dissolution acceptance criteria for enteric-coated products is accelerating substitution toward phthalate-based cellulose derivatives with proven pH-triggered release profiles.
- India's pharmaceutical manufacturing scale-up:Domestic formulation capacity and CDMO infrastructure expansion is concentrating procurement demand for excipient-grade cellulose acetate phthalate.
- Hot melt extrusion technology:EHS-driven solvent reduction mandates are pulling coating processes toward melt-based application systems compatible with engineered polymer pellets.
Market Restraints
- Acetic acid feedstock volatility:Purified cellulose and acetic anhydride input costs fluctuate with energy pricing and agricultural commodity cycles, compressing margin predictability for esterification producers.
- East Asian supply concentration:Pharmaceutical-grade purification capacity clusters in Japan and China, creating geographic vulnerability to logistics disruptions and trade policy friction.
- REACH phthalate restrictions:ECHA's evolving classification of phthalate esters creates regulatory uncertainty for European formulation customers evaluating long-term excipient commitments.
Strategic Opportunities
- Brazilian generic pharmaceutical expansion:ANVISA's accelerated approval pathways for complex generics is opening demand for imported enteric coating polymers among local formulation houses.
- Biologic oral delivery formats:Acid-labile peptide and protein formulations requiring intestinal protection represent an emerging application segment beyond traditional small-molecule coatings.
- Continuous manufacturing integration:Film-grade pellet formats engineered for direct feeding into hot melt extrusion lines command premium positioning against conventional powder supply.
Industry Challenges
- Excipient master file compilation:EMA's quality-by-design documentation requirements and FDA's Inactive Ingredient Database submissions demand specialized regulatory affairs capacity that mid-tier polymer suppliers struggle to staff.
- Analytical method transfer:USP-NF residual solvent testing protocols and dissolution apparatus qualification create certification bottlenecks during supplier qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellulose Acetate Phthalate Market |
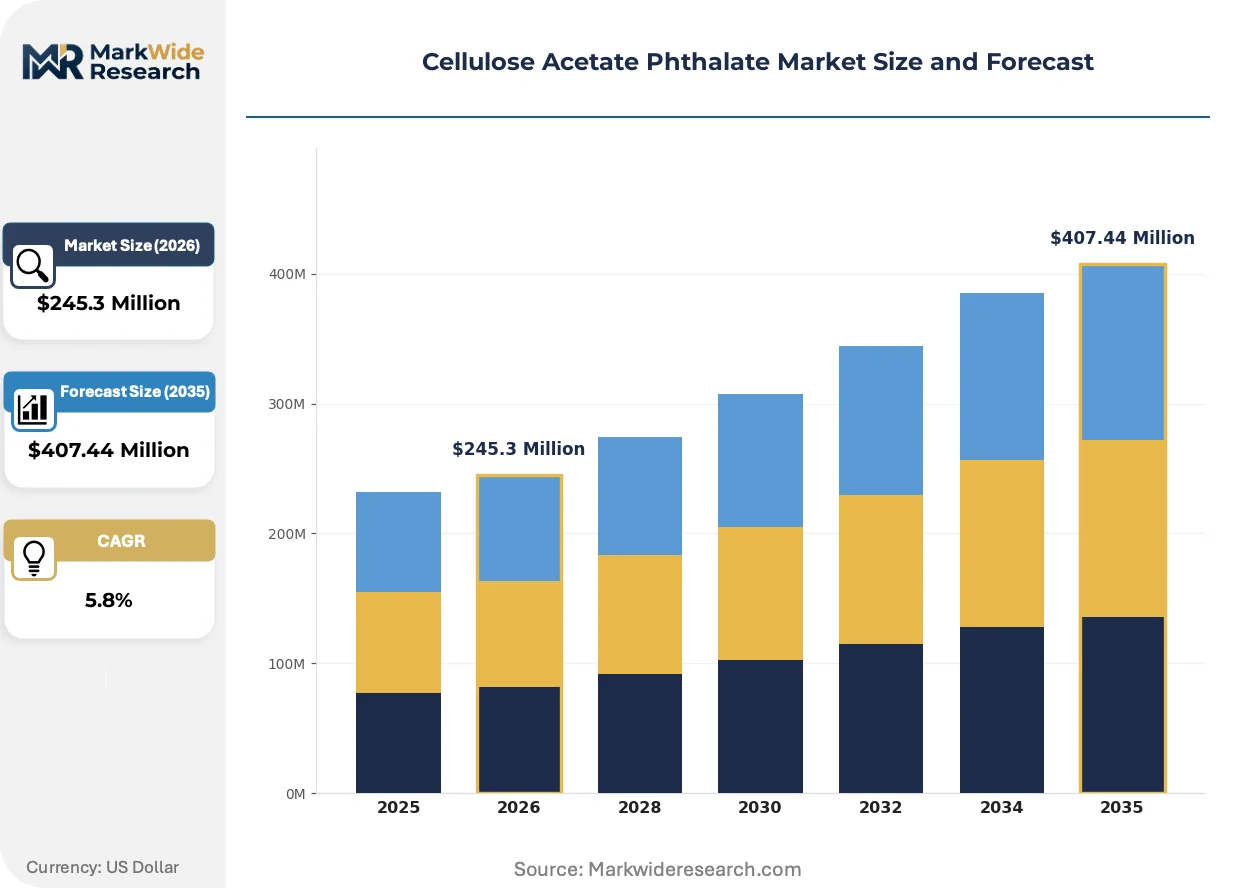
| Market Size in 2026 | $245.3 Million |
| Market Size in 2035 | $407.44 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Pellets, Films Application: Coatings, Film Coating, Drug Delivery, Pharmaceutical Use End User: Pharmaceutical Companies, Research Laboratories, Cosmetics Industry, Food Industry Technology: Solvent Coating, Spray Drying, Hot Melt Extrusion, Electrospray |
| Companies Covered | Daicel Corporation, China National Tobacco Corporation, Eastman Chemical Company, Mitsubishi Chemical Holdings Corporation, Sichuan Push Acetati LLC, Solvay SA, Celanese Corporation, Rayonier Advanced Materials Inc., Sappi Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellulose Acetate Phthalate Market Strategic Shifts
Process intensification and regulatory harmonization pressures are simultaneously reshaping coating technology selection and supplier qualification protocols across pharmaceutical manufacturing networks.
Hot melt extrusion is converging with precision pelletization to produce flow-engineered cellulose acetate phthalate granules that eliminate solvent handling entirely. Oral solid dosage manufacturers adopting continuous processing lines are specifying these formats to achieve steady-state coating uniformity. This convergence is compressing demand for traditional solvent-based coating systems and the infrastructure they require.
REACH phthalate restriction proposals are forcing European formulators to re-evaluate long-term excipient strategies ahead of potential reclassification. Industrial consequence includes accelerated dossier preparation for alternative polymers and defensive stockpiling of regulatory-compliant cellulose derivatives. Modified-release coating segments serving European export markets are most affected, with manufacturers dual-sourcing to mitigate approval timeline risk.
Specification-driven procurement is consolidating buyer power among top-tier pharmaceutical companies with dedicated excipient qualification teams. Direct supplier relationships are displacing distributor intermediaries for volume cellulose acetate phthalate contracts. This pattern is most visible in India, where domestic formulation leaders are building captive excipient testing laboratories to compress vendor onboarding cycles.
Cellulose Acetate Phthalate Market Segmentation
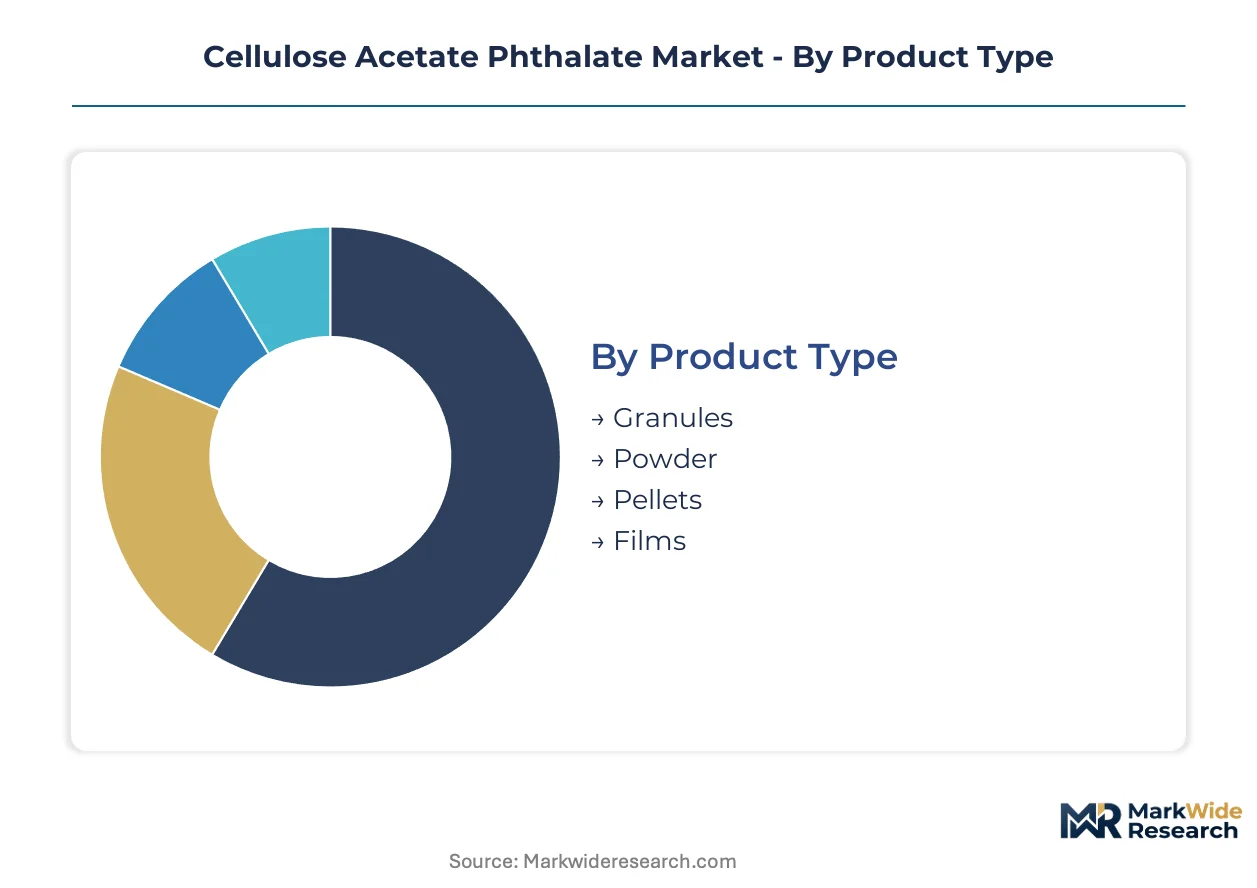
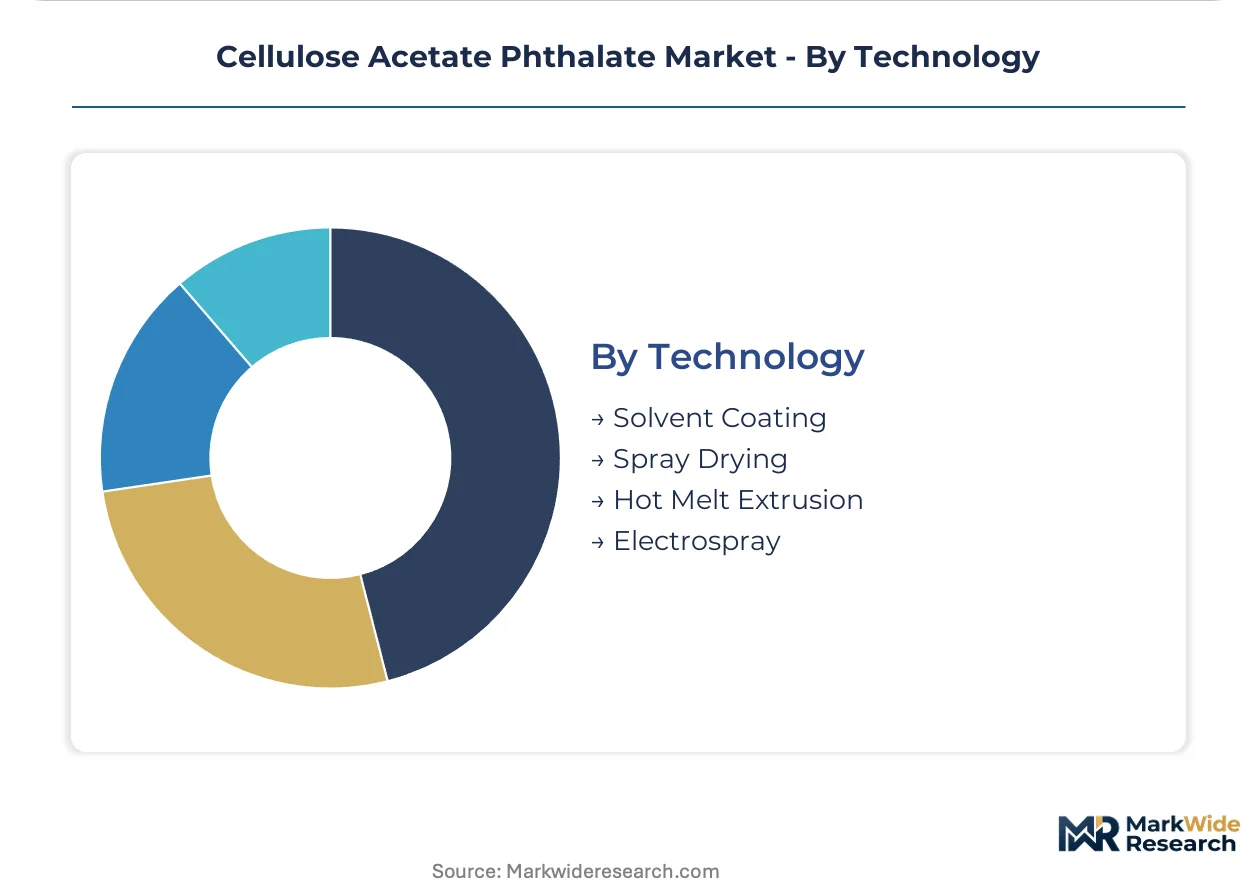
Cellulose acetate phthalate procurement patterns diverge sharply across physical formats and coating technologies. Pharmaceutical manufacturers select product types and application methods based on equipment compatibility, regulatory compliance burdens, and solvent handling constraints.
Product Type:
Format selection tracks the upgrade cycle from legacy batch coating toward continuous manufacturing lines, with flow properties and dissolution kinetics driving substitution decisions.
- Powder:Fine-milled cellulose acetate phthalate with particle sizes optimized for traditional pan coating dissolution. Demand concentrates among Indian generic manufacturers operating solvent-based batch lines where powder reconstitution fits existing equipment footprints.
- Pellets:Precision-engineered spherical granules engineered for direct feeding into twin-screw extrusion systems. European formulation houses adopting hot melt extrusion specify these formats to eliminate solvent recovery infrastructure and compress cycle times.
- Granules:Intermediate particle size distribution offering compromise flow characteristics for hybrid coating operations.
- Films:Pre-cast enteric membranes for specialized osmotic pump and multilayer tablet architectures.
Powder sits at the top of the volume ranking, with pellets climbing the fastest.
Application:
Cost tier differentiation separates commodity enteric protection from high-value modified-release engineering.
- Coatings:Conventional enteric coating for acid-labile API protection represents the baseline application segment. Indian and Brazilian generic manufacturers drive procurement volume for standard dissolution-triggered release profiles.
- Film Coating:Thin, uniform enteric layers applied to tablet cores for aesthetic and functional finishing. Demand clusters among North American specialty pharmaceutical companies seeking EMA-compliant dossiers for European export markets.
- Drug Delivery:Advanced intestinal targeting systems incorporating pH-sensitive polymers into complex multilayer or multiparticulate architectures.
- Pharmaceutical Use:Broad excipient category encompassing compounding and investigational formulation activities.
Coatings command the largest revenue pool, while film coating gains share fastest among quality-by-design adopters.
End User:
Customer type determines specification stringency and qualification timeline intensity.
- Pharmaceutical Companies:Integrated formulation operations with captive excipient testing laboratories and direct supplier relationships. These buyers specify pharmaceutical-grade cellulose acetate phthalate with full regulatory dossier support for FDA and EMA submissions.
- Research Laboratories:Investigational drug development operations requiring small-batch, high-purity polymer supply with flexible minimum order quantities.
- Cosmetics Industry:Niche enteric applications for oral beauty supplements and probiotic encapsulation.
- Food Industry:Limited food-grade applications constrained by phthalate regulatory scrutiny in major markets.
Pharmaceutical companies dominate procurement volume, with research laboratories expanding most quickly on biologic oral delivery investments.
Technology:
Process maturity curves separate established solvent systems from emerging melt-based alternatives.
- Solvent Coating:Organic solvent dissolution and spray application onto tablet cores in perforated pan systems. This technology occupies the majority of installed capacity globally, though EHS compliance costs are accelerating replacement cycles.
- Hot Melt Extrusion:Thermoplastic processing of polymer-active blends without solvent handling. European manufacturers facing REACH solvent restrictions and EPA-aligned EHS mandates are converting coating lines to this technology.
- Spray Drying:Aqueous or solvent-based polymer atomization for microparticle generation.
- Electrospray:Emerging electrohydrodynamic atomization for nanoscale coating precision in specialized delivery systems.
Solvent coating retains the largest installed base, with hot melt extrusion posting the steepest expansion trajectory on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cellulose acetate phthalate production geography as compliance-cost gaps between jurisdictions widen. Manufacturers are relocating pharmaceutical-grade purification capacity toward markets with streamlined excipient approval pathways and lower environmental enforcement burdens.
United States
FDA's updated dissolution acceptance criteria for delayed-release formulations is accelerating domestic procurement of phthalate-based cellulose derivatives. The agency's Inactive Ingredient Database requirements shape supplier qualification timelines for oral solid dosage manufacturers. Eastman Chemical Company's integrated Kingsport manufacturing anchors North American supply with captive acetic acid sourcing.
India
Domestic pharmaceutical production and CDMO infrastructure expansion is concentrating procurement demand for excipient-grade cellulose acetate phthalate. CDSCO's streamlined excipient approval pathways under the PLI scheme for active pharmaceutical ingredients reduce regulatory friction for imported polymer supply. Mumbai-Pune and Hyderabad clusters host formulation houses building captive excipient testing laboratories to compress vendor onboarding cycles.
Germany
EMA's quality-by-design documentation requirements and evolving REACH phthalate restrictions create dual pressure on European formulators. ECHA's classification uncertainty around phthalate esters is forcing defensive stockpiling of regulatory-compliant cellulose derivatives. Frankfurt-Rhine-Main pharmaceutical corridor manufacturers are dual-sourcing enteric coating polymers to mitigate approval timeline risk for export markets.
Japan
PMDA's stringent pharmaceutical-grade purity standards sustain premium positioning for domestic acetate ester producers. METI's industrial policy supports captive cellulose and acetic acid integration for margin control across specialty chemical derivatives. Osaka-Kobe chemical manufacturing belt hosts producers leveraging backward integration into forestry-derived cellulose feedstocks.
Brazil
ANVISA's accelerated approval pathways for complex generics is opening demand for imported enteric coating polymers among local formulation houses. The regulator's harmonization with FDA dissolution standards reduces technical barriers for phthalate-based cellulose derivative adoption. São Paulo state's generic pharmaceutical manufacturing cluster represents the primary demand concentration for excipient procurement.
Cellulose Acetate Phthalate Market Competitive Environment
East Asian producers anchor the integrated-tier supply base; European specialists hold regulatory-dossier positioning. The vendor structure concentrates around cellulose acetate manufacturers with backward integration into forestry feedstocks and acetic acid supply. Three archetypes dominate: integrated chemical conglomerates with captive raw material access, pharmaceutical-grade purification specialists with EMA/FDA master file depth, and regional acetate ester fabricators serving generic formulation markets. Capacity expansion and regulatory dossier compilation represent the dominant competitive moves as qualification timelines extend.
Within the integrated-tier archetype, Daicel Corporation and Eastman Chemical Company exemplify producers with captive cellulose and acetic acid sourcing that sustains margin control across acetate ester derivatives. Solvay SA occupies a position among European specialists competing on regulatory dossier depth for excipient compliance. These three anchors represent distinct geographic and strategic positioning vectors—Japanese integrated chemical production, North American vertically structured manufacturing, and European regulatory-specialist supply.
| Leading Market Players |
|---|
| Daicel Corporation |
| China National Tobacco Corporation |
| Eastman Chemical Company |
| Mitsubishi Chemical Holdings Corporation |
| Sichuan Push Acetati LLC |
| Solvay SA |
| Celanese Corporation |
| Rayonier Advanced Materials Inc. |
| Sappi Limited |
| Others |
Value Chain & Pricing Dynamics
Indian generic pharmaceutical manufacturers concentrate procurement demand for excipient-grade cellulose acetate phthalate, forcing suppliers into volume-scaled contract pricing with thin distributor margins. This buyer concentration rewards backward-integrated producers with captive acetic acid supply while squeezing regional acetate ester fabricators on cost pass-through.
Pricing Analysis
Distributor margins compress to single digits for pharmaceutical-grade cellulose acetate phthalate as direct supplier relationships displace intermediaries. Three-tier pricing structure across pharmaceutical-grade, technical-grade, and food-grade certification levels tracks USP-NF monograph compliance burdens. Pricing pressure stems from acetic acid feedstock volatility tied to energy pricing cycles. Indian generic manufacturers exhibit highest price sensitivity, while North American specialty pharmaceutical companies prioritize regulatory dossier completeness over unit cost.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade cellulose acetate phthalate remain minimal given excipient stability and batch-traceability requirements that discourage returns. Supply concentrates in Japan, China, and the United States, with pharmaceutical-grade purification capacity clustering around Osaka-Kobe, Shanghai-Ningbo, and Kingsport. Raw material dependencies center on purified cellulose from forestry operations and acetic anhydride from petrochemical or bio-based routes. Single-source vulnerability persists for pharmaceutical-grade acetic acid supply. Distribution runs through direct supplier relationships with top-tier pharmaceutical companies, bypassing traditional chemical distributors for volume contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cellulose acetate phthalate represents a late-cycle quality story as oral solid dosage manufacturers shift procurement toward pelletized formats engineered for continuous manufacturing lines. This specification upgrade favors suppliers with regulatory dossier depth over commodity acetate ester producers.
For Market Incumbents: Cement regulatory positioning by compiling EMA excipient master files and FDA Type II drug master files ahead of REACH phthalate reclassification uncertainty. Expand pharmaceutical-grade pelletization capacity in India to capture CDMO procurement demand. Daicel Corporation and Eastman Chemical Company's backward integration into cellulose and acetic acid supply provides cost insulation against feedstock volatility that threatens margin sustainability for non-integrated competitors.
For New Entrants and Emerging Players: Brazilian generic formulation houses represent an underserved buyer archetype with accelerating demand under ANVISA's complex generic approval pathways. Target São Paulo-state manufacturers with imported enteric coating polymers certified to FDA dissolution standards. Hot melt extrusion-compatible pellet formats offer the most penetrable product entry point, as European REACH solvent restrictions pull coating technology conversion.
For Investors and Strategic Acquirers: Pharmaceutical CDMOs are the most active acquirer in this space, seeking captive excipient supply to compress vendor qualification timelines. The five-to-ten year viability window hinges on cellulose acetate phthalate maintaining its position against alternative enteric polymers during REACH regulatory review. Acquisition targets should display regulatory dossier depth for multiple pharmacopeial jurisdictions. Monitor ECHA's phthalate ester classification proceedings as the critical inflection indicator for European demand trajectory.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | EMA and FDA master file compilation accelerates supplier qualification for oral solid dosage manufacturers. |
| Continuous Manufacturing Integration | Pellet format engineering for twin-screw extrusion lines commands premium positioning against powder supply. |
| Backward Integration | Captive acetic acid and cellulose sourcing insulates margin control from agricultural commodity cycles. |
| Geographic Capacity Expansion | Indian pharmaceutical manufacturing clusters demand localized excipient testing and direct supplier relationships. |
| Alternative Polymer Development | Defensive investment in non-phthalate enteric coatings mitigates REACH reclassification risk for European exposure. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with regulatory affairs directors at enteric coating polymer suppliers, procurement leads at Indian generic pharmaceutical companies, formulation scientists at CDMOs, and technical sales managers at acetate ester distributors informed demand-side dynamics. Secondary sources included FDA Inactive Ingredient Database filings, EMA excipient master file registries, USP-NF monograph updates, and customs trade data for cellulose derivative imports. Bottom-up volume modeling triangulated against top-down market sizing from producer capacity disclosures.
Granularity-level modeling tracked product format, coating technology, and end-user type across the projection horizon. Segmentation dimensions included physical form, application method, and customer archetype, with pharmaceutical-grade purity tier as an industry-specific stratification. CAGRs derived from regression analysis of historical procurement volumes against pharmaceutical production indices and regulatory filing trends. Forecast inputs incorporated CDSCO PLI scheme implementation timelines and ANVISA complex generic approval velocity.
Underlying measurement precision varies by segment; pharmaceutical company procurement carries tighter precision than research laboratory demand. Forecasts reflect assumptions on continuous manufacturing adoption rates and REACH phthalate regulatory trajectory. Practitioners should monitor ECHA classification proceedings, FDA dissolution guidance updates, and Indian CDMO capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Distarch Phosphate Market
Specialty Chemicals
Germany Starch Derivatives Market
Specialty Chemicals
Dipentene (Limonene) Market
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Glutathione Market
Specialty Chemicals
Anhydroxylitol Market
Specialty Chemicals
Global Vacuum Grease Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Diisobutyl Adipate Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Global Spray Polyurethanes Foam Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
PEG and PPG Esters Market
Specialty Chemicals
AEA Salicylic Acid Market