
 Homosalate Market | 2026-2036
Homosalate Market Size, Share, and Industry Trends Forecast 2026-2036
Homosalate Market Foresight
China is narrowing its dependence on imported homosalate intermediates through domestic synthesis scale-up in Jiangsu and Zhejiang provinces. BASF leverages integrated aromatic chemistry capabilities to sustain European supply continuity. ZX Chem anchors Asia-Pacific bulk production with dedicated esterification capacity. Ascent FineChem differentiates through pharmaceutical-grade certification for dermal API applications.
Homosalate is an organic ester synthesized from salicylic acid and 3,3,5-trimethylcyclohexanol, functioning as a UVB-absorbing photostabilizer with peak absorption near 306 nanometers. Manufacturers deploy acid-catalyzed esterification followed by molecular distillation to achieve cosmetic-grade purity thresholds above 99 percent. Lotions dominate volume consumption in mass-market sun care, while gels capture premium positioning among sport and pediatric formulations. Dermatologist channels command higher margin pools through prescription-strength photoprotection protocols, whereas online retail accelerates direct-to-consumer access for specialized SPF products.
FDA regulates homosalate as an over-the-counter sunscreen active under the Tentative Final Monograph, requiring safety and efficacy substantiation for concentrations up to 15 percent. REACH in Europe mandates full toxicological dossiers for homosalate registration, influencing reformulation trends toward biodegradable UV filter alternatives. ECHA hazard classifications shape ingredient substitution timelines across EU cosmetic manufacturers. Stakeholders must monitor regulatory divergence between FDA monograph updates and EU restriction proposals to align portfolio positioning with divergent compliance thresholds.
Market Dynamics
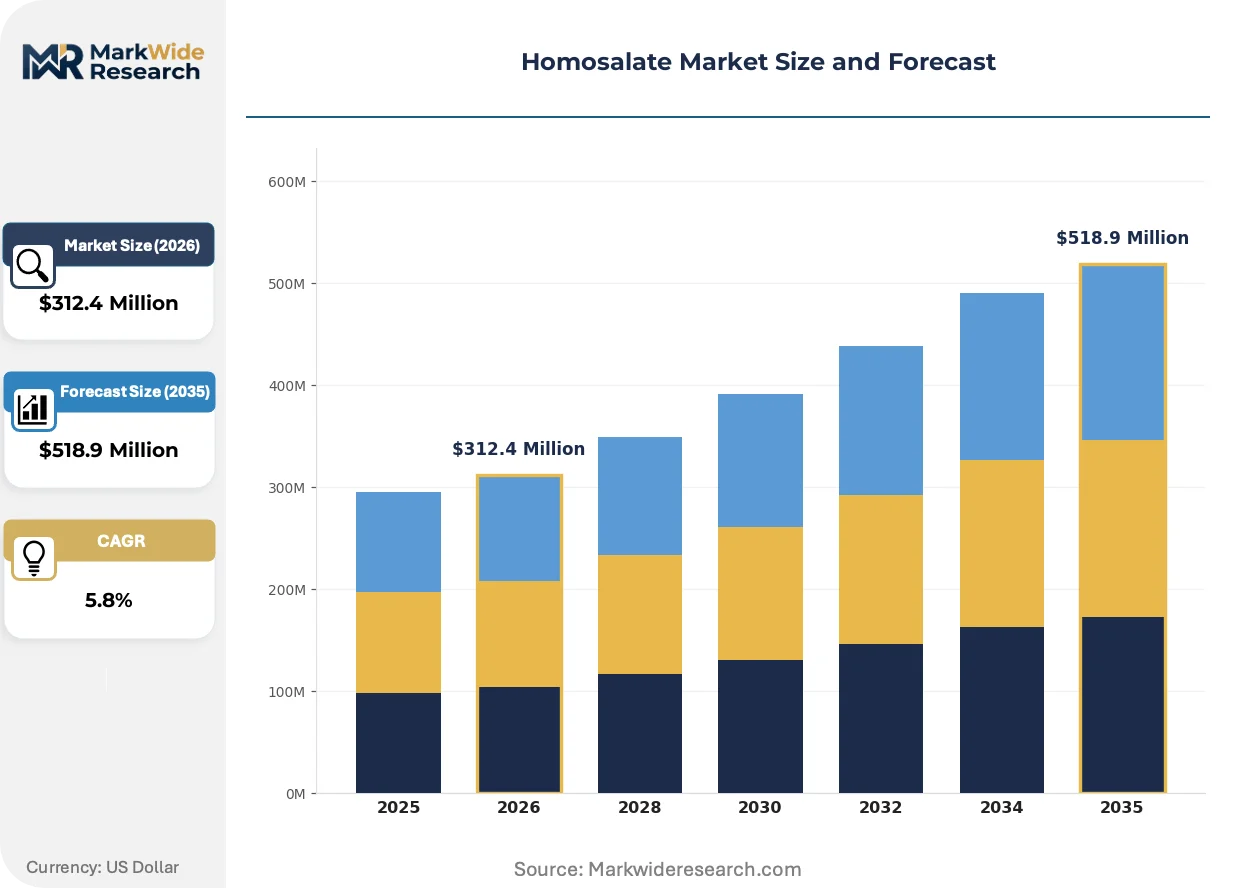
FDA's Tentative Final Monograph review is compressing formulation timelines for UV filter suppliers while dermatology clinics expand professional photoprotection protocols. This regulatory pressure intersects with domestic synthesis scale-up in China to reshape competitive positioning among esterification specialists.
Growth Catalysts
- Professional Channel Expansion:Dermatology clinics in the United States are institutionalizing prescription-strength sunscreen protocols, creating dedicated demand pools for pharmaceutical-grade homosalate certified above 99 percent purity.
- Domestic Intermediate Synthesis:Jiangsu and Zhejiang provinces in China have achieved captive production of 3,3,5-trimethylcyclohexanol feedstock, reducing import dependence for salicylate ester manufacturers.
- Sport Formulation Premiumization:Gel-based pediatric and athletic sun care products command higher margin positioning, pulling demand toward specialized esterification capacity with enhanced photostability specifications.
Market Restraints
- Salicylic Acid Price Volatility:Aromatic feedstock costs fluctuate with phenol derivative markets, compressing margin structures for non-integrated esterification specialists lacking backward integration into phenol chemistry.
- ECHA Hazard Reclassification Risk:REACH dossier requirements and emerging ECHA hazard classifications for UV filters are forcing EU cosmetic manufacturers toward biodegradable alternative reformulations.
- Photostabilizer Substitution Threat:Mineral oxide dispersions and novel triazine derivatives are displacing organic ester UVB absorbers in clean-label positioning strategies across mass-market channels.
Strategic Opportunities
- Indian Mass-Market Penetration:BIS standards alignment for cosmetic actives creates pathway for certified suppliers to access underserved tropical climate demand through domestic formulation partnerships.
- Dermal API Certification:Pharmaceutical-grade homosalate for topical drug applications remains underdeveloped, with only specialized manufacturers holding current Good Manufacturing Practice compliance for active pharmaceutical ingredient status.
- Direct-to-Consumer Channel Expansion:Online retail platforms are compressing traditional distributor layers, enabling specialized SPF brands to build subscription-based recurring revenue with personalized photoprotection protocols.
Industry Challenges
- Toxicological Dossier Compilation:REACH registration requires extensive endocrine disruption and aquatic toxicity studies, stretching technical documentation capabilities for mid-scale esterification operations.
- Molecular Distillation Capacity Constraints:Achieving cosmetic-grade purity above 99 percent demands specialized wiped-film equipment with significant capital intensity and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Homosalate Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lotions, Creams, Gels, Sprays End User: Individuals, Dermatologists, Pharmacies, Hospitals Application: Skin Protection, UV Filters, Cosmetics, Healthcare Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Ampak Company, Spectrum Chemical, Universal Esters, ZX Chem, ZhenYiBio Technology, ATK Chemicals, Ascent FineChem, BASF, Natural Micron Chem Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Homosalate Market Shifts & Advancements
Computational molecular modeling is compressing development cycles for photostabilizer formulations while regulatory divergence between FDA monograph updates and EU restriction proposals fragments compliance strategies. These forces are reshaping how esterification specialists allocate R&D resources across certification tiers.
Encapsulation technology using silica and polymer shell architectures is virtualizing traditional bulk homosalate incorporation methods. Premium sunscreen formulators in sport and pediatric segments are adopting these delivery systems to enhance photostability and reduce dermal penetration concerns. This virtualization is enabling formulation houses to command technology premiums while compressing commodity ester margins in mass-market channels.
REACH authorization procedures under ECHA oversight are tightening toxicological substantiation requirements for UV filters classified as potential endocrine disruptors. European cosmetic manufacturers are accelerating reformulation timelines toward biodegradable alternatives ahead of potential restriction proposals. The professional dermatology channel faces the most complex compliance burden, as prescription-strength products must satisfy both pharmaceutical and cosmetic regulatory frameworks simultaneously.
Subscription-based replenishment models are displacing traditional retail purchasing for specialized SPF products among digitally native consumer segments. Direct-to-consumer brands are capturing recurring revenue through personalized skin-type matching algorithms and automated delivery scheduling. This behavioral shift is most visible in United States coastal metropolitan markets, where UV awareness correlates with higher willingness-to-pay for premium photoprotection protocols.
Homosalate Market Segmentation
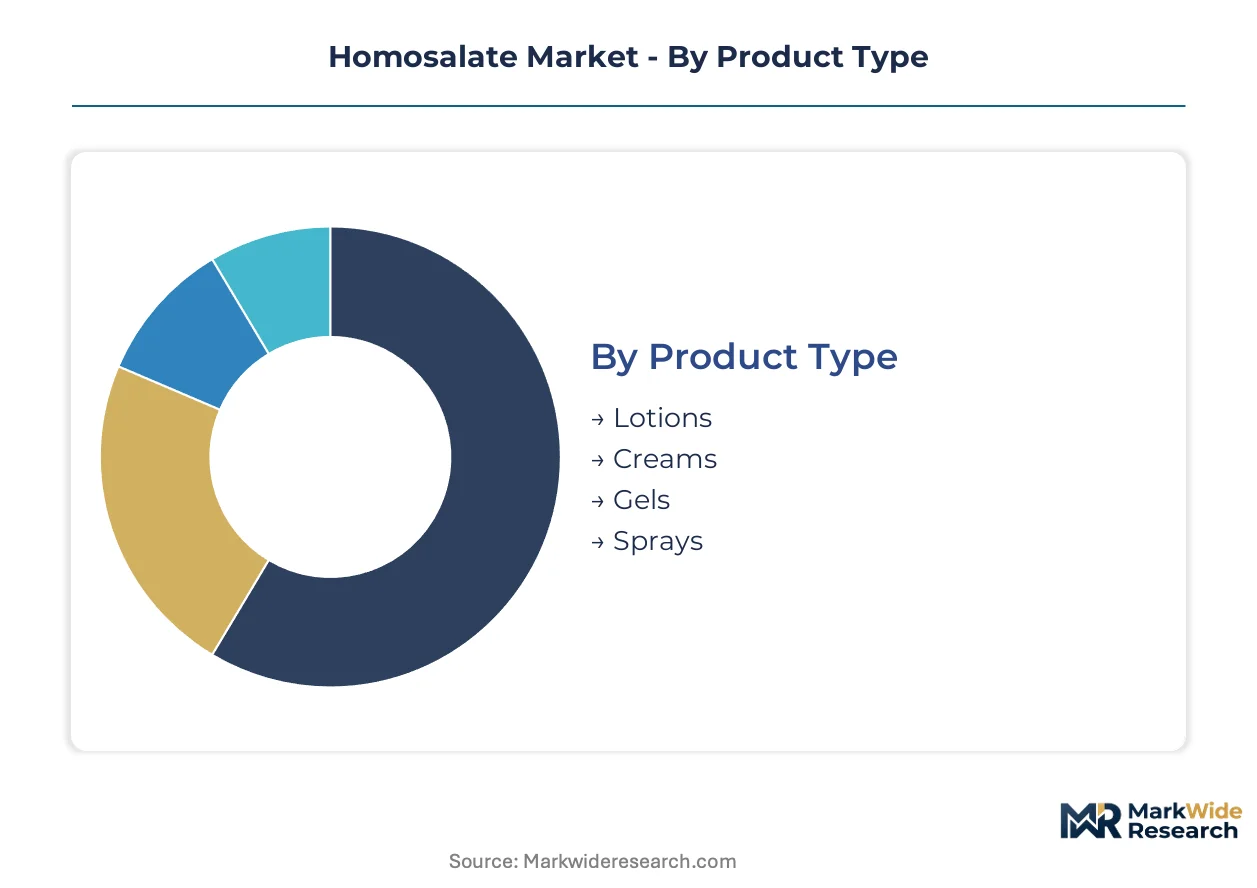
Homosalate demand fragments across formulation physics, professional gatekeepers, and channel economics. Each segmentation dimension reveals distinct purity requirements, pricing power, and regulatory exposure that manufacturers must navigate.
Product Type:
Formulation physics determines homosalate loading rates, photostability demands, and manufacturing complexity across delivery systems.
- Lotions:Oil-in-water emulsions accommodate the highest homosalate loadings, typically 10-15 percent by weight, enabling mass-market SPF 50+ positioning at volume scale. Demand concentrates in United States drugstore channels where consumers prioritize spreadability and cost efficiency over sensorial refinement.
- Gels:Alcohol-thickened matrices require specialized esterification grades with enhanced solubility in polar solvents, commanding premium positioning among sport and pediatric formulations. United States coastal metropolitan markets drive adoption where sweat resistance and non-comedogenic claims justify higher unit economics.
- Creams:Thicker emollients target dry skin segments with occlusive film-forming properties that extend UV protection duration.
- Sprays:Aerosol and pump-dispensed formats demand low-viscosity homosalate grades with flash point considerations for propellant compatibility.
Lotions hold installed capacity. Gels are rotating up the share rankings.
End User:
Customer type stratifies purity certification requirements and procurement authority across consumer and institutional channels.
- Dermatologists:Prescription-strength protocols mandate pharmaceutical-grade homosalate certified above 99 percent purity with current Good Manufacturing Practice documentation. United States clinic networks institutionalize photoprotection counseling, creating dedicated demand pools with annual purchasing contracts and formulary loyalty.
- Individuals:Mass-market consumers prioritize SPF efficacy claims and sensorial experience over technical specifications, purchasing through retail and digital channels with minimal professional guidance. Price sensitivity dominates with private-label capture accelerating in United States supermarket and online retail environments.
- Pharmacies:Pharmacist-assisted selection elevates technical disclosure requirements compared to unaided retail, particularly for sensitive skin positioning.
- Hospitals:Burn centers and oncology units require sterile-grade documentation for immunocompromised patient protocols with batch-level traceability.
Dermatologists command margin premiums. Individual consumers are expanding volume contribution fastest.
Application:
Use case determines regulatory pathway, performance testing standards, and ingredient disclosure obligations.
- UV Filters:Primary sunscreen active applications face the most stringent FDA Tentative Final Monograph compliance, requiring photostability testing and absorption spectrum documentation. United States formulators dominate demand as monograph updates compress approval timelines for new UV filter combinations.
- Skin Protection:Moisturizer-plus-SPF hybrid positioning allows lower homosalate loadings with cosmetic rather than drug regulatory classification, expanding formulation flexibility. Daily wear protocols in United States urban markets drive frequency-of-use expansion beyond seasonal beach applications.
- Cosmetics:Color cosmetic integration with SPF claims requires micronized homosalate grades compatible with pigment dispersion and long-wear film formers.
- Healthcare:Topical drug applications as active pharmaceutical ingredients demand therapeutic equivalence studies and abbreviated new drug application pathways.
UV Filters anchor revenue concentration. Skin Protection is climbing the fastest.
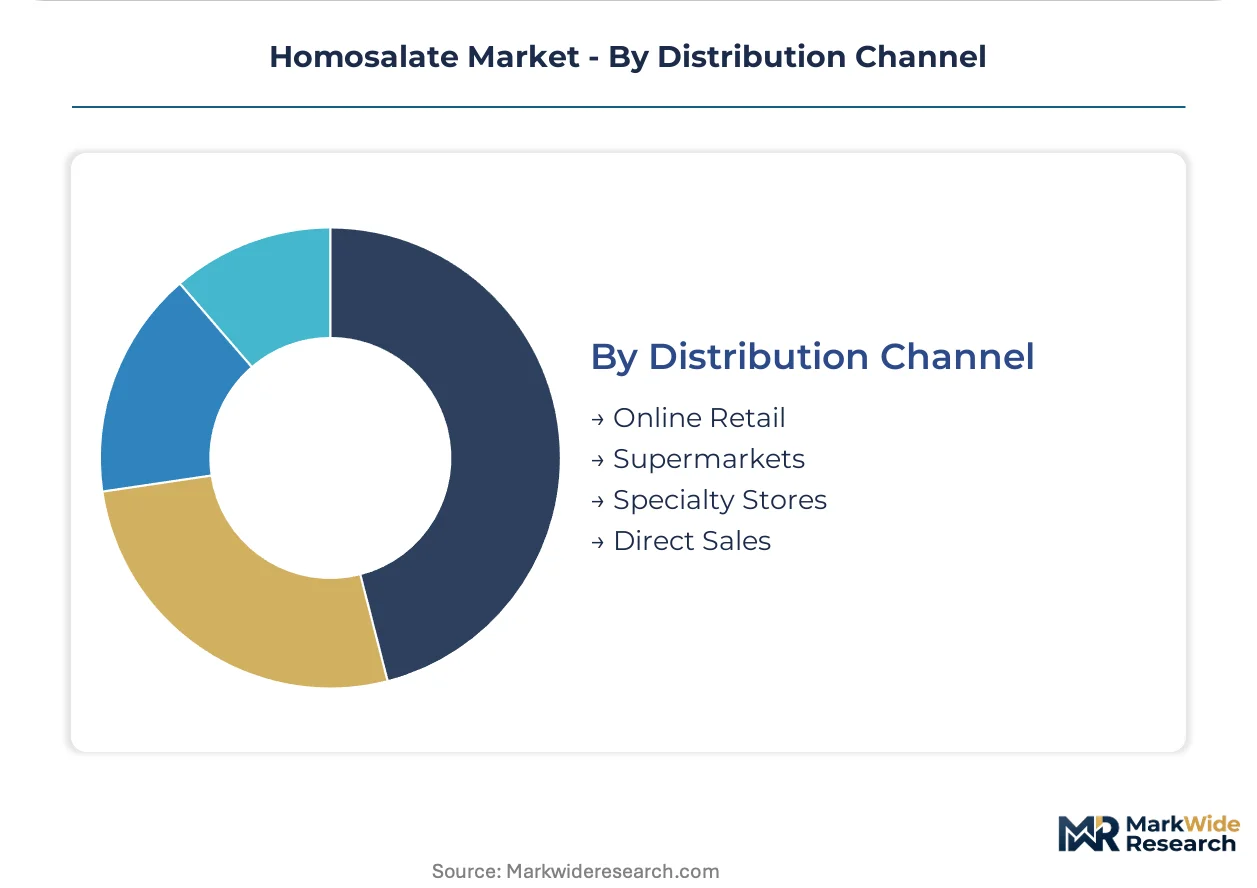
Distribution Channel:
Channel economics determine margin stacking, brand control, and consumer data capture capabilities.
- Online Retail:Direct-to-consumer platforms enable subscription-based replenishment with personalized skin-type algorithms, compressing traditional distributor margins. United States digital-native brands capture recurring revenue through automated delivery scheduling and SPF education content.
- Specialty Stores:Sephora and Ulta Beauty in the United States provide discovery environments for premium positioning with trained beauty advisor consultation and trial-sized sampling programs.
- Supermarkets:Mass-market volume concentration with high-velocity shelf turnover and promotional dependency driving private-label penetration.
- Direct Sales:Dermatologist office dispensing and pharmaceutical representative detailing maintain highest margin capture with patient compliance monitoring.
Supermarkets hold volume concentration. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Esterification capacity clusters in three distinct geographies with divergent regulatory exposure. United States dermatology clinics drive pharmaceutical-grade certification demand. Chinese domestic synthesis reduces import dependence for cyclohexanol feedstock. European REACH dossier requirements accelerate reformulation toward biodegradable alternatives.
United States
FDA's Tentative Final Monograph review compresses formulation timelines for UV filter suppliers. Dermatology clinics in coastal metropolitan markets institutionalize prescription-strength photoprotection protocols with annual purchasing contracts. New Jersey and California host formulation houses serving mass-market and professional channels respectively.
China
Jiangsu and Zhejiang provinces achieve captive production of 3,3,5-trimethylcyclohexanol intermediates through domestic synthesis scale-up. NMPA cosmetic ingredient filings align with tightening safety documentation requirements. Yangtze River Delta chemical parks concentrate esterification capacity with backward integration into phenol derivative supply chains.
Germany
BASF leverages integrated aromatic chemistry capabilities from Ludwigshafen headquarters to sustain European supply continuity. ECHA hazard classifications for UV filters force reformulation timelines toward biodegradable alternatives. REACH authorization procedures demand extensive endocrine disruption and aquatic toxicity study compilation.
India
BIS standards alignment for cosmetic actives creates market entry pathways for certified suppliers. Tropical climate conditions drive mass-market sunscreen consumption through domestic formulation partnerships. Maharashtra and Gujarat host emerging contract manufacturing capacity for regional brand supply.
Japan
METI industrial standards govern cosmetic active purity specifications with stringent photostability testing protocols. Kanto region formulation specialists serve premium skin protection segments with enhanced sensorial positioning. PMDA consultation procedures for quasi-drug sunscreen classification extend product development cycles.
Homosalate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope. The vendor base stratifies between multinational chemical conglomerates with integrated aromatic capabilities and mid-scale esterification specialists focused on cosmetic-grade certification. Three archetypes dominate: integrated petrochemical platforms, dedicated UV filter manufacturers, and pharmaceutical-grade certification holders. Capacity expansion in Chinese chemical parks and M&A consolidation among European specialty chemical portfolios represent the dominant competitive vectors.
Among Asia-Pacific bulk producers, ZX Chem anchors regional supply with dedicated esterification infrastructure. BASF exemplifies the integrated platform archetype through captive phenol chemistry and molecular distillation capabilities. Ascent FineChem occupies a position within the pharmaceutical-grade certification tier, differentiating through dermal API compliance for topical drug applications. These three players represent distinct strategic postures across commodity, integrated, and regulated-grade market segments.
| Leading Market Players |
|---|
| Ampak Company |
| Spectrum Chemical |
| Universal Esters |
| ZX Chem |
| ZhenYiBio Technology |
| ATK Chemicals |
| Ascent FineChem |
| BASF |
| Natural Micron Chem Tech |
| Others |
Supply & Pricing Matrix
Overcapacity in Yangtze River Delta esterification facilities is compressing spot pricing for cosmetic-grade homosalate while tightening margins for non-integrated producers. This utilization dynamic simultaneously rewards backward-integrated phenol derivative operators and forces mid-scale specialists toward pharmaceutical-grade certification premiums to escape commodity tier erosion.
Pricing Analysis
FDA's Tentative Final Monograph dictates the pricing tier structure across pharmaceutical-grade, cosmetic-grade, and technical-grade homosalate segments. Pharmaceutical-grade certification above 99 percent purity commands substantial premiums through dermatology clinic procurement contracts, while mass-market lotion formulations compete on volume scale with compressed unit economics. Price differentiation hinges on molecular distillation capability and current Good Manufacturing Practice documentation status. Cost compression in standard cosmetic grades is intensifying because Chinese domestic synthesis scale-up has expanded Jiangsu and Zhejiang nameplate capacity. Individual consumers through supermarket and online retail channels exhibit highest price sensitivity, whereas United States dermatology clinic networks demonstrate inelastic demand for prescription-strength photoprotection protocols.
Supply Chain Analysis
ZX Chem and BASF concentrate contract manufacturing capacity for homosalate esterification across China, Germany, and India. Geographic supply concentration clusters in Jiangsu province chemical parks, Ludwigshafen integrated aromatic complexes, and emerging Maharashtra contract manufacturing zones. Raw material dependencies draw from phenol derivative markets, 3,3,5-trimethylcyclohexanol intermediate supply, and salicylic acid feedstock channels. Single-source vulnerability in wiped-film molecular distillation equipment creates bottleneck risk for pharmaceutical-grade purity achievement. Distribution runs through direct sales to dermatology clinics, bulk supply agreements with multinational formulators, and spot market transactions for mass-market cosmetic houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Homosalate supply is approaching a platform-economics inflection where pharmaceutical-grade certification interoperability determines supplier switching costs and formulary lock-in across United States dermatology networks.
For Market Incumbents: Build regulatory dossier moats through REACH authorization completion and FDA monograph alignment ahead of potential ECHA restriction proposals. BASF and ZX Chem should expand molecular distillation capacity in named chemical parks to capture pharmaceutical-grade certification demand from clinic network consolidation. Defensive consolidation through acquisition of mid-scale esterification specialists lacking backward integration protects margin pools from Chinese overcapacity spillover. For New Entrants and Emerging Players: Indian mass-market formulation partnerships with BIS-certified supply represent the most penetrable entry point for tropical climate sunscreen demand. Dermal API certification for topical drug applications remains structurally underdeveloped, with only Ascent FineChem holding current Good Manufacturing Practice compliance for active pharmaceutical ingredient status. Direct-to-consumer subscription platforms enable bypass of traditional distributor margin stacking through personalized SPF protocol algorithms. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across pharmaceutical-grade wiped-film distillation capacity, favoring scaled platform operators over fragmented commodity specialists. Long-term viability in the 5-10 year window rests on regulatory dossier completion ahead of potential EU restriction timelines. Acquisition target archetypes include mid-scale esterification specialists with incomplete REACH registration facing compliance cost burdens. Monitor ECHA hazard classification proceedings for UV filters as the critical signal for reformulation-driven demand destruction or certification-premium expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical-Grade Certification Investment | Current Good Manufacturing Practice compliance unlocks dermatology clinic procurement contracts with annual purchasing loyalty. |
| Backward Integration into Phenol Chemistry | Captive salicylic acid production insulates margin structures from aromatic feedstock volatility in derivative markets. |
| Encapsulation Technology Licensing | Silica and polymer shell architectures enable premium positioning in sport and pediatric sunscreen formulations. |
| Direct-to-Consumer Channel Expansion | Subscription-based replenishment models compress traditional distributor layers for specialized SPF brands. |
| REACH Dossier Completion | Full toxicological substantiation secures European market access ahead of potential ECHA restriction proposals. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Tentative Final Monograph filings, ECHA REACH registration databases, and customs trade data for salicylate ester flows. Primary interviews engaged plant managers at Yangtze River Delta chemical parks, procurement leads at United States dermatology clinic networks, and technical R&D directors at European cosmetic formulators. Secondary validation drew from SEC 10-K disclosures of listed specialty chemical operators, NMPA cosmetic ingredient filing records, and BIS standards documentation for Indian market entry pathways. Bottom-up demand modeling triangulated against top-down capacity assessments across named production clusters.
Forecast inputs incorporate formulation physics segmentation across lotions, gels, creams, and sprays; end-user stratification between dermatologists, individual consumers, pharmacies, and hospitals; and distribution channel economics spanning online retail, specialty stores, supermarkets, and direct sales. CAGRs were derived through regression analysis of historical volume trends against regulatory timeline inflections and capacity expansion announcements. Industry-specific forecast inputs include FDA monograph update schedules and ECHA hazard classification proceeding timelines.
Stress conditions across salicylic acid price volatility bands, ECHA restriction probability scenarios, and photostabilizer substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory pathway continuity and clinic network procurement consolidation trajectories. Quarterly review of FDA monograph proceeding status, ECHA SVHC candidate list updates, and Chinese chemical park utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Organo-Modified Siloxanes Market
Specialty Chemicals
Global Prepacked Chromatography Columns Market
Specialty Chemicals
Phosphonate Market
Specialty Chemicals
Tubatoxin Market
Specialty Chemicals
Cyclomethicone Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Lignin Products Market
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Enzyme Inhibitors Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Metal Biocide Market
Specialty Chemicals
Colloidal Gold Suspension Market