
 Ethylhexane Diol Market | 2026-2036
Ethylhexane Diol Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylhexane Diol Market Analytics
China is rewriting capacity dynamics for ethylhexane diol as domestic producers expand output for downstream plastics and coatings industries. BASF SE leverages its integrated Ludwigshafen complex to sustain cost advantages across European supply chains. LANXESS anchors its position through specialty-grade production tailored to automotive OEM specifications. Evonik Industries AG competes on R&D intensity, particularly in bio-based diol pathways.
Ethylhexane diol (2-ethyl-1,3-hexanediol) functions as a coupling solvent and viscosity modifier with a molecular weight of 146.23 g/mol and boiling point near 244 degrees Celsius, serving primarily to enhance film formation in coatings and stabilize emulsion systems. The specialty grade segment commands premium positioning due to pharmaceutical and high-performance coatings compliance requirements, while the bio-based category represents the fastest-growing formulation type as manufacturers respond to renewable content mandates. Liquid form dominates volume throughput given its compatibility with continuous processing equipment across adhesives and paints applications.
EPA oversight under the Toxic Substances Control Act shapes permissible emission profiles for U.S.-based manufacturing, while REACH registration in Europe imposes rigorous substance evaluation protocols that elevate compliance costs for imported material. China's SAMR enforces GB standards for chemical purity that increasingly align with downstream automotive industry specifications. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation strategies and supply chain qualification timelines.
Market Dynamics
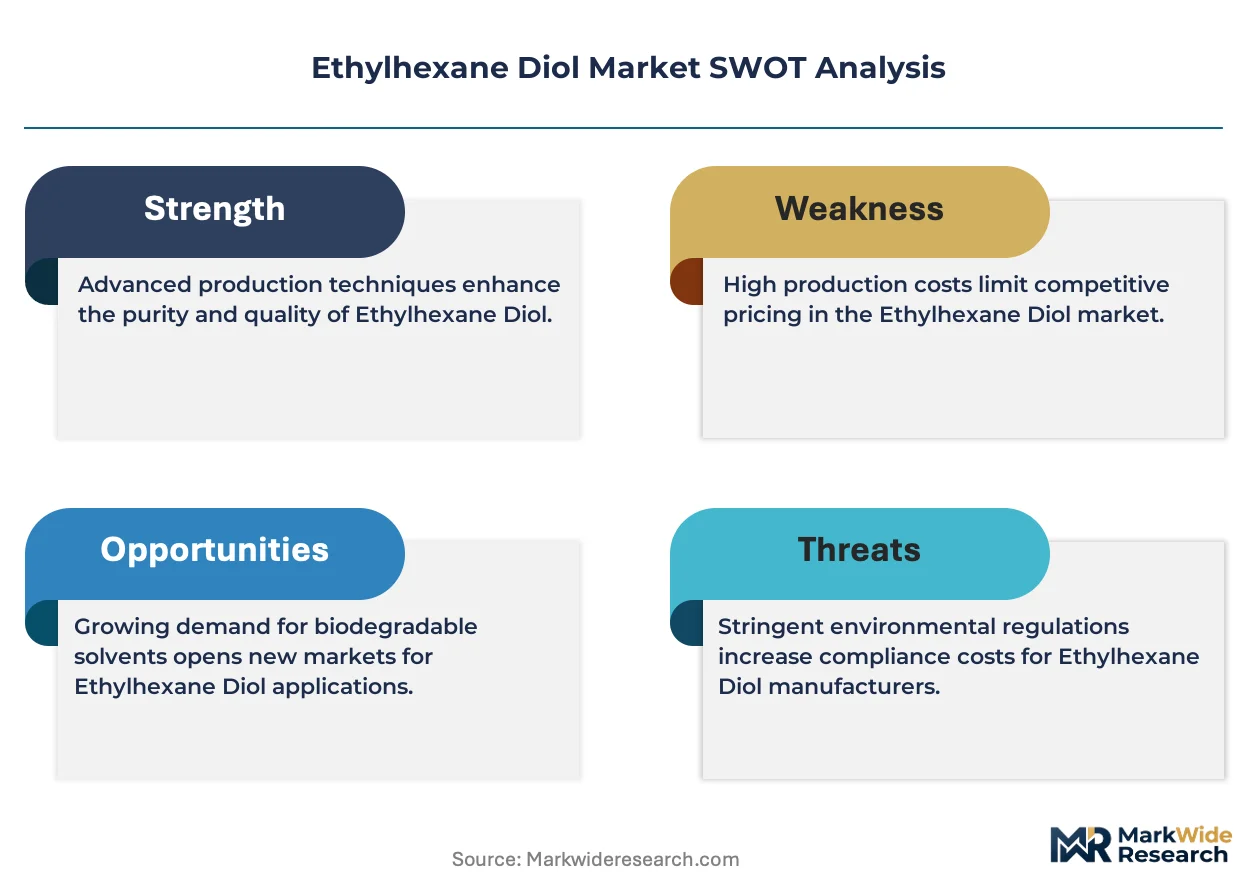
REACH registration protocols in Europe and EPA emission standards in the United States are compressing formulation flexibility for ethylhexane diol manufacturers, forcing simultaneous compliance investments across multiple purity thresholds and documentation frameworks.
Growth Catalysts
- Automotive OEM specifications:Specialty-grade ethylhexane diol demand concentrates in vehicle coating systems where film formation properties meet durability requirements for exterior finishes.
- REACH substance evaluation:European registration protocols create competitive moats for pre-registered suppliers capable of navigating ECHA documentation requirements.
- GB standard alignment:China's SAMR enforcement of automotive-grade purity specifications drives domestic capacity expansion for downstream plastics manufacturing.
Market Restraints
- Propylene feedstock volatility:Crude oil price fluctuations transmit directly to ethylhexane diol production economics through n-butanol and propylene oxide input costs.
- Specialty-grade supply concentration:Pharmaceutical-compliant production capacity clusters among integrated German and Chinese chemical complexes with dedicated purification assets.
- Bio-based glycol substitution:1,3-propanediol and bio-sourced alternatives gain formulation share in personal care and select coatings applications.
Strategic Opportunities
- India industrial corridor expansion:BIS certification pathways for specialty chemicals create first-mover positioning in Gujarat and Maharashtra manufacturing clusters.
- Waterborne coatings transition:Emulsion stabilization properties position ethylhexane diol for volume growth as solvent-based systems face regulatory pressure.
- EU Green Deal chemical sustainability:Renewable content mandates accelerate bio-based diol pathway development for compliant formulation portfolios.
Industry Challenges
- Cross-jurisdictional registration expertise:Simultaneous EPA TSCA, REACH, and SAMR compliance requires specialized regulatory affairs capabilities.
- Specialty-grade capex thresholds:Pharmaceutical-grade purification infrastructure demands dedicated distillation and analytical equipment investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylhexane Diol Market |
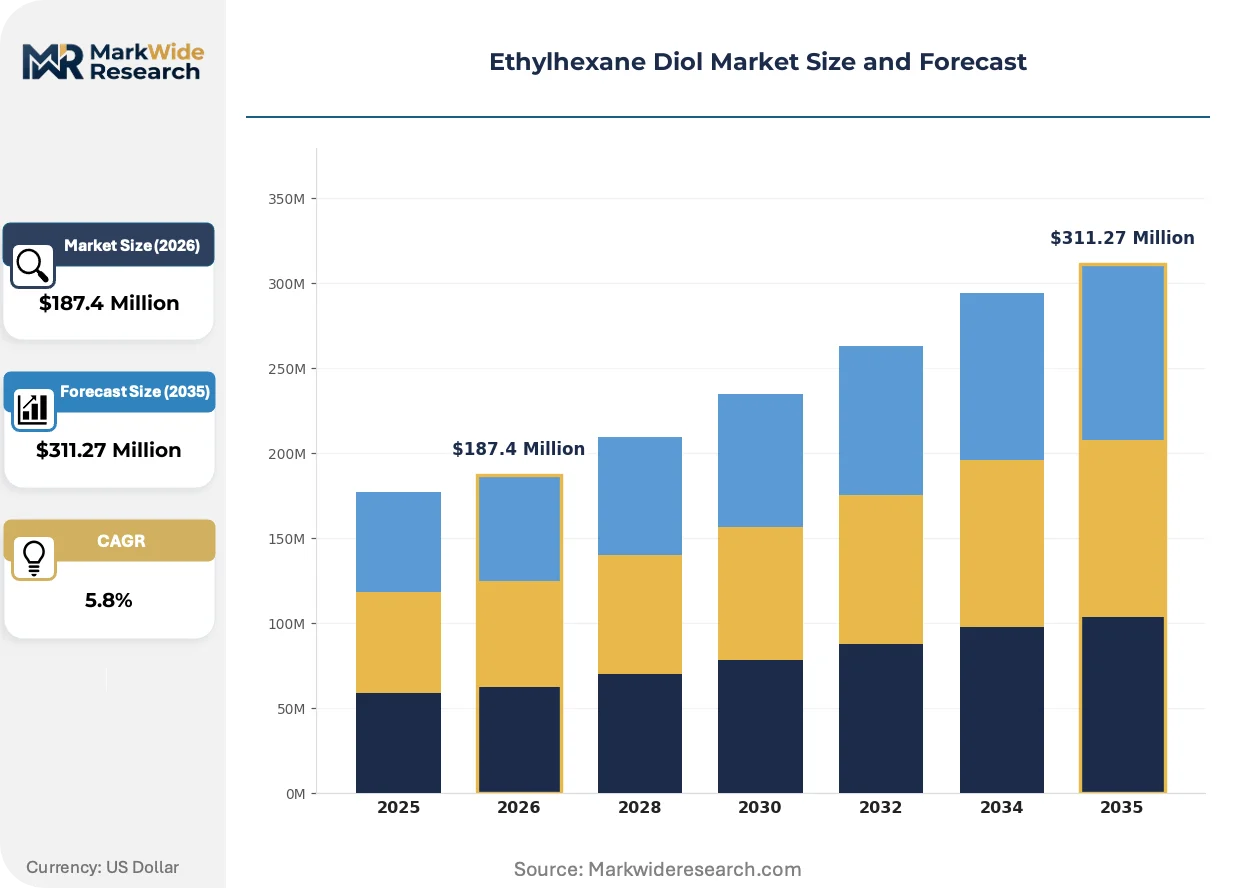
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose, Specialty Grade, Bio-based, Industrial Application: Plastics, Paints, Coatings, Adhesives Form: Liquid, Solid, Concentrate, Emulsion End User: Chemicals, Textiles, Pharmaceuticals, Automotive |
| Companies Covered | BASF SE, LANXESS, UBE Corporation, PETRONAS Chemicals Group Berhad, Prasol Chemicals Ltd., Evonik Industries AG, Perstorp Holding AB, Lishui Nanming Chemical Co., Hefei TNJ Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylhexane Diol Market Evolving Landscape
Bio-based synthesis pathways and continuous processing technologies are restructuring production economics for ethylhexane diol, while regulatory fragmentation across major chemical markets forces parallel compliance architectures.
Enzymatic reduction processes for 2-ethyl-1,3-hexanediol production operate at lower temperature profiles than conventional catalytic hydrogenation. Specialty chemical producers in Germany and the Netherlands pilot these biocatalytic routes to reduce energy intensity. The technology is rendering obsolete batch-wise high-pressure hydrogenation assets that dominate legacy manufacturing footprints.
EPA's Toxic Substances Control Act Section 5 notification requirements for new chemical substances tighten scrutiny on modified glycol ether formulations. Manufacturers face extended review timelines for structural analogs of ethylhexane diol. Coatings formulators in the United States accelerate pre-manufacture notification submissions to secure supply continuity for qualified substances.
Automotive Tier 1 suppliers consolidate qualified material lists around fewer coupling solvent platforms to simplify supply chain audit requirements. Direct procurement relationships with integrated chemical producers replace distributor-mediated purchasing for high-volume coating applications. This concentration pattern is most pronounced in Germany and China where OEM specification alignment drives supplier selection criteria.
Ethylhexane Diol Market Segmentation
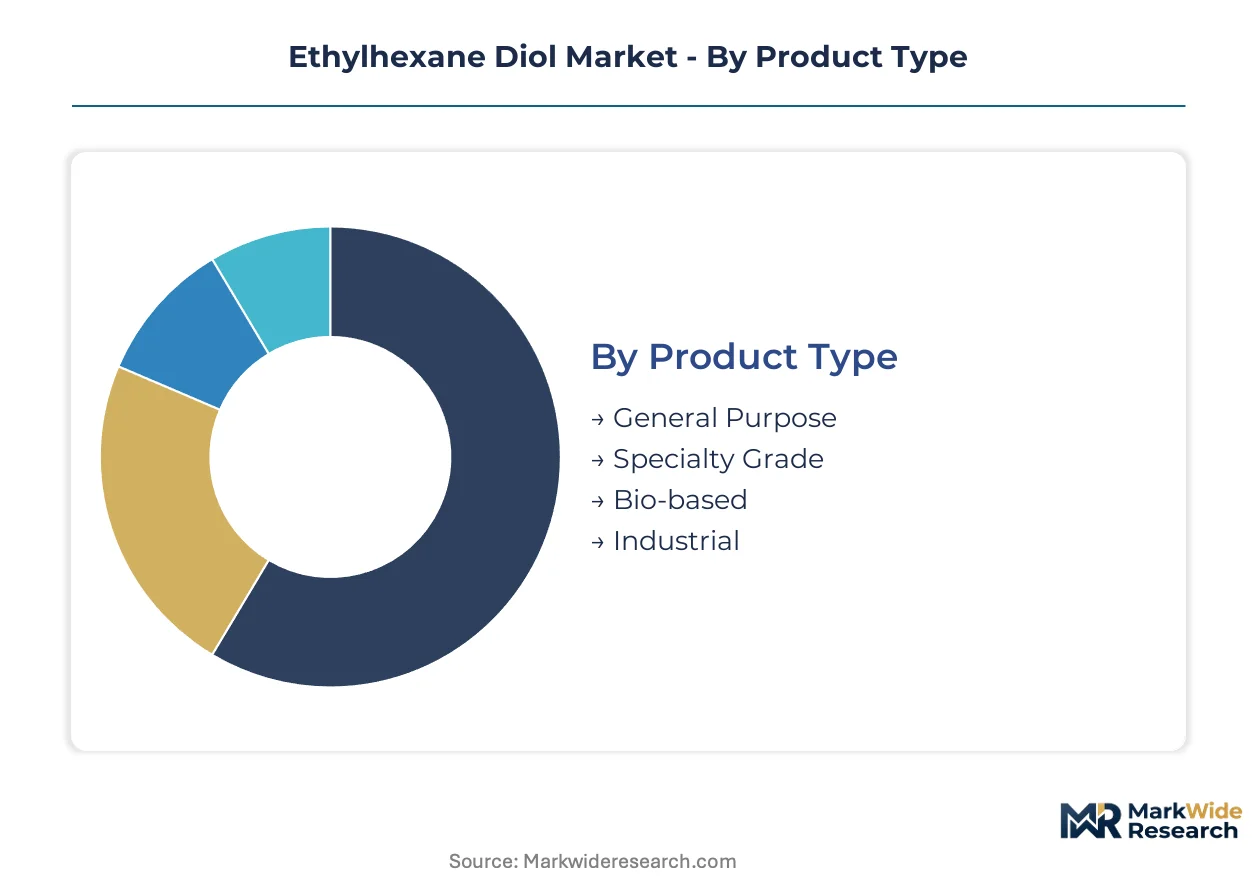
Ethylhexane diol formulation strategies diverge sharply across purity grades and downstream specifications. Manufacturers must align production assets with distinct compliance thresholds that separate commodity industrial supply from pharmaceutical-grade and bio-based alternatives.
Product Type:
Cost tier stratification separates commodity formulations from premium-certified production, with capital intensity and purification infrastructure determining competitive positioning.
- Specialty Grade:Pharmaceutical and automotive OEM compliance demands sub-ppm impurity thresholds. German and Chinese integrated complexes anchor supply for exterior vehicle coatings and active pharmaceutical ingredient synthesis where ECHA documentation and SAMR GB standards apply.
- Bio-based:Enzymatic reduction pathways at lower temperature profiles displace conventional catalytic hydrogenation. Dutch and German producers pilot biocatalytic routes to meet EU Green Deal renewable content mandates in personal care and sustainable coatings.
- General Purpose:Standard viscosity modification for industrial adhesives and sealants without pharmaceutical or automotive certification requirements.
- Industrial:Bulk coupling solvent applications in chemical processing and textile finishing with baseline purity specifications.
Specialty grade commands the established base. The steepest expansion runs through bio-based formulations.
Application:
End-use performance requirements dictate molecular weight optimization and film formation characteristics across divergent substrate chemistries.
- Coatings:Exterior automotive finishes demand precise boiling point control near 244 degrees Celsius for optimal leveling and durability. Waterborne emulsion stabilization properties position ethylhexane diol for volume growth as EPA emission standards pressure solvent-based systems.
- Adhesives:Coupling solvent functionality enhances compatibility between polar and non-polar components in structural bonding applications. Procurement concentrates among Tier 1 automotive suppliers consolidating qualified material lists around fewer solvent platforms.
- Paints:Architectural and industrial formulations utilize viscosity modification for brushability and spray application consistency.
- Plastics:Polymer processing aid functionality supports extrusion and molding operations in packaging and consumer goods manufacturing.
Coatings applications anchor current volume. The steepest expansion trajectory sits with adhesives as automotive supply chain consolidation accelerates.
Form:
Physical state determines compatibility with continuous processing equipment and storage logistics across manufacturing footprints.
- Liquid:Dominates throughput given pumpability and metering precision in automated coating and adhesive production lines. Compatibility with continuous stirred-tank reactors and inline blending systems sustains preference across German and Chinese manufacturing clusters.
- Concentrate:Reduced freight costs and customized dilution protocols serve remote formulation facilities with limited solvent handling infrastructure.
- Emulsion:Pre-dispersed aqueous systems simplify waterborne coatings integration for smaller formulators lacking high-shear mixing assets.
- Solid:Powder handling for specialty applications requiring extended shelf stability and reduced flammability during transport.
Liquid form holds the volume base. Concentrate formats climb fastest as regional blending capacity expands.
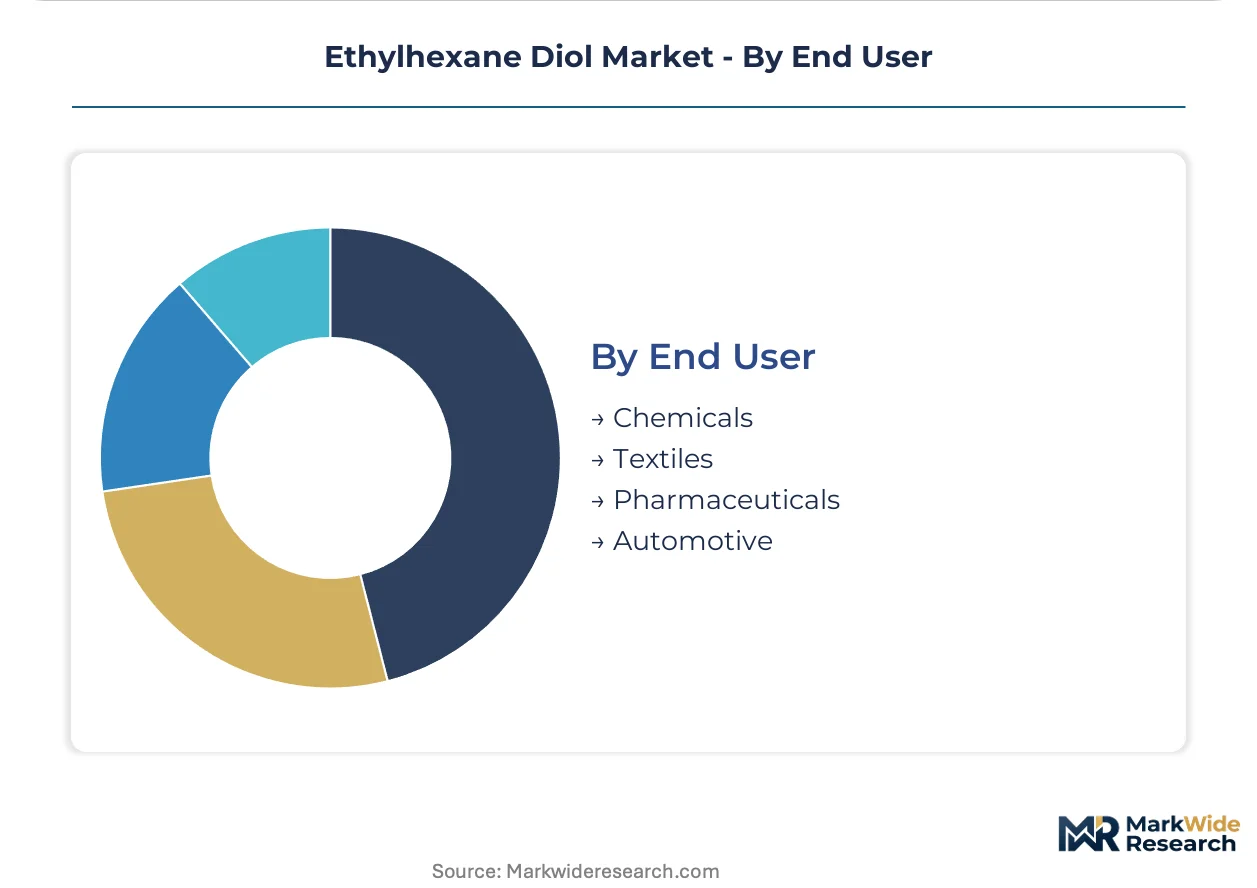
End User:
Customer type segmentation reflects divergent specification stringency from commodity chemical processing to regulated pharmaceutical synthesis.
- Automotive:OEM exterior finish durability requirements drive specialty-grade procurement with direct producer relationships replacing distributor channels. Tier 1 supplier consolidation in Germany and China favors integrated chemical complexes with dedicated analytical laboratories.
- Pharmaceuticals:Active ingredient synthesis and excipient applications impose pharmacopeial compliance with documented supply chain audit trails. REACH registration and FDA Drug Master File requirements elevate barriers for non-integrated suppliers.
- Chemicals:Intermediate processing and solvent recovery operations across industrial chemical manufacturing with standard purity tolerances.
- Textiles:Fiber lubrication and finishing treatments in synthetic yarn and fabric production with moderate specification requirements.
Automotive demand anchors the customer base. Pharmaceutical applications expand most quickly as synthesis outsourcing concentrates among qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emission standards under the Toxic Substances Control Act anchor North American compliance architecture for ethylhexane diol manufacturers, while SAMR GB standards and REACH registration protocols shape parallel qualification requirements in Asia-Pacific and European supply chains respectively.
United States
Automotive OEM coating specifications and waterborne paint transitions drive specialty-grade consumption. EPA TSCA Section 5 notification requirements extend review timelines for structural analogs. Houston-Gulf Coast chemical clusters concentrate bulk industrial production with dedicated export capacity for Latin American markets.
Germany
REACH registration moats and pharmaceutical-grade purification demand sustain premium positioning. ECHA substance evaluation protocols elevate documentation burdens for non-integrated importers. Ludwigshafen and Leverkusen integrated complexes anchor European supply with dedicated analytical laboratories serving automotive Tier 1 suppliers.
China
Domestic plastics manufacturing expansion and automotive coatings localization concentrate demand. SAMR enforcement of GB standards for chemical purity tightens specification alignment with downstream industries. Yangtze River Delta chemical parks scale capacity for adhesives and sealants feedstock supply.
India
BIS certification pathways for specialty chemicals create qualification opportunities in Gujarat and Maharashtra industrial corridors. CDSCO pharmaceutical excipient standards elevate barriers for imported material. Mumbai-Pune manufacturing clusters attract regional blending capacity for waterborne coatings formulation.
Netherlands
EU Green Deal renewable content mandates accelerate bio-based diol pathway pilot programs. ECHA registration expertise concentrates among Rotterdam-Antwerp chemical logistics hubs. Biocatalytic reduction technologies operate at lower temperature profiles than conventional hydrogenation assets.
Ethylhexane Diol Market Competitive Landscape
Capability concentration sits with integrated petrochemical complexes possessing dedicated purification infrastructure; scale advantage sits with diversified chemical conglomerates operating across multiple glycol ether product lines. The market structures around three tiers: multinational integrated producers with REACH-registered portfolios, regional specialists serving automotive qualification requirements, and commodity industrial suppliers competing on freight-adjusted delivered pricing. Dominant competitive moves include backward integration into propylene oxide feedstock and geographic expansion through distributor network consolidation.
Among German integrated chemical producers, BASF SE and LANXESS occupy positions within the specialty-grade tier where ECHA documentation capabilities create qualification moats. Evonik Industries AG represents the R&D-intensive archetype with pilot programs in enzymatic reduction pathways. These three companies exemplify divergent strategic postures: scale-driven vertical integration, automotive specification focus, and bio-based technology development respectively.
| Leading Market Players |
|---|
| BASF SE |
| LANXESS |
| UBE Corporation |
| PETRONAS Chemicals Group Berhad |
| Prasol Chemicals Ltd. |
| Evonik Industries AG |
| Perstorp Holding AB |
| Lishui Nanming Chemical Co. |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Propylene feedstock volatility compresses margin structures across all purity tiers while simultaneously forcing geographic consolidation of purification assets around integrated Ludwigshafen and Yangtze River Delta complexes. This input-cost instability widens spreads between pharmaceutical-grade and industrial formulations as dedicated distillation infrastructure becomes the price-setting bottleneck.
Pricing Analysis
Freight-adjusted delivered spreads between German and Chinese supply points exceed baseline production differentials due to REACH documentation costs and SAMR GB-standard compliance investments. Three-tier pricing structure across specialty, bio-based, and industrial grades reflects purification capital intensity rather than raw material differentials alone. Pricing pressure stems from bio-based glycol substitution in personal care applications where 1,3-propanediol gains formulation share. Tier 1 automotive suppliers exhibit lowest price sensitivity given OEM qualification lock-in, while commodity industrial buyers concentrate purchasing power through distributor consolidation.
Supply Chain Analysis
Upstream n-butanol and propylene oxide sourcing draws from Houston-Gulf Coast, Rotterdam-Antwerp, and Singapore-Jurong petrochemical hubs with crude oil price transmission direct to ethylhexane diol production economics. Specialty-grade supply concentrates in Germany and China where integrated complexes maintain dedicated analytical laboratories for ECHA and SAMR documentation. Single-source vulnerability sits with pharmaceutical-grade purification assets clustered among three Ludwigshafen-area producers. Distribution runs through direct procurement relationships replacing distributor channels for high-volume automotive coating applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Waterborne coatings transition represents an early-cycle penetration opportunity as EPA emission standards accelerate solvent-based system displacement across North American and European automotive finishing operations.
For Market Incumbents: Entrench qualification moats by deepening backward integration into propylene oxide feedstock and expanding dedicated analytical capacity for REACH substance evaluation protocols. Bio-based glycol substitution from 1,3-propanediol suppliers threatens personal care segment share and demands accelerated enzymatic reduction pilot programs to defend premium positioning.
For New Entrants and Emerging Players: Pursue BIS certification pathways in Gujarat and Maharashtra industrial corridors where CDSCO pharmaceutical excipient standards create qualification barriers for imported material. Waterborne emulsion concentrate formats offer the most penetrable entry point for regional blending facilities lacking high-shear mixing assets.
For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors integrated producers with REACH-registered portfolios and dedicated purification infrastructure. Long-term viability rests on bio-based pathway development and automotive OEM specification alignment. Monitor enzymatic reduction technology maturation as the inflection signal for production economics restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Oxide | Captive feedstock supply insulates margin structures from crude oil volatility transmission. |
| Enzymatic Reduction Technology Scale-Up | Lower-temperature biocatalytic routes reduce energy intensity versus legacy hydrogenation assets. |
| REACH Registration Portfolio Expansion | ECHA documentation capabilities create competitive moats against non-integrated importers. |
| Waterborne Emulsion Concentrate Development | Pre-dispersed formats capture regional blending demand from smaller coatings formulators. |
| Automotive Tier 1 Direct Supply Agreements | OEM qualification alignment replaces distributor-mediated purchasing for exterior finish applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with coatings formulators, automotive Tier 1 procurement leads, chemical plant managers, and distribution channel partners. Secondary validation drew from ECHA registration databases, SAMR GB standard filings, SEC 10-K disclosures from diversified chemical conglomerates, and customs trade data for propylene derivative flows. Bottom-up capacity assessments and top-down demand modeling were triangulated to reconcile production economics with end-use consumption patterns.
Calibration against historical REACH registration timelines and EPA TSCA Section 5 review durations anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include purity grade tier, end-use industry vertical, physical form factor, and regional regulatory cluster. CAGRs were derived from supply-demand balance projections incorporating propylene feedstock cost trajectories and automotive OEM specification evolution.
Sensitivities concentrate around crude oil price volatility, enzymatic reduction technology maturation curves, and cross-jurisdictional registration timeline extensions. Forecasts reflect documented assumptions regarding bio-based substitution rates and waterborne coatings penetration trajectories. Cross-checking against Cefic chemical production statistics and ACC market tracking data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Foam Blowing Agents Market
Specialty Chemicals
Global Metal Chelates Market
Specialty Chemicals
United States Aerosol Cans Market
Specialty Chemicals
Bio-Wax Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Eco-Friendly Plasticizers Market
Specialty Chemicals
Silicone Derivative Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Sol-Gel Processing Market
Specialty Chemicals
Allantoin Market
Specialty Chemicals
Global 28-Homobrassinolide Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
North America Perms and Relaxants Market
Specialty Chemicals
Phenylbenzimidazole Sulfonic Acid Market