
 Electrical Insulating Varnish for Motor Vehicle Market | 2026-2036
Electrical Insulating Varnish for Motor Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Electrical Insulating Varnish for Motor Vehicle Market Analysis
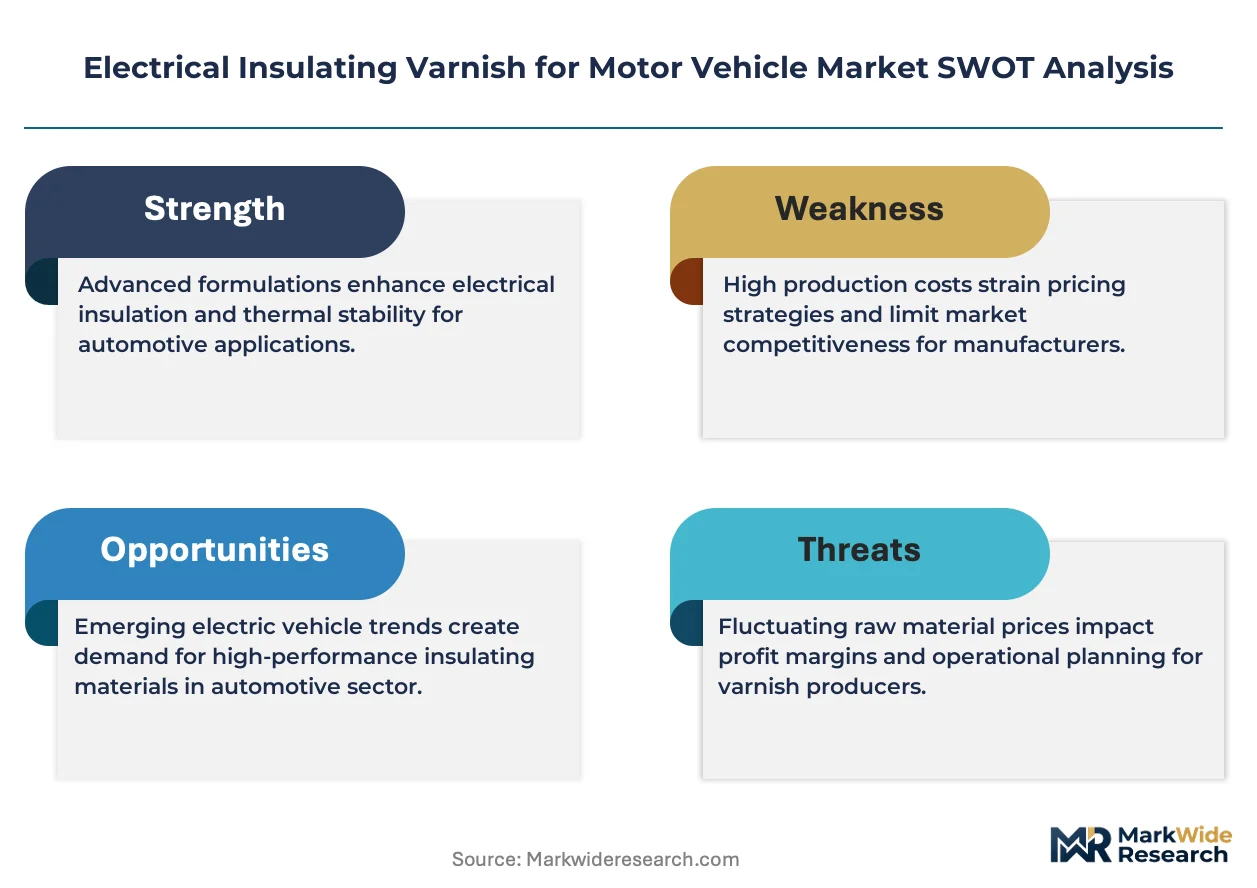
EV-dedicated motor manufacturers is bifurcating from legacy internal-combustion suppliers as the dominant demand archetype in automotive insulating varnish procurement. Axalta Coating Systems leverages its North American OEM relationships to sustain volume commitments across electric traction motor programs. Elantas GmbH anchors European supply through specialized resin formulations for high-voltage winding insulation. Momentive Performance Materials competes on silicone-based thermal stability for premium EV platforms.
Electrical insulating varnish for motor vehicle comprises resin-based formulations—typically polyester, epoxy, or polyurethane chemistries cured at 130°C to 180°C—that establish dielectric barriers between copper windings and grounded motor housings. These coatings prevent inter-turn short circuits while conducting heat away from stator cores operating at sustained loads above 10,000 rpm. Epoxy formulations command the widest application footprint across OEM motor lines due to their superior chemical resistance and bond strength at elevated temperatures. Water-based technology is gaining fastest adoption as assemblers retool coating lines to meet volatile organic compound restrictions without sacrificing film uniformity.
EPA emission thresholds and NHTSA corporate average fuel economy mandates compel motor designers to specify higher thermal class insulations, directly elevating varnish performance requirements across US vehicle production. REACH restrictions on solvent-based chemistries in Europe force reformulation investments that favor suppliers with captive resin synthesis capabilities. Stakeholders must monitor regulatory divergence between California Air Resources Board rules and federal standards to anticipate specification fragmentation across North American supply chains.
Market Dynamics
Vehicle electrification is forcing a complete redesign of motor insulation specifications, as copper winding temperatures in electric traction motors now exceed the thermal limits that legacy internal-combustion starter motor varnishes were engineered to withstand.
Growth Catalysts
- NHTSA Fuel Economy Mandates:US motor designers must specify higher thermal class insulations to meet corporate average fuel economy standards, directly elevating varnish performance requirements across domestic vehicle production.
- Epoxy Chemistry Advancement:Superior chemical resistance and bond strength at elevated temperatures has cemented epoxy formulations as the dominant resin system across OEM electric motor lines.
- German OEM Redesign Cycles:Concentrated demand from Stuttgart and Munich-based manufacturers redesigning motor architectures for next-generation hybrid and battery-electric platforms is pulling specialized high-voltage winding insulation procurement.
Market Restraints
- Petrochemical Feedstock Volatility:Polyester and epoxy resin synthesis depends on benzene and propylene derivatives whose price swings compress coating manufacturer margins unpredictably.
- European Supply Concentration:REACH-compliant resin formulation capabilities cluster among German and Swiss chemical specialists, creating single-source vulnerability for automotive OEMs outside these geographies.
- Silicone Substitution Ceiling:Premium silicone-based thermal stability solutions from specialty chemical suppliers capture high-end EV platforms but face cost barriers to volume adoption in mass-market segments.
Strategic Opportunities
- India Motor Manufacturing:PLI scheme incentives for electric vehicle component production are attracting traction motor assembly investments that lack established local varnish supply relationships.
- Water-Based Coating Conversion:Volatile organic compound restrictions in California and EU member states create first-mover advantage for suppliers with proven water-based film uniformity at 130°C to 180°C cure profiles.
- Stator-Direct Cooling Convergence:Integration of oil-immersed thermal management with traditional varnish dielectric barriers opens specification space for hybrid insulation systems in 800V architectures.
Industry Challenges
- High-Voltage Safety Certification:IEC 60034-18-41 partial discharge resistance testing timelines extend motor qualification cycles by 12-18 months, straining supplier-engineering bandwidth.
- Legacy Equipment Retooling:Dip-and-bake varnish lines designed for solvent-based chemistries require substantial capital redeployment to handle water-based viscosity and flow characteristics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrical Insulating Varnish for Motor Vehicle Market |
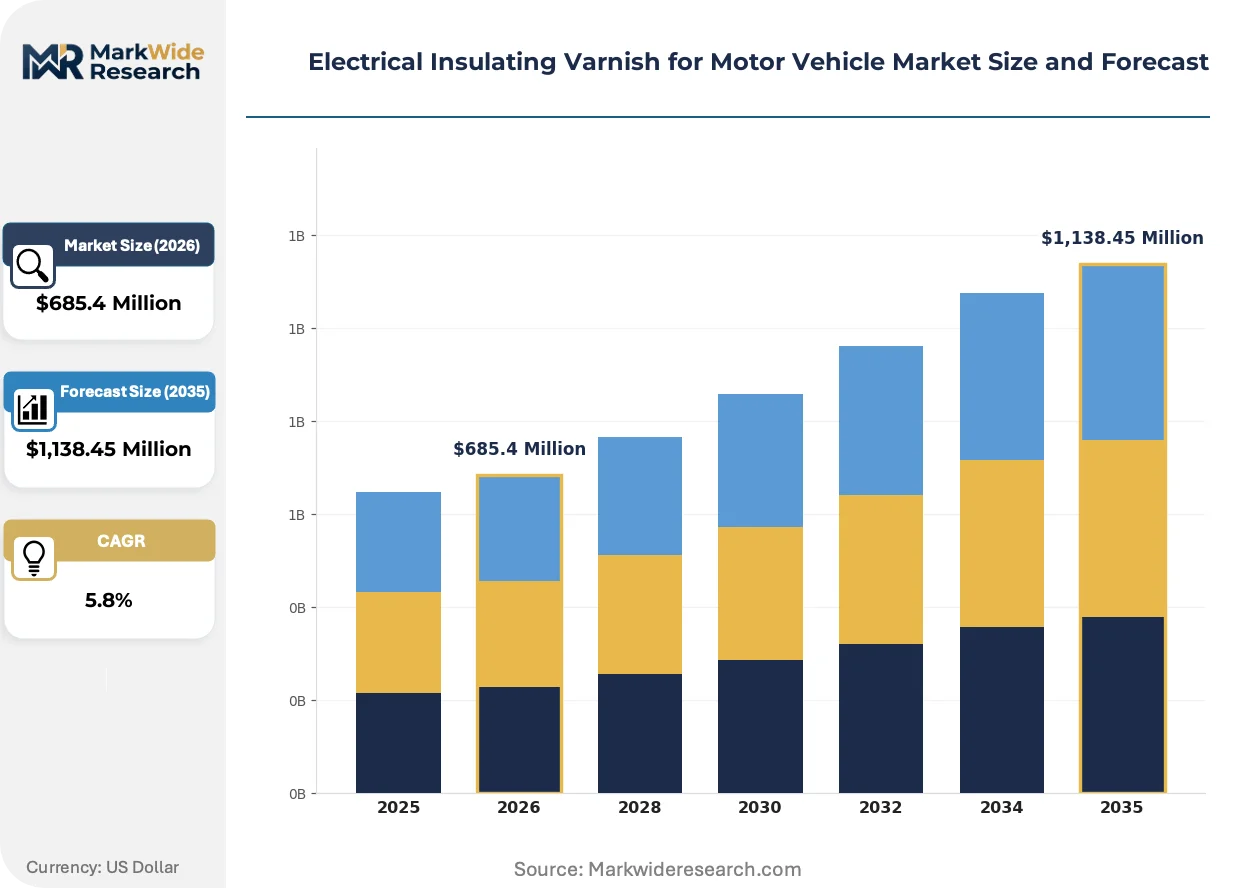
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethane, Polyester, Epoxy, Silicone Application: Insulation, Coating, Adhesive, Encapsulation End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Conventional, Nano-coating, Water-based, Solvent-based |
| Companies Covered | Axalta Coating Systems, 3M Company, Elantas GmbH, Momentive Performance Materials, Nitto Denko Corporation, Hitachi Chemical (Resonac Holdings), Von Roll Holding AG, PPG Industries, Kyocera Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrical Insulating Varnish for Motor Vehicle Market Emerging Trajectories
Formulation chemistry, application methodology, and procurement specification are all undergoing simultaneous revision as electric powertrain thermal loads rewrite the performance envelope for motor insulation systems.
Water-based insulating varnish is supplanting solvent-borne systems in coating lines retooling for volatile organic compound compliance. European and North American motor assemblers are adopting aqueous epoxy and polyurethane dispersions at accelerated pace to meet REACH and EPA emission thresholds without sacrificing film build uniformity. This transition is compressing incumbent solvent-based supplier market presence while rewarding captive resin synthesis capabilities.
REACH restrictions on solvent-based chemistries are forcing reformulation investments across European automotive supply chains. ECHA substance of very high concern listings for traditional aromatic diluents have eliminated cost-competitive formulation options for non-integrated coating suppliers. German OEMs and Tier-1 suppliers are responding by consolidating procurement relationships with resin manufacturers possessing in-house synthesis and regulatory compliance documentation.
Direct stator oil cooling is altering specification priorities for varnish dielectric performance. Motor designers in premium EV platforms now prioritize varnish compatibility with transmission-grade thermal fluids over standalone thermal conductivity metrics. This behavioral shift is most visible in California and Germany, where 800V traction motor programs are specifying hybrid insulation systems that combine traditional varnish barriers with engineered oil-impregnated paper slot liners.
Electrical Insulating Varnish for Motor Vehicle Market Segmentation
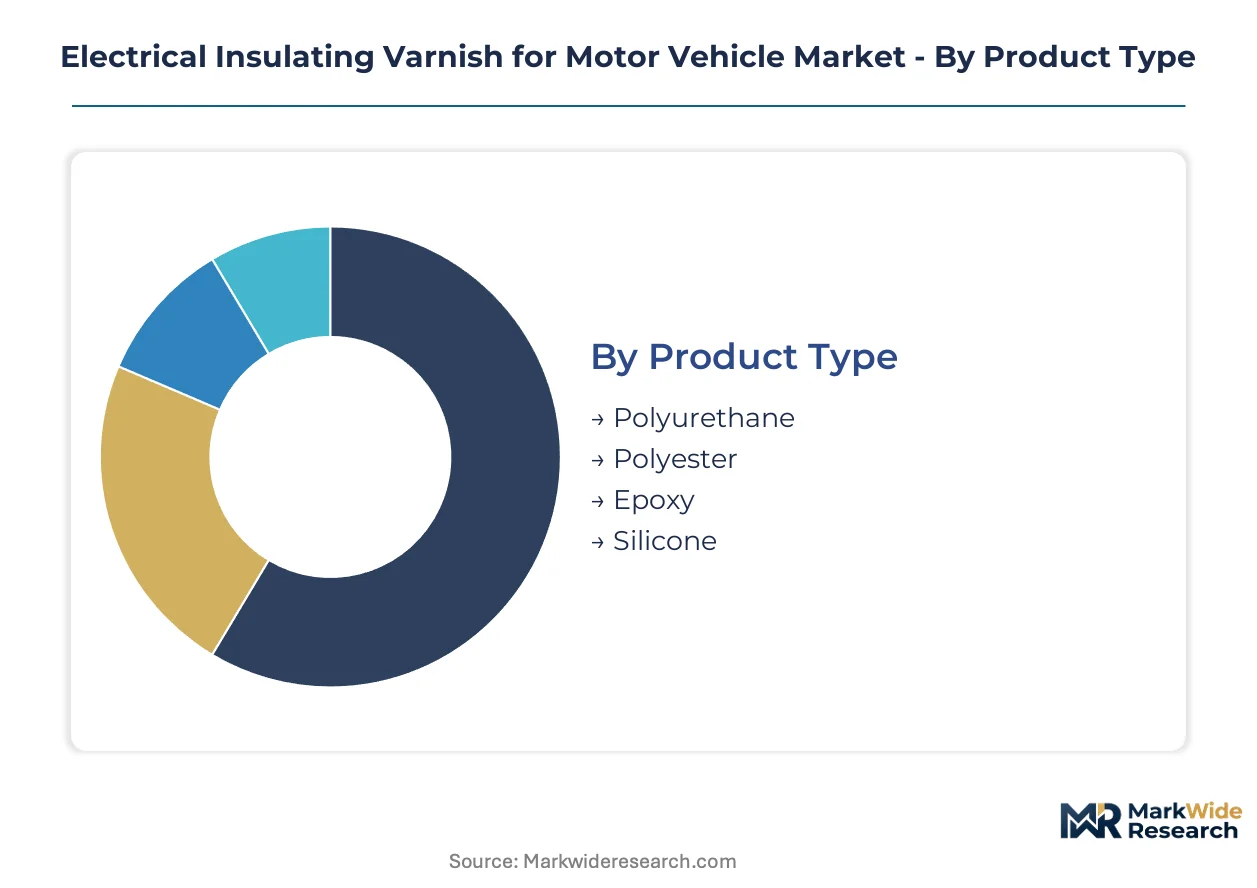
Segmentation in electrical insulating varnish for motor vehicles reveals how thermal class requirements, regulatory compliance costs, and coating line retooling investments distribute margin pools unevenly across chemistry types and application methods. Procurement specifications now diver sharply between legacy internal-combustion motor refurbishment and electric traction motor original equipment.
Product Type:
Margin concentration sits with formulations delivering thermal stability above 180°C cure profiles where specification premiums offset petrochemical feedstock volatility.
- Epoxy:Dominant chemistry across OEM electric motor lines due to superior chemical resistance and bond strength at sustained loads above 10,000 rpm. Axalta Coating Systems and Elantas GmbH anchor supply relationships with traction motor manufacturers in Michigan and Stuttgart redesigning architectures for 800V platforms.
- Polyester:Cost-competitive option for starter motor and auxiliary applications in internal-combustion vehicles where thermal loads remain below 155°C. Demand concentrates in aftermarket refurbishment channels across US Midwest manufacturing corridors where legacy equipment persists.
- Polyurethane:Flexible film characteristics suit vibration-intensive environments in commercial vehicle alternators.
- Silicone:Premium thermal stability commands price multiples for high-performance EV platforms; Momentive Performance Materials competes on this chemistry.
The dominant share belongs to Epoxy, while Silicone is closing the gap fastest among premium EV platform specifications.
Application:
Volume throughput clusters with processes compatible with automated stator winding lines and dip-and-bake coating equipment.
- Insulation:Core dielectric barrier function preventing inter-turn short circuits in copper windings. IEC 60034-18-41 partial discharge resistance testing extends qualification cycles 12-18 months for this application, favoring suppliers with captive engineering bandwidth in Germany and Japan.
- Coating:Surface protection layer establishing thermal conductivity pathways between stator cores and motor housings. Water-based epoxy dispersions are displacing solvent-borne systems in California and EU coating lines retooling for REACH and EPA volatile organic compound thresholds.
- Adhesive:Bonding agent securing winding end-turns against centrifugal forces at high rotational speeds.
- Encapsulation:Complete potting solutions for power electronics integration with motor control modules.
Insulation commands the largest procurement volume, though Coating exhibits the steepest expansion trajectory as OEMs consolidate dielectric and thermal management functions.
End User:
Specification authority determines margin capture, with entities controlling motor architecture redesign cycles extracting maximum compliance cost absorption from coating suppliers.
- OEMs:Direct procurement of high-voltage winding insulation for proprietary electric traction motor programs. Stuttgart and Munich-based manufacturers are redesigning motor architectures for next-generation hybrid and battery-electric platforms, pulling specialized formulation demand.
- Tier-1 Suppliers:Intermediate specification holders translating OEM thermal class requirements into coating line protocols. These entities concentrate in German automotive supply clusters with REACH-compliant resin formulation capabilities.
- Vehicle Assemblers:Final integration points where varnish compatibility with transmission-grade thermal fluids is prioritized for oil-immersed stator cooling systems.
- Aftermarket Providers:Fragmented demand for starter motor refurbishment in legacy internal-combustion vehicle parc.
OEMs retain dominant specification authority, while Tier-1 Suppliers are gaining procurement influence fastest as motor manufacturing consolidates among specialized powertrain integrators.
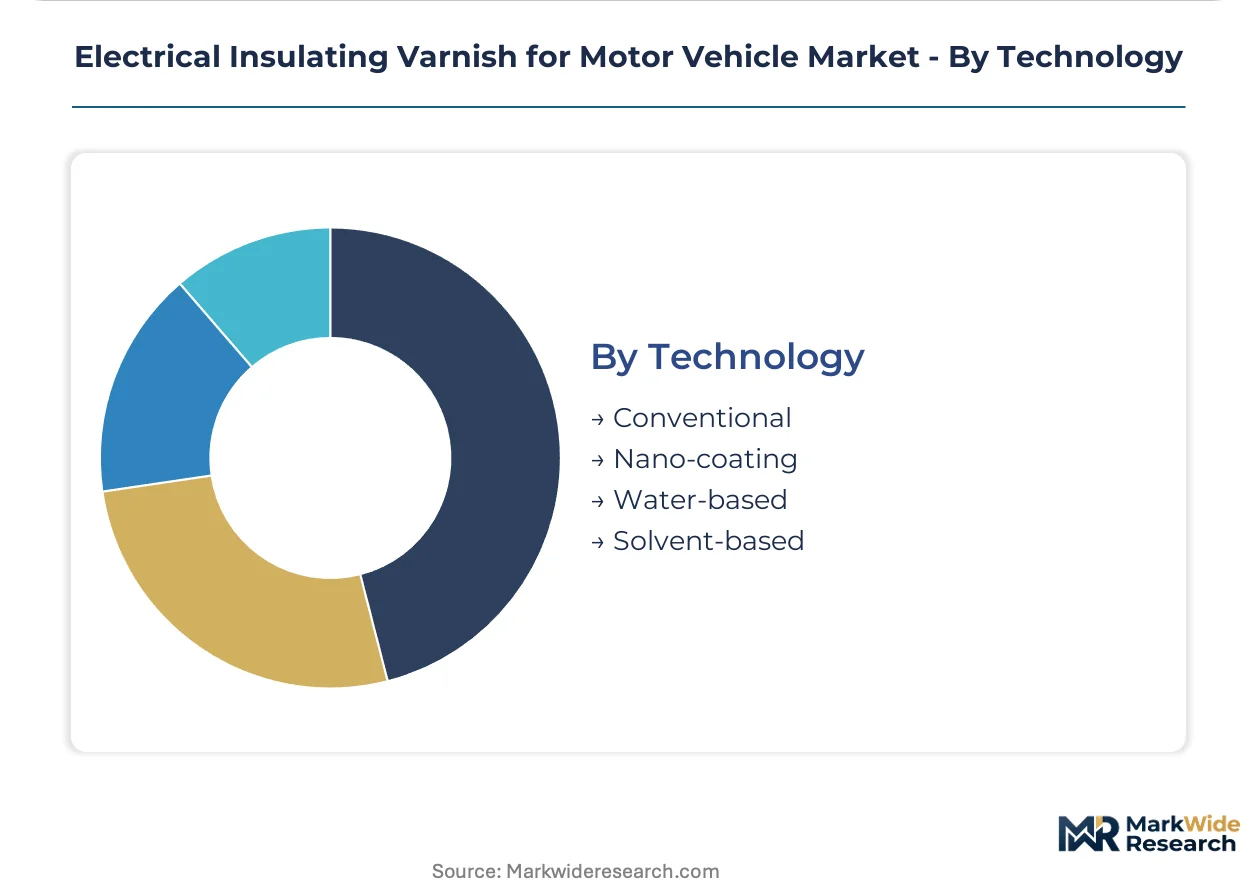
Technology:
Regulatory compliance timelines are concentrating investment returns with aqueous formulation platforms that eliminate volatile organic compound exposure without sacrificing film uniformity.
- Water-based:Aqueous epoxy and polyurethane dispersions curing at 130°C to 180°C. European and North American motor assemblers adopt at accelerated pace to meet ECHA substance of very high concern listings and California Air Resources Board rules.
- Solvent-based:Traditional aromatic diluent systems facing elimination from cost-competitive formulation options under REACH restrictions.
- Nano-coating:Emerging ultra-thin dielectric layers for 800V architectures requiring reduced thermal resistance.
- Conventional:Legacy dip-and-bake processes requiring substantial capital redeployment to handle water-based viscosity characteristics.
Water-based technology holds dominant regulatory tailwinds, while Nano-coating is advancing fastest toward qualification for next-generation high-voltage platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German resin formulators export specialized high-voltage winding insulation to US and Chinese electric powertrain manufacturers as vehicle electrification accelerates across three continents.
United States
NHTSA fuel economy mandates compel Michigan-based motor designers to specify higher thermal class insulations for domestic electric traction motor production. EPA emission thresholds tighten thermal management requirements across automotive assembly lines in the Midwest manufacturing corridor. Detroit-area OEMs are redesigning motor architectures for next-generation battery-electric platforms, pulling specialized varnish procurement from established coating suppliers.
Germany
Stuttgart and Munich-based manufacturers anchor European demand for 800V traction motor insulation systems as hybrid and battery-electric platforms multiply. REACH restrictions on solvent-based chemistries force reformulation investments that favor suppliers with captive resin synthesis capabilities. The Baden-Württemberg automotive cluster concentrates REACH-compliant formulation expertise among specialized chemical specialists serving Tier-1 powertrain integrators.
China
MIIT new energy vehicle production quotas drive copper winding temperature specifications beyond legacy internal-combustion motor limits in Yangtze River Delta assembly plants. GB standards for electric vehicle components elevate dielectric performance requirements across domestic motor manufacturing. Shanghai and Shenzhen-based powertrain producers are expanding procurement of high-temperature insulating coatings for export-qualified traction motor programs.
Japan
METI carbon neutrality roadmaps accelerate stator-direct cooling convergence in Nagoya-area motor manufacturing for premium hybrid platforms. JIS standards for high-voltage motor insulation extend qualification cycles for partial discharge resistance testing. Toyota City and surrounding Aichi Prefecture clusters concentrate engineering bandwidth for IEC 60034-18-41 certification among established varnish suppliers.
India
PLI scheme incentives for electric vehicle component production attract traction motor assembly investments lacking established local varnish supply relationships. BIS certification timelines for imported insulating materials create first-mover advantage for domestic formulation partnerships. Tamil Nadu and Maharashtra manufacturing corridors are emerging as procurement destinations for water-based coating technologies compatible with retooled assembly lines.
Electrical Insulating Varnish for Motor Vehicle Market Vendor Landscape
Player mix skews toward diversified coating conglomerates with captive resin synthesis capabilities and specialized chemical subsidiaries focused on high-voltage motor insulation. Market structure concentrates procurement relationships among German and North American suppliers possessing regulatory compliance documentation for REACH and EPA thresholds. Three archetypes dominate: integrated resin manufacturers with backward control over petrochemical feedstocks, automotive coating specialists leveraging OEM relationships, and silicone-based thermal stability providers serving premium EV platforms. Competitive moves center on water-based formulation licensing and strategic partnerships with stator-direct cooling system integrators.
Within the integrated resin manufacturer tier, Elantas GmbH and Momentive Performance Materials exemplify divergent chemistry strategies for high-voltage winding insulation. Axalta Coating Systems anchors the automotive coating specialist archetype through established OEM relationships across electric traction motor programs. Among diversified chemical conglomerates, 3M Company occupies a position spanning multiple insulation technology vectors without single-chemistry dependency.
| Leading Market Players |
|---|
| Axalta Coating Systems |
| 3M Company |
| Elantas GmbH |
| Momentive Performance Materials |
| Nitto Denko Corporation |
| Hitachi Chemical (Resonac Holdings) |
| Von Roll Holding AG |
| PPG Industries |
| Kyocera Corporation |
| Others |
Supply Flow & Price Mechanics
Long-term offtake contracts between German resin formulators and Stuttgart-based OEMs lock in both supply access and price visibility across 800V traction motor programs, insulating procurement teams from benzene derivative volatility while committing volumes through platform redesign cycles.
Pricing Analysis
Current-generation water-based epoxy formulations command 15-25% premiums over prior-generation solvent-borne systems, while next-generation nano-coating technologies remain pre-commercial with qualification-stage pricing. Three-tier pricing structure across premium silicone, standard epoxy, and economy polyester chemistries stratifies by thermal class certification and volume commitment scale. Pricing pressure stems from REACH-compliant reformulation costs that non-integrated suppliers cannot absorb, compressing margins in the mid-market epoxy tier. Tier-1 powertrain integrators exhibit lowest price sensitivity due to pass-through mechanisms with OEMs, while aftermarket refurbishment channels in the US Midwest face acute cost compression.
Supply Chain Analysis
Germany and Switzerland anchor REACH-compliant resin formulation capabilities, while China and Japan concentrate high-volume epoxy synthesis for domestic powertrain production. Benzene, propylene derivatives, and specialized amine hardeners constitute critical input dependencies, with feedstock sourcing tethered to petrochemical complexes in the US Gulf Coast and Rotterdam. Single-source vulnerability concentrates among German chemical specialists holding ECHA documentation for high-voltage winding insulation, exposing non-European OEMs to export license risk. Distribution runs through Tier-1 powertrain integrators who consolidate specification authority and coating line protocols before final delivery to vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicone-based thermal stability solutions threaten epoxy dominance in premium EV platforms above 800V architectures, forcing incumbent suppliers to defend formulation lock-in through certification depth and captive resin synthesis.
For Market Incumbents: Consolidate procurement relationships with German OEMs by securing IEC 60034-18-41 certification bandwidth ahead of platform redesign cycles, while deepening backward integration into benzene derivative supply to offset petrochemical volatility. Prioritize water-based formulation licensing to capture California Air Resources Board and EPA compliance premiums before solvent-borne alternatives face complete phase-out. For New Entrants and Emerging Players: Technical service gaps in stator-direct cooling compatibility testing create white-space opportunity for specialized engineering consultancies supporting 800V motor qualification. Target India's Tamil Nadu and Maharashtra manufacturing corridors where PLI scheme incentives attract traction motor assembly without established varnish supply relationships, offering water-based coating line retooling partnerships as the primary go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward integrated resin manufacturers possessing captive synthesis capabilities and REACH documentation depth, as regulatory compliance moats widen against non-integrated competitors. Long-term viability hinges on exposure to 800V platform proliferation rather than legacy internal-combustion motor refurbishment exposure. Monitor ECHA substance of very high concern listing velocity as the critical inflection signal for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Petrochemical Feedstocks | Captive benzene derivative supply insulates margin compression from Rotterdam spot market volatility. |
| Water-Based Formulation Licensing | Technology transfer agreements capture California Air Resources Board compliance premiums in retooled coating lines. |
| IEC 60034-18-41 Certification Investment | Partial discharge resistance testing bandwidth extends supplier-engineering relationships through 18-month qualification cycles. |
| Stator-Direct Cooling System Partnership | Hybrid insulation specification alignment with transmission-grade thermal fluid compatibility opens 800V architecture procurement. |
| India Manufacturing Joint Venture | Domestic formulation partnerships overcome BIS certification timelines for PLI scheme traction motor investments. |
Methodological Framework
The analysis maps epoxy, polyester, polyurethane, and silicone formulation sub-sectors, each validated through motor design engineers, Tier-1 procurement leads, coating line operators, and regulatory compliance officers across Germany, the United States, China, and Japan. Primary intelligence combined structured interviews with secondary validation against SEC 10-K filings, ECHA substance registration databases, MIIT new energy vehicle production disclosures, and customs trade data for benzene derivative flows. Bottom-up volume triangulation against top-down OEM platform deployment estimates ensured segment-level consistency.
Consistency checks validated volume and value outputs against IHS Markit vehicle production databases, regional powertrain assembly counts, and coating content-per-motor assumptions across the projection horizon. Segmentation modeling incorporated chemistry type, application method, thermal class tier, and regional regulatory cluster dimensions. CAGRs derived from compound growth mechanics applied to base-year market sizing, with sensitivity analysis around EV penetration trajectories and REACH implementation timelines as key forecast inputs.
Forecasts assume regulatory continuity in EPA emission thresholds, REACH substance restrictions, and MIIT production quotas; material policy shifts in these regimes would require re-modeling. Specific risks include faster-than-anticipated silicone substitution in premium platforms, ECHA expansion of very high concern listings, and NHTSA fuel economy mandate relaxation. Recalibration cycles align with material shifts in OEM platform electrification roadmaps and ECHA regulatory publication schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Sphingolipids Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Acetyl Isovaleryl Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
Ascorbic Acid Market
Specialty Chemicals
Global Cyclodextrin Market
Specialty Chemicals
VCI Aerosol Market
Specialty Chemicals
Halogen-Free Flame Retardants Market
Specialty Chemicals
Methyltrimethoxysilane Market
Specialty Chemicals
Sandarac Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Ferrous Gluconate Market
Specialty Chemicals
Micronized PTFE Market
Specialty Chemicals
Dimethyl Succinyl Succinate Market
Specialty Chemicals
Global Release Agents Market
Specialty Chemicals
Fluoroethylene Carbonate (FEC) Market