
 Single-Domain Antibody Platforms Market | 2026-2036
Single-Domain Antibody Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Domain Antibody Platforms Market Analytics
Specialized protein engineering talent is rotating toward single-domain antibody platforms as traditional monoclonal pipelines face productivity constraints. GenScript leverages its mammalian expression infrastructure to sustain high-throughput nanobody production for global clients. Creative BioLabs anchors its competitive position through deep specialization in camelid-derived VHH libraries. BioCat GmbH competes by controlling distribution channels across European research institutes.
Single-domain antibody platforms comprise recombinant and engineered binding proteins derived from the variable heavy-chain domain of heavy-chain-only antibodies, typically featuring molecular weights near 15 kDa and enhanced thermal stability for tissue penetration and modular formatting in therapeutic constructs. Their primary commercial purpose centers on enabling next-generation biologics with simplified manufacturing, reduced immunogenicity risk, and superior targeting of cryptic epitopes compared to conventional immunoglobulin architectures. Nanobodies within the product type spectrum capture expanding margin pools as pharmaceutical sponsors prioritize smaller-format candidates for solid tumor indications and blood-brain barrier traversal. Phage display technology dominates discovery workflows, though yeast display is gaining traction for its eukaryotic folding quality control and direct fluorescence-activated sorting capabilities.
FDA oversight of investigational new drug applications shapes clinical entry timelines and manufacturing quality standards for platform-derived candidates, while EMA's evolving guidance on biologic comparability influences European partnership structures. ISO 13485 certification requirements for diagnostic applications constrain market access for unqualified suppliers. Stakeholders must monitor emerging regulatory clarity around nanobody immunogenicity assessment frameworks and position manufacturing investments accordingly.
Market Dynamics
Pharmaceutical sponsors are compressing discovery timelines by migrating from hybridoma-based monoclonal pipelines to single-domain antibody platforms, driven by the imperative to access cryptic epitopes in solid tumor targets and central nervous system indications.
Growth Catalysts
- FDA Breakthrough Therapy designation:Accelerated clinical pathways for nanobody candidates reduce regulatory friction and compress time-to-market for sponsors developing blood-brain barrier penetrant therapeutics.
- Solid tumor targeting:Enhanced tissue penetration of 15 kDa VHH formats enables access to stromal and intracellular epitopes unreachable by conventional immunoglobulin architectures.
- Yeast surface display:Eukaryotic folding quality control and direct fluorescence-activated sorting capabilities are displacing bacterial expression systems in high-throughput screening workflows.
Market Restraints
- Camelid immunogen supply concentration:Dependence on llama and alpaca serum sources creates vulnerability to veterinary disease outbreaks and geographic sourcing limitations in South American breeding operations.
- Immunogenicity assessment frameworks:Absence of standardized nanobody-specific regulatory guidelines forces sponsors into costly case-by-case immunogenicity risk evaluations with FDA and EMA.
- Manufacturing scale-up costs:Transition from research-grade to GMP-compliant microbial or mammalian expression requires capital-intensive facility retrofits and specialized downstream processing equipment.
Strategic Opportunities
- Intracellular target engagement:VHH formats capable of cytosolic delivery open therapeutic modalities against previously undruggable intracellular protein-protein interactions.
- India CDMO expansion:Contract development and manufacturing organizations in Hyderabad and Bangalore are building nanobody-specific bioprocessing capabilities to capture outsourced production from Western sponsors.
- Companion diagnostic convergence:Single-domain antibody platforms enable dual-purpose reagent development where the same VHH clone serves both therapeutic and imaging applications.
Industry Challenges
- Protein engineering talent scarcity:Specialized expertise in camelid immunology and phage display library construction concentrates at a limited number of academic institutions and platform technology companies.
- ISO 13485 certification timelines:Diagnostic application suppliers face extended quality management system audits that delay market entry for in vitro diagnostic-grade nanobody reagents.
- Intellectual property fragmentation:Dense patent thickets surrounding VHH humanization methods and half-life extension technologies complicate freedom-to-operate analyses for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Domain Antibody Platforms Market |
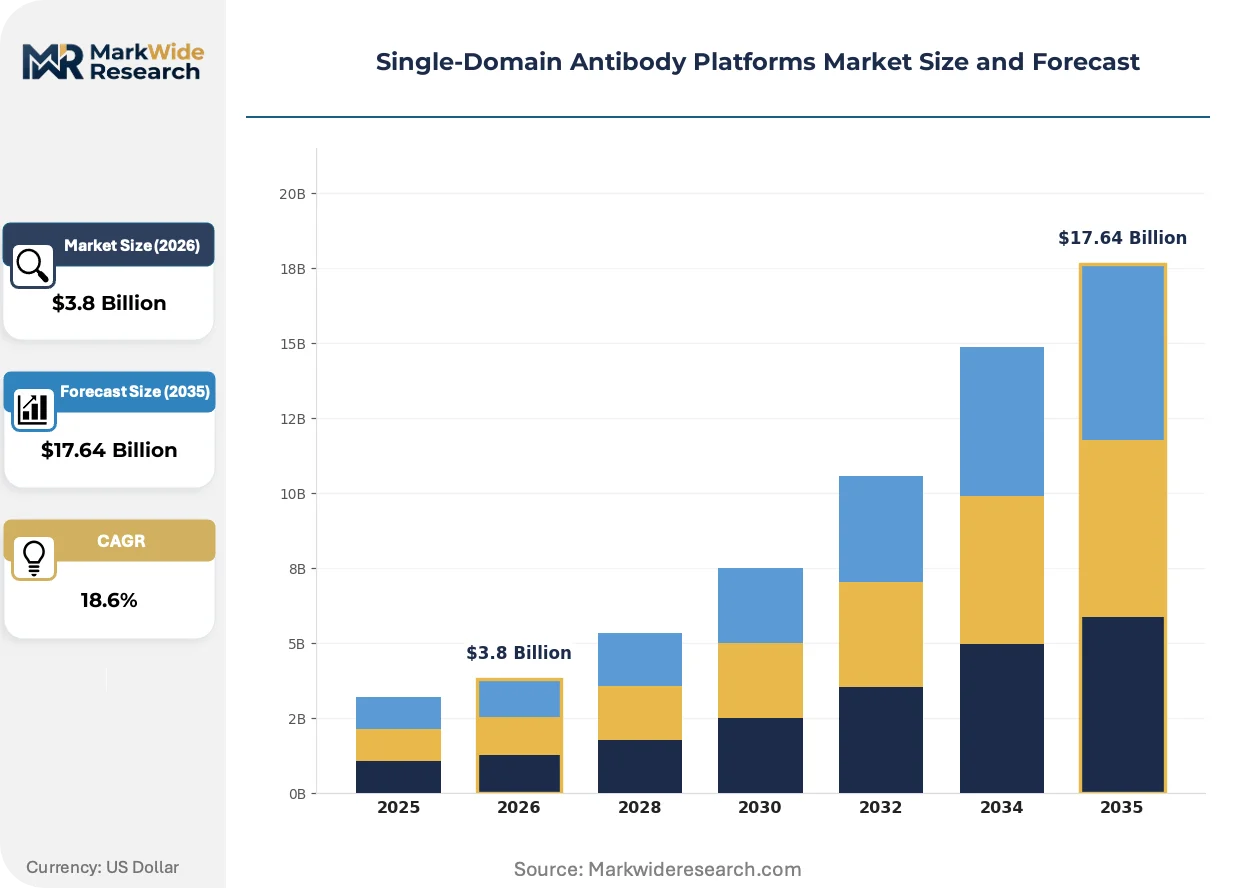
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Recombinant Antibodies, Monoclonal Antibodies, Polyclonal Antibodies, Nanobodies End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Contract Research Organizations Application: Diagnostics, Therapeutics, Research, Laboratory Use Technology: Phage Display, Yeast Display, Ribosome Display, Surface Display |
| Companies Covered | BioCat GmbH, GenScript, Creative BioLabs, Rockland Immunochemicals Inc, Oak BioSciences Inc, Synbio Technologies, Antibody Design Labs, Hybrigenics Services, ProSci Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Domain Antibody Platforms Market Evolving Landscape
Platform engineering is converging with synthetic biology to enable programmable nanobody formats that integrate effector functions, half-life modulation, and tissue-specific targeting within single genetic constructs.
Next-generation phage display libraries incorporating synthetic codon diversification and error-prone PCR mutagenesis are decomposing the traditional immunization-dependent discovery paradigm. Contract research organizations in Belgium and the Netherlands are adopting these synthetic libraries to eliminate the 8-12 week immunization phase. This compression is enabling rapid response capabilities for emerging infectious disease targets and pandemic preparedness programs.
EMA's evolving guidance on biologic comparability and immunogenicity risk assessment is reshaping partnership structures between European academic centers and pharmaceutical sponsors. Sponsors now front-load immunogenicity characterization studies to preempt regulatory queries during scientific advice procedures. This shift most affects oncology programs where repeated dosing cycles amplify immunogenicity signal detection requirements.
Biopharmaceutical procurement departments are consolidating vendor relationships around platform technology providers offering integrated discovery-to-GMP manufacturing services. Large-cap sponsors are displacing fragmented supplier networks with preferred partnerships that bundle phage display library access, hit-to-lead optimization, and regulatory dossier preparation. This concentration is most visible in the Boston-Cambridge and San Francisco Bay Area clusters where venture-funded biotechs prioritize speed over cost minimization.
Single-Domain Antibody Platforms Market Segmentation
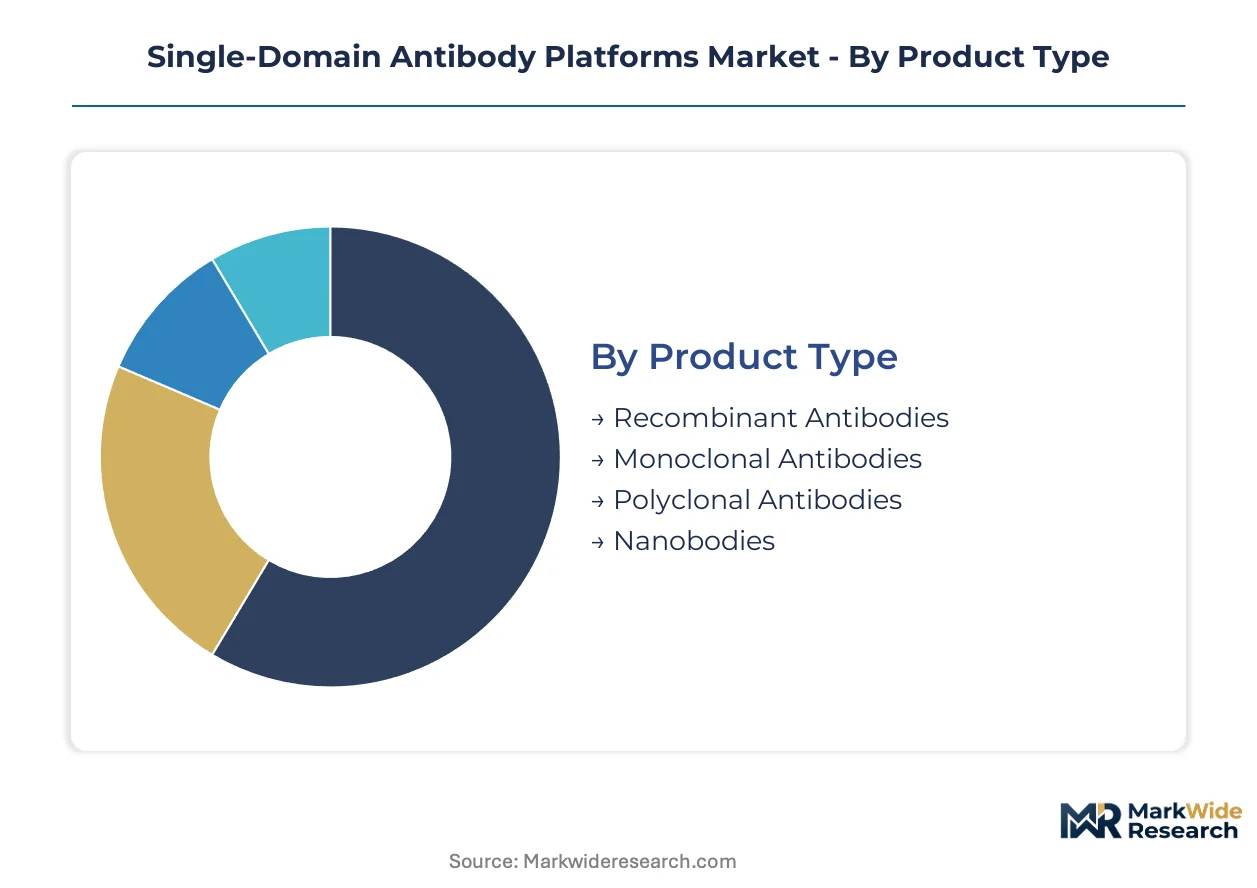
Single-domain antibody platforms fragment across four structural dimensions that determine competitive positioning and margin capture. Product type and technology selection drive manufacturing economics, while end-user concentration and application mix shape pricing power and partnership structures.
Product Type:
Recombinant formats face intensifying substitution pressure from synthetic library-derived nanobodies that bypass immunization bottlenecks entirely.
- Nanobodies:Derived from camelid VHH domains with 15 kDa molecular weight and enhanced thermal stability. Demand concentrates among pharmaceutical sponsors developing blood-brain barrier penetrant therapeutics, driven by FDA Breakthrough Therapy pathway acceleration for solid tumor indications.
- Recombinant Antibodies:Engineered binding proteins produced through microbial or mammalian expression systems. Biotechnology firms in the Boston-Cambridge cluster prioritize these for modular formatting flexibility and simplified GMP manufacturing scale-up.
- Monoclonal Antibodies:Traditional immunoglobulin architectures facing displacement pressure from smaller-format alternatives in tissue penetration applications.
- Polyclonal Antibodies:Heterogeneous serum-derived reagents retaining niche demand in diagnostic reference standards and veterinary applications.
Nanobodies retain volume leadership; recombinant antibodies hold the steepest expansion curve as synthetic biology compresses discovery timelines.
End User:
Procurement concentration among large-cap sponsors is forcing vendor consolidation around integrated discovery-to-GMP service providers.
- Pharmaceutical Companies:Multinational sponsors with internal biologics pipelines. These buyers dominate contract value, prioritizing platform providers with regulatory dossier preparation capabilities and established FDA interaction histories.
- Biotechnology Firms:Venture-funded developers in San Francisco Bay Area and Basel clusters. Speed-to-IND dominates vendor selection over unit cost, with preference for phage display libraries offering rapid hit identification.
- Research Institutes:Academic centers with limited commercial manufacturing requirements.
- Contract Research Organizations:Service providers building nanobody-specific capabilities to capture outsourced discovery from Western sponsors.
Pharmaceutical companies anchor procurement volume; biotechnology firms are expanding most quickly as venture funding concentrates in platform-enabled modalities.
Application:
Therapeutic applications command premium pricing multiples that diagnostics cannot approach, creating a two-tier margin structure.
- Therapeutics:Clinical-stage biologics targeting oncology and central nervous system indications. Sponsors front-load immunogenicity characterization to preempt EMA scientific advice queries, with repeated dosing cycles amplifying signal detection requirements.
- Diagnostics:In vitro diagnostic-grade reagents requiring ISO 13485 certification. Quality management system audits extend market entry timelines, constraining supplier participation to qualified platform providers.
- Research:Discovery-grade reagents with minimal regulatory burden.
- Laboratory Use:Standard analytical applications with commodity pricing dynamics.
Therapeutics captures the dominant value share; diagnostics climbs the fastest as companion diagnostic convergence creates dual-purpose reagent demand.
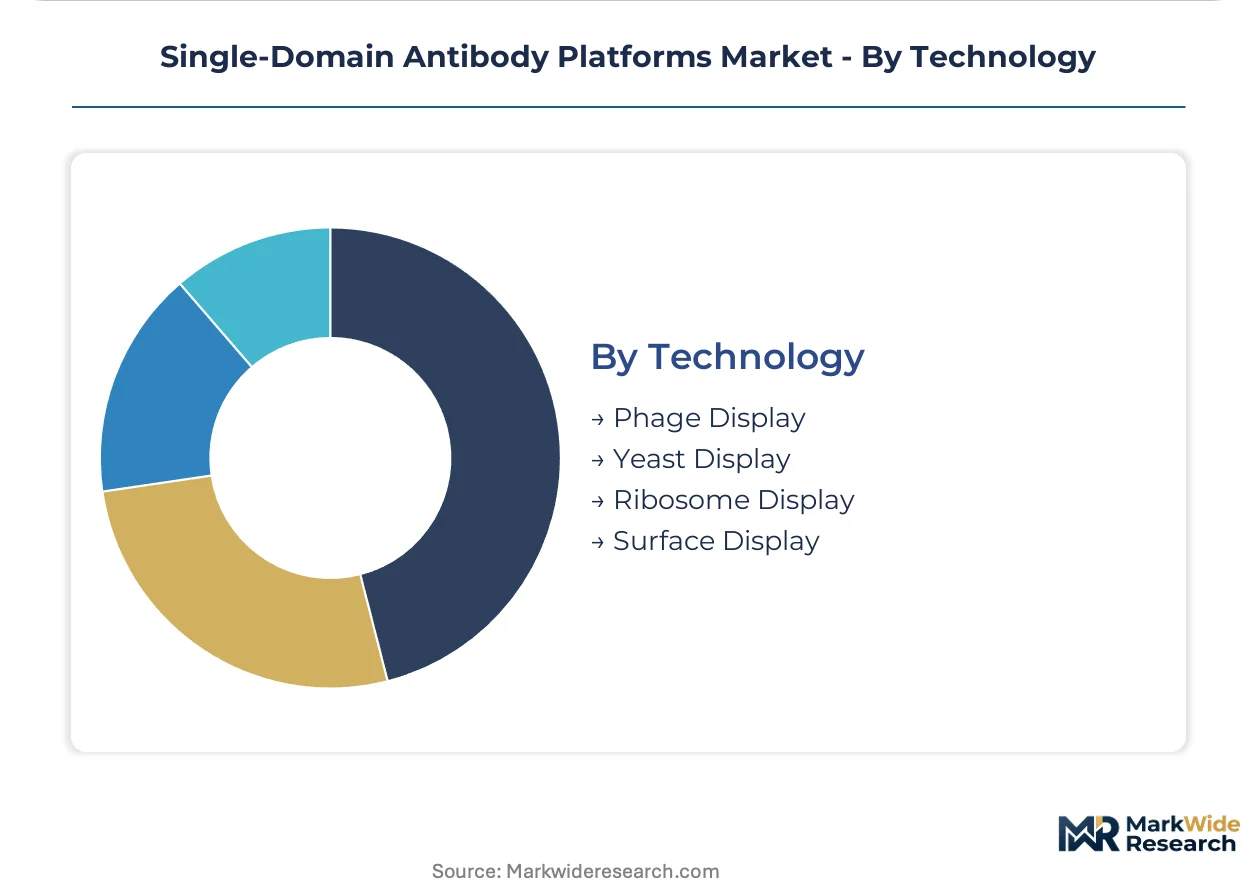
Technology:
Display technology selection determines folding fidelity, screening throughput, and ultimate clinical manufacturability of platform-derived candidates.
- Phage Display:Bacteriophage-based screening with mature protocol libraries and extensive validation data. Contract research organizations in Belgium and the Netherlands leverage synthetic codon diversification to eliminate the 8-12 week immunization phase.
- Yeast Display:Saccharomyces cerevisiae surface expression with eukaryotic quality control. Direct fluorescence-activated sorting capabilities are displacing bacterial systems in high-throughput workflows, particularly for complex membrane targets.
- Ribosome Display:In vitro selection without cellular transformation constraints.
- Surface Display:Alternative bacterial and mammalian display formats with niche application.
Phage display maintains installed base dominance; yeast display gains share fastest as sponsors prioritize eukaryotic folding fidelity for clinical candidate quality.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA oversight of investigational new drug applications anchors the dominant geography, with breakthrough therapy designations accelerating clinical entry for nanobody candidates. Venture funding concentrates in established biotech clusters, while European and Asian regulators develop competing frameworks for biologic comparability.
United States
Pharmaceutical sponsors prioritize speed-to-IND over unit cost in the Boston-Cambridge and San Francisco Bay Area clusters. FDA Breakthrough Therapy pathways compress regulatory timelines for blood-brain barrier penetrant therapeutics. The Greater Boston metropolitan area hosts concentrated venture-funded biotechs building internal nanobody discovery capabilities.
Belgium
Contract research organizations leverage synthetic codon diversification to eliminate the 8-12 week immunization phase entirely. EMA scientific advice procedures front-load immunogenicity characterization requirements for repeated dosing oncology programs. Flanders-based service providers capture outsourced discovery work from Western pharmaceutical sponsors.
Netherlands
Yeast surface display adoption accelerates among Dutch research institutes prioritizing eukaryotic folding quality control. The country's national pharmaceutical regulator aligns with evolving EMA guidance on biologic comparability assessments. Amsterdam and Utrecht host specialized phage display library providers serving European biotechnology firms.
China
NMPA oversight of biologics manufacturing quality standards shapes partnership structures for domestic platform technology providers. The Yangtze River Delta region concentrates contract development organizations building nanobody-specific bioprocessing capabilities. Shanghai-based sponsors prioritize GMP-compliant microbial expression scale-up for export markets.
India
CDSCO regulatory pathways for biosimilar development create demand for qualified single-domain antibody reagents in diagnostic applications. Hyderabad and Bangalore contract manufacturing organizations invest in specialized downstream processing equipment for nanobody production. Karnataka's biotechnology corridor attracts Western sponsor outsourcing for cost-sensitive discovery programs.
Single-Domain Antibody Platforms Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with procurement departments consolidating vendor relationships around platform providers offering bundled discovery-to-GMP services. The vendor base separates into three archetypes: mammalian expression infrastructure operators, camelid-derived library specialists, and distribution channel controllers. Capacity expansion and strategic partnerships dominate competitive moves as sponsors displace fragmented supplier networks with preferred partnerships.
Among integrated service providers, GenScript anchors the mammalian expression infrastructure archetype, while Creative BioLabs exemplifies deep specialization in camelid-derived VHH libraries. BioCat GmbH occupies a position within the distribution-focused tier, controlling European research institute channels. These three entities represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| BioCat GmbH |
| GenScript |
| Creative BioLabs |
| Rockland Immunochemicals Inc |
| Oak BioSciences Inc |
| Synbio Technologies |
| Antibody Design Labs |
| Hybrigenics Services |
| ProSci Incorporated |
| Others |
Value Network & Pricing Analysis
ISO 13485 certification gates both supply qualification and price differentiation simultaneously, as diagnostic-grade nanobody reagents command premium positioning over research-grade alternatives while unqualified suppliers face exclusion from in vitro diagnostic partnerships entirely. Pharmaceutical sponsors absorb higher unit costs for GMP-compliant microbial expression to secure FDA-enabled clinical trial pathways, compressing margins for contract manufacturers unable to cross the certification threshold.
Pricing Analysis
Geographic price spreads widen between United States biotechnology clusters and Indian contract manufacturing operations, with Boston-Cambridge sponsors prioritizing speed-to-IND over unit cost. Project-based pricing dominates discovery services, while licensing arrangements govern therapeutic candidates reaching clinical stages. Price differentiation rests on GMP certification tier and regulatory dossier preparation capabilities, with ISO 13485-qualified suppliers capturing 40-60% premiums over research-grade competitors. Cost compression in standard discovery-grade reagents intensifies as synthetic phage display libraries commoditize hit identification workflows. Biotechnology firms exhibit lowest price sensitivity; academic research institutes drive hardest bargain negotiations.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes inflate inbound logistics costs for South American camelid serum shipments destined for European phage display library providers. Supply concentrates in Belgium, the Netherlands, and China, with Flanders-based contract research organizations and Yangtze River Delta bioprocessors anchoring global capacity. Raw material dependencies center on llama and alpaca immunogen sources, synthetic codon diversification reagents, and specialized downstream processing resins. Single-source vulnerability in camelid breeding operations exposes discovery timelines to veterinary disease outbreak risks. Distribution runs through integrated platform providers bundling discovery-to-GMP services rather than fragmented vendor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware as regulatory dossier preparation and immunogenicity characterization layers outgrow basic discovery revenues, with sponsors front-loading scientific advice support to preempt EMA queries.
For Market Incumbents: Secure preferred partnership status with large-cap pharmaceutical sponsors by bundling phage display library access with regulatory dossier preparation capabilities. Invest in captive GMP microbial expression capacity in the Yangtze River Delta to displace fragmented supplier networks. Synthetic library commoditization threatens discovery-service margins; counter by deepening half-life extension technology expertise.
For New Entrants and Emerging Players: Differentiate on rapid-response infectious disease capabilities using synthetic codon diversification to eliminate immunization bottlenecks entirely. Target India CDMO expansion in Hyderabad and Bangalore, where Western sponsors outsource cost-sensitive discovery programs. Lead with yeast surface display specialization for complex membrane targets underserved by established phage display providers.
For Investors and Strategic Acquirers: FDA Breakthrough Therapy designation reshapes the acquisition landscape by accelerating clinical entry timelines for nanobody candidates targeting blood-brain barrier penetration. Long-term viability centers on platform providers with integrated discovery-to-GMP footprints spanning three or more regulatory jurisdictions. Acquisition target archetype: specialized yeast display providers with eukaryotic folding quality control capabilities. Signal to watch: EMA publication of nanobody-specific immunogenicity assessment frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Enables FDA IND submissions for blood-brain barrier penetrant therapeutics. |
| Synthetic Library Licensing | Eliminates 8-12 week immunization phases for pandemic response capabilities. |
| Regulatory Dossier Partnership | Front-loads EMA scientific advice preparation for repeated dosing oncology programs. |
| Yeast Display Infrastructure | Captures share from bacterial systems for complex membrane target quality. |
| India CDMO Capacity Buildout | Positions Hyderabad and Bangalore for Western sponsor cost-sensitive outsourcing. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA investigational new drug filings, EMA scientific advice procedures, ClinicalTrials.gov entries, and ISO 13485 certification databases. Primary interviews engaged drug development executives at biotechnology firms, regulatory affairs leads at contract research organizations, hospital procurement managers for diagnostic applications, and camelid breeding operation veterinarians. Secondary validation drew from SEC 10-K disclosures of publicly traded platform providers, patent filings surrounding VHH humanization methods, and trade flow data for specialized bioprocessing equipment. Bottom-up segment sizing triangulates against top-down market envelope estimates.
Segmentation dimensions modeled span product type, end user, application, and technology across the projection horizon. The analytical framework incorporates therapeutic indication clustering, regulatory pathway classification, and manufacturing expression system economics. CAGRs derive from slope analysis of historical adoption curves adjusted for technology substitution effects. Forecast inputs include venture funding concentration patterns in Boston-Cambridge and San Francisco Bay Area clusters, plus CDMO capacity expansion announcements in India and China.
Material uncertainties — camelid disease outbreaks, nanobody-specific immunogenicity guideline publication delays, and trade lane disruption for South American serum sourcing — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory pathway stability and synthetic library performance parity with immunization-dependent methods. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Tamoxifen Market
Biopharmaceuticals
Middle East and Africa Insulin Delivery Devices Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Global Akabane Vaccines Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Protein Therapeutics Market
Biopharmaceuticals
Norethisterone Enanthate API Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Global Human Recombinant Insulin Market