
 Big Data Technology Market | 2026-2036
Big Data Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Technology Market Intelligence
Buyer concentration among large enterprises in sectors like telecommunications and government agencies is hardening the competitive landscape for platform providers. Microsoft leverages its extensive Azure cloud ecosystem to offer integrated data services. Databricks specializes in unified analytics combining data science and engineering workflows. Snowflake differentiates through its multi-cloud data platform architecture, decoupling storage and compute.
Big data technology encompasses the frameworks and software tools designed to process and analyze datasets characterized by high volume, velocity, and variety. These systems, including technologies like Apache Spark and NoSQL databases, enable organizations to extract value from information that overwhelms traditional databases. Hybrid and multi-cloud deployment models are becoming standard for achieving flexibility and avoiding vendor lock-in. While Customer Analytics remains a core application, demand for real-time Fraud Detection and Supply Chain Optimization is accelerating.
Data governance regulations directly influence technology design and deployment strategies across geographies. The EU’s GDPR and the upcoming EU AI Act set stringent rules for data privacy and algorithmic accountability. Similarly, China's Cybersecurity Law imposes data localization requirements. Navigating this fragmented regulatory environment is now a central strategic challenge for vendors and enterprise adopters.
Market Dynamics
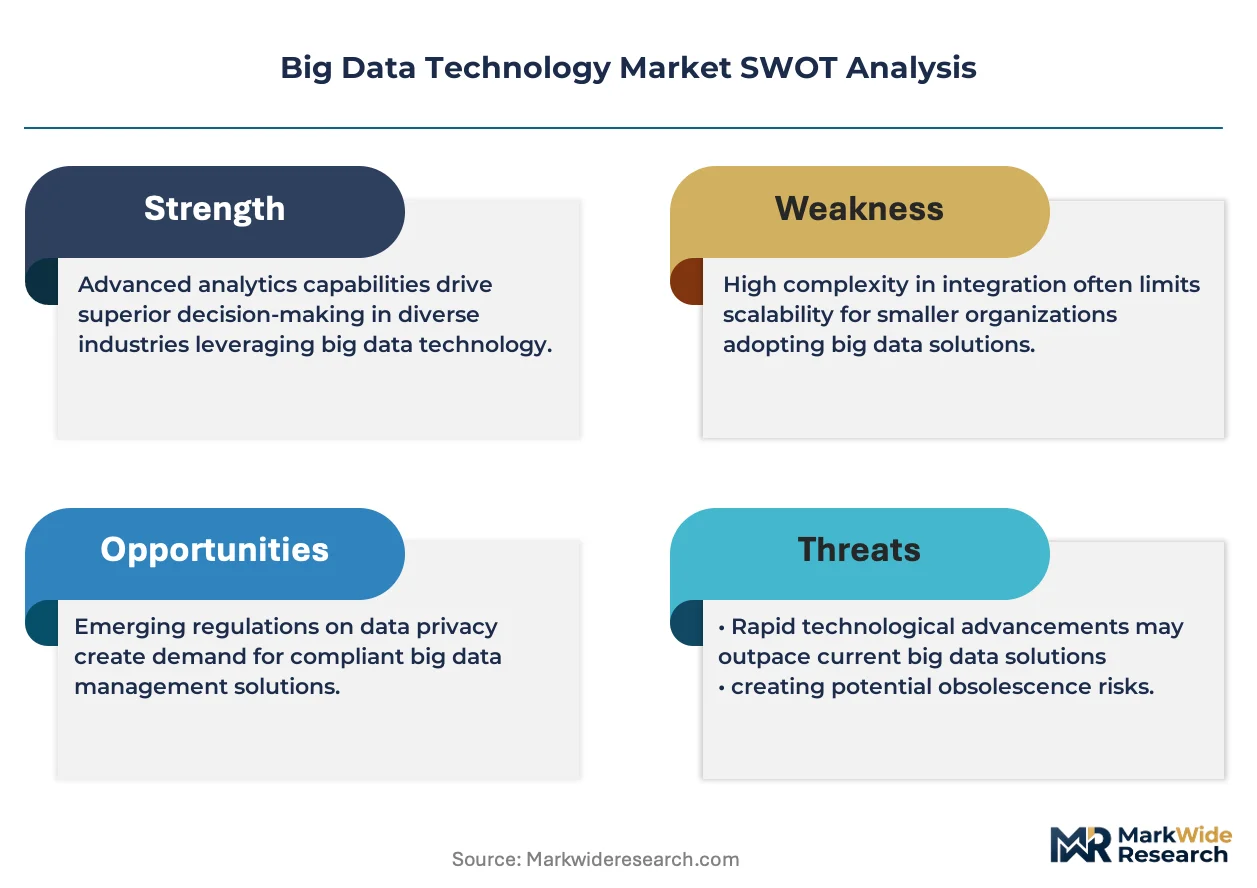
The central dynamic is the tension between demand for flexible, multi-cloud architectures and the fragmented landscape of data governance. Regulations like the EU’s GDPR and China's Cybersecurity Law dictate platform design, forcing a complex balance between global scalability and local compliance.
Growth Catalysts
- Predictive Maintenance:Industrial adoption in Germany's automotive sector drives demand for platforms processing IoT sensor data for asset optimization.
- Real-time Fraud Detection:Financial services and e-commerce sectors require analytics to analyze transaction patterns instantly, meeting AML compliance.
- EU AI Act Preparedness:Enterprises are adopting data governance tools to meet upcoming requirements for algorithmic transparency and risk management.
Market Restraints
- High Compute Costs:Decoupled storage and compute models lead to unpredictable cloud infrastructure costs, deterring smaller enterprises from adoption.
- Data Localization:China's Cybersecurity Law and similar mandates fragment data architectures and increase operational overhead for multinational firms.
- Interoperability Complexity:Integrating modern cloud platforms with legacy on-premise systems remains a significant and costly technical barrier.
Strategic Opportunities
- Southeast Asian Digital Banking:The rise of digital banks in Indonesia and Vietnam creates a greenfield market for mobile-first analytics platforms.
- Supply Chain Digital Twins:Creating virtual models of supply chains for simulation is an emerging application for platforms integrating logistics and inventory data.
- Generative AI Integration:Combining LLMs with enterprise data warehouses offers a new frontier for natural language querying and automated insight generation.
Industry Challenges
- Data Engineering Skill Gaps:A persistent shortage of skilled data and MLOps professionals slows project deployment and increases labor costs.
- Legacy System Integration:Connecting modern platforms with entrenched mainframe databases in banking creates significant implementation friction and extends project timelines.
- Algorithmic Accountability:Complying with the EU AI Act’s rules for high-risk AI systems demands new tools for model auditing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Technology Market |
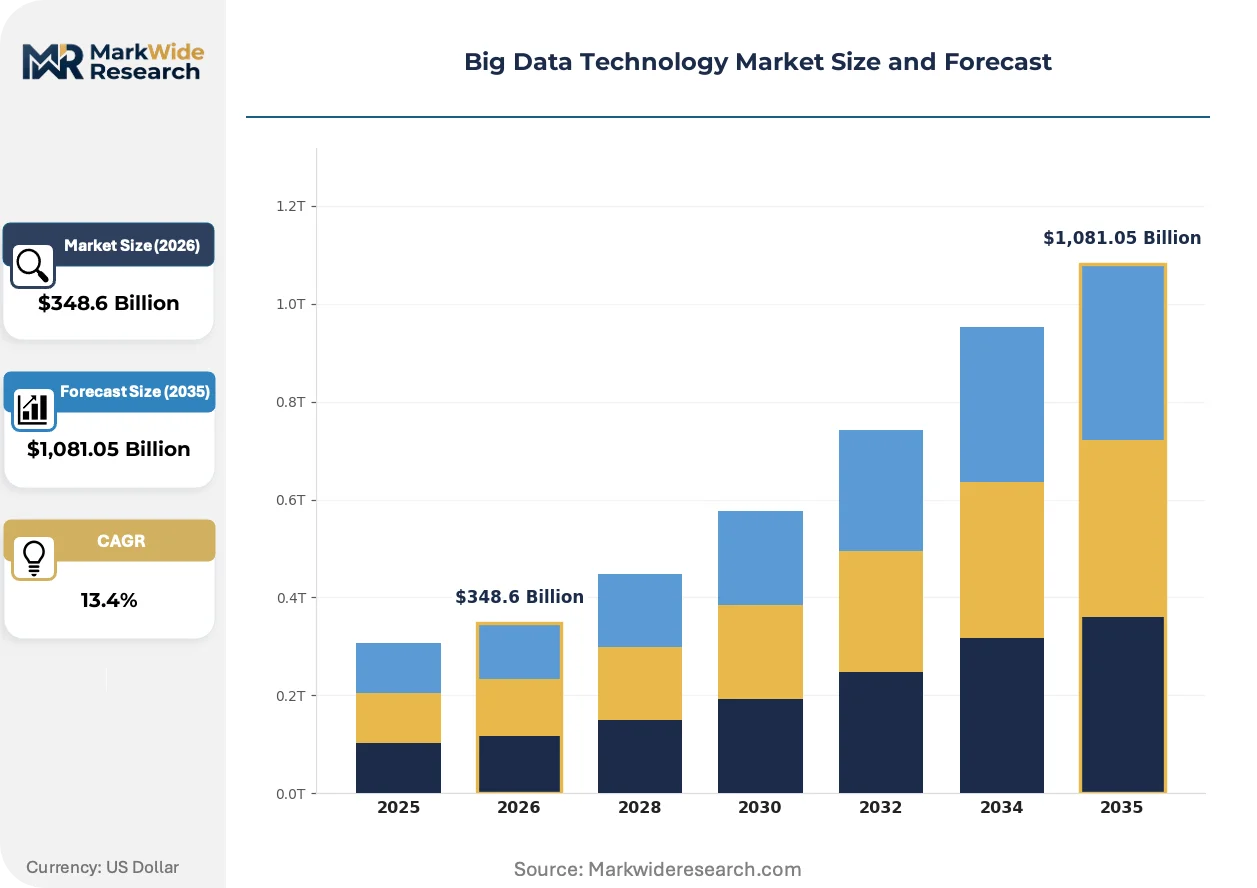
| Market Size in 2026 | $348.6 Billion |
| Market Size in 2035 | $1,081.05 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hadoop, Apache Spark, NoSQL Databases, Stream Processing, In-Memory Analytics, Data Integration Deployment: On-Premise, Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, Edge Computing Application: Customer Analytics, Fraud Detection, Risk Management, Predictive Maintenance, Supply Chain Optimization, Sentiment Analysis End User Industry: Telecommunications, Manufacturing, Government Agencies, Media & Entertainment, Energy & Utilities, Transportation |
| Companies Covered | Databricks, Palantir, Microsoft, Tata Consultancy Services, Accenture, Amazon, Snowflake, Capgemini, Alphabet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Technology Market Strategic Shifts & Innovations
A shift towards composable architectures defines the current market evolution. Organizations are moving away from monolithic platforms, instead assembling best-of-breed components for data ingestion, storage, processing, and analytics to gain flexibility and avoid vendor lock-in.
Data mesh is an architectural paradigm treating data as a product, decentralizing ownership to domain-specific teams. Technology and financial services firms are leading its adoption to improve data agility and overall scalability. This approach is modularizing the traditional central data lake, shifting responsibility from a single data team to distributed domain experts.
The U.S. Federal Trade Commission (FTC) is intensifying enforcement against unfair or deceptive practices related to AI. This regulatory pressure compels companies to implement more transparent and explainable AI (XAI) frameworks. Consumer-facing sectors like lending are most affected, investing in tools that can audit algorithms for bias.
Consumption-based pricing models are displacing traditional software licensing as the preferred procurement method. This model, popularized by cloud data platforms, allows costs to scale directly with compute and storage usage. The trend is most prominent in the United States and Europe among companies aligning operational expenditures with data processing workloads.
Big Data Technology Market Segmentation
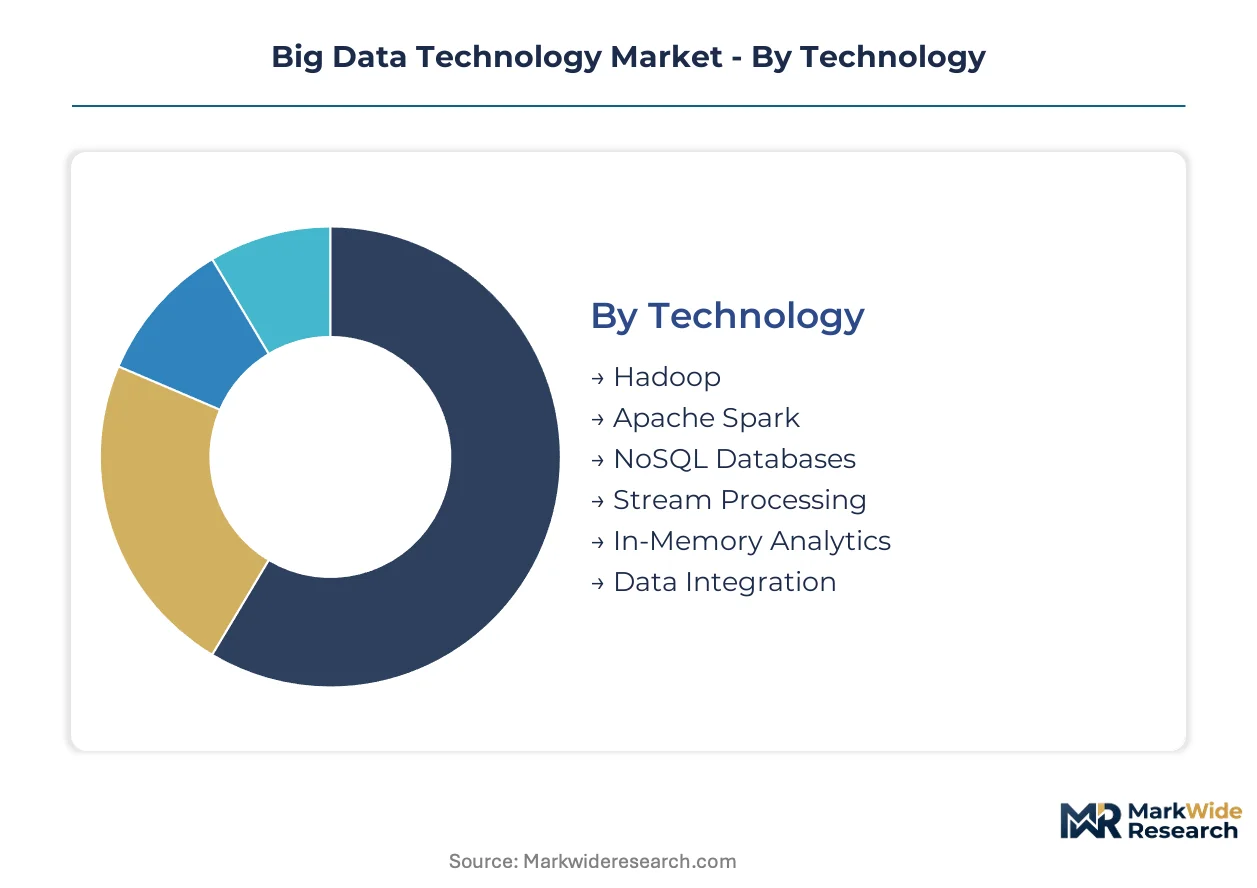
Understanding the Big Data Technology Market requires a granular examination of its constituent parts. This analysis dissects the market across key dimensions, revealing where innovation concentrates and where value accrues. Each segment reflects distinct technological approaches or operational models, influencing adoption patterns across diverse enterprise environments.
Technology:
The technology segment reveals varied capital outlays, with some foundational frameworks demanding substantial infrastructure investments for initial deployment.
- Apache Spark:This open-source unified analytics engine processes large datasets with high speed, supporting SQL, streaming, machine learning, and graph processing. Demand concentrates in financial services for real-time fraud detection, driven by the need for low-latency transaction analysis.
- NoSQL Databases:These non-relational databases offer flexible schemas and horizontal scalability, handling unstructured and semi-structured data efficiently. Enterprises in e-commerce and social media adopt them widely for managing vast volumes of user-generated content and personalization data.
- Hadoop:This framework enables distributed processing of large datasets across clusters of commodity hardware.
- Stream Processing:Technologies in this segment analyze data in motion, providing immediate insights from continuous data streams.
- In-Memory Analytics:These systems store data in RAM for rapid query response, accelerating complex analytical operations.
- Data Integration:This category encompasses tools and processes for combining data from disparate sources into a unified view.
Hadoop absorbs the bulk of installed capacity; Apache Spark is expanding most quickly.
Deployment:
Deployment models offer varying degrees of flexibility and control, influencing how organizations manage data sovereignty and operational scalability.
- Hybrid Cloud:This model combines private cloud infrastructure with public cloud services, allowing data and applications to be shared between them. Enterprises in Germany leverage hybrid deployments for predictive maintenance, balancing sensitive industrial data with scalable compute resources.
- Multi-Cloud:This strategy involves using multiple cloud computing services from different providers within a single architecture. Companies in the United States adopt multi-cloud for vendor lock-in avoidance and resilience, distributing workloads across AWS, Azure, and Google Cloud.
- On-Premise:Data infrastructure and applications are hosted and managed within an organization's own facilities.
- Public Cloud:Cloud services are delivered over the internet by a third-party provider, offering high scalability and pay-as-you-go pricing.
- Private Cloud:Dedicated cloud infrastructure is used exclusively by a single organization, offering enhanced security and control.
- Edge Computing:Data processing occurs closer to the data source, reducing latency and bandwidth usage for real-time applications.
Hybrid Cloud dominates market share; Multi-Cloud exhibits the steepest expansion trajectory.
Application:
The application segment highlights the diverse strategic objectives enterprises pursue, from optimizing internal operations to enhancing customer engagement.
- Predictive Maintenance:This application uses data analytics to forecast equipment failures, enabling proactive maintenance and reducing downtime. Manufacturing firms, particularly in the German automotive sector, rely on it to optimize asset performance and extend machinery lifespan.
- Fraud Detection:Systems in this area analyze transaction patterns and behavioral data to identify and prevent fraudulent activities in real-time. Financial services institutions globally deploy these platforms to comply with AML regulations and protect customer assets.
- Customer Analytics:This involves collecting and analyzing customer data to understand behavior, preferences, and trends for personalized experiences.
- Risk Management:Applications here assess and mitigate financial, operational, and cybersecurity risks using large datasets.
- Supply Chain Optimization:These tools enhance efficiency across logistics, inventory, and procurement through data-driven insights.
- Sentiment Analysis:This application extracts subjective information from text data to understand opinions and emotions, often from social media.
Predictive Maintenance generates the most revenue; Fraud Detection demonstrates the most significant growth potential.
End User Industry:
Different end-user industries generate varying volumes and complexities of data, driving specific technology requirements and solution designs.
- Manufacturing:This sector utilizes big data for optimizing production processes, quality control, and asset management, particularly for IoT sensor data. Automotive manufacturers in Germany integrate these technologies for advanced predictive maintenance and supply chain visibility.
- Telecommunications:Telecom companies leverage big data for network optimization, customer experience management, and fraud prevention through analyzing call detail records and network traffic. Large enterprises in the United States deploy these solutions to manage vast subscriber data.
- Government Agencies:Public sector entities employ big data for public safety, urban planning, and citizen services, handling large demographic and operational datasets.
- Media & Entertainment:This industry uses big data for content recommendation, audience analytics, and advertising optimization, processing extensive user interaction data.
- Energy & Utilities:Companies in this sector apply big data for smart grid management, demand forecasting, and operational efficiency, analyzing sensor data from infrastructure.
- Transportation:Big data supports logistics optimization, fleet management, and traffic flow analysis in this sector, utilizing real-time location and operational data.
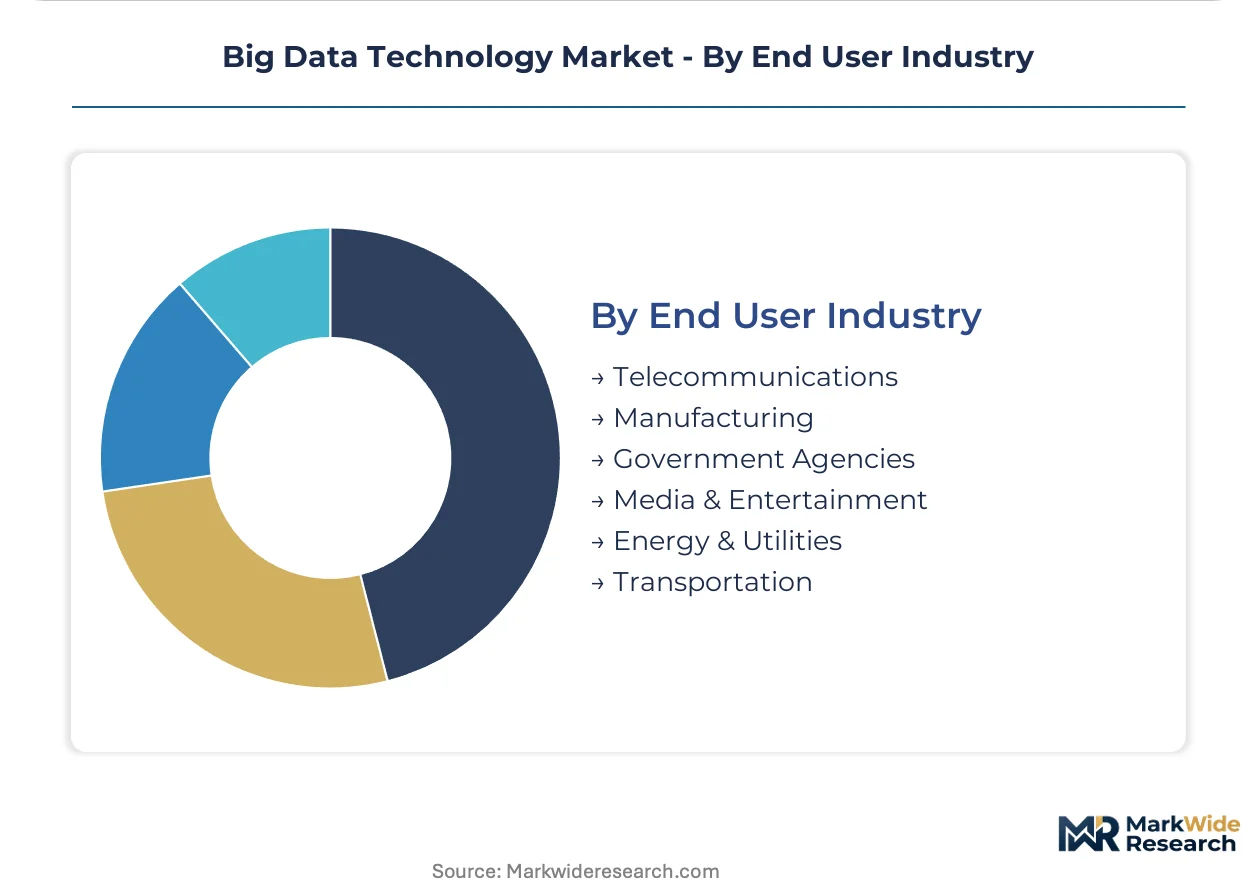
Manufacturing accounts for the largest share; Telecommunications is experiencing the fastest expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for big data technology remains pronounced in economically advanced regions and rapidly digitizing emerging markets. Enterprises in these geographies prioritize data platforms for operational efficiency and regulatory compliance. This regional analysis highlights key market drivers and regulatory influences shaping adoption across diverse economies.
United States
The United States exhibits robust demand for cloud-native data platforms, particularly within telecommunications and financial services for large enterprises. The Federal Trade Commission (FTC) is intensifying enforcement against unfair AI practices, compelling companies to adopt transparent AI frameworks. Silicon Valley in California continues to anchor innovation, driving the development of advanced analytics and machine learning solutions.
China
China demonstrates significant uptake of big data technologies, especially for managing vast volumes of user-generated content in e-commerce and social media. China's Cybersecurity Law imposes stringent data localization requirements, influencing platform design and deployment strategies for multinational firms. The Yangtze River Delta region, including Shanghai, is a hub for cloud-native data platform adoption and digital transformation initiatives.
Germany
Germany's manufacturing sector drives substantial demand for big data platforms, primarily for predictive maintenance applications utilizing IoT sensor data. The EU AI Act and GDPR set stringent rules for algorithmic accountability and data privacy, impacting technology design. The automotive sector in regions like Bavaria and Baden-Württemberg heavily integrates these technologies for asset optimization and extended machinery lifespan.
Indonesia
Indonesia's rapidly expanding digital banking sector creates a greenfield market for mobile-first analytics platforms and real-time data processing. The country's financial services regulator (OJK) influences data governance practices, encouraging secure and compliant data handling. Jakarta emerges as a key hub for fintech innovation, with numerous startups leveraging big data for customer insights and fraud detection.
Big Data Technology Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue specialized niches in advanced analytics and AI integration. The market structure features a mix of large technology conglomerates offering broad platforms and specialized data platform providers focusing on specific use cases. Strategic archetypes include cloud infrastructure giants, unified analytics specialists, and industry-specific solution vendors. Companies are engaging in strategic partnerships, portfolio diversification, and geographic expansion to enhance their offerings and secure market share amidst evolving regulatory landscapes.
Within the cloud infrastructure and platform segments, Microsoft, through its extensive Azure ecosystem, represents a comprehensive integrated data services provider. Databricks exemplifies a specialist in unified analytics, combining data science and engineering workflows for enterprise clients. Snowflake occupies a distinct position as a multi-cloud data platform architect, differentiating through its decoupled storage and compute model. These entities anchor different strategic approaches, ranging from broad ecosystem plays to highly specialized, multi-cloud data warehousing solutions.
| Leading Market Players |
|---|
| Databricks |
| Palantir |
| Microsoft |
| Tata Consultancy Services |
| Accenture |
| Amazon |
| Snowflake |
| Capgemini |
| Alphabet |
Cost & Logistics Intelligence
Data engineering skill gaps globally drive significant labor-cost differentials, directly influencing pricing tiers across big data technology services. This scarcity creates premium pricing for specialized talent, impacting overall solution costs.
Pricing Analysis
Volume-based consumption models now dominate big data technology pricing, with margins varying significantly based on service complexity. Customization level and performance tiers, such as real-time analytics capabilities, drive significant price differentiation. Pricing pressure stems from the high compute costs associated with decoupled storage and compute, particularly affecting smaller enterprises. Large telecommunications firms and government agencies, requiring specialized integration and support, exhibit lower price sensitivity.
Supply Chain Analysis
Direct cloud service providers distribute big data technology platforms globally, catering to diverse enterprise demand. Supply concentration for advanced analytics and machine learning solutions anchors in Silicon Valley, California, and the Yangtze River Delta, China, for cloud-native platforms. Key dependencies include hyperscale cloud infrastructure from providers like Microsoft Azure and open-source frameworks such as Apache Spark. Data localization requirements, particularly China's Cybersecurity Law, represent a significant structural risk, fragmenting data architectures. This distribution model enables widespread access but relies heavily on global internet infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The big data technology market presents a consolidation play, as high compute costs and persistent data engineering skill gaps exert pressure on smaller, less capitalized providers. This environment favors established players with comprehensive ecosystems and deep talent pools.
For Market Incumbents: Deploy comprehensive ecosystem integration across existing product lines to counter emerging specialized entrants. Microsoft, leveraging its Azure cloud, should deepen integration of AI-driven analytics with core business applications, enhancing value proposition. Expand multi-cloud data governance tools to address fragmented regulatory landscapes like the EU AI Act, retaining large enterprise clients. Focus on reducing unpredictable cloud infrastructure costs for customers to mitigate adoption barriers.
For New Entrants and Emerging Players: Capture greenfield opportunities in Southeast Asian digital banking by offering mobile-first analytics platforms. Focus on specific applications like Supply Chain Digital Twins, integrating logistics and inventory data for manufacturers. The most penetrable segment lies within mid-sized enterprises requiring specialized, compliant solutions for real-time fraud detection. Go-to-market strategies should emphasize consumption-based pricing models, aligning costs directly with processing workloads for rapid adoption.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized data platform providers given the market's projected expansion to over $1 trillion by 2035. Long-term viability hinges on companies that effectively navigate fragmented regulatory environments and address data engineering skill gaps. Acquisition targets should include unified analytics specialists like Databricks or firms offering advanced data governance tools for EU AI Act compliance. The signal to watch is the accelerated adoption of composable architectures and data mesh paradigms by large enterprises.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrate Generative AI into Data Warehouses | This allows natural language querying and automated insight generation for enterprise data users. |
| Expand Multi-Cloud Data Governance Solutions | Companies can meet fragmented data localization and privacy regulations like GDPR and China's Cybersecurity Law. |
| Specialize in Real-time Fraud Detection Platforms | Financial services institutions require instant transaction analysis to meet AML compliance and protect assets. |
| Develop Mobile-First Analytics for Digital Banking | Digital banks in Indonesia and Vietnam need platforms tailored for high-velocity, user-generated data. |
| Invest in Data Engineering Skill Development Programs | Addressing persistent skill gaps accelerates project deployment and reduces labor costs for big data initiatives. |
Research Approach
SEC filings, academic research on advanced analytics, and government reports on digital transformation formed the secondary backbone for this study. This was complemented by primary interviews with CTOs, IT procurement officers, platform engineers, and data scientists across diverse industries. The approach combined bottom-up data aggregation with top-down market validation, ensuring comprehensive coverage. All insights underwent rigorous triangulation across both primary and secondary sources.
A bottom-up sizing approach, validated through top-down market estimates, underpinned the forecast framework across the analysis window. Segmentation dimensions modeled included technology, deployment, application, end-user industry, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical adoption trends and projected enterprise investment in digital transformation. Key industry-specific inputs included IoT sensor data volumes and the increasing complexity of AI models.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rapid technological shifts and evolving regulatory mandates. All forecasts reflect inherent assumptions regarding market dynamics and enterprise adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
IPTV Market
Digital Solutions
Digital Certificates Market
Digital Solutions
Global Enterprise Mobility Management (EMM) Market
Digital Solutions
Web Based E-Detailing Market
Digital Solutions
Asia-Pacific Desktop Virtualization Market
Digital Solutions
Indonesia Digital Software Solutions Market
Digital Solutions
Data Governance Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
North America API Management Market
Digital Solutions
Data Monetization Platform Market
Digital Solutions
Decision Support System Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
End User Experience Monitoring (EUEM) Market
Digital Solutions
Work From Home Setup Market
Digital Solutions
Part-Time Job Platform Market