
 Global Enterprise Mobility Management (EMM) Market | 2026-2036
Global Enterprise Mobility Management (EMM) Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enterprise Mobility Management (EMM) Market Foresight
The EMM competitive landscape is shifting between premium unified endpoint security suites and commoditized mobile device management point solutions. Microsoft Corporation leverages its Entra identity fabric and Intune cloud infrastructure to anchor enterprise-grade deployments across regulated industries. VMware, Inc. competes through Workspace ONE's deep endpoint telemetry and cross-platform virtualization stack. BlackBerry Limited specializes in hardened government and defense-grade mobile security, sustaining premium positioning where data sovereignty requirements are non-negotiable.
Enterprise Mobility Management encompasses the centralized provisioning, security policy enforcement, and lifecycle governance of smartphones, tablets, laptops, and IoT endpoints accessing corporate data, typically integrating certificate-based authentication, containerization, and over-the-air configuration profiles to enforce least-privilege access. Mobile Device Management remains the foundational revenue layer, though Mobile Application Management and Identity & Access Management are capturing disproportionate growth as organizations decommission VPN-centric access models. Cloud-Based deployment dominates new bookings, while Hybrid configurations persist in manufacturing and government verticals where air-gapped subnets retain sensitive operational technology interfaces.
The EU AI Act and GDPR impose algorithmic transparency and data localization obligations on EMM platforms processing biometric or behavioral telemetry, compelling vendors to architect region-specific tenant isolation. The US FAA and NHTSA are extending cybersecurity directives into connected fleet and aviation ground operations, broadening EMM addressable markets beyond conventional knowledge-worker endpoints. Stakeholders must evaluate whether their current vendor roadmaps incorporate post-quantum cryptographic standards before certificate infrastructure refresh cycles lock in decade-long commitments.
Market Dynamics
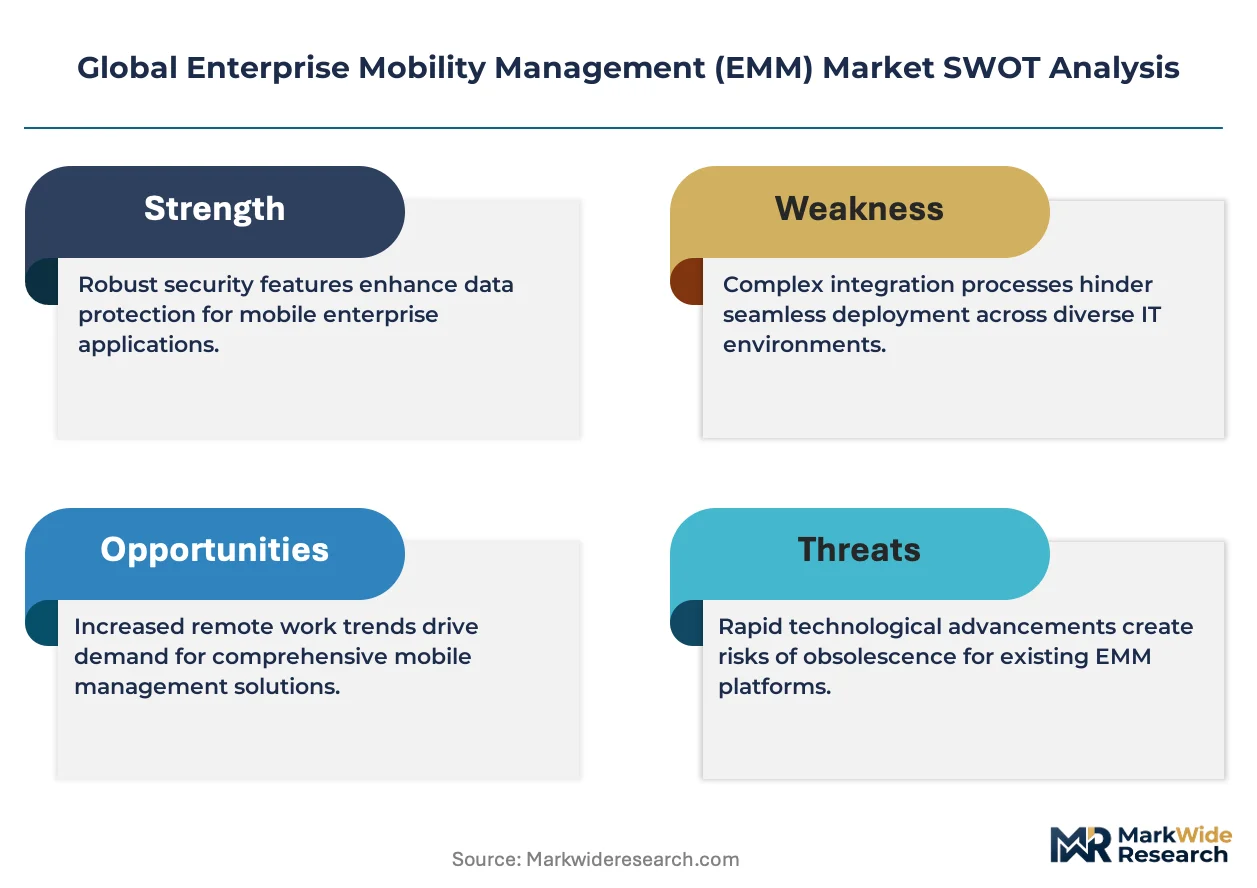
Zero-trust security mandates are compressing enterprise procurement cycles as organizations dismantle perimeter-based VPN architectures in favor of continuous verification models that govern every endpoint session.
Growth Catalysts
- GDPR-mandated data residency:European Union enforcement actions against cross-border data transfers are compelling platform upgrades to region-isolated tenant architectures.
- Connected fleet cybersecurity:US FAA and NHTSA directives extending into aviation ground operations and autonomous vehicle fleets are broadening EMM addressable markets beyond knowledge-worker devices.
- Post-quantum cryptographic standards:NIST's finalized quantum-resistant algorithms are accelerating certificate infrastructure refresh cycles before decade-long vendor commitments lock in.
Market Restraints
- Legacy system integration costs:Air-gapped operational technology subnets in manufacturing and government verticals require expensive hybrid deployment configurations.
- Certificate authority concentration:Dependence on a limited pool of root certificate providers creates systemic vulnerability to supply chain compromise.
- Biometric telemetry regulatory friction:EU AI Act algorithmic transparency obligations impose compliance burdens that slow behavioral analytics deployment.
Strategic Opportunities
- India's digital public infrastructure:Unified Payments Interface expansion and RBI mobile banking mandates are creating demand for hardened device governance in financial services.
- Convergence of EMM and identity fabrics:Integration between endpoint management and cloud-native access platforms opens unified procurement budgets.
- Brazil's LGPD enforcement wave:ANVISA and central bank data protection audits are driving first-time EMM adoption among mid-market enterprises.
Industry Challenges
- Zero-trust architecture skill scarcity:Shortage of engineers capable of implementing continuous verification across heterogeneous endpoint fleets.
- Cross-platform containerization complexity:Fragmentation between iOS, Android, and emerging IoT operating systems complicates unified policy enforcement.
- Air-gapped subnet maintenance:Government and manufacturing clients require specialized personnel for hybrid cloud-on-premises orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enterprise Mobility Management (EMM) Market |
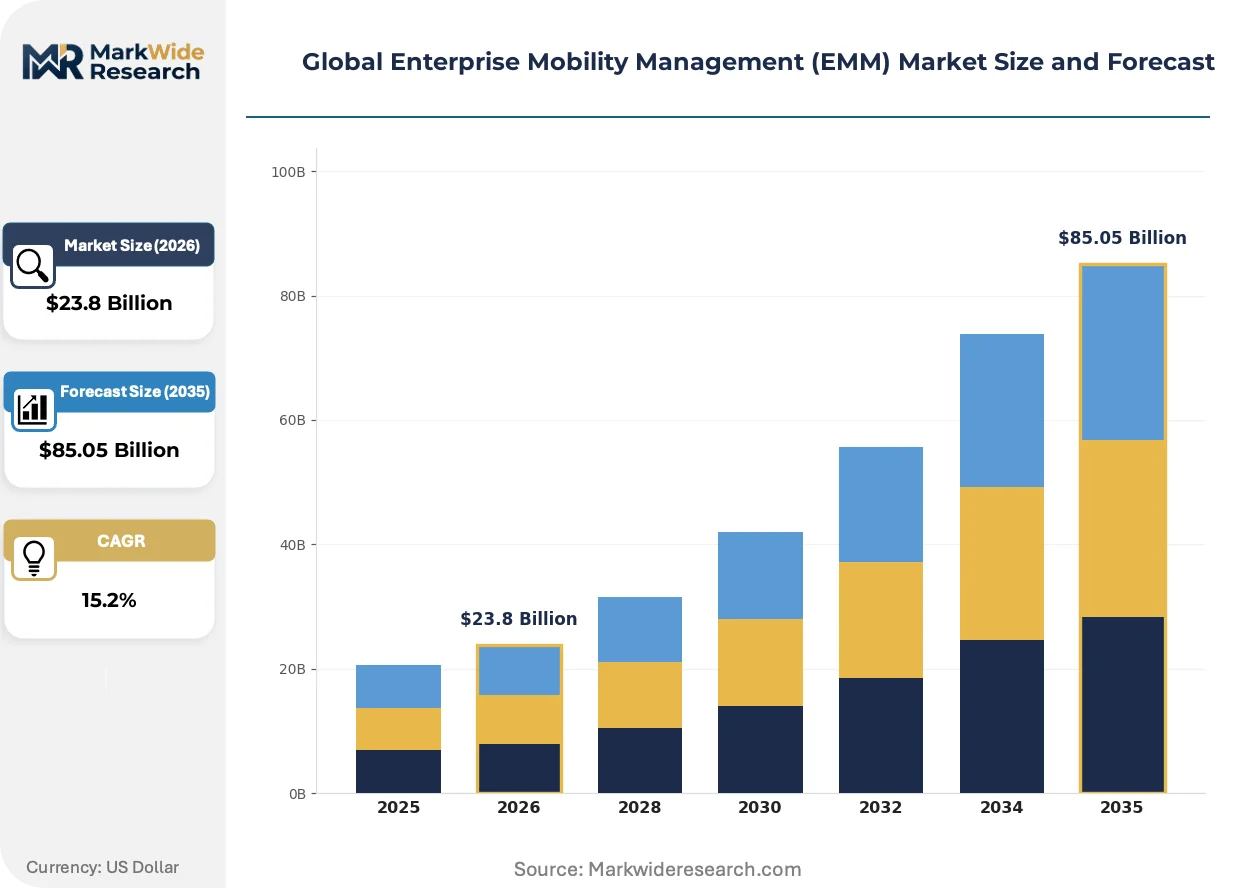
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $85.05 Billion |
| CAGR (2026 – 2036) | 15.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Hosted, Virtual Solution Type: Mobile Device Management, Mobile Application Management, Identity & Access Management, Mobile Content Management, Secure Email End User Industry: BFSI, Telecommunications, Government Agencies, Manufacturing, Education Integration Level: Basic, Advanced, Custom, Plug-in, API-Based |
| Companies Covered | Microsoft Corporation, IBM Corporation, VMware, Inc., Cisco Systems, Inc., Citrix Systems, SAP SE, Ivanti, BlackBerry Limited, Broadcom, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enterprise Mobility Management (EMM) Market Shifts & Advancements
Cloud-native endpoint governance is displacing on-premises mobile device management consoles as enterprises consolidate fragmented security stacks into unified SaaS-delivered platforms.
Passwordless FIDO2 authentication is overtaking certificate-based legacy access across financial services deployments. Trading floors and wealth advisory functions are adopting hardware-bound cryptographic credentials at accelerated pace. This shift is compressing traditional identity provider margins and forcing incumbent vendors to rearchitect around WebAuthn standards.
EU AI Act algorithmic transparency mandates are reshaping behavioral telemetry collection across European deployments. Vendors must now maintain explainable audit trails for biometric risk scoring models. German automotive manufacturers and French banking consortia are most affected, with several delaying AI-driven anomaly detection rollouts pending regulatory clarity.
Consumption-based licensing is fragmenting traditional enterprise software procurement in North American deployments. Mid-market buyers are unbundling endpoint security suites and purchasing mobile application management as standalone modules. This pattern is most visible among US healthcare systems responding to HIPAA audit pressure with targeted rather than comprehensive platform investments.
Global Enterprise Mobility Management (EMM) Market Segmentation
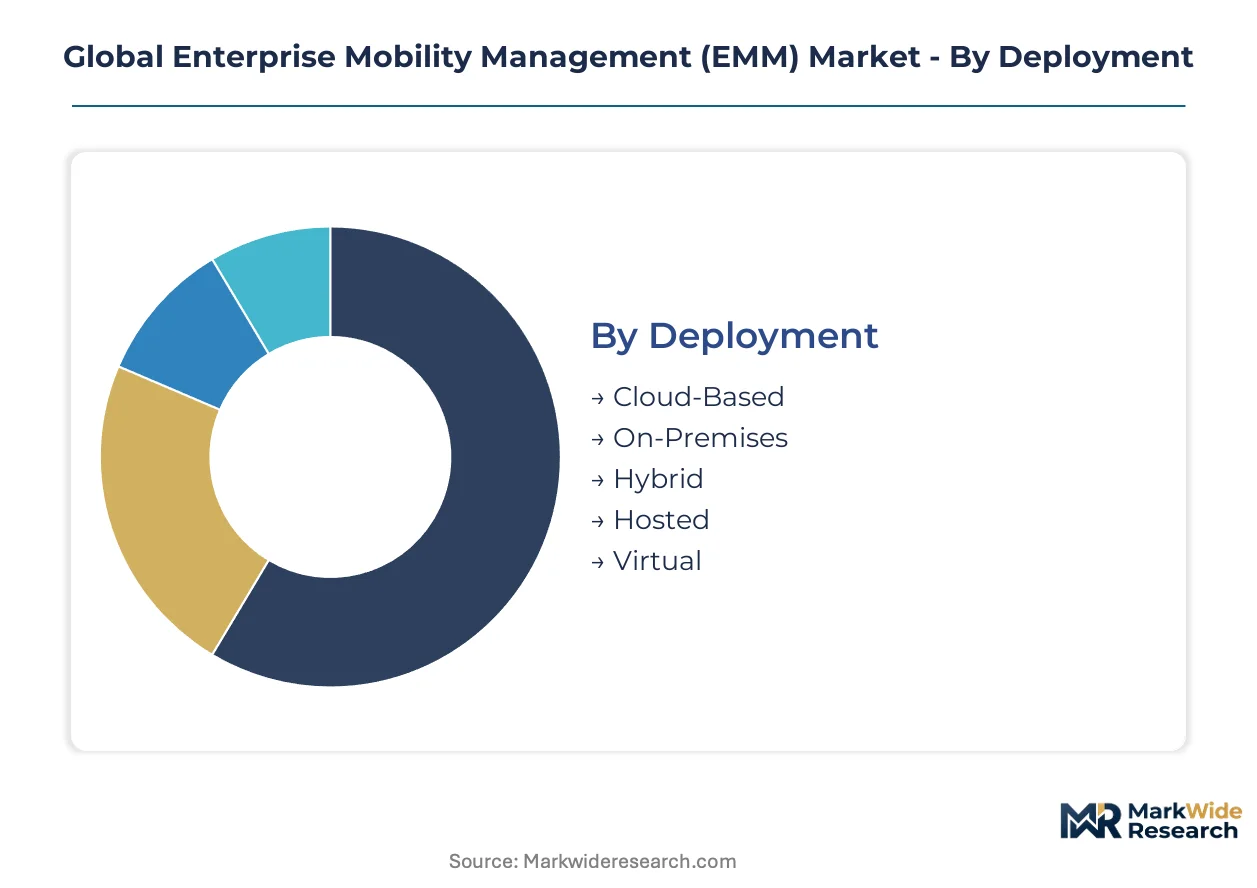
EMM procurement patterns diverge sharply across deployment architectures, solution maturity, and vertical compliance requirements. Understanding these axes reveals where unified suite consolidation is displacing point solutions versus where fragmented stacks persist.
Deployment:
Cloud-native infrastructure now dominates new bookings, though air-gapped requirements in regulated verticals sustain hybrid demand.
- Cloud-Based:SaaS-delivered consoles with multi-tenant isolation support rapid policy propagation across distributed workforces. Demand concentrates among US financial services firms consolidating fragmented endpoint stacks into unified Entra-integrated suites. GDPR-mandated EU data residency is accelerating region-specific tenant architectures.
- Hybrid:Split orchestration between cloud policy engines and on-premises device management servers addresses manufacturing OT subnets and government classified networks. German automotive manufacturers and French defense contractors require this configuration for air-gapped operational technology interfaces.
- On-Premises:Legacy console deployments in highly regulated environments with decade-old certificate infrastructure.
- Hosted:Single-tenant dedicated instances for mid-market buyers avoiding shared infrastructure compliance risks.
- Virtual:Containerized management planes for rapid disaster recovery and cross-region failover scenarios.
Mature deployment sits with On-Premises. Newer deployment is concentrated in Cloud-Based.
Solution Type:
Revenue is migrating from device-centric licensing toward identity-anchored access governance and application-level containerization.
- Mobile Device Management:Foundational layer encompassing over-the-air enrollment, configuration profile distribution, and remote wipe capabilities. BFSI trading floors in London and Singapore retain this as core spend, though margins compress as vendors bundle MDM into broader suites.
- Identity & Access Management:Converged endpoint and cloud-native access platforms govern continuous verification sessions under zero-trust mandates. US healthcare systems responding to HIPAA audit pressure are unbundling IAM from comprehensive suites for targeted procurement.
- Mobile Application Management:Containerized corporate data separation without full device control, expanding most quickly among BYOD-heavy professional services.
- Mobile Content Management:Document-level encryption and rights management for regulated document workflows.
- Secure Email:Gateway and client-side encryption for classified communications in government agencies.
Established revenue sits with Mobile Device Management. Fastest expansion is occurring in Identity & Access Management.
End User Industry:
Compliance stringency and mobile workforce penetration determine solution sophistication requirements across verticals.
- BFSI:Trading floors and wealth advisory functions demand FIDO2 hardware-bound credentials with real-time session risk scoring. RBI mobile banking mandates in India and Brazil's LGPD enforcement wave are driving first-time EMM adoption among mid-market financial institutions.
- Government Agencies:Classified mobility programs require hardened device governance with data sovereignty guarantees. BlackBerry's defense-grade positioning persists here where EU AI Act algorithmic transparency obligations and national security requirements overlap.
- Telecommunications:Field technician fleets and retail store operations need scalable device provisioning across heterogeneous Android estates.
- Manufacturing:Connected fleet cybersecurity directives from the US FAA and NHTSA extend EMM into aviation ground operations and autonomous vehicle production lines.
- Education:1:1 device programs with limited IT staffing favor simplified cloud-native management consoles.
Complex deployment sits with Government Agencies. Volume scaling is concentrated in Telecommunications.
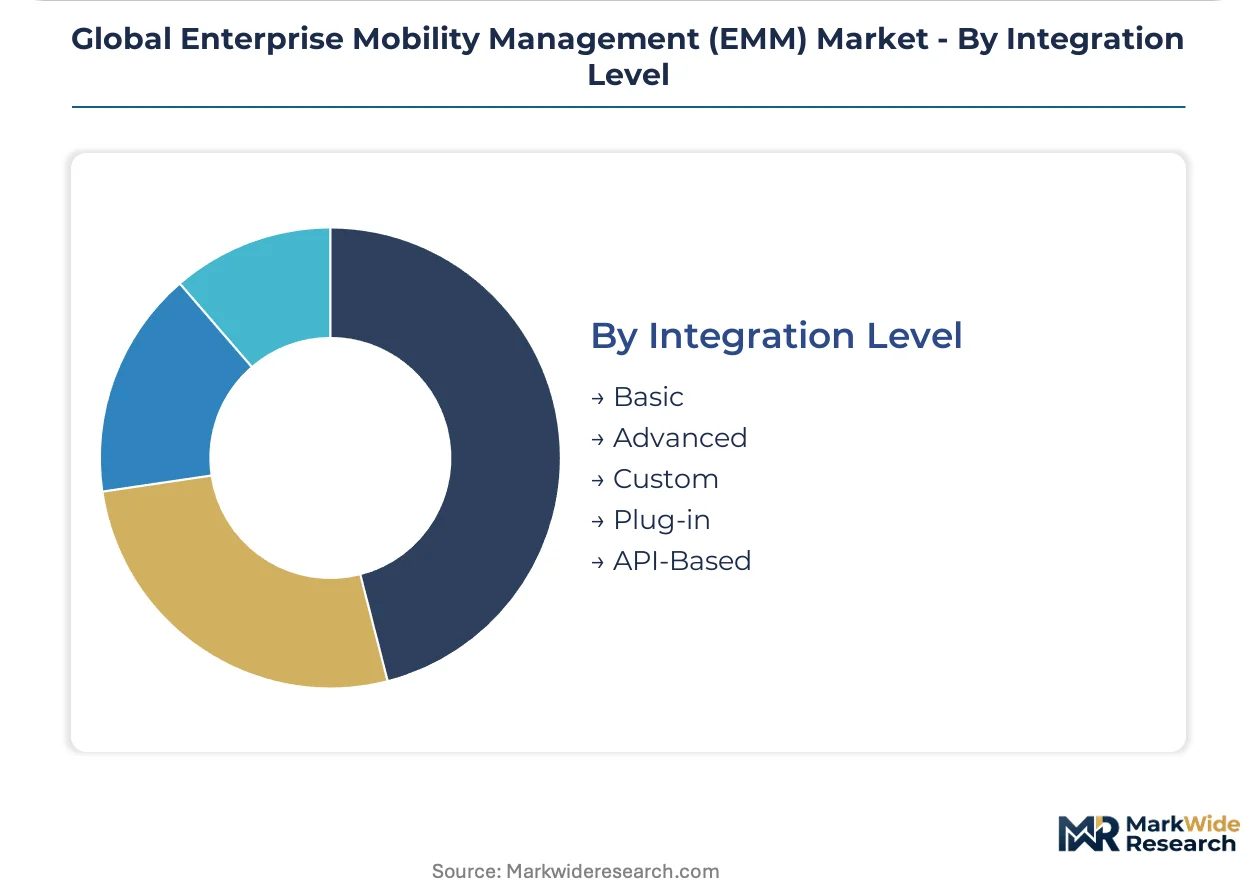
Integration Level:
API maturity determines whether EMM platforms function as orchestration hubs or isolated policy enforcement points.
- API-Based:RESTful and SCIM interfaces enable real-time bidirectional synchronization with SIEM, SOAR, and ITSM platforms. US enterprises dismantling VPN architectures favor this tier for continuous verification telemetry exchange.
- Advanced:Pre-built connectors to major identity providers and endpoint detection vendors reduce deployment friction.
- Custom:Bespoke integration development for legacy mainframe and proprietary OT system interoperability.
- Plug-in:Extension modules for specific compliance or industry vertical requirements.
- Basic:Limited directory synchronization without automated policy orchestration.
Legacy deployment sits with Basic. Modern architecture adoption is concentrated in API-Based.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Redmond anchors North American EMM platform consolidation as financial services firms dismantle perimeter-based VPN architectures across Manhattan trading floors and Chicago advisory operations.
United States
Federal zero-trust mandates from the Office of Management and Budget compress procurement cycles for continuous verification platforms. FAA cybersecurity directives extending into aviation ground operations broaden addressable markets beyond knowledge-worker endpoints. Silicon Valley SaaS vendors and Seattle cloud infrastructure providers dominate new bookings as healthcare systems respond to HIPAA audit pressure with targeted IAM investments.
Germany
Automotive manufacturers in Stuttgart and Munich require air-gapped hybrid configurations for operational technology interfaces in connected fleet production lines. EU AI Act algorithmic transparency obligations delay AI-driven anomaly detection rollouts pending regulatory clarity. Bavarian defense contractors sustain premium positioning for hardened device governance where data sovereignty requirements intersect with national security frameworks.
United Kingdom
London financial services trading floors demand FIDO2 hardware-bound credentials with real-time session risk scoring. Financial Conduct Authority operational resilience requirements accelerate certificate infrastructure refresh cycles. The City of London and Canary Wharf clusters concentrate vendor engagement for wealth advisory mobile workforce deployments.
India
RBI mobile banking mandates and Unified Payments Interface expansion create demand for hardened device governance among mid-market financial institutions. Mumbai and Bangalore technology corridors anchor domestic platform development and managed service delivery. SEBI cybersecurity circulars impose endpoint telemetry collection standards on brokerage and advisory operations.
Brazil
ANVISA and central bank data protection audits drive first-time EMM adoption among mid-market enterprises previously reliant on consumer-grade mobile management. São Paulo financial services concentration generates regional demand for LGPD-compliant tenant architectures. Rio de Janeiro and Belo Horizonte industrial clusters extend procurement into connected logistics and field service operations.
Global Enterprise Mobility Management (EMM) Market Competitive Landscape
Premium-margin players sit above commodity-margin players across identity-anchored versus device-centric licensing dimensions. The vendor base stratifies between unified endpoint security suites commanding consolidated procurement budgets and unbundled mobile application management modules capturing mid-market fragmentation. Three archetypes dominate: cloud-native platform orchestrators, defense-grade hardened security specialists, and legacy on-premises console maintainers. M&A activity concentrates on identity fabric convergence, while portfolio diversification pushes toward IoT endpoint governance beyond conventional smartphones and tablets.
Within the cloud-native platform tier, Microsoft Corporation and VMware, Inc. anchor enterprise-grade deployments across regulated industries. BlackBerry Limited occupies a distinct position where government classified mobility programs and data sovereignty requirements sustain premium pricing. These three entities exemplify the competitive tension between horizontal platform consolidation and vertical specialization in security-sensitive deployments.
| Leading Market Players |
|---|
| Microsoft Corporation |
| IBM Corporation |
| VMware, Inc. |
| Cisco Systems, Inc. |
| Citrix Systems |
| SAP SE |
| Ivanti |
| BlackBerry Limited |
| Broadcom, Inc. |
| Others |
Supply & Pricing Matrix
Suite-versus-point-solution divergence separates premium unified endpoint security platforms from commoditized mobile device management modules, with this bifurcation manifesting in subscription tiers anchored to identity-fabric integration depth and supply chains segmented between cloud-native orchestration hubs and legacy on-premises console maintainers. Financial services procurement teams in Manhattan and London pay premiums for FIDO2 hardware-bound credential bundles, while mid-market healthcare systems unbundle mobile application management for targeted HIPAA compliance spending.
Pricing Analysis
Value-based pricing tied to endpoint session throughput and continuous verification uptime anchors enterprise SaaS tiers. Three-tier pricing structure across premium identity-fabric suites, standard MDM bundles, and economy per-device licensing reflects integration complexity and vertical certification requirements. Cost compression in standard tiers is intensifying because Microsoft Entra-Intune bundling collapses standalone vendor margins. Mid-market buyers exhibit highest price sensitivity, while government agencies with classified mobility mandates show lowest elasticity due to data sovereignty non-negotiability.
Supply Chain Analysis
Dual-sourcing requirements for root certificate infrastructure and cryptographic hardware modules compel buyers to qualify multiple HSM vendors and certificate authorities. Supply concentration centers on United States cloud infrastructure providers, Taiwanese semiconductor foundries for secure enclave chips, and German automotive-grade hardware security module manufacturers. The supply chain draws from silicon wafer fabrication, FIDO2 authenticator assembly, and multi-tenant SaaS orchestration layers. Single-source vulnerability in concentrated root certificate providers creates systemic exposure to supply chain compromise. Distribution runs through direct enterprise sales teams, hyperscaler marketplaces, and managed security service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise Mobility Management functions as a cost-of-compliance market where GDPR-mandated data residency and EU AI Act algorithmic transparency obligations erect barrier-to-entry moats for vendors with region-isolated tenant architectures and explainable biometric audit trails.
For Market Incumbents: Lock in government and defense verticals through post-quantum cryptographic certification investments before NIST algorithm standardization locks in decade-long infrastructure commitments. Acquire identity fabric specialists to defend against Microsoft Entra-Intune bundling pressure. Air-gapped hybrid deployment expertise in German automotive and French defense verticals represents a defensible moat against cloud-native commoditization. For New Entrants and Emerging Players: Brazil's LGPD enforcement wave in São Paulo financial services opens a window for first-time EMM adoption among mid-market enterprises previously reliant on consumer-grade mobile management. India's RBI mobile banking mandates and Unified Payments Interface expansion create white-space demand for hardened device governance in Mumbai and Bangalore mid-market institutions. A channel-native go-to-market through managed security service providers bypasses direct sales cost disadvantages against entrenched platforms. For Investors and Strategic Acquirers: Re-rating potential sits with identity-anchored endpoint governance specialists given zero-trust security mandate acceleration and VPN dismantling timelines across US federal and financial services deployments. Long-term viability in this market hinges on post-quantum cryptographic readiness and EU regulatory compliance architecture. The signal to watch as inflection indicator is NIST post-quantum algorithm finalization triggering certificate infrastructure refresh cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Certification | NIST algorithm finalization compels infrastructure refresh before decade-long vendor commitments crystallize. |
| EU Data Residency Tenant Isolation | GDPR enforcement actions mandate region-specific architectures for biometric telemetry processing. |
| Identity Fabric Convergence | Integration between endpoint management and cloud-native access platforms unlocks unified procurement budgets. |
| FIDO2 Hardware Security Module Partnership | Trading floors and wealth advisory functions demand hardware-bound credentials at accelerated deployment pace. |
| Air-Gapped Hybrid Orchestration Capability | German automotive manufacturers require split cloud-on-premises configurations for operational technology interfaces. |
Research Methodology
SEC filings, hyperscaler capex disclosures, and EU regulatory enforcement databases formed the secondary backbone, supplemented by customs records of cryptographic hardware imports and IT services trade flow data. Primary interviews with CISOs at financial services institutions, federal agency IT directors, platform engineers at cloud-native vendors, and procurement leads at German automotive manufacturers combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up modeling of endpoint deployment volumes across cloud-native, hybrid, and on-premises architectures integrated with top-down macroeconomic scaling factors across the projection horizon. Segmentation dimensions modeled include deployment model, organization size tier, vertical compliance stringency, integration complexity level, and regional regulatory framework cluster. CAGRs were derived from fitted growth curves against historical adoption velocity and policy mandate acceleration timelines, with inputs including zero-trust security procurement cycle compression and post-quantum cryptographic refresh demand elasticity.
The model assumes a particular technology adoption path; alternative pathways for passwordless FIDO2 authentication would alter the outlook if certificate-based legacy access persists longer than projected. Deviation in EU AI Act enforcement intensity or NIST post-quantum algorithm standardization timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Onboarding Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Digital String Encoder Market
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Global Photo Management Software Market
Digital Solutions
Europe Content Moderation Services Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Online Classified Ad Platform Market
Digital Solutions
Document Case Management (DCM) Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Weather App Market
Digital Solutions
Europe Smart Government Market
Digital Solutions
Product Engineering Services Market
Digital Solutions
Brazil Digital Twin Market