
 Asia-Pacific Desktop Virtualization Market | 2026-2036
Asia-Pacific Desktop Virtualization Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Desktop Virtualization Market Insights
Enterprise-grade security specifications are redrawing competitive boundaries across the Asia-Pacific Desktop Virtualization Market. VMware leverages its hypervisor stack to anchor multi-tenant cloud deployments across Southeast Asian data centers. Microsoft Corporation sustains dominance through Azure Virtual Desktop integration with existing enterprise licensing. Huawei Technologies competes aggressively on price-performance for on-premises VDI rollouts in China's state-owned enterprise sector.
Desktop virtualization delivers centralized desktop environments from data center or cloud infrastructure to endpoint devices, typically operating over protocols such as HDX, PCoIP, or RDP with latency thresholds under 50 milliseconds for acceptable user experience. Its primary commercial purpose eliminates endpoint hardware refresh cycles while enabling secure remote workforce access. Cloud deployment type captures the fastest expansion as enterprises migrate from capital-intensive on-premises VDI to subscription-based DaaS models. Government end-user segments present concentrated margin pools where compliance requirements favor hybrid architectures blending sovereign cloud with local infrastructure.
India's BIS mandates and TRAI data-localization guidelines shape product architectures by requiring citizen data residency within national boundaries. Australia's ASD Essential Eight and Japan's METI cybersecurity frameworks further fragment technical standards across the region, forcing vendors to maintain multiple certification tracks. China's MIIT cloud service licensing adds another access barrier for foreign platform providers. Stakeholders must weigh sovereignty-compliant infrastructure investments against the operational complexity of fragmented regulatory compliance.
Market Dynamics
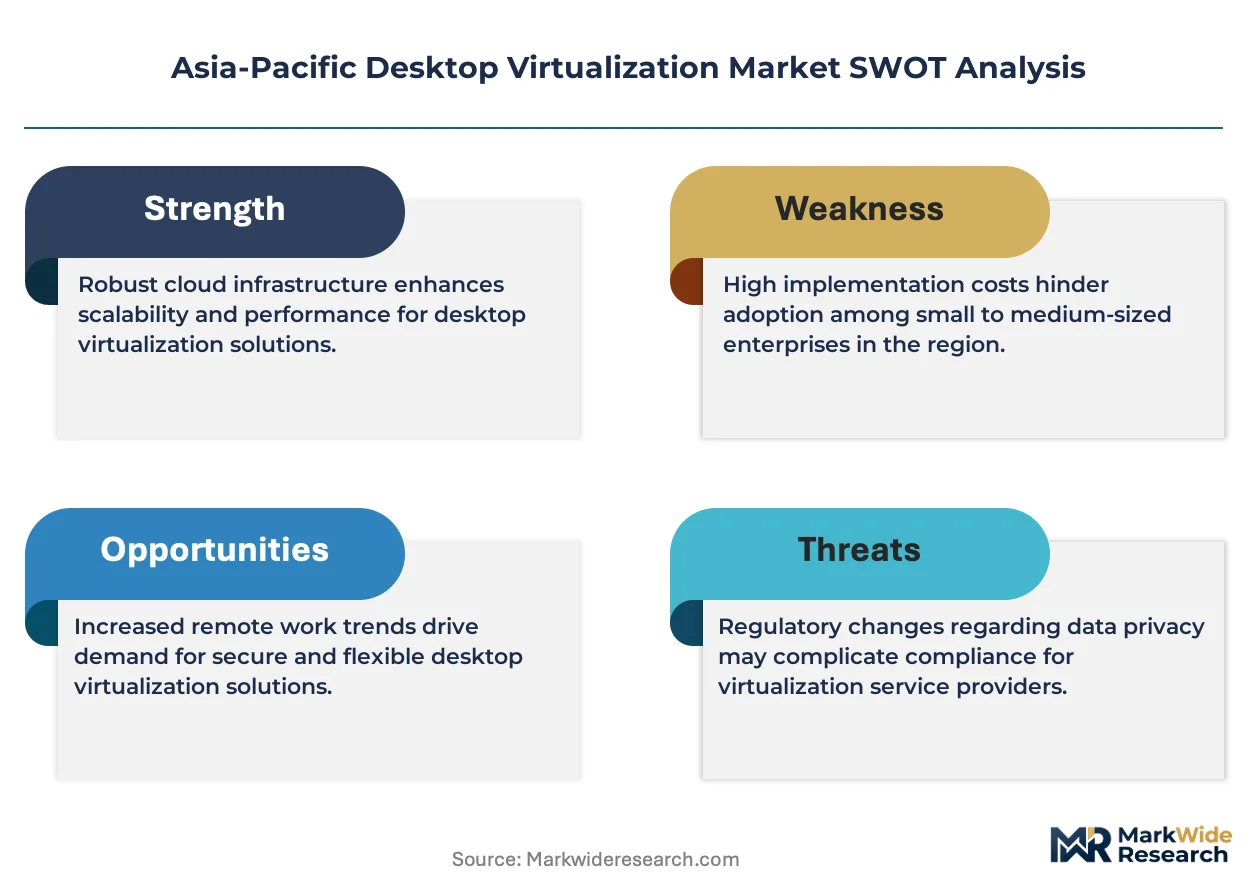
Data-localization mandates from India's TRAI and BIS are fragmenting cloud architectures across Asia-Pacific, forcing vendors to deploy sovereign infrastructure stacks that complicate cross-border operations while opening margin-rich compliance service layers.
Growth Catalysts
- Financial services VDI expansion:India's banking sector deploys desktop virtualization to meet RBI data-residency requirements while enabling branch workforce mobility.
- TRAI localization guidelines:Telecom carriers must store subscriber data within national boundaries, accelerating sovereign cloud VDI procurement cycles.
- GPU-accelerated virtual desktops:Engineering and media firms adopt graphics-intensive DaaS for remote workstation access without endpoint hardware investment.
Market Restraints
- Latency infrastructure gaps:Rural fiber deployment lags in Indonesia and Philippines, degrading HDX protocol performance below 50-millisecond thresholds.
- MIIT licensing barriers:China's cloud service licensing restricts foreign platform providers from operating sovereign data centers serving state-owned enterprises.
- On-premises VDI stranded assets:Capital-intensive server farms face accelerated obsolescence as subscription DaaS models displace five-year hardware refresh cycles.
Strategic Opportunities
- Vietnam manufacturing corridor:Electronics assembly plants seek centralized desktop management for transient contract workforces across industrial zones.
- ASD Essential Eight compliance services:Australian government cloud migration creates demand for hybrid architectures blending sovereign infrastructure with managed security.
- Edge-VDI convergence:5G network slicing enables sub-20-millisecond desktop delivery to construction sites and offshore platforms without data center proximity.
Industry Challenges
- Multi-framework certification backlog:Vendors must simultaneously pursue BIS, ASD Essential Eight, and METI cybersecurity accreditations with divergent technical standards.
- Legacy ERP integration friction:Manufacturing customers require custom protocol bridges to connect virtualized SAP clients with shop-floor SCADA systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Desktop Virtualization Market |
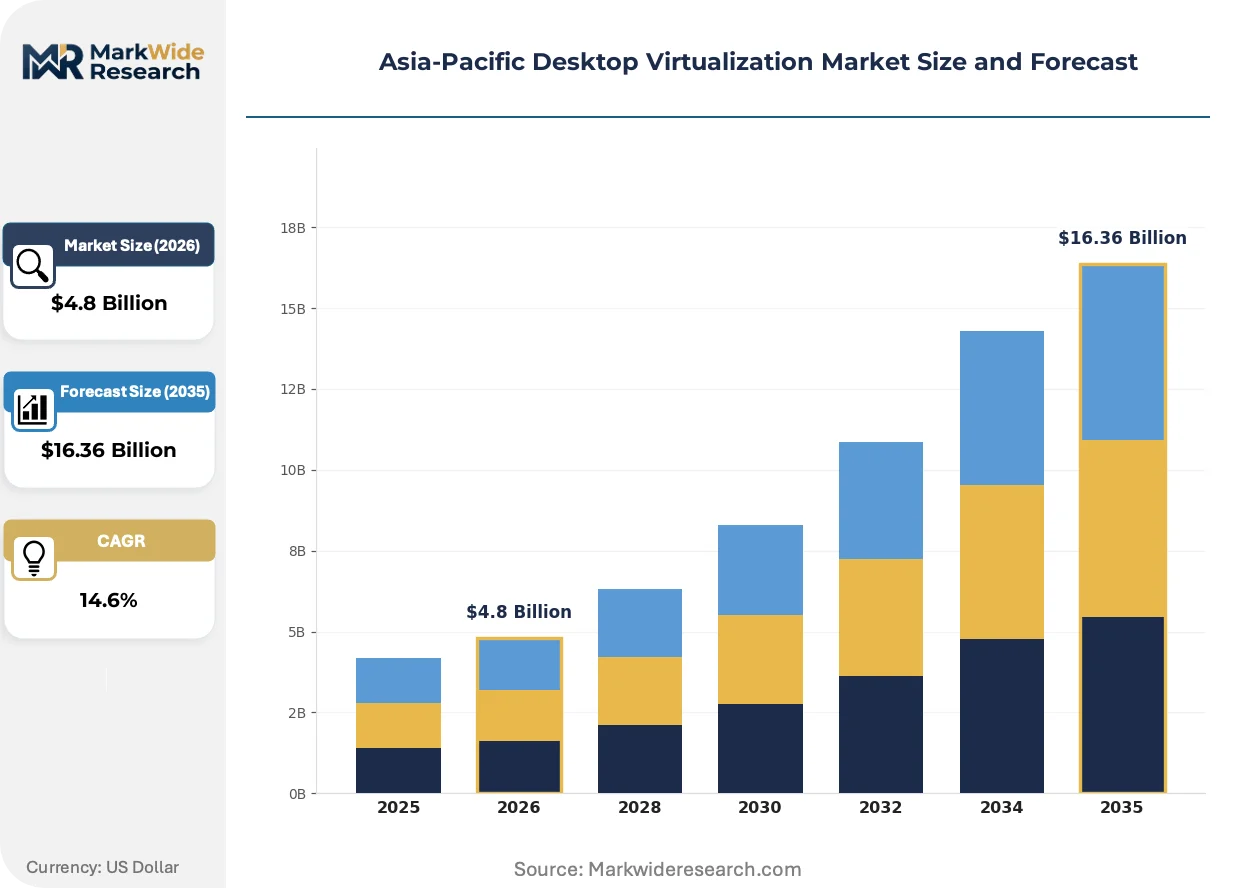
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $16.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: On-Premises, Cloud, Hybrid, Managed Services End User: Enterprise, SMBs, Government, Educational Institutions Technology: VDI, DaaS, Application Virtualization, Remote Desktop Services Service Type: Support Services, Maintenance Services, Consulting Services, Training Services |
| Companies Covered | VMware, Microsoft Corporation, IBM Corporation, Citrix Systems, Huawei Technologies, Dell Technologies, Cisco Systems, Hewlett Packard Enterprise, Amazon Web Services, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Desktop Virtualization Market Trends and Innovations
Protocol optimization and sovereign infrastructure deployment are compressing latency tolerances while expanding addressable use cases beyond traditional knowledge-worker segments.
Teradici PCoIP Ultra is miniaturizing packet overhead for high-fidelity graphics transmission over constrained bandwidth links. Mining operations in Western Australia adopt these optimized protocols to deliver CAD workstations to remote exploration camps via satellite backhaul. The technology is miniaturizing the minimum viable connectivity threshold, expanding addressable geography for graphics-intensive VDI beyond fiber-served metro zones.
Australia's ASD Essential Eight maturity model mandates application whitelisting and credential hardening for government desktop virtualization procurements. Federal agencies now require hybrid architectures with local infrastructure components for OFFICIAL-classified workloads. Defense contractors and critical infrastructure operators face the steepest compliance timelines, driving demand for pre-certified sovereign cloud stacks.
Consumption-based DaaS pricing is displacing perpetual licensing for enterprise desktop virtualization procurement. Japanese automotive suppliers now pay per concurrent user-hour rather than maintaining peak-capacity server farms for seasonal engineering cycles. This shift is most visible in capital-sensitive manufacturing verticals across Thailand and Malaysia, where CFOs prioritize opex treatment for IT infrastructure.
Asia-Pacific Desktop Virtualization Market Segmentation
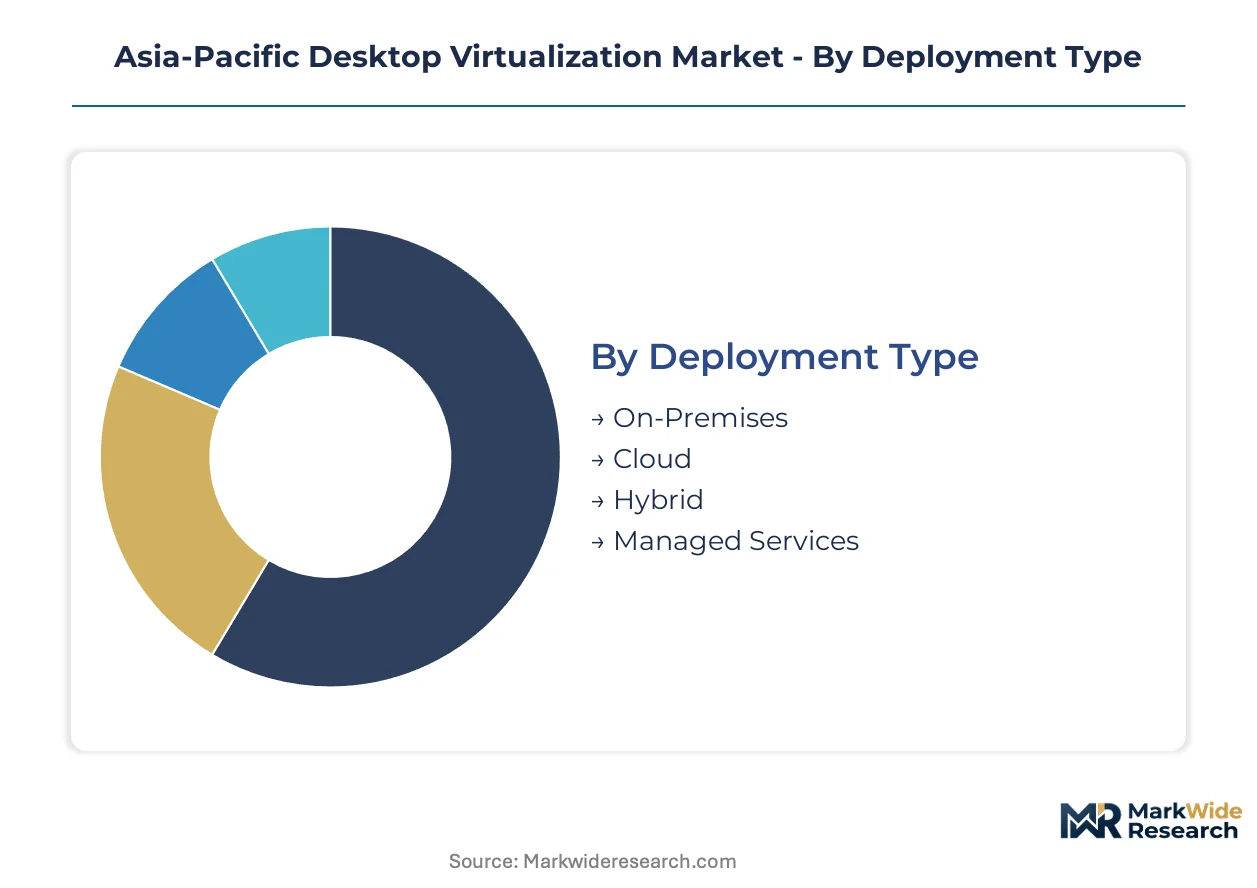
Desktop virtualization architectures fragment across deployment models, end-user security tiers, and protocol technologies. Each segment carries distinct compliance obligations and infrastructure economics that reshape vendor competitive positioning.
Deployment Type:
India's BIS data-localization mandates and Australia's ASD Essential Eight framework drive architectural divergence between sovereign on-premises stacks and subscription cloud models.
- On-Premises:Organizations deploy hypervisor clusters within owned data centers to maintain physical custody of citizen data. India's banking sector favors this architecture to satisfy RBI data-residency requirements without third-party cloud exposure.
- Cloud:Subscription DaaS models shift capital expenditure to operational budgets through per-user pricing. Japanese automotive suppliers adopt consumption-based billing for seasonal engineering workforce scaling.
- Hybrid:Blends local infrastructure for classified workloads with cloud burst capacity for transient demand. Australian federal agencies require this architecture for OFFICIAL-classified desktop virtualization procurements.
- Managed Services:Third-party operators assume full infrastructure lifecycle responsibility. Southeast Asian enterprises lacking in-house VDI expertise favor this model for compliance-managed deployments.
Established volume favors On-Premises; emerging adoption favors Cloud.
End User:
Security certification requirements and procurement scale separate margin profiles across customer tiers.
- Enterprise:Financial services institutions in India deploy desktop virtualization to enable branch workforce mobility while containing endpoint hardware refresh costs. Multi-thousand seat contracts command dedicated engineering support and custom protocol optimization.
- Government:Australia's ASD Essential Eight maturity model mandates application whitelisting and credential hardening for all desktop virtualization procurements. Defense contractors face compressed compliance timelines driving sovereign cloud stack demand.
- SMBs:Capital-constrained organizations adopt per-user DaaS subscriptions to avoid server farm investments. Thailand and Malaysia manufacturing CFOs prioritize opex treatment for IT infrastructure.
- Educational Institutions:Universities provision semester-scale virtual lab environments without permanent endpoint hardware. Seasonal enrollment fluctuations favor consumption-based pricing models.
Procurement scale concentrates in Enterprise; compliance premium concentrates in Government.
Technology:
Protocol performance thresholds and graphics fidelity requirements differentiate technical architectures.
- VDI:Dedicated virtual machines per user deliver isolated desktop environments with persistent personalization. Engineering firms in Vietnam manufacturing corridors adopt GPU-accelerated VDI for CAD workstation virtualization.
- DaaS:Cloud-native desktop delivery eliminates infrastructure ownership through multi-tenant pooling. This segment climbs the fastest as enterprises migrate from capital-intensive on-premises models.
- Application Virtualization:Streams individual software packages without full desktop encapsulation. Legacy ERP integration scenarios favor this lighter-weight approach for SAP client deployment.
- Remote Desktop Services:Session-based sharing of server operating systems maximizes density for task-worker profiles. Call center operations across Philippines and Indonesia adopt this model for cost-sensitive seat provisioning.
Performance isolation favors VDI; density economics favor Remote Desktop Services.
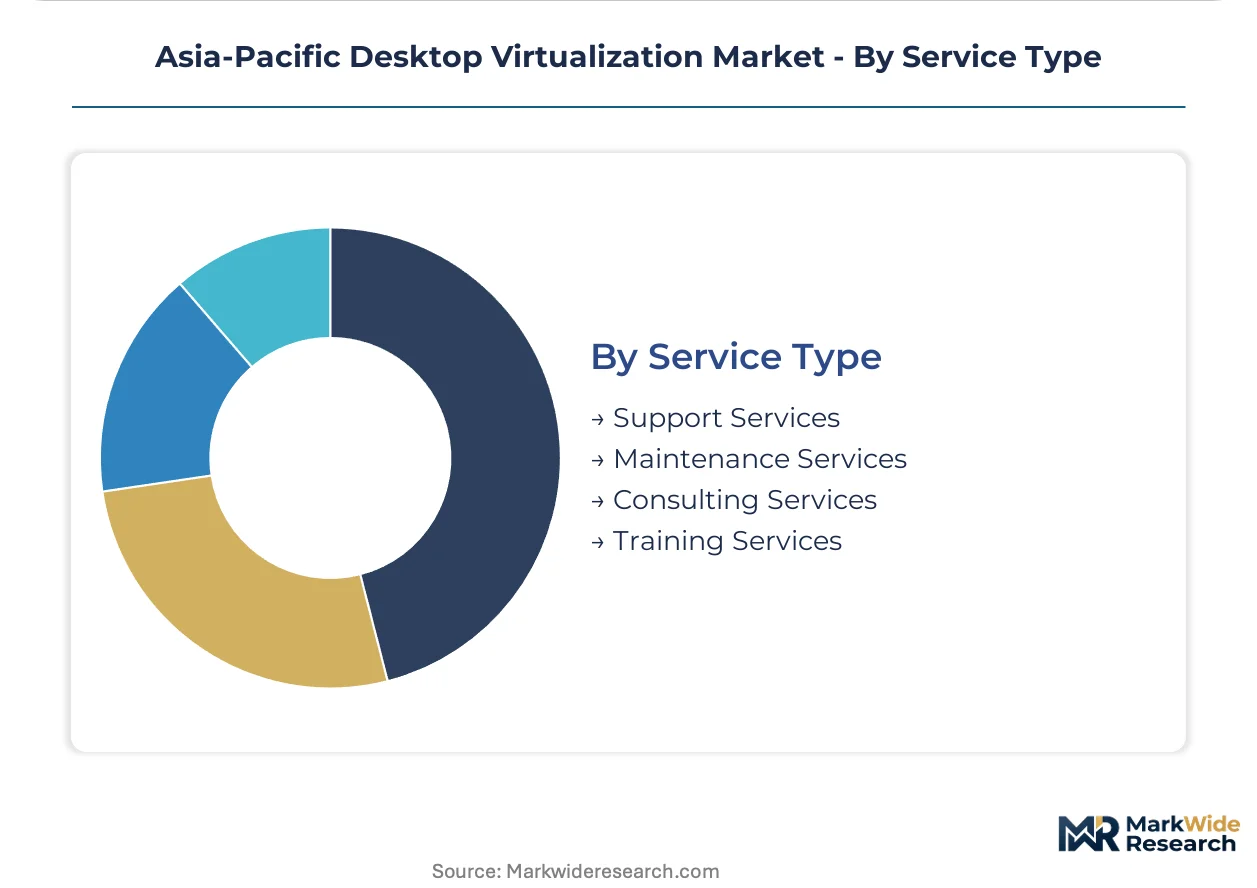
Service Type:
Margin accrual shifts from implementation toward ongoing compliance and optimization services.
- Consulting Services:Architects design sovereign-compliant deployments navigating India's TRAI guidelines and Japan's METI cybersecurity frameworks. Multi-framework certification backlogs extend engagement durations.
- Support Services:24/7 operational assistance for latency-sensitive protocol performance. Mining operations in Western Australia require satellite-optimized HDX troubleshooting for remote exploration camps.
- Maintenance Services:Patch management and hypervisor updates for security posture maintenance. Government end-users mandate these services for continuous ASD Essential Eight compliance.
- Training Services:Administrator certification and end-user onboarding for virtual desktop environments. Educational institutions bundle these with semester-scale lab deployments.
Recurring revenue concentrates in Support Services; project margin concentrates in Consulting Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hypervisor infrastructure concentrates in sovereign data centers across India, Australia, and China, with each jurisdiction imposing distinct compliance architectures that fragment cross-border service delivery. Data-localization mandates from TRAI, BIS, ASD, and MIIT force vendors to maintain parallel certification tracks and redundant infrastructure stacks. These regulatory boundaries reshape procurement patterns and margin distribution across the region.
India
Financial institutions deploy desktop virtualization to satisfy RBI data-residency requirements while enabling branch workforce mobility. TRAI mandates telecom carriers to store subscriber metadata within national boundaries, accelerating sovereign cloud procurement. Mumbai and Bengaluru data centers anchor multi-tenant VDI deployments for banking and IT services sectors.
Australia
Federal agencies migrate OFFICIAL-classified workloads to hybrid architectures blending local infrastructure with cloud burst capacity. ASD Essential Eight maturity models mandate application whitelisting and credential hardening for all desktop virtualization contracts. Sydney and Canberra defense contractors face compressed compliance timelines driving pre-certified sovereign stack demand.
China
State-owned enterprises favor on-premises VDI rollouts for physical custody of citizen and operational data. MIIT cloud service licensing restricts foreign platform providers from operating sovereign data centers serving government and strategic industries. Beijing and Shanghai technology corridors host domestic hypervisor deployments for manufacturing and energy conglomerates.
Japan
Automotive suppliers adopt consumption-based DaaS pricing for seasonal engineering workforce scaling without peak-capacity server investments. METI cybersecurity frameworks establish technical standards for critical infrastructure desktop virtualization. Nagoya and Toyota City manufacturing clusters provision GPU-accelerated virtual workstations for CAD-intensive design cycles.
Singapore
Regional headquarters operations leverage the city-state's fiber infrastructure to deliver sub-20-millisecond virtual desktops across Southeast Asian subsidiaries. Financial services firms utilize Singapore data centers as a compliance hub for cross-border data governance. Marina Bay and Changi technology parks host managed VDI services for multinational corporate networks.
Asia-Pacific Desktop Virtualization Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Asia-Pacific Desktop Virtualization Market. The vendor base stratifies into three tiers: global cloud platforms with enterprise licensing integration, regional specialists delivering sovereign-compliant on-premises stacks, and managed service providers assuming full infrastructure lifecycle responsibility. Competitive moves concentrate on strategic partnerships with telecom carriers for edge-VDI deployment and portfolio diversification into GPU-accelerated workstation virtualization.
Within the global platform tier, VMware and Microsoft Corporation occupy positions defined by hypervisor depth and existing enterprise licensing relationships. Huawei Technologies exemplifies the regional specialist archetype competing aggressively on price-performance for state-owned enterprise deployments in China. Amazon Web Services anchors the cloud-native DaaS segment with multi-tenant infrastructure scaling across Southeast Asian availability zones.
| Leading Market Players |
|---|
| VMware |
| Microsoft Corporation |
| IBM Corporation |
| Citrix Systems |
| Huawei Technologies |
| Dell Technologies |
| Cisco Systems |
| Hewlett Packard Enterprise |
| Amazon Web Services |
| Others |
Pricing and Supply Chain Analysis
Subscription-based DaaS models replacing perpetual VDI licensing simultaneously redistribute supply geography toward sovereign cloud operators and compress pricing premiums for on-premises hardware vendors. India's BIS mandates and Australia's ASD Essential Eight frameworks force foreign platform providers to deploy localized infrastructure stacks, fragmenting procurement across national boundaries while elevating compliance service margins.
Pricing Analysis
India's BIS data-localization guidelines dictate the pricing tier structure across the Asia-Pacific Desktop Virtualization Market. Three-tier pricing stratifies across premium sovereign-cloud deployments, standard hybrid architectures, and economy-grade session-based remote desktop services. Price differentiation rests on certification grade and geographic data residency, with government end-users bearing compliance premiums while SMB manufacturing segments in Thailand and Malaysia drive cost compression through consumption-based DaaS procurement.
Supply Chain Analysis
Just-in-time hypervisor licensing and strategic stockpiling of GPU accelerator cards characterize inventory strategies across desktop virtualization supply chains. Hardware components concentrate in Taiwan for semiconductor fabrication, China for server assembly, and South Korea for memory modules. Supply chain risk centers on MIIT licensing restrictions blocking foreign cloud platforms from Chinese state-owned enterprise procurement. Distribution runs through telecom carrier partnerships for edge-VDI deployment and direct enterprise licensing for multinational corporate networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across India's BIS, Australia's ASD, and China's MIIT creates specialized niche opportunities for compliance-certified platform variants. Sovereign infrastructure requirements splinter demand into national segments where localized expertise commands premium positioning.
For Market Incumbents: Shield installed-base revenue by embedding TRAI-compliant data residency modules into existing multi-tenant deployments. Accelerate certification investments for ASD Essential Eight and METI cybersecurity frameworks before compliance deadlines compress procurement windows. Vertical integration into sovereign data center operations in Mumbai and Sydney anchors physical custody capabilities against pure-cloud competitors.
For New Entrants and Emerging Players: BIS certification fast-tracks unlock India's banking sector procurement cycles where RBI data-residency requirements exclude unaccredited foreign platforms. Target Vietnam's manufacturing corridor for GPU-accelerated VDI deployments serving transient electronics assembly workforces. Lead with managed service wrappers that assume full infrastructure lifecycle responsibility for Southeast Asian enterprises lacking in-house VDI expertise.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional specialists holding sovereign cloud certifications in Australia and Japan. Five-to-ten year viability hinges on sustained regulatory fragmentation preventing global platform consolidation. Monitor TRAI enforcement intensity as the inflection signal—accelerated carrier compliance timelines would compress valuation multiples for uncertified entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BIS and ASD accreditations unlock India's banking and Australia's federal agency procurement pipelines. |
| GPU-Accelerated Workstation Virtualization | CAD-intensive engineering firms in Vietnam and Japan automotive clusters adopt graphics-intensive DaaS for remote design cycles. |
| Telecom Carrier Partnership | 5G network slicing agreements with TRAI-regulated carriers enable sub-20-millisecond edge-VDI delivery to construction sites. |
| Compliance-Managed Service Launch | Third-party operators assuming full infrastructure lifecycle responsibility capture Southeast Asian enterprises lacking VDI expertise. |
| Protocol Optimization Investment | Teradici PCoIP Ultra miniaturization expands addressable geography for mining operations in Western Australia beyond fiber zones. |
Research Methodology
A spread of perspectives from CTOs at financial institutions, IT procurement officers in automotive manufacturing, platform engineers at telecom carriers, and integration specialists at systems integrators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation drawing from SEC filings of listed virtualization vendors, hyperscaler capex disclosures, and regulatory filings with India's TRAI and Australia's ASD. Bottom-up deployment counts triangulated against top-down enterprise IT spending estimates across the analysis window.
Segmentation dimensions modeled include deployment type, end-user security tier, protocol technology, and service type across the projection horizon. CAGRs derived from historical adoption curves weighted by regulatory enforcement timelines and infrastructure investment cycles. Forecast inputs incorporated sovereign data center buildout schedules in Mumbai and Sydney alongside GPU accelerator supply constraints affecting graphics-intensive VDI rollouts.
Underlying assumptions cover sustained data-localization enforcement, with deviation risk concentrated in MIIT licensing liberalization or harmonized regional cybersecurity standards. Revision becomes warranted when cross-border data governance frameworks achieve mutual recognition thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Europe IT Asset Disposition Market
Digital Solutions
Digital Project Delivery Solutions Market
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Digital Clothing Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Business Information Market
Digital Solutions
North America Product Design and Development Services Market
Digital Solutions
Core Graphics Market
Digital Solutions
Healthcare Computerized Maintenance Management System Market
Digital Solutions
Search Engine Optimization Services Market
Digital Solutions
Utility Cases Market
Digital Solutions
Experience Optimization Platforms Market
Digital Solutions
Digital Manufacturing Market
Digital Solutions
Ediscovery Market
Digital Solutions
Digital Onboarding Software Market