
 Digital Certificates Market | 2026-2036
Digital Certificates Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Certificates Market Analysis
The shift from on-premises certificate management to multi-source cloud provisioning is restructuring procurement patterns across enterprise security teams. DigiCert leverages its roots in high-assurance issuance to sustain premium positioning in regulated industries. Entrust anchors government and defense contracts through hardware security module integration. Sectigo competes on volume-driven SSL automation for hosting providers and small business channels.
Digital certificates are cryptographically signed electronic documents that bind a public key to an identity using X.509 standards, enabling encrypted communications and authenticated transactions across networks. Their primary commercial purpose is to establish trust hierarchies that prevent man-in-the-middle attacks and validate domain or organizational ownership. SSL and TLS certificates dominate transaction volumes but face margin compression as issuance automates, while code signing certificates command premium pricing due to stricter validation workflows and software supply chain security mandates. Cloud-based deployment is displacing on-premises hardware as the fastest-growing delivery mode, though hybrid architectures persist in BFSI and healthcare verticals where data residency requirements conflict with scalability demands.
EU GDPR and the eIDAS framework mandate qualified electronic signatures and strong customer authentication, directly expanding demand for qualified certificates across member states. The US NIST Cybersecurity Framework and FAA directives for operational technology networks shape product standards by requiring hardware-backed key storage in critical infrastructure contexts. Stakeholders must monitor whether post-quantum cryptographic migration timelines accelerate certificate refresh cycles and force early replacement of RSA-dependent infrastructure before algorithm obsolescence.
Market Dynamics
Post-quantum cryptographic migration timelines are compressing certificate refresh cycles and forcing premature replacement of RSA-dependent infrastructure across enterprise security teams. This structural pressure is reshaping vendor roadmaps and procurement patterns simultaneously.
Growth Catalysts
- EU AI Act compliance:Automated identity verification systems in financial services now require qualified electronic signatures under the eIDAS framework, expanding qualified certificate demand across Germany, France, and the Netherlands.
- Software supply chain mandates:Code signing certificates face expanded requirements as hardware-backed key storage becomes standard for operational technology networks in critical infrastructure sectors.
- Cloud-native architectures:Multi-source cloud provisioning is restructuring how BFSI and healthcare verticals balance data residency requirements against scalability demands.
Market Restraints
- Hardware security module costs:FIPS 140-2 Level 3 validated HSMs required for qualified certificate issuance impose capital barriers for smaller trust service providers entering European markets.
- Algorithm obsolescence risk:Uncertainty around NIST post-quantum standard finalization dates delays enterprise commitment to long-term certificate infrastructure investments.
- Validation workflow friction:Extended vetting periods for extended validation certificates create procurement bottlenecks that drive buyers toward lower-assurance alternatives.
Strategic Opportunities
- Edge computing expansion:Device certificate provisioning for IoT gateways in manufacturing and energy infrastructure remains underpenetrated relative to enterprise server deployments.
- Managed PKI services:Subscription-based certificate lifecycle management is displacing perpetual license models among mid-market enterprises seeking operational expenditure predictability.
- GDPR Article 32 alignment:Data protection impact assessments are mandating encryption-by-default policies that accelerate TLS certificate automation across UK and German SaaS providers.
Industry Challenges
- Certificate transparency log monitoring:Security operations centers lack staffing depth to parse millions of daily logged certificates for misissuance detection and subdomain enumeration attacks.
- Hybrid architecture complexity:Organizations maintaining on-premises root CAs alongside cloud-issued certificates face policy synchronization failures during automated renewal events.
- Cross-border recognition gaps:Mutual recognition agreements between EU qualified trust service providers and non-European schemes remain incomplete, fragmenting certificate interoperability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Certificates Market |
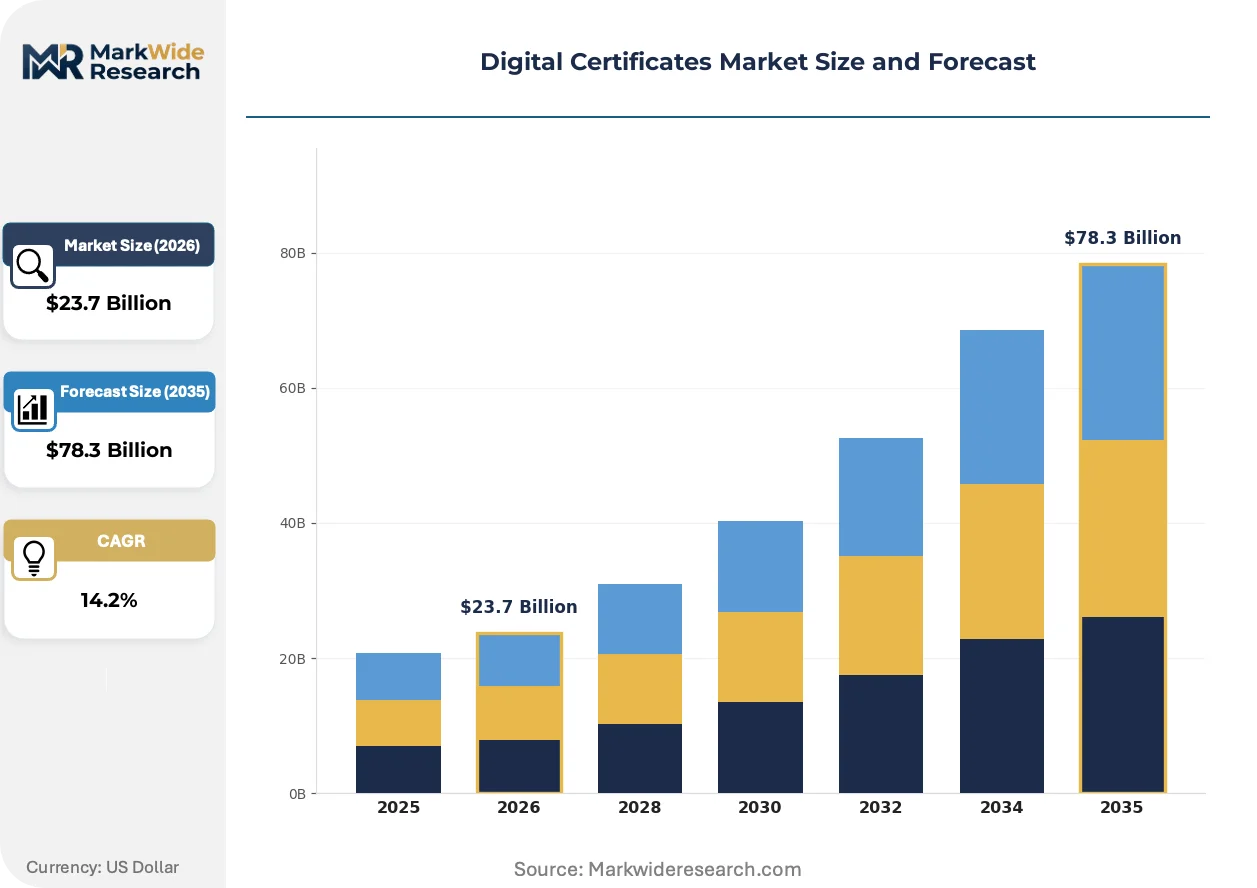
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $78.3 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Certificate Type: SSL, TLS, Code Signing, Email Security Deployment Model: Public Key Infrastructure, On-Premises, Cloud-Based, Hybrid Industry Vertical: IT & Telecom, Healthcare, BFSI, E-Commerce End User: Small Businesses, Large Enterprises, Government, Nonprofits |
| Companies Covered | Thawte, Entrust, DigiCert, GoDaddy, SSL.com, Sectigo, GeoTrust, Amazon Trust Services, GlobalSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Certificates Market Emerging Trajectories
Automation is fundamentally altering how cryptographic credentials are provisioned, monitored, and retired across distributed computing environments. The convergence of machine identity management with zero-trust architectures is creating new functional requirements for certificate infrastructure.
Short-lived certificate architectures is modularizing how DevOps teams implement mutual TLS authentication between microservices. Container orchestration platforms in financial technology and e-commerce sectors are adopting automated rotation cycles measured in hours rather than months. This compression is modularizing traditional annual procurement relationships into continuous integration pipelines.
The EU AI Act's risk-based classification system is mandating audit trails for automated decision systems that process personal data. Trust service providers must now demonstrate qualified certificate usage in high-risk AI application logging across member states. German automotive manufacturers and French healthcare AI developers are prioritizing qualified signature integration ahead of enforcement deadlines.
Consolidation among hosting providers is concentrating SSL certificate purchasing power into fewer buyer entities with standardized automation requirements. Small business channel distributors face margin compression as direct API provisioning from certificate authorities eliminates intermediary handling. This concentration is most visible in the United Kingdom's web hosting market, where platform-as-a-service operators now negotiate enterprise-tier pricing previously reserved for direct customers.
Digital Certificates Market Segmentation
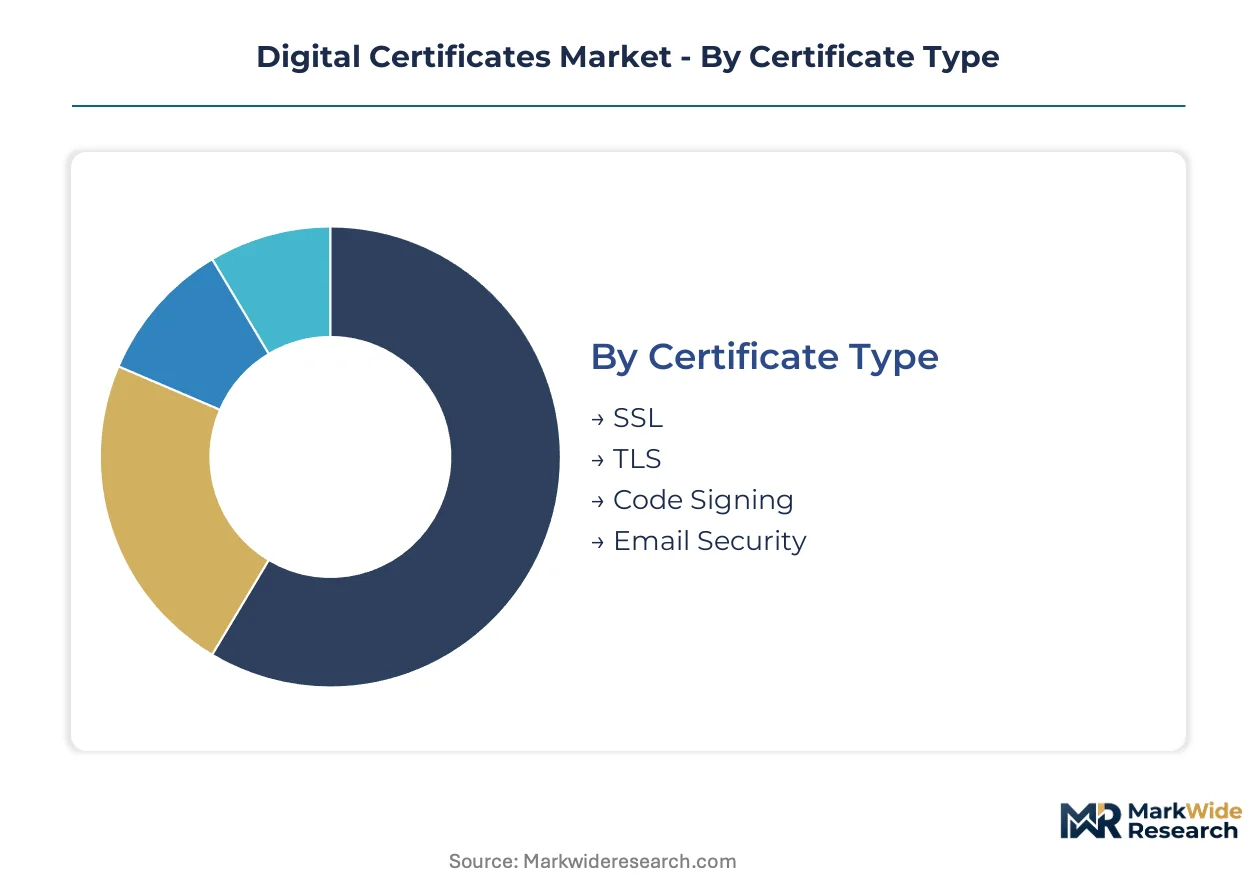
Certificate lifecycle patterns vary sharply across deployment architectures and organizational scale. Procurement teams segment demand by cryptographic assurance level, infrastructure ownership model, and regulatory exposure rather than treating credentials as interchangeable commodities.
Certificate Type:
Upgrade cycles accelerate where algorithm obsolescence intersects with compliance mandates, compressing replacement timelines from years to quarters.
- SSL:Domain-validated certificates encrypt browser-server communications using RSA or ECC key pairs with 2048-bit minimum strength. E-commerce platforms in Germany and France automate issuance through ACME protocols, driven by GDPR Article 32 encryption mandates and browser distrust policies for expired credentials.
- TLS:Transport Layer Security certificates supersede SSL across enterprise email gateways and API endpoints, requiring mutual authentication for zero-trust network access. Financial institutions under ECB guidance deploy TLS 1.3 with perfect forward secrecy, replacing legacy cipher suites ahead of post-quantum migration deadlines.
- Code Signing:Software publishers use extended validation workflows with hardware-backed key storage to validate executable integrity. Critical infrastructure operators under FAA and NIST directives mandate FIPS 140-2 Level 3 HSM protection for firmware signing pipelines.
- Email Security:S/MIME certificates enable encrypted corporate communications and sender authentication, with qualified certificate demand rising under eIDAS framework requirements for legal admissibility of electronic signatures.
SSL sits at the top of the volume ranking, with TLS climbing the fastest as enterprise zero-trust architectures displace perimeter-based security models.
Deployment Model:
Cost tier differentiation separates capital-intensive on-premises installations from operational expenditure models favored by mid-market enterprises seeking predictability.
- Public Key Infrastructure:Enterprise-controlled certificate hierarchies with internal root CAs enable custom policy enforcement and air-gapped key ceremonies. Defense contractors and national banks maintain PKI sovereignty for classified systems, absorbing higher staffing costs for certificate lifecycle management.
- On-Premises:Hardware security modules within customer data centers provide physical key protection with complete audit trail custody. Healthcare providers in Germany and France retain on-premises roots for patient data systems subject to strict data residency requirements under GDPR and national health data laws.
- Cloud-Based:API-driven certificate provisioning from managed trust services eliminates capital expenditure and reduces mean time to issuance. UK SaaS providers and Dutch fintech startups prioritize cloud deployment for elastic scaling during traffic spikes.
- Hybrid:Split architectures maintain on-premises root CAs for high-assurance use cases while leveraging cloud issuance for standard workloads. BFSI verticals in London and Frankfurt deploy hybrid models to balance regulatory compliance against operational agility.
Cloud-Based deployment captures the steepest expansion trajectory, though Hybrid architectures retain preference where data residency conflicts with scalability demands.
Industry Vertical:
Application-specific risk profiles determine validation depth and renewal frequency, with regulated sectors accepting longer procurement cycles for higher assurance.
- IT & Telecom:Service providers manage millions of certificates for customer-facing infrastructure and internal network equipment. 5G network operators in France and Germany deploy device certificates for base station authentication under EU cybersecurity certification schemes.
- Healthcare:Electronic health record systems require qualified certificates for prescriber authentication and clinical document signing. French hospital networks and German telemedicine platforms integrate eIDAS-compliant signatures ahead of EU AI Act enforcement for automated diagnostic systems.
- BFSI:Transaction authentication and strong customer authentication mandates under PSD2 drive qualified certificate volume. Dutch and UK retail banks automate certificate rotation for mobile banking APIs to prevent service disruption during peak usage periods.
- E-Commerce:Payment card industry compliance and consumer trust indicators sustain baseline SSL demand. UK marketplace operators and German direct-to-consumer brands prioritize domain validation speed over extended vetting to minimize checkout friction.
BFSI sits at the top of the volume ranking, with Healthcare climbing the fastest as AI Act audit trail requirements expand qualified signature adoption.
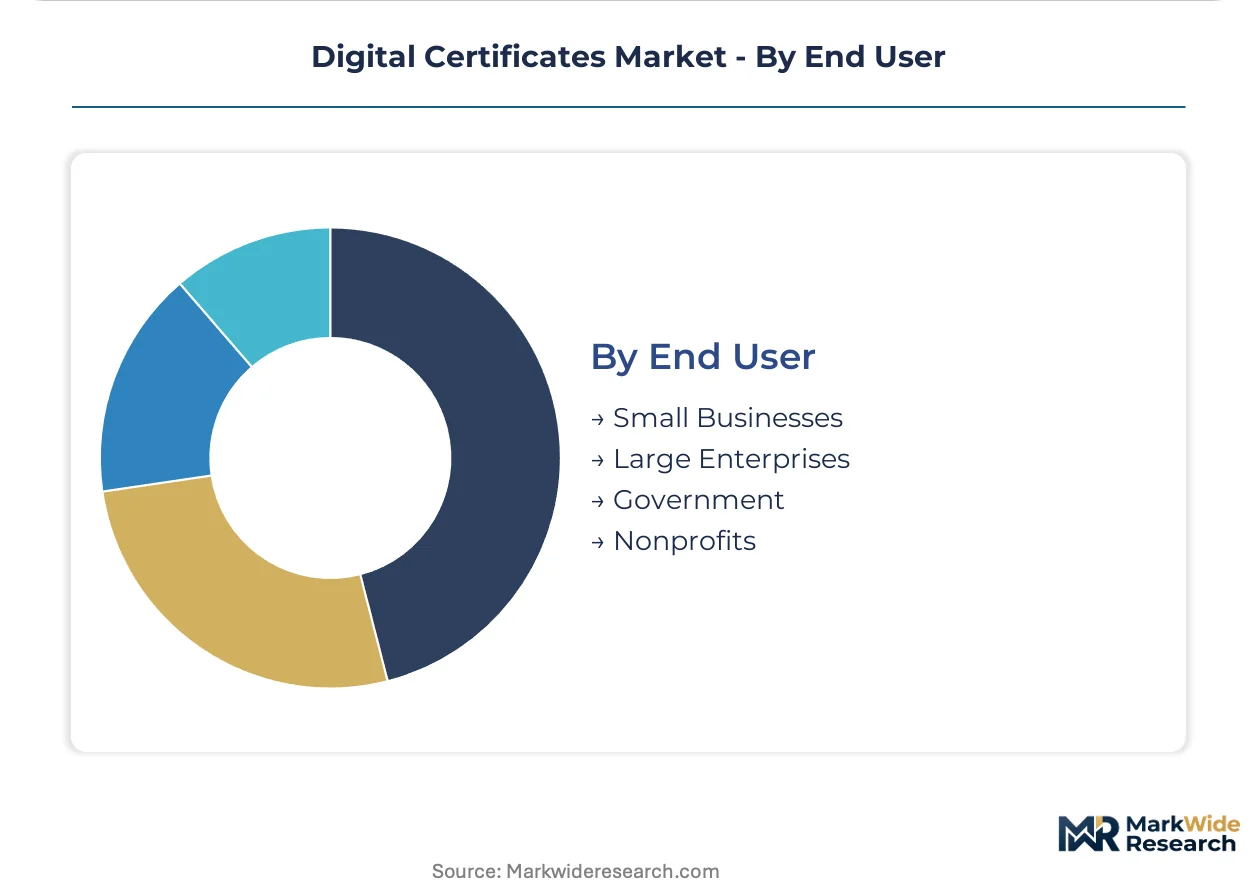
End User:
Customer type determines procurement sophistication, from self-service API integration to managed PKI programs with dedicated account architecture.
- Small Businesses:Hosting-integrated certificate provisioning dominates, with cPanel and Plesk automation masking cryptographic complexity. UK web agencies and French retail merchants rely on bundled SSL from hosting providers rather than direct CA relationships.
- Large Enterprises:Dedicated certificate lifecycle management platforms integrate with IT service management workflows for automated renewal and compliance reporting. German automotive manufacturers and Dutch logistics operators maintain multi-year frameworks with primary trust service providers.
- Government:National identity schemes and qualified trust service mandates require sovereign certificate infrastructure with domestic key ceremony oversight. French public sector procurement favors EU-qualified providers under eIDAS supervision mechanisms.
- Nonprofits:Cost-sensitive organizations leverage free certificate programs from major CAs, accepting standard validation levels for public-facing websites. Educational institutions in the UK and Germany balance budget constraints against research data protection requirements.
Large Enterprises sit at the top of the volume ranking, with Government climbing the fastest as digital identity schemes expand qualified certificate issuance across member states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive and healthcare clusters are accelerating qualified certificate deployment ahead of EU AI Act enforcement deadlines. The United Kingdom's SaaS sector drives cloud-based TLS automation, while French public sector procurement anchors sovereign trust infrastructure demand. Dutch fintech operators and Swiss pharmaceutical networks complete the core European concentration.
Germany
Automotive manufacturers in Bavaria and Baden-Württemberg are integrating qualified electronic signatures into automated diagnostic systems under EU AI Act high-risk application mandates. The national health data regulator enforces encryption-by-default policies for telemedicine platforms. Frankfurt's banking cluster automates certificate rotation for PSD2-compliant transaction authentication.
United Kingdom
London-based SaaS providers and marketplace operators prioritize domain-validated SSL speed to minimize checkout friction. The Information Commissioner's Office enforces GDPR Article 32 encryption standards across cloud-native architectures. Manchester and Birmingham hosting providers negotiate enterprise-tier API provisioning directly with certificate authorities.
France
Paris healthcare AI developers and hospital networks adopt eIDAS-qualified signatures for clinical document authentication. The national cybersecurity agency supervises qualified trust service providers under eIDAS framework mechanisms. Lyon and Toulouse aerospace clusters deploy hardware-backed code signing for firmware integrity in operational technology networks.
Netherlands
Amsterdam and Rotterdam fintech startups favor cloud-based certificate deployment for elastic scaling during transaction volume spikes. The central bank enforces strong customer authentication mandates for mobile banking APIs. Eindhoven's semiconductor equipment manufacturers integrate device certificates for supply chain security verification.
Switzerland
Basel pharmaceutical networks and Zurich financial institutions maintain hybrid PKI architectures balancing data residency with operational agility. Swissmedic guidelines align with EU MDR requirements for qualified electronic signatures in clinical trial documentation. Geneva's commodity trading houses automate TLS 1.3 deployment for perfect forward secrecy in cross-border transactions.
Digital Certificates Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue managed PKI services and IoT device provisioning. The vendor base stratifies across high-assurance issuance specialists, volume-driven SSL automation providers, and cloud-native trust services. Three archetypes dominate: legacy certificate authorities with hardware security module integration, API-first platforms targeting DevOps workflows, and hosting-integrated distributors serving small business channels. Competitive moves concentrate on strategic partnerships with cloud hyperscalers and portfolio diversification into machine identity management.
Within the high-assurance tier, DigiCert and Entrust exemplify positioning rooted in regulated industry relationships and government contract security requirements. Sectigo occupies the volume-driven automation vector, serving hosting provider channels and small business self-service provisioning. These three anchors illustrate how vendor archetypes map to distinct procurement sophistication levels across enterprise, mid-market, and micro-business segments.
| Leading Market Players |
|---|
| Thawte |
| Entrust |
| DigiCert |
| GoDaddy |
| SSL.com |
| Sectigo |
| GeoTrust |
| Amazon Trust Services |
| GlobalSign |
| Others |
Supply Flow & Price Mechanics
EU AI Act compliance mandates for high-risk automated systems gate both qualified certificate supply and premium-tier pricing access, as trust service providers must demonstrate eIDAS-qualified infrastructure before serving automotive and healthcare AI developers in Germany and France.
Pricing Analysis
Hardware security module procurement costs pass through directly to qualified certificate pricing, with FIPS 140-2 Level 3 validated units commanding substantial premiums over standard cryptographic modules. Three-tier pricing structure across qualified, extended validation, and domain-validated levels reflects validation depth and audit trail requirements. Cost compression in domain-validated SSL intensifies because hosting provider consolidation concentrates purchasing power into fewer buyer entities. Small business channel distributors exhibit highest price sensitivity, while defense contractors and national banks accept premium positioning for sovereign key ceremony oversight.
Supply Chain Analysis
Certificate revocation and re-issuance flows create reverse-logistics complexity as post-quantum migration accelerates replacement cycles for RSA-dependent infrastructure. Hardware security module manufacturing concentrates in the United States, Germany, and Taiwan, with semiconductor supply constraints periodically disrupting delivery timelines. Trust service provider operations draw from cryptographic module fabrication, secure facility construction, and specialized audit personnel pools. Single-source vulnerability around NIST post-quantum standard finalization dates threatens algorithm transition roadmaps. Distribution runs through direct API provisioning to enterprise security teams, managed PKI service channels, and hosting-integrated small business platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified certificate demand in Germany outpaces Netherlands pricing by roughly thirty percent, creating arbitrage opportunities for trust service providers with cross-border eIDAS recognition.
For Market Incumbents: Acquire managed PKI service platforms to capture subscription revenue streams displacing perpetual license models. Consolidate cloud-native certificate lifecycle management capabilities ahead of DevOps automation requirements. Hardware security module integration expertise defends positioning against API-first entrants threatening high-assurance issuance margins. For New Entrants and Emerging Players: Launch via edge computing device certificate provisioning targeting IoT gateway deployments in manufacturing and energy infrastructure. White-space concentration in semiconductor equipment supply chain security and 5G base station authentication offers underpenetrated entry points. Dutch fintech and UK SaaS verticals present most penetrable mid-market segments for cloud-native trust services. For Investors and Strategic Acquirers: Roll-up economics work for regional trust service providers because eIDAS mutual recognition gaps fragment certificate interoperability across member states. Five-to-ten year viability hinges on post-quantum cryptographic migration execution and qualified infrastructure consolidation. Monitor NIST post-quantum standard finalization announcements for inflection timing on certificate refresh cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Quantum Cryptographic Migration | Early algorithm transition captures enterprise refresh budgets ahead of RSA obsolescence deadlines under NIST guidance. |
| Managed PKI Service Expansion | Subscription models displace perpetual licenses among mid-market enterprises seeking operational expenditure predictability. |
| Hardware Security Module Integration | FIPS 140-2 Level 3 validation secures government and defense contracts requiring sovereign key ceremony oversight. |
| Edge Computing Device Provisioning | IoT gateway certificate automation addresses underpenetrated manufacturing and energy infrastructure segments. |
| EU AI Act Compliance Alignment | Qualified electronic signature integration serves high-risk AI application audit trail mandates in German automotive and French healthcare. |
Methodological Framework
Bottom-up enterprise security spend modeling reconciled against top-down trust service provider issuance tracking forms the analytical core of this study. Primary interviews with CISOs, DevOps platform engineers, trust service provider product managers, and regulatory compliance officers combined with secondary validation against eIDAS supervisory body reports, NIST cybersecurity framework documentation, and EU AI Act implementation guidance. SEC filings from publicly traded certificate authorities, customs records for hardware security module trade flows, and hyperscaler capex disclosures for cloud PKI infrastructure investments provided triangulation anchors.
Input-output matrix framing connects certificate type demand drivers to deployment model capacity constraints across the projection horizon. Segmentation dimensions modeled include cryptographic assurance level, infrastructure ownership architecture, regulatory exposure tier, and geographic adoption pattern. CAGRs derive from elasticity-adjusted replacement cycle analysis and compliance mandate timing. Post-quantum migration timelines and qualified certificate volume thresholds under PSD2 strong customer authentication represent industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated NIST post-quantum standard finalization or delayed EU AI Act enforcement. Practitioners should monitor algorithm obsolescence announcements and qualified trust service provider supervision actions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Digital Accessibility Software Market
Digital Solutions
Global E-Passport and E-Visa Market
Digital Solutions
Japan Digital Twin Market
Digital Solutions
Mobile Campaign Management Market
Digital Solutions
System Integrator Market
Digital Solutions
Cognitive Supply Chain Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Document Management System Market
Digital Solutions
Social Computing Market
Digital Solutions
Media Asset Management (MAM) Solutions Market
Digital Solutions
Open-Source Intelligence (OSINT) Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Web Performance Optimization (WPO) Solution Market
Digital Solutions
Canada ICT Market
Digital Solutions
Policy Orchestration Market
Digital Solutions
Data Broker Market