
 Work From Home Setup Market | 2026-2036
Work From Home Setup Market Size, Share, and Industry Trends Forecast 2026-2036
Work From Home Setup Market Insights
Enterprise procurement teams is rotating toward individual employee stipends as the dominant purchasing channel for home office equipment. HP leverages its direct-to-employee fulfillment platforms to capture this decentralized demand. Dell Technologies anchors its competitive position through configurable workstation bundles tailored to corporate remote-work policies. IKEA competes on price-accessible ergonomics, extending its flat-pack logistics model into residential delivery.
Work From Home Setup encompasses furniture, peripherals, lighting, and connectivity hardware designed for sustained residential productivity, typically incorporating adjustable height mechanisms, lumbar support systems, and electromagnetic interference shielding in monitor arms. Ergonomic chairs and adjustable desks dominate product-type revenue, while video conferencing tools and smart lighting within the technology segment capture expanding margin pools as employers prioritize professional video presence. Corporate employees and freelancers within the end-user dimension show divergent purchasing patterns, with the former demanding IT-integrated bundles and the latter seeking modular, upgradeable components.
OSHA guidelines in the United States and EU ergonomics directives under the European Agency for Safety and Health at Work shape product certification requirements for seating and display positioning equipment. REACH compliance in Europe and California Proposition 65 restrictions constrain material selection for foam cushioning and plastic housings, elevating compliance costs for cross-border suppliers. Stakeholders must monitor evolving employer liability frameworks for home workplace injuries, as jurisdictional ambiguity around remote-site coverage threatens to reshape insurance and indemnification structures.
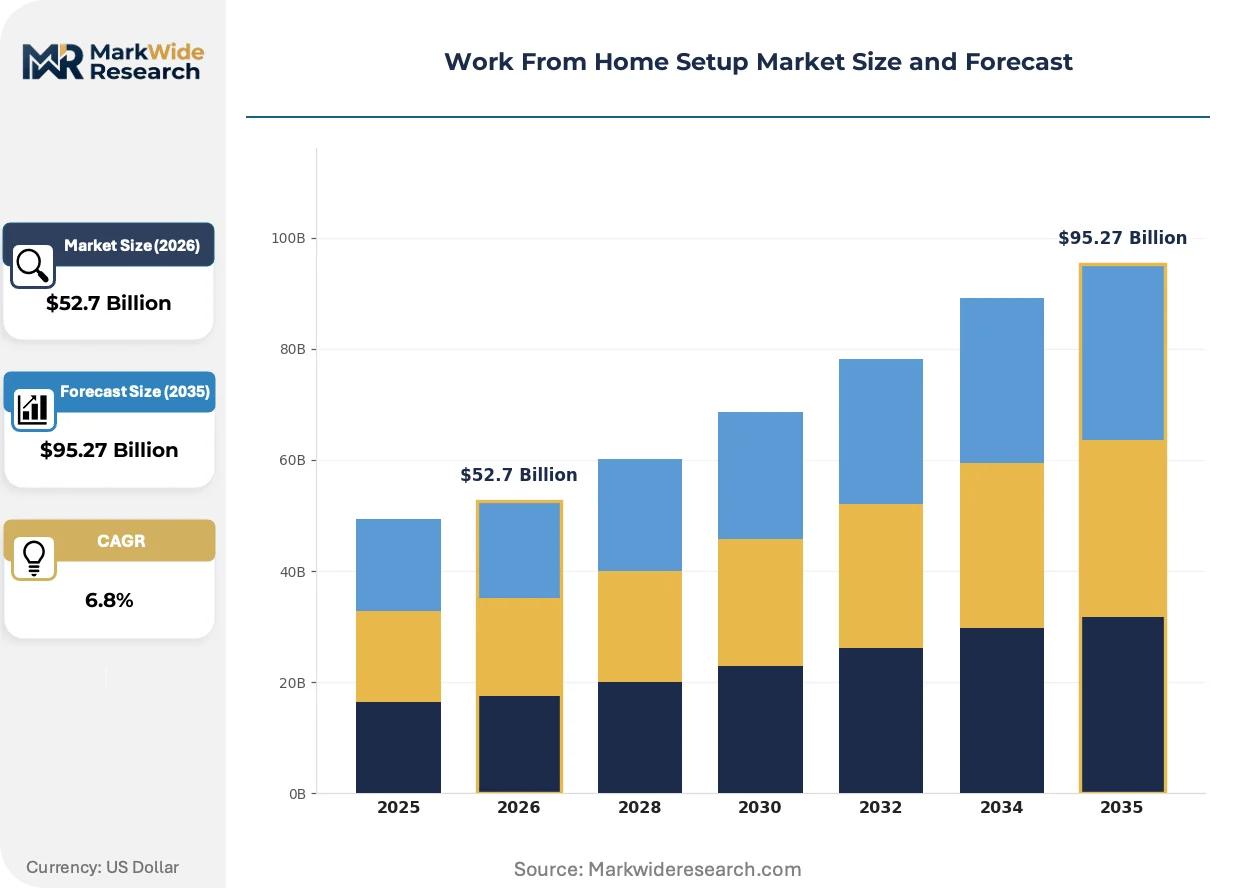
Market Dynamics
Enterprise stipend programs are decentralizing procurement authority from IT departments to individual employees, fragmenting volume concentration and forcing manufacturers to build direct-to-employee fulfillment capabilities.
Growth Catalysts
- OSHA ergonomic guidelines:United States employers face expanded liability exposure for home workplace injuries, accelerating investment in certified seating and adjustable monitor arms that meet federal safety thresholds.
- Video-first collaboration protocols:Technology sector employers mandate professional-grade lighting and camera positioning for distributed teams, pulling smart illumination and acoustic panels into standard equipment bundles.
- Hybrid work policy stabilization:Corporate real estate reductions in major metropolitan clusters free capital for sustained residential infrastructure spending among knowledge workers.
Market Restraints
- Memory foam input volatility:Petrochemical feedstock price swings compress margin stability for cushioning manufacturers dependent on polyurethane supply chains concentrated in Gulf Coast production corridors.
- Cross-border certification friction:REACH chemical restrictions in Europe and California Proposition 65 disclosure requirements force dual testing protocols, elevating compliance overhead for unified product lines.
- Flat-pack shipping density limits:Ergonomic chair volumetric weight ratios constrain last-mile economics, privileging regional assembly hubs over centralized manufacturing.
Strategic Opportunities
- Smart home convergence:Voice assistant integration and circadian lighting algorithms are bifurcating the peripheral category, creating premium attach-rate potential for connected desk ecosystems.
- Freelancer modular upgrade paths:Independent contractors seek component-swappable systems rather than bundled replacements, opening subscription-based hardware refresh models.
- EU Green Deal circularity mandates:Take-back and recycling requirements for electronics housings incentivize design-for-disassembly patents and closed-loop material partnerships.
Industry Challenges
- Electromagnetic interference certification:Monitor arm manufacturers face extended FCC testing timelines for integrated USB-C and wireless charging hubs, delaying product launches.
- Legacy ERP integration:Direct-to-employee fulfillment platforms require real-time inventory visibility incompatible with corporate procurement systems built for batch requisition workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Work From Home Setup Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ergonomic Chairs, Adjustable Desks, Monitor Stands, Noise-Cancelling Headphones, Desk Lamps Technology: Wireless Connectivity, Voice Assistance, Smart Lighting, Cable Management Systems, Video Conferencing Tools Application: Remote Collaboration, Personal Productivity, Virtual Training, Customer Support, Content Creation End User: Freelancers, Corporate Employees, Educators, Entrepreneurs, Consultants |
| Companies Covered | Logitech, HP, Dell Technologies, Herman Miller, Steelcase, Humanscale, IKEA, Amazon, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Work From Home Setup Market Trends and Innovations
Biomechanical sensor integration and adaptive environmental controls are transforming static furniture into responsive productivity infrastructure. Three developments warrant particular attention.
Adjustable desk actuators with embedded posture monitoring are bifurcating the workstation category. Corporate wellness programs in the United States subsidize these systems for high-utilization remote employees. The technology compresses traditional furniture replacement cycles by enabling software-defined ergonomic adjustments.
REACH substance restrictions and EU Green Deal circularity requirements are tightening material specifications for foam cushioning and plastic structural components. Manufacturers serving European markets must reformulate supply chains to eliminate restricted flame retardants and establish verified recycling streams. Seating producers with German and French distribution footprints face the most compressed compliance timelines.
Individual employee stipends are displacing centralized IT procurement for peripheral categories. Technology sector employers in Seattle, Austin, and San Francisco clusters lead this transition. Channel partners must rebuild commission structures around self-service selection tools rather than enterprise sales relationships.
Work From Home Setup Market Segmentation
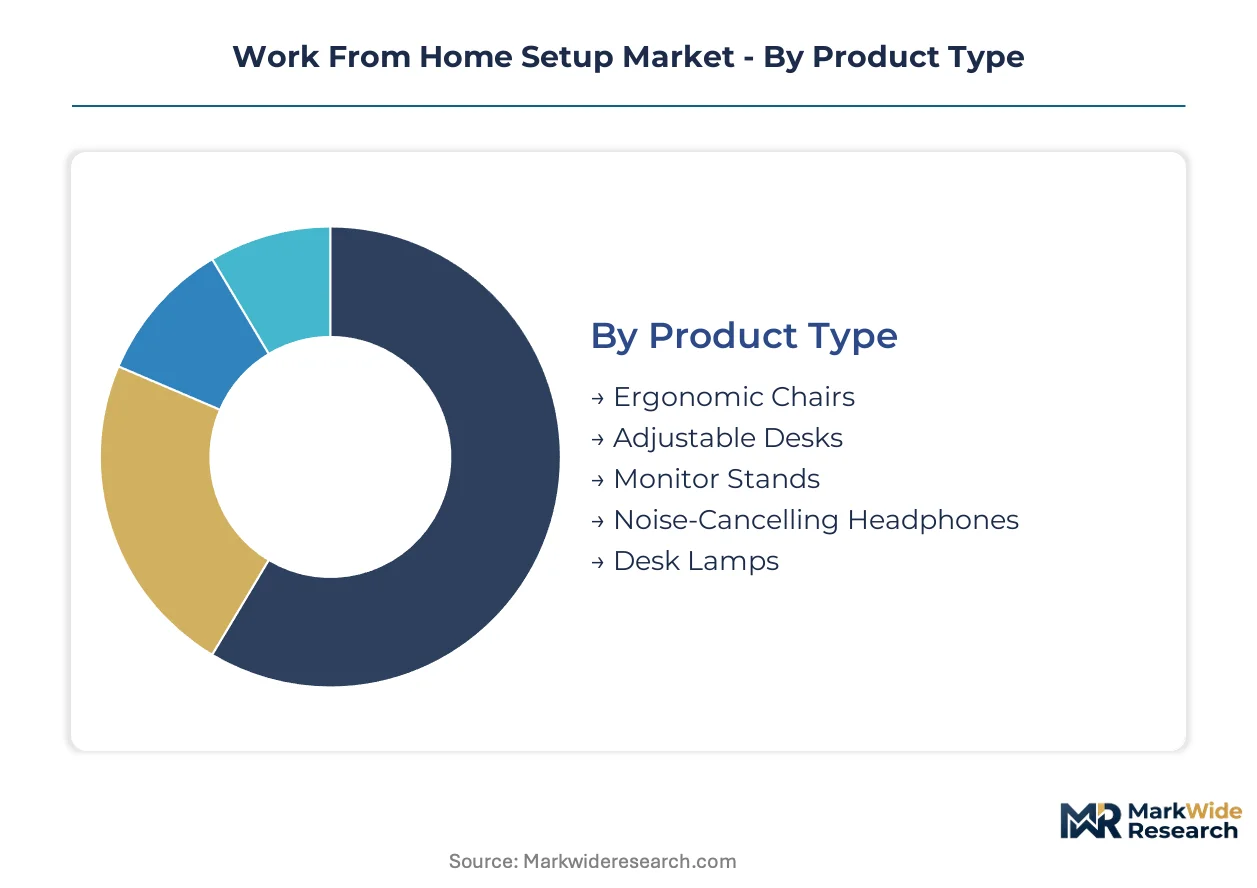
Segmentation in the Work From Home Setup Market reveals divergent compliance burdens and purchasing authority patterns across product categories. OSHA seating certifications, FCC electromagnetic approvals, and REACH substance restrictions create tiered regulatory exposure that reshapes manufacturer prioritization and channel investment.
Product Type:
OSHA ergonomic guidelines and EU machinery directives impose divergent testing protocols on seating versus peripheral categories, elevating compliance costs for cross-border suppliers.
- Ergonomic Chairs:Lumbar support systems with adjustable armrests and seat depth mechanisms dominate procurement volume. Corporate stipend programs in the United States concentrate demand for certified seating that meets federal safety thresholds, though memory foam input volatility compresses margin stability for polyurethane-dependent manufacturers.
- Adjustable Desks:Electric actuators with embedded height memory and anti-collision sensors define the technical specification. Seattle and Austin technology employers subsidize these systems for high-utilization remote employees, compressing traditional furniture replacement cycles through software-defined ergonomic adjustments.
- Monitor Stands:VESA-compatible arms with integrated cable routing and USB-C hubs.
- Noise-Cancelling Headphones:Active noise reduction with beamforming microphones for video-first collaboration protocols.
- Desk Lamps:Circadian lighting algorithms with voice assistant integration.
Ergonomic chairs handle the majority of throughput; adjustable desks are expanding most quickly on share as hybrid policies stabilize.
Technology:
Cost tier differentiation separates premium connected ecosystems from baseline utility peripherals, with voice assistance and smart lighting commanding attach-rate premiums.
- Smart Lighting:Tunable white LED arrays with circadian rhythm algorithms and occupancy sensing. Technology sector employers in San Francisco clusters mandate professional-grade illumination for distributed teams, pulling these systems into standard equipment bundles.
- Video Conferencing Tools:4K cameras with auto-framing and acoustic echo cancellation. Corporate procurement teams prioritize IT-integrated bundles that satisfy video-first collaboration protocols, displacing standalone peripheral purchases.
- Wireless Connectivity:Bluetooth 5.3 and Wi-Fi 6E protocols for peripheral pairing.
- Voice Assistance:Embedded microphones with natural language processing for environmental control.
- Cable Management Systems:Electromagnetic interference shielding for power and data routing.
Smart lighting captures the steepest margin expansion; video conferencing tools are gaining share fastest as employer subsidy programs mature.
Application:
Customer type fragmentation splits procurement patterns between employer-subsidized standardization and individual modular preferences.
- Remote Collaboration:Acoustic paneling and camera positioning equipment optimized for synchronous video communication. United States technology sector employers drive standardization through centralized IT procurement for this use case.
- Content Creation:Color-accurate displays and adjustable mounting systems for multimedia production. Freelancers in creative clusters seek component-swappable systems rather than bundled replacements, opening subscription-based hardware refresh models.
- Personal Productivity:Ergonomic seating and task lighting for individual focus work.
- Virtual Training:Dual-monitor configurations with annotation capture capabilities.
- Customer Support:Noise isolation and headset integration for call-intensive roles.
Remote collaboration handles the majority of throughput; content creation is climbing the fastest on share as independent contractor populations expand.
End User:
Purchasing authority concentration varies sharply between institutional stipend channels and direct consumer acquisition.
- Corporate Employees:Knowledge workers receiving employer-funded equipment allowances through decentralized self-service platforms. HP and Dell Technologies compete for this segment through direct-to-employee fulfillment capabilities.
- Freelancers:Independent contractors purchasing modular, upgradeable components without institutional subsidy. IKEA price-accessible ergonomics and flat-pack logistics capture this price-sensitive demand.
- Educators:Institutional procurement for remote instruction infrastructure.
- Entrepreneurs:Self-funded investment in professional-grade residential productivity systems.
- Consultants:Mobile professionals requiring portable peripheral configurations.
Corporate employees handle the majority of throughput; freelancers are gaining share fastest as platform economy participation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States' dense fiber-optic backbone and last-mile delivery infrastructure underwrites its dominance in remote work equipment distribution. Cross-border data corridors and integrated logistics networks enable rapid fulfillment across North American and European markets.
United States
OSHA ergonomic guidelines and employer liability frameworks accelerate certified seating procurement for distributed teams. Technology sector employers in Seattle, Austin, and San Francisco subsidize adjustable desk systems and smart lighting through individual stipend programs. The Pacific Northwest corridor concentrates demand for biomechanical sensor-integrated workstations.
Germany
EU machinery directives and REACH chemical restrictions impose dual compliance burdens on foam cushioning and plastic structural components. Industrial clusters in North Rhine-Westphalia and Baden-Württemberg host seating manufacturers reformulating supply chains to eliminate restricted flame retardants. Berlin-Brandenburg emerges as a testbed for circularity-mandated take-back programs.
United Kingdom
Corporate real estate reductions in London and Southeast England free capital for sustained residential infrastructure spending. HSE ergonomic regulations shape product certification requirements for display positioning equipment. The Midlands manufacturing belt adapts flat-pack logistics models to serve decentralized employee procurement.
Japan
METI standards for electromagnetic interference constrain monitor arm integrated hub designs, extending FCC testing timelines for unified product lines. Tokyo-Osaka corridor employers mandate professional-grade video presence equipment for hybrid collaboration. Kansai region distributors rebuild commission structures around self-service selection tools.
India
BIS certification requirements and expanding platform economy participation drive modular component demand among independent contractors. Karnataka and Maharashtra technology clusters adopt employer-subsidized ergonomic equipment for distributed engineering teams. Delhi-NCR emerges as a price-accessible logistics hub for flat-pack residential delivery.
Work From Home Setup Market Competitive Landscape
Listed leaders compete with private specialists across fulfillment capabilities and compliance architectures. The vendor base stratifies into three tiers: direct-to-employee fulfillment platforms, configurable workstation bundlers, and price-accessible flat-pack logistics operators. Competitive positioning depends on real-time inventory visibility, cross-border certification management, and regional assembly hub density. M&A activity concentrates on circularity patent portfolios and voice assistant integration licenses.
Within the direct-to-employee fulfillment tier, HP and Dell Technologies exemplify platform-centric architectures, while IKEA occupies a position anchoring price-accessible ergonomics. HP leverages direct-to-employee fulfillment capabilities to capture decentralized stipend demand. Dell Technologies anchors competitive positioning through configurable workstation bundles. IKEA extends flat-pack logistics expertise into residential delivery for independent contractors.
| Leading Market Players |
|---|
| Logitech |
| HP |
| Dell Technologies |
| Herman Miller |
| Steelcase |
| Humanscale |
| IKEA |
| Amazon |
| Microsoft |
| Others |
Pricing and Supply Chain Analysis
OSHA ergonomic guidelines and EU machinery directives gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb certification costs into tiered product architectures while buyers sort across federal safety thresholds and premium feature bundles. Corporate stipend programs fragment volume concentration, compressing margin stability for cross-border suppliers navigating dual testing protocols.
Pricing Analysis
Volume-discount tiering structures separate enterprise procurement contracts from individual employee stipend purchases, with certified seating commanding premiums over baseline utility configurations. Price differentiation hinges on OSHA compliance tier and embedded sensor integration, with technology sector employers in Seattle and Austin clusters showing lowest price sensitivity for biomechanical monitoring systems. Cost compression in polyurethane-dependent cushioning categories intensifies because petrochemical feedstock volatility compresses margin stability for mid-tier manufacturers. Freelancers purchasing through flat-pack channels exhibit highest price sensitivity, prioritizing modularity over certification grade.
Supply Chain Analysis
China and Vietnam anchor foam cushioning and plastic component fabrication, while Taiwan and South Korea dominate electric actuator and sensor module production. Raw material dependencies center on polyurethane feedstocks, rare-earth magnets for desk motors, and tunable white LED arrays. Single-source vulnerability concentrates in Gulf Coast petrochemical corridors, where hurricane exposure threatens cushioning input stability. Distribution runs through regional assembly hubs in North America and Europe, privileging last-mile density over centralized manufacturing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise stipend decentralization fragments purchasing authority into thousands of individual decision nodes, creating white-space opportunities for direct-to-employee fulfillment platforms and modular component specialists.
For Market Incumbents: Secure circularity patent portfolios ahead of EU Green Deal take-back mandates, and lock regional assembly hub density in Pacific Northwest and Texas corridors to defend against flat-pack logistics entrants. Certification investment in REACH-compliant foam formulations represents the critical lever for European market retention. For New Entrants and Emerging Players: Anchor in freelancer modular upgrade paths, where component-swappable systems and subscription-based hardware refresh models remain underpenetrated relative to corporate stipend saturation. Voice assistant integration licenses offer the most penetrable technology wedge for peripheral category entry. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified furniture conglomerates with dormant ergonomic seating divisions, where compliance architecture and stipend-channel relationships can be reactivated. Watch employer liability framework clarifications for home workplace injury coverage as the inflection signal for insurance-linked equipment subsidy expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Employee Fulfillment Platform Buildout | HP and Dell Technologies capture decentralized stipend demand through self-service selection tools. |
| Backward Integration into Actuator Manufacturing | Adjustable desk producers secure supply stability for electric height-memory systems. |
| Circularity Patent Portfolio Acquisition | Seating manufacturers establish design-for-disassembly capabilities ahead of EU mandates. |
| Voice Assistant Integration Licensing | Peripheral producers attach premium pricing to connected desk ecosystems. |
| Regional Assembly Hub Expansion | Flat-pack logistics operators compress last-mile delivery costs for ergonomic chairs. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with corporate procurement officers, ergonomic equipment manufacturers, flat-pack logistics operators, and workplace safety consultants; and secondary validation through OSHA technical documentation, EU machinery directive filings, SEC 10-K supply chain disclosures, and customs trade data for foam cushioning inputs. Bottom-up triangulation across employer stipend program structures and top-down reconciliation against residential furniture shipment volumes anchored value estimates.
Across the analysis window, forecasts model product type segmentation by certification tier, technology segmentation by connectivity protocol, application segmentation by employer subsidy status, and end-user segmentation by purchasing authority concentration. CAGRs derive from employer real estate reduction trajectories and hybrid policy stabilization curves, with petrochemical feedstock volatility and cross-border certification friction as key sensitivity inputs.
Decision-makers should treat outputs as directional under stable employer liability frameworks and continued technology sector stipend subsidization; material deviation in home workplace injury coverage case law would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Quality Process Management Application Market
Digital Solutions
Europe Digital Twin Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Big Data and Data Engineering Services Market
Digital Solutions
Intelligent Virtual Store Design Solution Market
Digital Solutions
South Korea Cloud OSS BSS Market
Digital Solutions
Boat Navigation Software Market
Digital Solutions
Subscription (Digital) Services Market
Digital Solutions
Virtual Client Computing Market
Digital Solutions
Global Dock and Yard Management System Market
Digital Solutions
Smart Recording Pen Market
Digital Solutions
Docker Monitoring Market
Digital Solutions
North America IT Asset Disposition Market
Digital Solutions
Voice Remote Control Market
Digital Solutions
Service Virtualization Market
Digital Solutions
Enterprise Application Integration (EAI) Market