
 IPTV Market | 2026-2036
IPTV Market Size, Share, and Industry Trends Forecast 2026-2036
IPTV Market Intelligence
Subscription-based leasing of CDN infrastructure and content licensing is reconfiguring capital requirements for new entrants. Fubo TV leverages sports-centric vertical integration to sustain customer lifetime value in a crowded field. CatchON TV anchors its position through aggressive geographic pricing in emerging broadband markets. Apollo Group TV differentiates via curated international channel bundles that appeal to diaspora communities.
Internet protocol television delivers multicast or unicast video streams over packet-switched networks using MPEG transport streams or HLS/DASH adaptive bitrate protocols, with primary commercial purpose of replacing traditional terrestrial, satellite, and cable distribution with interactive, addressable media services. Video on Demand and Live TV command the largest revenue pools, while Time-Shifted TV and Catch-up TV represent the fastest-expanding service types as cloud DVR functionality becomes standard. Fiber Optic technology leads infrastructure deployments for quality-of-service guarantees, though Satellite remains critical for rural last-mile coverage.
FCC net neutrality enforcement and the EU AI Act content moderation obligations shape how IPTV platforms manage traffic prioritization and algorithmic recommendation transparency. India's TRAI tariff orders and BIS streaming quality standards further constrain pricing flexibility and technical service parameters. Stakeholders must monitor how convergence between IPTV and 5G broadcast multicast services alters competitive moats and infrastructure partnerships.
Market Dynamics
Fiber-to-the-home deployments and cloud-native delivery architectures are compressing infrastructure costs while fragmenting subscriber bases across multicast and unicast protocols. This structural shift forces operators to rebuild monetization models around addressable advertising and tiered quality-of-service guarantees rather than flat subscription fees.
Growth Catalysts
- EU AI Act transparency mandates:Algorithmic recommendation disclosure requirements accelerate investment in explainable content curation engines that improve subscriber retention metrics.
- India PLI scheme for telecom equipment:Domestic manufacturing incentives reduce set-top box and fiber termination unit costs for regional service providers expanding into tier-2 cities.
- HLS/DASH adaptive bitrate protocols:These streaming standards enable consistent quality across variable broadband conditions, lowering churn in emerging markets with uneven last-mile infrastructure.
Market Restraints
- Content licensing concentration:Sports and premium entertainment rights aggregators in Western Europe extract disproportionate revenue shares, compressing operator margins.
- Satellite backhaul dependency:Rural coverage requirements in Brazil and Indonesia tie providers to geostationary capacity with high per-gigabyte transport costs.
- FCC net neutrality uncertainty:Traffic prioritization rule ambiguity prevents long-term quality-of-service contracting with enterprise video customers.
Strategic Opportunities
- 5G broadcast multicast convergence:Integration of 3GPP Release 17 multicast capabilities with IPTV core networks enables stadium and venue direct-to-mobile streaming without cellular congestion.
- Time-Shifted TV cloud DVR expansion:Regulatory storage mandates in South Korea and Japan create forced upgrade cycles for legacy hardware-based recording systems.
- Diaspora channel bundling:Curated international packages targeting South Asian, Middle Eastern, and Latin American expatriate communities command premium pricing in North American and European urban clusters.
Industry Challenges
- Multicast-to-unicast migration complexity:Legacy MPEG transport stream headends require parallel operation during IPv6 transition periods, doubling operational overhead.
- Cloud DVR compliance fragmentation:Divergent recording duration limits across German federal states and Indian TRAI tariff orders force jurisdiction-specific storage architectures.
- Low-latency live streaming engineering:Sub-two-second delay requirements for sports betting synchronization demand edge compute investments that strain capex planning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IPTV Market |
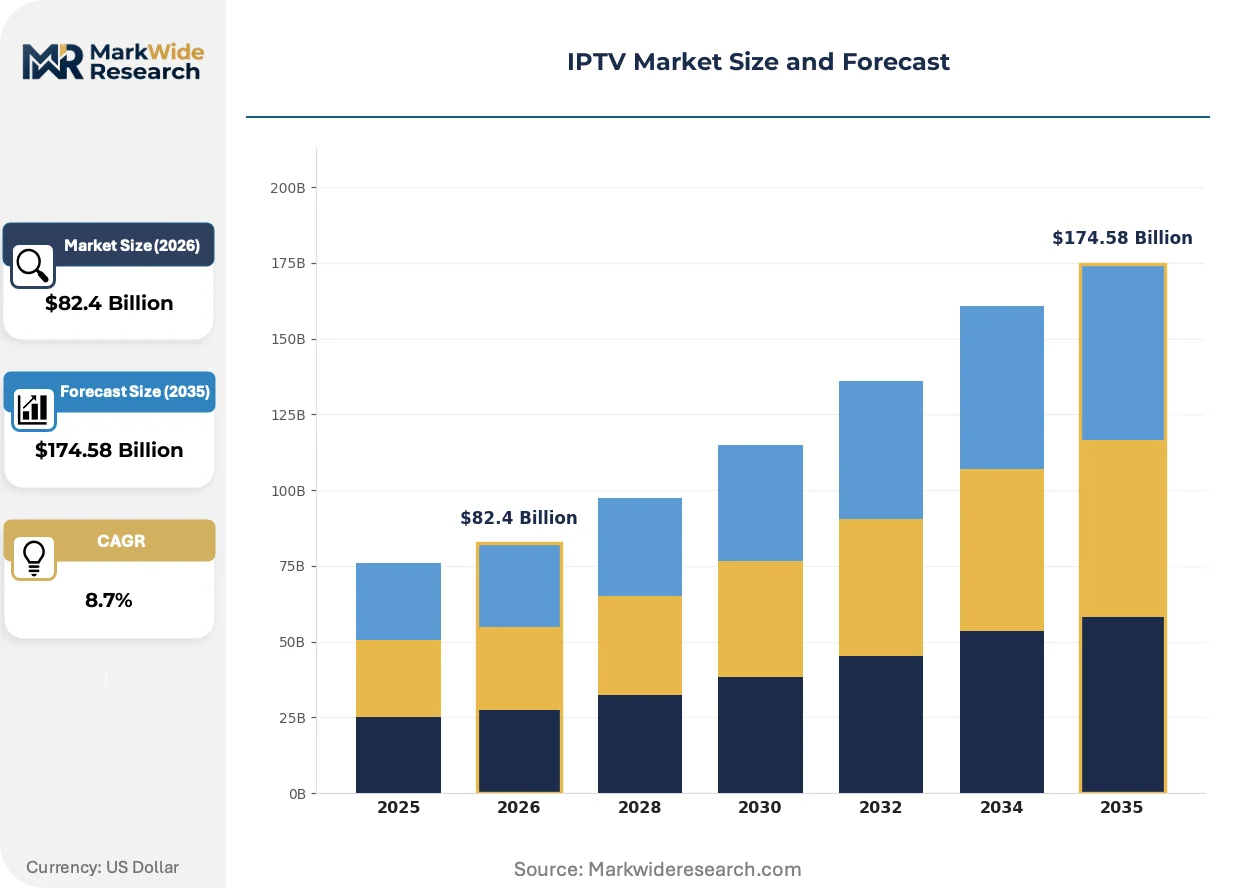
| Market Size in 2026 | $82.4 Billion |
| Market Size in 2035 | $174.58 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Video on Demand, Live TV, Time-Shifted TV, Near Video on Demand, Catch-up TV Technology: Internet Protocol Multicast, Asynchronous Transfer Mode, Digital Subscriber Line, Fiber Optic, Satellite, Cable Application: Residential Entertainment, Hospitality, Education & Training, Corporate Communication, Government Broadcasting End User: Home Users, Hotels & Resorts, Educational Institutions, Enterprises, Public Administration |
| Companies Covered | JBNOTT, CatchON TV, ZYMINEX, Fubo TV, Xtreme HD IPTV, IPVARIO, Lumo IPTV, Apollo Group TV, TELEVIXY, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IPTV Market Strategic Shifts & Innovations
Software-defined video processing and edge caching architectures are collapsing traditional content delivery cost structures while enabling personalization at scale. These shifts reconfigure competitive advantage around data infrastructure rather than spectrum ownership.
Server-side ad insertion technology is collapsing the distinction between broadcast and digital advertising workflows. Tier-1 operators in Germany and the United States are deploying frame-accurate replacement engines that swap national spots for household-level targeted creative. This compression of ad-tech stacks enables revenue per subscriber to approach levels previously reserved by pure-play streaming platforms.
The EU AI Act content moderation obligations are forcing algorithmic transparency disclosures for recommendation engines across all member states. IPTV platforms must now document training data provenance and provide user-facing explanation interfaces. French and Italian regulators are conducting the first compliance audits, with penalties tied to annual turnover creating immediate operational priority for technical documentation teams.
Household procurement of video services is fragmenting across multiple app-based subscriptions rather than consolidating through traditional IPTV bundles. Younger demographics in urban India and Southeast Asian markets are bypassing operator set-top boxes entirely, accessing content through smart TV native applications. This channel disintermediation pressures wholesale content licensing terms and forces operators to rebuild distribution economics around broadband-only relationships.
IPTV Market Segmentation
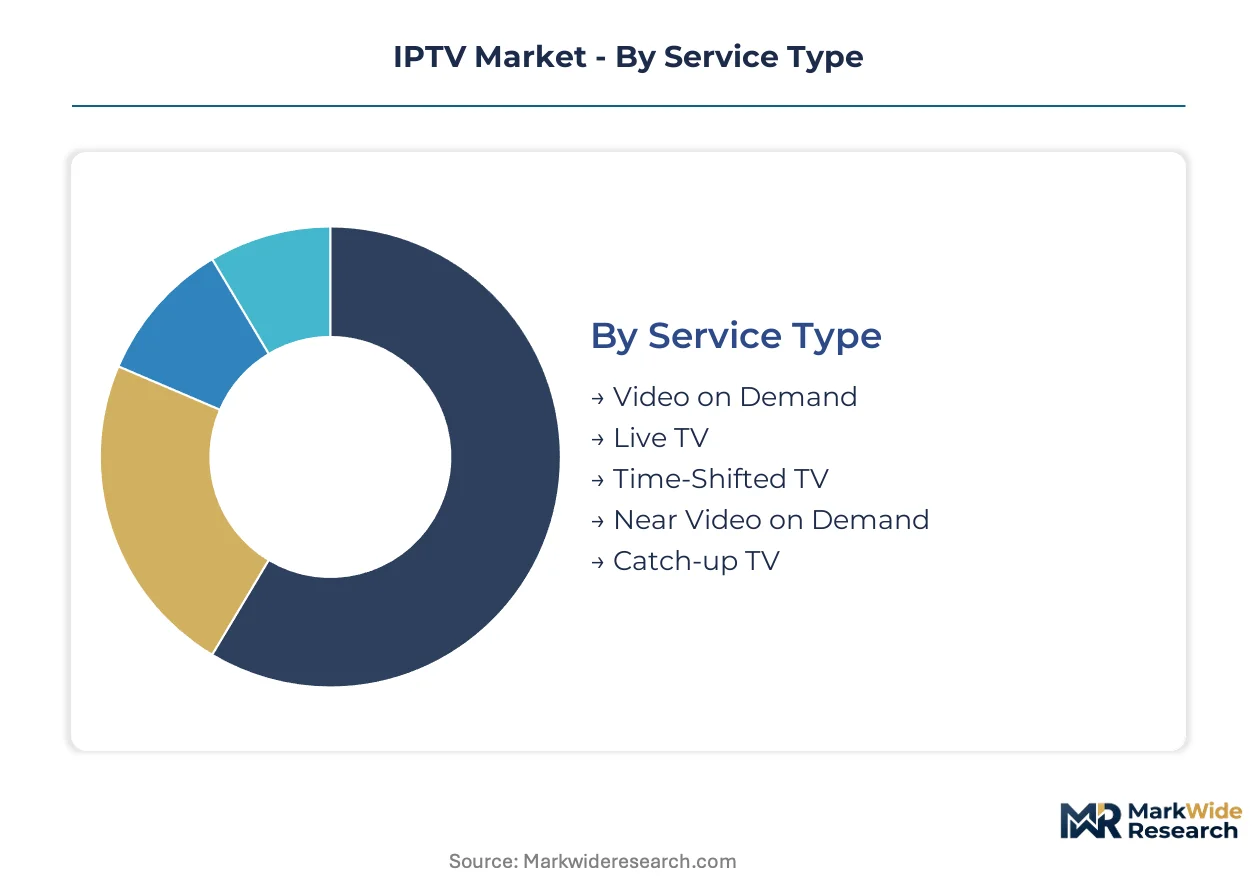
IPTV market segmentation reveals distinct capital intensity cycles across service delivery modes and infrastructure technologies. Understanding these temporal patterns helps operators sequence investments between mature revenue pools and emerging growth vectors.
Service Type:
Live TV and Video on Demand command the longest subscriber retention cycles, while Time-Shifted TV and Catch-up TV turn over features fastest as cloud DVR capabilities iterate quarterly.
- Video on Demand:Unicast streaming architecture delivering library content on request. Demand concentrates in India's tier-1 cities where TRAI tariff orders have compressed linear TV pricing, pushing subscribers toward à la carte libraries.
- Live TV:Real-time multicast or unicast transmission of scheduled programming. Sports rights concentration in Western Europe and North America drives premium tiering, with low-latency requirements forcing edge compute investments for betting synchronization.
- Time-Shifted TV:Cloud-based recording with user-controlled playback timing. Regulatory storage mandates in South Korea and Japan accelerate hardware replacement cycles.
- Near Video on Demand:Scheduled start times with pause functionality, bridging linear and on-demand experiences. Niche deployment in hospitality verticals with synchronized content windows.
- Catch-up TV:Limited-lookback replay of recently aired programming. Fastest feature turnover as broadcasters negotiate window exclusivity terms.
Live TV dominates installed base. Catch-up TV is where expansion concentrates.
Technology:
Cost tiers separate capital-light overlay deployments from fiber-deep infrastructure builds requiring decade-long amortization schedules.
- Fiber Optic:End-to-end optical transport enabling guaranteed quality-of-service for 4K and 8K streams. Deployment concentrates in India's urban corridors under PLI scheme incentives for domestic termination equipment.
- Internet Protocol Multicast:Efficient one-to-many packet distribution reducing backbone congestion. European operators leverage this for stadium direct-to-mobile convergence with 3GPP Release 17.
- Digital Subscriber Line:Copper-pair last-mile delivery with vectoring enhancements. Rural Germany and Australia retain substantial installed base despite bandwidth constraints.
- Satellite:Geostationary backhaul for uncovered territories. Brazil and Indonesia depend on this for rural reach despite high per-gigabyte transport economics.
- Cable:DOCSIS 3.1/4.0 hybrid fiber-coax architecture. North American operators upgrade to compete with fiber overbuilders.
- Asynchronous Transfer Mode:Legacy cell-based transport, now decommissioned except in isolated enterprise networks.
Fiber Optic captures new build capex. Cable defends the largest legacy subscriber base.
Application:
Volume concentration varies dramatically: Residential Entertainment scales through mass-market pricing, while Government Broadcasting runs on elongated procurement cycles with multi-year RFP horizons.
- Residential Entertainment:Mass-market subscription services delivered to households. India's broadband infrastructure expansion and aggressive pricing by CatchON TV accelerate subscriber acquisition in tier-2 cities.
- Hospitality:In-room entertainment systems for hotels and resorts. Branded property requirements in Dubai and Singapore drive integration with property management systems.
- Education & Training:Institutional video delivery for remote learning and corporate L&D. Korean regulatory mandates for cloud storage duration shape platform selection.
- Corporate Communication:Internal broadcast networks for enterprise messaging. Financial services in London and Frankfurt prioritize low-latency town hall delivery.
- Government Broadcasting:Public service distribution and emergency alert systems. EU AI Act transparency requirements extend to state-funded recommendation engines.
Residential Entertainment dominates subscriber volume. Hospitality offers the steepest expansion trajectory as travel recovery accelerates property technology refresh.
End User:
Customer type determines pricing power: Enterprises negotiate multi-year quality-of-service contracts, while Home Users churn seasonally around content rights windows.
- Home Users:Individual households consuming subscription or ad-supported services. Younger demographics in urban India bypass operator set-top boxes for smart TV native applications.
- Hotels & Resorts:Commercial hospitality properties requiring centralized content management. Dubai luxury properties demand 4K integration with in-room control systems.
- Educational Institutions:Universities and K-12 systems deploying lecture capture and remote learning. Japanese universities drive cloud DVR compliance investments.
- Enterprises:Corporate entities using video for internal communications and training. German industrial conglomerates specify frame-accurate ad replacement for global town halls.
- Public Administration:Government agencies delivering public information and emergency services. FCC net neutrality uncertainty complicates traffic prioritization contracting.
Home Users anchor global subscriber count. Enterprises concentrate pricing power through multi-year service level agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in IPTV infrastructure equipment and content licensing show India importing fiber termination units under PLI scheme incentives while Western European operators export proprietary CDN software to emerging markets. Service revenue patterns reverse this flow, with North American and European platforms licensing content into Asian markets.
United States
FCC net neutrality uncertainty shapes quality-of-service contracting for enterprise video customers, while sports betting synchronization demands sub-two-second latency engineering. California and New York media clusters host server-side ad insertion technology deployments that swap national spots for household-level targeted creative.
Germany
Vectoring-enhanced DSL infrastructure retains substantial rural installed base despite fiber migration pressure. The EU AI Act mandates algorithmic transparency disclosures for recommendation engines, with French and Italian regulators conducting first compliance audits. Bavarian industrial conglomerates specify frame-accurate ad replacement for global town hall broadcasts.
India
TRAI tariff orders compress linear TV pricing and push subscribers toward à la carte libraries in tier-1 cities. The PLI scheme for telecom equipment reduces set-top box costs for regional providers expanding into tier-2 markets. Maharashtra and Karnataka broadband corridors anchor fiber-to-the-home deployment acceleration.
Brazil
Geostationary satellite backhaul dependency ties rural coverage to high per-gigabyte transport economics. ANVISA and national telecom regulators shape content delivery obligations without the granular intervention seen in Asian markets. São Paulo media clusters concentrate sports rights aggregation and premium tiering strategies.
South Korea
Regulatory cloud DVR storage mandates accelerate hardware replacement cycles for legacy recording systems. Japanese universities and Korean educational institutions drive compliance investments in institutional video delivery platforms. Seoul metropolitan infrastructure supports edge compute deployments for low-latency live streaming engineering.
IPTV Market Key Industry Players
On the supply side, the industry is fragmented across subscription-based platform operators, CDN infrastructure lessors, and verticalized sports specialists. Tier-1 incumbents compete with agile challengers through differentiated bundling strategies rather than scale economies alone. Three archetypes dominate: sports-centric vertical integrators, diaspora-focused international curators, and geographic pricing aggressors in emerging broadband markets. Consolidation pressure manifests through content licensing concentration and infrastructure partnership formations rather than direct M&A activity.
Within the sports-centric tier, Fubo TV exemplifies vertical integration into live rights ownership as a retention mechanism. Apollo Group TV anchors the diaspora bundling archetype through curated international channel packages. CatchON TV occupies the emerging-market pricing position, leveraging aggressive geographic pricing to capture subscriber growth in tier-2 broadband expansion zones. These three patterns illustrate how competitive positioning fragments across retention, curation, and acquisition vectors rather than converging on uniform scale plays.
| Leading Market Players |
|---|
| JBNOTT |
| CatchON TV |
| ZYMINEX |
| Fubo TV |
| Xtreme HD IPTV |
| IPVARIO |
| Lumo IPTV |
| Apollo Group TV |
| TELEVIXY |
| Others |
Cost & Logistics Intelligence
Overcapacity in fiber termination equipment manufacturing across India and Southeast Asia compresses supplier margins while enabling aggressive subscriber acquisition pricing in emerging broadband markets. This utilization dynamic forces operators to choose between premium quality-of-service tiering and volume-driven economy positioning.
Pricing Analysis
Residential entertainment subscribers anchor a subscription-tiered pricing structure across premium, standard, and economy levels differentiated by streaming quality grade and bundled channel count. Price differentiation stems from 4K HDR certification tiers and geographic delivery cost variations across fiber-deep versus satellite-backhaul territories. Pricing pressure stems from content licensing concentration in Western Europe as sports rights aggregators extract disproportionate revenue shares. Home users in India's tier-2 cities exhibit highest price sensitivity, while enterprise customers in Germany and the United States negotiate multi-year quality-of-service contracts with lowest sensitivity.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Jabil, and Flex holding capacity for set-top box and fiber termination unit assembly across China, Vietnam, and Mexico. Raw material dependencies center on high-purity optical fiber from Corning and Sumitomo, semiconductor components from Taiwan and South Korea, and rare-earth magnet materials for satellite receiver assemblies. Supply chain risk hinges on tariff exposure affecting cross-border component flows between ASEAN manufacturing hubs and Indian assembly plants. Distribution runs through operator-direct procurement for tier-1 incumbents and regional distributor networks for emerging market challengers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of edge compute engineering talent capable of sub-two-second latency optimization constrains competitive differentiation in live sports streaming. This capability gap separates operators who can monetize betting synchronization from those trapped in commodity unicast delivery.
For Market Incumbents: Insulate subscriber retention through backward integration into exclusive sports rights ownership rather than licensing dependency. Prioritize certification investment in EU AI Act algorithmic transparency documentation to preempt regulatory audit exposure. Channel control through proprietary set-top box ecosystems defends against smart TV native application disintermediation threatening tier-1 urban markets. For New Entrants and Emerging Players: Establish a beachhead in diaspora channel bundling for South Asian and Middle Eastern expatriate communities in North American urban clusters. Target tier-2 Indian cities where PLI scheme incentives reduce infrastructure capital requirements and TRAI tariff orders compress incumbent pricing power. Go-to-market through broadband-only partnerships bypassing legacy set-top box distribution economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sports-centric vertical integrators with captive live rights and betting synchronization capabilities. Long-term viability favors operators with fiber-deep infrastructure in markets where 5G broadcast multicast convergence enables stadium direct-to-mobile expansion. Acquisition target archetype: mid-scale platforms with curated international channel bundles and established diaspora subscriber bases. Signal to watch: regulatory cloud DVR storage mandate adoption across Asian markets forcing legacy hardware replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Compute Infrastructure Deployment | Sub-two-second latency enables sports betting synchronization revenue streams in regulated markets. |
| EU AI Act Compliance Investment | Algorithmic transparency documentation preempts French and Italian regulatory audit penalties tied to turnover. |
| 5G Broadcast Multicast Integration | 3GPP Release 17 convergence creates stadium direct-to-mobile streaming without cellular congestion. |
| Diaspora Channel Bundle Curation | South Asian and Middle Eastern packages command premium pricing in North American urban clusters. |
| Cloud DVR Hardware Replacement | South Korean and Japanese regulatory storage mandates accelerate forced upgrade cycles for legacy systems. |
Research Approach
The analysis maps fiber infrastructure deployment, CDN software licensing, content rights aggregation, and subscriber acquisition economics, each validated through CTOs at tier-1 operators, content licensing directors at sports rights aggregators, regulatory affairs leads at platform providers, and procurement officers at set-top box manufacturers. Primary interview insights triangulate against FCC net neutrality filings, EU AI Act regulatory texts, TRAI tariff orders, SEC 10-K disclosures from listed operators, and hyperscaler capex reports. Bottom-up subscriber and infrastructure counts reconcile with top-down market value estimates across service type, technology, and application segments.
Assumptions held fixed include current regulatory frameworks for net neutrality and content moderation, prevailing fiber-to-the-home deployment rates in India, and satellite backhaul cost structures in Brazil and Indonesia. Variables stress-tested encompass 5G broadcast multicast adoption velocity, sports rights inflation trajectories, and cloud DVR regulatory mandate expansion. Segmentation modeling spans service delivery mode, infrastructure technology, application vertical, and end-user type. CAGRs derive from installed base growth rates applied to average revenue per subscriber trajectories, with inputs including broadband penetration curves, content licensing cost escalations, and edge compute deployment timelines.
Stress conditions across fiber deployment cost inflation, sports rights concentration, and regulatory storage mandate adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions without claiming predictive certainty for exogenous shocks. Quarterly review of 5G multicast standard adoption, EU AI Act enforcement patterns, and Indian PLI scheme utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Interactive Kiosk Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Epedigree Software Market
Digital Solutions
Container Management Software Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
India ICT Market
Digital Solutions
Internet of Things (IoT) Engineering Services Market
Digital Solutions
Poland ICT Market
Digital Solutions
Global Connected Enterprise Market
Digital Solutions
Legal Technology Market
Digital Solutions
Enterprise Mobility in Manufacturing Market
Digital Solutions
Data Monetization Market
Digital Solutions
Cloud Electronic Design Automation Market