
 Quality Process Management Application Market | 2026-2036
Quality Process Management Application Market Size, Share, and Industry Trends Forecast 2026-2036
Quality Process Management Application Market Analytics
Cloud-native architecture is reshaping how quality process management applications are deployed and consumed across regulated industries. MasterControl Inc. leverages deep validation protocols to anchor its position in life sciences compliance. Siemens AG extends its digital thread strategy by integrating quality modules with manufacturing execution systems. Autodesk Inc. competes through design-to-manufacture connectivity that embeds quality checkpoints earlier in product development.
Quality process management applications constitute software systems that enforce standardized workflows, capture non-conformance data, and maintain audit trails with timestamped electronic signatures for regulatory defensibility. Their primary commercial purpose is to reduce cost-of-quality while ensuring product safety and regulatory adherence across complex supply chains. Cloud-based deployment now leads growth as enterprises prioritize scalable infrastructure over capital-intensive on-premise installations, while quality compliance applications command the deepest margin pools due to specialized validation requirements and recurring audit support revenue. SaaS delivery models are displacing perpetual licenses fastest among mid-market manufacturers seeking faster implementation without dedicated IT overhead.
FDA 21 CFR Part 11, ISO 9001:2015, and EU MDR collectively shape product requirements by mandating electronic records integrity, risk-based thinking, and post-market surveillance traceability. These frameworks compel vendors to embed validation documentation, audit trail immutability, and risk assessment workflows as core platform capabilities rather than optional add-ons. Stakeholders must monitor evolving harmonization between FDA digital health guidance and EU AI Act conformity requirements for automated quality decision systems.
Market Dynamics
Cloud-native architecture is collapsing the traditional on-premise deployment model as pharmaceutical and medical device manufacturers face escalating FDA enforcement of 21 CFR Part 11 electronic records integrity.
Growth Catalysts
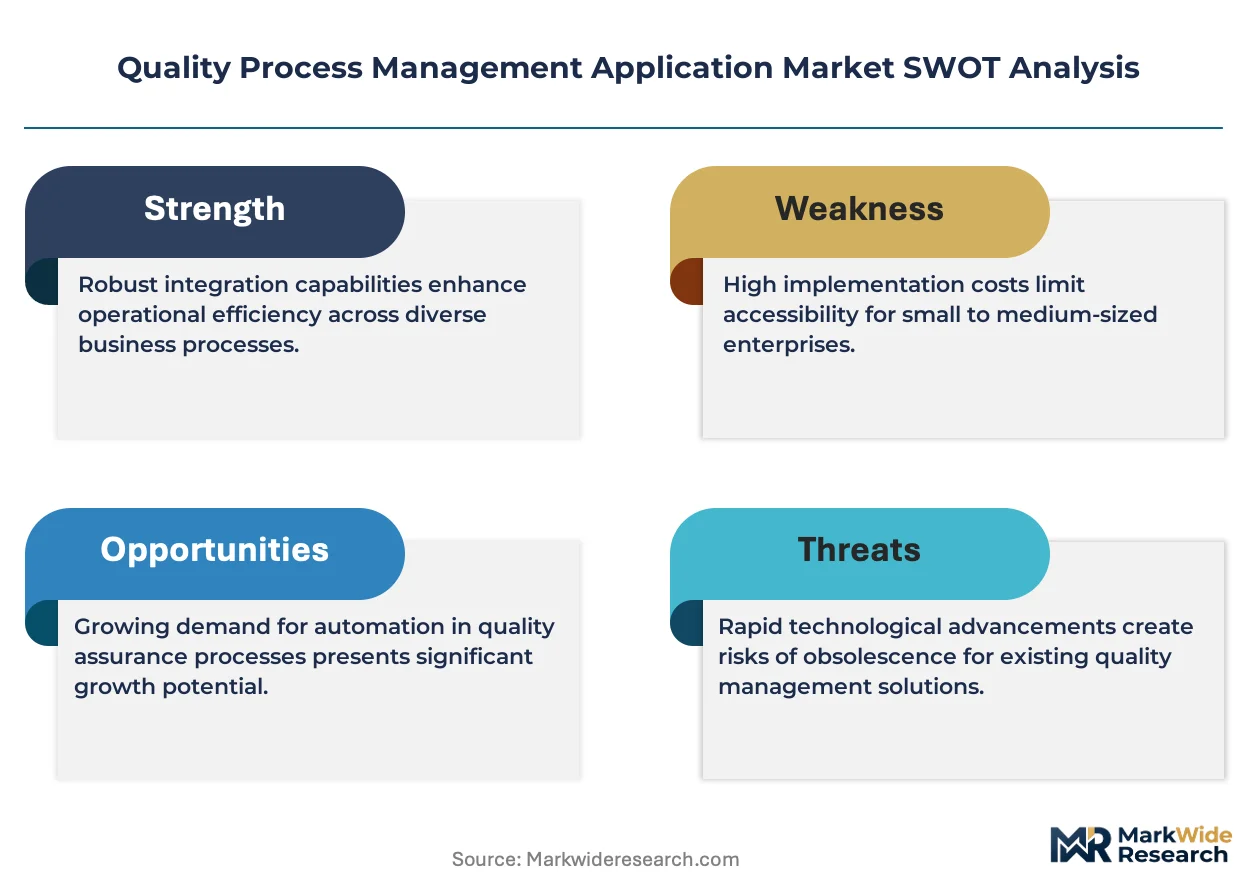
- FDA 21 CFR Part 11:Enforcement of electronic records and signature requirements compels life sciences enterprises to replace paper-based quality systems with validated software platforms.
- ISO 9001:2015 risk-based thinking:Manufacturing organizations across automotive and aerospace sectors embed quality process management applications to operationalize documented risk assessment workflows.
- Cloud infrastructure maturation:Scalable SaaS delivery eliminates capital-intensive server procurement, accelerating adoption among mid-market manufacturers without dedicated IT departments.
Market Restraints
- Specialized validation costs:Life sciences deployments require IQ/OQ/PQ documentation packages that extend implementation timelines and professional services expenditure.
- Legacy system entrenchment:Large industrial conglomerates maintain decades-old custom-built quality databases with sunk-cost inertia blocking replacement decisions.
- EU MDR transition friction:Medical device manufacturers divert software investment toward clinical evidence generation and notified body conformity assessments.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO alignment with international ICH guidelines creates demand for electronic batch records among domestic API producers and formulation facilities.
- EU AI Act automated decision systems:Conformity requirements for quality algorithms used in automated inspection and deviation classification open new compliance service revenue streams.
- Connected quality-digital thread convergence:Integration between quality process management applications and manufacturing execution systems enables real-time non-conformance detection.
Industry Challenges
- CSV talent scarcity:Computer system validation specialists with simultaneous GxP and cloud architecture expertise command premium compensation and extend hiring cycles.
- Multi-site harmonization complexity:Global manufacturers struggle to standardize quality workflows across facilities with divergent legacy infrastructures and regional regulatory interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Quality Process Management Application Market |
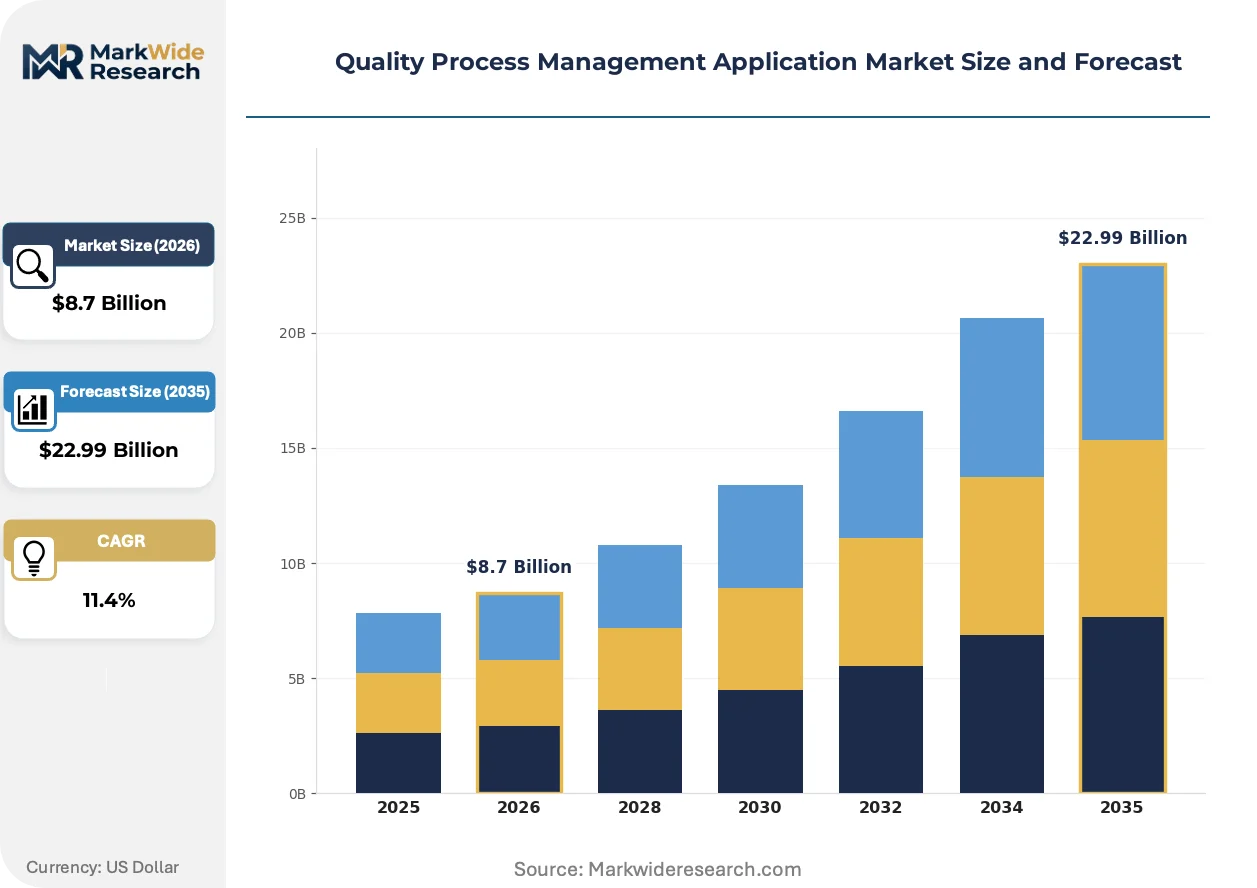
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Platform, Tool, Service End User: Manufacturers, Service Providers, Enterprises, Consultants Deployment: On-Premise, Cloud-Based, Hybrid, SaaS Application: Quality Compliance, Process Improvement, Audit Management, Risk Assessment |
| Companies Covered | MasterControl Inc., Autodesk Inc., Oracle Corporation, Siemens AG, Dassault Systemes SE, ETQ, Arena Solutions Inc., PTC, Intelex Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Quality Process Management Application Market Evolving Landscape
Artificial intelligence and machine learning capabilities are embedding into quality process management platforms, transforming deviation investigation from reactive documentation into predictive intervention systems.
Low-code workflow configurators are collapsing the traditional custom development cycle for quality process management applications. Pharmaceutical quality units now deploy electronic batch record templates without vendor professional services engagement. This capability compression is shortening implementation timelines from twelve months to under ninety days for standardized use cases.
EU MDR post-market surveillance requirements are mandating systematic quality data collection across device lifecycles. Manufacturers must establish automated vigilance reporting pipelines connecting complaint handling to regulatory submission systems. Class III implantable device producers in Germany and Ireland face the steepest compliance burden and are prioritizing integrated quality platforms.
Subscription-based commercial models are displacing perpetual license arrangements across the buyer base. Mid-market medical device manufacturers in Minnesota and Massachusetts now demand consumption-scaled pricing tied to active user counts rather than enterprise-wide site licenses. This preference shift is compressing vendor revenue recognition cycles while expanding addressable market penetration.
Quality Process Management Application Market Segmentation
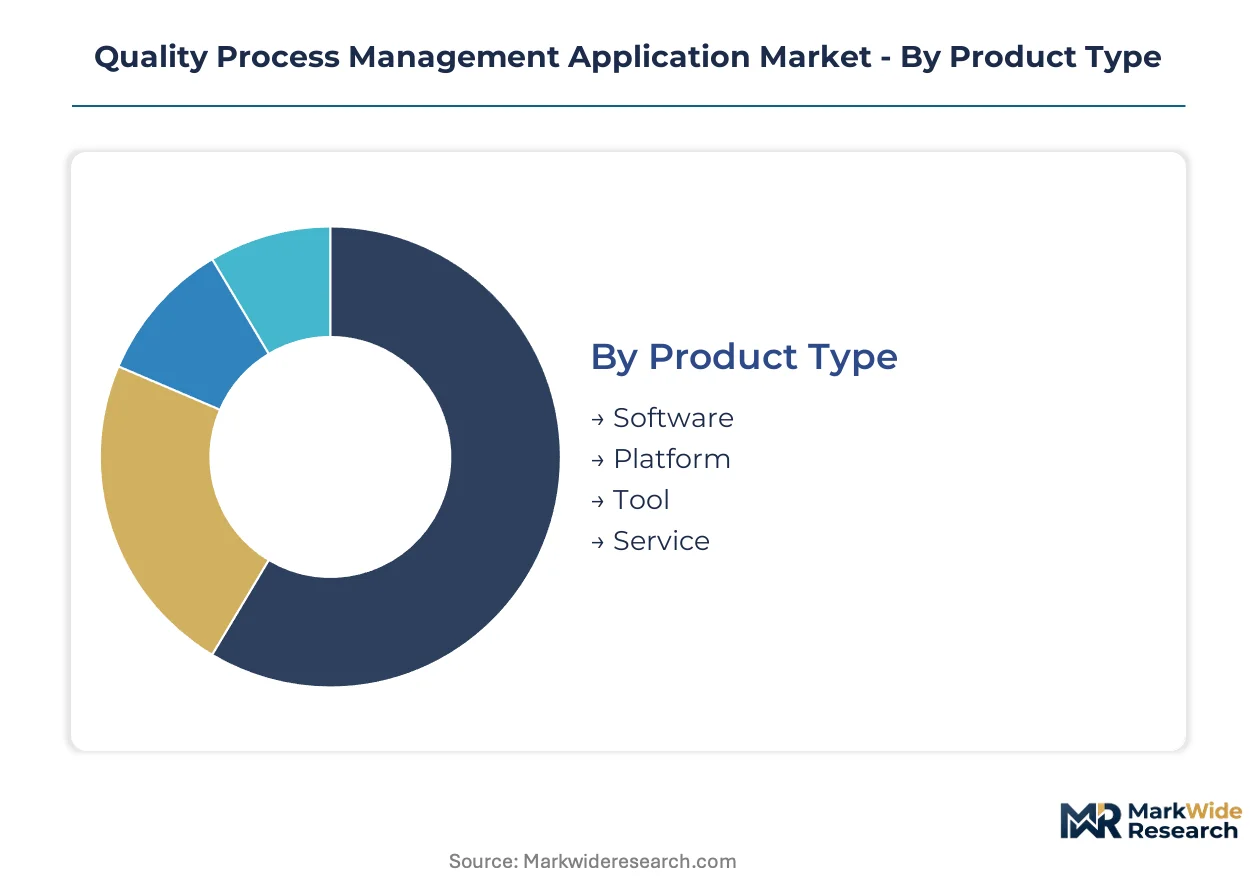
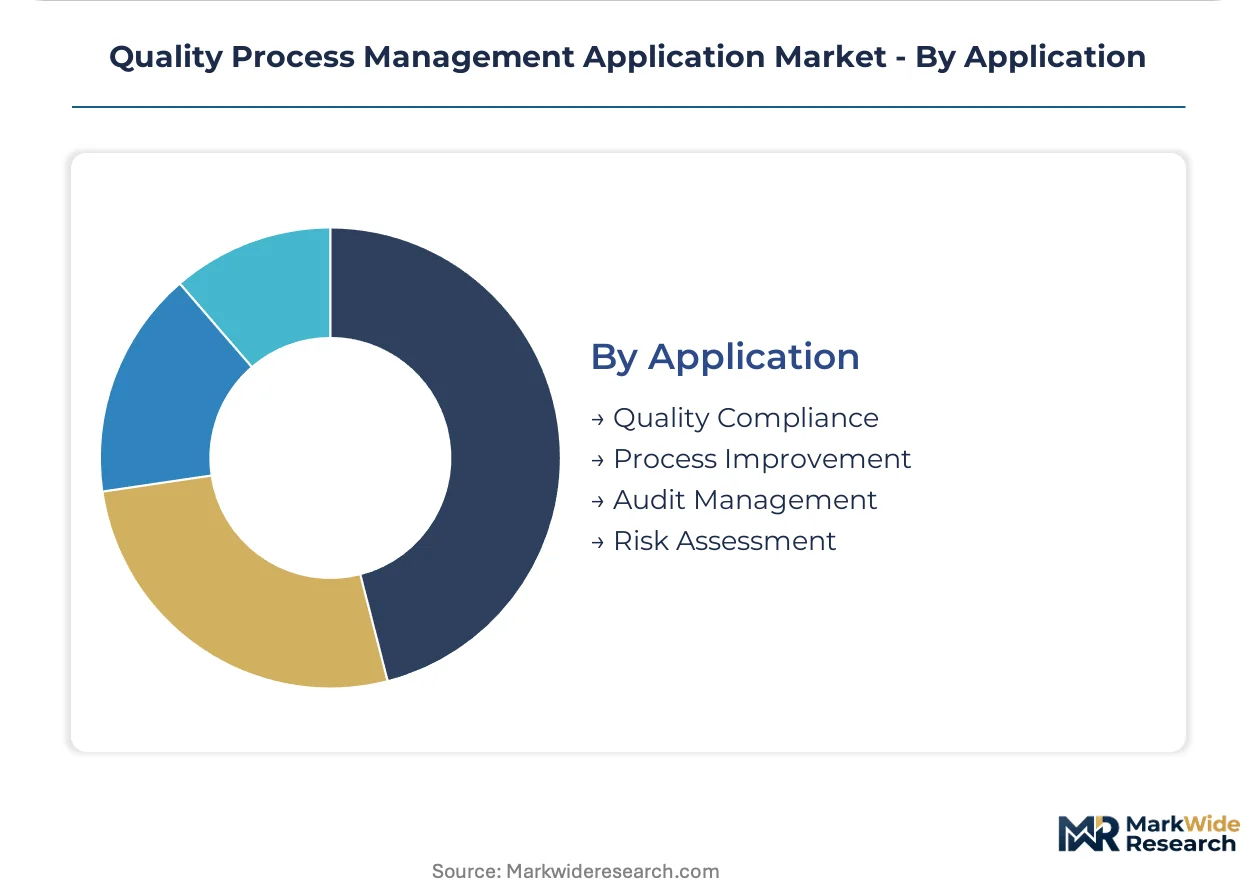
Quality process management applications serve heterogeneous operational contexts across regulated industries. Deployment architecture, commercial model, and functional depth create distinct purchasing segments with divergent margin profiles and implementation complexity.
Product Type:
Commercial form factor determines integration depth and professional services attachment rates across buyer organizations.
- Software:Standalone applications enforce document control, deviation tracking, and CAPA workflows through configurable modules. Pharmaceutical manufacturers in the United States deploy these systems to satisfy FDA 21 CFR Part 11 electronic records requirements without extensive customization.
- Platform:Integrated technology stacks connect quality data with manufacturing execution and enterprise resource planning systems through API architectures. Medical device producers leverage these environments to establish digital threads spanning design history files through post-market surveillance.
- Tool:Point solutions address discrete quality functions such as statistical process control or supplier scorecarding. Mid-market manufacturers adopt these for targeted problem-solving without enterprise-wide replacement cycles.
- Service:Validation documentation, audit preparation, and regulatory consulting bundled with technology licenses. Life sciences enterprises procure these packages to address computer system validation talent scarcity and accelerate FDA inspection readiness.
Software commands the established base. The steepest expansion runs through Platform.
End User:
Organizational scale and regulatory exposure intensity shape purchasing authority and solution sophistication requirements.
- Manufacturers:Production organizations across pharmaceutical, medical device, automotive, and aerospace verticals implement quality process management applications to operationalize ISO 9001 risk-based thinking and reduce cost-of-quality metrics.
- Service Providers:Contract manufacturing organizations and quality consulting firms deploy multi-tenant configurations to manage client-specific quality data segregation and audit trail isolation.
- Enterprises:Large conglomerates with diversified manufacturing footprints require harmonized quality workflows across facilities with divergent legacy infrastructures and regional regulatory interpretations.
- Consultants:Advisory practices leverage quality process management platforms to deliver remediation services following FDA warning letters or ISO certification gaps, creating recurring technology-enabled revenue streams.
Manufacturers anchor current revenue concentration. Service Providers are climbing the fastest as outsourcing accelerates.
Deployment:
Infrastructure location and commercial terms create divergent total cost of ownership profiles across buyer maturity levels.
- On-Premise:Server installations within buyer data centers maintain complete data sovereignty and direct control over validation documentation. Defense contractors and classified manufacturing facilities mandate these deployments for security compliance.
- Cloud-Based:Vendor-managed infrastructure eliminates capital expenditure and enables elastic scaling during regulatory submission peaks. Mid-market medical device manufacturers in Massachusetts and Minnesota prioritize these models to bypass dedicated IT overhead.
- Hybrid:Mixed architectures retain sensitive quality records on-premise while leveraging cloud analytics for benchmarking and predictive deviation detection. Aerospace suppliers use these configurations to protect proprietary process data.
- SaaS:Subscription delivery with consumption-scaled pricing tied to active user counts rather than enterprise site licenses. This model is displacing perpetual licenses fastest among growth-stage manufacturers seeking ninety-day implementation timelines.
On-Premise retains the legacy installed base. SaaS is gaining share fastest among new deployments.
Application:
Functional use case determines integration complexity and regulatory defensibility requirements.
- Quality Compliance:Electronic batch records, audit trails, and electronic signatures ensuring FDA 21 CFR Part 11 and EU MDR conformity. These applications command premium pricing due to specialized validation requirements and recurring audit support revenue.
- Process Improvement:Statistical process control, root cause analysis, and continuous improvement workflow automation. Automotive Tier 1 suppliers embed these capabilities to reduce defect rates and warranty claims.
- Audit Management:Scheduled inspection planning, finding tracking, and corrective action verification across internal and external audit programs. Medical device manufacturers facing notified body surveillance audits prioritize these modules.
- Risk Assessment:FMEA documentation, risk control verification, and post-market surveillance data integration. EU MDR transition is compelling systematic quality data collection across device lifecycles for Class III implantable producers.
Quality Compliance dominates current spending. Risk Assessment is expanding most quickly under EU MDR pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German quality process management application vendors export validated compliance platforms to pharmaceutical manufacturers across the United States and Switzerland, while Indian software providers serve contract research organizations in North America and Europe seeking cost-efficient electronic batch record systems.
United States
FDA enforcement of 21 CFR Part 11 compels pharmaceutical and medical device manufacturers to replace paper-based quality systems with validated electronic records platforms. The agency's inspectional focus on data integrity violations drives enterprise investment in audit trail immutability and timestamped signature capabilities. Minnesota and Massachusetts host dense clusters of mid-market medical device manufacturers prioritizing SaaS deployment models to bypass dedicated IT overhead.
Germany
EU MDR post-market surveillance requirements pressure Class III implantable device producers to establish automated vigilance reporting pipelines connecting complaint handling to regulatory submission systems. The country's notified body infrastructure and IVD regulation alignment create specialized demand for risk assessment workflow automation. Bavaria and Baden-Württemberg concentrate medical technology manufacturing where digital thread integration between quality modules and manufacturing execution systems accelerates.
India
CDSCO alignment with international ICH guidelines generates demand for electronic batch records among domestic API producers and formulation facilities serving export markets. The regulator's phased implementation of good manufacturing practice harmonization drives replacement of legacy paper systems in pharmaceutical manufacturing zones. Maharashtra and Gujarat host formulation facilities and contract manufacturing organizations adopting cloud-native quality platforms to satisfy FDA and EMA inspection readiness for export consignments.
Switzerland
Swissmedic's stringent pharmacovigilance requirements and medical device conformity assessment procedures compel manufacturers to maintain systematic quality data collection across product lifecycles. The country's precision manufacturing base and pharmaceutical research concentration demand specialized validation documentation and audit support services. Basel and Zurich anchor pharmaceutical headquarters and contract manufacturing operations integrating quality process management applications with global enterprise resource planning systems.
Japan
PMDA's emphasis on quality risk management and post-approval change management drives pharmaceutical manufacturers to embed documented risk assessment workflows into operational technology. The regulator's data reliability guidance for computerized systems aligns with international ICH Q9 and Q10 frameworks. Tokyo and Osaka metropolitan areas concentrate pharmaceutical headquarters and medical device manufacturing operations where hybrid deployment architectures retain sensitive quality records on-premise while leveraging cloud analytics.
Quality Process Management Application Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic tiers: enterprise-grade platform providers with deep validation protocols, design-to-manufacture integrators embedding quality checkpoints earlier in product development, and specialized compliance vendors serving life sciences verticals. Dominant competitive moves include strategic partnerships connecting quality modules with manufacturing execution systems and portfolio diversification into AI-enabled deviation classification and automated inspection capabilities.
Within the enterprise platform tier, MasterControl Inc. and Siemens AG exemplify divergent strategic positioning: the former anchors life sciences compliance through specialized validation documentation and recurring audit support revenue, while the latter extends digital thread architecture by integrating quality modules with broader manufacturing execution environments. Autodesk Inc. occupies a distinct position at the design-manufacture boundary, embedding quality checkpoints into product development workflows rather than treating quality as a downstream operational function.
| Leading Market Players |
|---|
| MasterControl Inc. |
| Autodesk Inc. |
| Oracle Corporation |
| Siemens AG |
| Dassault Systemes SE |
| ETQ |
| Arena Solutions Inc. |
| PTC |
| Intelex Technologies |
| Others |
Value Network & Pricing Analysis
Trans-Pacific fiber-optic bandwidth costs determine how quality process management application vendors distribute validation documentation packages and SaaS infrastructure across concentrated development hubs in the United States, Germany, and India, with latency-sensitive compliance modules commanding premium pricing against standardized workflow tools.
Pricing Analysis
Legacy on-premise perpetual licenses, current-generation SaaS subscriptions, and emerging AI-augmented quality platforms occupy distinct pricing tiers separated by validation depth and integration complexity. Three-tier pricing structure across premium, standard, and economy levels stratifies by FDA 21 CFR Part 11 certification grade and ISO 9001 audit support bundling. Cost compression in mid-market SaaS tiers is intensifying because low-code configurators collapse implementation timelines from twelve months to ninety days. Contract manufacturing organizations exhibit the highest price sensitivity due to thin margins, while Class III medical device manufacturers accept premium pricing for specialized EU MDR vigilance reporting capabilities.
Supply Chain Analysis
Extended payment terms from ninety to one hundred twenty days now anchor supplier relationships as cloud infrastructure providers compete for quality application hosting contracts. Software development concentrates in the United States, Germany, and India, with validation documentation services drawing from Switzerland and Ireland. Raw material dependencies include cloud compute capacity, cybersecurity certification labor, and API integration middleware. Single-source vulnerability runs through hyperscaler concentration for SaaS delivery. Distribution runs through direct enterprise sales teams supplemented by quality consulting firm channel partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quality process management applications constitute a defensive-moat market where regulatory entrenchment creates durable competitive positioning. FDA 21 CFR Part 11 validation protocols and ISO 9001 certification requirements erect switching costs that protect incumbent revenue streams.
For Market Incumbents: Entrench market position by deepening vertical integration into computer system validation talent pools and expanding audit support service capacity in FDA inspection-heavy corridors. MasterControl Inc. and Siemens AG demonstrate how specialized IQ/OQ/PQ documentation packages create annuity revenue that emerging cloud-native competitors cannot replicate without multi-year compliance track records. Threat from low-code disruptors demands accelerated AI-enabled deviation classification R&D investment. For New Entrants and Emerging Players: Build out white-space presence in Indian pharmaceutical manufacturing zones where CDSCO harmonization with ICH guidelines drives electronic batch record replacement cycles among domestic API producers. EU AI Act automated decision system conformity requirements represent the most penetrable segment for algorithm-native entrants. Go-to-market angle should target mid-market medical device manufacturers in Massachusetts and Minnesota with consumption-scaled SaaS pricing tied to active user counts rather than enterprise site licenses. For Investors and Strategic Acquirers: Carve-out targets emerge from industrial conglomerates divesting non-core quality software assets amid portfolio rationalization pressures. Long-term viability centers on recurring audit support revenue and validation documentation renewal cycles rather than perpetual license peaks. Acquisition archetype: specialized compliance vendors with deep FDA 483 response expertise and established notified body relationships. Signal to watch is CDSCO inspection intensity escalation in Maharashtra and Gujarat pharmaceutical manufacturing zones.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Quality module embedding within Siemens AG manufacturing execution systems accelerates real-time non-conformance detection. |
| AI-Enabled Deviation Classification | Machine learning algorithms transform reactive documentation into predictive intervention systems for pharmaceutical batch releases. |
| Regulatory Consulting Bundling | Computer system validation talent scarcity drives professional services attachment rates above standardized software margins. |
| Geographic Expansion | Indian API producers adopting cloud-native platforms to satisfy FDA and EMA inspection readiness for export consignments. |
| Low-Code Workflow Configurator Launch | Ninety-day implementation timelines displace twelve-month legacy deployment cycles among mid-market manufacturers. |
Research Methodology
Initial hypotheses were tested against primary input from quality assurance directors, regulatory affairs leads, computer system validation specialists, and pharmaceutical manufacturing executives and refined through secondary validation against FDA 483 observation databases, ISO certification registry filings, SEC 10-K software revenue disclosures, and cloud infrastructure capex reports. Bottom-up segmentation modeling triangulated against top-down market sizing from enterprise quality software spending surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with deployment architecture, commercial model, functional depth, and regional regulatory cluster serving as core segmentation dimensions. CAGRs were derived from installed base migration rates and new customer acquisition velocity calibrated against FDA enforcement action trends. Forecast inputs included EU MDR transition timelines and CDSCO good manufacturing practice harmonization phases.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler-backed quality platform entrants would shift outcomes through pricing disruption. Forecasts reflect assumptions regarding regulatory enforcement continuity and cloud infrastructure cost trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Workforce Productivity Systems Market
Digital Solutions
India Digital Twin Market
Digital Solutions
Europe Data Virtualization Market
Digital Solutions
Agent-Oriented Enterprise Architecture Market
Digital Solutions
Global Electronic Shift Operations Management Solutions (Esoms) Market
Digital Solutions
North America Everything As a Service (Xaas) Market
Digital Solutions
Australia Digital Twin Market
Digital Solutions
Global Industrial Design Market
Digital Solutions
Contactless Ticketing Solutions Market
Digital Solutions
Digital Fitness Apps Market
Digital Solutions
Data Analytics in the Smart Home Market
Digital Solutions
AQI App Market
Digital Solutions
Shipping Software Market
Digital Solutions
Master Data Management Market
Digital Solutions
Product Prototyping Market
Digital Solutions
Global Asset Tracking and Inventory Management Solutions Market