
 Manufacturing Predictive Analytics Market | 2026-2036
Manufacturing Predictive Analytics Market Size, Share, and Industry Trends Forecast 2026-2036
Manufacturing Predictive Analytics Market Intelligence
A shortage of data engineers with industrial domain expertise is unwinding deployment timelines for predictive analytics in factories. Siemens AG leverages its digital twin portfolio to anchor factory automation contracts in European automotive plants. Microsoft Corporation competes through Azure IoT integration with existing enterprise software stacks. IBM Corporation sustains relevance via Watson-powered asset performance management for pharmaceutical cleanroom operations.
Manufacturing predictive analytics encompasses software systems that apply statistical algorithms and machine learning to operational data from sensors, PLCs, and MES layers to forecast equipment failures, quality deviations, and energy anomalies. These systems typically process time-series vibration, thermal, and current-signature data at sampling rates between 1 kHz and 20 kHz to generate remaining-useful-life estimates for critical rotating machinery. Cloud-based deployment is capturing the fastest expansion as manufacturers seek elastic compute for seasonal production peaks without capital-intensive server farms. Software solutions dominate revenue pools due to recurring subscription models and continuous algorithm retraining services.
The US FDA enforces data integrity requirements for pharmaceutical manufacturers deploying predictive systems in GMP environments, compelling validation documentation that shapes vendor selection criteria. Germany's KBA coordinates with industry groups to embed predictive quality analytics into automotive supplier certification pathways under evolving type-approval frameworks. China's MIIT mandates industrial data localization standards that restrict cross-border cloud processing for strategic manufacturing sectors. Stakeholders must weigh sovereign data requirements against the latency advantages of edge-native architectures as factory networks densify.
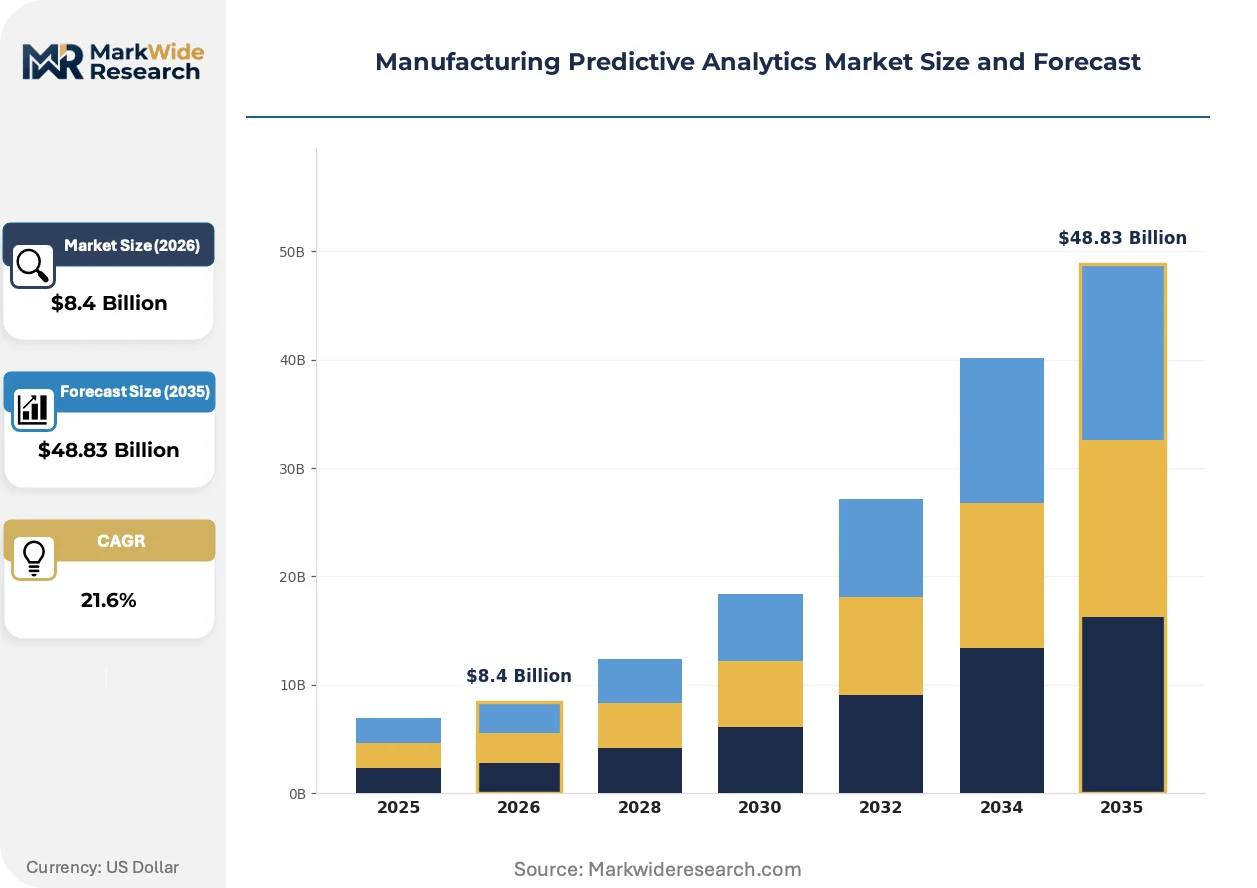
Market Dynamics
Cloud-native architectures are fragmenting the installed base of on-premise predictive analytics systems across automotive and pharmaceutical manufacturing floors, forcing vendors to rebuild deployment models around elastic consumption.
Growth Catalysts
- Automotive predictive maintenance mandates:Germany's KBA embeds predictive quality analytics into automotive supplier certification pathways, compelling Tier-1 component manufacturers to deploy sensor-based failure forecasting systems.
- FDA data integrity enforcement:The US FDA's 21 CFR Part 11 requirements for pharmaceutical GMP environments create vendor stickiness through validation documentation that locks manufacturers into compliant predictive platforms.
- Edge computing convergence:Time-series processing at 1-20 kHz sampling rates for vibration and thermal signatures now executes on GPU-accelerated edge nodes, reducing cloud egress costs for rotating machinery monitoring.
Market Restraints
- Data engineer scarcity:Industrial domain expertise in PLC, MES, and SCADA integration commands salary premiums that extend deployment timelines by 8-14 months for mid-sized manufacturers.
- Cross-border data localization:China's MIIT mandates industrial data residency for strategic manufacturing sectors, blocking cloud-native architectures that rely on distributed global infrastructure.
- Legacy MES integration friction:Proprietary protocols from 1990s-era manufacturing execution systems require custom middleware development that consumes 30-40% of implementation budgets.
Strategic Opportunities
- Pharmaceutical cleanroom expansion:Aseptic filling and lyophilization operations in Ireland and Singapore present greenfield deployments where predictive contamination monitoring replaces scheduled maintenance intervals.
- EU AI Act compliance services:Risk management system documentation and conformity assessments for high-risk industrial AI applications create recurring revenue streams adjacent to core analytics software.
- Digital twin convergence:Integration of physics-based simulation with machine learning anomaly detection enables virtual commissioning of predictive maintenance rules before physical deployment.
Industry Challenges
- Multi-skilled technician shortage:Maintenance teams must simultaneously interpret vibration spectra, SQL query time-series databases, and calibrate IoT sensors—a competency stack rarely found in single candidates.
- Validation timeline compression:Pharmaceutical manufacturers face 18-24 month GMP qualification cycles for predictive systems that must demonstrate statistical process control equivalence to existing manual inspection regimes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Manufacturing Predictive Analytics Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $48.83 Billion |
| CAGR (2026 – 2036) | 21.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Tools, Platforms, Solutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge End User: Aerospace, Automotive, Electronics, Pharmaceuticals Technology: Machine Learning, Data Mining, Statistical Analysis, Predictive Modeling |
| Companies Covered | IBM Corporation, SAP SE, Oracle Corporation, Microsoft Corporation, SAS Institute Inc., General Electric Company, Siemens AG, Cisco Systems Inc., TIBCO Software Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Manufacturing Predictive Analytics Market Strategic Shifts & Innovations
Federated learning architectures and sovereign cloud deployments are reshaping how operational technology data traverses factory networks, creating new competitive axes around data custody rather than algorithm performance alone.
Edge-native inference engines are fragmenting the centralized cloud analytics model that dominated early predictive maintenance deployments. Automotive powertrain manufacturers now process bearing fault signatures on NVIDIA Jetson modules mounted directly on gearbox housings, compressing anomaly detection latency from seconds to milliseconds while satisfying German automotive OEM cybersecurity requirements for air-gapped production lines.
The EU AI Act's risk classification framework for industrial AI systems is restructuring vendor liability and documentation burdens. High-risk predictive quality systems deployed in medical device manufacturing must now maintain post-market monitoring protocols and human oversight mechanisms, compelling software providers to rebuild architecture around explainable decision trees rather than black-box neural networks for critical defect classification tasks.
Outcome-based contracting is displacing traditional perpetual license sales for predictive analytics platforms. Mining equipment operators in Western Australia now negotiate agreements where vendors earn fees proportional to avoided downtime hours rather than sensor counts, transferring performance risk to solution providers and demanding real-time integration with OEM maintenance scheduling systems.
Manufacturing Predictive Analytics Market Segmentation
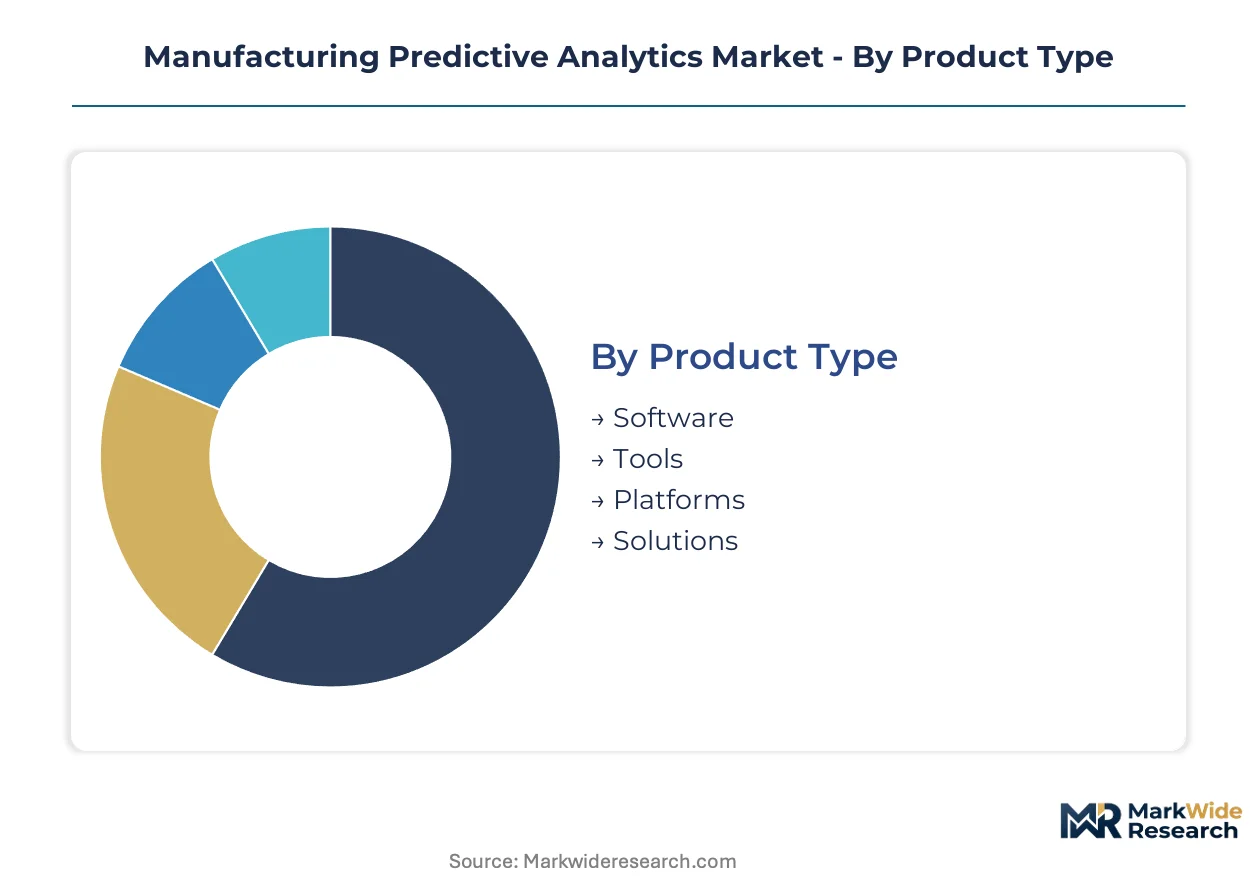
Segmentation in manufacturing predictive analytics reveals how deployment economics, regulatory exposure, and data sovereignty requirements reshape vendor strategies. Buyers select architectures based on latency tolerance, validation burdens, and cross-border data restrictions.
Product Type:
Software-as-a-service offerings face substitution pressure from open-source machine learning frameworks that industrial IT teams customize internally.
- Software:Subscription-based applications process vibration and thermal time-series data at 1-20 kHz sampling rates. Automotive manufacturers in Germany favor these for predictive quality analytics under KBA certification pathways.
- Tools:Modular diagnostic utilities integrate with existing MES layers through proprietary middleware. Pharmaceutical cleanroom operators in Ireland deploy these for contamination monitoring that replaces scheduled maintenance intervals.
- Platforms:Unified environments combine data ingestion, model training, and visualization dashboards.
- Solutions:Turnkey packages bundle hardware sensors with analytics software and implementation services.
Software retains volume leadership; Tools hold the steepest expansion curve.
Deployment:
Cost tier stratification separates capital-intensive on-premise installations from consumption-priced cloud alternatives.
- Cloud-Based:Elastic compute architectures scale processing capacity for seasonal production peaks without server farm investments. China's MIIT data localization mandates block these deployments for strategic manufacturing sectors.
- Edge:GPU-accelerated nodes mounted on gearbox housings compress anomaly detection latency to milliseconds. German automotive OEMs mandate these for air-gapped powertrain lines under cybersecurity requirements.
- On-Premise:Dedicated server installations persist in FDA-regulated pharmaceutical environments requiring 21 CFR Part 11 validation documentation.
- Hybrid:Split architectures process sensitive data locally while aggregating anonymized patterns to cloud training pipelines.
Cloud-Based captures the broadest installed base; Edge gains share fastest in automotive applications.
End User:
Application intensity varies by sector-specific equipment criticality and regulatory validation timelines.
- Automotive:Powertrain and Tier-1 component manufacturers deploy sensor-based failure forecasting to satisfy predictive quality mandates embedded in supplier certification pathways.
- Pharmaceuticals:Aseptic filling and lyophilization operations demand predictive contamination monitoring with 18-24 month GMP qualification cycles.
- Aerospace:Engine MRO providers forecast remaining useful life for rotating machinery across global maintenance networks.
- Electronics:Semiconductor fabs apply statistical process control to etching and deposition equipment for yield optimization.
Automotive dominates current procurement volumes; Pharmaceuticals climbs the fastest as cleanroom expansion accelerates.
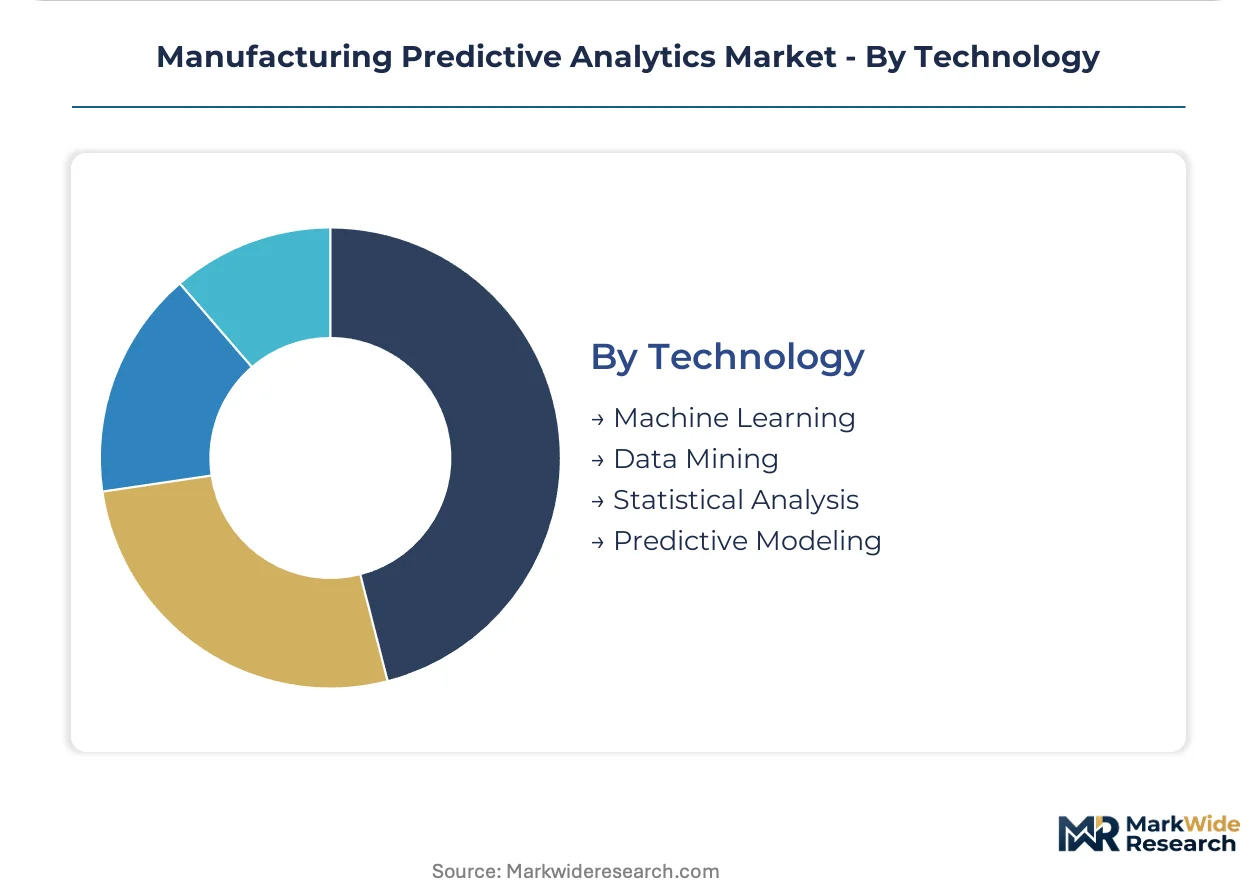
Technology:
Customer type preferences split between explainable methods for regulated environments and black-box approaches for non-critical monitoring.
- Machine Learning:Neural network architectures detect non-linear fault patterns in vibration spectra. EU AI Act risk classifications now compel explainable decision trees for medical device defect classification.
- Predictive Modeling:Physics-informed simulations generate remaining-useful-life estimates by combining operational data with material degradation models.
- Data Mining:Pattern recognition algorithms identify correlation clusters across historical maintenance records.
- Statistical Analysis:Control chart methods establish baseline variance thresholds for quality deviation alerts.
Machine Learning leads commercial adoption; Predictive Modeling expands most quickly through digital twin convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. United States pharmaceutical manufacturers prioritize FDA-validated on-premise systems, while German automotive suppliers embed edge-native analytics under KBA certification mandates. Chinese state-owned enterprises face MIIT data localization requirements that reshape cloud architecture decisions.
United States
FDA's 21 CFR Part 11 enforcement drives pharmaceutical manufacturers toward validated predictive platforms with extensive documentation requirements. The agency's data integrity guidelines create vendor stickiness through multi-year qualification cycles. Boston-Cambridge biotech clusters and New Jersey pharmaceutical corridors anchor the highest deployment density of GMP-compliant analytics systems.
Germany
KBA-mandated predictive quality analytics for Tier-1 automotive suppliers accelerate edge computing adoption in powertrain manufacturing. The EU AI Act's risk classification framework imposes documentation burdens on high-risk industrial AI applications. Stuttgart and Munich automotive clusters lead implementation of GPU-accelerated edge nodes for air-gapped production lines.
China
MIIT industrial data localization standards restrict cross-border cloud processing for strategic manufacturing sectors, compelling domestic cloud infrastructure investments. State-owned enterprises in aerospace and semiconductor fabrication deploy predictive systems under sovereign data requirements. Yangtze River Delta manufacturing hubs concentrate the highest volume of localized predictive analytics deployments.
Ireland
Aseptic filling and lyophilization operations in pharmaceutical cleanrooms present greenfield predictive contamination monitoring opportunities. EMA-aligned regulatory frameworks attract multinational pharmaceutical manufacturers expanding European manufacturing footprints. Dublin and Cork pharmaceutical corridors drive demand for systems replacing scheduled maintenance intervals with real-time anomaly detection.
Singapore
Advanced pharmaceutical manufacturing investments from multinational corporations create demand for predictive systems in sterile processing environments. The country's national pharmaceutical regulator enforces GMP standards aligned with FDA and EMA frameworks. Tuas Biomedical Park and one-north research clusters concentrate deployments of digital twin-integrated predictive maintenance platforms.
Manufacturing Predictive Analytics Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in manufacturing predictive analytics. Siemens AG and General Electric Company anchor the integrated tier with hardware-software portfolios spanning digital twins and industrial automation. Specialist vendors concentrate on narrow application domains such as vibration analysis or pharmaceutical validation documentation. Dominant competitive moves include strategic partnerships with cloud hyperscalers and vertical integration into edge hardware manufacturing.
Within the integrated tier, Siemens AG and Microsoft Corporation exemplify divergent architectural strategies. Siemens leverages its German industrial heritage and digital twin portfolio to anchor European automotive contracts. Microsoft competes through Azure IoT integration with existing enterprise software stacks, targeting manufacturers seeking elastic cloud consumption models. IBM Corporation occupies a position in regulated pharmaceutical environments through Watson-powered asset performance management systems.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| SAS Institute Inc. |
| General Electric Company |
| Siemens AG |
| Cisco Systems Inc. |
| TIBCO Software Inc. |
| Others |
Cost & Logistics Intelligence
Forty-five to ninety-day lead times for GPU-accelerated edge hardware anchor pricing power with semiconductor distributors serving German automotive OEMs, while cloud-native software subscriptions face compression from open-source alternatives. This inventory concentration shapes vendor margins across deployment architectures.
Pricing Analysis
Long-term SaaS contracts with annual retraining clauses dominate enterprise procurement, though pharmaceutical manufacturers negotiate project-based validation bundles for FDA-compliant deployments. Price differentiation hinges on GMP certification tier and edge hardware integration depth. Cost compression in mid-market cloud tiers intensifies as AWS and Azure reduce egress fees for industrial IoT workloads. Tier-1 automotive suppliers show lowest price sensitivity due to KBA mandate compliance requirements.
Supply Chain Analysis
GPU inventory cycles stretching 60-120 days concentrate supply risk with NVIDIA and AMD distributors in Taiwan and South Korea, while sensor fabrication rests on MEMS foundries in China and Japan. Raw material dependencies span silicon wafers, rare-earth magnets for vibration sensors, and specialty polymers for harsh-environment housings. Single-source vulnerability in automotive-grade GPU modules threatens deployment timelines for edge-native architectures. Distribution runs through systems integrators with PLC programming expertise.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Manufacturing predictive analytics sits in early-cycle expansion as pharmaceutical cleanroom operators replace scheduled maintenance with real-time anomaly detection, accelerating penetration beyond automotive's mandate-driven base.
For Market Incumbents: Secure validation documentation moats in FDA-regulated environments where 21 CFR Part 11 compliance creates switching costs. Anchor cloud partnerships with hyperscalers to defend against open-source framework substitution. Invest in edge hardware backward integration to capture GPU-accelerated node margins from automotive cybersecurity mandates. For New Entrants and Emerging Players: Mid-market pharmaceutical manufacturers in Ireland and Singapore present service-layer gaps where incumbents under-serve GMP qualification support. Target greenfield cleanroom deployments with bundled contamination monitoring and validation documentation. Pursue outcome-based contracting models that transfer performance risk and differentiate from perpetual license incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software tiers as containerization reduces infrastructure overhead. Five-to-ten year viability favors vendors with dual capability in edge hardware manufacturing and regulatory validation services. Watch for EU AI Act conformity assessment delays as an inflection signal for explainable AI architecture demand.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Hardware Backward Integration | Captures GPU module margins from German automotive OEM cybersecurity mandates. |
| Regulatory Validation Service Bundling | Locks pharmaceutical manufacturers into 18-24 month GMP qualification cycles. |
| Outcome-Based Contracting Transition | Transfers downtime risk to vendors in Western Australian mining equipment markets. |
| Federated Learning Architecture Deployment | Satisfies China's MIIT data localization while preserving model training scale. |
| Digital Twin Platform Integration | Enables virtual commissioning of predictive rules for Siemens automotive contracts. |
Research Approach
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base. Primary interviews combined with secondary validation from SEC filings, hyperscaler capex disclosures, automotive production databases, and FDA 483 observation logs. Bottom-up deployment counts triangulated against top-down software spending estimates across the analysis window.
Sensitivity analysis tested elasticity assumptions across deployment model, organization size, vertical application, and regional regulatory cluster. CAGRs derived from segmented adoption curves weighted by equipment criticality and validation timeline compression. Forecast inputs incorporated edge hardware cost decline trajectories and cloud egress pricing trends without year-specific anchoring.
Underlying assumptions cover sustained FDA enforcement intensity, EU AI Act implementation pace, and MIIT data localization scope, with deviation risk concentrated in pharmaceutical qualification timeline extensions and automotive semiconductor supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Analytics
IT Operation Analytics (ITOA) Software Market
Analytics
Regression Analysis Tool Market
Analytics
Predictive Analytics Market
Analytics
Cognitive Analytics Solutions Market
Analytics
Capacity Management Analytics Market
Analytics
Global Customer Analytics Market
Analytics
Content Analytics and Discovery Software Market
Analytics
Europe Network and Location Analytics Market
Analytics
Speech and Voice Analytics Market
Analytics
Global Mobile BI Market
Analytics
Research and Development (Randd) Analytics Market
Analytics
Global Industrial Analytics Market
Analytics
Global Visual Analytics Market
Analytics
Asia Pacific Speech Analytics Market
Analytics
US Predictive Analytics Market
Analytics
Business Analytics Market