
 Indonesia Digital Software Solutions Market | 2026-2036
Indonesia Digital Software Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Digital Software Solutions Market Insights
Platform licensing revenue is fragmenting across deployment models as Indonesian enterprises diversify beyond perpetual licenses toward consumption-based arrangements. Microsoft Corporation leverages its Azure cloud infrastructure to anchor hybrid deployments across state-owned enterprises. SAP SE sustains dominance in ERP modernization for manufacturing conglomerates in Java. Salesforce Inc. differentiates through CRM specialization targeting Indonesia's rapidly digitizing retail sector.
Indonesia Digital Software Solutions encompass enterprise-grade software applications, cloud infrastructure services, and data analytics platforms engineered for modular deployment across on-premises, cloud-based, and hybrid architectures. These solutions integrate API-first design patterns, containerized microservices, and real-time data pipelines to automate commercial workflows, regulatory reporting, and customer engagement for Indonesian organizations. Enterprise Software and Cloud Solutions command the dominant margin pools as large enterprises prioritize legacy system migration, while SaaS deployment is expanding fastest among Small & Medium Enterprises seeking lower upfront capital commitment. Analytics Tools represent an emerging structural segment where demand from Indonesia's banking and retail verticals is intensifying for predictive risk modeling and consumer behavior forecasting.
Kominfo's data localization mandates and BIS-aligned cybersecurity standards shape product architecture requirements for foreign vendors seeking market access. Indonesia's Personal Data Protection Law and sector-specific regulations issued by OJK for financial services impose compliance obligations that filter vendor eligibility and inflate implementation costs. Stakeholders must monitor enforcement consistency across provincial jurisdictions and anticipate how forthcoming AI governance frameworks will reshape software procurement criteria.
Market Dynamics
Kominfo's data localization mandates under Indonesia's Personal Data Protection Law are forcing foreign software vendors to re-architect cloud delivery models and establish domestic infrastructure partnerships, compressing deployment timelines and inflating compliance costs across banking and retail verticals.
Growth Catalysts
- Banking Cloud Migration:Indonesian financial institutions are accelerating replacement of legacy core systems with cloud-native platforms to meet OJK digital banking guidelines and reduce operational latency in transaction processing.
- PDP Law Enforcement:Kominfo's mandatory data residency requirements are creating captive demand for localized data center capacity and sovereign cloud deployments among multinational enterprises operating in Jakarta.
- API-First Architecture:Containerized microservices and real-time data pipelines are enabling modular system upgrades without wholesale replacement, lowering adoption barriers for mid-tier manufacturing conglomerates in Java.
Market Restraints
- Domestic Infrastructure Scarcity:Tier-III data center capacity concentrates in Greater Jakarta, forcing Surabaya and Bandung enterprises to absorb inter-island latency penalties or premium colocation costs.
- Localization Compliance Burden:Indonesia's Personal Data Protection Law imposes audit and breach-notification obligations that inflate implementation timelines by 40-60% relative to regional peers.
- Talent Pipeline Constraints:Certified cloud architects and cybersecurity specialists remain concentrated in Jakarta's financial district, creating wage inflation and project delays for deployments in secondary cities.
Strategic Opportunities
- Surabaya Tech Corridor Expansion:East Java's emerging enterprise cluster presents first-mover advantage for hybrid cloud providers establishing edge nodes outside Jakarta's saturated infrastructure market.
- SME SaaS Penetration:Consumption-based licensing models are unlocking software access for Indonesia's 64 million small and medium enterprises previously excluded by perpetual license capital requirements.
- AI Governance Preparation:Anticipated Kominfo frameworks for algorithmic accountability will create compliance tooling demand among banks and insurers building predictive risk models.
Industry Challenges
- Legacy System Integration Complexity:State-owned enterprises and established conglomerates operate heterogeneous technology stacks accumulated over decades, requiring costly middleware development for cloud connectivity.
- Provincial Enforcement Inconsistency:Data protection audits and cybersecurity certifications face variable interpretation across regional Kominfo offices, creating regulatory uncertainty for nationwide deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Digital Software Solutions Market |
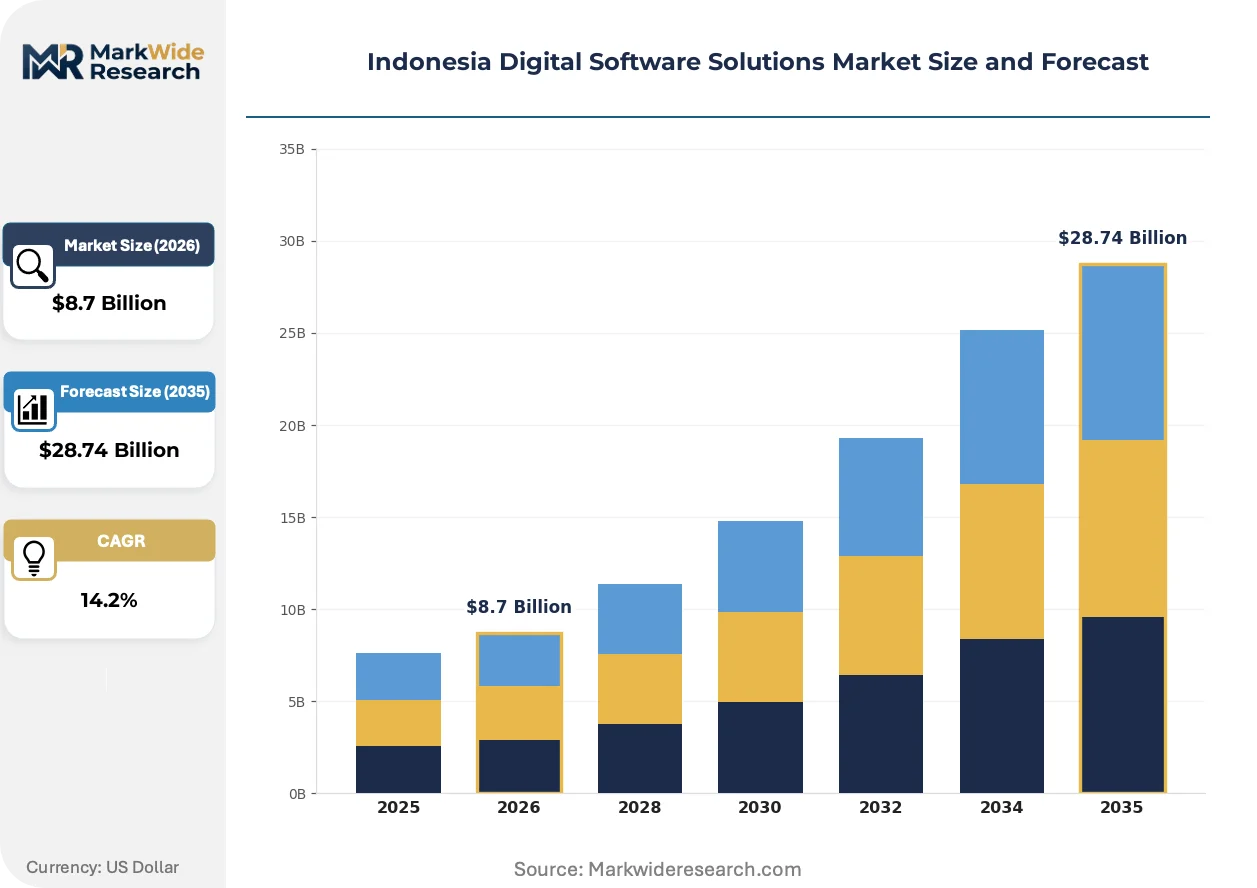
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
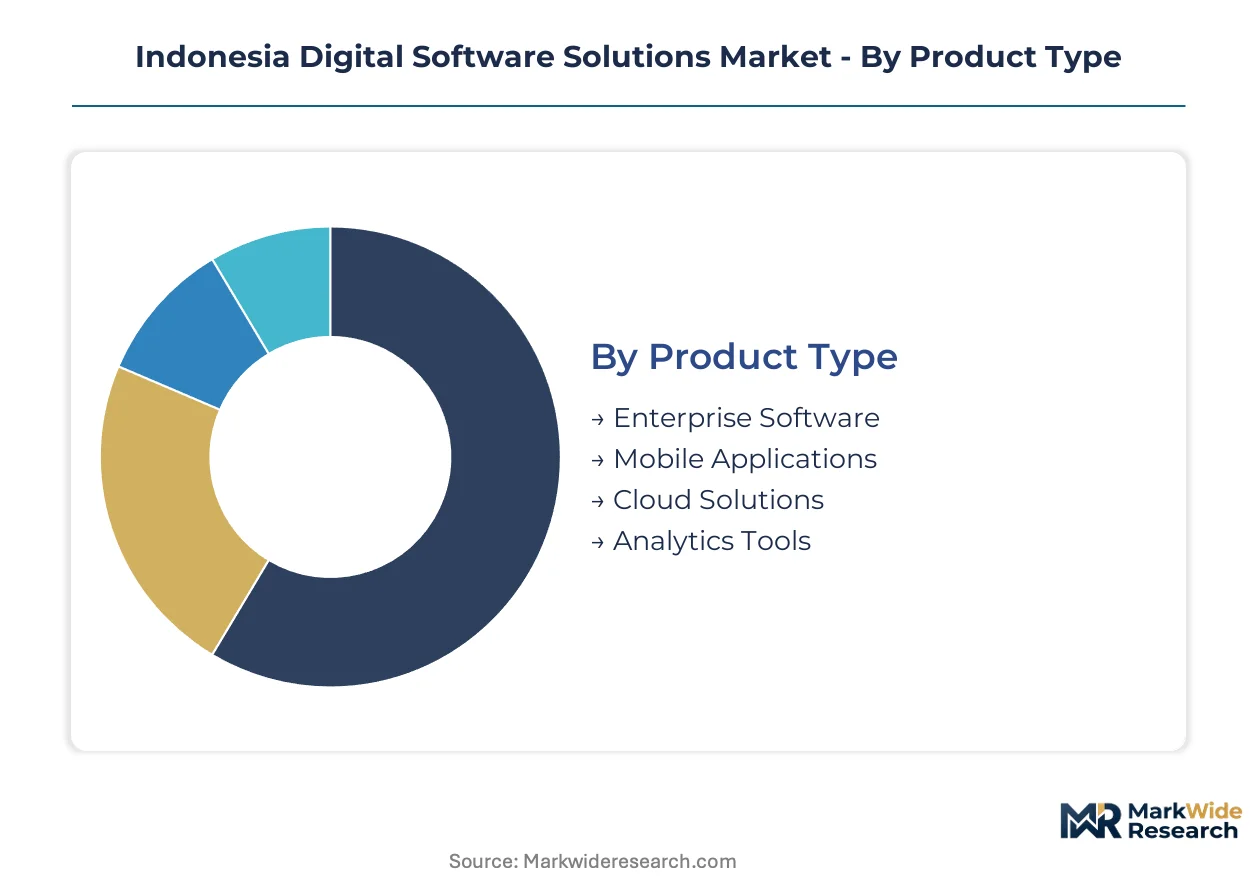
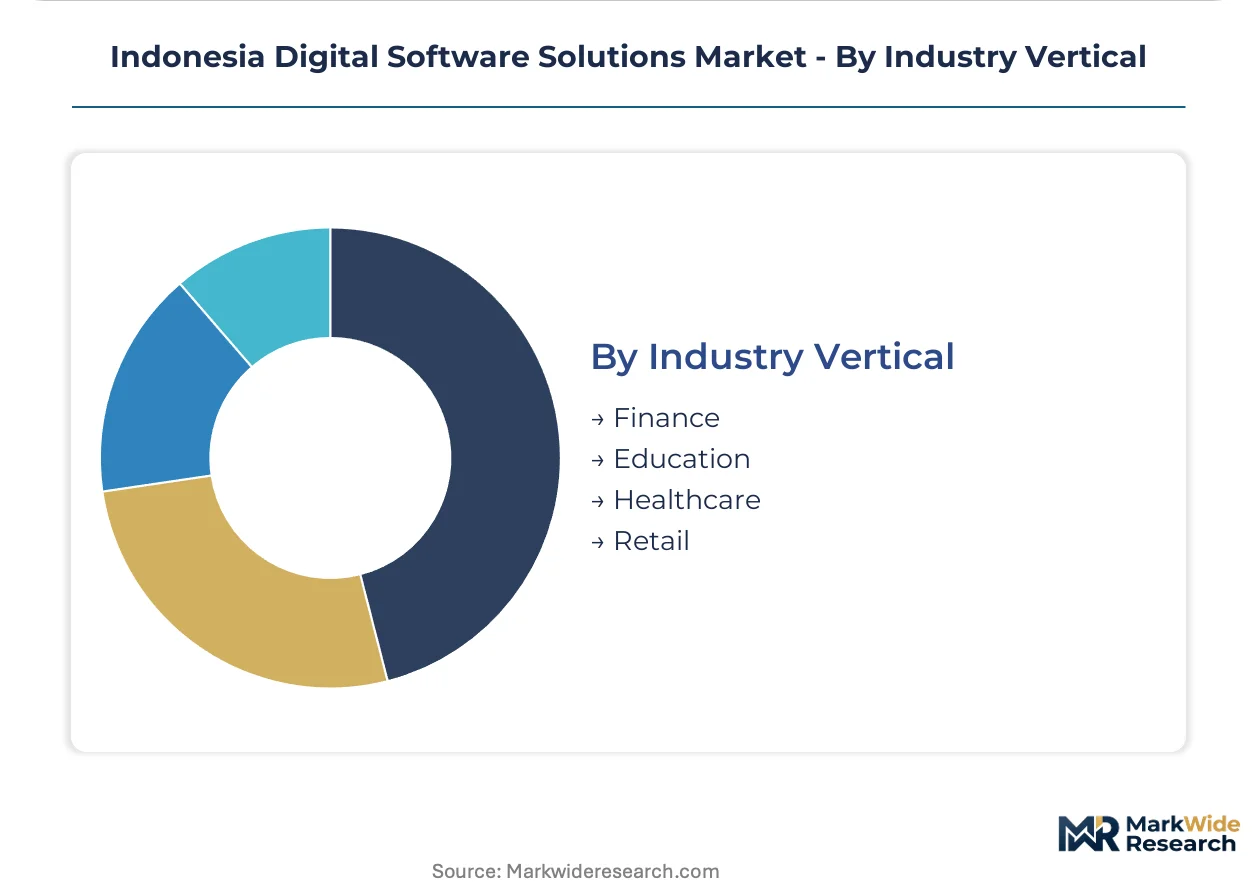
| Segmentation | Product Type: Enterprise Software, Mobile Applications, Cloud Solutions, Analytics Tools Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Small & Medium Enterprises, Large Enterprises, Government Agencies, Non-Profits Industry Vertical: Finance, Education, Healthcare, Retail |
| Companies Covered | Oracle Corporation, SAP SE, Microsoft Corporation, Salesforce Inc., IBM Corporation, PT Soltius Indonesia, PT Abyor International, Telkomsigma, Workday, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Digital Software Solutions Market Trends and Innovations
Software delivery architectures in Indonesia are fragmenting across deployment models as enterprises reject monolithic upgrades in favor of incremental, API-driven modernization paths that preserve operational continuity.
Container orchestration platforms are migrating from experimental pilot status to production-grade infrastructure for Indonesian banks. State-owned enterprises and private lenders in Jakarta are adopting Kubernetes-based deployments at accelerating velocity, compressing the traditional five-year core banking replacement cycle into phased microservice rollouts that reduce operational risk.
Kominfo's sector-specific data localization circulars are reshaping vendor eligibility criteria for public cloud providers. Foreign hyperscalers must now establish domestic legal entities and certified data residency zones to serve financial and healthcare verticals, forcing infrastructure partnerships with local telecommunications operators and state-owned data center providers.
Enterprise buyers in Indonesia's retail and manufacturing sectors are unbundling software procurement from systems integration services. Large conglomerates are directly negotiating SaaS subscriptions while retaining implementation partners for customization, compressing vendor margins and shifting value capture toward specialized deployment consultancies in Surabaya and Jakarta.
Indonesia Digital Software Solutions Market Segmentation
Indonesian enterprises fragment procurement priorities across cost tiers, compliance mandates, and legacy system constraints. Segment boundaries blur as hybrid architectures let organizations straddle deployment models without wholesale replacement.
Product Type:
Cost tier determines vendor eligibility and implementation complexity for Indonesian buyers navigating Kominfo's data localization requirements.
- Enterprise Software:Modular ERP and CRM suites integrate with legacy mainframes through API middleware. Banking conglomerates in Jakarta's financial district prioritize these systems for OJK regulatory reporting automation.
- Cloud Solutions:Hyperscaler infrastructure and sovereign cloud deployments anchor digital transformation programs. Demand concentrates among state-owned enterprises seeking PDP Law compliance without capital-intensive data center construction.
- Mobile Applications:Consumer-facing transaction platforms and internal workforce tools.
- Analytics Tools:Predictive modeling engines for risk assessment and demand forecasting.
Enterprise Software holds installed capacity. Cloud Solutions is rotating up the share rankings.
Deployment:
Application architecture determines where data residency obligations intersect with operational latency requirements.
- Hybrid:Split workloads between on-premises legacy systems and cloud burst capacity. Manufacturing conglomerates in Java favor this model for production continuity during connectivity disruptions.
- Cloud-Based:Fully managed infrastructure eliminating physical hardware ownership. Surabaya's emerging tech corridor shows accelerating uptake as local data center capacity expands.
- On-Premises:Self-managed servers within organizational facilities.
- SaaS:Subscription software access without infrastructure management.
On-Premises holds installed capacity. Hybrid is rotating up the share rankings.
End User:
Customer type shapes procurement authority and implementation risk tolerance across Indonesia's fragmented commercial landscape.
- Large Enterprises:Dedicated procurement teams negotiate enterprise licensing with direct vendor relationships. These organizations absorb complex integration timelines for customized deployments.
- Small & Medium Enterprises:Consumption-based licensing removes upfront capital barriers. The 64 million SME base in Indonesia accesses software previously excluded by perpetual license economics.
- Government Agencies:Public sector procurement through formal tender processes.
- Non-Profits:Grant-funded technology adoption with constrained implementation budgets.
Large Enterprises holds installed capacity. Small & Medium Enterprises is rotating up the share rankings.
Industry Vertical:
Geography within Indonesia concentrates demand where regulatory pressure and competitive intensity converge.
- Finance:Core banking replacement and digital payment infrastructure dominate technology budgets. OJK guidelines mandate cloud-native architectures for licensed institutions.
- Retail:Omnichannel customer engagement platforms and supply chain visibility tools. Jakarta's consumer markets drive demand for real-time inventory analytics.
- Healthcare:Electronic medical records and telemedicine platforms.
- Education:Learning management systems and administrative digitization.
Finance holds installed capacity. Retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's digital software infrastructure concentrates in Greater Jakarta, where hyperscaler availability zones and state-owned data centers cluster within a 50-kilometer radius of the financial district. This geographic concentration creates latency arbitrage opportunities for providers establishing edge presence in secondary metros. Provincial demand patterns diverge sharply based on local regulatory enforcement capacity and industrial base composition.
Greater Jakarta
Jakarta's financial district anchors cloud-native banking deployments as OJK-mandated digital transformation compresses core system replacement timelines. Kominfo's data localization audits concentrate enforcement resources here, creating compliance cost premiums for foreign vendors serving multinational headquarters. The Jakarta-Bogor-Depok-Tangerang-Bekasi corridor houses 70% of certified Tier-III data center capacity, forcing Surabaya and Bandung enterprises to absorb inter-island connectivity penalties or premium colocation fees.
East Java / Surabaya
Surabaya's emerging tech corridor presents first-mover positioning for hybrid cloud providers establishing sovereign infrastructure outside Jakarta's saturated market. Manufacturing conglomerates in Gresik and Sidoarjo prioritize API-first architectures for production continuity during connectivity disruptions. Local Kominfo offices show variable interpretation of PDP Law breach-notification timelines, creating regulatory uncertainty for nationwide software deployments.
West Java / Bandung
Bandung's educational technology cluster generates demand for learning management systems and administrative digitization platforms. The region's textile and garment manufacturers adopt consumption-based SaaS licensing to bypass perpetual license capital barriers. Talent pipeline constraints bite hardest here—certified cloud architects remain concentrated in Jakarta, inflating project timelines for Bandung-based implementations.
Bali / Denpasar
Tourism-dependent enterprises in Bali accelerate mobile application deployment for customer engagement and contactless transaction processing. The island's limited data center infrastructure forces reliance on Jakarta-based cloud burst capacity, introducing latency into real-time analytics workloads. Provincial government digitization initiatives create captive demand for localized software implementations compliant with Kominfo's sector-specific circulars.
North Sumatra / Medan
Medan's palm oil and agricultural processing conglomerates represent an underpenetrated vertical for predictive analytics and supply chain visibility tools. The region's distance from Jakarta's talent markets exacerbates implementation delays for complex ERP modernization projects. Local banking institutions lag in OJK-mandated cloud-native architecture adoption, creating a deferred demand pool for core banking platform replacements.
Indonesia Digital Software Solutions Market Competitive Landscape
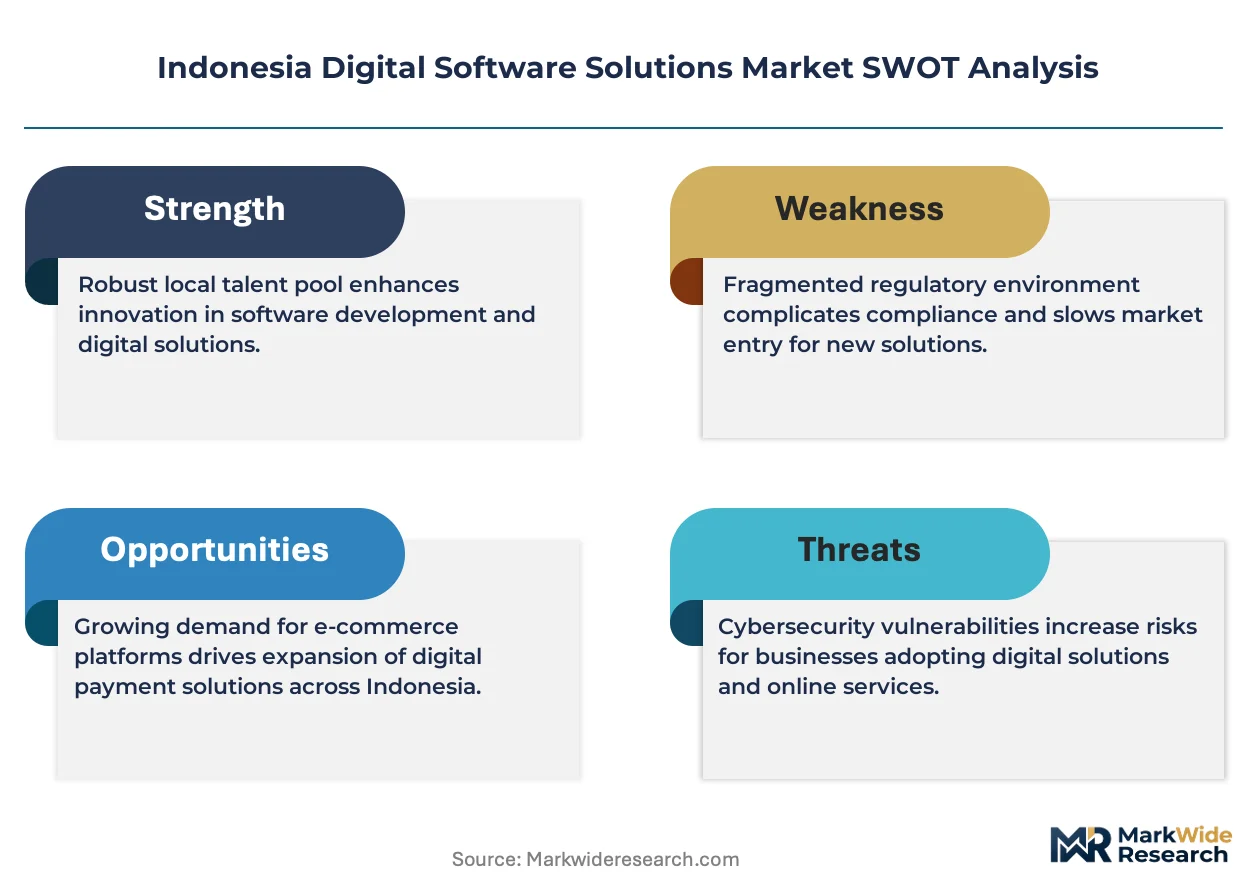
Hyperscale platform providers and specialized systems integrators split the Indonesia digital software market along deployment complexity lines. Market structure tilts toward consolidation in enterprise-grade infrastructure, where capital requirements for PDP Law-compliant data residency zones filter smaller competitors. Three archetypes dominate: global cloud hyperscalers anchoring hybrid deployments, regional ERP specialists customizing legacy migrations, and local systems integrators navigating provincial regulatory interpretation. Competitive intensity concentrates on strategic partnerships with state-owned telecommunications operators and certification velocity for sovereign cloud eligibility.
Within the global hyperscaler tier, Microsoft Corporation and Oracle Corporation exemplify platform providers leveraging domestic legal entity structures to access financial and healthcare verticals. SAP SE occupies a position representing ERP modernization specialists serving Java-based manufacturing conglomerates. Among Indonesia-based service providers, PT Soltius Indonesia and Telkomsigma exemplify systems integrators bridging foreign software licensing with localized implementation and compliance support. Salesforce Inc. represents the CRM specialization archetype targeting retail sector digitization. These named entities anchor competitive dynamics without exhaustively mapping market participation.
| Leading Market Players |
|---|
| Oracle Corporation |
| SAP SE |
| Microsoft Corporation |
| Salesforce Inc. |
| IBM Corporation |
| PT Soltius Indonesia |
| PT Abyor International |
| Telkomsigma |
| Workday |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Jakarta's Tier-III data center cluster is compressing colocation pricing and forcing infrastructure providers toward value-added service bundling, while simultaneously accelerating procurement negotiations for enterprises seeking sovereign cloud compliance without capital-intensive builds.
Pricing Analysis
Implementation and integration services drive lifetime value as Indonesian enterprises unbundle software licensing from deployment support. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade for PDP Law compliance and geographic delivery cost to secondary cities. Cost compression in mid-market ERP deployments is intensifying because local systems integrators compete on fixed-fee project structures. Small and medium enterprises exhibit highest price sensitivity due to consumption-based SaaS adoption constraints, while state-owned enterprises absorb premium tiers for sovereign cloud eligibility.
Supply Chain Analysis
Export-control restrictions on advanced semiconductor manufacturing equipment limit Indonesia's direct access to cutting-edge cloud infrastructure hardware, forcing reliance on pre-configured hyperscaler deployments. Supply concentrates in Singapore, Malaysia, and the United States for enterprise-grade server hardware and networking equipment. Component dependencies span specialized cooling systems, redundant power management units, and high-throughput fiber interconnects. Single-source vulnerability persists for certified data residency hardware compliant with Kominfo circulars. Distribution runs through state-owned telecommunications operators and their authorized systems integration partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story as cloud-native core banking adoption accelerates under OJK digital transformation mandates, creating sustained infrastructure demand across Jakarta's financial district and emerging secondary metros.
For Market Incumbents: Entrench dominance in sovereign cloud eligibility by securing certification velocity for PDP Law-compliant data residency zones before regulatory interpretation hardens. Deepen partnerships with state-owned telecommunications operators to control distribution channels against emerging hyperscaler competition. Prioritize API middleware development for legacy system integration to capture manufacturing conglomerate modernization budgets in Java.
For New Entrants and Emerging Players: Establish a beachhead in Surabaya's emerging tech corridor where Tier-III capacity scarcity creates first-mover positioning for edge node deployments. Target mid-tier manufacturing conglomerates in East Java with hybrid cloud solutions emphasizing production continuity during connectivity disruptions. Pursue consumption-based SaaS licensing models to unlock Indonesia's 64 million SME base previously excluded by perpetual license economics.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because Kominfo's evolving data localization mandates and anticipated AI governance frameworks will continuously filter vendor eligibility and inflate compliance costs for undercapitalized competitors. Acquisition target archetype: local systems integrators with established provincial regulatory relationships and certified implementation capacity outside Jakarta. Watch enforcement consistency across regional Kominfo offices as the signal for nationwide deployment feasibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first middleware development enables phased legacy modernization for Java manufacturing conglomerates. |
| Strategic Partnership | Domestic legal entity structures with state-owned telecommunications operators unlock sovereign cloud eligibility. |
| Geographic Expansion | Edge node deployment in Surabaya captures latency arbitrage from Jakarta's saturated infrastructure market. |
| Acquisition of Specialist Firm | Certified systems integrators bridge foreign software licensing with provincial regulatory interpretation. |
| Product Launch | AI governance compliance tooling anticipates Kominfo algorithmic accountability frameworks for banking verticals. |
Research Methodology
A spread of perspectives from chief technology officers, IT procurement officers, platform engineers, and systems integration specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC filings, hyperscaler capex disclosures, Kominfo regulatory circulars, and OJK digital banking guidelines. Bottom-up demand modeling across deployment modes and organization sizes triangulated with top-down market sizing from infrastructure capacity announcements and certified data center registrations.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled by deployment architecture, organization scale, industry vertical, integration complexity, and regional adoption pattern. CAGRs derived from trajectory analysis of historical licensing transitions and projected cloud migration timelines. Forecast inputs incorporated OJK-mandated core banking replacement schedules and anticipated PDP Law enforcement resource allocation across provincial jurisdictions.
Sensitivities concentrate around regulatory interpretation consistency, sovereign cloud certification velocity, and hyperscaler domestic partnership structures. Forecasts reflect documented assumptions regarding infrastructure buildout timelines and enterprise procurement authority centralization. Material shifts in AI governance framework timing or data localization audit intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Advanced Distribution Management System (ADMS) Market
Digital Solutions
Online Advocacy Platform Market
Digital Solutions
Electronic Records Management Solutions Market
Digital Solutions
Consent Management Market
Digital Solutions
Utility Cases Market
Digital Solutions
Affiliate Marketing Platform Market
Digital Solutions
Supplier Contract Management Market
Digital Solutions
NFT Creation Software Market
Digital Solutions
Asia-Pacific Route Optimization Software Market
Digital Solutions
Ticketing Solution Market
Digital Solutions
Global Media (Video) Processing Solutions Market
Digital Solutions
Coin Sorter Machines Market
Digital Solutions
Cloud E-Signature Tools Market
Digital Solutions
Advanced Drill Data Management Solutions Market
Digital Solutions
France ICT Market
Digital Solutions
Model Based Enterprise Market