
 Residential Solar Shading System Market | 2026-2036
Residential Solar Shading System Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Solar Shading System Market Analysis
European shading component manufacturers are pivoting toward automated fabrication lines to address capacity constraints in motorized systems. Hunter Douglas N.V. leverages its vertical manufacturing footprint across the Netherlands and Germany to sustain premium positioning in roller shade assemblies. Lutron Electronics Co., Inc. anchors North American demand through its lighting-control-integrated shading platforms. WAREMA Nederland B.V. dominates Benelux distribution channels with region-specific product configurations.
Residential solar shading systems comprise architectural elements—roller shades, awnings, exterior shutters, and interior louvers—engineered from aluminum, fabric, wood, or PVC to modulate solar heat gain, glare, and daylight penetration through fenestration. Fixed and motorized installation types incorporate sensors, motors, and control interfaces that respond to irradiance thresholds, optimizing thermal comfort and reducing HVAC loads. Roller shades capture the largest volume share across residential homes and apartments due to retrofit compatibility and cost accessibility. Motorized systems represent the fastest-expanding installation category, driven by smart home integration and rising condominium specifications in urban clusters.
The EU Green Deal and F-Gas Regulation shape product material standards, pushing fabricators toward low-emission coatings and recyclable aluminum extrusions. Germany's Building Energy Act and the Netherlands' national energy performance mandates require solar shading in new residential construction, directly expanding addressable demand. REACH compliance and CE marking obligations filter market access for imported PVC and coated fabric components. Stakeholders must monitor evolving national building codes and smart home interoperability standards to secure specification wins in the next construction cycle.
Market Dynamics
Residential solar shading is pivoting from static architectural elements to sensor-driven, automated climate interfaces. The EU Green Deal and national building energy mandates are compressing specification timelines while forcing fabricators to reengineer supply chains around low-emission aluminum and recyclable coated fabrics.
Growth Catalysts
- EU Green Deal material standards:The framework mandates low-carbon aluminum extrusions and recyclable fabric coatings, redirecting procurement toward certified European mills.
- Smart home integration protocols:Matter and KNX interoperability standards are collapsing installation complexity, accelerating motorized system adoption in multi-unit residential construction.
- Netherlands energy performance mandates:National building codes now require solar shading in new residential construction, expanding specification opportunities for fenestration-integrated systems.
Market Restraints
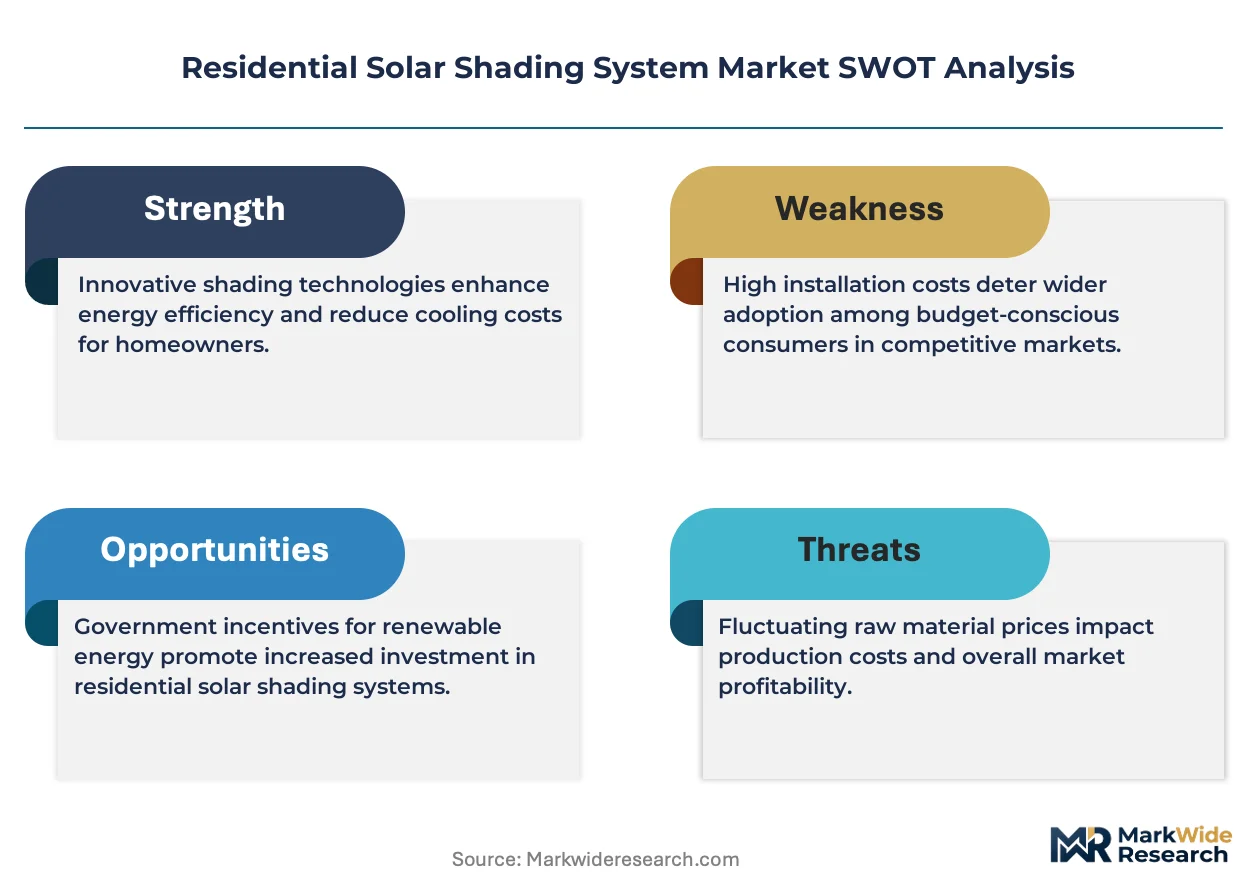
- Aluminum price volatility:Input cost swings for extruded profiles compress margin predictability for mid-tier fabricators without captive smelter relationships.
- REACH compliance timelines:ECHA substance restrictions on coated fabrics extend product certification cycles, delaying market entry for imported PVC components.
- Fixed shading substitution:Traditional exterior shutters retain cost advantage in Mediterranean retrofit markets, constraining motorized premium penetration.
Strategic Opportunities
- Benelux luxury townhouse pipeline:Amsterdam and Rotterdam development clusters specify integrated shading-HVAC systems, creating demand for turnkey motorized platforms.
- Germany Building Energy Act amendments:The mandate for solar shading in new construction opens specification windows for sensor-integrated roller assemblies.
- Lighting-control convergence:Daylight harvesting algorithms fused with LED dimming systems are creating bundled specification opportunities in high-end residential segments.
Industry Challenges
- Automation engineering talent scarcity:Motorized system assembly requires mechatronics specialists that fabricators struggle to recruit outside Eindhoven and Stuttgart industrial clusters.
- CE marking documentation burden:Machinery Directive compliance for motorized actuators extends product development timelines and strains smaller engineering teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Solar Shading System Market |
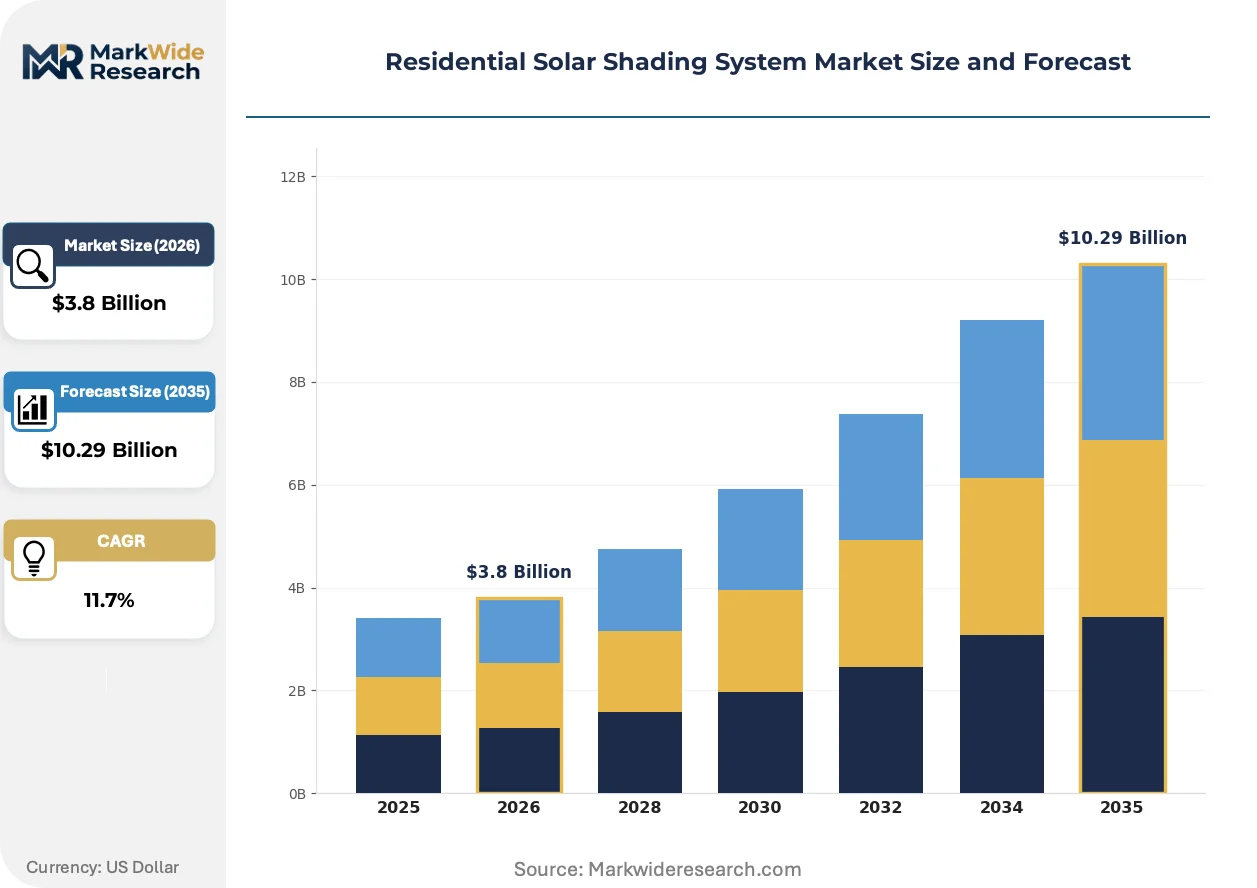
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roller Shades, Awnings, Exterior Shutters, Interior Louvers Material: Aluminum, Fabric, Wood, PVC Application: Residential Homes, Apartments, Condominiums, Townhouses Installation Type: Fixed, Motorized, Manual, Adjustable |
| Companies Covered | Hunter Douglas N.V., Lutron Electronics Co., Inc., Insolroll Window Shading Systems, Skyco Shading Systems, Inc., Springs Window Fashions, LLC, Glasscon GmbH, Duco Ventilation & Sun Control, WAREMA Nederland B.V., Unicel Architectural Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Solar Shading System Market Emerging Trajectories
Sensor-integrated shading systems are absorbing functionality from adjacent building automation categories. Fabricators now compete on algorithmic daylight optimization rather than material aesthetics alone.
Photovoltaic-integrated shading fabrics are absorbing surplus rooftop generation capacity in German and Dutch residential deployments. Luxury developers in Berlin and The Hague specify these dual-function membranes to meet net-zero certification thresholds. The technology is absorbing market share from conventional opaque awnings by collapsing the capital stack for solar-plus-shading retrofits.
Germany's amended Building Energy Act now mandates solar shading integration in all new residential construction permits. The regulation compresses specification windows for fenestration contractors and eliminates pure fixed-shading options from compliant bids. Motorized roller assemblies with irradiance sensors are capturing disproportionate share in Munich and Hamburg permit filings.
Specification authority is migrating from general contractors to specialized fenestration consultants in Benelux residential projects. These intermediaries unbundle shading selection from window procurement, introducing outcome-based performance guarantees. The shift concentrates decision power in Rotterdam and Amsterdam technical advisory firms that certify thermal comfort outcomes.
Residential Solar Shading System Market Segmentation
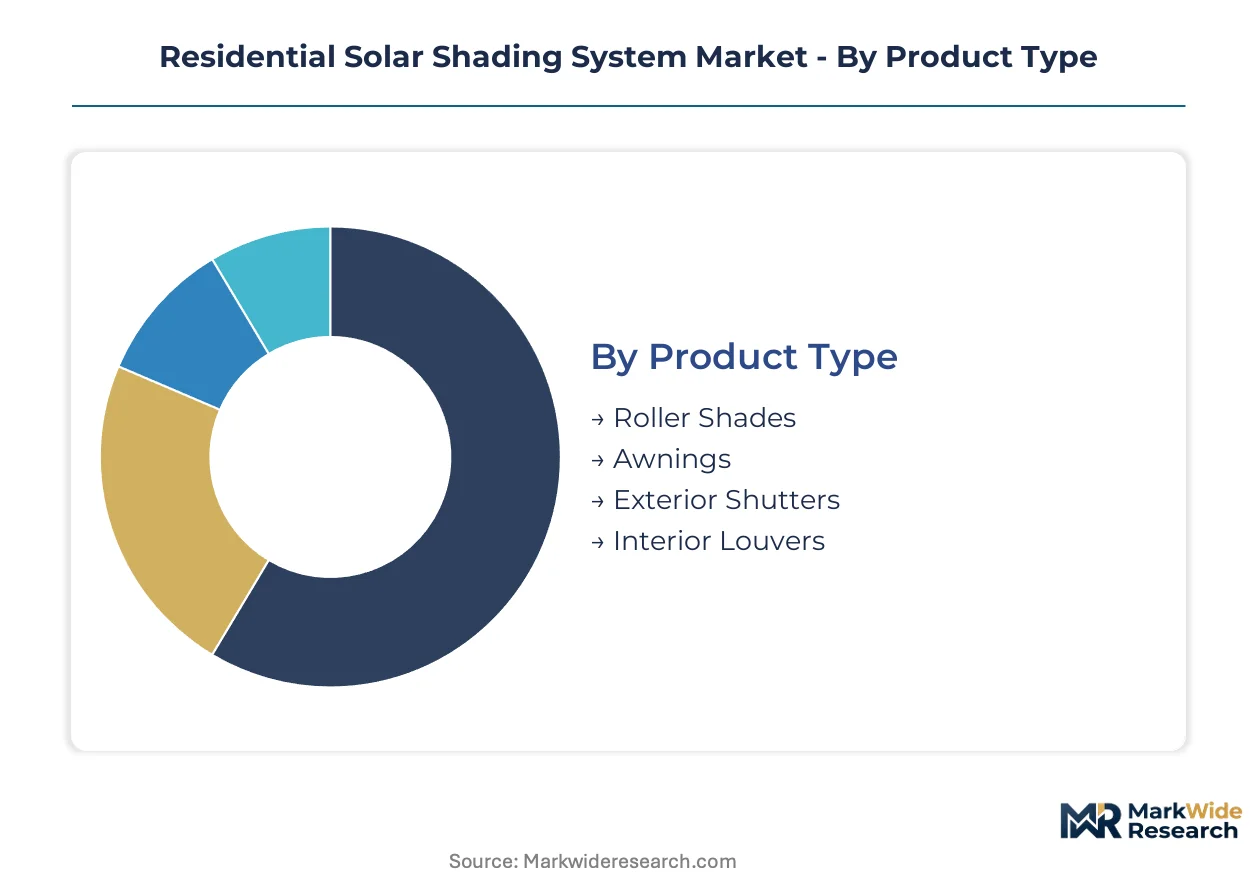
Product architecture in residential solar shading demands precise segmentation mapping. CE marking obligations and Machinery Directive compliance vary sharply across motorized versus fixed installations, creating divergent certification pathways for fabricators.
Product Type:
CE marking requirements intensify for motorized assemblies, while fixed systems face lighter conformity burdens under the Construction Products Regulation.
- Roller Shades:Fabric or membrane-based assemblies mounted on aluminum extrusion cassettes, engineered for retrofit compatibility in existing fenestration. Demand concentrates in Dutch and German apartment renovations where space constraints eliminate external shutter options. Matter protocol integration is accelerating specification in smart home developments across Rotterdam and Hamburg.
- Awnings:Cantilevered fabric or metal projections extending from facade planes, typically manual or motorized for terrace and balcony coverage. Italian and Spanish retrofit markets retain fixed-arm specifications due to cost sensitivity, though German new-build mandates are shifting specification toward sensor-integrated retractable models in Munich residential clusters.
- Exterior Shutters:Hinged or sliding panel systems in aluminum, wood, or PVC providing security alongside solar control. Mediterranean markets sustain demand for manually operated louvered designs.
- Interior Louvers:Adjustable slat systems installed within glazing cavities or as secondary interior screens. Benelux luxury townhouse developments specify these for daylight harvesting integration with LED dimming platforms.
Roller shades sit at the top of the volume ranking, with motorized awnings climbing the fastest.
Material:
REACH substance restrictions and F-Gas Regulation compliance costs stratify procurement tiers, with low-carbon aluminum commanding premium positioning against PVC alternatives.
- Aluminum:Extruded profiles with low-emission anodized or powder-coated finishes, specified for structural load-bearing in motorized roller cassettes and exterior shutter frames. German fabricators source certified low-carbon billet from Norwegian and Icelandic smelters to meet EU Green Deal embodied carbon thresholds.
- Fabric:Coated polyester, fiberglass, or photovoltaic-integrated membranes engineered for tensile strength and solar reflectance. Dutch developers specify PV-embedded fabrics in The Hague net-zero residential projects to collapse capital stacks for dual-function retrofits.
- Wood:Sustainably sourced timber species with preservative treatments for exterior durability. Austrian and Swiss alpine markets retain specification for aesthetic continuity with traditional architecture.
- PVC:Extruded vinyl profiles offering cost-accessible shutter and louver construction. ECHA substance restrictions on plasticizer chemistries extend certification cycles for imported components.
Aluminum dominates the value ranking, with photovoltaic-integrated fabrics expanding most quickly.
Application:
Building code mandates in Germany and the Netherlands create divergent specification intensity across housing typologies, with multi-unit construction facing tighter energy performance enforcement.
- Residential Homes:Single-family detached and semi-detached dwellings where homeowners control retrofit timing. German Building Energy Act amendments now mandate solar shading in all new permits, eliminating pure fixed-shading bids.
- Apartments:Multi-unit buildings with centralized facade management constraining individual unit modifications. Amsterdam and Rotterdam development clusters specify integrated shading-HVAC systems for BENG compliance.
- Condominiums:Owner-occupied multi-unit properties with homeowners association governance over exterior modifications. Smart home interoperability standards are accelerating motorized system adoption in Berlin and Hamburg luxury developments.
- Townhouses:Attached single-family units common in Benelux urban infill projects. Specification authority is migrating to fenestration consultants certifying thermal comfort outcomes.
Apartments command the largest addressable base, with condominiums gaining share fastest.
Installation Type:
Machinery Directive compliance for motorized actuators extends development timelines, while fixed and manual systems bypass mechatronics certification burdens.
- Fixed:Static architectural elements without moving components, including permanent awnings and fixed louver screens. Mediterranean retrofit markets retain cost advantage though German regulations are eliminating pure fixed options from compliant new-build bids.
- Motorized:Sensor-driven automated systems with irradiance-responsive control interfaces. Eindhoven and Stuttgart industrial clusters concentrate mechatronics engineering talent for actuator assembly.
- Manual:Human-operated crank, cord, or pole mechanisms for cost-accessible deployment. Standard in Spanish and Italian retrofit segments.
- Adjustable:Position-modifiable systems including tiltable louvers and retractable arms without motorization. Bridge specification for mid-tier residential projects seeking flexibility without smart home integration costs.
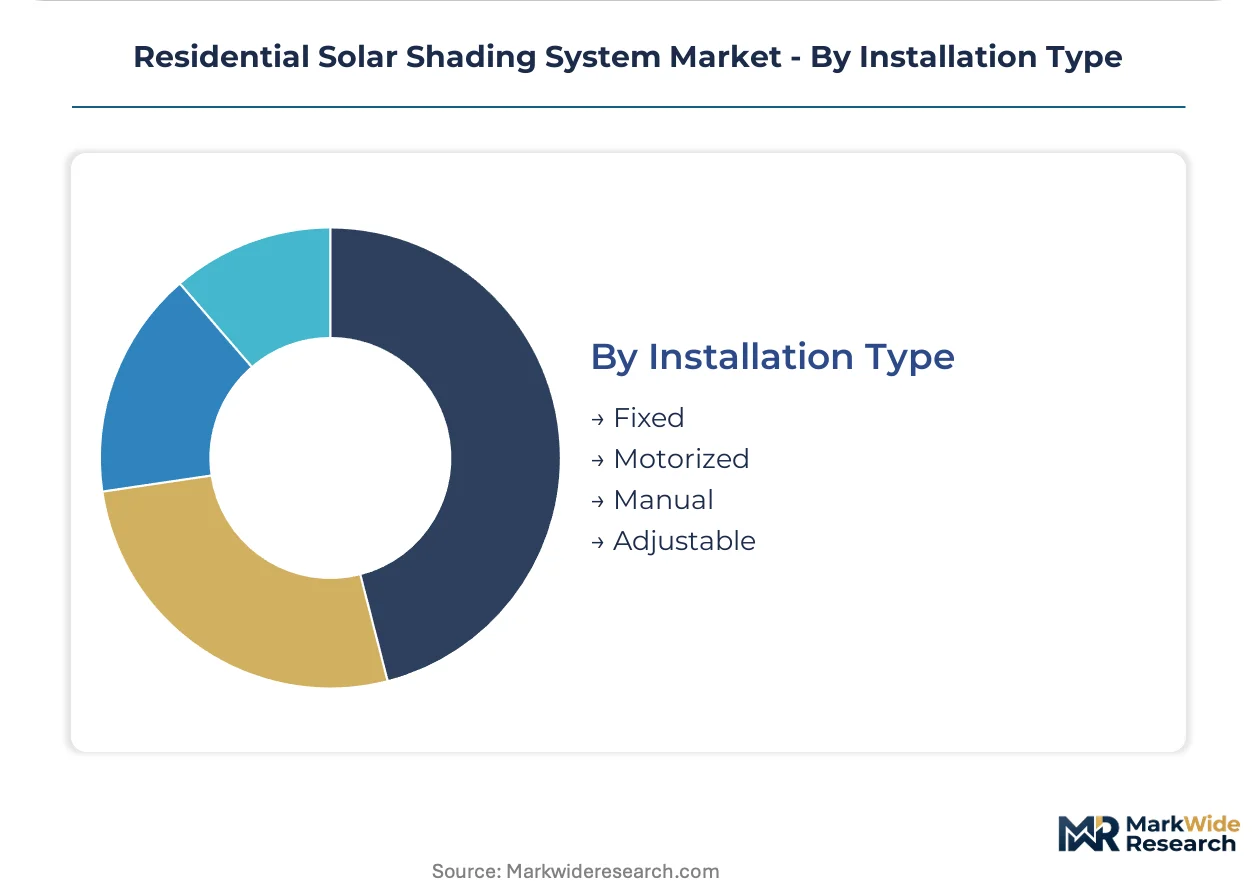
Fixed installations retain volume leadership, with motorized systems capturing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany mandates solar shading in all new residential permits while the Netherlands concentrates motorized system demand in Amsterdam-Rotterdam development clusters. Regulatory divergence between these markets shapes distinct specification timelines and product mixes.
Germany
Building Energy Act amendments eliminate pure fixed-shading bids from compliant new-build permits. Munich and Hamburg permit filings show disproportionate capture by sensor-integrated roller assemblies. Eindhoven industrial clusters supply mechatronics talent for actuator assembly serving southern German fabricators.
Netherlands
National energy performance mandates require solar shading in new residential construction under BENG compliance frameworks. Rotterdam and Amsterdam townhouse developments specify integrated shading-HVAC systems. WAREMA Nederland B.V. and Duco Ventilation & Sun Control anchor Benelux distribution networks with region-specific configurations.
United States
Smart home interoperability standards accelerate motorized system adoption in multi-unit residential construction. Lutron Electronics Co., Inc. anchors North American demand through lighting-control-integrated platforms. California and New York metro clusters drive premium specification for daylight harvesting algorithms.
Italy
Mediterranean retrofit markets retain manually operated louvered exterior shutters due to cost sensitivity. Fixed-arm awning specifications persist in terrace and balcony coverage segments. Northern Italian industrial districts supply aluminum extrusion components to German fabricators meeting EU Green Deal embodied carbon thresholds.
France
Auvergne-Rhône-Alpes and Île-de-France regions concentrate luxury residential development specifying interior louvers for daylight harvesting integration. REACH compliance timelines for coated fabrics extend product certification cycles for imported components. French fenestration consultants increasingly unbundle shading selection from window procurement.
Residential Solar Shading System Market Vendor Landscape
European fabricators anchor one tier; North American specialists hold another through smart home integration platforms. Market structure tilts toward consolidated premium positioning at the motorized-system end and fragmented fixed-shading supply at the retrofit-accessible end. Two archetypes dominate: vertically integrated European manufacturers with captive aluminum supply and control-system specialists bundling lighting-shading convergence. Competitive moves concentrate on automated production line expansion and strategic partnerships for sensor technology licensing.
Among Netherlands-based fabricators, Hunter Douglas N.V. and WAREMA Nederland B.V. represent the vertically integrated archetype with regional manufacturing footprints. Lutron Electronics Co., Inc. occupies a position exemplifying the control-system convergence specialist. These three entities anchor distinct competitive vectors—European fabrication scale, Benelux distribution density, and North American smart home platform integration—without overlapping strategic positioning.
| Leading Market Players |
|---|
| Hunter Douglas N.V. |
| Lutron Electronics Co., Inc. |
| Insolroll Window Shading Systems |
| Skyco Shading Systems, Inc. |
| Springs Window Fashions, LLC |
| Glasscon GmbH |
| Duco Ventilation & Sun Control |
| WAREMA Nederland B.V. |
| Unicel Architectural Corp. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied carbon thresholds gate qualified supply for premium-tier aluminum extrusions while compressing margin structures for fabricators without certified smelter relationships. Buyers face tiered access: certified low-carbon billet commands structural premiums, while uncertified imports compete on price in Mediterranean retrofit channels.
Pricing Analysis
Capacity additions in the Netherlands and Germany are reshaping price floors for motorized roller assemblies as automated fabrication lines absorb fixed overhead across larger production runs. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated systems with Matter protocol compatibility from basic motorized units and fixed-shading alternatives. Pricing pressure stems from aluminum price volatility transmitted through extrusion supply contracts. Residential homeowners in single-family retrofits exhibit highest price sensitivity, while Benelux luxury townhouse developers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Germany's domestic-content preferences under Building Energy Act compliance frameworks are reshaping sourcing patterns for mechatronics components and certified aluminum billet. Supply concentrates in Germany, the Netherlands, and Italy for extruded profiles, coated fabrics, and manual shutter assemblies. Raw material dependencies center on Norwegian and Icelandic low-carbon aluminum, Belgian coated polyester membranes, and Chinese-sourced actuator motors. Single-source vulnerability in irradiance sensor chipsets creates procurement risk for motorized system fabricators. Distribution runs through fenestration consultants in Benelux, direct contractor relationships in Germany, and building-material retailers in Mediterranean retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a geographic-arbitrage play: German regulatory mandates compress specification timelines and elevate compliance costs, while Dutch distribution density offers scale economies unavailable in fragmented Mediterranean channels.
For Market Incumbents: Deploy automated production line expansion in Eindhoven and Stuttgart industrial clusters to defend margin position against aluminum price volatility. Capture specification authority migration by certifying thermal comfort outcomes through Rotterdam and Amsterdam technical advisory partnerships. Backward integration into low-carbon aluminum sourcing from Norwegian smelters secures EU Green Deal compliance premiums.
For New Entrants and Emerging Players: Photovoltaic-integrated fabric technology offers a technology-first wedge into The Hague and Berlin net-zero residential developments where dual-function retrofits collapse capital stacks. Target Italian and Spanish manual-shading retrofit markets where cost sensitivity excludes motorized incumbents. Pursue white-label manufacturing partnerships with established Benelux distributors to bypass CE marking documentation burdens.
For Investors and Strategic Acquirers: Roll-up economics work for specialized fenestration consultants because specification authority unbundling from general contractors creates recurring revenue streams tied to BENG and Building Energy Act compliance. Acquire mid-cap fabricators with captive aluminum supply and existing Matter protocol integration. Watch German permit filing velocity as inflection indicator for motorized system demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Production Line Expansion | Netherlands-based fabricators reduce per-unit labor costs for sensor-integrated roller assemblies. |
| Photovoltaic Fabric Integration | Dutch developers in The Hague specify dual-function membranes for net-zero certification thresholds. |
| Smart Home Protocol Certification | Matter and KNX interoperability collapses installation complexity in multi-unit Rotterdam construction. |
| Low-Carbon Aluminum Sourcing | German fabricators secure EU Green Deal compliance through Norwegian and Icelandic smelter relationships. |
| Fenestration Consultant Partnerships | Amsterdam and Rotterdam technical advisory firms now control shading specification unbundled from window procurement. |
Methodological Framework
Direct dialogue with fenestration consultants, shading system fabricators, aluminum extrusion procurement leads, smart home integration specialists, and building code compliance officers grounded qualitative findings. Secondary validation drew from EU Construction Products Regulation filings, ECHA REACH substance restriction updates, German Building Energy Act permit databases, Dutch BENG compliance frameworks, and Benelux trade association shipment data. Bottom-up and top-down triangulation cross-checked manufacturer capacity disclosures against national construction permit volumes.
Bottom-up modeling aggregated segment-level demand across product type, material, application, and installation type dimensions. Top-down validation referenced macro construction spending and residential fenestration replacement cycles across the analysis window. CAGRs derived from polynomial trend fitting to permit filing trajectories and smart home device adoption curves. Industry-specific forecast inputs included aluminum LME price volatility bands and Eindhoven mechatronics engineering labor availability indices.
The model holds under stable regulatory enforcement of EU Green Deal material standards and Building Energy Act mandates; deviation in aluminum tariff regimes or ECHA substance restriction timelines would shift capacity deployment patterns. A small set of named triggers—German permit filing velocity, Matter protocol adoption rates, and Nordic smelter capacity allocation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
PERC Solar Cell Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Asia-Pacific Solar Blanket Market
Solar Power Systems
Global Solar Microinverter Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Utility Solar PV EPC Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Ground Mount PV Utility Market
Solar Power Systems
Asia Pacific Solar Backsheet Market
Solar Power Systems
Poland Solar Energy Market
Solar Power Systems
Australia Rooftop Solar Market