
 Acetic Ether Market | 2026-2036
Acetic Ether Market Size, Share, and Industry Trends Forecast 2026-2036
Acetic Ether Market Analysis
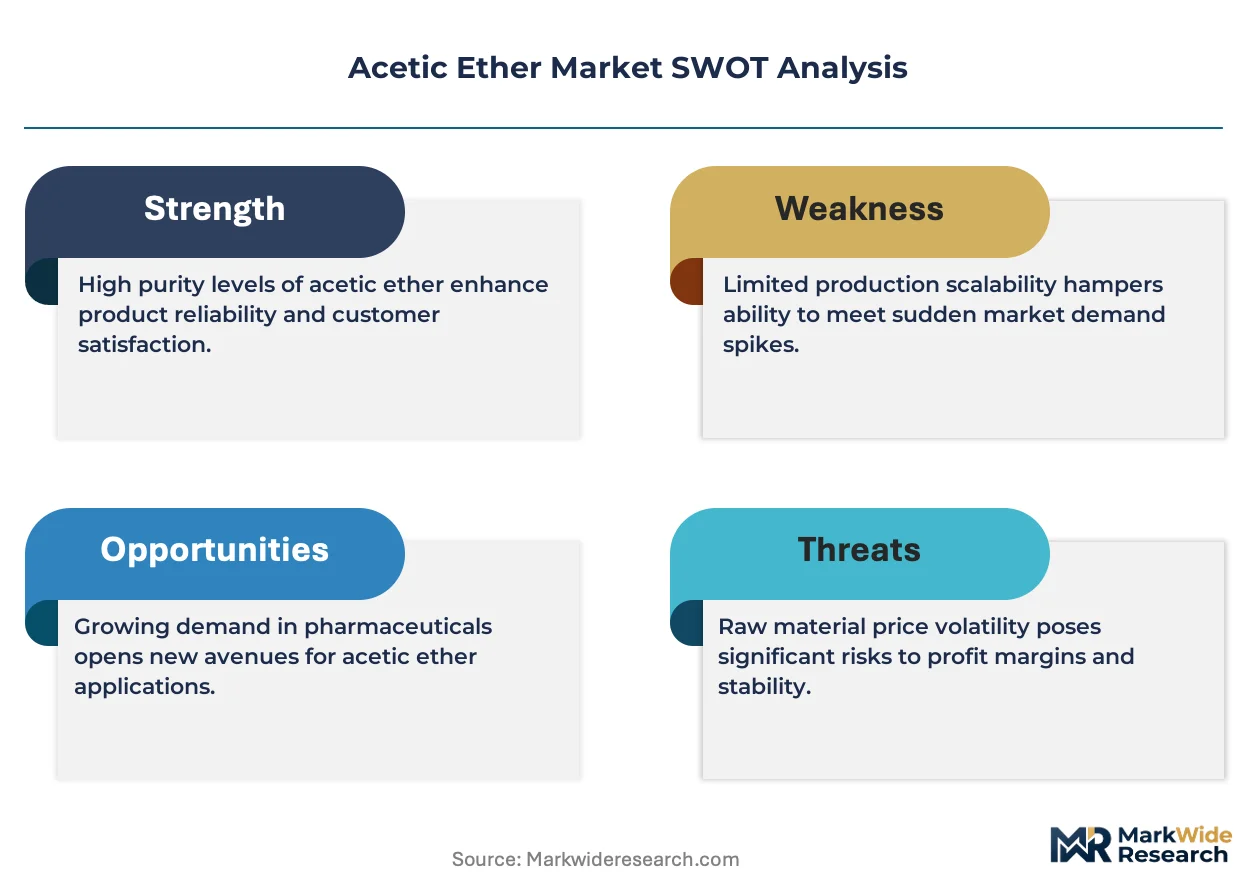
China's Shandong province is tilting the regional supply balance with expanded acetic ether production corridors. Celanese Corporation leverages its integrated acetyl chain to sustain cost-advantaged positions in high-purity grades. Eastman Chemical Company anchors North American supply through specialized solvent portfolios. INEOS Group Ltd. competes across European industrial channels with standardized bulk offerings.
Acetic ether, also known as ethyl acetate, is an organic ester with the molecular formula CH₃COOCH₂CH₃ and a boiling point near 77 degrees Celsius, manufactured primarily through Fischer esterification of acetic acid with ethanol or via Tishchenko condensation of acetaldehyde. It serves as a polar aprotic solvent prized for its moderate evaporation rate, low residual odor, and broad resin compatibility in coatings, adhesives, and pharmaceutical extraction processes. Industrial grade material dominates volume flows across global chemical distribution networks, while high purity segments command premium positioning in pharmaceutical and electronics applications where residual water and acid content must fall below 0.05 percent. Reagent grade supply channels maintain narrower specifications for analytical laboratories, though these volumes remain comparatively constrained against bulk industrial offtake.
The EPA governs volatile organic compound emissions from acetic ether handling and storage facilities under Clean Air Act provisions, pushing end-users toward recovery systems and lower-emission alternatives in US manufacturing zones. ECHA's REACH framework mandates comprehensive substance registration and safety data documentation for European market access, elevating compliance costs for non-EU producers while creating preference for certified domestic suppliers. China's SAMR enforces GB standards for industrial chemical purity and labeling, shaping import acceptance criteria at major port terminals. Stakeholders must monitor evolving solvent restriction lists across multiple jurisdictions while calibrating product grade portfolios to shifting regulatory thresholds rather than single-market specifications.
Market Dynamics
REACH compliance documentation in the European Union is forcing acetic ether suppliers to reconfigure purity certification workflows, elevating compliance costs while creating preference for certified domestic suppliers over import-dependent distributors.
Growth Catalysts
- Pharmaceutical solvent demand:Active ingredient synthesis in Germany is expanding procurement volumes for high-purity acetic ether grades, with formulators prioritizing suppliers offering sub-0.05% residual water specifications.
- China's coastal industrialization:Eastern provinces including Shandong and Jiangsu are concentrating coatings and agrochemical intermediate production, driving regional consumption corridors for industrial-grade material.
- Fischer esterification efficiency gains:Process optimization at integrated acetyl complexes is lowering unit production costs for ethanol-based manufacturing routes, improving margin structures for bulk suppliers.
Market Restraints
- Ethanol feedstock volatility:Bioethanol pricing fluctuations linked to corn harvest cycles in the US and Brazilian sugarcane seasons create input cost instability for esterification-based producers.
- Shandong supply concentration:China's provincial production corridors control disproportionate global capacity, exposing buyers to single-region logistics disruptions and port congestion risks.
- Acetone substitution pressure:Methyl ethyl ketone and acetone are displacing acetic ether in select coating formulations where faster evaporation rates outweigh odor and compatibility trade-offs.
Strategic Opportunities
- Electronics-grade expansion:Semiconductor cleaning applications in South Korea and Taiwan are creating demand for ultra-high-purity material with particulate specifications below 100 ppm.
- Recovery system retrofitting:EPA Clean Air Act enforcement is mandating solvent recovery installations at US coatings facilities, creating service and equipment bundling opportunities for chemical suppliers.
- SAMR certification alignment:China's GB standards for industrial chemical labeling are tightening, rewarding early-adopter suppliers with streamlined port clearance and distributor preference.
Industry Challenges
- Analytical chemistry talent scarcity:Qualified technicians capable of executing gas chromatography purity verification to REACH documentation standards are concentrated in Western European labor markets, constraining quality control scaling.
- Multi-jurisdiction certification timelines:Simultaneous ECHA registration, EPA TSCA compliance, and SAMR filing requirements create 18-24 month product launch delays for new grade introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetic Ether Market |
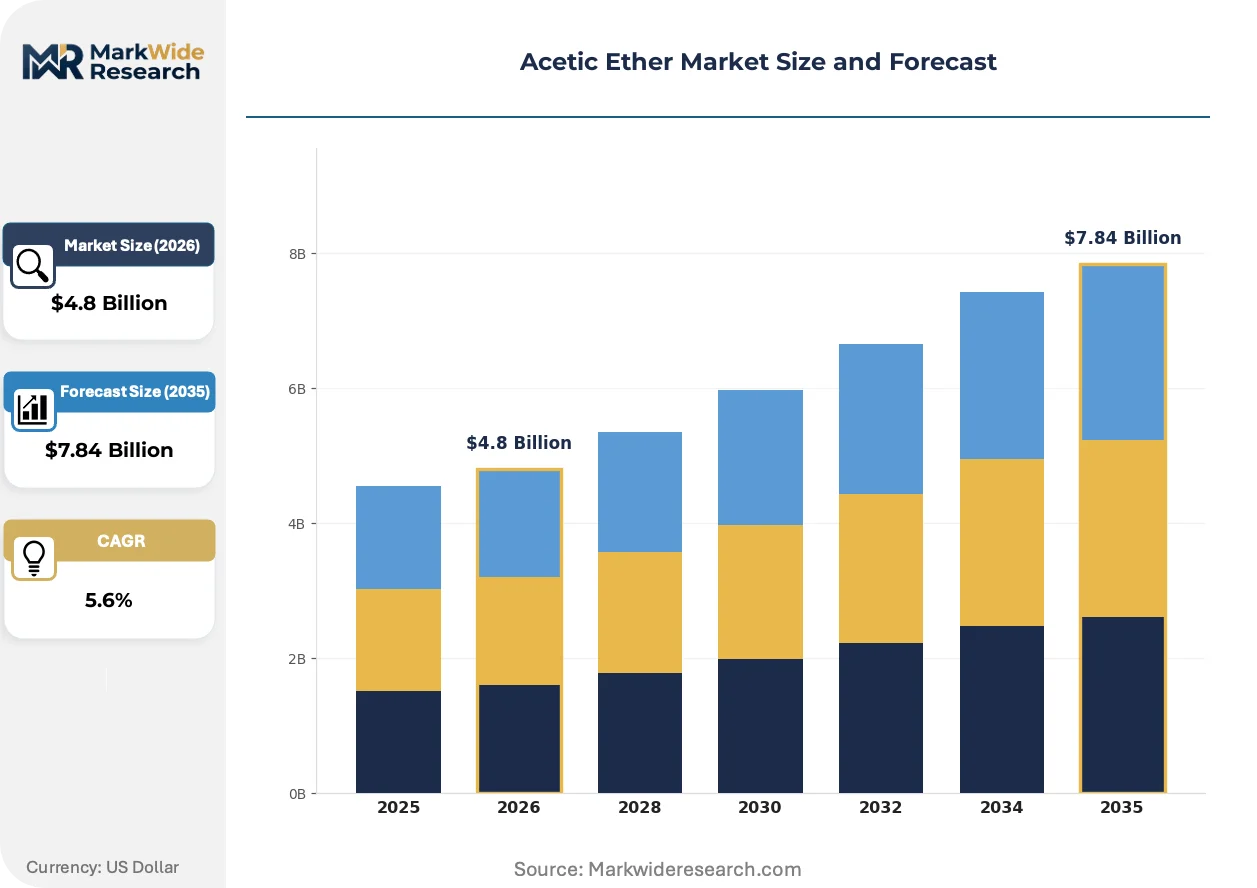
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.84 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Purity, Reagent Grade, Industrial Grade, Anhydrous End Use Industry: Pharmaceuticals, Agrochemicals, Food & Beverage, Coatings Distribution Channel: Direct Sales, Online Retail, Distributors, Chemical Suppliers Application: Solvent, Intermediate, Additive, Extractant |
| Companies Covered | Celanese Corporation, Eastman Chemical Company, INEOS Group Ltd., Daicel Corporation, Solvay S.A., Sasol Ltd., Yip's Chemical Holdings Limited, Shandong Jinyimeng Group Co., Ltd., Jiangsu Sopo (Group) Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetic Ether Market Emerging Trajectories
Process analytical technology is digitizing quality assurance workflows, while regulatory frameworks in major economies are tightening purity documentation requirements. Buyer procurement patterns are simultaneously compressing supplier qualification cycles and demanding integrated compliance support.
Inline near-infrared spectroscopy is digitizing real-time moisture and acid content monitoring during Fischer esterification operations. Pharmaceutical manufacturers in Germany and Switzerland are adopting these systems to eliminate batch-release delays. The technology is digitizing quality control from offline laboratory testing to continuous process verification, compressing certification timelines from days to hours.
REACH substance registration requirements are expanding safety data documentation obligations for acetic ether importers into the European Union. ECHA's updated dossier standards now mandate chronic toxicity endpoint studies for volumes exceeding 1000 tonnes annually. High-purity pharmaceutical grade suppliers are responding by consolidating registration responsibilities with integrated acetyl chain producers rather than maintaining independent filings.
Coatings formulators in China's eastern provinces are consolidating solvent procurement through integrated chemical distributors offering bundled logistics and compliance documentation. Small and mid-sized paint manufacturers are abandoning direct mill relationships in favor of third-party platforms providing REACH-aligned certification packages. This channel migration is most visible in Jiangsu province, where port-proximate distribution hubs are capturing increasing volume share from traditional trading companies.
Acetic Ether Market Segmentation
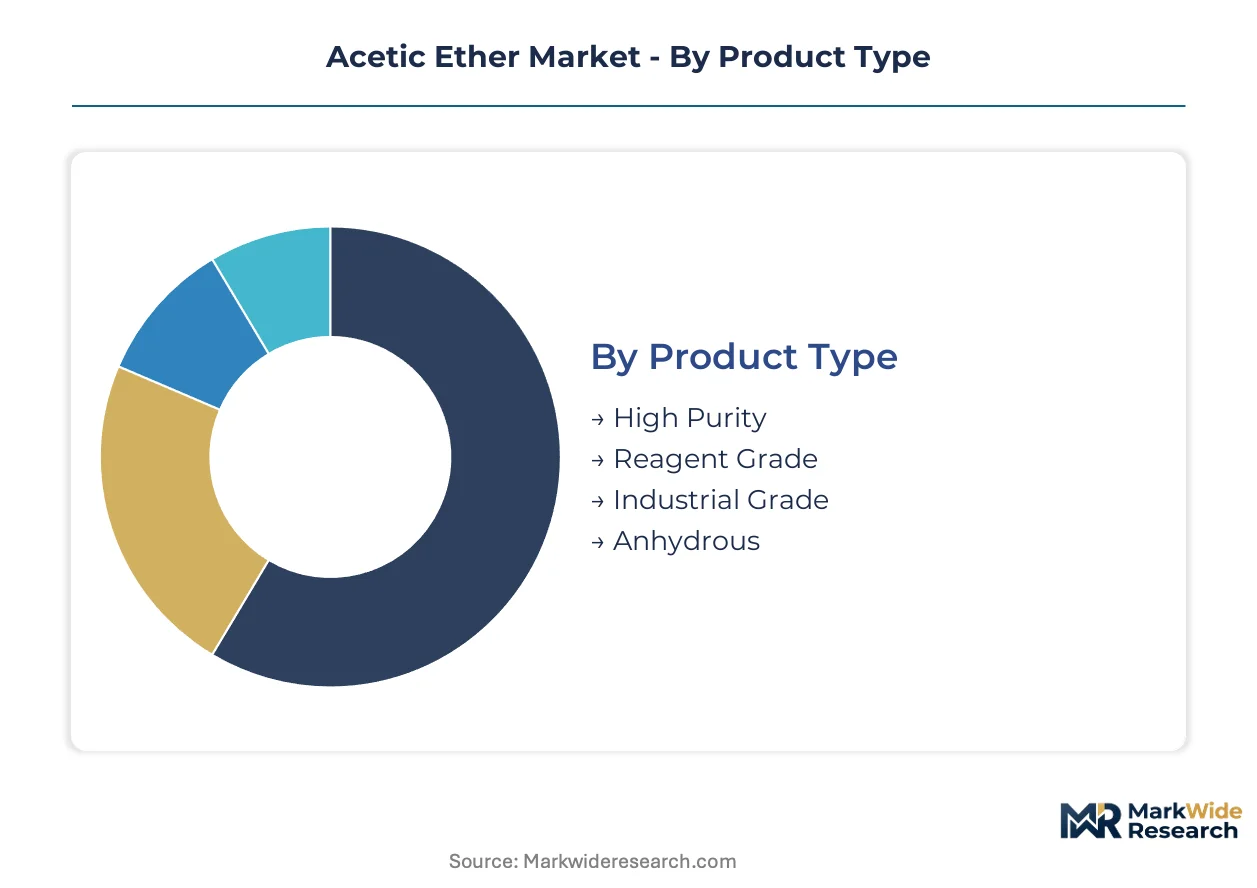
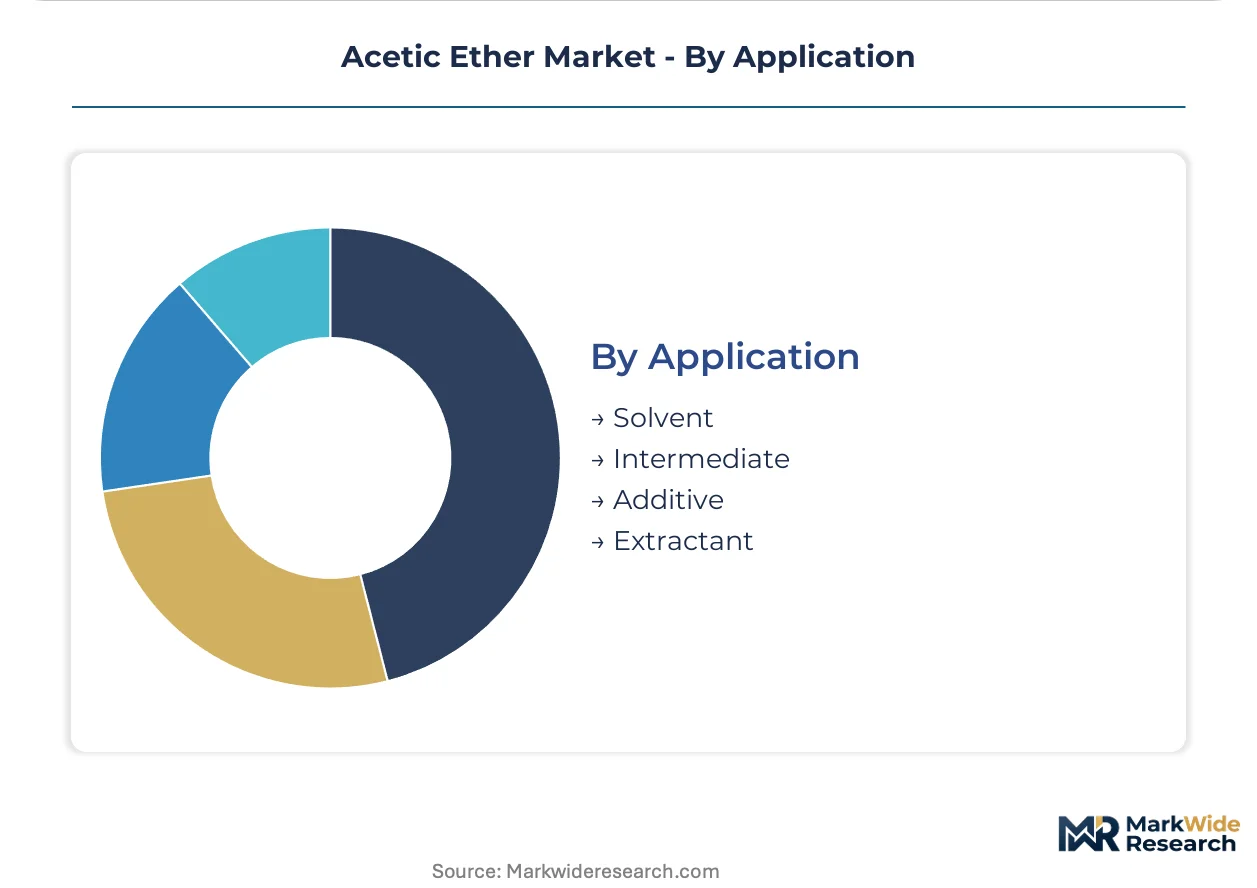
Acetic ether's functional versatility creates distinct demand profiles across purity grades and end-use applications. Segmentation reveals how pharmaceutical extraction tolerances diverge sharply from industrial coating requirements, shaping supplier specialization strategies.
Product Type:
Mature bulk grades dominate tonnage flows while emerging high-specification segments capture margin expansion opportunities.
- Industrial Grade:Material with 85-99% purity serves coatings manufacturers and adhesive formulators across China's Shandong production corridors. Demand concentrates in solvent applications where moderate residual water content tolerances keep unit economics favorable for high-volume buyers.
- High Purity:Sub-0.05% residual water specifications command premium positioning in German pharmaceutical active ingredient synthesis. ECHA REACH documentation requirements favor certified domestic European suppliers over import-dependent distributors for this grade.
- Reagent Grade:Analytical laboratory applications in Switzerland and Germany maintain stringent gas chromatography verification protocols.
- Anhydrous:Electronics cleaning applications in South Korea and Taiwan require particulate specifications below 100 ppm.
Industrial Grade retains volume leadership; High Purity holds the steepest expansion curve.
End Use Industry:
Application-driven cost tiers separate pharmaceutical premium positioning from commodity industrial offtake.
- Pharmaceuticals:Active ingredient extraction and synthesis in Germany and Switzerland demands sub-0.05% residual acid content. Inline near-infrared spectroscopy adoption is compressing batch-release timelines from days to hours for high-purity procurement.
- Coatings:Resin compatibility and moderate evaporation rates sustain demand across China's Jiangsu province paint manufacturing clusters. EPA Clean Air Act enforcement is mandating solvent recovery system retrofits at US coatings facilities.
- Agrochemicals:Intermediate production in China's eastern coastal provinces consumes industrial-grade volumes for pesticide synthesis.
- Food & Beverage:Flavor extraction and decaffeination processes require food-grade certification alignment.
Coatings commands the largest tonnage position; Pharmaceuticals is climbing the fastest.
Distribution Channel:
Channel structure reflects customer scale concentration and compliance documentation bundling requirements.
- Distributors:Integrated chemical distributors in China's Jiangsu province are capturing volume share from traditional trading companies by offering REACH-aligned certification packages bundled with logistics.
- Direct Sales:Celanese Corporation and Eastman Chemical Company anchor North American supply through mill-direct relationships with large coatings manufacturers.
- Chemical Suppliers:Specialized solvent portfolios serve mid-sized formulators requiring technical support.
- Online Retail:Small-volume laboratory procurement channels serve analytical chemistry applications.
Distributors retain volume leadership; Direct Sales holds the most stable margin structure.
Application:
Functional role determines specification stringency and customer switching costs.
- Solvent:Polar aprotic properties with 77°C boiling point serve broad resin compatibility in adhesives and coatings. China's eastern provinces concentrate this demand.
- Intermediate:Agrochemical synthesis in Shandong province consumes industrial-grade material for pesticide active ingredient production.
- Extractant:Pharmaceutical manufacturers in Germany prioritize suppliers offering real-time purity verification systems.
- Additive:Flavor and fragrance formulations require food-grade certification pathways.
Solvent retains volume leadership; Extractant is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's GB standards for industrial chemical purity and labeling are reshaping import acceptance criteria at China's major port terminals, creating preference for early-adopter suppliers with streamlined clearance pathways.
China
Shandong province's production corridors control disproportionate global acetyl chain capacity, exposing buyers to single-region logistics disruptions. SAMR enforces GB standards for industrial chemical purity and labeling at Qingdao and Shanghai terminals. Jiangsu province paint manufacturing clusters are consolidating solvent procurement through integrated distributors offering bundled compliance documentation.
Germany
Pharmaceutical formulators in Baden-Württemberg and Bavaria are expanding high-purity acetic ether procurement for active ingredient synthesis. ECHA's REACH framework mandates comprehensive substance registration and safety data documentation for European market access. The Rhine-Main chemical corridor concentrates demand for sub-0.05% residual water specifications.
United States
The EPA governs volatile organic compound emissions from acetic ether handling and storage facilities under Clean Air Act provisions. Coatings manufacturers in Ohio and Texas face mandates for solvent recovery system retrofits. Gulf Coast petrochemical complexes anchor North American supply through specialized solvent portfolios.
South Korea
Semiconductor cleaning applications in Gyeonggi-do and Suwon are creating demand for ultra-high-purity material with particulate specifications below 100 ppm. MFDS maintains pharmaceutical-grade chemical import standards aligned with international harmonization protocols. The Seoul Capital Area electronics cluster drives premium-grade consumption corridors.
Switzerland
Analytical laboratory applications in Basel and Zurich maintain stringent gas chromatography verification protocols for reagent-grade supply. Swissmedic enforces pharmaceutical chemical purity standards exceeding baseline European requirements. The Basel-Land chemical manufacturing belt concentrates precision-grade demand.
Acetic Ether Market Vendor Landscape
Integrated acetyl chain producers and specialized solvent portfolio operators split the market between cost-advantaged bulk positioning and premium-grade technical service. The structure tilts toward scale-driven consolidation at the industrial-grade tier while fragmenting across high-purity niches requiring certification depth. Three archetypes dominate: captive acetyl chain operators, independent esterification specialists, and regional distribution-integrated suppliers. Capacity expansion in Shandong province and REACH-aligned certification investments represent the dominant competitive moves.
Among integrated acetyl chain operators, Celanese Corporation and Eastman Chemical Company exemplify the scale-driven archetype through captive ethanol-esterification pathways. INEOS Group Ltd. occupies a position within the European bulk supply tier. These three anchors demonstrate how backward integration into acetic acid and ethanol feedstocks creates defensive positioning against bioethanol price volatility.
| Leading Market Players |
|---|
| Celanese Corporation |
| Eastman Chemical Company |
| INEOS Group Ltd. |
| Daicel Corporation |
| Solvay S.A. |
| Sasol Ltd. |
| Yip's Chemical Holdings Limited |
| Shandong Jinyimeng Group Co., Ltd. |
| Jiangsu Sopo (Group) Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Qingdao-Shanghai freight corridors carry the dominant share of acetic ether volume movements, with container rate volatility feeding directly into Shandong-origin price premiums and downstream tier separation between industrial and pharmaceutical grades. This logistics cost dynamic amplifies the pricing power held by integrated acetyl chain operators while compressing margins for import-dependent distributors serving high-purity segments.
Pricing Analysis
Regional price spreads between Shandong industrial-grade deliveries and Rhine-Main pharmaceutical-grade supply exceed three-to-one multiples, with certification documentation bundling the primary differentiation driver alongside real-time purity verification capabilities. Three-tier pricing structure across premium, standard, and economy levels stratifies by residual water specifications and REACH alignment depth. Cost compression in industrial-grade spot markets is intensifying because acetone substitution pressure accelerates in coatings applications. Small and mid-sized paint manufacturers in Jiangsu province exhibit the highest price sensitivity, while German pharmaceutical formulators prioritize specification adherence over unit cost.
Supply Chain Analysis
Tariff exposure between US Gulf Coast petrochemical complexes and European derivative markets dominates strategic sourcing calculations for coatings manufacturers seeking supply diversification. Production gravity centers on China, the United States, and Germany, with ethanol feedstock sourcing drawing from Brazilian sugarcane and US corn harvest cycles. Single-source vulnerability concentrates in Shandong province production corridors, where port congestion risks amplify delivery uncertainty. Distribution runs through integrated chemical distributors in Jiangsu province and mill-direct relationships anchored by Celanese and Eastman in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Acetic ether demand tracks pharmaceutical manufacturing cycles and coatings construction activity, with bioethanol harvest volatility the dominant cyclical driver resetting margin structures every 12-18 months.
For Market Incumbents: Entrench certification depth as the primary defensive moat by consolidating REACH registration responsibilities with integrated acetyl chain partners rather than maintaining independent ECHA filings. Expand captive ethanol-esterification capacity in Texas and Louisiana to offset Brazilian sugarcane price volatility. Acetone substitution pressure in industrial coatings represents the most immediate margin threat requiring specification differentiation investment. For New Entrants and Emerging Players: Build out ultra-high-purity electronics-grade supply capability targeting South Korean semiconductor cleaning applications, where particulate specifications below 100 ppm command premium positioning and incumbent concentration remains lowest. Taiwan's Gyeonggi-do electronics cluster offers the most penetrable geographic entry point. Partner with German inline near-infrared spectroscopy vendors to compress batch-release timelines as the differentiated go-to-market angle. For Investors and Strategic Acquirers: Regional distribution-integrated suppliers with SAMR certification alignment and Jiangsu province port access represent the most attractive acquisition target archetype for medium-term consolidation plays. Long-term viability hinges on regulatory certification asset accumulation rather than pure production scale. Watch for ECHA dossier standard updates on chronic toxicity endpoints as the inflection signal indicating registration cost barriers rising sufficiently to trigger forced seller dynamics among independent esterification specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethanol Feedstock | Celanese and Eastman control captive supply chains insulating margin structures from Brazilian sugarcane harvest volatility. |
| REACH-Aligned Certification Investment | ECHA's expanded dossier standards reward early adopters with streamlined European market access and distributor preference. |
| Electronics-Grade Capacity Expansion | South Korean MFDS standards and Taiwan's semiconductor cluster create premium positioning for sub-100 ppm particulate material. |
| Solvent Recovery System Retrofitting | EPA Clean Air Act enforcement mandates create service bundling opportunities for chemical suppliers at Ohio and Texas coatings facilities. |
| SAMR GB Standards Alignment | China's port clearance streamlining rewards certified suppliers with distributor volume capture in Jiangsu province procurement consolidation. |
Methodological Framework
A standing panel of plant managers at integrated acetyl complexes, procurement leads at German pharmaceutical formulators, distribution channel partners in Jiangsu province, and technical R&D directors at coatings manufacturers provided ongoing calibration across quarterly update cycles. Primary interview insights combined with secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up grade-tier demand modeling and top-down regional consumption estimates underwent continuous reconciliation.
Scenario-bracketing around bioethanol price volatility and REACH compliance cost trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled included purity grade tier, end-use industry concentration, regional production hub configuration, and certification documentation depth. CAGRs derived from historical volume correlations with downstream pharmaceutical and coatings activity, cross-referenced against Fischer esterification efficiency gain curves and acetone substitution elasticity parameters.
Sensitivities concentrate around Brazilian sugarcane harvest disruptions, ECHA dossier standard revisions, and Shandong province logistics congestion events that could revise forecasts outside modeled bands. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Fatty Alcohol Ethoxylates Market
Chemicals
Chemical Distribution Market
Chemicals
Hydrophobing Agents Market
Chemicals
HATU Market
Chemicals
Global Diacetone Alcohol Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Natural Fatty Alcohols Market
Chemicals
Xanthates Market
Chemicals
Egypt Construction Chemicals Market
Chemicals
Myclobutanil Market
Chemicals
Benzenoid Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Asia-Pacific Construction Chemicals Market
Chemicals
Guanidine Carbonate Market
Chemicals
Solder Flux Market
Chemicals
Selenium Sulfide Market