
 White Phosphorus Market | 2026-2036
White Phosphorus Market Size, Share, and Industry Trends Forecast 2026-2036
White Phosphorus Market Intelligence
Purity grade certification and traceability services is expanding the value proposition beyond bulk material supply. Hubei Xingfa Chemicals Group leverages its significant production scale to influence regional supply dynamics in Asia. Meanwhile, Excel Industries Limited specializes in downstream derivatives, creating a distinct position in the Indian market. Yunnan Phosphorus Group Company Limited sustains its market presence through control over key phosphate rock resources.
White phosphorus is a highly reactive allotrope of phosphorus, existing as tetrahedral P4 molecules and produced via an electrothermal furnace process. Its primary industrial purpose is as a key intermediate for high-purity phosphoric acid and other phosphorus compounds. The chemical synthesis application dominates consumption, serving as a precursor for various industrial chemicals. While the pesticides segment matures, use in advanced flame retardants for electronics and polymers represents a significant value-added opportunity.
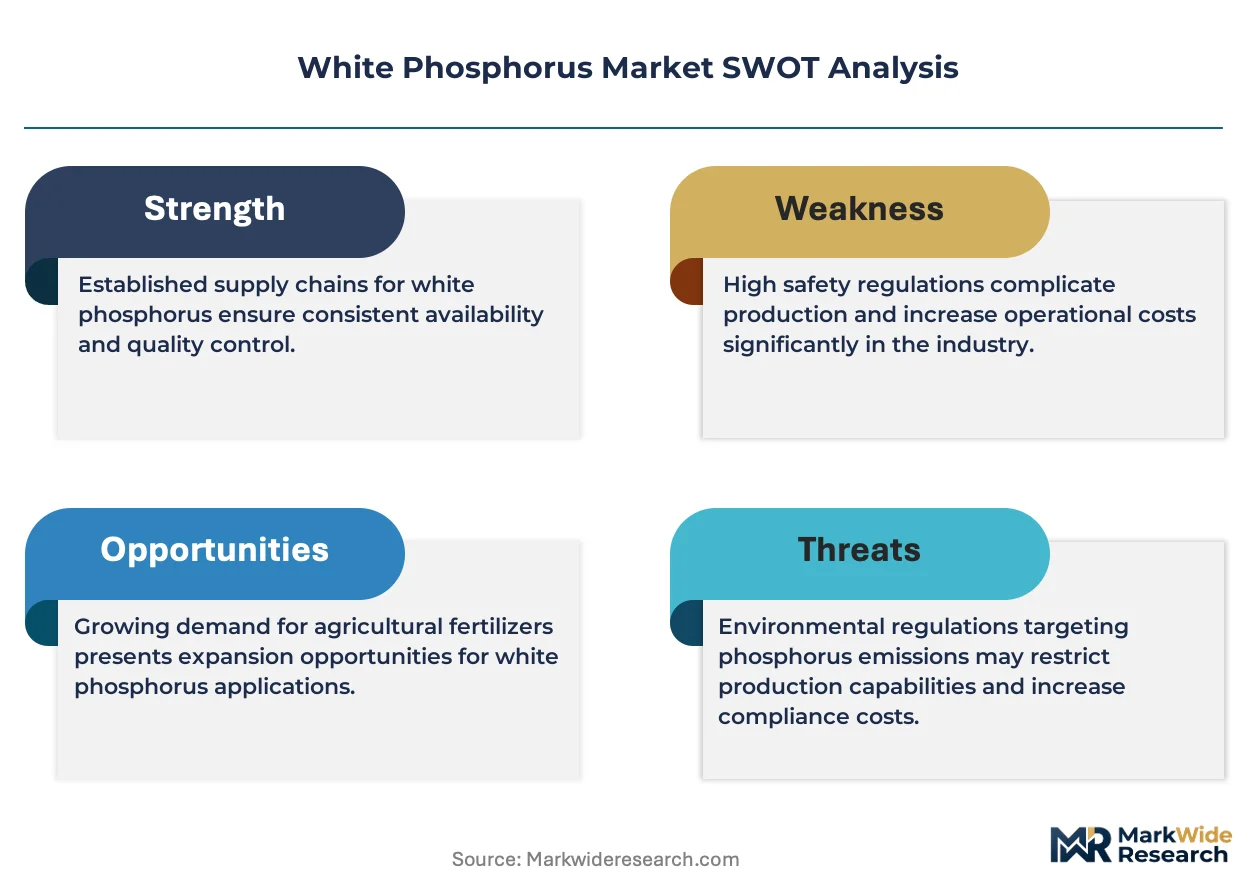
The market operates under stringent controls, including monitoring by the Organisation for the Prohibition of Chemical Weapons (OPCW) under the Chemical Weapons Convention. In parallel, national bodies like the US EPA and China's Ministry of Ecology and Environment (MEE) enforce strict regulations on production emissions and transportation safety. Navigating the evolving landscape of environmental stewardship and supply chain security will be critical for producers and downstream users.
Market Dynamics
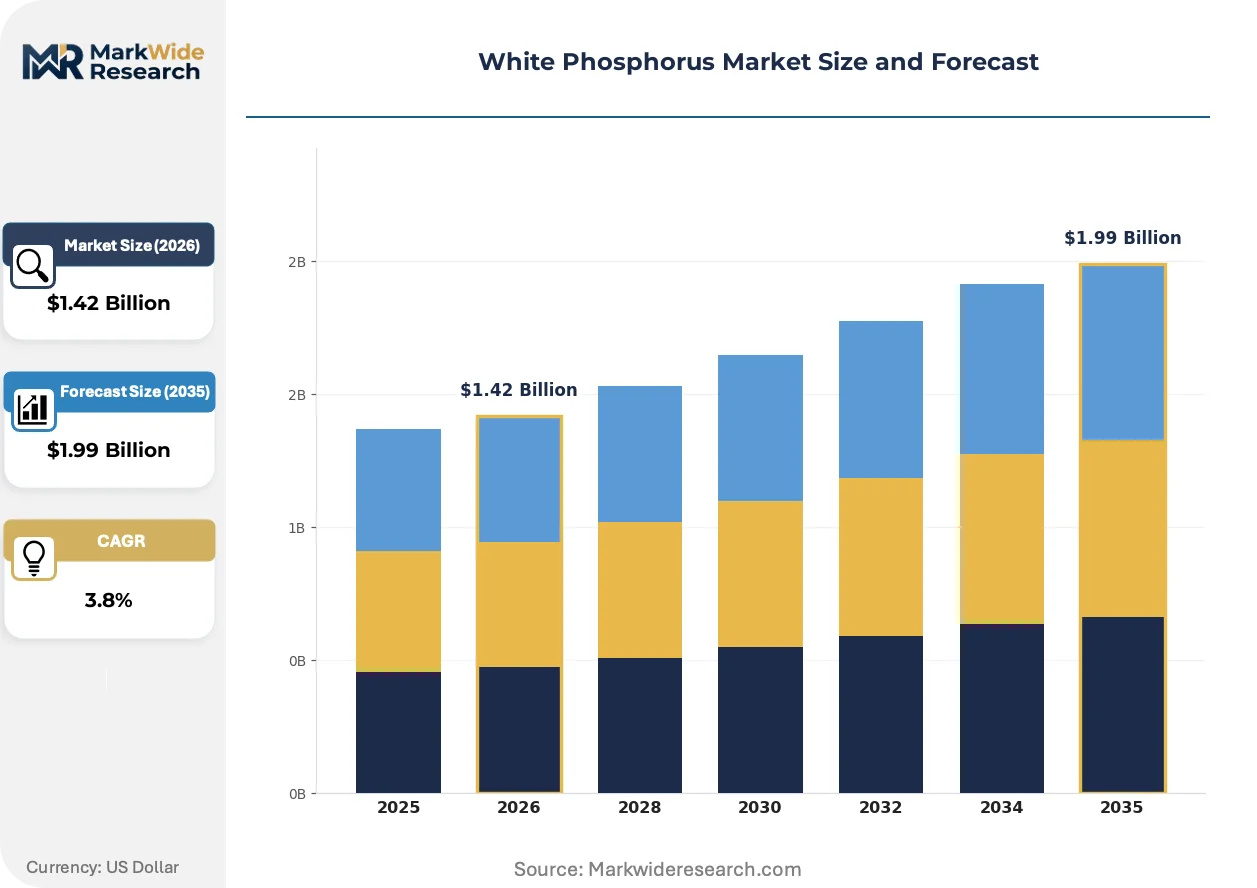
The market's central dynamic is the tension between heavy production concentration within China, which dictates global price and availability, and increasingly stringent international safety and environmental regulations that add cost and complexity to the supply chain.
Growth Catalysts
- Flame Retardant Demand:The transition to halogen-free flame retardants in electronics and construction materials, driven by regulations like the EU's RoHS directive, creates sustained demand for phosphorus-based compounds derived from white phosphorus.
- Agricultural Modernization:Government initiatives in nations like India and Brazil to improve crop yields support the domestic production of organophosphate pesticides, which use white phosphorus as a foundational chemical precursor.
- High-Purity Applications:The expansion of the semiconductor and specialty battery industries requires ultra-high-purity phosphoric acid, for which white phosphorus is a critical starting material, creating a high-value demand stream.
Market Restraints
- Energy Cost Volatility:The electrothermal furnace process is extremely energy-intensive, making production costs highly sensitive to electricity price fluctuations in key manufacturing regions like Yunnan province in China.
- Stringent Transport Protocols:As a dual-use chemical monitored under the Chemical Weapons Convention, white phosphorus is subject to exceptionally strict global handling, storage, and transportation rules, increasing logistical costs and complexity.
- Substitution in Detergents:The successful phase-out of phosphates in consumer detergents in North America and Europe, driven by environmental concerns over eutrophication, has eliminated a historical large-volume application.
Strategic Opportunities
- Battery Material Development:Research into phosphorus-based compounds as components for anodes or solid-state electrolytes in next-generation lithium-ion and sodium-ion batteries presents a significant long-term growth vector.
- Southeast Asian Market Entry:Establishing downstream finishing and derivative production facilities in Southeast Asia could capture value by serving the region's growing electronics and agrochemical industries locally.
- Enhanced Traceability Services:Offering blockchain-enabled or digitally certified traceability from phosphate rock to final product can create a premium for suppliers serving the electronics and food-grade additive markets.
Industry Challenges
- Modernization Capex:The high capital investment required to retrofit or build new furnace facilities compliant with stringent environmental rules, such as those from China's MEE, presents a barrier to entry and a challenge for existing producers.
- OPCW Compliance Burden:Managing the rigorous declaration, verification, and inspection regimes mandated by the Organisation for the Prohibition of Chemical Weapons requires specialized internal expertise and adds significant administrative overhead.
- Specialized Talent Scarcity:A limited pool of chemical engineers and technicians possess the specific expertise required to safely manage and optimize high-temperature electrothermal phosphorus production processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | White Phosphorus Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $1.99 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Military Applications, Chemical Synthesis, Flame Retardants, Pesticides End Use Industry: Aerospace, Agriculture, Pharmaceuticals, Chemicals Form: Granular, Powder, Liquid, Crystalline Packaging Type: Drums, Bags, Containers, Cylinders |
| Companies Covered | Yunnan Phosphorus Group Company Limited, Sichuan Chuantou Chemical Industry Group Company Ltd., Guizhou Qianneng Tianhe Phosphate, Hubei Xingfa Chemicals Group, Viet Hong Chemical and Trading Company Limited, Excel Industries Limited, Nippon Chemical, Chongqing Chuandong Chemical, Guizhou Sino-Phos Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
White Phosphorus Market Strategic Shifts & Innovations
Process intensification and supply chain security are defining current innovation. Producers and consumers are exploring technological and service-based solutions to mitigate the risks associated with a highly concentrated and regulated supply chain, pushing the industry beyond simple bulk material provision.
Modular production technologies for creating high-purity phosphoric acid directly from elemental phosphorus are gaining attention. Specialty chemical and semiconductor firms are the primary evaluators, seeking to reduce dependence on the global transport of hazardous materials. This potential for on-site or near-site intermediate synthesis is decentralizing a portion of the value chain away from geographically distant, large-scale chemical complexes.
The EU's REACH regulation continues to impact the market by requiring extensive data submission and risk assessment for chemical imports, including phosphorus derivatives. This forces non-EU producers, particularly from China, to invest significantly in compliance to maintain market access, effectively creating a regulatory trade barrier. The pesticide and polymer additive segments are most affected, often reformulating products to use substances with more complete registration dossiers.
A notable shift in buyer behavior is the increasing preference for material with certified purity and documented provenance. End-users in the electronics and food ingredient sectors are moving away from sourcing based on price alone, instead prioritizing suppliers who can provide comprehensive data packages that ensure quality and supply chain integrity. This demand for transparency is most evident in supply chains connecting Asian producers with regulated markets in North America and Europe.
White Phosphorus Market Segmentation
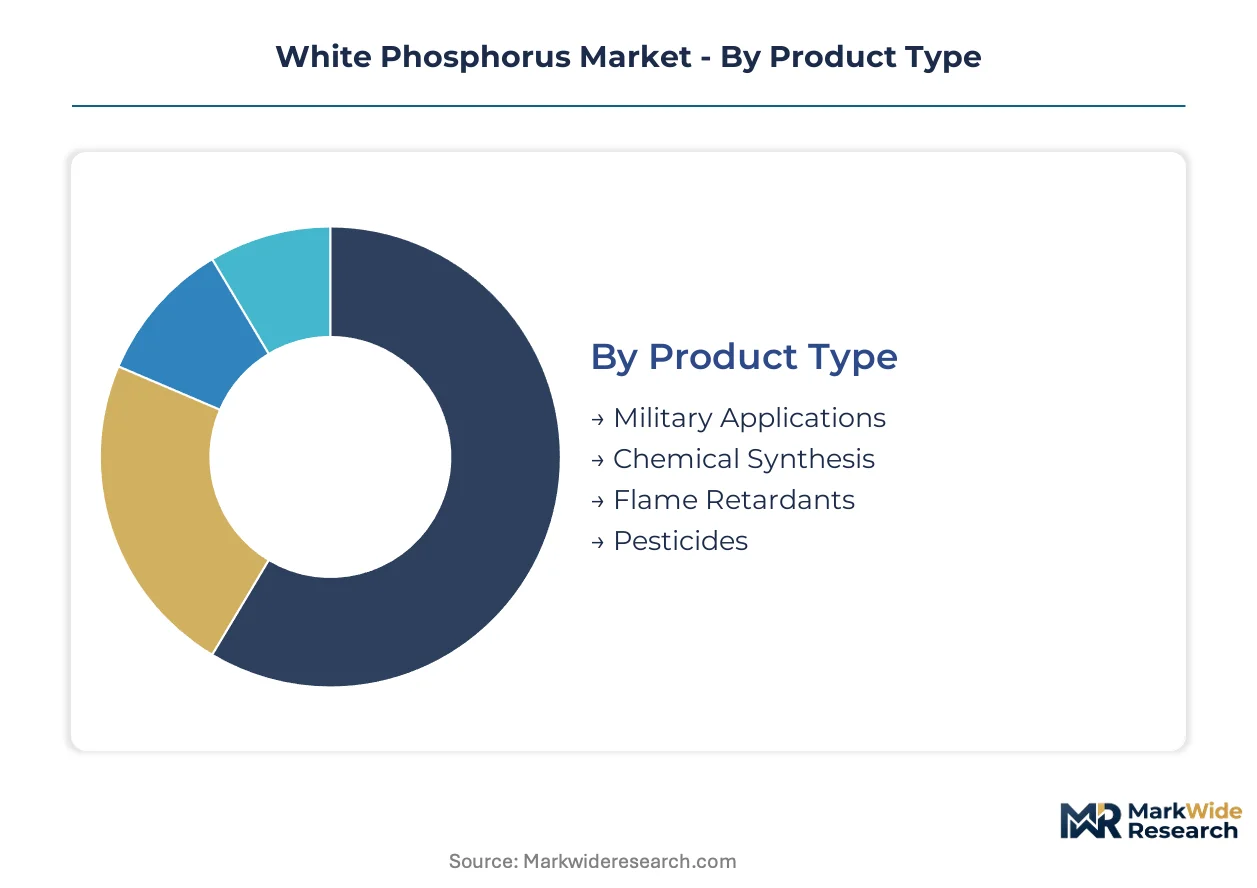
Understanding the White Phosphorus market through segmentation reveals distinct demand drivers and supply chain considerations for its various forms and applications. This granular analysis identifies specific value pools within a highly regulated chemical industry. Each segment reflects unique operational challenges and commercial opportunities.
Product Type:
The demand for white phosphorus often correlates with the life cycles and modernization requirements of its derivative products, influencing the pace of material upgrades.
- Chemical Synthesis:This segment represents the primary industrial purpose, serving as a key intermediate for high-purity phosphoric acid and other phosphorus compounds. It dominates consumption, driving demand from downstream specialty chemical manufacturers globally.
- Flame Retardants:Demand here is driven by the transition to halogen-free flame retardants in electronics and construction materials, propelled by regulations like the EU's RoHS directive. This application offers a significant value-added opportunity for phosphorus-based compounds.
- Military Applications:Used in incendiary devices and smoke screens, its supply is subject to stringent international controls by the OPCW.
- Pesticides:Organophosphate pesticides, derived from white phosphorus, support crop yield improvement initiatives in nations such as India and Brazil.
Chemical Synthesis sits at the top of the volume ranking, with Flame Retardants climbing the fastest.
End Use Industry:
End-use industries determine the specific purity and form requirements for white phosphorus derivatives, reflecting varied application demands across sectors.
- Chemicals:This segment encompasses the vast majority of white phosphorus consumption, as it serves as a foundational precursor for high-purity phosphoric acid and other industrial compounds. Demand originates from diverse specialty chemical manufacturers.
- Agriculture:Organophosphate pesticides, derived from white phosphorus, support crop yield improvement initiatives in nations like India and Brazil. Government policies promoting food security influence this sector's demand.
- Aerospace:Niche applications in specialized alloys or components for aerospace require extremely high-purity phosphorus derivatives for performance specifications.
- Pharmaceuticals:This sector uses white phosphorus for synthesizing specific drug intermediates, demanding stringent quality control and certification for end-products.
The Chemicals industry continues to represent the largest consumption base, while Agriculture exhibits consistent expansion driven by global food demand.
Form:
The physical form of white phosphorus significantly impacts its handling, storage, and transportation protocols, adding complexity to supply chain logistics.
- Crystalline:Elemental white phosphorus typically exists as a soft, waxy solid with a tetrahedral P4 molecular structure, requiring inert atmosphere storage due to high reactivity. This form is the direct output from the electrothermal furnace process.
- Liquid:While solid at room temperature, white phosphorus is often handled and transported under water or in molten form to mitigate its extreme reactivity and spontaneous combustion risks. This state facilitates continuous industrial processing.
- Granular:This form offers easier handling and precise dosing in some industrial applications, but still requires inert conditions for safety protocols.
- Powder:Used in specialized chemical reactions where high surface area is critical, though its fine particulate nature increases reactivity hazards.
Crystalline white phosphorus forms the primary raw material, with Liquid forms facilitating safer industrial processing and transport.
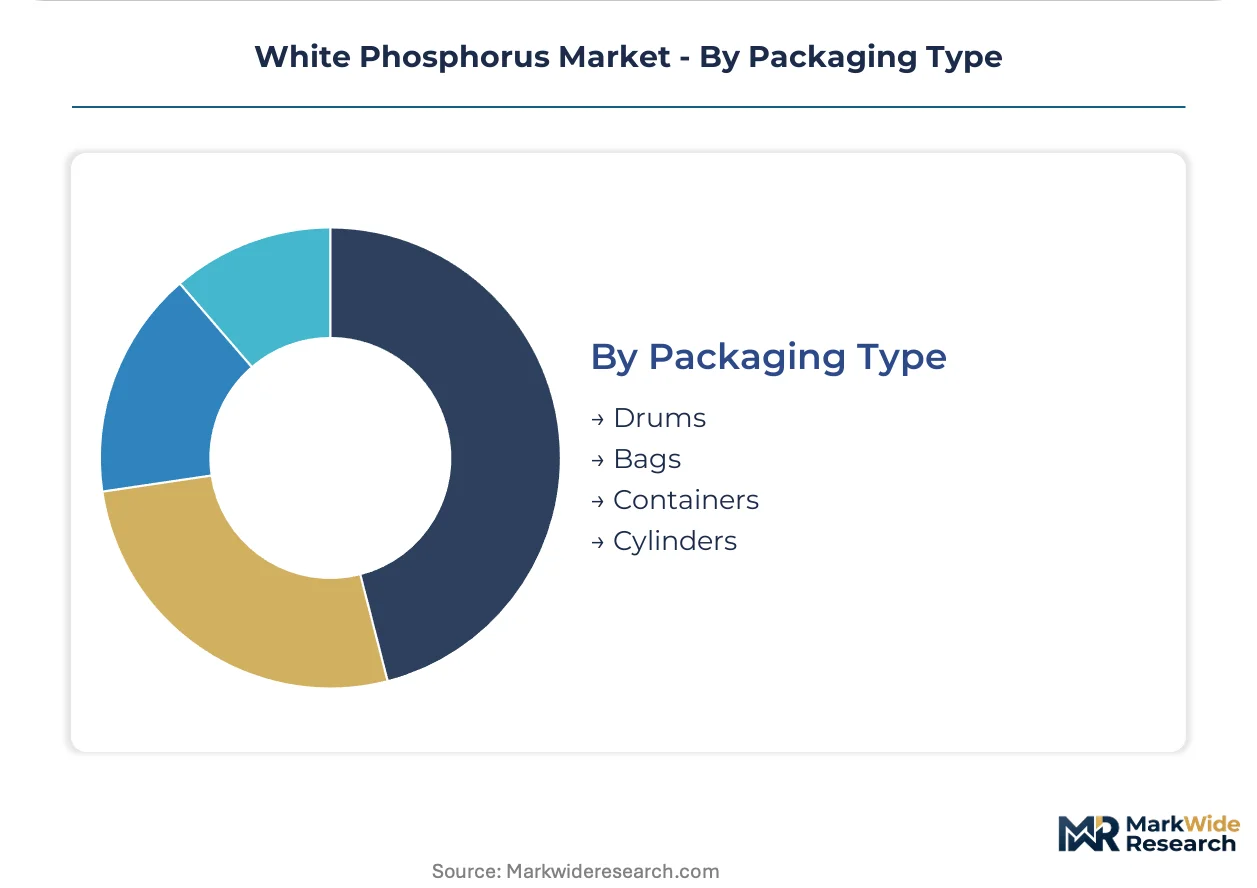
Packaging Type:
Packaging types for white phosphorus are primarily dictated by stringent safety regulations and international transport guidelines, minimizing environmental and handling risks.
- Drums:Steel drums filled with water are a standard packaging method for white phosphorus, ensuring its immersion and preventing exposure to air to avert spontaneous ignition. These are critical for smaller volume shipments.
- Containers:Specialized ISO tanks or larger intermodal containers are employed for bulk shipments of white phosphorus, often transporting it molten under inert gas or submerged in water. This method supports large-scale international logistics.
- Bags:Rarely used for elemental white phosphorus due to reactivity, specialized multi-layered and inert-filled bags are for derivative products.
- Cylinders:Associated with compressed gases, for white phosphorus this refers to specialized pressure vessels for very specific controlled applications or derivatives.
Drums are standard for regulated smaller shipments, while Containers manage the complexities of high-volume international transport.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global white phosphorus market exhibits diverse regional dynamics, with production heavily concentrated in Asia while demand drivers vary significantly across continents. Each region presents unique regulatory landscapes and industrial requirements for phosphorus derivatives.
China
China's vast production capacity drives global white phosphorus supply, largely supporting its domestic chemical synthesis and agrochemical industries. The Ministry of Ecology and Environment (MEE) enforces strict emissions controls, influencing operational costs and capacity utilization. Yunnan province, with its abundant phosphate rock resources and energy infrastructure, remains the primary production hub.
India
India's agricultural modernization initiatives fuel consistent demand for organophosphate pesticides, leveraging white phosphorus as a critical precursor. The country's central and state environmental bodies implement regulations on chemical manufacturing and distribution. Mumbai and Gujarat are significant centers for chemical and agrochemical production, driving regional consumption.
United States
The United States sees strong demand for high-purity phosphoric acid derivatives, particularly from its semiconductor and specialty battery industries. The US Environmental Protection Agency (EPA) oversees stringent regulations on chemical production emissions and hazardous material transport. Chemical clusters in Texas and Louisiana utilize white phosphorus for advanced materials manufacturing.
Germany
Germany's sophisticated specialty chemicals sector demands white phosphorus for advanced flame retardants and high-performance polymers. The EU's REACH regulation dictates rigorous data submission and risk assessment for all chemical imports and production. Industrial regions like North Rhine-Westphalia and Bavaria are key consumers for phosphorus-based compounds.
Japan
Japan's electronics and advanced materials industries require ultra-high-purity phosphorus compounds for specialized applications. The Ministry of Economy, Trade and Industry (METI) promotes stringent quality standards and environmental compliance for chemical manufacturers. Osaka and Tokyo Bay areas host numerous electronics and chemical companies utilizing white phosphorus derivatives.
White Phosphorus Market Key Industry Players
Top-tier vendors anchor the global white phosphorus market, while a fragmented base of regional specialists and downstream derivative producers also contributes. The market structure features a few large-scale integrated producers alongside numerous smaller, niche players. Strategic archetypes include resource-backed giants, pure-play derivative manufacturers, and specialized chemical synthesis providers. Dominant competitive moves involve capacity expansion and strategic partnerships to secure raw material access or expand downstream product portfolios.
Among Chinese producers, Yunnan Phosphorus Group Company Limited and Hubei Xingfa Chemicals Group exemplify the scale-driven, vertically integrated model, leveraging significant control over phosphate rock resources. These entities primarily focus on bulk white phosphorus and its foundational derivatives, influencing regional supply dynamics in Asia. Excel Industries Limited, based in India, represents a downstream specialist, concentrating on phosphorus derivatives like pesticides for its domestic market. These companies collectively demonstrate the varied approaches to value creation within the white phosphorus industry.
| Leading Market Players |
|---|
| Yunnan Phosphorus Group Company Limited |
| Sichuan Chuantou Chemical Industry Group Company Ltd. |
| Guizhou Qianneng Tianhe Phosphate |
| Hubei Xingfa Chemicals Group |
| Viet Hong Chemical and Trading Company Limited |
| Excel Industries Limited |
| Nippon Chemical |
| Chongqing Chuandong Chemical |
| Guizhou Sino-Phos Chemical |
| Others |
Cost & Logistics Intelligence
The EU's REACH regulation extensively gates qualified white phosphorus supply, directly influencing premium-tier pricing access for compliant materials. This regulatory framework adds compliance costs across the value chain.
Pricing Analysis
Capacity additions in China are reshaping price floors for bulk white phosphorus, particularly from Yunnan province. Commodity spot pricing dominates for bulk material, alongside contract-based long-term offtake agreements. High-purity grade certification and documented provenance drive price differentiation in regulated markets. Energy cost volatility in key production regions like China exerts upward pressure on base prices, impacting agrochemical buyers who are more price-sensitive than electronics firms seeking ultra-high-purity material.
Supply Chain Analysis
Specialized talent availability in China and India is critical for optimizing white phosphorus production processes. China dominates global production, with India and Japan contributing to derivative manufacturing. The industry relies on phosphate rock and electricity as primary inputs, creating single-source vulnerability due to heavy Chinese concentration. Distribution runs through specialized chemical distributors and direct sales to large industrial consumers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The white phosphorus market represents a late-cycle quality story, driven by a significant demand-shift towards ultra-high-purity phosphorus compounds. This shift is particularly evident in the semiconductor and specialty battery industries.
For Market Incumbents:To counter the threat of single-source supply vulnerability from China, incumbents must diversify their raw material sourcing strategy. Investing in modular production technologies for high-purity phosphoric acid can decentralize intermediate synthesis. Strategic partnerships for downstream derivative expansion in Southeast Asia will capture regional value. Enhancing purity grade certification processes also strengthens market position against emerging competitors.
For New Entrants and Emerging Players:Blockchain-enabled traceability platforms offer a digital-channel route for new entrants to differentiate their white phosphorus offerings. Target the underpenetrated specialty battery material development segment with innovative phosphorus-based compounds. Focus on advanced flame retardants for electronics, a market valuing documented provenance and certified purity. A go-to-market angle emphasizing comprehensive data packages ensures supply chain integrity for regulated buyers.
For Investors and Strategic Acquirers:Roll-up economics work for mid-sized specialty chemical producers because stringent environmental regulations create barriers to entry for smaller players. The market offers stable long-term returns given its critical role in high-growth industries like semiconductors and batteries. Target vertically integrated firms with control over phosphate rock resources or advanced derivative capabilities. Increased M&A activity in Southeast Asian downstream processing is a key signal to watch for market consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | In China, capacity expansion by Hubei Xingfa Chemicals Group secures bulk supply. |
| Backward Integration | Yunnan Phosphorus Group Company Limited deepens control over phosphate rock resources. |
| Green Manufacturing Transition | Investment in cleaner electrothermal furnace technologies addresses China's MEE regulations. |
| Long-term Supply Agreement | Securing supply for high-purity phosphoric acid users in the US semiconductor industry. |
| Joint Venture | Partnering for advanced flame retardant production in Germany supports EU RoHS compliance. |
Research Approach
Multiple input streams — industry association reports, corporate financial statements, and academic research — were reconciled to build a comprehensive market view. Primary interviews with plant managers, procurement leads at downstream OEMs, and technical R&D directors provided critical insights. This primary data validated secondary sources like customs/trade data and SEC 10-K filings. A rigorous bottom-up and top-down triangulation approach ensured data consistency.
Data-stream reconciliation established the analytical framework across the modeling period. The market was modeled by product type, end-use industry, packaging format, and regional production hub. Compound annual growth rates were derived from historical trends and projected demand shifts in downstream applications. Key forecast inputs included energy price projections and new regulatory compliance costs impacting production economics.
The model assumes a particular technology adoption path; alternative pathways for phosphorus-based battery materials would alter the outlook. Forecasts reflect assumptions regarding regulatory stability and raw material availability. Material deviation in these named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Indonesia Nitric Acid Market
Chemicals
Global Monochloroacetic Acid Market
Chemicals
p-Coumaric Acid Market
Chemicals
Insect Repellent Active Ingredients Market
Chemicals
Carbon Tetrabromide Market
Chemicals
Sulfuric Acid Market
Chemicals
Hydrophobing Agents Market
Chemicals
Triethanolamine Market
Chemicals
Cummene Derivatives Market
Chemicals
Thiourea Market
Chemicals
Iso Nonanol Market
Chemicals
Global Glycine Market
Chemicals
Ethanolamine Market
Chemicals
Guanidine Carbonate Market
Chemicals
Vinyl Acetate Market