
 Stimulation Materials Market | 2026-2036
Stimulation Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Stimulation Materials Market Intelligence
North American proppant capacity is narrowing as domestic sand mining expands across Wisconsin and Texas deposits. Halliburton leverages integrated logistics networks to control last-mile delivery costs into Permian and Appalachian basins. Schlumberger anchors its position through R&D intensity in resin-coated proppant formulations. Baker Hughes differentiates via ceramic proppant technology leadership in high-closure-stress well environments.
Stimulation materials encompass engineered proppants, chemical additives, and diverting agents used to sustain fracture conductivity in hydrocarbon-bearing formations. Frac sand specifications typically require 99% quartz content with sphericity exceeding 0.6 and acid solubility below 2% to prevent formation damage under reservoir conditions. Biopolymer-based friction reducers are capturing share from synthetic guar derivatives as operators prioritize biodegradability in flowback fluid management. Composite proppants command premium positioning in deep-basin applications where crush resistance above 10,000 psi preserves fracture width under overburden pressure.
EPA effluent limitation guidelines shape water recycling mandates that alter chemical additive selection across US shale plays. OSHA permissible exposure limits for respirable crystalline silica force mining operators to implement wet suppression systems and enclosed conveyor infrastructure. The analysis indicates stakeholders must monitor evolving state-level seismicity protocols that restrict injection rates and proppant loading in seismically active basins.
Market Dynamics
Proppant specification divergence between Permian Basin operators and Appalachian shale developers is fragmenting procurement standards across North American unconventional plays. This technical bifurcation forces suppliers to maintain dual product lines while absorbing compliance costs from diverging state-level frac fluid disclosure mandates.
Growth Catalysts
- OSHA Silica Rule Enforcement:Tighter respirable crystalline silica exposure limits are accelerating wet suppression system deployments at Wisconsin and Texas sand mining operations, expanding addressable equipment market for dust control technologies.
- Texas Railroad Commission Seismic Protocols:Injection rate restrictions in seismically active Permian sub-basins are driving demand for engineered diversion systems that maintain fracture complexity at reduced pumping pressures.
- Resin-Coated Proppant Thermal Stability:Deep-basin operators in the Delaware sub-basin require proppant formulations that preserve pack conductivity above 350°F reservoir temperatures, pulling premium product development.
Market Restraints
- Natural Gas Price Volatility:Henry Hub pricing below breakeven thresholds for dry gas windows suppresses completion activity in Marcellus and Utica formations, idling regional sand demand.
- Midstream Water Handling Bottlenecks:Insufficient produced water pipeline infrastructure in the Permian constrains recycled water utilization rates, limiting biopolymer friction reducer adoption despite EPA effluent guidelines.
- Ceramic Proppant Import Dependency:High-purity bauxite sourcing concentrates among Chinese refractory suppliers, exposing US ceramic proppant manufacturers to SAMR export license unpredictability.
Strategic Opportunities
- Appalachian Basin Recompletions:Mature Marcellus horizontals reaching production decline inflection points create demand for refracturing campaigns using higher-strength proppant to restore fracture conductivity in stress-shadowed zones.
- Carbon-Negative Proppant Feedstocks:CO2-cured geopolymers from industrial waste streams align with EPA greenhouse gas reporting requirements for Scope 3 emissions disclosure in operator supply chains.
- Last-Mile Rail-to-Truck Transloading:Unit train terminals in the Permian with direct wellsite trucking networks collapse delivered sand costs for operators beyond 75-mile radii from traditional mine loadouts.
Industry Challenges
- Frac Engineer Talent Pipeline:Petroleum engineering program enrollment declines at Texas and Oklahoma universities constrain operator capacity to optimize proppant loading designs for complex zipper-frac sequences.
- API/ISO Proppant Testing Harmonization:Divergent crush resistance measurement protocols between API RP 19C and ISO 13503-2 create certification duplication costs for suppliers serving both North American and Middle Eastern markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stimulation Materials Market |
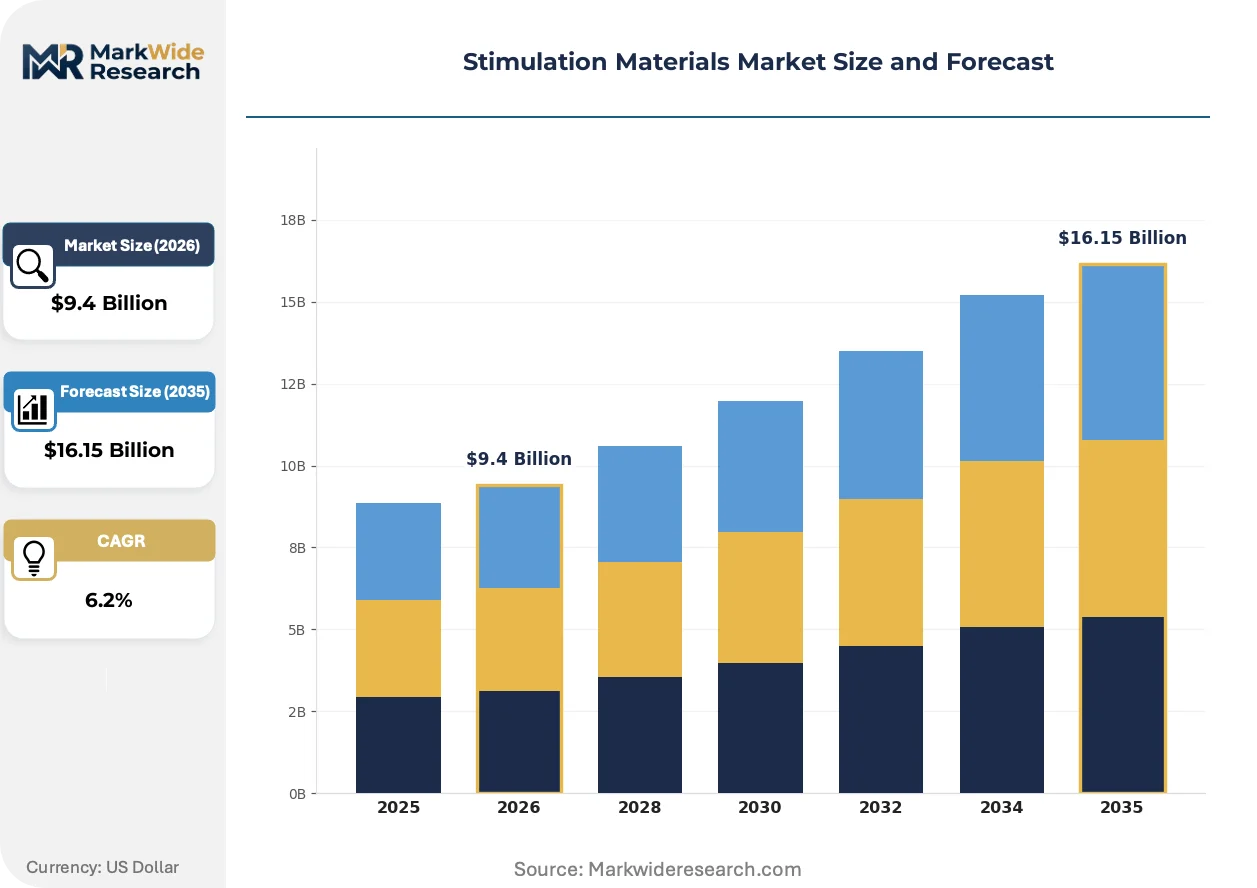
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.15 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Biopolymer, Metal, Composite, Glass Application: Medical Devices, Aerospace Components, Automotive Parts, Electronics End User: Manufacturers, Healthcare Providers, Research Institutions, Aerospace Firms Form Factor: Sheet, Rod, Tube, Granule |
| Companies Covered | Halliburton, Schlumberger, Baker Hughes, Ecolab (Nalco), Chevron Phillips Chemicals, Weatherford International, Carbo Ceramics, FMC Corporation, Badger Mining Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stimulation Materials Market Strategic Shifts & Innovations
Material science advances and regulatory pressure on flowback fluid chemistry are converging to reshape proppant selection criteria and additive formulation priorities across unconventional basins.
Ultra-lightweight proppants manufactured from high-strength ceramic microspheres are collapsing conventional density-performance tradeoffs that previously forced operators to choose between transport efficiency and crush resistance. Bakken and Powder River Basin operators are adopting these materials for extended-reach laterals where proppant settling in low-viscosity slickwater systems previously caused screenout failures. The technology is collapsing the addressable market for intermediate-strength bauxite proppants in 8,000-10,000 psi closure stress applications.
EPA effluent limitation guidelines under the Clean Water Act are forcing operators to document chemical additive toxicity profiles in produced water discharge permits. This regulatory friction is accelerating substitution of synthetic guar-based friction reducers with modified cellulose and biopolymer alternatives that meet biodegradability thresholds for surface water release. Appalachian operators with limited deep-well injection capacity are most exposed, driving formulation partnerships between chemical suppliers and regional water treatment providers.
Integrated proppant procurement platforms linking mine loadouts directly to operator wellsite inventories are compressing traditional distributor markups in the Permian and Eagle Ford. These digital procurement systems aggregate real-time consumption data across multi-well pads, enabling just-in-time delivery scheduling that reduces working capital requirements for exploration and production companies. The model is most advanced among Permian independents with concentrated acreage positions and predictable drilling calendars.
Stimulation Materials Market Segmentation
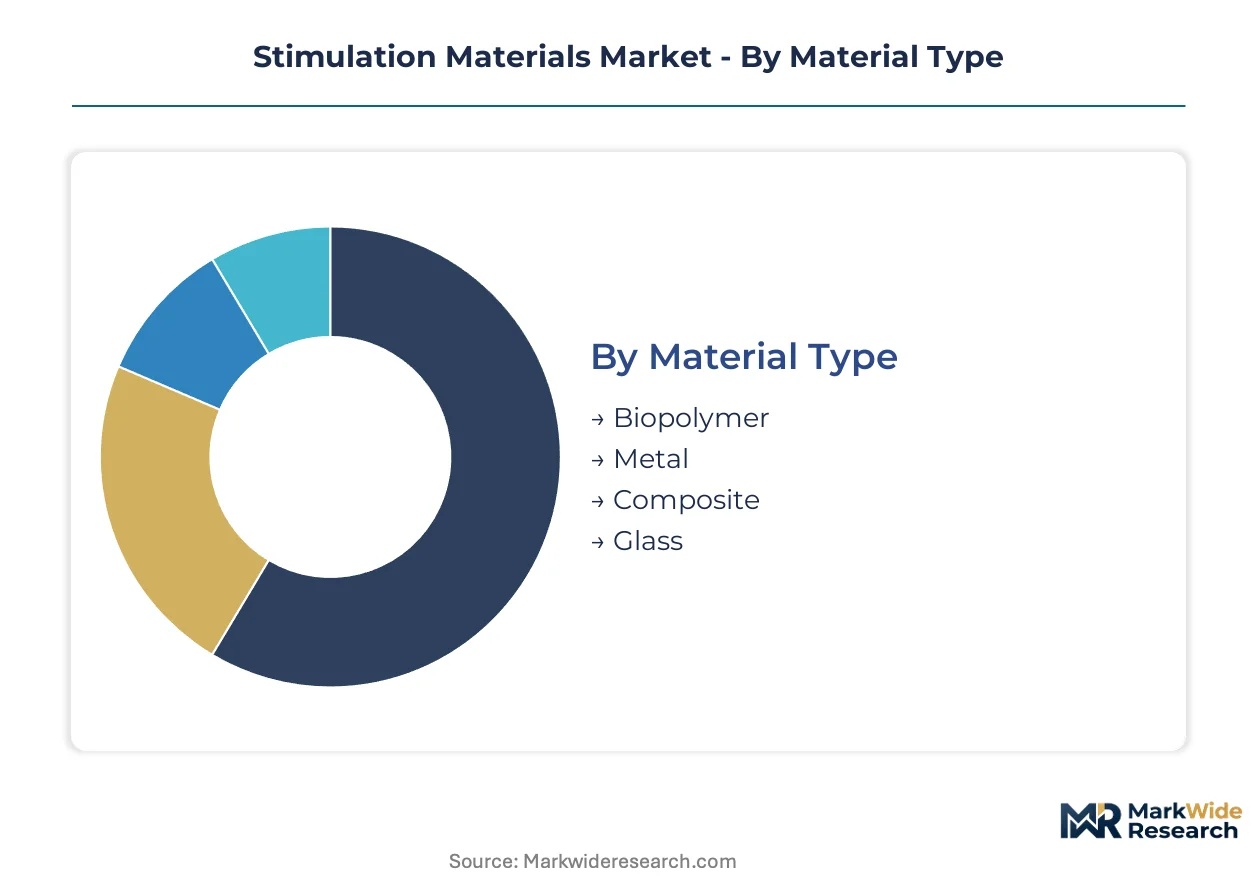
Stimulation materials span divergent performance requirements across hydraulic fracturing, medical intervention, and industrial processing applications. Segmentation reveals how material specifications, delivery formats, and end-use constraints fragment procurement patterns and supplier specialization strategies.
Material Type:
Proppant and additive chemistry spans natural, synthetic, and engineered substrates with distinct crush resistance, thermal stability, and biodegradability profiles.
- Biopolymer:Modified cellulose and guar derivatives serve as friction reducers in slickwater fracturing fluids. Appalachian operators with limited deep-well injection capacity prioritize these formulations for EPA-compliant surface water discharge in the Marcellus shale.
- Metal:High-strength bauxite and alumina-based ceramic proppants withstand closure stresses above 10,000 psi in Delaware sub-basin deep wells. Chinese SAMR export licensing unpredictability constrains US manufacturer feedstock security.
- Composite:Resin-coated sand bonds under reservoir temperature to prevent proppant flowback in high-rate gas wells.
- Glass:Hollow glass microspheres reduce slurry density for extended-reach lateral applications.
The dominant share belongs to Biopolymer, while Metal is closing the gap fastest.
Application:
End-use environments dictate material certification, sterilization compatibility, and mechanical loading specifications.
- Medical Devices:Bioresorbable stimulation materials enable controlled drug release and tissue scaffolding with FDA 510(k) pathway requirements.
- Aerospace Components:Lightweight composite formulations reduce structural mass while maintaining fatigue resistance under cyclic loading.
- Automotive Parts:Metal and glass-reinforced polymers absorb vibration in powertrain assemblies.
- Electronics:Thermally conductive composites dissipate heat in semiconductor packaging.
Medical Devices commands the largest revenue pool, though Aerospace Components exhibits the steepest expansion trajectory.
End User:
Procurement scale and technical specification authority vary sharply across organizational types.
- Manufacturers:Tier-1 suppliers integrate stimulation materials into finished assemblies with just-in-time inventory requirements.
- Healthcare Providers:Hospital systems and surgical centers demand lot-traceable biopolymers with sterilization validation.
- Research Institutions:Academic and government laboratories drive novel formulation development through SBIR-funded partnerships.
- Aerospace Firms:Prime contractors impose AS9100 quality system mandates on material suppliers.
Manufacturers retain the dominant procurement volume, while Research Institutions are gaining share fastest through federal advanced materials initiatives.
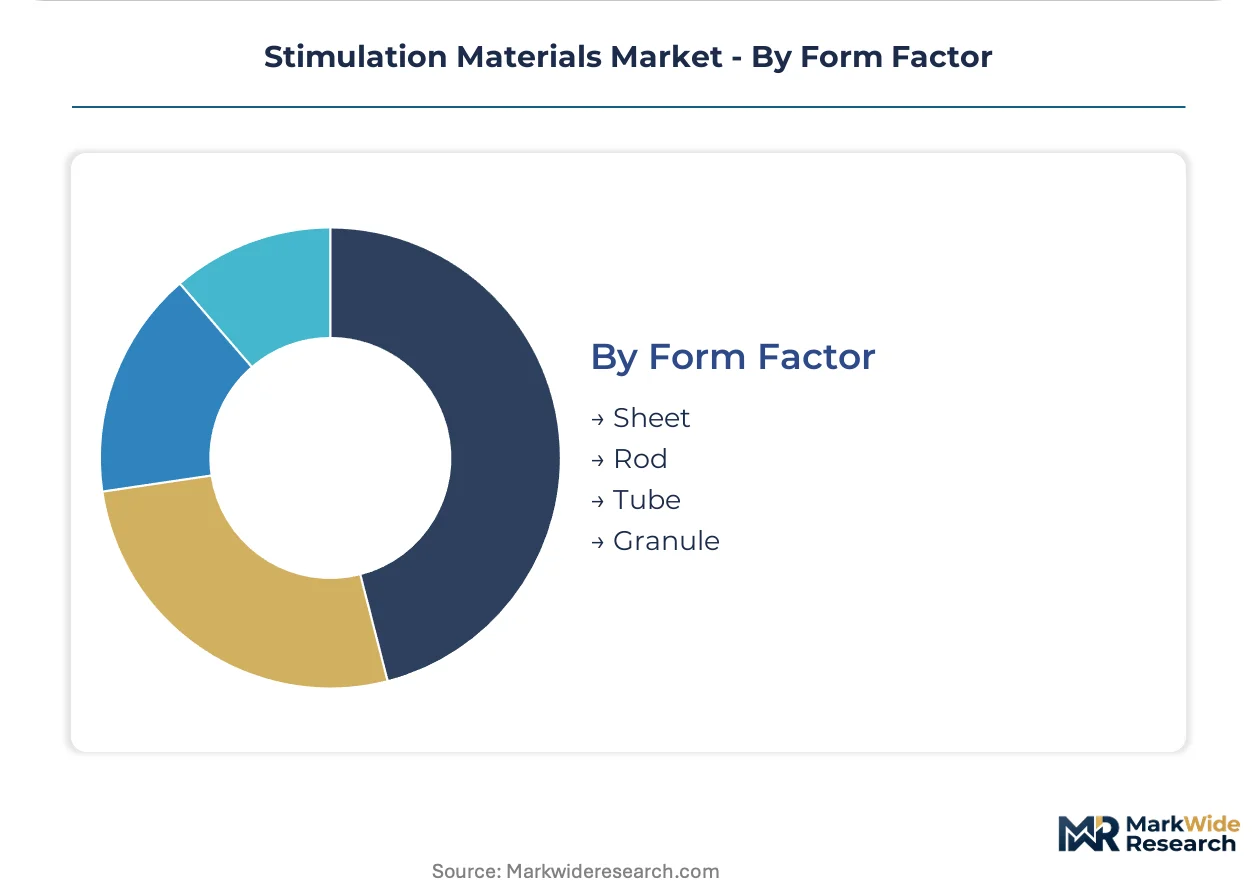
Form Factor:
Physical geometry determines handling infrastructure, dosing precision, and integration method across downstream processes.
- Sheet:Roll-fed formats enable continuous lamination in automotive and electronics manufacturing lines.
- Rod:Extruded profiles suit machining operations for medical instrument shafts and aerospace fasteners.
- Tube:Hollow cylindrical geometries serve as catheter substrates and fluid delivery conduits.
- Granule:Free-flowing proppant sizing through 20/40 and 40/70 mesh specifications dominates Permian Basin well completions.
Granule holds the dominant position, while Tube is expanding most quickly through minimally invasive surgical device demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frac sand mining concentrates in Wisconsin and Texas deposits, while ceramic proppant feedstock sourcing faces Chinese export licensing exposure. Regional demand patterns diverge sharply between Permian Basin oil operators and Appalachian gas producers.
United States
Permian Basin operators in Texas and New Mexico consume 60% of domestic frac sand volumes for unconventional well completions. EPA effluent limitation guidelines under the Clean Water Act mandate chemical additive toxicity documentation in produced water discharge permits. Midland-Odessa logistics clusters anchor last-mile rail-to-truck transloading infrastructure that collapses delivered sand costs for operators beyond 75-mile mine radii.
Canada
Montney and Duvernay formation operators in Alberta and British Columbia drive ceramic proppant demand for high-closure-stress deep gas wells. Health Canada and PMRA regulate chemical additive environmental release through the New Substances Notification program. Calgary-based procurement offices coordinate cross-border supply chains linking US Midwest sand mines to Western Canadian Sedimentary Basin well sites.
China
Domestic shale gas development in Sichuan-Chongqing basin regions consumes locally manufactured ceramic proppants from high-purity bauxite processing. SAMR export licensing unpredictability constrains US manufacturer feedstock security for refractory-grade alumina. Zhengzhou and Zibo industrial clusters host integrated proppant production facilities serving both domestic operators and export markets.
Saudi Arabia
Unconventional gas development in Jafurah basin formations drives demand for high-strength proppant formulations in high-temperature carbonate reservoirs. The national oil company mandates local content requirements that stimulate domestic manufacturing partnerships with international suppliers. Eastern Province industrial zones near Jubail host emerging proppant coating and logistics facilities.
Australia
Coal seam gas operators in Queensland and New South Wales utilize fine-mesh sand proppants for shallow unconventional completions in Surat and Bowen basins. The country's national environmental regulator enforces water management protocols that restrict flowback fluid disposal and stimulate chemical additive substitution. Brisbane and Toowoomba service clusters coordinate procurement for Cooper Basin tight gas developments.
Stimulation Materials Market Key Industry Players
Integrated oilfield service conglomerates and specialized proppant manufacturers split the market into distinct competitive spheres. Three archetypes dominate: full-service providers with captive logistics networks, technology-focused specialists in engineered proppant formulations, and regional sand mining operators with mine-mouth cost advantages. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure feedstock access and basin-specific distribution rights.
Within the integrated service tier, Halliburton and Schlumberger exemplify archetypes combining proppant supply with pumping services and logistics coordination. Baker Hughes occupies a position emphasizing technology differentiation in high-stress well environments. These three anchors demonstrate how service integration and material science specialization create divergent paths to basin-level competitiveness.
| Leading Market Players |
|---|
| Halliburton |
| Schlumberger |
| Baker Hughes |
| Ecolab (Nalco) |
| Chevron Phillips Chemicals |
| Weatherford International |
| Carbo Ceramics |
| FMC Corporation |
| Badger Mining Corporation |
| Others |
Cost & Logistics Intelligence
Union Pacific rail corridors linking Wisconsin sand mines to Permian Basin transload terminals compress logistics costs while amplifying price differentiation between mine-mouth and delivered proppant tiers. This freight-cost wedge widens procurement spreads for operators beyond 75-mile mine radii, concentrating supply power among integrated logistics operators.
Pricing Analysis
OSHA silica exposure rules dictate the pricing tier structure across frac sand procurement, separating wet-processed premium grades from dry-mined economy volumes. Three-tier pricing stratifies across resin-coated ceramic, Northern White sand, and regional brown sand categories. Cost compression in economy-tier volumes intensifies because of mine-mouth oversupply in Texas deposits. Dry gas operators in the Marcellus exhibit highest price sensitivity, while Delaware sub-basin deep-well specialists absorb premium ceramic premiums without volume elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk for ceramic proppant feedstock security. High-purity bauxite concentrates in Chinese Zhengzhou and Zibo processing clusters, while Wisconsin and Texas anchor natural sand supply. Refractory-grade alumina sourcing rests on SAMR export licensing unpredictability. Unit train-to-truck transloading networks in Midland-Odessa collapse last-mile delivery costs for Permian operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon-negative proppant substitutes threaten incumbent positioning as EPA Scope 3 disclosure mandates harden supply chain accountability. Incumbents must navigate this substitution defense while preserving fracture conductivity performance premiums.
For Market Incumbents: Harden feedstock security through backward integration into Wisconsin sand mining or captive bauxite offtake agreements with Australian suppliers. Resin-coated proppant R&D intensity must accelerate to outpace CO2-cured geopolymer substitutes threatening premium positioning in deep-basin applications. Wet suppression system deployment at Texas mine sites defuses OSHA enforcement risk before penalty exposure accumulates. For New Entrants and Emerging Players: Appalachian Basin recompletion campaigns represent the most penetrable entry point for higher-strength proppant specialists targeting stress-shadowed fracture restoration. Marcellus operators with limited deep-well injection capacity prioritize EPA-compliant biopolymer friction reducers, opening formulation partnerships for regional chemical suppliers. Direct-to-operator digital procurement platforms bypass established distributor markups in concentrated acreage positions. For Investors and Strategic Acquirers: Regional sand mining operators with rail-served loadouts and transloading infrastructure command premium acquisition multiples. Long-term viability hinges on water recycling technology integration as produced water pipeline bottlenecks constrain biopolymer adoption despite regulatory tailwinds. Monitor Texas Railroad Commission seismic protocol expansion as the inflection signal for diversion system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sand Mining | Wisconsin mine acquisitions secure Northern White feedstock for Permian delivery contracts. |
| Resin-Coated Proppant R&D Expansion | Thermal stability above 350°F preserves conductivity premiums in Delaware sub-basin deep wells. |
| Wet Suppression System Deployment | OSHA silica compliance defuses enforcement risk across Texas and Wisconsin mining operations. |
| Digital Procurement Platform Launch | Direct mine-to-wellsite scheduling collapses working capital requirements for Permian independents. |
| Carbon-Negative Geopolymer Development | CO2-cured industrial waste formulations align with EPA Scope 3 supply chain disclosure mandates. |
Research Approach
Operator-level perspectives from frac engineers, sand mine operations managers, chemical procurement leads, and rail logistics coordinators anchored the qualitative base. Primary interviews combined with secondary validation from EPA effluent limitation guidelines, OSHA enforcement bulletins, Texas Railroad Commission seismic protocols, and SEC 10-K filings from integrated service providers. Bottom-up well completion counts and top-down basin-level proppant demand estimates underwent triangulation.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeled across material type, application environment, closure stress tier, and regional regulatory cluster. CAGRs derived from unit economics analysis of proppant loading designs and well completion intensity by basin. Forecast inputs incorporated frac sand mesh specification trends and ceramic proppant thermal stability thresholds.
Practitioners should monitor Henry Hub price volatility, SAMR export license unpredictability, and state-level seismic protocol expansion for early signals of forecast revision. Forecasts reflect assumptions about unconventional drilling activity persistence and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Tetrapotassium Pyrophosphate Market
Chemicals
Europe Textile Chemicals Market
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Hypophosphorous Acid Market
Chemicals
Middle East Construction Chemicals Market
Chemicals
Desalination Chemicals Market
Chemicals
Global Glycol Ether Market
Chemicals
Diethyl Sulfate Market
Chemicals
Methidathion (CAS 950-37-8) Market
Chemicals
Chromium Trioxide Market
Chemicals
Global Benzalkonium Chloride Market
Chemicals
Barbituric Acid Market
Chemicals
Methyl Ethyl Ketone Peroxide (MEKP) Market
Chemicals
Photographic Chemicals Market
Chemicals
Bakers Ammonia Market