
 Industrial Hydrofluoric Acid Market | 2026-2036
Industrial Hydrofluoric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Hydrofluoric Acid Market Analysis
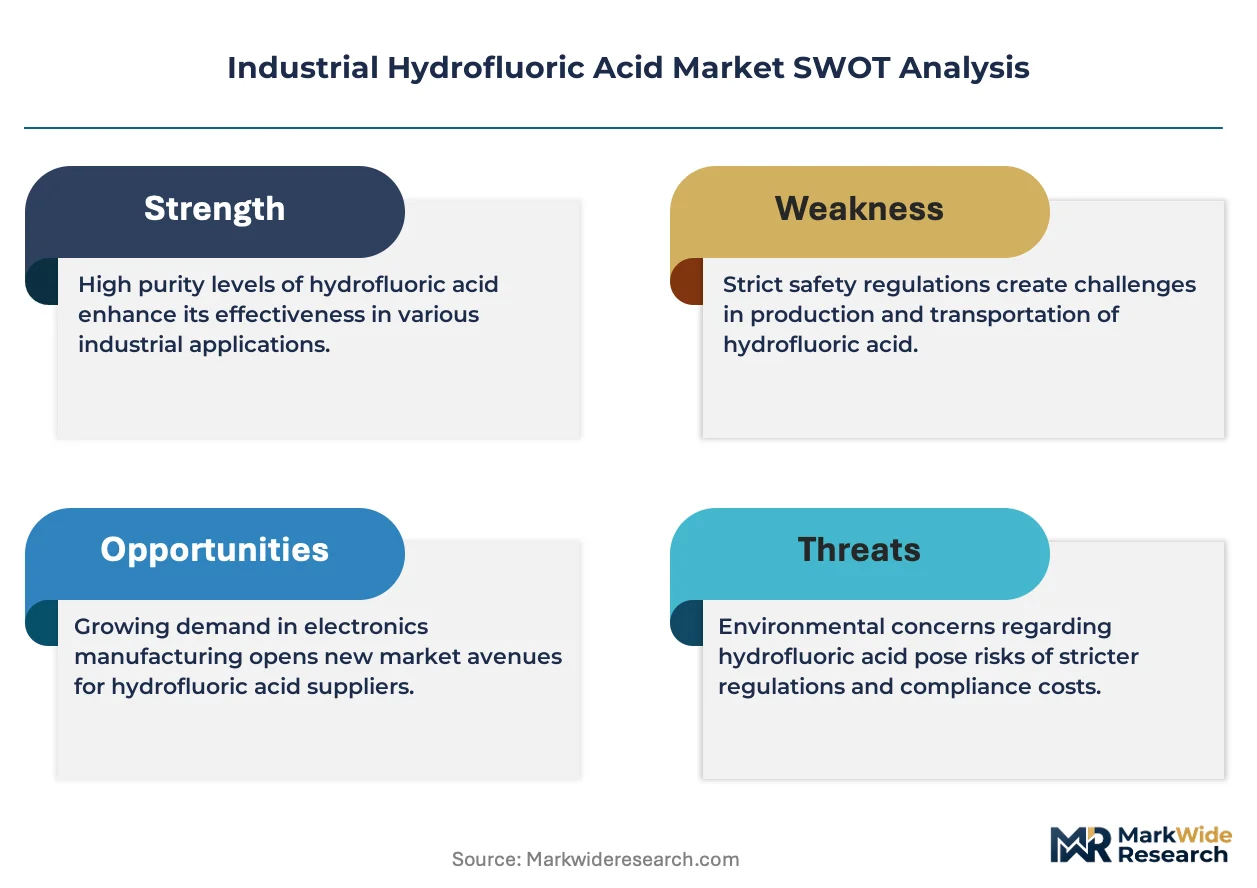
Buyer concentration in electronics is decoupling from traditional chemical manufacturing offtake as semiconductor foundries diversify supply sources. Honeywell International Inc. leverages captive fluorite reserves to sustain vertical integration across the value chain. Solvay anchors European supply through specialized anhydrous production at its Tarragona complex. Dongyue Group dominates Chinese domestic flows with integrated chlor-alkali and fluorochemical operations.
Industrial hydrofluoric acid is an aqueous or anhydrous solution of hydrogen fluoride, typically manufactured by reacting sulfuric acid with fluorite ore at temperatures exceeding 200 degrees Celsius, yielding concentrations from 49% to 70% for industrial use and higher purities for electronics. Its primary commercial purpose centers on fluorocarbon precursor synthesis, metal oxide dissolution, and silicon wafer surface conditioning in semiconductor fabrication. Aqueous hydrofluoric acid leads volume flows due to established metal processing and glass etching demand, while purified grades represent the fastest-expanding margin pool as chipmakers tighten contamination specifications. Fluorocarbon production remains the mature revenue anchor though regulatory pressure is shifting investment toward oil refining alkylation and specialty electronics chemicals.
The EPA governs hydrofluoric acid handling under Risk Management Plan requirements for threshold quantities, while OSHA mandates permissible exposure limits that shape workplace engineering controls and regional siting decisions. REACH and the EU F-Gas Regulation restrict certain fluorocarbon applications, redirecting European demand toward lower-GWP alternatives and non-fluorocarbon acid uses. China's MEE enforces emission standards around fluorochemical parks that concentrate compliant capacity. Stakeholders must monitor regulatory divergence between fluorocarbon phase-down timelines and semiconductor subsidy programs that pull in opposite directions on acid demand composition.
Market Dynamics
Semiconductor foundries in East Asia are pulling ultra-pure hydrofluoric acid volumes away from traditional fluorocarbon synthesis, fragmenting demand composition across the value chain.
Growth Catalysts
- EU F-Gas Regulation phase-down:The tightening fluorocarbon schedule redirects acid flows toward alkylation catalysts and specialty electronics chemicals, opening alternative revenue streams.
- Fluorochemical park clustering:China's eastern chemical corridor concentrates compliant capacity, lowering logistics costs and accelerating just-in-time delivery to wafer fabs.
- Silicon wafer surface conditioning:Advanced node fabrication below 7 nanometers consumes higher-purity grades per wafer, expanding margin pools for purification specialists.
Market Restraints
- Fluorite ore supply concentration:Mexican and Chinese deposits dominate global feedstock, exposing processors to export quota volatility and geopolitical friction.
- REACH authorization burdens:European downstream users face extended compliance timelines for certain fluorinated intermediates, delaying new product introductions.
- Sulfuric acid input cost spikes:Energy-intensive sulfuric acid production transmits volatility directly into hydrofluoric acid manufacturing economics.
Strategic Opportunities
- Alkylation catalyst substitution:US refineries seek alternatives to solid acid catalysts, creating inlet for anhydrous grades in fuel upgrading operations.
- Photovoltaic silicon etching:Solar cell manufacturers in Southeast Asia adopt wet chemical processing, generating parallel demand for lower-purity aqueous solutions.
- India's PLI scheme for semiconductors:Domestic fabrication subsidies will localize acid demand currently served by imports from China and Japan.
Industry Challenges
- Ultra-pure certification timelines:SEMI standards for parts-per-trillion metal specifications require 18-24 month qualification cycles with individual foundries.
- Fluorine chemist scarcity:Specialized handling expertise for anhydrous systems remains concentrated among legacy operators, constraining capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Hydrofluoric Acid Market |
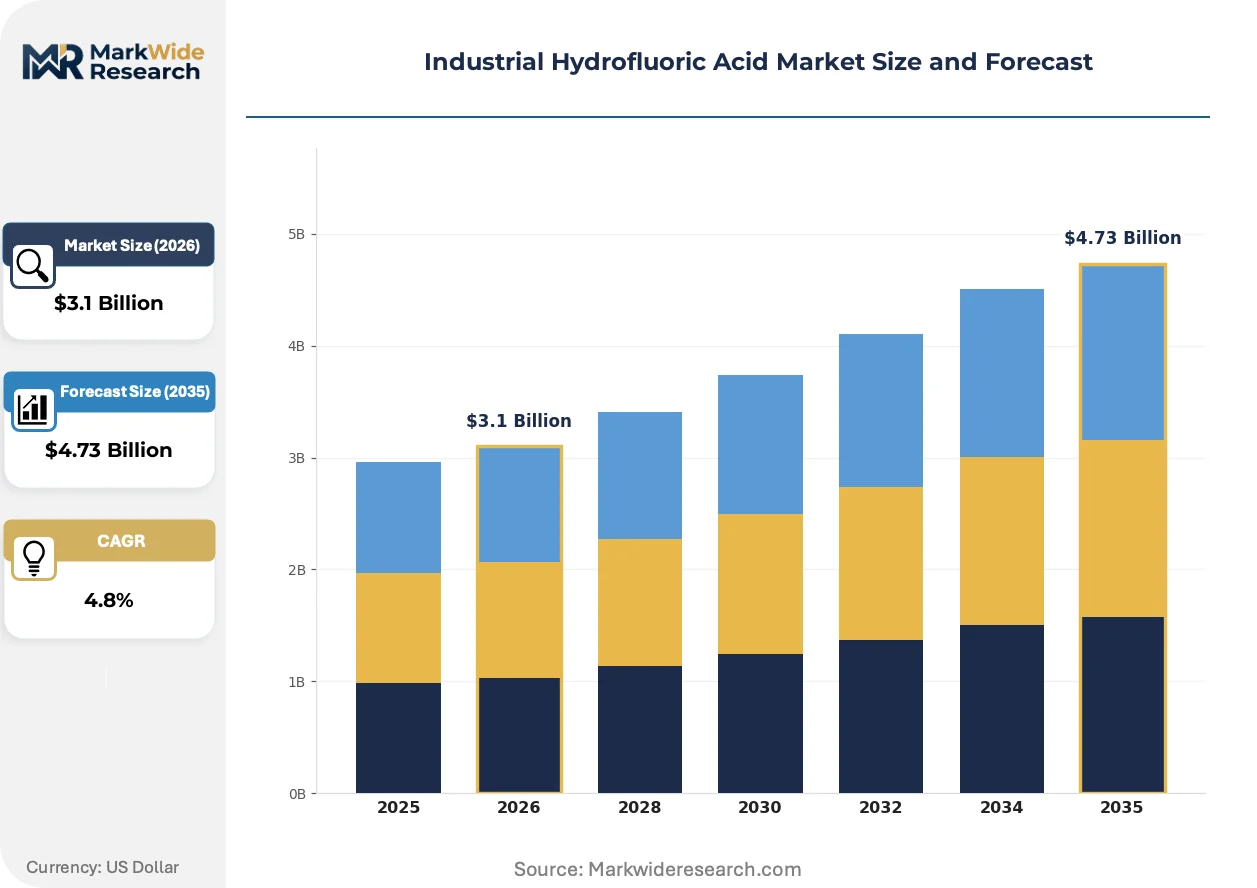
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.73 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous Hydrofluoric Acid, Aqueous Hydrofluoric Acid, Stabilized Hydrofluoric Acid, Purified Hydrofluoric Acid End User: Chemical Manufacturing, Metal Processing, Electronics, Glass Etching Application: Fluorocarbon Production, Metal Cleaning, Surface Treatment, Oil Refining Packaging Type: Drums, Cylinders, IBC Totes, Buckets |
| Companies Covered | Honeywell International Inc., Solvay, Stella Chemifa Corporation, LANXESS, Daikin, Dongyue Group, Sinochem, Zhejiang Kaisn Fluorochemical Co., Ltd., Koura Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Hydrofluoric Acid Market Emerging Trajectories
Point-of-use purification systems are compressing traditional supply chains, while regulatory phase-downs and buyer consolidation are rewriting competitive requirements.
Membrane-based fluoride recovery from spent etching baths is decentralizing acid regeneration. Semiconductor fabs in Taiwan and South Korea now capture 40-60 percent of spent material for on-site reprocessing. This technology is decentralizing the historical dominance of centralized chemical suppliers in high-volume electronics corridors.
REACH restrictions on per- and polyfluoroalkyl substances are tightening precursor availability for certain fluorocarbon categories. European formulators face reformulation mandates that redirect acid consumption toward non-fluorinated alternatives. Electronics-grade producers with existing purification infrastructure are capturing displaced volume from commodity fluorocarbon synthesis.
Long-term supply agreements now embed price-adjustment clauses tied to fluorite ore indices rather than fixed formulas. Korean and Japanese chipmakers are consolidating purchase volumes through nominated distributors, compressing spot market liquidity. This contractual evolution is most pronounced in the Yangtze River Delta, where foundry concentration enables buyer-led standardization of purity specifications.
Industrial Hydrofluoric Acid Market Segmentation
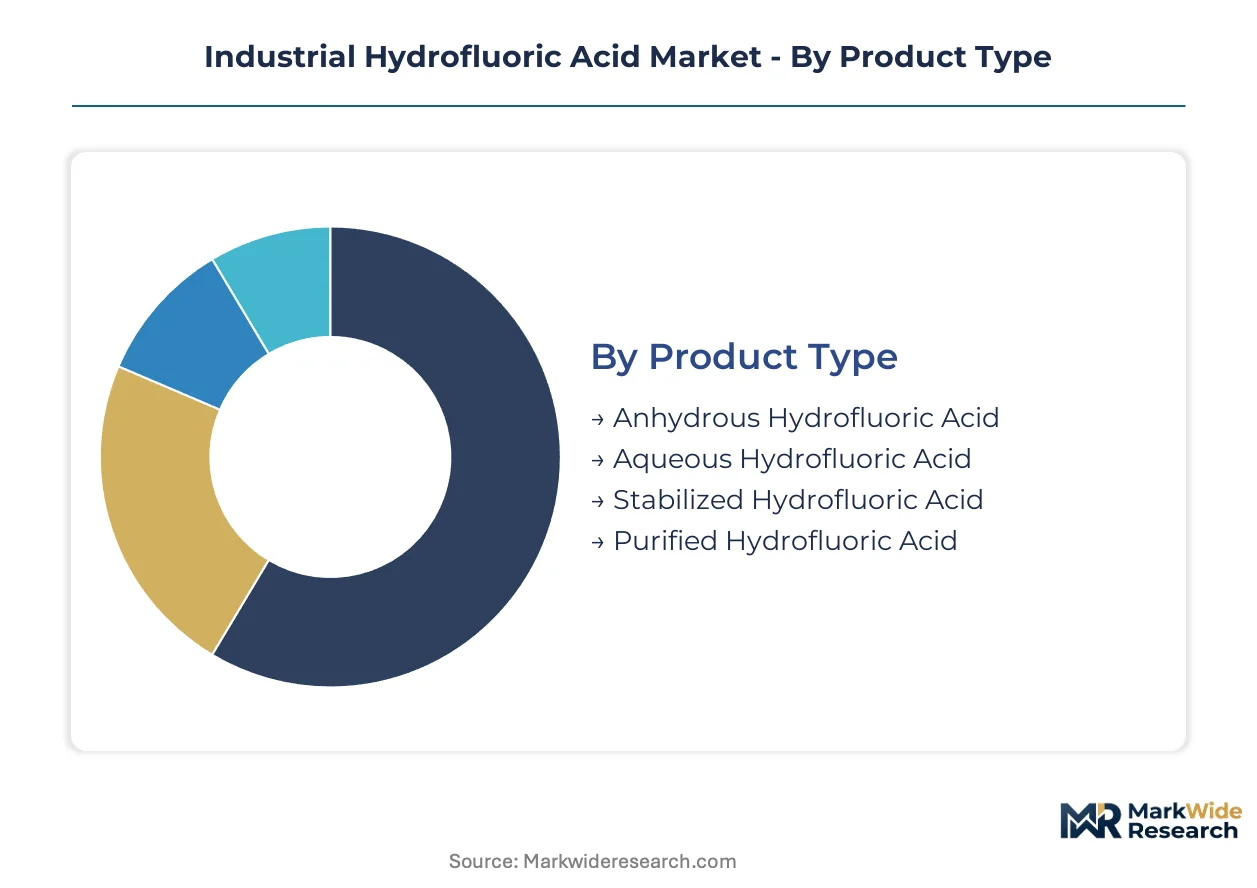
Hydrofluoric acid segmentation reveals divergent margin structures across purity grades and end-use specifications. Electronics buyers command premium pricing for contamination-controlled solutions while commodity applications absorb cost volatility through volume contracting.
Product Type:
Purity thresholds separate buyers by contamination tolerance and handling sophistication rather than volume scale alone.
- Anhydrous Hydrofluoric Acid:Near 100% hydrogen fluoride concentration demands specialized pressure-rated containment and fluorine-handling expertise. Demand concentrates at US Gulf Coast refineries pursuing alkylation catalyst substitution, constrained by OSHA threshold quantity regulations that shape regional siting decisions.
- Purified Hydrofluoric Acid:SEMI-grade specifications with parts-per-trillion metal limits undergo 18-24 month foundry qualification cycles. Taiwan and South Korea fabs drive specification tightening as advanced node fabrication below 7 nanometers consumes higher purity grades per wafer.
- Aqueous Hydrofluoric Acid:49-70% concentration solutions serve established metal oxide dissolution and glass etching operations with mature logistics infrastructure.
- Stabilized Hydrofluoric Acid:Additive-inhibited formulations reduce corrosion rates in extended storage applications for remote mining and metallurgical operations.
Volume sits with aqueous grades; growth tilts toward purified specifications.
End User:
Process sensitivity and regulatory exposure define procurement patterns across consuming industries.
- Electronics:Semiconductor foundries impose SEMI standards with individual qualification protocols, consolidating purchase volumes through nominated distributors in the Yangtze River Delta. Korean and Japanese chipmakers now embed fluorite ore index clauses rather than fixed pricing formulas.
- Chemical Manufacturing:Fluorocarbon precursor synthesis remains the mature revenue anchor though EU F-Gas Regulation phase-downs redirect acid flows toward alternative chemistries. REACH authorization burdens delay European downstream product introductions.
- Metal Processing:Stainless steel pickling and aluminum brightening operations absorb lower-purity aqueous solutions with price-sensitive spot market procurement.
- Glass Etching:Architectural and automotive glass surface treatment consumes standardized concentrations with established regional supplier relationships.
Revenue concentrates in electronics; expansion is accelerating fastest in chemical manufacturing redirection toward non-fluorinated applications.
Application:
Regulatory trajectory and technology substitution reshape competitive requirements across use cases.
- Fluorocarbon Production:Refrigerant and aerosol propellant precursor synthesis faces structural decline in Europe under tightened F-Gas schedules while Asian production continues at scale.
- Oil Refining:US alkylation units seek anhydrous alternatives to solid acid catalysts, creating inlet for high-purity grades in fuel upgrading operations.
- Metal Cleaning:Oxide dissolution and scale removal in steel and aluminum processing maintains steady offtake with established aqueous supply chains.
- Surface Treatment:Silicon wafer conditioning and photovoltaic cell texturing pull volumes toward electronics corridors with just-in-time delivery requirements.
Fluorocarbon synthesis retains volume dominance; surface treatment applications are expanding most quickly.
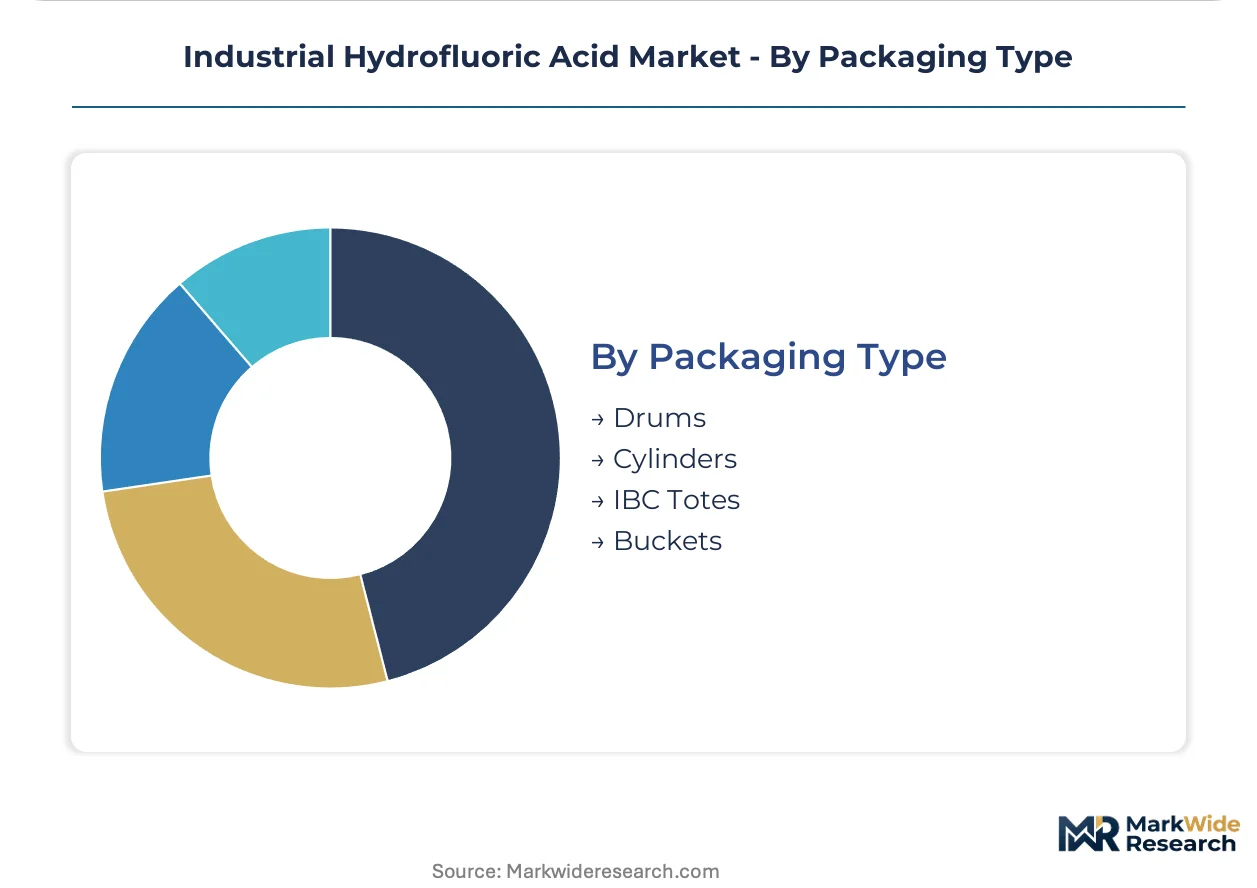
Packaging Type:
Container specification tracks hazard classification and consumption rate rather than end-use technology.
- Cylinders:Pressure-rated steel vessels handle anhydrous grades for refinery alkylation and specialty chemical operations with stringent leak detection protocols.
- IBC Totes:Intermediate bulk containers serve high-volume electronics fabs and integrated fluorochemical parks with automated handling systems.
- Drums:Standard 55-gallon steel drums accommodate aqueous grades for metal processing and glass etching with established logistics networks.
- Buckets:Small-format containers support laboratory, maintenance, and specialty repair applications with limited storage requirements.
IBC totes capture electronics volume; cylinder demand is climbing fastest on refinery substitution trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Semiconductor fabrication clusters in East Asia pull ultra-pure hydrofluoric acid volumes away from traditional fluorocarbon synthesis, fragmenting demand composition across geographies.
China
Yangtze River Delta foundries consume expanding volumes of SEMI-grade acid for advanced node production below 7 nanometers. MEE emission standards around fluorochemical parks concentrate compliant capacity in the eastern chemical corridor. Dongyue Group anchors domestic supply through integrated chlor-alkali and fluorochemical operations in Shandong Province.
United States
Gulf Coast refineries pursue anhydrous grades for alkylation catalyst substitution as alternatives to solid acid systems. EPA Risk Management Plan requirements for threshold quantities shape regional siting decisions and engineering controls. Honeywell International Inc. leverages captive fluorite reserves to sustain backward integration across the value chain.
Germany
REACH authorization burdens delay European downstream product introductions for certain fluorinated intermediates. The EU F-Gas Regulation redirects acid flows toward lower-GWP alternatives and non-fluorocarbon applications. Industrial consumers in the Rhine-Ruhr chemical cluster face extended compliance timelines affecting procurement patterns.
Japan
Korean and Japanese chipmakers embed fluorite ore index clauses in long-term supply agreements rather than fixed pricing formulas. METI oversees industrial chemical standards while semiconductor foundries consolidate purchase volumes through nominated distributors. Kyushu-based fabrication facilities drive specification tightening for contamination-controlled solutions.
South Korea
Membrane-based fluoride recovery systems capture 40-60 percent of spent etching material for on-site reprocessing at Taiwan and South Korea fabs. MFDS regulates chemical handling while foundry concentration in the Seoul Capital Area enables buyer-led standardization of purity specifications. Domestic demand localizes acid consumption currently served by Chinese and Japanese imports.
Industrial Hydrofluoric Acid Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue purification specialization and regional integration. The vendor base clusters around three strategic archetypes: integrated miners with captive fluorite reserves, diversified chemical conglomerates with anhydrous expertise, and purification specialists serving electronics corridors. Capacity expansion and strategic partnerships dominate competitive moves as participants defend position in tightening regulatory environments.
Among North American operators, Honeywell International Inc. exemplifies the integrated miner archetype through upstream control over feedstock reserves. Solvay anchors European supply capabilities through specialized production infrastructure at its Tarragona complex. Dongyue Group occupies a position within the Asia-Pacific tier through integrated operations spanning chlor-alkali and fluorochemical production.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Solvay |
| Stella Chemifa Corporation |
| LANXESS |
| Daikin |
| Dongyue Group |
| Sinochem |
| Zhejiang Kaisn Fluorochemical Co., Ltd. |
| Koura Global |
| Others |
Supply Flow & Price Mechanics
Fluorite ore cost volatility transmits directly through three pricing tiers, with Mexican and Chinese export quota decisions rippling from mine mouth to semiconductor foundry contracts. Sulfuric acid energy intensity compounds input pressure, forcing contract renegotiation at US Gulf Coast refineries and Yangtze River Delta fabs alike.
Pricing Analysis
Volume concentrates in aqueous grades while margin pools shift toward purified specifications. Three-tier pricing structure across electronics-grade, industrial-standard, and commodity-aqueous levels reflects contamination tolerance and qualification burden rather than volume scale alone. Price differentiation tracks SEMI certification status and captive fluorite access, with unintegrated processors absorbing sulfuric acid cost spikes Korean and Japanese chipmakers now embed fluorite ore index clauses, compressing spot liquidity for commodity tiers. Metal processing operations remain most price-sensitive, while semiconductor foundries prioritize supply security over unit cost.
Supply Chain Analysis
Anhydrous grade supply rests on Chinese and Mexican fluorite ore deposits, with sulfuric acid and specialized pressure-rated containment equipment as co-dependent inputs. Raw material concentration exposes processors to export quota volatility from Beijing and geopolitical friction around critical mineral access. Single-source vulnerability concentrates in fluorite beneficiation capacity, where limited alternative feedstock quality constrains rapid supplier switching. Distribution runs through integrated fluorochemical parks in China's eastern corridor, with IBC tote logistics serving high-volume electronics corridors and cylinder networks supplying refinery alkylation units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fluorine chemist scarcity and 18-24 month SEMI qualification timelines constrain capacity expansion, propping pricing power for qualified suppliers against unintegrated commodity producers.
For Market Incumbents: Deploy captive reserve leverage to secure long-term offtake with Korean and Japanese chipmakers before India's PLI scheme localizes demand. Expand purification infrastructure at existing Tarragona-class complexes to capture fluorocarbon phase-down displacement, rather than greenfield capacity exposed to OSHA threshold quantity restrictions. Defend against membrane-based on-site regeneration by embedding service contracts that capture spent acid recovery economics. For New Entrants and Emerging Players: Begin with photovoltaic silicon etching in Southeast Asia, where lower-purity aqueous specifications bypass SEMI qualification barriers and established logistics networks remain underdeveloped. Target India's semiconductor fabrication corridors before localized supply relationships crystallize around Chinese and Japanese incumbents. Pursue joint venture structures with chlor-alkali operators to share fluorine-handling infrastructure and certification burden. For Investors and Strategic Acquirers: EU F-Gas Regulation enforcement acceleration is the leading indicator that European fluorocarbon capacity will convert to electronics-grade purification at distressed asset valuations. Five-to-ten year viability favors processors with existing SEMI relationships and backward integration into compliant fluorite sources. Watch for Korean foundry consolidation of purchase volumes through nominated distributors as the signal that spot market liquidity compression is reaching terminal phase.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorite Reserves | Honeywell-style captive supply insulates against Mexican and Chinese export quota volatility. |
| SEMI Certification Investment | 18-24 month qualification cycles create moats against unqualified commodity entrants. |
| Fluorochemical Park Clustering | MEE-compliant concentration in China's eastern corridor lowers logistics costs for just-in-time delivery. |
| Membrane-Based Regeneration Partnership | Taiwan and South Korea fabs capturing 40-60 percent of spent material decentralizes traditional supplier dominance. |
| Alkylation Catalyst Substitution Supply | US Gulf Coast refinery demand for anhydrous grades creates alternative revenue as fluorocarbon synthesis declines. |
Methodological Framework
Multi-period observation of fluorite ore export quotas, SEMI qualification timelines, and F-Gas Regulation enforcement actions anchored the trend analysis, supplemented by interviews with fluorochemical plant managers, semiconductor procurement leads at Taiwanese and Korean foundries, distribution channel partners in the Yangtze River Delta, and technical R&D directors at purification specialists. Secondary validation drew from Chinese MEE emission disclosures, EU ECHA authorization databases, US EPA Risk Management Plan filings, and ACC trade flow data. Bottom-up capacity modeling triangulated against top-down consumption estimates across electronics and chemical manufacturing end-uses.
Segment-weighting approached derived CAGRs by disaggregating grade tier, end-use industry, packaging format, and regional production hub contributions across the projection horizon. Electronics-grade specifications, refinery alkylation substitution rates, and photovoltaic wet processing adoption served as industry-specific forecast inputs. Cross-segment elasticity modeling captured fluorocarbon phase-down redirection toward alternative chemistries.
Fluorite ore supply disruption, SEMI specification tightening acceleration, and REACH authorization timeline extension are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about regulatory enforcement intensity and foundry capacity buildout pacing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Phosphorus Trichloride Market
Chemicals
Chromium Trioxide Market
Chemicals
Electronic Grade Hydrofluoric Acid Market
Chemicals
Trifluoroacetic Acid (TFA) Market
Chemicals
6 Hexanediol Market
Chemicals
Myclobutanil Market
Chemicals
Phenylethyl Market
Chemicals
Global Methyl Methacrylate (MMA) Monomer Market
Chemicals
Global Acetic Anhydride Market
Chemicals
Allyl Chloride Market
Chemicals
Hexamethylenetetramine (HMTA) Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Para Cresol Market
Chemicals
Formalin Market
Chemicals
Europe Biguanide Market
Chemicals
Pyrimidine Market