
 Metaphenoxy Benzaldehyde (MPBD) Market | 2026-2036
Metaphenoxy Benzaldehyde (MPBD) Market Size, Share, and Industry Trends Forecast 2026-2036
Metaphenoxy Benzaldehyde (MPBD) Market Insights
Specialty chemical distribution is tilting toward direct manufacturer relationships as bulk pharmaceutical buyers seek supply chain transparency. Tagros Chemicals India leverages its integrated agrochemical platform to control upstream MPBD output for captive pyrethroid synthesis. Sigma-Aldrich (Merck KGaA) sustains premium positioning across research-grade channels through exacting certificate-of-analysis protocols. Gharda Chemicals anchors western India supply through dedicated aldehyde capacity serving regional dye houses.
Metaphenoxy benzaldehyde is an aromatic aldehyde bearing a phenoxy substituent at the meta position, typically synthesized via Vilsmeier-Haack formylation of metaphenoxy precursors with phosphorus oxychloride and dimethylformamide, yielding a crystalline solid with characteristic aldehyde reactivity essential for carbon-carbon bond formation in downstream synthesis. Pharmaceutical-grade MPBD commands the steepest quality premiums as FDA and EMA filing requirements mandate sub-ppm impurity profiles for intermediates entering approved drug master files. Industrial-grade volumes dominate absolute tonnage as dye manufacturing and agrochemical formulation absorb standardized purity material at contracted offtake rates.
EPA registration requirements for pesticide intermediates and REACH substance authorization under ECHA scrutiny are elevating analytical documentation burdens for MPBD exporters seeking sustained market access. India's CDSCO alignment with ICH Q3D guidelines on elemental impurities is reshaping pharmaceutical-grade specifications for domestic manufacturers supplying regulated export markets. Stakeholders must monitor evolving regulator convergence on genotoxic impurity thresholds to avoid batch disqualification in cross-border pharmaceutical ingredient trade.
Market Dynamics
REACH substance authorization under ECHA scrutiny is forcing MPBD exporters to reconfigure analytical documentation workflows, while Indian agrochemical formulators expand captive aldehyde consumption to secure pyrethroid supply chains.
Growth Catalysts
- Pharmaceutical synthesis expansion:Contract manufacturers scaling active ingredient production are pulling additional MPBD volumes for carbon-carbon bond formation in downstream drug intermediates.
- REACH compliance tightening:Evolving ECHA substance evaluations are elevating purity benchmarks for European imports, creating demand for certified pharmaceutical-grade material.
- India's agrochemical integration:Domestic formulators expanding captive aldehyde consumption are concentrating demand within the country's western chemical clusters.
Market Restraints
- Phosphorus oxychloride cost volatility:Vilsmeier-Haack synthesis relies on this regulated input, exposing margins to supply shocks from Chinese export quotas.
- Supply concentration in western India:Dedicated aldehyde capacity clusters around Gujarat and Maharashtra create geographic single-point vulnerability.
- Substitution by alternative formylation routes:Gattermann-Koch and Reimer-Tiemann chemistries offer competing pathways for meta-substituted benzaldehydes.
Strategic Opportunities
- CDSCO-ICH Q3D alignment:India's adoption of elemental impurity guidelines creates regulatory tailwind for domestic manufacturers supplying regulated export markets.
- Research-grade channel expansion:Certificate-of-analysis protocols are opening premium positioning for exacting analytical documentation in specialty chemical distribution.
- Dye manufacturing standardization:Industrial-grade MPBD absorption at contracted offtake rates offers volume stability through long-term supply agreements.
Industry Challenges
- Genotoxic impurity threshold compliance:Regulator convergence on ICH M7 guidelines demands enhanced analytical chemistry capabilities to avoid batch disqualification.
- Dual-use chemical licensing complexity:MPBD's precursor status under chemical weapons convention schedules creates cross-border documentation friction.
- Legacy quality management system upgrades:Pharmaceutical-grade producers must retrofit facilities for FDA and EMA filing requirements on sub-ppm impurity profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metaphenoxy Benzaldehyde (MPBD) Market |
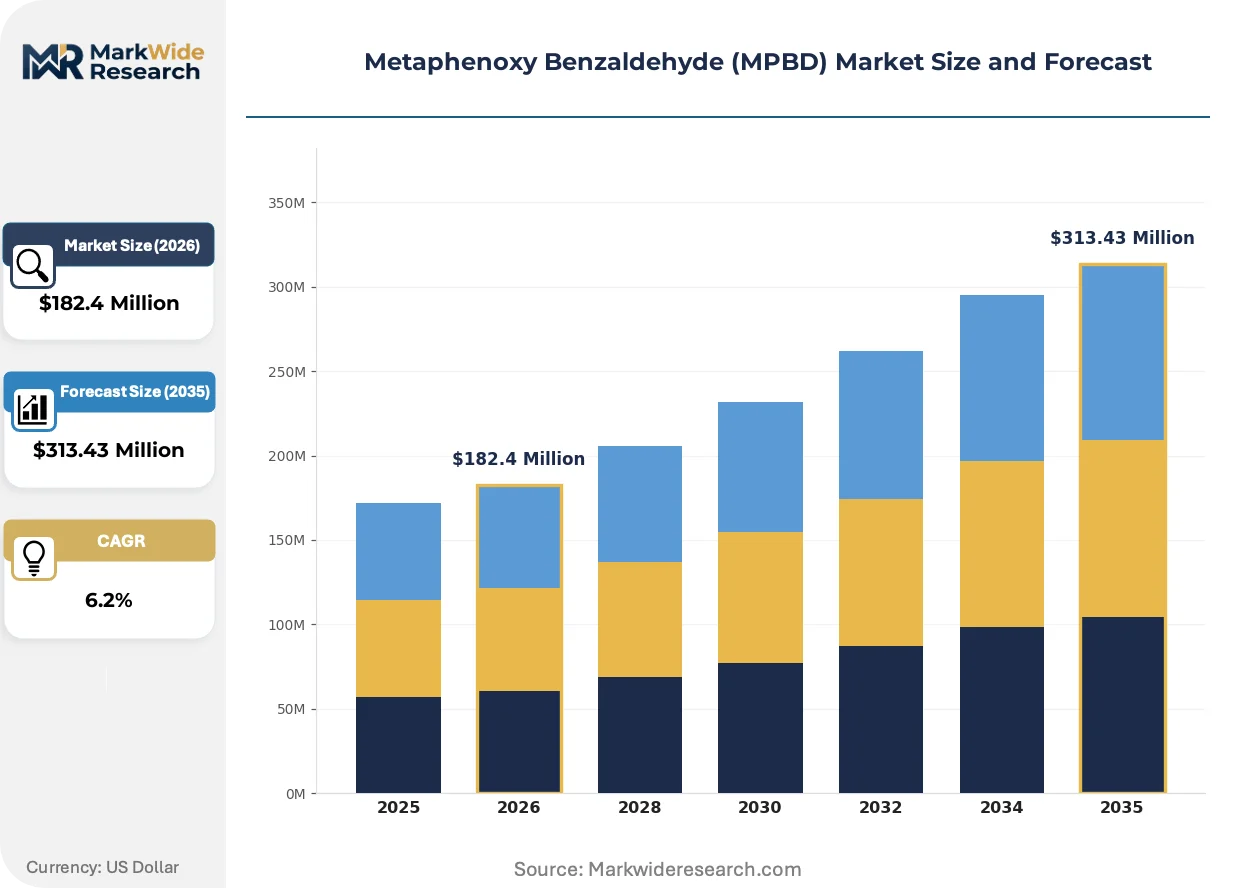
| Market Size in 2026 | $182.4 Million |
| Market Size in 2035 | $313.43 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Research Grade Application: Fragrance, Dye Manufacturing, Pharmaceutical Synthesis, Agrochemical Production End User: Cosmetic Manufacturers, Pharmaceutical Companies, Research Institutions, Textile Industries Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Tagros Chemicals India, Sigma-Aldrich (Merck KGaA), Gharda Chemicals, Alfa Aesar (Thermo Fisher Scientific), TCI Chemicals, Heranba Industries, Hemani Group, Toronto Research Chemicals Inc., Bharat Rasayan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metaphenoxy Benzaldehyde (MPBD) Market Trends and Innovations
Process analytical technology is compressing batch release timelines, while regulatory documentation automation and direct manufacturer relationships are restructuring how specialty chemical buyers secure supply chain transparency.
Continuous flow Vilsmeier-Haack reactors are virtualizing traditional batch formylation by enabling real-time reaction monitoring and tighter temperature control. Pharmaceutical contract manufacturers in India and Europe are adopting these systems at pilot scale. This technology is virtualizing the gap between laboratory synthesis and commercial production, collapsing scale-up timelines from months to weeks.
ECHA's evolving substance evaluation protocols under REACH are mandating enhanced analytical datasets for aromatic aldehyde imports. Industrial consequence includes mandatory third-party certification for genotoxic impurity screening before customs clearance. Pharmaceutical-grade MPBD entering European drug master files faces the steepest documentation burden, with exporters investing in dedicated regulatory affairs capacity.
Specialty chemical buyers are consolidating vendor relationships around direct manufacturer contracts that certificate-of-analysis protocols support. Bulk pharmaceutical purchasers in North America and Europe are displacing traditional distributor intermediaries with audited supply agreements. This pattern concentrates procurement leverage among formulators with sufficient volume to justify dedicated account management.
Metaphenoxy Benzaldehyde (MPBD) Market Segmentation
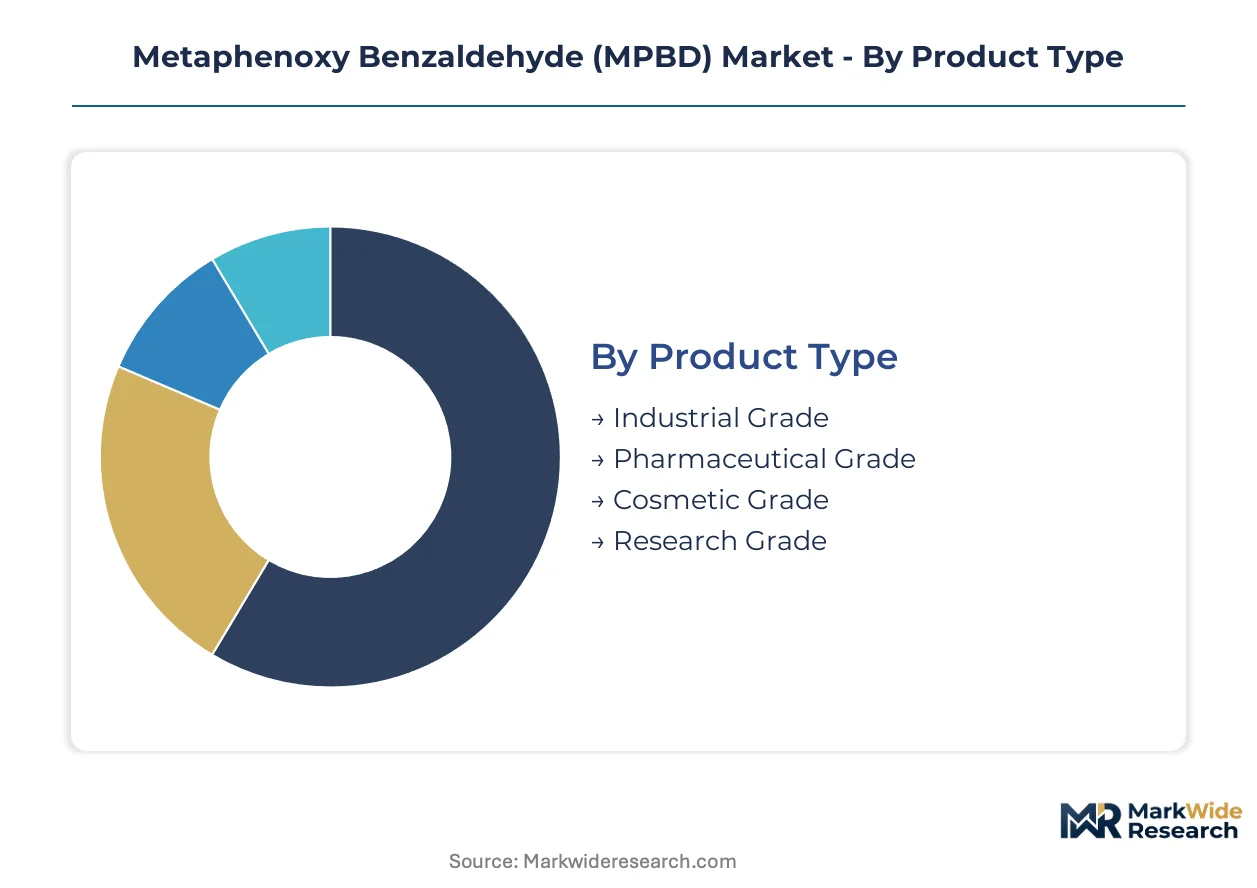
MPBD segmentation reveals how purity specifications and regulatory documentation intensity fragment supply chains across pharmaceutical, agrochemical, and industrial channels. Each tier demands distinct analytical protocols, manufacturing footprints, and customer engagement models.
Product Type:
After-sales service intensity escalates dramatically from industrial to pharmaceutical grades, with certificate-of-analysis support and regulatory filing assistance becoming core value components.
- Pharmaceutical Grade:Sub-ppm impurity profiles meet FDA and EMA filing requirements for drug master files. CDSCO-aligned Indian manufacturers capture expanding contract manufacturing demand from European and North American sponsors seeking compliant intermediates.
- Industrial Grade:Standardized purity material serves dye manufacturing and bulk agrochemical formulation at contracted offtake rates. Western India chemical clusters anchor supply through dedicated aldehyde capacity serving regional absorption.
- Research Grade:Exact certificate-of-analysis protocols support carbon-carbon bond formation studies in academic and contract research settings.
- Cosmetic Grade:Fragrance intermediate specifications balance sensory performance with regulatory safety documentation for personal care formulations.
By volume, Industrial Grade leads. By growth pace, Pharmaceutical Grade is expanding most quickly.
Application:
Margin structures diverge sharply across applications, with pharmaceutical synthesis commanding quality premiums while dye manufacturing absorbs standardized material at scale-driven pricing.
- Pharmaceutical Synthesis:Carbon-carbon bond formation in downstream drug intermediates pulls MPBD volumes as contract manufacturers scale active ingredient production. REACH compliance tightening elevates documentation burdens for European-bound shipments.
- Agrochemical Production:Pyrethroid synthesis drives captive aldehyde consumption among Indian formulators securing supply chain control. EPA registration requirements for pesticide intermediates create cross-border documentation friction.
- Dye Manufacturing:Aromatic aldehyde reactivity supports colorant intermediate synthesis for textile processing.
- Fragrance:Phenoxy-substituted benzaldehyde character contributes to specialty scent formulations in personal care.
By absolute tonnage, Agrochemical Production dominates. By regulatory complexity, Pharmaceutical synthesis sets the pace.
End User:
Customer procurement maturity spans from spot purchasing in textile industries to audited supply agreements with pharmaceutical sponsors demanding supply chain transparency.
- Pharmaceutical Companies:Bulk active ingredient manufacturers displace distributor intermediaries with direct manufacturer contracts supported by exacting analytical documentation. ICH M7 genotoxic impurity compliance reshapes vendor qualification protocols.
- Research Institutions:Academic and contract research laboratories source through specialty chemical channels with certificate-of-analysis requirements for reproducible synthesis.
- Cosmetic Manufacturers:Fragrance houses and personal care formulators seek consistent sensory performance with safety dossier support.
- Textile Industries:Dye houses in western India absorb industrial-grade volumes through regional supply agreements.
By contract value, Pharmaceutical Companies lead. By volume throughput, Textile Industries show the steepest expansion trajectory.
Distribution Channel:
Channel economics reflect buyer scale and documentation intensity, with direct relationships consolidating among large formulators while smaller consumers retain distributor access.
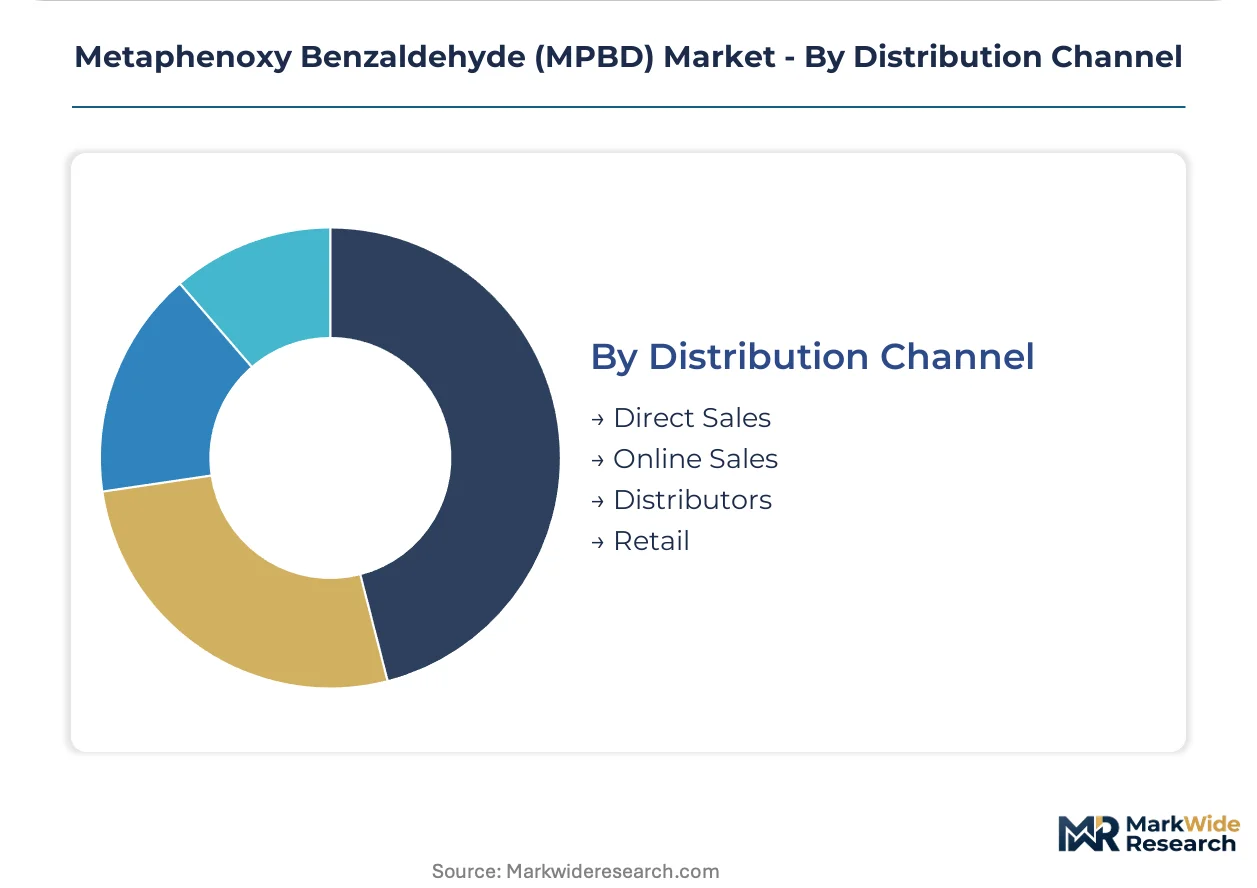
- Direct Sales:Audited supply agreements concentrate procurement leverage among North American and European bulk pharmaceutical purchasers seeking supply chain transparency. Dedicated account management justifies relationship investment at sufficient volume thresholds.
- Distributors:Traditional specialty chemical intermediaries serve fragmented research and cosmetic customers lacking scale for manufacturer-direct engagement.
- Online Sales:Digital procurement platforms facilitate research-grade material access for smaller laboratories with immediate analytical needs.
- Retail:Minimal presence given MPBD's intermediate chemical status and regulatory documentation requirements.
By revenue concentration, Direct Sales leads. By channel growth, Online Sales is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH substance authorization protocols anchor European demand for certified pharmaceutical-grade MPBD, while India's CDSCO alignment with ICH guidelines is reshaping export specifications for western chemical clusters.
India
Domestic agrochemical formulators in Gujarat and Maharashtra are expanding captive aldehyde consumption to secure pyrethroid supply chains. CDSCO's adoption of ICH Q3D elemental impurity guidelines is elevating documentation requirements for pharmaceutical-grade exports. Ankleshwar and Vapi chemical clusters anchor dedicated aldehyde capacity serving regional dye houses and active ingredient manufacturers.
Germany
Contract manufacturers scaling carbon-carbon bond formation for drug intermediates are pulling certified MPBD volumes through audited supply agreements. EMA filing requirements mandate sub-ppm impurity profiles for intermediates entering approved drug master files. Frankfurt and Ludwigshafen pharmaceutical hubs concentrate procurement leverage among sponsors seeking REACH-compliant material.
United States
Bulk pharmaceutical purchasers are displacing distributor intermediaries with direct manufacturer contracts demanding supply chain transparency. EPA registration requirements for pesticide intermediates create cross-border documentation friction for agrochemical applications. New Jersey and Massachusetts pharmaceutical corridors anchor demand for research-grade material with exacting certificate-of-analysis protocols.
China
Phosphorus oxychloride export quotas are exposing Vilsmeier-Haack synthesis margins to supply volatility, forcing formulators to reconfigure input sourcing. NMPA alignment with ICH M7 genotoxic impurity guidelines is elevating analytical documentation for pharmaceutical-bound shipments. Jiangsu and Zhejiang chemical provinces concentrate industrial-grade production for dye manufacturing absorption.
Japan
PMDA's stringent impurity profiling for drug master files is concentrating demand for pharmaceutical-grade MPBD among Tokyo-Osaka pharmaceutical sponsors. METI chemical management regulations are tightening handling protocols for aromatic aldehyde intermediates. Kanto and Kansai industrial belts anchor research-grade consumption through specialty chemical channels.
Metaphenoxy Benzaldehyde (MPBD) Market Competitive Landscape
Integrated agrochemical platforms and research-grade specialists split the market between volume-driven captive consumption and premium analytical documentation. The vendor base organizes around three strategic archetypes: western India chemical houses with dedicated aldehyde capacity, global life science distributors with exacting certificate-of-analysis protocols, and mid-scale formulators securing backward integration into pyrethroid precursors. Capacity expansion and regulatory filing assistance represent the dominant competitive moves as buyers consolidate around audited supply agreements.
Among western India-based chemical houses, Tagros Chemicals India and Gharda Chemicals exemplify the integrated agrochemical archetype with captive aldehyde output serving regional pyrethroid synthesis. Sigma-Aldrich (Merck KGaA) occupies a position within the research-grade distribution tier, anchoring premium positioning through exacting analytical documentation for pharmaceutical and academic channels. These three entities represent the structural fault lines between volume-driven industrial absorption and specification-intensive pharmaceutical supply.
| Leading Market Players |
|---|
| Tagros Chemicals India |
| Sigma-Aldrich (Merck KGaA) |
| Gharda Chemicals |
| Alfa Aesar (Thermo Fisher Scientific) |
| TCI Chemicals |
| Heranba Industries |
| Hemani Group |
| Toronto Research Chemicals Inc. |
| Bharat Rasayan |
| Others |
Pricing and Supply Chain Analysis
Phosphorus oxychloride export quota volatility from Chinese authorities compresses Vilsmeier-Haack synthesis margins and simultaneously widens pharmaceutical-industrial grade spreads while forcing buyers toward long-term offtake structures that bypass spot market exposure.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade MPBD commands substantial premiums over standardized industrial material. Three-tier pricing structure across pharmaceutical, industrial, and research grades reflects documentation intensity and certification burden. Cost compression in industrial-grade channels is intensifying because dye manufacturers negotiate contracted offtake rates at volume scale. Agrochemical formulators show highest price sensitivity due to pyrethroid margin pressure, while pharmaceutical sponsors accept premium pricing for sub-ppm impurity profiles.
Supply Chain Analysis
Export-control restrictions on phosphorus oxychloride under chemical weapons convention schedules limit input flows and elevate compliance costs. Manufacturing concentrates in India, China, and Germany, with western Indian chemical clusters anchoring dedicated aldehyde capacity. Vilsmeier-Haack synthesis rests on dimethylformamide and phosphorus oxychloride feedstocks. Single-source vulnerability around Chinese phosphorus oxychloride suppliers creates structural risk. Distribution runs through direct manufacturer contracts for bulk pharmaceutical purchasers and specialty chemical distributors for fragmented research customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ICH M7-compliant analytical chemistry capabilities constrains batch release velocity and creates bottlenecks for pharmaceutical-grade producers seeking drug master file eligibility.
For Market Incumbents: Insulate margin position through backward integration into phosphorus oxychloride sourcing and captive dimethylformamide recovery systems. Add dedicated regulatory affairs capacity in Frankfurt and New Jersey corridors to sustain EMA and FDA filing support. Defend against continuous flow reactor substitution by locking multi-year pharmaceutical sponsor contracts with embedded certificate-of-analysis protocols. For New Entrants and Emerging Players: Establish a beachhead in research-grade channels serving academic laboratories and contract research organizations with exacting analytical documentation. Target cosmetic fragrance intermediates as the most penetrable application, where sensory performance requirements are less stringent than pharmaceutical specifications. Pursue digital procurement platform partnerships to bypass traditional distributor intermediaries. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated agrochemical platforms with captive aldehyde output and established pyrethroid downstream demand. Five-to-ten year viability hinges on REACH compliance infrastructure and CDSCO-ICH alignment capabilities. Watch for ECHA substance authorization rulings as the inflection signal that separates compliant from disqualified supplier bases.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphorus Oxychloride | Reduces exposure to Chinese export quotas and stabilizes Vilsmeier-Haack input costs. |
| Continuous Flow Reactor Installation | Compresses batch release timelines from months to weeks for pharmaceutical contract manufacturers. |
| CDSCO-ICH Q3D Certification Investment | Unlocks regulated export markets for Indian manufacturers supplying European and North American sponsors. |
| Long-term Supply Agreement with Dye Houses | Secures volume stability through contracted offtake rates at western India chemical clusters. |
| Regulatory Affairs Capacity Expansion | Supports EMA and FDA drug master file submissions with dedicated compliance documentation teams. |
Research Methodology
A standing panel of pharmaceutical procurement directors, agrochemical formulator supply chain managers, specialty chemical distribution executives, and analytical chemistry laboratory heads provided ongoing calibration across the study period. Primary interviews with plant managers at western India aldehyde facilities combined with secondary validation from CDSCO guidance documents, ECHA substance evaluation protocols, SEC filings of listed chemical manufacturers, and customs trade data. Bottom-up volume estimates from individual production facilities triangulated against top-down demand aggregation from end-use applications.
Scenario-bracketing around phosphorus oxychloride supply disruption, REACH authorization timelines, and CDSCO enforcement intensity bounded the forecast range across the analysis window. Segmentation modeling incorporated grade tier, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from slope analysis of historical trajectory adjustments applied to capacity expansion announcements and sponsor pipeline visibility. Industry-specific inputs included pharmaceutical contract manufacturing growth rates and pyrethroid formulation demand curves.
Stress conditions across Chinese export quota severity, ECHA genotoxic impurity threshold revisions, and Indian captive consumption acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory convergence timing and input cost trajectories. Material shifts in chemical weapons convention scheduling or ICH M7 guideline enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Acid Chlorides Market
Chemical Intermediates
Cytosine Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
9-Decanoic Acid Methyl Ester Market
Chemical Intermediates
Triisobutyl Phosphate Market
Chemical Intermediates
Natural Chelating Agents Market
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Myristoyl Chloride Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
Thioesters Market
Chemical Intermediates
Carboxylic Acid Chlorides Market