
 Benzyl Alcohol Market | 2026-2036
Benzyl Alcohol Market Size, Share, and Industry Trends Forecast 2026-2036
Benzyl Alcohol Market Analysis
Multi-source procurement is rebalancing toward captive benzyl chloride supply among top manufacturers. Evonik Industries AG anchors European production through backward integration into toluene derivatives. LANXESS competes on technical-grade scale for coating and epoxy intermediates. Merck KGaA differentiates via pharmaceutical-grade certification for parenteral applications.
Benzyl alcohol is an aromatic primary alcohol with the formula C₆H₅CH₂OH, typically produced via toluene oxidation or benzyl chloride hydrolysis, and functions as a solvent, preservative, and local anesthetic in injectable formulations. The cosmetics application leads volume, with skin care formulations absorbing the largest share of cosmetic-grade output. Pharmaceutical-grade purity levels command the strongest margin pools due to USP and EP certification requirements. Technical-grade supply sustains industrial coating and dye intermediates demand.
EPA oversight governs toluene feedstock emissions and waste streams in US manufacturing, while REACH restricts residual benzaldehyde and chloride content in European imports. FDA monographs define permissible limits for benzyl alcohol in parenteral and ophthalmic drug products, directly shaping qualification costs for pharmaceutical-grade suppliers. Stakeholders must monitor evolving impurity specifications across FDA, EMA, and China's NMPA as biosimilar injectable volumes expand.
Market Dynamics
Pharmaceutical-grade benzyl alcohol supply is tightening as REACH compliance in Europe and NMPA standards in China simultaneously raise impurity thresholds, forcing manufacturers to reconfigure purification trains and validate new analytical methods.
Growth Catalysts
- Injectable drug solvent preference:Parenteral formulations are absorbing higher benzyl alcohol volumes as preservative systems in multi-dose vials. FDA monographs for ophthalmic and injectable applications validate this demand trajectory.
- REACH compliance:Tightened residual benzaldehyde and chloride thresholds in European imports are accelerating qualification of dedicated pharmaceutical-grade production lines among incumbent suppliers.
- China API production scaling:Domestic active pharmaceutical ingredient manufacturing is concentrating benzyl alcohol procurement within Shanghai and Jiangsu province chemical parks.
Market Restraints
- Toluene feedstock volatility:Crude oil-linked aromatics pricing transmits directly to benzyl alcohol cost structures, compressing margin predictability for non-integrated producers.
- Supply concentration risk:Captive benzyl chloride supply among top three manufacturers limits spot market liquidity and raises switching costs for qualified pharmaceutical buyers.
- Benzaldehyde substitution:Certain coating and dye intermediate applications are partially substituting technical-grade benzyl alcohol with alternative aromatic solvents where purity specifications permit.
Strategic Opportunities
- Biosimilar injectable expansion:EMA and FDA biosimilar approval pathways are opening dedicated benzyl alcohol qualification programs for follow-on biologics requiring preservative systems.
- Green chemistry incentives:EU Green Deal funding streams favor toluene oxidation process improvements with lower emission profiles versus legacy benzyl chloride hydrolysis routes.
- Direct-to-formulator distribution:Pharmaceutical-grade suppliers are bypassing traditional chemical distributors to establish direct technical service relationships with injectable drug manufacturers.
Industry Challenges
- Multi-jurisdiction validation timelines:Simultaneous USP, EP, and NMPA certification requirements extend qualification cycles and tie up analytical chemistry capacity.
- Purification train capex intensity:Pharmaceutical-grade impurity thresholds demand continuous liquid-liquid extraction and molecular distillation investments that strain mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzyl Alcohol Market |
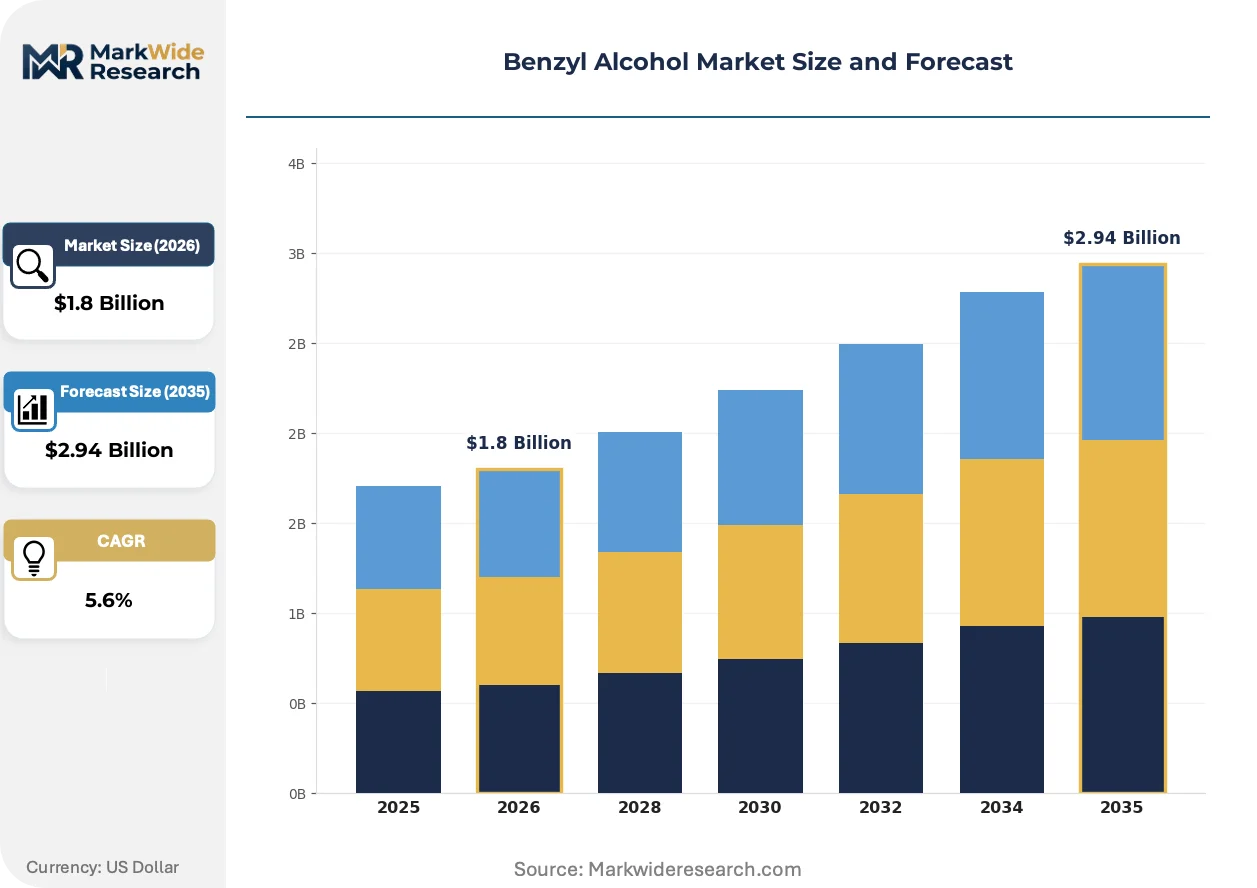
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Fragrances, Preservatives Application: Skin Care, Hair Care, Antiseptics, Flavoring Agents End User: Manufacturers, Retailers, Wholesalers, Distributors Purity Level: High Purity, Technical Grade, Food Grade, Cosmetic Grade |
| Companies Covered | Evonik Industries AG, Honeywell Research Chemicals, The Dow Chemical Company, Elan Chemical, Avantor Inc., Thermo Fisher Scientific Inc., LANXESS, Emerald Performance Materials, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzyl Alcohol Market Emerging Trajectories
Continuous processing technologies and regulatory harmonization pressures are reshaping how benzyl alcohol manufacturers structure production assets and quality systems. Three developments warrant particular attention.
Continuous toluene oxidation reactor designs are expanding into commercial pharmaceutical-grade production, replacing batch-wise benzyl chloride hydrolysis with steady-state operation that reduces solvent waste and improves lot-to-lot consistency. European manufacturers with REACH compliance obligations are piloting these systems fastest. The technology is expanding into dedicated parenteral-grade supply chains previously reserved for batch-validated assets.
REACH authorization requirements for residual chlorides are tightening analytical detection thresholds and mandating ion chromatography substitution for legacy titration methods in European import testing. Pharmaceutical-grade suppliers are revalidating entire quality systems to maintain EMA-recognized certificates of suitability. Cosmetic and technical-grade exporters to Europe face the steepest compliance cost escalation.
Formulator consolidation among top ten injectable drug manufacturers is concentrating procurement leverage and demanding dedicated inventory positions with documented pedigree. Long-term supply agreements with built-in price adjustment mechanisms are displacing spot market purchases for pharmaceutical-grade volumes. This concentration is most visible in North American parenteral manufacturing clusters.
Benzyl Alcohol Market Segmentation
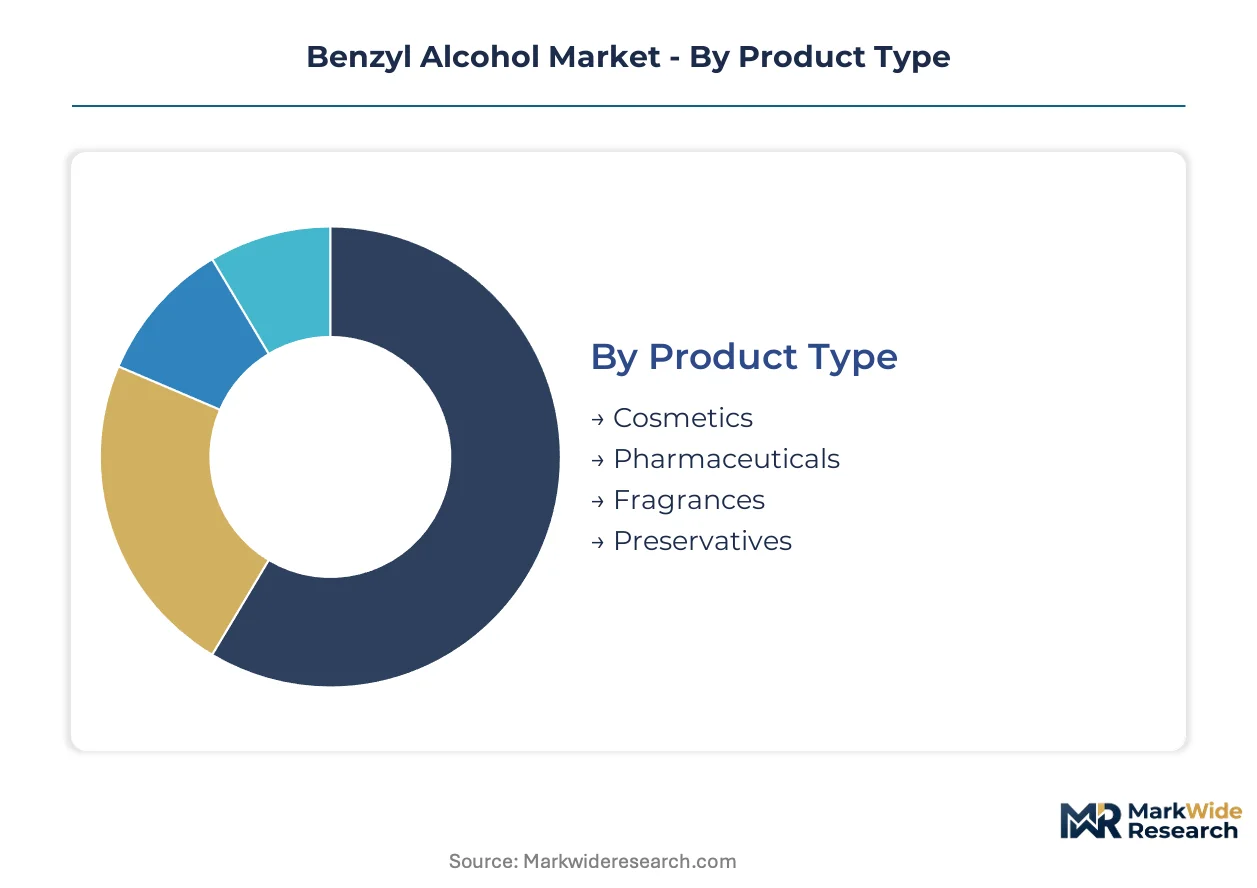
Benzyl alcohol market segmentation reveals how purity specifications and end-use requirements fragment supply chains into distinct qualification tiers. Each segment carries unique regulatory burdens and margin structures that reshape competitive positioning across pharmaceutical, cosmetic, and industrial applications.
Product Type:
Upgrade cycles from technical-grade to pharmaceutical-grade supply are compressing as multi-dose injectable volumes expand and impurity thresholds tighten across FDA, EMA, and NMPA jurisdictions.
- Pharmaceuticals:USP and EP-certified material serves as solvent and preservative in parenteral formulations, with demand concentrating in sterile injectable manufacturing clusters in New Jersey, Basel, and Shanghai as biosimilar pipelines mature.
- Cosmetics:This segment absorbs the largest volume share, functioning as fragrance carrier and viscosity modifier in skin care emulsions, with procurement gravitating toward integrated toluene oxidation supply from European REACH-compliant producers.
- Fragrances:Technical-grade supply supports aroma chemical synthesis for consumer products, typically sourced through spot market channels with lower qualification overhead.
- Preservatives:Multi-dose ophthalmic and topical applications require intermediate purity grades, bridging cosmetic and pharmaceutical specifications.
Cosmetics sits at the top of the volume ranking, with Pharmaceuticals climbing the fastest.
Application:
Cost tier differentiation separates mass-market personal care from prescription-grade therapeutic uses, with certification requirements driving order-of-magnitude price spreads between adjacent segments.
- Skin Care:Moisturizer and anti-aging formulations employ benzyl alcohol as penetration enhancer and mild preservative, with demand clustering in Korean and French cosmetic manufacturing hubs serving export markets.
- Antiseptics:Hospital-grade disinfectant formulations require documented purity pedigree and batch-specific analytical certificates, concentrating procurement among pharmaceutical-grade suppliers with validated quality systems.
- Hair Care:Conditioning agents and scalp treatments utilize technical-grade material where dermal irritation thresholds permit broader impurity bands.
- Flavoring Agents:Food-grade certification under FEMA and JECFA standards governs this niche application, with supply constrained by dedicated manufacturing line requirements.
Skin Care dominates absolute volume, while Antiseptics expands most quickly on hospital infection control protocols.
End User:
Customer type determines contract structure, with direct manufacturer relationships displacing distributor channels as qualification documentation requirements intensify.
- Manufacturers:Injectable drug producers and cosmetic formulators drive pharmaceutical-grade demand, negotiating long-term supply agreements with built-in technical service provisions and dedicated inventory positions.
- Distributors:Chemical distribution networks retain relevance in technical-grade and cosmetic-grade spot markets, though margin compression from manufacturer direct sourcing is eroding traditional value-add.
- Retailers:Private-label cosmetic brands and compounding pharmacies source smaller volumes with less stringent pedigree requirements.
- Wholesalers:Regional chemical traders facilitate technical-grade supply to coating and dye intermediate producers with limited supplier qualification capabilities.
Manufacturers command the largest procurement volumes, with Distributors gaining share fastest on inventory consolidation trends.
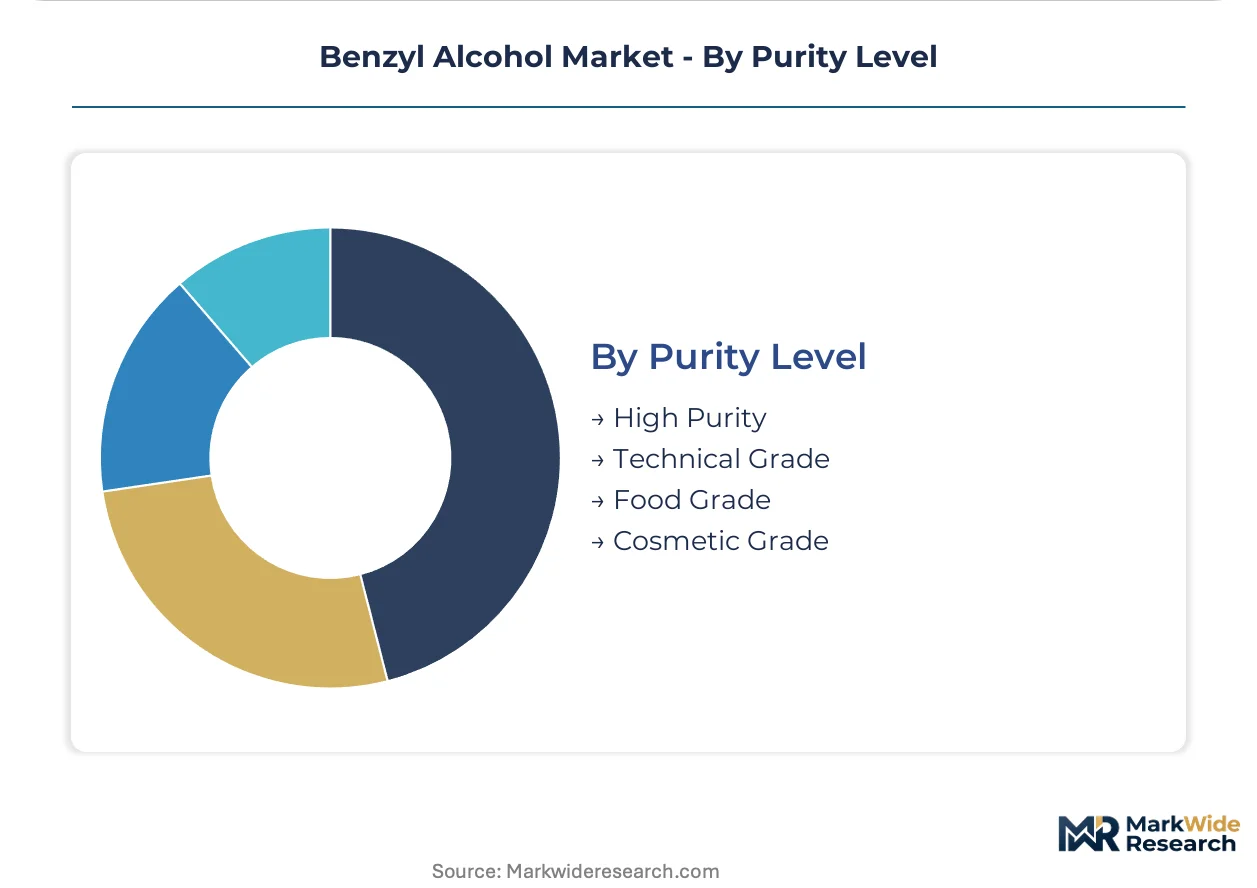
Purity Level:
Margin stratification across purity tiers reflects capital intensity of purification trains and analytical validation burdens, with top grades commanding substantial premia over technical specifications.
- High Purity:Parenteral-grade material meeting USP, EP, and NMPA monographs requires continuous liquid-liquid extraction and molecular distillation, with supply concentrating among backward-integrated toluene oxidation producers in Germany and China.
- Technical Grade:Industrial coating and epoxy resin applications tolerate broader impurity profiles, sourcing from benzyl chloride hydrolysis routes with lower environmental compliance investments.
- Cosmetic Grade:Intermediate specifications for personal care balance sensory properties against preservation efficacy, with REACH residual chloride thresholds tightening qualification requirements for European imports.
- Food Grade:FEMA GRAS and JECFA compliance restricts this segment to dedicated production assets with documented allergen and contaminant controls.
Technical Grade leads volume, with High Purity showing the steepest expansion trajectory on injectable drug growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai and Jiangsu province chemical parks concentrate the world's largest benzyl alcohol production capacity, serving domestic API manufacturing and export pharmaceutical-grade supply chains. Regulatory divergence across FDA, EMA, and NMPA jurisdictions is fragmenting qualification requirements and reshaping regional trade flows.
China
Domestic active pharmaceutical ingredient manufacturing scales rapidly in Shanghai chemical parks, absorbing captive benzyl alcohol output from backward-integrated toluene oxidation facilities. NMPA impurity threshold tightening mirrors REACH standards and accelerates dedicated pharmaceutical-grade line investments. Jiangsu province hosts the densest cluster of cosmetic-grade production serving Korean and Japanese personal care exporters.
Germany
Evonik Industries AG anchors European pharmaceutical-grade supply through integrated toluene derivative complexes in Marl and Antwerp-adjacent operations. REACH residual chloride and benzaldehyde restrictions mandate ion chromatography substitution for legacy titration methods, elevating analytical validation costs. The country's national chemical regulator enforces the strictest import testing protocols for parenteral-grade material entering EMA-recognized manufacturing sites.
United States
New Jersey and Massachusetts sterile injectable manufacturing clusters drive pharmaceutical-grade benzyl alcohol procurement under FDA monographs for multi-dose vials and ophthalmic formulations. EPA toluene feedstock emission controls govern domestic production economics, while parenteral drug pricing pressures compress solvent cost tolerance. Direct-to-formulator distribution channels are displacing traditional chemical distributors in North American procurement.
India
CDSCO pharmaceutical-grade certification requirements are converging with USP and EP standards as domestic biosimilar injectable pipelines mature. Maharashtra and Gujarat chemical parks concentrate technical-grade capacity for coating and dye intermediate exports to Middle East and Southeast Asian markets. The country's national pharmaceutical regulator has accelerated import substitution incentives for preservative-system raw materials.
Switzerland
Basel pharmaceutical manufacturing clusters source high-purity benzyl alcohol for parenteral formulations under Swissmedic and EMA dual jurisdiction requirements. The country's cantonal chemical oversight bodies enforce documentation standards exceeding standard REACH compliance for materials entering sterile drug production. Swiss-based formulator consolidation concentrates procurement leverage and demands dedicated inventory positions with full batch pedigree.
Benzyl Alcohol Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biosimilar injectable qualification partnerships and green chemistry process licensing. The vendor base concentrates among three to five backward-integrated manufacturers controlling captive benzyl chloride supply, with mid-scale hydrolysis-route operators retreating to technical-grade spot markets. Strategic archetypes include toluene-oxidation specialists with REACH-compliant pharmaceutical lines, benzyl-chloride hydrolysis mass producers serving industrial coatings, and laboratory chemical distributors with USP-certified packaging operations. Capacity expansion and direct-to-formulator distribution partnerships constitute the dominant competitive moves reshaping channel economics.
Among German chemical conglomerates with integrated toluene derivative operations, Evonik Industries AG exemplifies the backward-integrated archetype with dedicated pharmaceutical-grade assets. LANXESS occupies a position within the technical-grade scale tier, serving coating and epoxy intermediate demand. Merck KGaA represents the certified-pharmaceutical specialist segment, anchoring parenteral-grade supply relationships through documented quality system validation.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Honeywell Research Chemicals |
| The Dow Chemical Company |
| Elan Chemical |
| Avantor Inc. |
| Thermo Fisher Scientific Inc. |
| LANXESS |
| Emerald Performance Materials |
| Merck KGaA |
| Others |
Supply Flow & Price Mechanics
Injectable drug manufacturers in North America and Europe concentrate procurement leverage through long-term supply agreements, locking in contract-based long-term offtake pricing with built-in toluene feedstock adjustment mechanisms. This buyer concentration feeds back into supply chain configuration, forcing producers to dedicate inventory positions with full batch pedigree documentation.
Pricing Analysis
Toluene feedstock volatility transmits directly into benzyl alcohol cost structures, with crude oil-linked aromatics pricing forcing continuous recalibration of contract terms. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels separates USP-certified parenteral material from REACH-compliant personal care supply and industrial coating inputs. Pricing pressure stems from parenteral drug pricing compression in North America, squeezing solvent cost tolerance for multi-dose vial formulations. Technical-grade buyers in coating and dye intermediates exhibit highest price sensitivity, while pharmaceutical-grade purchasers prioritize quality system validation over unit cost.
Supply Chain Analysis
Regional distribution centers in Shanghai chemical parks and Antwerp-adjacent hubs operate on hub-and-spoke patterns serving sterile injectable clusters in New Jersey, Basel, and Massachusetts. Manufacturing concentrates in China, Germany, and the United States, with Jiangsu province hosting densest cosmetic-grade capacity and Marl complex anchoring European pharmaceutical supply. Toluene feedstock, benzyl chloride intermediates, and analytical certification capacity constitute critical input dependencies. Single-source vulnerability runs through captive benzyl chloride supply among top three manufacturers, limiting spot market liquidity. Distribution runs through direct-to-formulator channels for pharmaceutical-grade volumes, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Benzyl alcohol functions as a regulatory compounder, with REACH authorization requirements for residual chlorides and benzaldehyde tightening thresholds and accelerating dedicated pharmaceutical-grade line investments across European supply chains.
For Market Incumbents: Acquire continuous liquid-liquid extraction and molecular distillation assets to defend pharmaceutical-grade margin pools against mid-scale hydrolysis-route competitors. Backward integration into toluene oxidation capacity in Shanghai or Marl secures feedstock cost control against crude oil volatility. Ion chromatography analytical capacity investment addresses EMA-recognized certificate of suitability revalidation demands. For New Entrants and Emerging Players: Capture biosimilar injectable qualification partnerships as EMA and FDA approval pathways open dedicated preservative-system supply programs for follow-on biologics. Technical-grade spot markets in India and Southeast Asia present most penetrable entry points with lower qualification overhead. Green chemistry process licensing from EU Green Deal funding streams offers differentiated positioning against legacy benzyl chloride hydrolysis producers. For Investors and Strategic Acquirers: Pharmaceutical-grade specialists with validated USP, EP, and NMPA quality systems are the most active acquirer targets in this space, commanding premia for documented batch pedigree capabilities. Long-term viability hinges on regulatory harmonization trajectory across FDA, EMA, and NMPA jurisdictions over the next decade. Watch NMPA impurity threshold convergence with REACH standards as inflection indicator for China domestic API manufacturing import substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Oxidation | Captive feedstock supply in Marl and Shanghai chemical parks insulates margin from crude-linked aromatics volatility. |
| Pharmaceutical-Grade Certification Investment | USP, EP, and NMPA monograph compliance opens multi-dose injectable preservative-system contracts with top ten formulators. |
| Direct-to-Formulator Distribution | Bypassing traditional chemical distributors in North America captures technical service relationships and inventory dedication. |
| Green Manufacturing Transition | Continuous toluene oxidation reactor designs reduce solvent waste and align with EU Green Deal funding eligibility. |
| Long-term Supply Agreement | Built-in price adjustment mechanisms with New Jersey and Basel sterile injectable manufacturers lock in volume commitments. |
Methodological Framework
Bottom-up injectable drug and cosmetic formulation modeling reconciled against top-down toluene derivative production tracking forms the analytical core of this study. Primary interviews with plant managers at backward-integrated manufacturers, procurement leads at parenteral drug OEMs, distribution channel partners in European chemical distribution networks, and technical R&D directors at fragrance compounders combined with secondary validation from customs and trade data, Cefic industry reports, SEC 10-K filings of listed chemical conglomerates, and FDA drug master file submissions. Triangulation across these sources ensures segmentation outputs reflect actual qualification tier volumes rather than capacity nameplate estimates.
Input-output matrix framing connects toluene feedstock availability, benzyl chloride intermediate conversion rates, and purification train throughput to end-use demand across pharmaceutical-grade, cosmetic-grade, and technical-grade segments. Grade tier, end-use industry, and regional production hub dimensions structure the segmentation model throughout the projection horizon. CAGRs derive from regression against historical pharmaceutical formulation growth patterns and REACH compliance cost escalation trajectories. Forecast inputs include biosimilar injectable pipeline maturation rates and NMPA standard convergence timelines with European thresholds.
Underlying measurement precision varies by segment; pharmaceutical-grade volumes carry tighter precision than technical-grade spot market estimates due to documented batch pedigree requirements. Forecasts reflect stated assumptions regarding regulatory harmonization pace and toluene feedstock price continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solvents
Trifluoroethanol Market
Solvents
Diethylene Glycol (DEG) Market
Solvents
Global Aliphatic Hydrocarbon Solvents Market
Solvents
N-Hexane Market
Solvents
Ultra-Low-VOC Methacrylate Reactive Diluents Market
Solvents
5-Isopropyl-M-Xylene Market
Solvents
Europe Acetonitrile Market
Solvents
Benzylamine Market
Solvents
Vapor Degreasing Solvents Market
Solvents
Nitroglycerin Market
Solvents
Global Chloroform Market
Solvents
N-Methyl Pyrrolidone Market
Solvents
North America Acetonitrile Market
Solvents
Dipropylene Glycol N-Propyl Ether Market
Solvents
Hydrocarbon Solvents Market
Solvents
Isoamylene Market