
 Benzalkonium Bromide Market | 2026-2036
Benzalkonium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Benzalkonium Bromide Market Outlook
China's Jiangsu province is narrowing the cost gap between domestic pharmaceutical-grade output and imported European supply. Dow Chemical leverages backward integration into alkylamine feedstocks to sustain margin stability across cyclical raw material swings. Stepan Company anchors North American disinfectant formulation channels through long-term supply agreements with institutional cleaning contractors.
Benzalkonium bromide is a quaternary ammonium salt composed of alkyl dimethyl benzyl ammonium bromide, typically supplied as a white crystalline powder or aqueous solution with active concentrations ranging from 50% to 80% w/w. It functions primarily as a cationic surfactant with broad-spectrum antimicrobial activity against bacteria, fungi, and enveloped viruses, serving industrial and commercial markets as a disinfectant, preservative, and phase-transfer catalyst. Pharmaceutical-grade material commands premium positioning due to stringent USP and EP monograph compliance requirements for parenteral and ophthalmic applications. Industrial-grade aqueous solutions dominate volume throughput in surface disinfection and sanitizers, where cost sensitivity among municipal and institutional buyers limits margin expansion.
EPA registration requirements for hard-surface disinfectants and FDA oversight of ophthalmic drug preservatives govern product specifications and market access in the United States. EMA and national competent authorities enforce European Pharmacopoeia monograph alignment for pharmaceutical-grade imports, while China's NMPA intensifies cGMP inspections of active pharmaceutical ingredient facilities. Stakeholders must monitor regulatory divergence between jurisdictions on acceptable impurity profiles and environmental discharge limits, as compliance cost differentials will increasingly determine competitive viability in cross-border supply arrangements.
Market Dynamics
REACH compliance in Europe and EPA surface disinfectant rule evolution are compressing impurity tolerances and forcing supplier qualification overhauls across pharmaceutical and industrial channels.
Growth Catalysts
- Ophthalmic formulation expansion:Pharmaceutical formulators in India are scaling procurement of pharmaceutical-grade material for preservative applications in eye drops and nasal sprays.
- REACH purity thresholds:Tightened European chemical registration requirements are disqualifying non-compliant suppliers and consolidating viable supply into cGMP-certified producers.
- Jiangsu-Shandong cluster scaling:China's chemical manufacturing hubs are expanding export-oriented pharmaceutical-grade capacity with NMPA-aligned quality systems.
Market Restraints
- Alkylamine feedstock volatility:Long-chain fatty amine price swings compress margins for non-integrated producers dependent on spot market sourcing.
- Single-region supply concentration:China's Jiangsu and Shandong provinces control disproportionate global pharmaceutical-grade output, creating geopolitical exposure.
- Quaternary ammonium substitution pressure:Polyhexamethylene biguanide and chlorine dioxide formulations are displacing benzalkonium bromide in certain hard-surface disinfection segments.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's tightening of active pharmaceutical ingredient oversight creates first-mover advantage for EU- and US-compliant suppliers establishing local technical partnerships.
- Biocide authorization alignment:The EU BPR review timeline offers window for compliant producers to secure Article 95 listing ahead of 2025-2026 reauthorization deadlines.
- Continuous flow synthesis adoption:Integration of microreactor technology with traditional batch processing is virtualizing quality consistency and reducing batch-to-batch variation for pharmaceutical-grade output.
Industry Challenges
- cGMP certification timelines:FDA and EMA inspection backlogs delay facility qualification, extending time-to-revenue for new pharmaceutical-grade production lines by 18-24 months.
- Analytical method harmonization:Divergent USP, EP, and ChP monograph requirements for alkyl chain distribution force redundant testing protocols and inventory segmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Benzalkonium Bromide Market |
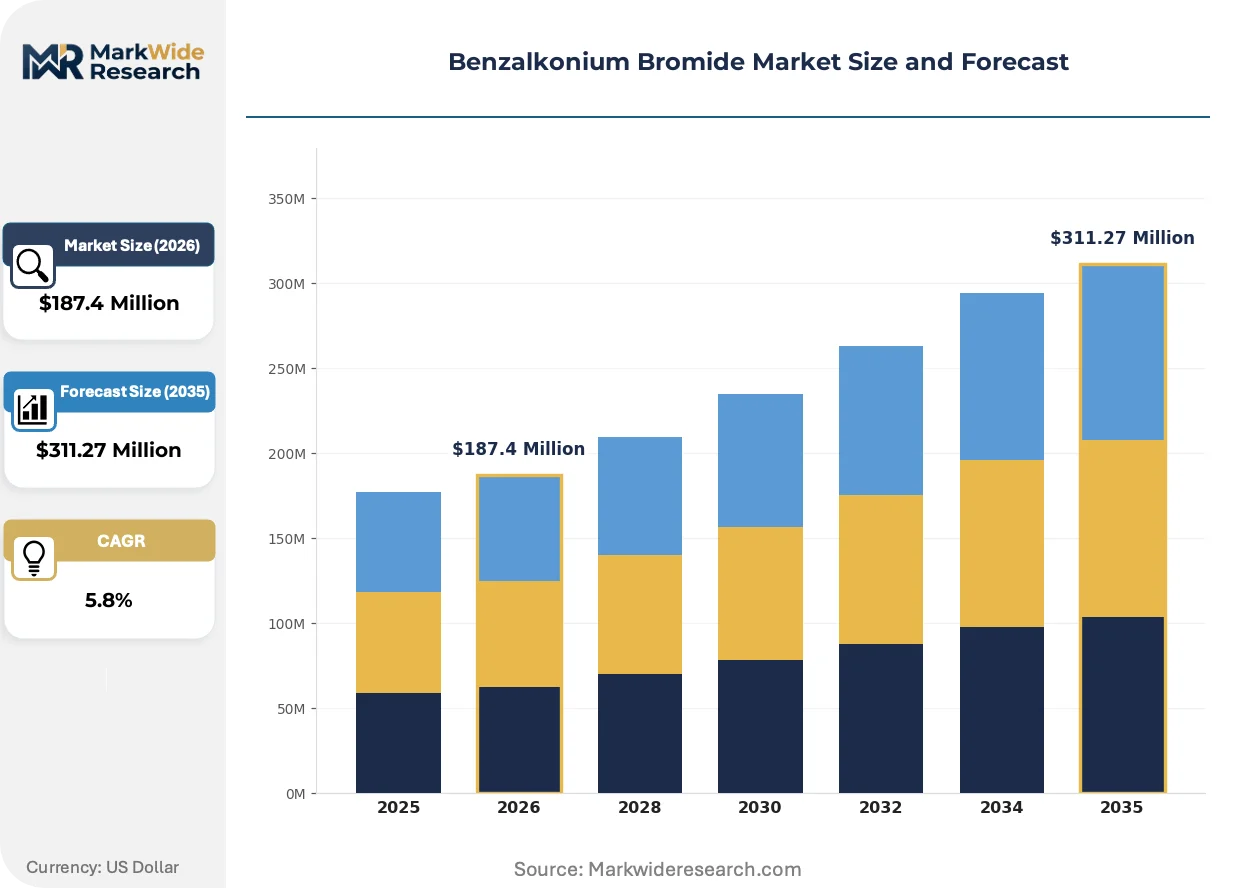
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Solutions, Emulsifiers, Disinfectants, Preservatives End Use Industry: Pharmaceuticals, Cosmetics, Textiles, Agriculture Grade: Industrial Grade, Pharmaceutical Grade, Cosmetic Grade, Food Grade Application: Surface Disinfection, Antiseptics, Sanitizers, Preservation |
| Companies Covered | AkzoNobel, Dow Chemical, Clariant, Stepan Company, LG Chem, Innospec, TCI Chemicals, Hubei Green Home Chemical, Vynova, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Benzalkonium Bromide Market Strategic Shifts
Digitalization of quality assurance and regulatory submission workflows is compressing compliance cycles while advanced manufacturing techniques reshape production economics for high-purity grades.
Continuous manufacturing platforms for quaternary ammonium synthesis are virtualizing batch record integrity and enabling real-time release testing for pharmaceutical applications. European and North American contract manufacturers are piloting these systems to reduce holding costs and accelerate FDA pre-approval inspection readiness. The technology is compressing working capital requirements for multi-product facilities serving both disinfectant and drug preservative markets.
EPA's evolving surface disinfectant efficacy testing protocols are forcing reformulation investments and label claim substantiation studies. Manufacturers must now generate additional virucidal and fungicidal data packages to maintain product registrations under revised OCSPP 810 guidelines. Hospital and long-term care procurement channels are prioritizing suppliers with complete emerging pathogen claim portfolios.
Formulator direct sourcing from API-grade producers is fragmenting traditional distributor channels in North American institutional cleaning markets. Large municipal and healthcare system buyers are establishing technical qualification programs that bypass regional chemical distributors. This pattern concentrates most visibly in California and Texas, where consolidated purchasing cooperatives negotiate multi-year supply agreements with cGMP-certified manufacturers.
Benzalkonium Bromide Market Segmentation
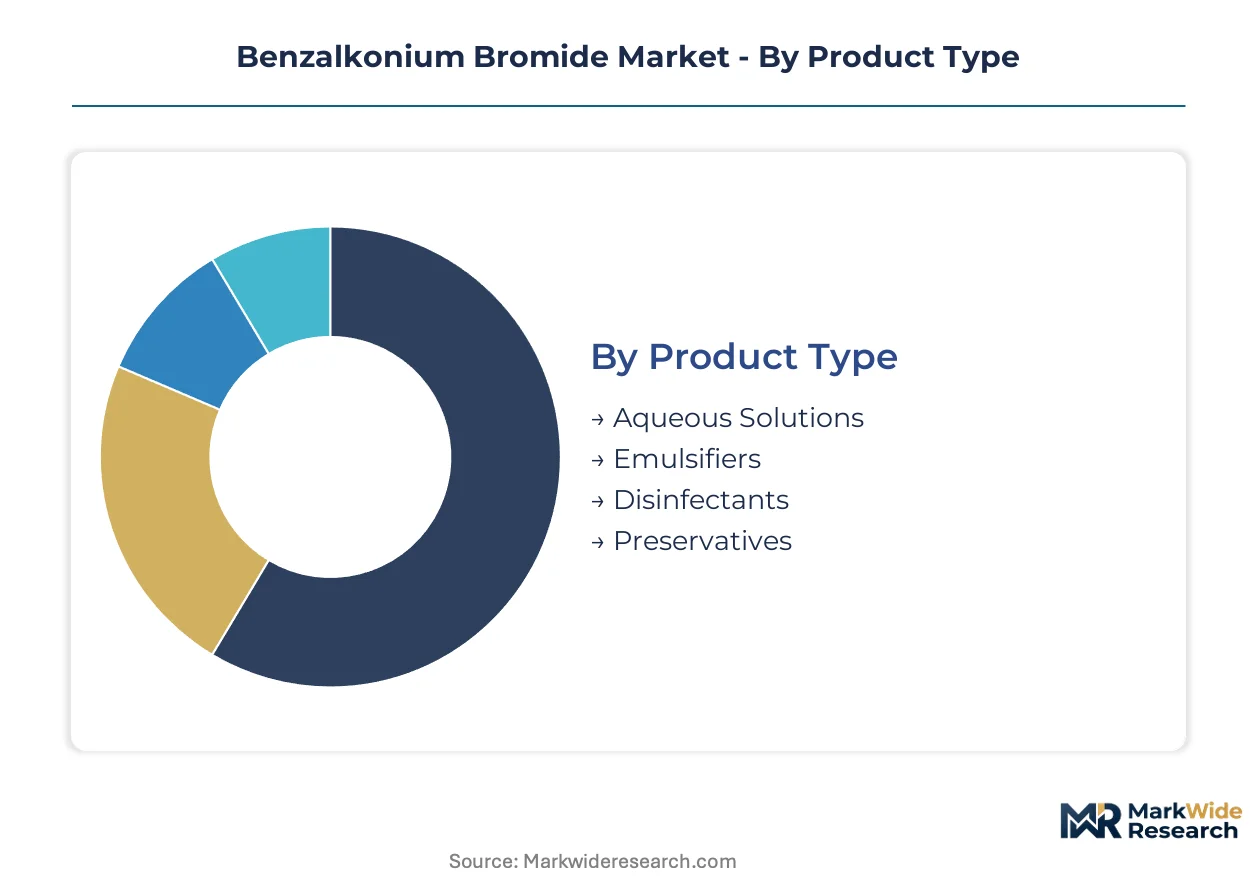
Benzalkonium bromide's functional versatility across antimicrobial, preservative, and surfactant roles creates distinct demand profiles by formulation type, purity threshold, and end-use specification. Each segmentation dimension carries divergent margin structures and regulatory compliance burdens that reshape supplier competitive positioning.
Product Type:
Cost tier differentiation separates commodity bulk formulations from value-added delivery systems with embedded technical service.
- Aqueous Solutions:Supplied at 50-80% w/w active concentration in water or ethanol carriers, these formulations dominate volume throughput in institutional cleaning and surface disinfection. Municipal procurement in Jiangsu province and Texas municipal cooperatives are consolidating purchases through direct manufacturer agreements, compressing distributor margins.
- Disinfectants:Ready-to-use and concentrate formulations for hard-surface applications carry EPA registration requirements and emerging pathogen claim substantiation under revised OCSPP 810 protocols. Hospital procurement channels in California and long-term care facilities are prioritizing suppliers with complete virucidal and fungicidal data packages.
- Emulsifiers:Cationic surfactant functionality supports phase-transfer catalysis and emulsion stabilization in industrial chemical synthesis.
- Preservatives:Pharmaceutical-grade material for ophthalmic and nasal preparations commands premium positioning due to USP and EP monograph compliance requirements.
Aqueous solutions hold installed capacity. Disinfectants are rotating up the share rankings.
End Use Industry:
Application maturity varies sharply across sectors, with pharmaceutical and cosmetics carrying stringent purity mandates against industrial agriculture's cost-driven specifications.
- Pharmaceuticals:Ophthalmic drug preservatives and parenteral formulations require USP-NF and EP monograph alignment with tight alkyl chain distribution controls. CDSCO's tightening API oversight in India is redirecting procurement toward EU- and US-compliant suppliers establishing local technical partnerships.
- Cosmetics:Personal care preservation applications face EU BPR reauthorization deadlines and emerging consumer preference for alternative chemistries in premium segments.
- Textiles:Antimicrobial finishing treatments for medical and consumer fabrics leverage benzalkonium bromide's substantivity to cellulose and synthetic fibers.
- Agriculture:Disinfectant applications in livestock housing and equipment sanitization compete on cost with chlorine dioxide and peroxygen alternatives.
Pharmaceuticals maintains specification leadership. Cosmetics is gaining share fastest amid formulation reformulation cycles.
Grade:
Purity threshold segmentation creates three-tier pricing stratification across certification levels, with pharmaceutical and food grades requiring cGMP facility investment.
- Industrial Grade:Standard aqueous solutions for surface disinfection and sanitizers serve municipal and institutional buyers where cost sensitivity limits margin expansion.
- Pharmaceutical Grade:USP and EP monograph compliance with documented alkyl chain distribution enables parenteral and ophthalmic applications. NMPA cGMP inspections of Jiangsu and Shandong facilities are intensifying qualification barriers for export markets.
- Cosmetic Grade:Intermediate purity tier serves personal care preservation with regional regulatory alignment for EU BPR and emerging market requirements.
- Food Grade:Sanitizer applications in food processing equipment face divergent national approvals and environmental discharge limits.
Industrial grade commands volume throughput. Pharmaceutical grade is climbing the fastest as ophthalmic formulation expansion accelerates.
Application:
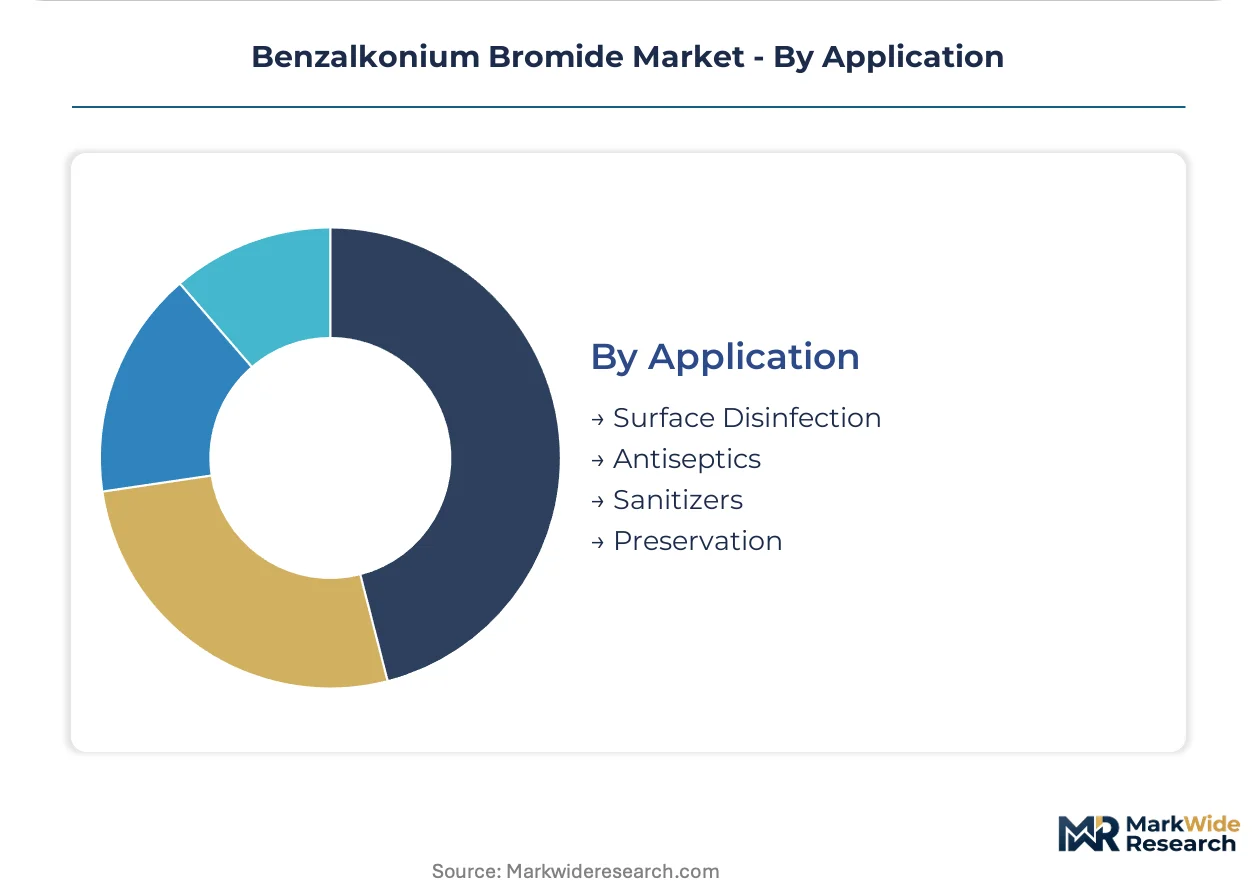
Functional use case segmentation maps directly to regulatory jurisdiction, with surface disinfection governed by EPA biocide rules and antiseptics falling under FDA or national pharmaceutical authority oversight.
- Surface Disinfection:Hard-surface sanitizers for healthcare, food service, and institutional settings constitute the largest volume application. EPA registration maintenance under evolving efficacy testing protocols is forcing reformulation investments and label claim substantiation studies.
- Preservation:Multi-dose ophthalmic and nasal spray formulations require pharmaceutical-grade material with demonstrated compatibility and stability profiles. Formulator direct sourcing from API-grade producers is fragmenting traditional distributor channels.
- Antiseptics:Skin and mucous membrane applications face competitive pressure from chlorhexidine and povidone-iodine alternatives in surgical preparation segments.
- Sanitizers:Hand hygiene and equipment sanitization applications expanded during public health emergency periods and are normalizing toward pre-crisis demand baselines.
Surface disinfection holds mature market position. Preservation is expanding most quickly on ophthalmic formulation growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. The United States prioritizes EPA-registered disinfectant formulations, while India and China drive pharmaceutical-grade procurement for ophthalmic applications. European markets emphasize REACH-compliant purity thresholds that reshape supplier qualification criteria.
United States
Hospital procurement channels and long-term care facilities drive demand for hard-surface disinfectants with emerging pathogen claims. EPA's revised OCSPP 810 efficacy testing protocols force reformulation investments and label substantiation studies. Texas municipal cooperatives and California healthcare systems consolidate purchases through direct manufacturer agreements, bypassing traditional distributor channels.
China
Jiangsu and Shandong province chemical clusters scale cGMP-compliant pharmaceutical-grade output for export markets. NMPA intensifies inspections of active pharmaceutical ingredient facilities, raising qualification barriers for international supply. Domestic producers narrow the cost gap with European imports while expanding capacity for ophthalmic and nasal preparation applications.
Germany
REACH compliance requirements disqualify non-compliant suppliers and consolidate viable supply into certified producers. EMA enforcement of European Pharmacopoeia monograph alignment governs pharmaceutical-grade import specifications. Industrial disinfectant formulators face tightened impurity tolerances that compress margins for non-integrated producers.
India
Pharmaceutical formulators scale procurement of pharmaceutical-grade material for preservative applications in multi-dose eye drops and nasal sprays. CDSCO's tightening of active pharmaceutical ingredient oversight redirects procurement toward EU- and US-compliant suppliers establishing local technical partnerships. Mumbai and Hyderabad manufacturing hubs drive regional demand concentration.
Japan
PMDA oversight of ophthalmic drug preservatives maintains stringent specifications for parenteral applications. METI-aligned industrial standards govern surface disinfection applications in healthcare and food processing settings. Osaka and Tokyo metropolitan areas concentrate formulation demand for high-purity grades.
Benzalkonium Bromide Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three distinct supplier archetypes: integrated petrochemical majors with captive alkylamine feedstocks, mid-scale specialty chemical producers with regional formulation partnerships, and API-grade specialists serving pharmaceutical channels. Competitive moves center on backward integration into long-chain fatty amine supply and direct procurement relationships with institutional buyers.
Within the integrated chemical tier, Dow Chemical exemplifies upstream control over alkylamine feedstocks that sustains margin stability across raw material cycles. Stepan Company anchors North American disinfectant formulation channels through established institutional cleaning contractor relationships. AkzoNobel and Clariant occupy positions bridging industrial and pharmaceutical-grade supply with European regulatory alignment.
| Leading Market Players |
|---|
| AkzoNobel |
| Dow Chemical |
| Clariant |
| Stepan Company |
| LG Chem |
| Innospec |
| TCI Chemicals |
| Hubei Green Home Chemical |
| Vynova |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Shandong province chemical clusters anchor global pharmaceutical-grade supply, concentrating margin capture with cGMP-certified producers while squeezing non-integrated formulators dependent on spot alkylamine markets. Long-term offtake agreements between institutional buyers and certified manufacturers now govern price discovery, displacing distributor-mediated spot transactions.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical-grade transactions, with three-tier pricing structure across pharmaceutical, cosmetic, and industrial grades. Price differentiation rests on USP and EP certification alignment plus alkyl chain distribution documentation. Cost compression in industrial aqueous solutions intensifies as municipal buyers consolidate procurement through direct manufacturer agreements. Institutional cleaning contractors exhibit highest price sensitivity, while ophthalmic formulators prioritize specification compliance over unit cost.
Supply Chain Analysis
Long-chain fatty amine feedstock supply concentrates in China, Germany, and the United States, with benzalkonium bromide production drawing from palm kernel oil and coconut oil derivatives. Single-region concentration in China's Jiangsu-Shandong corridor creates geopolitical exposure for pharmaceutical-grade supply. Distribution runs through direct technical partnerships with formulators, bypassing traditional chemical distributors in North American and European institutional channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service and regulatory compliance support now expand faster than commodity chemical sales, creating recurring revenue attachment opportunities for suppliers with cGMP certification and monograph alignment capabilities.
For Market Incumbents: Insulate pharmaceutical-grade positioning through backward integration into alkylamine feedstocks and accelerated FDA pre-approval inspection readiness. Polyhexamethylene biguanide substitution pressure in surface disinfection demands defensive capacity reallocation toward preservative applications. Channel control through direct procurement relationships with California and Texas healthcare systems reinforces margin stability. For New Entrants and Emerging Players: CDSCO-aligned technical partnerships in Mumbai and Hyderabad manufacturing hubs represent the most penetrable entry point for EU- and US-compliant suppliers. Microreactor-based continuous flow synthesis offers differentiation through batch-to-batch consistency for ophthalmic applications. First-mover positioning in Indian pharmaceutical manufacturing secures qualification ahead of intensifying API oversight. For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale specialty chemical producers with existing cGMP infrastructure and regional formulation partnerships in high-growth ophthalmic markets. Long-term viability hinges on regulatory alignment capabilities across USP, EP, and ChP monograph requirements. NMPA inspection intensity in Chinese export facilities signals inflection timing for supply chain diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkylamine Feedstocks | Dow Chemical's captive supply sustains margin stability across cyclical raw material swings. |
| cGMP Facility Certification Investment | FDA and EMA alignment opens pharmaceutical-grade channels with 18-24 month qualification timelines. |
| Continuous Flow Synthesis Adoption | Microreactor technology reduces batch-to-batch variation for ophthalmic preservative applications. |
| Direct Procurement Relationship Establishment | California and Texas healthcare systems bypass distributors for multi-year supply agreements. |
| Regulatory Compliance Service Layer Expansion | Technical partnerships with Indian formulators monetize CDSCO alignment expertise. |
Study Parameters
Operator-level perspectives from pharmaceutical formulators, institutional procurement managers, chemical plant engineers, and regulatory affairs specialists anchored the qualitative base. Primary fieldwork combined with secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and NMPA inspection disclosure records. Bottom-up capacity modeling and top-down demand triangulation cross-checked segment-level outputs.
Scenario-bracketing around feedstock price volatility, regulatory inspection intensity, and substitution elasticity shaped the analytical framework across the analysis window. Segmentation dimensions modeled include grade tier, end-use industry, application function, and regional production hub. CAGRs derived from normalized historical production data and forward capacity announcements, with alkylamine cost curves and ophthalmic formulation growth rates as key inputs.
Stress conditions across long-chain fatty amine price spikes, REACH impurity threshold tightening, and NMPA inspection backlog durations were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding cGMP certification timelines and regional regulatory divergence. Cross-checking against ECHA biocide authorization databases and FDA establishment inspection records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Benzenoid Market
Chemicals
Negative Photoresist Chemicals Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
LAMEA Dimethyl Phosphate Market
Chemicals
Saudi Arabia Construction Chemicals Market
Chemicals
Betaine Market
Chemicals
Global Pine Chemicals Market
Chemicals
Calcium Hydride Market
Chemicals
Thioacetic Acid Market
Chemicals
4-Dichlorodiphenyl Sulfone (DCDPS) Market
Chemicals
Deicing Fluid Market
Chemicals
Benzoyl Alcohol Market
Chemicals
Bakers Ammonia Market
Chemicals
Egypt Acidulants Market
Chemicals
Phosphotungstic Acid Market
Chemicals
HATU Market