
 Ammonium Bromide Market | 2026-2036
Ammonium Bromide Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Bromide Market Analysis
Process intensification in bromine extraction and purification is narrowing the cost gap between technical and pharmaceutical grades. Albemarle leverages captive bromine reserves in Arkansas and Jordan to sustain feedstock security across its ammonium bromide portfolio. ICL anchors its position through integrated Dead Sea operations that control upstream bromine supply. Jordan Bromine competes on geographic proximity to European and Middle Eastern offtake markets.
Ammonium bromide is an ionic salt with the formula NH₄Br, typically synthesized via neutralization of hydrobromic acid with ammonia and available in purities ranging from technical grade to pharmaceutical grade meeting USP/NF monographs. The compound functions primarily as a bromine donor in flame retardant formulations, photographic emulsions, and oilfield completion fluids. Pharmaceutical grade commands premium positioning due to API validation requirements and FDA compliance overhead, while technical grade dominates volume throughput in industrial flame retardant applications. Oilfield chemicals represents a structurally growing application segment as shale operators deepen reliance on high-density clear brines.
EPA oversight of brominated flame retardants under TSCA Section 6 risk evaluation shapes product reformulation timelines and substitution dynamics in the US market. China's MEE enforces discharge limits on bromine processing facilities, elevating compliance costs for producers serving domestic and export channels. REACH registration requirements in Europe constrain market access for non-compliant imports. Stakeholders must track evolving fire safety codes in major construction markets and assess backward integration options against regulatory-driven cost escalations.
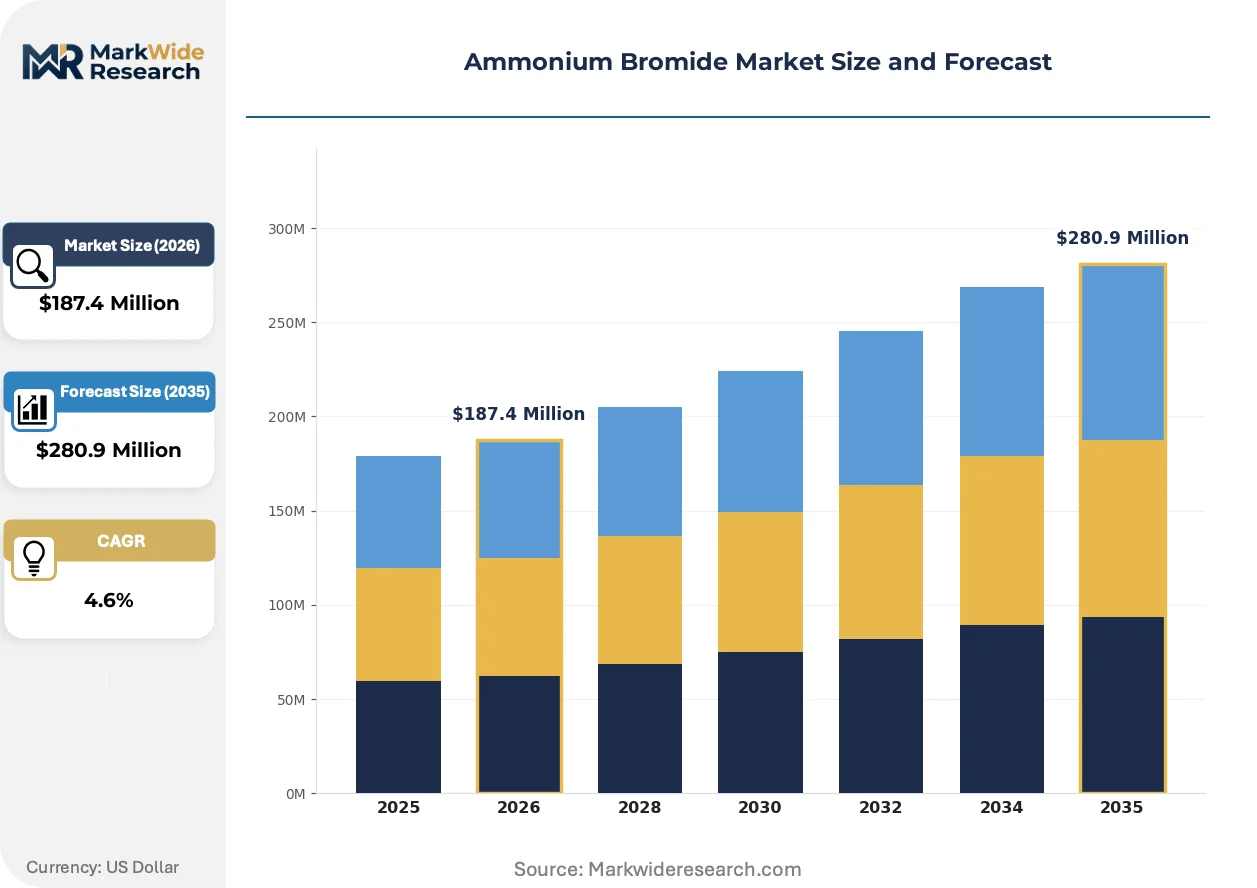
Market Dynamics
Process intensification in bromine extraction and purification is narrowing the cost gap between technical and pharmaceutical grades, compressing margin structures and forcing repositioning across the value chain. This structural shift reshapes competitive boundaries between industrial chemical suppliers and API-grade specialists.
Growth Catalysts
- GB standards tightening:China's fire safety codes for construction materials are mandating higher bromine content in flame retardant formulations, pulling additional ammonium bromide volume into building applications.
- Shale brine density requirements:Oilfield operators in North American basins are deepening reliance on high-density clear brines for well completion, structurally expanding ammonium bromide consumption in drilling chemistry.
- Photographic emulsion stabilization:Specialty chemical formulators in Japan continue sourcing pharmaceutical-grade ammonium bromide for silver halide crystal growth control in traditional film and industrial X-ray applications.
Market Restraints
- Bromine feedstock concentration:Over half of global elemental bromine originates from Dead Sea extraction operations controlled by two integrated producers, creating supply vulnerability for non-captive processors.
- REACH registration burden:European chemical importers face escalating compliance costs for ammonium bromide dossier maintenance, constraining market access for smaller traders without in-house regulatory functions.
- Phosphorus-nitrogen retardant substitution:Intumescent coating formulators in EU construction markets are partially displacing brominated systems to preempt regulatory scrutiny under persistent organic pollutant frameworks.
Strategic Opportunities
- India pharmaceutical API expansion:CDSCO's accelerated approval pathways for generic active ingredients create entry points for USP-grade ammonium bromide suppliers serving domestic and export formulation houses.
- Energy storage electrolyte chemistry:Zinc-bromine flow battery developers are validating ammonium bromide as a bromine complexing agent, opening a nascent demand channel outside traditional applications.
- Direct-to-compounder distribution:Flame retardant masterbatch producers in China's Jiangsu and Zhejiang corridors are bypassing distributors to source technical-grade material directly from bromine derivative manufacturers.
Industry Challenges
- Pharmaceutical validation timelines:API-grade producers face 18-24 month FDA compliance cycles for new manufacturing sites, delaying market entry despite technical readiness.
- Bromine processing emissions control:MEE discharge limits in China require capital-intensive scrubbing and wastewater treatment retrofits at extraction facilities, elevating fixed cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Bromide Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Pharmaceutical Grade, Food Grade, Industrial Grade Application: Flame Retardants, Photographic Chemicals, Water Treatment, Oilfield Chemicals End User: Pharmaceuticals, Electronics, Agriculture, Chemicals Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Albemarle, Lanxess, ICL, Jordan Bromine, Great Lakes, Perekop Bromine, Morre-TEC, Dhruv Chem, American Elements, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Bromide Market Emerging Trajectories
Continuous flow neutralization reactors are displacing batch synthesis in ammonium bromide production, enabling real-time quality adjustment and reducing in-process inventory. This equipment transition is compressing capital recovery timelines and reshaping plant economics across the supply base.
Membrane electrodialysis purification is rendering obsolete traditional crystallization sequences for technical-grade material. Chinese chemical processors in Shandong province are adopting this technology at scale. The shift enables simultaneous salt fractionation and water recovery, collapsing energy intensity per ton of finished product.
EPA's TSCA Section 6 risk evaluation for brominated flame retardants is forcing reformulation commitments from US-based building product manufacturers. The industrial consequence is accelerated qualification of alternative ammonium bromide grades in polymer systems previously dominated by decabromodiphenyl ether. Construction material suppliers in the US Southeast are responding by dual-sourcing technical grades from both domestic and Middle Eastern supply channels.
Specification-driven purchasing is consolidating buyer power among flame retardant masterbatch compounders. Large polymer processors are unbundling technical service from material supply, negotiating direct volume contracts with bromine derivative producers while retaining independent formulation consultants. This pattern is most visible in China's Yangtze River Delta manufacturing belt, where automotive and electronics OEMs are pushing compliance documentation requirements upstream to chemical suppliers.
Ammonium Bromide Market Segmentation
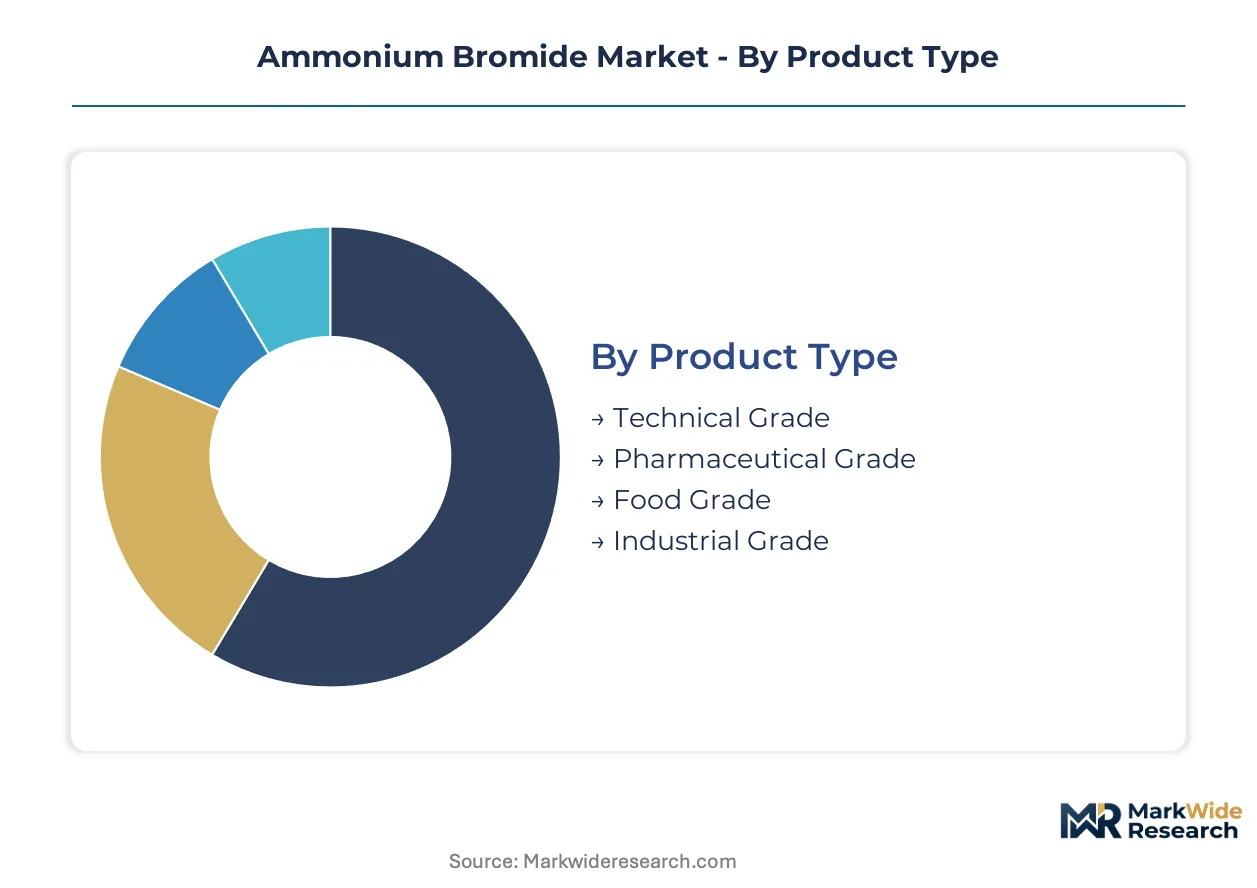
Segmentation in ammonium bromide reveals how purity specifications, application chemistry, and channel economics fragment a seemingly commoditized salt into distinct value tiers with divergent margin profiles and regulatory exposure.
Product Type:
Cost tier differentiation separates commodity volume from validated specialty grades, with each tier commanding distinct specification protocols and customer qualification barriers.
- Technical Grade:Material meeting industrial purity specifications serves flame retardant formulators and oilfield brine compounders. Demand concentrates in China's Jiangsu and Zhejiang manufacturing corridors where construction and electronics OEMs mandate GB-standard fire safety compliance.
- Pharmaceutical Grade:USP/NF monograph-compliant material undergoes API validation cycles and FDA facility registration. Japanese photographic chemical manufacturers in Shizuoka and Kanagawa prefectures source this grade for silver halide crystal growth control in industrial X-ray emulsions.
- Food Grade:Material meeting food additive purity standards for limited specialty applications.
- Industrial Grade:Broad-spectrum material for non-critical chemical processing and intermediate synthesis.
Technical Grade holds installed capacity. Pharmaceutical Grade is rotating up the share rankings.
Application:
Application chemistry determines bromine donor efficiency requirements, with each use case imposing distinct solubility, thermal stability, and compatibility specifications on the ammonium salt.
- Flame Retardants:Bromine content enables gas-phase radical quenching in polymer systems. Construction material suppliers across China's Yangtze River Delta respond to tightening GB standards by dual-sourcing technical grades from domestic and Jordanian supply channels.
- Oilfield Chemicals:High-density clear brines for well completion require precise density control and formation compatibility. North American shale operators in the Permian and Bakken basins deepen reliance on ammonium bromide for drilling chemistry as lateral lengths extend.
- Photographic Chemicals:Silver halide crystal growth modulation in traditional film and industrial radiography applications.
- Water Treatment:Limited specialty applications in industrial cooling and process water systems.
Flame Retardants holds installed capacity. Oilfield Chemicals is rotating up the share rankings.
End User:
Customer type segmentation exposes how regulatory proximity and formulation complexity shape procurement sophistication, from validated API supply chains to commodity chemical purchasing.
- Chemicals:Industrial chemical processors and bromine derivative manufacturers represent the foundational demand layer. Chinese chemical processing corridors in Shandong province absorb technical-grade volume for downstream formulation and re-export.
- Electronics:Flame retardant masterbatch compounders serving PCB laminates and connector housings. Specification-driven purchasing consolidates buyer power among large polymer processors in South Korea's Gyeonggi-do electronics belt.
- Pharmaceuticals:API manufacturers and generic formulation houses requiring validated supply chains.
- Agriculture:Limited specialty applications in soil fumigation and biocide intermediates.
Chemicals holds installed capacity. Electronics is rotating up the share rankings.
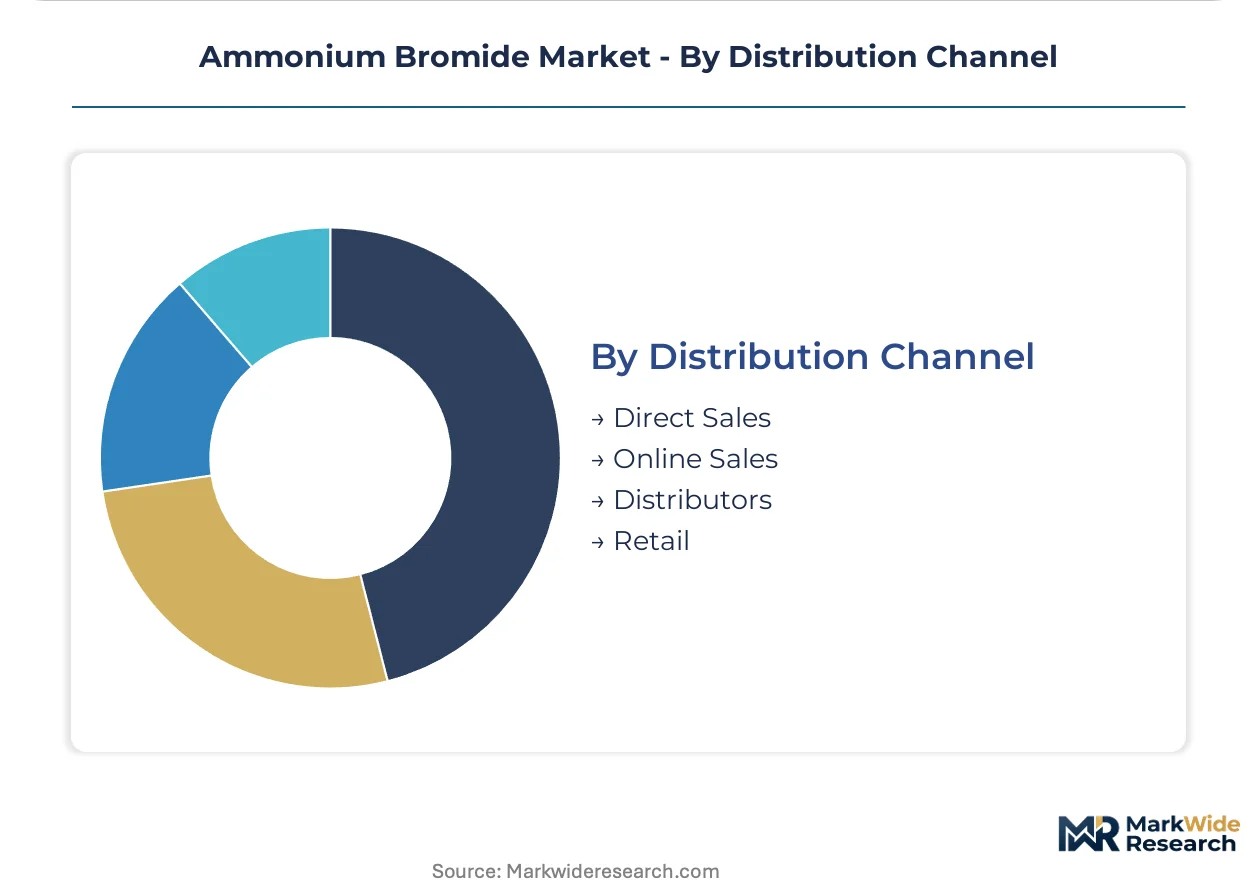
Distribution Channel:
Channel configuration reflects buyer scale and specification intensity, with direct relationships displacing intermediaries where compliance documentation requirements intensify.
- Direct Sales:Volume contracts between bromine derivative producers and flame retardant masterbatch compounders. China's automotive and electronics OEMs push compliance documentation upstream, forcing direct procurement relationships in the Yangtze River Delta.
- Distributors:Regional chemical distributors serve mid-scale formulators lacking in-house regulatory functions. REACH registration burdens in Europe constrain distributor viability for non-compliant import streams.
- Online Sales:Limited to standardized technical-grade material for research and small-batch industrial use.
- Retail:Minimal presence confined to laboratory chemical suppliers and specialty reagent vendors.
Direct Sales holds installed capacity. Distributors is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in ammonium bromide tilt toward surplus in bromine-rich economies while manufacturing-heavy importers absorb derivative volumes. China and Jordan dominate outbound trade in technical grades, whereas Japan and Germany concentrate pharmaceutical-grade imports for specialty chemical processing.
China
Flame retardant masterbatch compounders in Jiangsu and Zhejiang provinces drive technical-grade consumption as construction OEMs enforce GB 8624 fire safety codes. MEE discharge limits on bromine extraction facilities elevate compliance costs for Shandong-based processors. Chemical processing corridors along the Yangtze River Delta absorb domestic output while re-exporting formulated derivatives.
United States
Shale operators in the Permian and Bakken basins deepen offtake of high-density clear brines for extended lateral completions. EPA TSCA Section 6 risk evaluations force reformulation timelines in brominated flame retardant applications. Arkansas-based captive bromine reserves feed downstream ammonium bromide production for domestic oilfield chemical supply.
Germany
REACH registration burdens constrain non-compliant import streams, favoring established EU-registered suppliers. Industrial chemical distributors in North Rhine-Westphalia manage technical-grade inventory for flame retardant compounders serving automotive OEMs. ECHA dossier maintenance costs filter smaller traders from active market participation.
Japan
Photographic chemical manufacturers in Shizuoka and Kanagawa prefectures source pharmaceutical-grade material for silver halide crystal growth control. METI industrial standards govern purity specifications for industrial X-ray emulsion applications. Specialty chemical formulators maintain validated supply chains despite contracting traditional film volumes.
Jordan
Dead Sea extraction operations anchor elemental bromine supply for integrated derivative production. Geographic proximity to European and Middle Eastern offtake markets reduces logistics costs for technical-grade exports. Jordanian producers compete on delivery reliability to construction chemical distributors in Turkey and Egypt.
Ammonium Bromide Market Vendor Landscape
On the supply side, the industry is bifurcated between integrated bromine producers with captive feedstock and non-captive processors exposed to raw material volatility. Consolidation around Dead Sea extraction operations creates supply vulnerability for derivative manufacturers lacking upstream control. Two strategic archetypes dominate: integrated majors leveraging resource ownership, and regional specialists competing on geographic proximity to end-use clusters. Competitive moves center on backward integration into bromine extraction and direct-to-compounder distribution bypass.
Among integrated majors, Albemarle and ICL exemplify the captive-resource archetype, anchoring market positioning through controlled upstream bromine supply. Jordan Bromine occupies a position within the geographic-proximity tier, serving Middle Eastern and European markets from Dead Sea-adjacent operations. Lanxess represents the diversified chemical conglomerate model, sitting within a broader portfolio of bromine derivatives rather than pure-play ammonium bromide specialization.
| Leading Market Players |
|---|
| Albemarle |
| Lanxess |
| ICL |
| Jordan Bromine |
| Great Lakes |
| Perekop Bromine |
| Morre-TEC |
| Dhruv Chem |
| American Elements |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Dead Sea bromine extraction determines both pricing tier spreads and supply chain shape, compressing margin structures for non-captive processors while amplifying premium capture for integrated majors. This structural concentration forces derivative manufacturers to absorb feedstock volatility or surrender pricing power to upstream owners.
Pricing Analysis
Batch-to-continuous reactor technology gaps separate pricing tiers, with legacy producers commanding lower technical-grade quotes against membrane-electrodialysis adopters in Shandong province. Contract-based long-term offtake dominates volume transactions, while spot purchases concentrate among research-scale buyers. Price differentiation hinges on USP/NF certification overhead and captive bromine supply security. Cost compression in technical-grade runs through membrane technology adoption, eroding legacy batch-process margins. Pharmaceutical-grade buyers exhibit least price sensitivity due to API validation lock-in, whereas flame retardant masterbatch compounders in Jiangsu and Zhejiang provinces drive hardest bargain on technical-grade volume.
Supply Chain Analysis
Elemental bromine extraction in Jordan, Israel, and Arkansas anchors upstream supply, with Chinese processors in Shandong and Jiangsu provinces dominating downstream derivative production. Feedstock draws from Dead Sea evaporation ponds and Arkansas brine reserves, while ammonium neutralization capacity clusters near construction and electronics manufacturing corridors. Single-source vulnerability concentrates in Dead Sea operations controlled by two integrated producers, exposing non-captive processors to allocation risk. Distribution runs through direct volume contracts between bromine derivative producers and flame retardant masterbatch compounders, with regional chemical distributors serving mid-scale formulators lacking in-house regulatory functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonium bromide supply chains are approaching a platform-economics inflection as validated API-grade supply chains and direct-to-compounder distribution networks achieve interoperability, collapsing traditional intermediary layers.
For Market Incumbents: Harden captive bromine reserve positions through lease extensions or joint development agreements at Arkansas and Dead Sea extraction sites, insulating against feedstock allocation risk from upstream concentration. Deepen direct procurement relationships with flame retardant masterbatch compounders in China's Yangtze River Delta, preempting distributor disintermediation by offering bundled compliance documentation and technical service unbundling from material supply. For New Entrants and Emerging Players: CDSCO-accelerated generic API pathways in India represent the most penetrable entry point for USP-grade ammonium bromide suppliers, with domestic formulation houses and export-oriented generic manufacturers underserved by validated supply chains. Zinc-bromine flow battery electrolyte chemistry offers a second white-space target, with bromine complexing agent validation creating early-mover positioning ahead of commercial scale-up. Go-to-market execution should anchor in technical partnership models with battery developers rather than commodity chemical distribution. For Investors and Strategic Acquirers: Non-integrated pharmaceutical-grade specialists with pending FDA facility registrations and established Japanese photographic chemical relationships present the most attractive acquisition archetype, capturing validated supply chain premiums without upstream capital intensity. Long-term viability hinges on bromine feedstock security and regulatory compliance infrastructure rather than volume scale. Monitor EPA TSCA Section 6 risk evaluation timelines as inflection indicator, with accelerated brominated flame retardant restrictions potentially triggering consolidation waves among reformulation-dependent processors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bromine Extraction | Captive Dead Sea or Arkansas brine reserves eliminate feedstock allocation vulnerability for derivative manufacturers. |
| Membrane Electrodialysis Adoption | Shandong-based processors collapse energy intensity per ton against legacy crystallization sequences. |
| Direct-to-Compounder Distribution | Yangtze River Delta OEM compliance documentation requirements force bypass of regional chemical distributors. |
| USP-Grade FDA Facility Registration | 18-24 month validation cycles create qualification barriers protecting premium positioning against technical-grade competitors. |
| Zinc-Bromine Flow Battery Partnership | Bromine complexing agent validation opens nascent demand channel outside traditional flame retardant and oilfield applications. |
Methodological Framework
Initial hypotheses were tested against primary input from bromine extraction facility managers, flame retardant procurement leads at polymer OEMs, pharmaceutical API manufacturing directors, and oilfield chemical supply specialists, and refined through secondary validation against customs/trade data, ACC industry reports, EPA TSCA filing disclosures, and SEC 10-K chemical segment disclosures. Bottom-up capacity and consumption estimates were triangulated against top-down trade flow analysis across the analysis window.
Demand-supply-balance framing anchored the quantitative model, with segmentation dimensions spanning grade tier (technical/pharmaceutical), end-use industry (flame retardants/oilfield chemicals/photographic), and regional production hub. CAGRs were derived from installed capacity utilization trends and end-use consumption intensity ratios. Industry-specific forecast inputs incorporated GB standard fire safety code evolution in China and shale lateral length extension trajectories in North American basins.
Practitioners should monitor EPA TSCA Section 6 risk evaluation publication timelines, MEE discharge limit enforcement intensity at Shandong extraction facilities, and zinc-bromine flow battery commercial deployment announcements for early signals of forecast revision. Cross-checking against IEA critical minerals supply chain assessments and ECHA REACH registration status databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
United States Lime Market
Bulk Chemicals
Global Sebacic Acid Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Global Sodium Chlorate Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Calcium Sulfite Market
Bulk Chemicals
3-Mercapto-2-Pentanone Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Ethylene Dichloride Market
Bulk Chemicals
Antimony Trioxide Market
Bulk Chemicals
Potassium Chloride Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Sodium Gluconate Market
Bulk Chemicals
Global Lithium Derivatives Market