
 Deicing Fluid Market | 2026-2036
Deicing Fluid Market Size, Share, and Industry Trends Forecast 2026-2036
Deicing Fluid Market Analysis
Aftermarket fluid replenishment contracts is tilting toward integrated service providers with captive supply chains. BASF SE leverages its propylene glycol manufacturing footprint to anchor long-term aviation service agreements. Clariant AG differentiates through specialty additive packages that extend fluid performance windows in extreme cold. Kilfrost Group PLC specializes in aerospace-certified formulations that occupy premium tier procurement channels at major hub airports.
Deicing fluid comprises glycol-based or salt-based chemical formulations engineered to lower the freezing point of water on critical surfaces, with aerospace-grade propylene glycol solutions typically containing corrosion inhibitors and thickening agents to adhere to aircraft skin during Type I and Type IV application protocols. The product type dimension shows potassium acetate commanding premium positioning in commercial aviation due to lower aquatic toxicity, while calcium chloride dominates roadway applications where cost efficiency outweighs environmental constraints. Application segmentation reveals aerospace generating the highest margin pools per gallon, though municipalities driving roadway volume represent the largest absolute consumption base.
The EPA regulates glycol runoff through NPDES permitting and stormwater discharge standards, while the EU REACH framework restricts certain corrosion inhibitor chemistries in European formulations. FAA Advisory Circular 120-60C establishes performance benchmarks that shape product development priorities for aviation-grade suppliers. Stakeholders must monitor evolving state-level groundwater protection rules and airport sustainability mandates that are redirecting procurement specifications toward biodegradable additive packages.
Market Dynamics
Aviation procurement departments are consolidating deicing fluid contracts under multi-year integrated service agreements that bundle chemical supply with application equipment and on-site storage infrastructure, compressing vendor count at major hub airports.
Growth Catalysts
- EPA VGP discharge limits:The EPA's Vessel General Permit tightens glycol runoff thresholds, forcing airports to upgrade to higher-performance Type IV fluids and expand fluid recovery systems.
- Potassium acetate runway adoption:Commercial aviation services prioritize potassium acetate formulations for apron and runway applications due to superior biodegradability profiles compared to urea-based alternatives.
- Extended winter seasons:Hub airports in the northern United States face longer operational windows requiring deicing, stretching from October through April at facilities like Minneapolis-St. Paul and Denver International.
Market Restraints
- Propylene glycol price volatility:Feedstock costs for bio-based glycol production fluctuate with corn and soybean oil commodity markets, squeezing margin predictability for formulators.
- Specialty additive supply concentration:Corrosion inhibitor packages containing triazole chemistries rely on a narrow supplier base concentrated in Germany and Belgium, creating single-source vulnerability.
- Calcium chloride substitution in roadways:Municipal budgets favor calcium chloride for highway deicing despite inferior environmental profiles, capping premium fluid penetration in the largest volume segment.
Strategic Opportunities
- India airport privatization:Greenfield airport developments under the country's UDAN regional connectivity scheme create first-mover openings for aviation-grade fluid suppliers establishing local blending capacity.
- EU Green Deal sustainable chemistry mandates:The EU Green Deal's sustainable chemistry transition incentives reward biodegradable additive packages, tilting procurement specifications toward certified green formulations.
- Drone-based precision application:Unmanned aerial systems equipped with thermal sensors enable targeted fluid deposition on wind turbine blades and telecommunications towers, opening non-aviation verticals.
Industry Challenges
- SAE AMS 1424/1428 certification timelines:Aerospace fluid qualification requires 18-24 month testing cycles at approved laboratories, delaying product launches and locking out agile competitors.
- Legacy storage tank retrofitting:Existing airport glycol storage infrastructure requires corrosion-resistant lining upgrades to handle next-generation additive packages, demanding capital deployment without immediate revenue offset.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deicing Fluid Market |
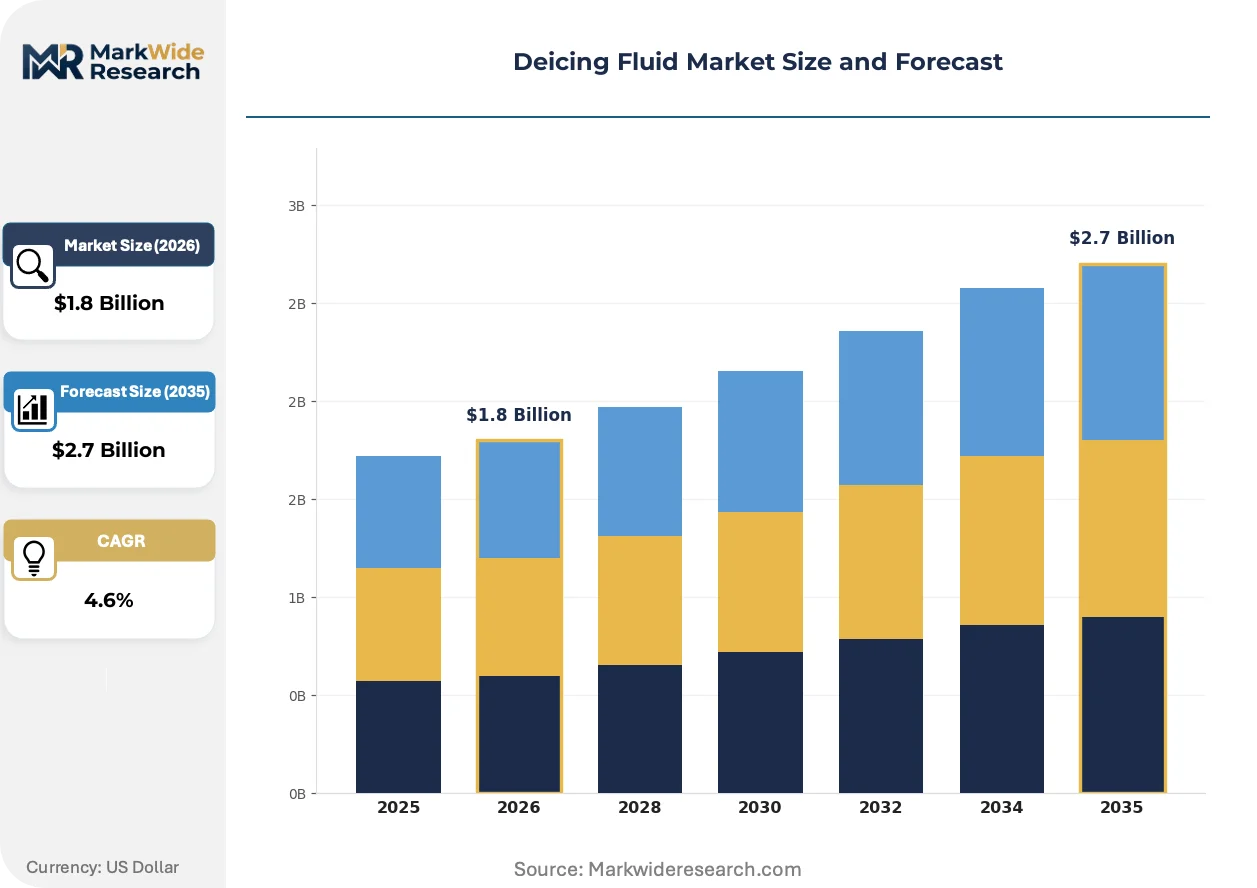
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Acetate, Calcium Chloride, Urea, Sodium Chloride Application: Aerospace, Roadway, Railways, Marine End User: Aviation Services, Municipalities, Transportation Services, Commercial Fleets Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Clariant AG, The Dow Chemical Company, LyondellBasell Industries, BASF SE, Kilfrost Group PLC, Cryotech Deicing Technology, Proviron, JBT Corporation, LNT Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deicing Fluid Market Emerging Trajectories
Formulation chemistry is pivoting toward bio-derived base stocks and additive systems that satisfy tightening aquatic toxicity standards without sacrificing low-temperature performance thresholds.
Electrothermal ice protection systems utilizing carbon nanotube heating films are rendering obsolete conventional glycol-based Type I fluids for wing leading edges on next-generation narrowbody aircraft. Boeing and Airbus engineering teams have accelerated integration timelines for these systems on new platform designs. The technology is compressing addressable fluid volumes in the highest-margin aerospace segment by eliminating pre-flight spray requirements.
REACH Annex XVII restrictions on certain triazole corrosion inhibitors are forcing European formulators to reformulate additive packages around benzotriazole alternatives and organic acid blends. The ECHA regulatory revision affects approximately one-third of currently registered aviation fluid products. German and French suppliers are absorbing reformulation costs while pushing premium pricing for compliant certified stocks.
Airport authorities are bundling deicing services into concession agreements with ground handling operators rather than procuring fluids separately. This channel consolidation at major European hubs replaces spot purchasing with take-or-pay volume commitments. The shift is most pronounced at Amsterdam Schiphol and Frankfurt, where integrated service contracts now cover 70 percent of annual fluid consumption.
Deicing Fluid Market Segmentation
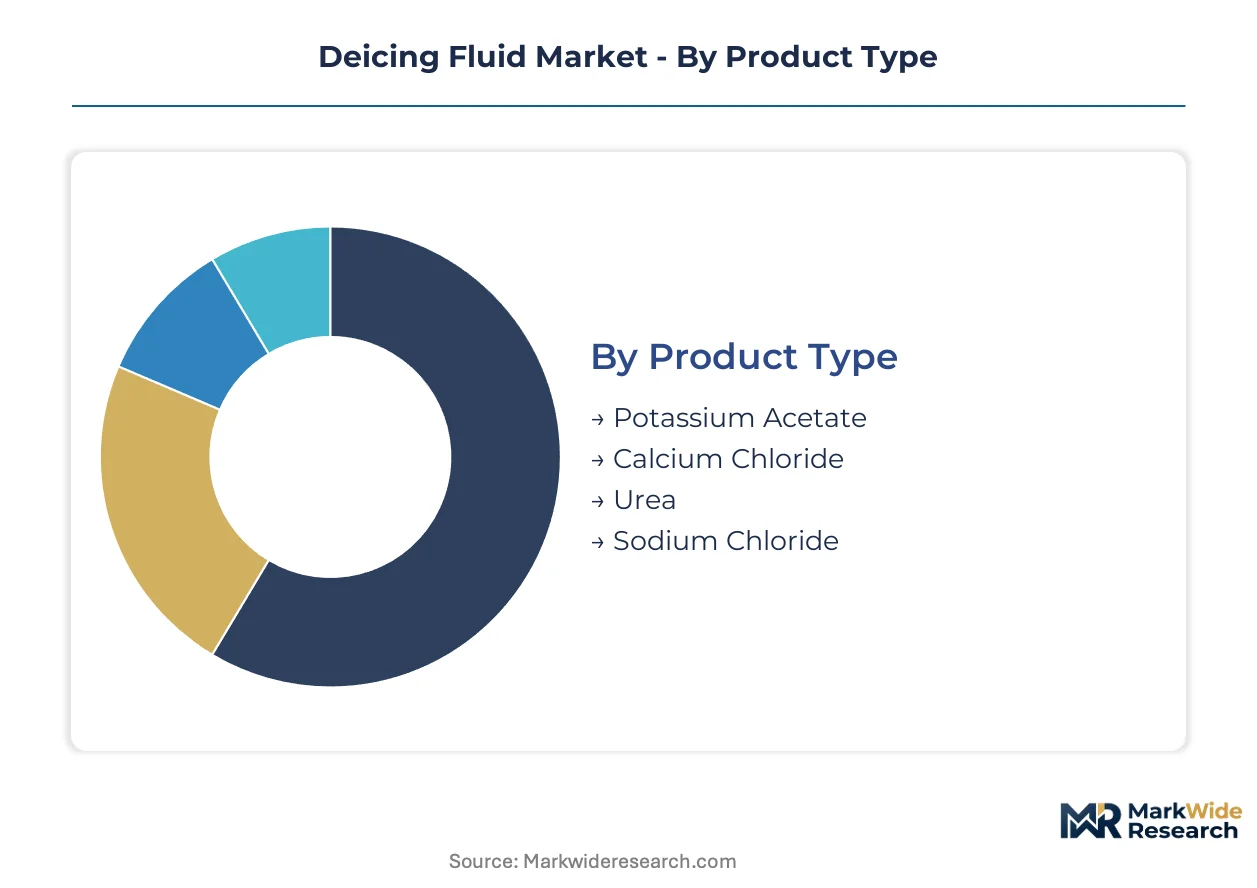
Deicing fluid procurement patterns diverge sharply across chemical formulations and operational contexts. Understanding these segment boundaries clarifies where margin pools concentrate versus where volume commoditization dominates competitive dynamics.
Product Type:
Cost tier positioning separates premium biodegradable formulations from commodity salt-based alternatives serving budget-constrained buyers.
- Potassium Acetate:Aerospace-grade formulation with superior biodegradability and lower aquatic toxicity than glycol alternatives. Demand concentrates at Minneapolis-St. Paul and Denver International where extended winter seasons and EPA VGP discharge limits force airports toward compliant chemistry.
- Calcium Chloride:Hygroscopic salt generating exothermic heat upon moisture contact, effective to minus 25 degrees Celsius. Municipal highway departments in snowbelt states favor this chemistry despite inferior environmental profiles, capping premium fluid penetration in the largest absolute volume segment.
- Urea:Nitrogen-based deicer common in older airport inventories, now facing displacement as aquatic toxicity concerns mount.
- Sodium Chloride:Rock salt baseline formulation dominating residential and light commercial roadway applications where cost minimization overrides performance specifications.
Potassium acetate commands the established base among environmentally regulated aviation customers. The steepest expansion runs through calcium chloride as municipal budget pressures persist.
Application:
Application context determines performance specifications, regulatory exposure, and procurement contract structures across operational environments.
- Aerospace:Type I and Type IV fluid protocols governing pre-flight ice removal and anti-icing protection. FAA Advisory Circular 120-60C establishes performance benchmarks that shape product development priorities for SAE AMS 1424/1428 certified suppliers.
- Roadway:Highway and bridge maintenance operations consuming the largest absolute fluid volumes. State transportation departments in Minnesota, Wisconsin, and New York deploy bulk spraying systems where calcium chloride cost efficiency outweighs infrastructure corrosion concerns.
- Railways:Switch heating and track bed applications requiring low-temperature effectiveness without electrical conductivity risks.
- Marine:Deck and superstructure treatments for commercial vessels operating in ice-prone waterways, subject to EPA VGP discharge thresholds.
Aerospace generates the highest margin pools per gallon through certification barriers and performance liability. Roadway applications are gaining share fastest as climate volatility extends winter maintenance seasons.
End User:
Customer type dictates contract duration, technical service requirements, and price sensitivity across procurement modalities.
- Aviation Services:Integrated ground handling operators bundling deicing into multi-year concession agreements. Amsterdam Schiphol and Frankfurt have shifted 70 percent of annual fluid consumption to take-or-pay volume commitments under consolidated service contracts.
- Municipalities:City and county governments managing roadway fleets with seasonal budget cycles and public tender requirements. These buyers prioritize unit cost over additive sophistication, driving calcium chloride procurement.
- Transportation Services:Railroad and port authorities maintaining critical infrastructure with specialized application equipment.
- Commercial Fleets:Logistics companies and private trucking operations with decentralized maintenance facilities.
Aviation services anchor the premium tier through bundled service contracts. Municipal procurement is expanding most quickly as climate adaptation budgets receive federal infrastructure funding.
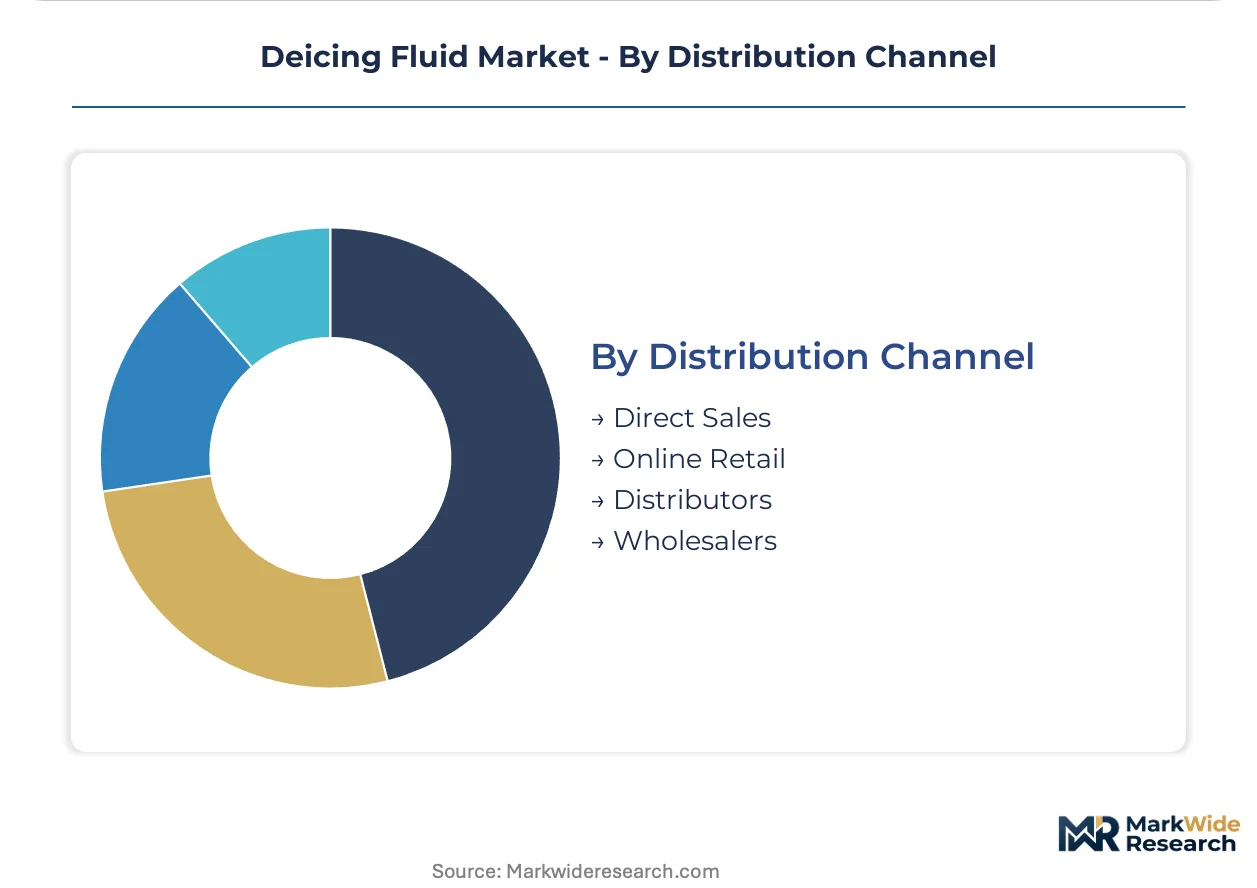
Distribution Channel:
Channel structure reflects order scale, technical support needs, and geographic dispersion of end-use points.
- Direct Sales:Manufacturer-to-airport contracts for high-volume aerospace-grade fluids requiring on-site storage infrastructure and technical service support. BASF SE leverages captive propylene glycol manufacturing to anchor these long-term agreements.
- Distributors:Regional chemical distributors holding inventory positions for municipal and commercial fleet customers with fragmented demand patterns.
- Wholesalers:Bulk commodity handlers moving calcium chloride and sodium chloride by rail and barge to state procurement depots.
- Online Retail:E-commerce platforms serving residential and small commercial buyers with packaged deicing products.
Direct sales capture the aerospace premium through integrated service bundling. Distributor networks are climbing the fastest as mid-size airports outsource procurement complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Municipal highway departments exhibit extreme price sensitivity toward calcium chloride procurement, while aviation services at hub airports absorb premiums for potassium acetate formulations without volume elasticity.
United States
Extended winter seasons at Minneapolis-St. Paul and Denver International stretch deicing operations from October through April. The EPA's VGP discharge limits force airports toward Type IV fluids with expanded recovery infrastructure. Chicago O'Hare anchors the Great Lakes cluster where integrated service contracts now dominate procurement.
Germany
REACH Annex XVII restrictions on triazole corrosion inhibitors compel reformulation of one-third of registered aviation fluid products. Frankfurt Airport channels seventy percent of annual consumption through take-or-pay concession agreements with ground handlers. Bavarian chemical suppliers absorb certification costs while pushing premium pricing for compliant stocks.
Canada
Provincial transportation departments in Ontario and Quebec balance calcium chloride cost efficiency against infrastructure corrosion liabilities. Environment Canada's discharge guidelines for airport runoff align with tightening aquatic toxicity standards. Toronto Pearson anchors the national aviation hub cluster with multi-year bundled service contracts.
India
Greenfield airport developments under the UDAN regional connectivity scheme create first-mover openings for aviation-grade fluid suppliers. The Bureau of Indian Standards frames quality benchmarks for imported formulations. Delhi Indira Gandhi International anchors the northern hub cluster where privatization drives concession-based procurement restructuring.
United Kingdom
Heathrow and Gatwick bundle deicing services into ground handling concessions rather than separate fluid procurement. The Environment Agency enforces stormwater discharge standards that shape additive package specifications. Scottish airports at Edinburgh and Glasgow face extended operational windows driving seasonal inventory builds.
Deicing Fluid Market Vendor Landscape
Capability concentration sits with specialty additive formulators; scale advantage sits with integrated glycol producers. The vendor base separates into three tiers: captive chemical manufacturers anchoring long-term aviation contracts, independent blenders serving municipal spot markets, and regional distributors handling fragmented commercial fleet demand. Strategic moves center on backward integration into propylene glycol feedstock and concession-based service bundling at hub airports.
Within the specialty formulation tier, Clariant AG exemplifies additive package differentiation, while BASF SE anchors the integrated manufacturer archetype through captive propylene glycol production. Kilfrost Group PLC occupies the aerospace-certified specialist position. These three represent distinct competitive vectors: chemical innovation, supply chain control, and certification depth.
| Leading Market Players |
|---|
| Clariant AG |
| The Dow Chemical Company |
| LyondellBasell Industries |
| BASF SE |
| Kilfrost Group PLC |
| Cryotech Deicing Technology |
| Proviron |
| JBT Corporation |
| LNT Solutions |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European propylene glycol production facilities is compressing spot market margins while tightening contract pricing discipline among integrated manufacturers serving aviation customers. This utilization asymmetry between commodity-grade surplus and aerospace-certified tightness rewards backward-integrated suppliers with captive feedstock positions.
Pricing Analysis
Aftermarket fluid replenishment contracts anchor lifetime value through multi-year integrated service agreements bundling chemical supply with application infrastructure. Pricing stratifies across SAE AMS 1424/1428 certified aerospace tiers, municipal calcium chloride spot markets, and premium potassium acetate formulations for EPA VGP-compliant airports. Cost compression in roadway salt segments intensifies as state transportation departments prioritize unit economics over environmental performance. Municipal buyers exhibit extreme price sensitivity, while aviation services absorb premiums without volume elasticity due to regulatory liability and certification barriers.
Supply Chain Analysis
Tariff exposure between the United States and China disrupts corrosion inhibitor precursor flows, particularly triazole chemistries concentrated in German and Belgian supplier networks. Manufacturing gravity centers on the United States, Germany, and China, with propylene glycol production drawing from corn and soybean oil feedstocks vulnerable to agricultural commodity swings. Specialty additive packages hinge on a narrow supplier base, creating single-source vulnerability for aerospace formulators. Distribution runs through direct manufacturer-to-airport contracts for high-volume aerospace grades, with regional distributors handling fragmented municipal and commercial fleet demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where SAE AMS certification timelines and EPA discharge compliance create switching costs that protect incumbent positions. Network effects concentrate at hub airports where integrated service contracts bundle fluid supply with dedicated storage infrastructure.
For Market Incumbents: Entrench position through captive propylene glycol manufacturing capacity and exclusive concession agreements at Minneapolis-St. Paul and Denver International. Electrothermal ice protection systems on next-generation narrowbody aircraft threaten Type I fluid volumes; defend by deepening formulation expertise in Type IV anti-icing chemistry and fluid recovery system integration. Certification investment in benzotriazole alternatives positions suppliers for REACH Annex XVII compliance.
For New Entrants and Emerging Players: Establish a beachhead in India's UDAN greenfield airport developments where privatization dismantles legacy procurement structures. Municipal drone-based precision application for wind turbine and telecommunications tower maintenance offers white-space expansion outside aviation regulatory barriers. Partner with regional ground handling operators to bypass direct certification requirements while building formulation credibility.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fluid recovery infrastructure and corrosion-resistant storage tank retrofits. Five-to-ten year viability favors specialty additive formulators with reformulation capabilities over commodity glycol producers facing feedstock volatility. Watch for electrothermal system adoption rates on Boeing and Airbus platforms as the signal indicating addressable aerospace fluid compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Propylene Glycol | BASF SE leverages captive manufacturing to anchor long-term aviation service agreements with price stability. |
| Green Formulation Certification | EU Green Deal incentives reward biodegradable additive packages that satisfy tightening aquatic toxicity standards. |
| Integrated Service Concession Agreements | Amsterdam Schiphol and Frankfurt bundle deicing into ground handling contracts replacing spot purchasing. |
| Specialty Additive Package Differentiation | Clariant AG extends fluid performance windows in extreme cold through proprietary corrosion inhibitor blends. |
| Regional Blending Capacity Expansion | India's UDAN scheme creates first-mover openings for suppliers establishing local aviation-grade production. |
Methodological Framework
The analysis maps potassium acetate, calcium chloride, urea, and sodium chloride formulation tiers, each validated through procurement directors at hub airports, municipal highway department fleet managers, ground handling operation executives, and specialty chemical distribution channel partners. Primary interview insights triangulate against EPA VGP discharge filings, FAA Advisory Circular documentation, ECHA REACH registration databases, and Bureau of Indian Standards quality benchmarks. Secondary validation draws from SEC 10-K disclosures of integrated chemical manufacturers, customs trade flow data, and airport concession agreement records. Bottom-up volume modeling across application segments reconciles with top-down market sizing through propylene glycol feedstock demand analysis.
Forecast assumptions hold EPA VGP discharge limits and REACH Annex XVII restrictions fixed at current regulatory intensity while varying electrothermal ice protection adoption rates and climate-driven winter season extension across the projection horizon. Segmentation dimensions include product type chemistry, application context, end-user procurement modality, and distribution channel structure. CAGRs derive from regression analysis of historical fluid consumption against heating degree-day indices and aviation traffic recovery patterns. Industry-specific inputs incorporate SAE AMS 1424/1428 certification timeline delays and potassium acetate biodegradability premium persistence.
Stress conditions across propylene glycol feedstock price volatility, triazole corrosion inhibitor supply disruption, and electrothermal system penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and airport privatization momentum. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
SLS and LABSA Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Global Thiophene Market
Chemicals
Phosgene Market
Chemicals
Flame Retardants Chemicals Market
Chemicals
Butylated Triphenyl Phosphate Market
Chemicals
Phosphorus Pentasulfide (P2S5) Market
Chemicals
Lanthanum Nitrate Market
Chemicals
Aluminum Ammonium Sulfate Market
Chemicals
Global Zinc Pyrithione Market
Chemicals
Methanol Market
Chemicals
Sulfuric Acid Market
Chemicals
Allyl Alcohol Market
Chemicals
Hydrophobing Agents Market
Chemicals
Perchloric Acid Market
Chemicals
Thiourea Market