
 Negative Photoresist Chemicals Market | 2026-2036
Negative Photoresist Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Negative Photoresist Chemicals Market Analytics
Multi-sourcing of resin precursors is repositioning procurement strategies across the negative photoresist chemicals value chain. Tokyo Ohka Kogyo leverages captive monomer production to secure supply continuity for advanced node customers. JSR Corporation anchors its competitive stance through deep R&D partnerships with leading lithography equipment makers. DuPont de Nemours, Inc. competes on broad formulation portfolios spanning both i-line and chemically amplified platforms.
Negative photoresist chemicals comprise photosensitive polymer systems, typically based on cyclized polyisoprene or chemically amplified resins, formulated with photoactive compounds and casting solvents to enable sub-micron pattern transfer in semiconductor fabrication. These materials function through crosslinking reactions upon UV, electron beam, or X-ray exposure, producing insoluble relief images for subsequent etch or lift-off processing. The polymer segment leads in value contribution due to raw material intensity and customization requirements for each technology node. Electron beam lithography represents the fastest-growing technology segment, driven by mask-making and direct-write applications where resolution demands exceed optical limits.
EPA oversight of solvent emissions and OSHA workplace exposure limits shape formulation choices and manufacturing site selection in the United States. REACH registration requirements and the EU F-Gas Regulation constrain fluorinated solvent use, pushing reformulation toward lower-VOC alternatives. Stakeholders must monitor evolving PFAS restrictions and lithography wavelength transitions to align product development timelines with regulatory and technology roadmaps.
Market Dynamics
Sub-7nm lithography node transitions are forcing reformulation cycles across the negative photoresist chemicals supply chain, compressing qualification timelines and elevating resin purity specifications beyond historical thresholds.
Growth Catalysts
- TSMC-Led Foundry Expansion:Taiwan's Tainan Science Park capacity builds are pulling advanced chemically amplified photoresist volumes for EUV and high-NA immersion layers.
- REACH Compliance Deadlines:ECHA registration requirements for novel monomer structures are accelerating substitution toward pre-registered resin backbones with established toxicological dossiers.
- Electron Beam Direct-Write:Maskless lithography for prototyping and low-volume ASIC production is expanding addressable demand beyond traditional mask-making applications.
Market Restraints
- Fluorinated Solvent Constraints:EU F-Gas Regulation phase-down schedules are limiting perfluorinated ether options for high-resolution casting formulations, forcing costly solvent swaps.
- Monomer Supply Concentration:Cyclized polyisoprene precursor production clusters in Japanese and Korean chemical parks, creating single-source vulnerability for non-captive formulators.
- EUV Resin Technical Ceiling:Current chemically amplified platforms face acid diffusion limits below 5nm half-pitch, constraining extendibility without molecular glass architectures.
Strategic Opportunities
- India Semiconductor Mission:PLI scheme incentives for domestic fab construction are opening qualification pathways for photoresist suppliers ahead of operational ramp.
- Biodegradable Solvent Platforms:Emerging lactone and terpene-derived casting vehicles align with EU Green Deal decarbonization mandates for Scope 3 emission reductions.
- X-Ray Lithography Convergence:Synchrotron-based patterning for MEMS and power devices is creating hybrid demand for resins spanning optical and shorter-wavelength exposure regimes.
Industry Challenges
- EUV Resist Chemist Scarcity:The intersection of polymer physics, photochemistry, and contamination control expertise remains severely under-supplied relative to foundry hiring targets.
- Qualification Timeline Compression:Node-to-node shrink cycles now outpace standard 18-24 month OEM validation protocols, forcing parallel risk-taking on unproven formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Negative Photoresist Chemicals Market |
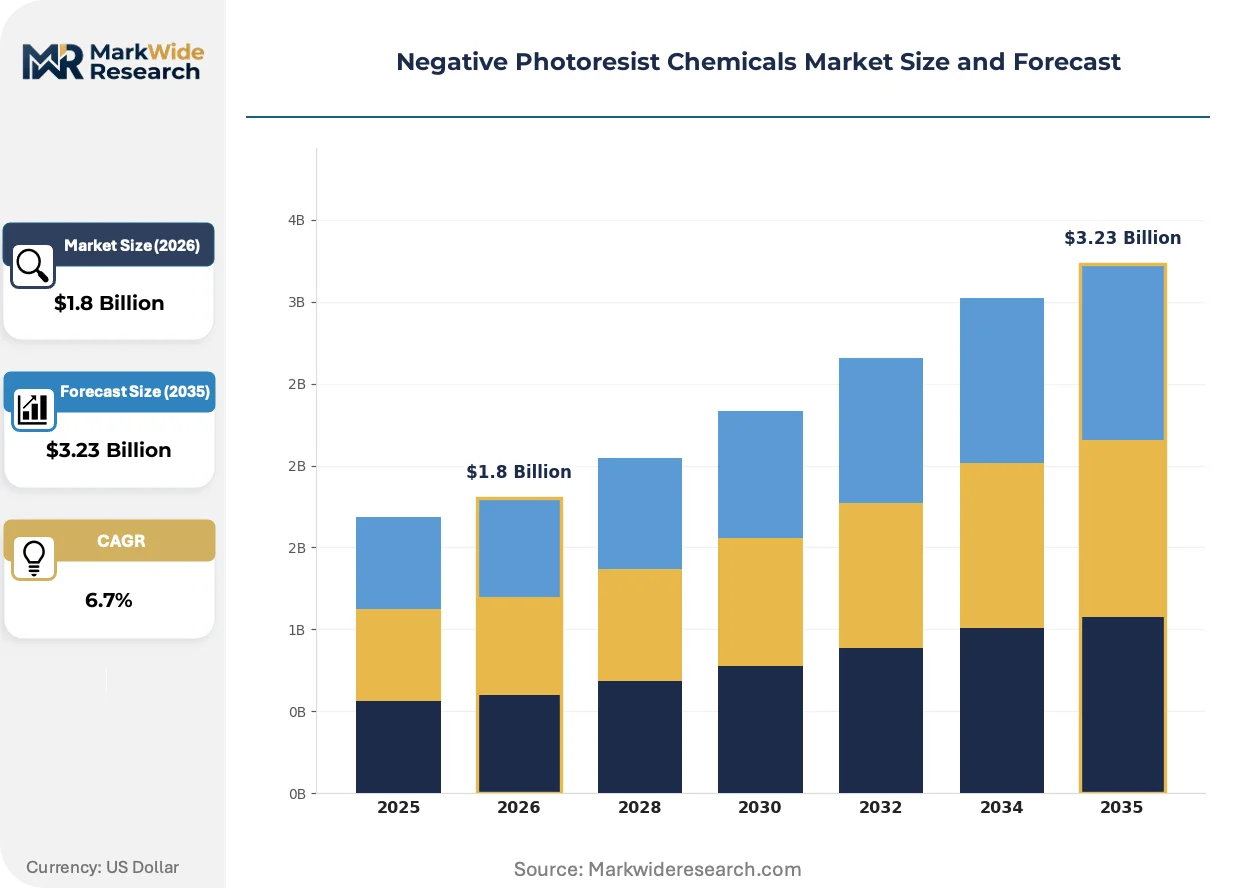
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Resin, Solvent, Additive Application: Semiconductors, Printed Circuit Boards, MEMS, Microfluidics End User: Electronics Manufacturers, Research Institutions, Telecommunications, Automotive Technology: UV Exposure, Electron Beam Lithography, X-ray Lithography, Nanoimprinting |
| Companies Covered | Tokyo Ohka Kogyo Co., Ltd., JSR Corporation, Fujifilm Holdings Corporation, Shin-Etsu Chemical Co., Ltd., DuPont de Nemours, Inc., Sumitomo Chemical Co., Ltd., Merck KGaA, Dow Inc., MicroChem Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Negative Photoresist Chemicals Market Evolving Landscape
Patterning architecture diversification and regulatory chemistry constraints are jointly reshaping how negative photoresist formulators allocate R&D resources and structure customer partnerships.
Molecular glass resist platforms are decentralizing the historical dominance of polymeric backbones in sub-10nm patterning. Semiconductor foundries in Taiwan and Korea are piloting these low-molecular-weight alternatives for reduced line-edge roughness. The shift is decentralizing formulation know-how from traditional polymer houses toward specialized small-molecule chemical suppliers with precision purification capabilities.
EU F-Gas Regulation amendments are tightening permissible global warming potential thresholds for fluorinated process chemicals used in lithography. Formulators serving European fabs must now validate non-fluorinated casting solvents or secure quota allocations for legacy materials. High-volume i-line and g-line resists for mature nodes face the steepest substitution economics under these constraints.
Consolidated procurement through foundry-level chemical management programs is displacing individual tool-level purchasing. TSMC and Samsung Electronics now negotiate multi-year photoresist supply agreements directly, compressing distributor margins and forcing qualification at parent rather than subsidiary levels. Taiwan and South Korea exhibit the most advanced concentration of this buying-pattern shift.
Negative Photoresist Chemicals Market Segmentation
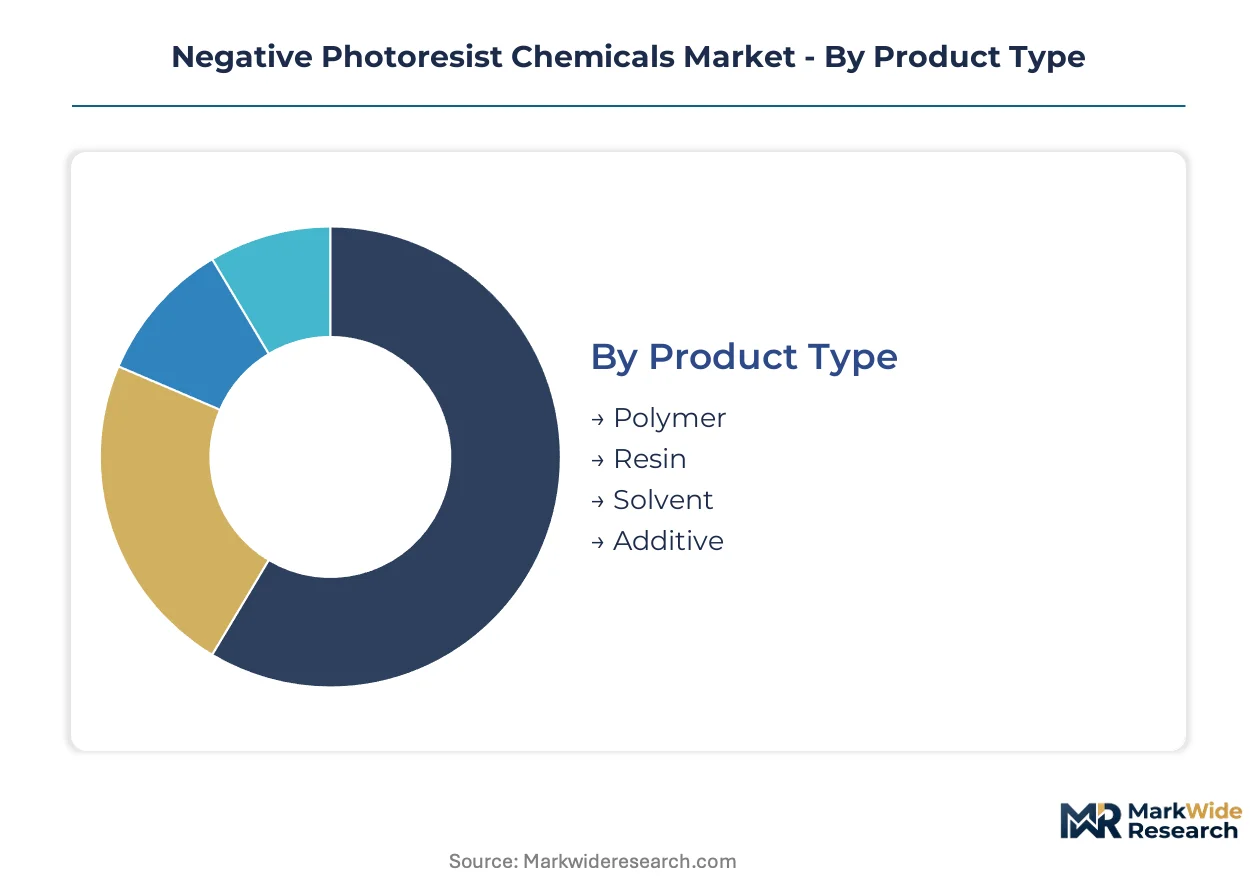
Segmentation in negative photoresist chemicals reveals how formulation complexity, regulatory burden, and node-specific performance requirements concentrate value differently across material categories and application tiers. Each dimension carries distinct certification obligations and supply chain risk profiles that shape procurement strategies.
Product Type:
Certification intensity varies sharply across material tiers — polymers face REACH dossier requirements for novel monomers, while solvents trigger F-Gas Regulation quota constraints in European manufacturing.
- Polymer:Cyclized polyisoprene and chemically amplified resin backbones dominate formulation costs. Demand concentrates at TSMC's Tainan Science Park facilities where sub-7nm nodes require customized molecular weight distributions and ultra-low metal contamination specifications.
- Resin:Photoactive compound carriers determine resolution limits and line-edge roughness. Procurement is tightening around pre-registered backbones with established ECHA toxicological profiles to accelerate qualification timelines.
- Solvent:Casting vehicles enable uniform film formation through spin-coat processes. EU F-Gas Regulation phase-downs are forcing substitution toward lower-global-warming-potential alternatives for European fab supply.
- Additive:Quenchers, surfactants, and adhesion promoters fine-tune process windows. These components face less stringent registration requirements but demand precise contamination control for advanced node compatibility.
Leading the category by volume: Polymer. Growing fastest: Resin.
Application:
Application tiers separate by resolution threshold and volume scale — semiconductor lithography commands premium pricing for sub-10nm capability while mature-node applications compete on cost efficiency.
- Semiconductors:Front-end patterning for logic and memory devices drives the highest specification requirements. EUV and high-NA immersion layers at Korean and Taiwanese foundries pull chemically amplified formulations with acid diffusion control below 5nm half-pitch.
- Printed Circuit Boards:i-line and g-line resists for substrate patterning operate at relaxed resolution constraints. REACH compliance costs here concentrate on solvent emissions rather than resin innovation cycles.
- MEMS:Thick-film negative resists enable high-aspect-ratio structures for sensors and actuators. X-ray lithography at synchrotron facilities is expanding addressable demand for hybrid optical and short-wavelength resin platforms.
- Microfluidics:Biocompatible patterning for lab-on-chip devices requires specialized adhesion and release properties. Research institutions anchor demand with smaller volume but higher formulation customization requirements.
Highest margin capture: Semiconductors. Steepest expansion trajectory: MEMS.
End User:
Customer type determines contract structure — foundry-level chemical management programs now displace tool-level purchasing, compressing distributor roles and forcing parent-level qualification.
- Electronics Manufacturers:Integrated device makers and OSATs consume photoresist across packaging and wafer-level processing. Multi-year supply agreements with formulators now lock in volume commitments ahead of capacity ramps.
- Research Institutions:Universities and national laboratories pilot emerging lithography modalities. These users tolerate higher per-liter costs for small-batch customization that would fail scale economics in production environments.
- Telecommunications:Optical component fabrication for fiber and wireless infrastructure relies on mature-node patterning. Specifications here prioritize throughput and yield stability over resolution extension.
- Automotive:Power device and sensor manufacturing for electric vehicles is pulling MEMS-compatible formulations. Functional safety requirements under ISO 26262 are extending traceability obligations into chemical supply chains.
Dominant procurement volume: Electronics Manufacturers. Fastest contract restructuring: Telecommunications.
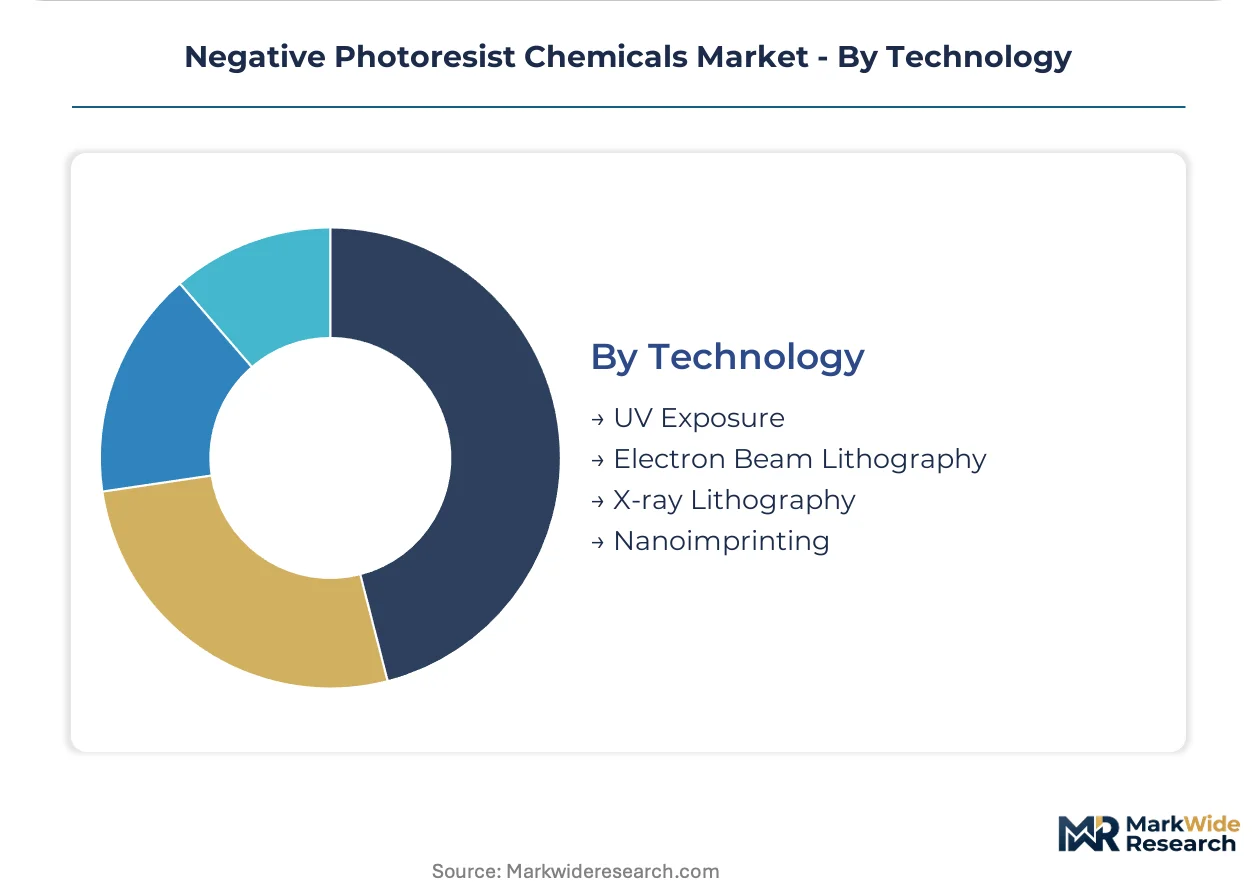
Technology:
Technology modality dictates resin architecture — crosslinking chemistry, sensitivity thresholds, and outgassing profiles must align with exposure wavelength and dose requirements.
- UV Exposure:i-line, h-line, and DUV systems remain workhorses for mature nodes and packaging applications. Formulation stability under ambient conditions reduces supply chain complexity relative to shorter-wavelength alternatives.
- Electron Beam Lithography:Mask-making and direct-write prototyping demand ultra-high resolution without optical diffraction limits. This segment is expanding most quickly as maskless patterning gains traction for low-volume ASIC production.
- X-ray Lithography:Synchrotron-based exposure for MEMS and power devices exploits high penetration depth. Hybrid resin demand spans both optical and X-ray sensitivity to enable multi-modal process flows.
- Nanoimprinting:Mechanical pattern transfer using etched templates offers cost advantages for repetitive structures. Resin requirements center on low-viscosity flow and precise shrinkage control rather than photochemical sensitivity.
Widest installed base: UV Exposure. Climbing the fastest: Electron Beam Lithography.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TSMC-led foundry expansion at Taiwan's Tainan Science Park concentrates advanced photoresist procurement, pulling formulation volumes that exceed regional consumption patterns. This demand concentration reshapes supplier qualification protocols and inventory positioning across East Asian chemical supply chains.
Taiwan
TSMC's Tainan Science Park capacity builds for sub-7nm EUV layers anchor regional photoresist consumption. Taiwan's Environmental Protection Administration enforces semiconductor-specific air emission standards for solvent-intensive processes. Kaohsiung's chemical port infrastructure supports just-in-time resin precursor deliveries to foundry clusters.
South Korea
Samsung Electronics and SK Hynix expand DRAM and logic capacity at Pyeongtaek and Yongin complexes. South Korea's Ministry of Environment implements K-REACH registration deadlines that accelerate monomer substitution timelines. The Gyeonggi-do province concentration of fab operations creates localized demand spikes for chemically amplified formulations.
Japan
Tokyo Ohka Kogyo and JSR Corporation anchor domestic resin precursor production for captive and merchant supply. Japan's Ministry of Economy, Trade and Industry (METI) coordinates national semiconductor strategy including material security provisions. The Kanto and Kansai industrial corridors maintain specialized polymer synthesis capabilities for advanced node requirements.
United States
Intel's Arizona and Ohio fab investments expand domestic EUV lithography capacity. EPA oversight of per- and polyfluoroalkyl substances (PFAS) constrains fluorinated solvent formulations under TSCA Section 5. Arizona's Phoenix metro area emerges as a southwestern semiconductor manufacturing cluster with localized chemical supply needs.
Germany
Bosch and Infineon expand power semiconductor fabrication at Dresden and Regensburg facilities. ECHA REACH registration requirements for novel monomer structures extend qualification timelines for non-registered resin backbones. The Saxony cluster around Dresden concentrates MEMS and automotive chip production with distinct photoresist specifications.
Negative Photoresist Chemicals Market Competitive Landscape
Strategic partnerships dominate the current landscape as formulators align with lithography equipment makers and foundry customers. The market structure consolidates around Japanese and Korean chemical conglomerates with captive monomer capabilities, tiered against European and American diversified material suppliers. Three archetypes prevail: integrated resin-to-formulation operators, specialized photoresist pure-plays, and diversified chemical portfolio holders. Technology licensing and backward integration into precursor production represent the most frequent competitive moves.
Among Japanese integrated chemical groups, Tokyo Ohka Kogyo Co., Ltd., JSR Corporation, and Shin-Etsu Chemical Co., Ltd. exemplify the resin-captive archetype with upstream control over cyclized polyisoprene and chemically amplified polymer synthesis. These entities occupy positions where monomer supply security translates directly into foundry qualification advantages. DuPont de Nemours, Inc. represents the diversified portfolio approach, spanning multiple lithography wavelength platforms without vertical integration into polymer feedstocks.
| Leading Market Players |
|---|
| Tokyo Ohka Kogyo Co., Ltd. |
| JSR Corporation |
| Fujifilm Holdings Corporation |
| Shin-Etsu Chemical Co., Ltd. |
| DuPont de Nemours, Inc. |
| Sumitomo Chemical Co., Ltd. |
| Merck KGaA |
| Dow Inc. |
| MicroChem Corp. |
| Others |
Value Network & Pricing Analysis
Cyclized polyisoprene precursor costs flow through three distinct pricing tiers before reaching foundry customers, with resin purity grades and REACH compliance certification separating premium formulations from commodity alternatives. Japanese and Korean chemical parks anchor upstream supply, concentrating margin capture among integrated producers while non-captive formulators absorb volatility through contract structures.
Pricing Analysis
High-volume i-line and g-line resists for mature nodes trade on thin margins, while sub-7nm chemically amplified formulations command substantial premiums for customized molecular weight distributions and ultra-low metal contamination specifications. Price differentiation rests on ECHA registration status and captive monomer supply security, with European fabs facing additional F-Gas Regulation quota costs for fluorinated casting vehicles. Cost compression in mature-node segments is intensifying as Chinese suppliers expand qualified volumes. Electronics manufacturers under multi-year chemical management programs exhibit lowest price sensitivity, whereas research institutions and small-scale OSATs remain most exposed to spot-market fluctuations.
Supply Chain Analysis
Reverse-logistics flows for expired or off-specification photoresist remain minimal given contamination risks and single-use process requirements, though solvent recovery programs at Taiwanese and Korean foundry clusters are gaining traction for environmental compliance. Raw material supply draws from Japanese cyclized polyisoprene synthesis facilities, Korean chemically amplified resin plants, and German specialty solvent refineries. Single-source vulnerability concentrates in cyclized polyisoprene precursor production, where Japanese and Korean chemical parks dominate global capacity. Distribution runs through foundry-level chemical management programs that displace traditional distributor networks, with TSMC and Samsung Electronics negotiating direct multi-year supply agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where upstream control over monomer synthesis and downstream qualification at parent foundry levels determine competitive survival. Players without captive resin capabilities face persistent margin compression and qualification disadvantages.
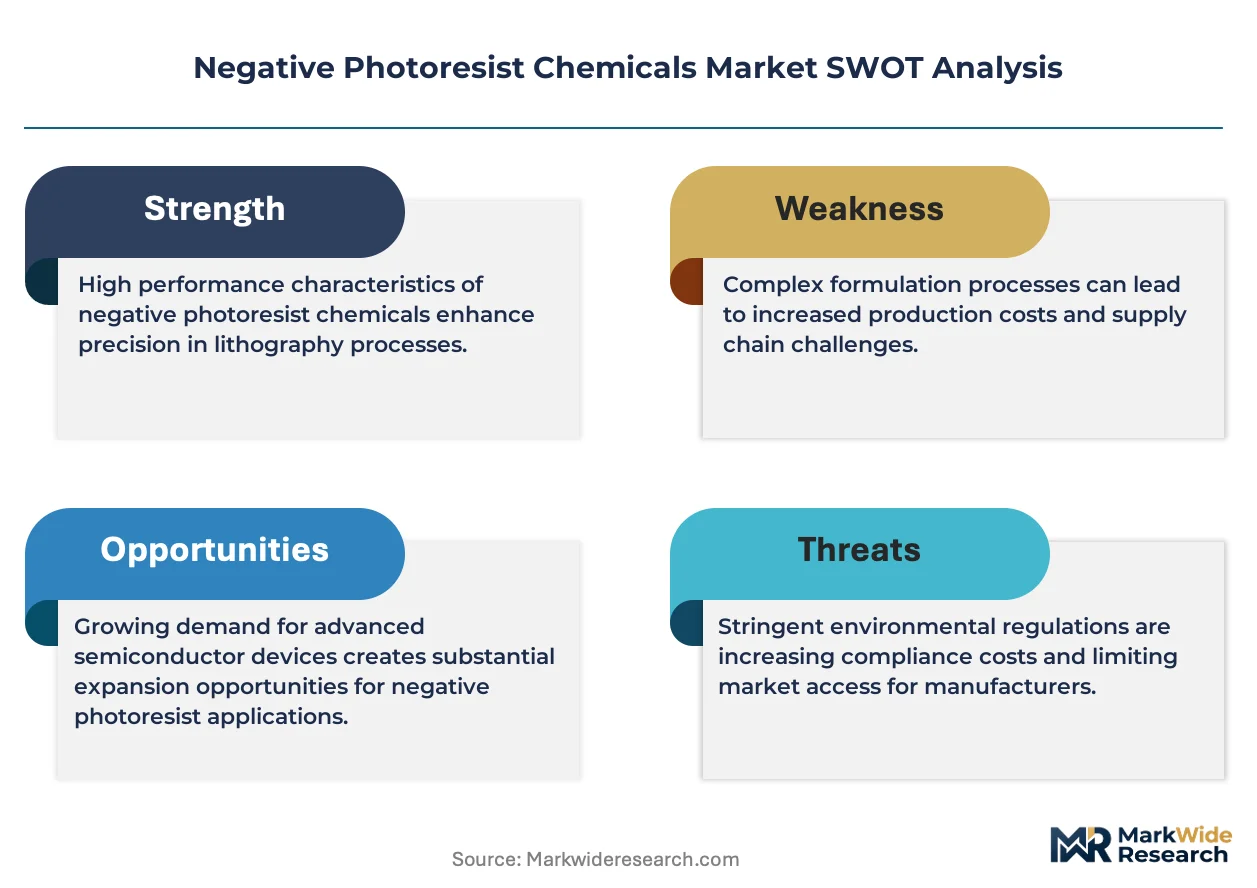
For Market Incumbents: Lock in foundry-level chemical management program participation before qualification windows close for upcoming node transitions. Secure captive supply of cyclized polyisoprene precursors through joint venture structures in Japanese or Korean chemical parks to defend against emerging Chinese suppliers with state-backed capacity expansion. ECHA registration deadlines for novel monomer structures pose imminent substitution threats for non-registered backbones. For New Entrants and Emerging Players: The pricing gap between premium EUV-grade formulations and economy-tier i-line resists offers entry space for mid-tier suppliers with pre-registered resin backbones and established toxicological dossiers. Target India's Semiconductor Mission qualification pathways ahead of operational fab ramps, where domestic content requirements and PLI scheme incentives create favorable procurement conditions. Lead with biodegradable solvent platforms aligned with EU Green Deal mandates to differentiate from incumbent fluorinated formulations. For Investors and Strategic Acquirers: TSMC's Tainan Science Park capacity build announcements are the leading indicator that advanced photoresist demand is accelerating faster than qualified supply expansion. Prioritize acquisition targets with molecular glass resist capabilities and precision purification expertise for sub-10nm patterning, as polymeric backbone dominance decentralizes toward small-molecule specialists. Monitor ECHA PFAS restriction proposals for early signals of solvent reformulation cycles that would favor non-fluorinated casting vehicle suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Captive cyclized polyisoprene production secures supply continuity for TSMC and Samsung qualification pipelines. |
| Long-term Supply Agreement with Foundry Chemical Management Programs | Direct contracts with TSMC and Samsung displace distributor margins and lock in volume commitments. |
| Green Manufacturing Transition to Biodegradable Solvents | Lactone and terpene-derived casting vehicles align with EU F-Gas Regulation phase-down schedules. |
| Joint Venture for Regional Production Hub | Localized resin synthesis in Taiwan or South Korea reduces logistics exposure and accelerates just-in-time delivery. |
| Acquisition of Molecular Glass Specialist | Low-molecular-weight resist platforms address acid diffusion limits below 5nm half-pitch for EUV extension. |
Research Methodology
SEC 10-K filings, ECHA registration databases, and customs trade data formed the secondary backbone for supply chain mapping and competitive positioning assessment. Primary interviews with photoresist formulator R&D directors, foundry procurement leads at TSMC and Samsung Electronics, and semiconductor equipment OEM technical specialists provided forward-looking qualification timeline intelligence. Bottom-up and top-down triangulation reconciled resin precursor production capacities against foundry capacity expansion announcements across the analysis window.
Bottom-up modeling built from individual fab-level photoresist consumption rates, technology node-specific formulation requirements, and foundry announced capacity ramps. Top-down validation cross-checked against regional semiconductor materials trade flows and chemical industry production statistics. Segmentation dimensions included polymer type, application tier, end-user contract structure, and lithography technology modality. CAGRs derived from slope analysis of node transition schedules and corresponding reformulation cycle frequencies, with EUV adoption curves and high-NA immersion deployment timelines as critical inputs.
Inputs from ECHA registration databases and foundry procurement disclosures were available through the study window; gaps in proprietary formulation specifications and exact monomer supply contracts introduce uncertainty bands around competitive share estimates. Forecasts reflect assumptions regarding node transition cadence, regulatory phase-down schedules, and qualification protocol durations. Practitioners should monitor ECHA PFAS restriction consultations, TSMC node transition announcements, and Indian fab construction milestones for early signals of demand inflection or supply restructuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Ethylenediaminetetraacetic Acid Market
Chemicals
Tanning Agents Market
Chemicals
Acetophenone Market
Chemicals
Triethylaluminum Market
Chemicals
Dimethyldichlorosilane Market
Chemicals
Morpholine Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
Global Thiophene Market
Chemicals
Inorganic Chemicals Market
Chemicals
Coagulant Market
Chemicals
Europe Calcium Peroxide Market
Chemicals
Laboratory Chemical Reagents Market
Chemicals
Latin America Construction Chemicals Market
Chemicals
Canada Methanol Market
Chemicals
Uranyl Carbonate Market
Chemicals
Isopropyl Alcohol (IPA) Market