
 Potassium Hydrogen Phthalate Market | 2026-2036
Potassium Hydrogen Phthalate Market Size, Share, and Industry Trends Forecast 2026-2036
Potassium Hydrogen Phthalate Market Insights
Sodium hydroxide titrant is broadening its displacement of potassium hydrogen phthalate in select pH buffer applications, yet KHP retains irreplaceable value as a primary standard for acid-base calibration. Merck KGaA leverages its European manufacturing footprint to sustain analytical reagent supply chains for European pharmacopeia users. Thermo Fisher Scientific Inc. anchors North American distribution through its Fisher Chemical portfolio, while Avantor Inc. competes on cGMP-compliant pharmaceutical grade production for biopharma QC workflows.
Potassium hydrogen phthalate is a crystalline dicarboxylic acid salt with formula C8H5KO4, possessing high purity and thermal stability that make it ideal as a primary standard in volumetric analysis. Its primary commercial purpose centers on calibration of sodium hydroxide solutions and pH meter standardization in regulated laboratory environments. Analytical Reagents command the largest volume share due to mandatory recalibration cycles in ISO 17025-accredited labs, while Pharmaceutical Grade captures the strongest margin pool as USP-NF and EP monograph compliance tightens. Calibration Standards applications lead in revenue intensity because regulatory audits require documented traceability chains, whereas Food Grade remains a smaller, price-sensitive niche.
EPA methods mandate KHP for wastewater acidity testing under Clean Water Act protocols, while USP-NF monographs govern its pharmaceutical-grade specifications and REACH registration shapes European chemical substance authorization. FDA cGMP inspections of analytical laboratories indirectly enforce KHP purity requirements through instrument qualification standards. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards to anticipate specification drift that could reshape sourcing strategies and qualification burdens.
Market Dynamics
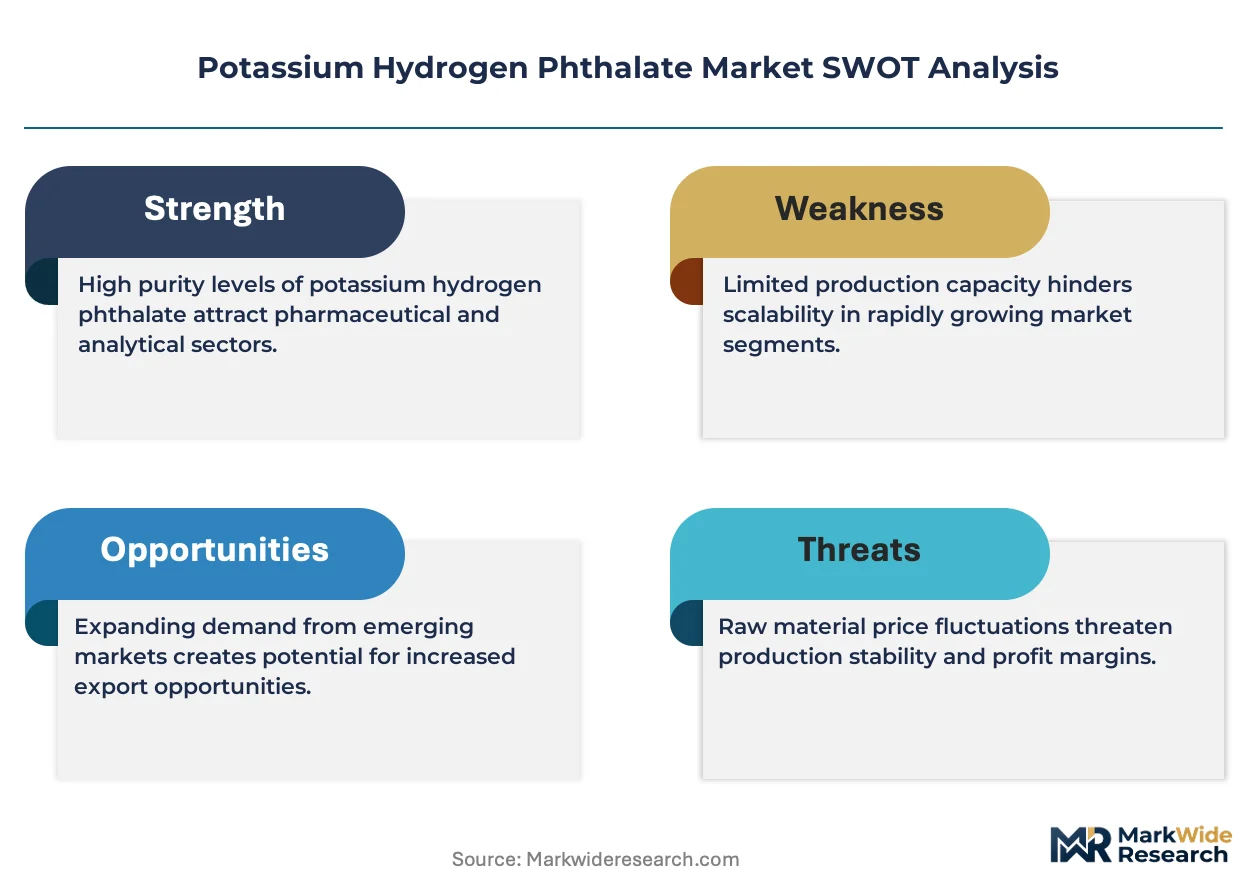
Tightening pharmacopeial harmonization between USP-NF, EP, and JP monographs is compressing specification tolerances for primary standards, forcing suppliers to invest in higher-purity production infrastructure or exit pharmaceutical-grade segments entirely.
Growth Catalysts
- REACH registration requirements:ECHA's substance authorization protocols for analytical reagents are elevating entry barriers for non-compliant suppliers, consolidating demand among certified European manufacturers.
- Biopharma QC expansion:Cell and gene therapy manufacturing in the United States and Germany requires more frequent sodium hydroxide calibration cycles, expanding KHP consumption per facility.
- ISO 17025 accreditation mandates:Third-party laboratory certification in Japan is accelerating documented traceability requirements for acid-base titration standards.
Market Restraints
- Potassium feedstock volatility:Fertilizer market swings directly impact KHP input costs, compressing margins for producers without backward integration into potassium carbonate supply.
- Substitution by sodium hydroxide buffers:pH buffer applications in wastewater testing are migrating toward direct NaOH formulations, eroding volume in non-calibration segments.
- Single-source dependency:High-purity phthalic anhydride supply concentrates among German and Chinese specialty chemical producers, creating geographic concentration risk.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's tightening GMP inspection protocols for export-oriented API producers creates demand for USP-NF compliant primary standards previously sourced from European traders.
- Digital titration systems:Automated burette calibration workflows in high-throughput environmental labs are enabling recurring KHP subscription models tied to equipment service contracts.
- EU Green Deal chemical substitution:Bio-based phthalate alternatives for non-analytical applications are freeing conventional KHP capacity for higher-margin pharmaceutical-grade production.
Industry Challenges
- Metrology technician scarcity:ISO 17025-accredited labs in the United States report difficulty recruiting analysts proficient in gravimetric primary standard preparation, extending qualification timelines.
- Multi-pharmacopeia qualification burden:Suppliers must maintain separate batch documentation for USP-NF, EP, and JP compliance, increasing quality system overhead without proportional price recovery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Potassium Hydrogen Phthalate Market |
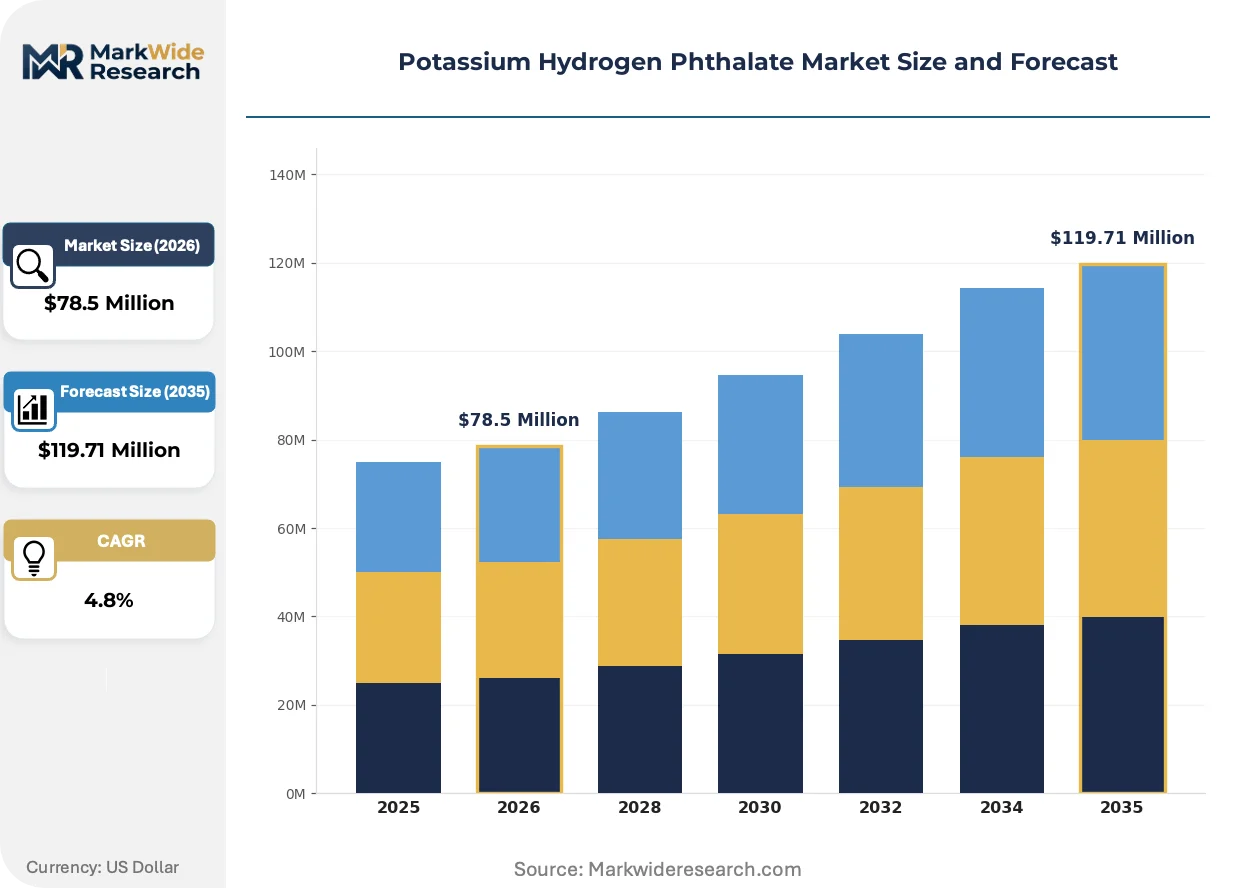
| Market Size in 2026 | $78.5 Million |
| Market Size in 2035 | $119.71 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analytical Reagents, Pharmaceutical Grade, Industrial Grade, Food Grade Application: Analytical Chemistry, Food Additives, Pharmaceutical Manufacturing, Calibration Standards End User: Research Laboratories, Pharmaceutical Companies, Food Industry, Academic Institutions Supply Chain: Distributors, Wholesalers, Retailers, Manufacturers |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc., Avantor Inc., Alfa Aesar, Tokyo Chemical Industry (TCI), TCI Chemicals, BASF SE, Solvay SA, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Potassium Hydrogen Phthalate Market Trends and Innovations
Digitalization of analytical workflows is compressing calibration cycles while elevating documentation requirements, reshaping how primary standards are procured, consumed, and validated across regulated laboratories.
Automated titration systems with integrated KHP cartridge recognition are automating standardization protocols in high-volume pharmaceutical QC labs. Merck KGaA and Thermo Fisher Scientific have deployed RFID-tagged primary standard vials that auto-populate calibration certificates, cutting analyst time per titration by half. This automation is compressing the addressable market for manual KHP preparation while expanding demand for pre-certified, ready-to-use formats.
REACH Annex XIV authorization reviews are tightening impurity thresholds for phthalate-derived substances used in analytical applications. ECHA's 2023 guidance on endocrine disruptor classification has triggered reformulation assessments among European reagent suppliers, with some phasing out legacy synthesis routes. Pharmaceutical-grade KHP manufacturers in Germany are responding by investing in dedicated phthalic anhydride purification trains to maintain EP compliance.
Consolidated procurement through laboratory chemical aggregators is displacing direct supplier relationships in mid-sized analytical labs. Fisher Scientific's channel dominance in North American academic and government labs has compressed price transparency, with buyers accepting standardized SKUs over custom specifications. This concentration is most visible in United States environmental testing facilities, where EPA method compliance requirements limit formulation flexibility regardless of sourcing channel.
Potassium Hydrogen Phthalate Market Segmentation
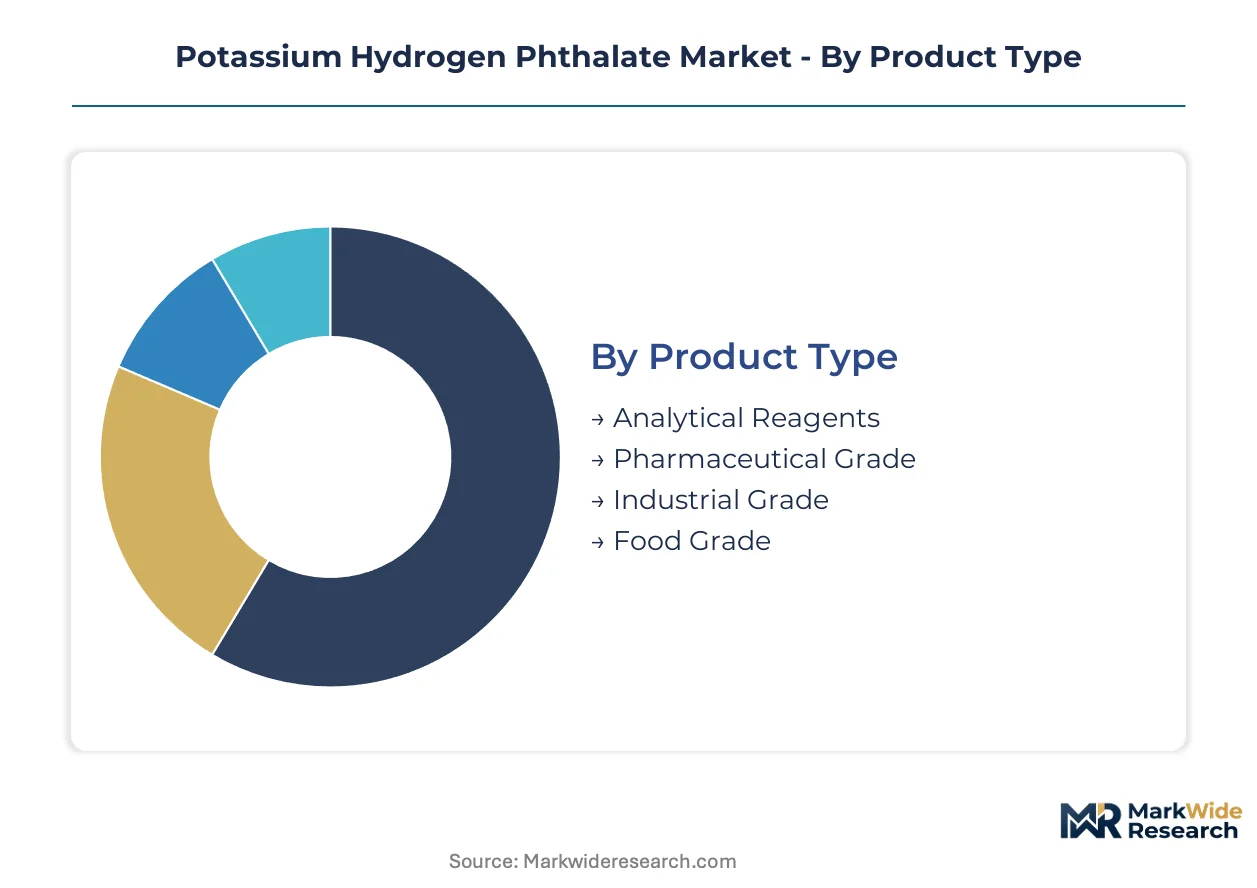
Segmentation in the potassium hydrogen phthalate market reveals how purity specifications and regulatory compliance tiers fragment demand across distinct value pools. Suppliers must align production infrastructure with the traceability and documentation burdens each segment imposes.
Product Type:
Supply concentration for high-purity grades tilts toward German and United States manufacturers with dedicated phthalic anhydride purification capabilities and pharmacopeial certification infrastructure.
- Analytical Reagents:Crystalline C8H5KO4 meeting ACS or ISO reagent specifications, with moisture content below 0.1% and trace metal certification. Demand concentrates in ISO 17025-accredited environmental testing laboratories across Germany and the United States where EPA and REACH protocols mandate documented lot traceability for acid-base titrations.
- Pharmaceutical Grade:Material complying with USP-NF, EP, and JP monographs for primary standard use in cGMP analytical laboratories. Biopharma QC workflows in the United States and Germany absorb volumes as cell and gene therapy manufacturing expands mandatory sodium hydroxide calibration cycles.
- Industrial Grade:Technical-grade material for non-regulated pH buffer and chemical synthesis applications, sourced primarily through bulk chemical distributors without pharmacopeial documentation.
- Food Grade:FCC-compliant material for pH adjustment in food processing, representing a price-sensitive niche with limited specification differentiation and concentrated demand in Japan's processed food sector.
Analytical Reagents absorbs the bulk of installed capacity; Pharmaceutical Grade is expanding most quickly.
Application:
Cost tier differentiation across applications separates high-documentation calibration workflows from commodity buffer uses, with margin structures inversely correlating to automation potential.
- Calibration Standards:Primary standard deployment for sodium hydroxide solution standardization and pH meter calibration in regulated laboratories. Revenue intensity peaks here as regulatory audits in the United States and Germany require documented traceability chains and certificate of analysis retention.
- Analytical Chemistry:Routine acid-base titrations, Karl Fischer reagent standardization, and thermal analysis reference material. Academic and government research laboratories in Japan drive volumes through recurring instrument qualification protocols.
- Pharmaceutical Manufacturing:In-process analytical method validation and finished product release testing. CDSCO-inspected API producers in India are emerging as incremental demand sources as GMP compliance tightens for export-oriented facilities.
- Food Additives:pH buffering and acidity regulation in processed foods, constrained by substitution from citrate and phosphate alternatives in cost-sensitive formulations.
Calibration Standards commands the steepest expansion trajectory; Food Additives faces volume pressure from substitute chemistries.
End User:
Customer type fragmentation maps directly to procurement sophistication, with pharmaceutical companies demanding vendor qualification and academic institutions prioritizing catalog availability over custom specifications.
- Research Laboratories:Environmental, clinical, and industrial testing facilities requiring ISO 17025-compliant documentation. Third-party accreditation mandates in Japan accelerate documented traceability requirements for acid-base titration standards.
- Pharmaceutical Companies:cGMP analytical laboratories in biopharma manufacturing, with FDA inspection history indirectly enforcing KHP purity through instrument qualification standards. Merck KGaA and Thermo Fisher Scientific anchor supply relationships through pre-certified vial formats.
- Academic Institutions:Teaching and research chemistry departments with standardized SKU preferences and consolidated procurement through Fisher Scientific channel dominance in North America.
- Food Industry:Quality control laboratories in processed food manufacturing, with demand concentrated in Japan and limited by pH buffer substitution trends.
Research Laboratories absorb the bulk of installed capacity; Pharmaceutical Companies is climbing the fastest.
Supply Chain:
Maturity across supply chain tiers reflects working capital intensity and regulatory burden, with direct manufacturer relationships commanding premium positioning against distributor commoditization.
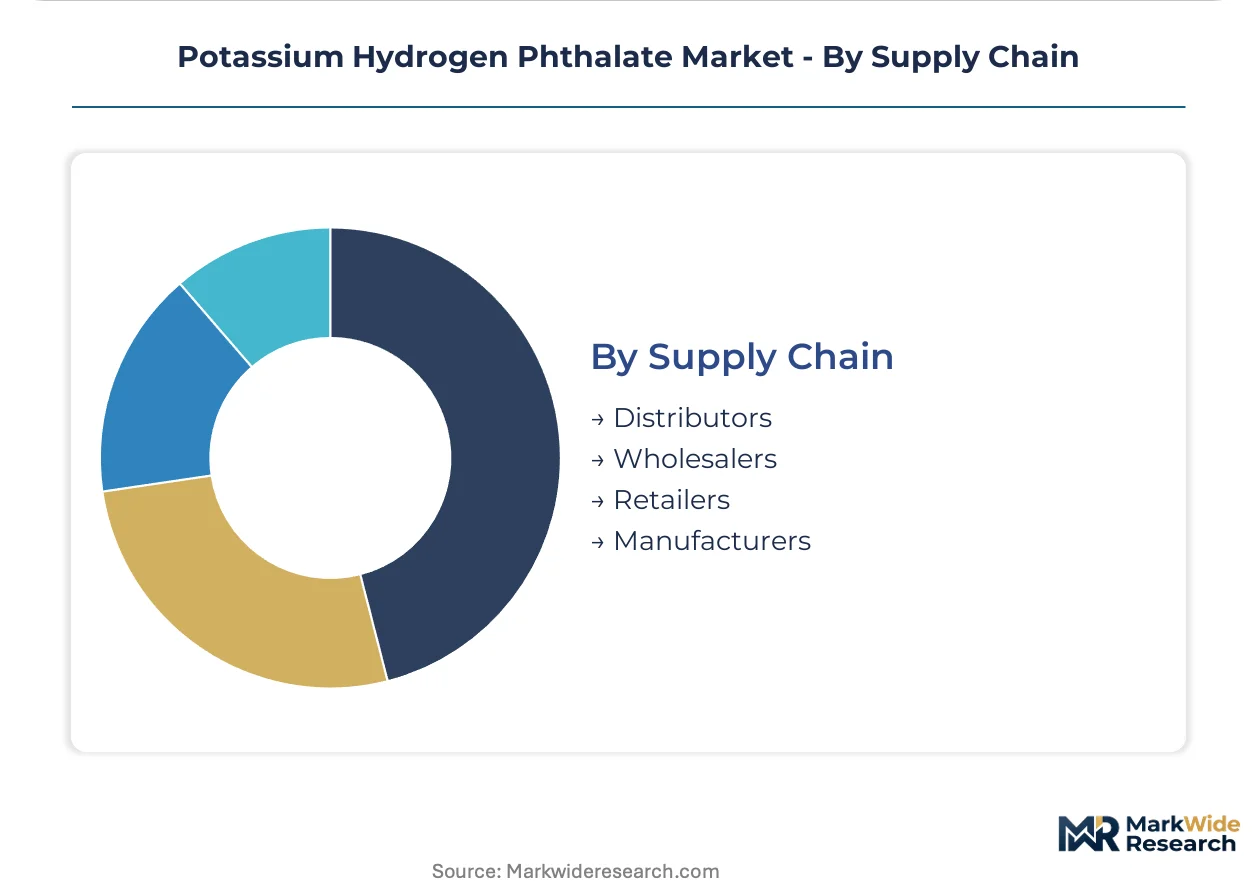
- Manufacturers:Integrated producers in Germany and the United States with captive phthalic anhydride supply and dedicated pharmaceutical-grade purification trains. REACH registration and USP-NF monograph maintenance create structural barriers to backward integration.
- Distributors:Laboratory chemical aggregators including Fisher Scientific's North American channel, consolidating procurement for mid-sized analytical labs and compressing price transparency through standardized SKU offerings.
- Wholesalers:Regional bulk chemical handlers serving industrial-grade applications with minimal documentation and spot-market pricing.
- Retailers:Limited direct-to-laboratory presence, primarily online catalog operations for small-volume academic and research customers.
Manufacturers absorb the bulk of installed capacity; Distributors is gaining share fastest through procurement consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade demand concentrates in laboratories across Germany, the United States, and Japan where pharmacopeial compliance mandates drive procurement decisions. REACH registration in Europe and USP-NF monograph revisions in North America shape formulation requirements for primary standards.
United States
Biopharma QC expansion in cell and gene therapy manufacturing accelerates sodium hydroxide calibration cycles. FDA cGMP inspections enforce instrument qualification standards that indirectly mandate KHP purity. The Boston-Cambridge corridor and Research Triangle Park host dense clusters of contract analytical labs consuming pharmaceutical-grade material.
Germany
Merck KGaA's European manufacturing footprint supplies analytical reagent supply chains for pharmacopeia users. ECHA's REACH authorization protocols elevate entry barriers for non-compliant suppliers. The Rhine-Main region and Bavaria concentrate ISO 17025-accredited environmental testing facilities under EPA-equivalent protocols.
Japan
Third-party laboratory certification accelerates documented traceability requirements for acid-base titration standards. METI oversight of analytical instrument qualification shapes procurement specifications. The Kanto region around Tokyo and the Kansai industrial belt around Osaka absorb volumes through recurring instrument qualification protocols.
India
CDSCO's tightening GMP inspection protocols for export-oriented API producers create demand for USP-NF compliant primary standards. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat shift from European trader sourcing to qualified local distributors. Hyderabad and Mumbai host expanding QC laboratories serving contract research organizations.
China
Domestic pharmaceutical-grade production scales to serve NMPA-inspected facilities reducing import dependency. MIIT standards for analytical reagents tighten impurity thresholds for domestic consumption. The Yangtze River Delta around Shanghai and the Bohai Rim region concentrate contract manufacturing organizations qualifying for USP-NF and EP export markets.
Potassium Hydrogen Phthalate Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical-grade procurement favoring established reagent brands while industrial applications tolerate distributor-sourced material. The vendor base organizes around three archetypes: integrated chemical conglomerates with captive phthalic anhydride supply, pure-play laboratory reagent specialists with pharmacopeial certification infrastructure, and regional distributors consolidating mid-sized lab procurement. Capacity expansion in high-purity purification trains and strategic partnerships for digital titration system integration represent the dominant competitive moves reshaping positioning.
Within the integrated chemical tier, Merck KGaA and BASF SE exemplify European manufacturers with backward integration into potassium carbonate supply chains and dedicated pharmaceutical-grade production infrastructure. Among North American laboratory supply specialists, Thermo Fisher Scientific Inc. anchors distribution through its Fisher Chemical portfolio, while Avantor Inc. occupies a position in cGMP-compliant pharmaceutical-grade production for biopharma QC workflows. These three companies represent the concentration of pharmacopeial certification capability and channel dominance across the primary demand centers.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| Avantor Inc. |
| Alfa Aesar |
| Tokyo Chemical Industry (TCI) |
| TCI Chemicals |
| BASF SE |
| Solvay SA |
| Honeywell International Inc. |
| Others |
Pricing and Supply Chain Analysis
REACH Annex XIV authorization reviews gate qualified supply for European pharmaceutical-grade production and simultaneously enforce premium-tier pricing access for compliant manufacturers. ECHA's tightening impurity thresholds for phthalate-derived substances compress available certified capacity while elevating documentation costs that transmit directly to buyer invoices.
Pricing Analysis
Volume concentrates in Analytical Reagents while margin pools in Pharmaceutical Grade, creating divergent pricing trajectories across the two tiers. Three-tier pricing structure across pharmaceutical-grade, analytical-reagent, and industrial-grade levels separates USP-NF compliant batches from ISO-certified material from technical-grade bulk. Cost compression in industrial-grade segments is intensifying because sodium hydroxide buffers displace KHP in wastewater testing applications. Academic institutions and mid-sized environmental labs exhibit the highest price sensitivity, whereas biopharma QC departments absorb premium pricing for pre-certified vial formats that compress calibration timelines.
Supply Chain Analysis
Single-source vulnerability sits with German and Chinese specialty chemical producers of high-purity phthalic anhydride, the critical feedstock for KHP synthesis. Manufacturing capacity clusters in Germany, the United States, and Japan, with these three countries anchoring pharmaceutical-grade purification infrastructure. The supply chain draws from potassium carbonate, phthalic anhydride, and hydrochloric acid as primary inputs. Tariff exposure on Chinese phthalic anhydride imports threatens margin stability for non-integrated producers. Distribution runs through laboratory chemical aggregators including Fisher Scientific's North American channel, which consolidates procurement for mid-sized analytical labs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing captive phthalic anhydride supply to escape feedstock volatility and secure pharmacopeial certification continuity.
For Market Incumbents: Acquire dedicated phthalic anhydride purification trains to secure high-purity feedstock access against Chinese supply concentration risk. Expand cGMP-compliant production capacity in Germany or the United States to capture biopharma QC volume growth. Sodium hydroxide buffer substitution in wastewater testing threatens industrial-grade margins, making backward integration into potassium carbonate supply essential for cost control. For New Entrants and Emerging Players: Begin with CDSCO-inspected API producers in India as the most penetrable customer segment, where tightening GMP protocols create demand for USP-NF compliant primary standards previously sourced from European traders. Target automated titration system partnerships as a go-to-market angle, embedding KHP cartridges into equipment service contracts that lock in recurring revenue streams. For Investors and Strategic Acquirers: ECHA's 2023 endocrine disruptor classification guidance triggering reformulation assessments is the leading indicator that dedicated pharmaceutical-grade purification infrastructure will command scarcity premiums. Over a five-to-ten-year horizon, vertically integrated manufacturers with REACH registration and USP-NF monograph maintenance capabilities represent the most defensible acquisition profile. Monitor REACH Annex XIV authorization review timelines as the critical signal for capacity exit and consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phthalic Anhydride | Captive feedstock supply insulates margins from Chinese producer concentration risk. |
| cGMP Production Capacity Expansion | FDA inspection readiness qualifies suppliers for biopharma QC workflow capture. |
| Digital Titration System Partnership | RFID-tagged vial integration with Merck KGaA and Thermo Fisher platforms automates calibration protocols. |
| REACH Registration Maintenance | ECHA compliance preserves European market access as authorization barriers elevate. |
| Indian Distribution Qualification | CDSCO-aligned local presence captures API producer demand shifting from European traders. |
Research Methodology
Pharmacopeial monograph databases, ECHA substance registration filings, and customs trade records formed the secondary backbone for supply-side mapping and regulatory trajectory assessment. Primary interviews with plant managers at European reagent manufacturers, procurement leads at biopharma QC laboratories, distribution channel partners in North America, and technical R&D directors at analytical instrument companies validated demand patterns and pricing dynamics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators to ensure internal consistency across grade-tier forecasts.
Historical trendline analysis of sodium hydroxide calibration cycle frequency, REACH registration timelines, and pharmacopeial revision patterns established baseline growth assumptions. The modeling framework segmented demand by product grade, end-use industry, regulatory compliance tier, and regional production hub across the projection horizon. CAGRs were derived from fitted growth curves adjusted for substitution elasticity in wastewater testing applications and biopharma manufacturing expansion rates.
Underlying measurement precision varies by segment; Pharmaceutical Grade and Calibration Standards applications carry tighter precision than Industrial Grade and Food Additives given more transparent regulatory documentation requirements. Forecasts reflect assumptions about pharmacopeial harmonization velocity, ECHA authorization stringency, and biopharma manufacturing geographic shifts that could materially revise outcomes. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Monoisopropanolamine (MIPA) Market
Chemicals
Neopentyl Polyhydric Alcohol Market
Chemicals
Asia Pacific Waterproofing Chemicals Market
Chemicals
Global Biotechnology-Based Chemical Market
Chemicals
Desalination Chemicals Market
Chemicals
Silicone Textile Softeners Market
Chemicals
Sodium Phosphate Tribasic Market
Chemicals
Household Insecticides Market
Chemicals
Cetyl Stearyl Alcohol Market
Chemicals
Superphosphoric Acid (SPA) Market
Chemicals
Fluorine Derivatives Market
Chemicals
Calcium Carbide Market
Chemicals
Pyrimidine Market
Chemicals
Diphenyl Sulfone Market
Chemicals
De-Icing Agents Market
Chemicals
North America Construction Chemicals Market