
 Middle East and Africa Non-Surgical Procedures Market | 2026-2036
Middle East and Africa Non-Surgical Procedures Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Non-Surgical Procedures Market Foresight
Licensed aesthetic practitioners across the Middle East and Africa is rotating from basic injectable administration toward advanced combination therapies involving energy-based devices. Alma Lasers leverages its Tel Aviv R&D base to dominate laser and energy-device supply across Gulf dermatology centers. Galderma sustains premium positioning in hyaluronic acid fillers through dedicated medical education programs for Arab-speaking clinicians. Allergan anchors botulinum toxin volumes via established distribution partnerships with hospital-affiliated clinics in South Africa and the UAE.
Non-surgical procedures encompass minimally invasive aesthetic interventions performed without excisional surgery, typically involving percutaneous delivery of neurotoxins, volumizing fillers, or selective thermal injury via calibrated wavelengths between 532 nm and 10,600 nm for tissue remodeling. These interventions serve commercial purposes spanning facial rejuvenation, body contouring, and skin tightening for outpatient consumers seeking reduced downtime relative to surgical alternatives. Botulinum toxin and dermal fillers together command the dominant product share, with laser treatments generating premium pricing in medical spa settings where device amortization and consumable costs structure margin pools differently. Chemical peels occupy a mature tier, while radiofrequency and ultrasound technologies within the technology dimension attract accelerated capital deployment from clinic chains seeking differentiation through lifting and tightening outcomes without injectables.
SFDA device registration requirements and MOHAP facility licensing standards shape market access by mandating clinical evidence packages and practitioner certification thresholds for energy-based systems. The UAE's health tourism certification framework and South Africa's Health Products Regulatory Authority (SAHPRA) oversight of dermal fillers further segment compliance burdens by product risk class. Stakeholders must monitor evolving national reimbursement classifications for medically indicated versus purely cosmetic applications, as these determinations will influence private-pay pricing elasticity and clinic investment cycles across the region.
Market Dynamics
Practitioner certification thresholds and device registration requirements across Gulf Cooperation Council states are compressing market entry timelines and reshaping competitive positioning among clinic operators and equipment suppliers.
Growth Catalysts
- SFDA streamlined pathways:The Saudi Food and Drug Authority's accelerated review for Class II energy-based devices reduces approval cycles for radiofrequency and ultrasound systems entering dermatology centers.
- Medical tourism infrastructure:Dubai Health Authority's health tourism certification framework attracts cross-border patients from Sub-Saharan Africa and South Asia seeking aesthetic interventions.
- Combination therapy protocols:Clinics are stacking botulinum toxin with fractional laser resurfacing to improve patient retention and per-visit revenue.
Market Restraints
- Consumable cost volatility:Hyaluronic acid filler prices fluctuate with raw material sourcing from bacterial fermentation facilities concentrated in Western Europe.
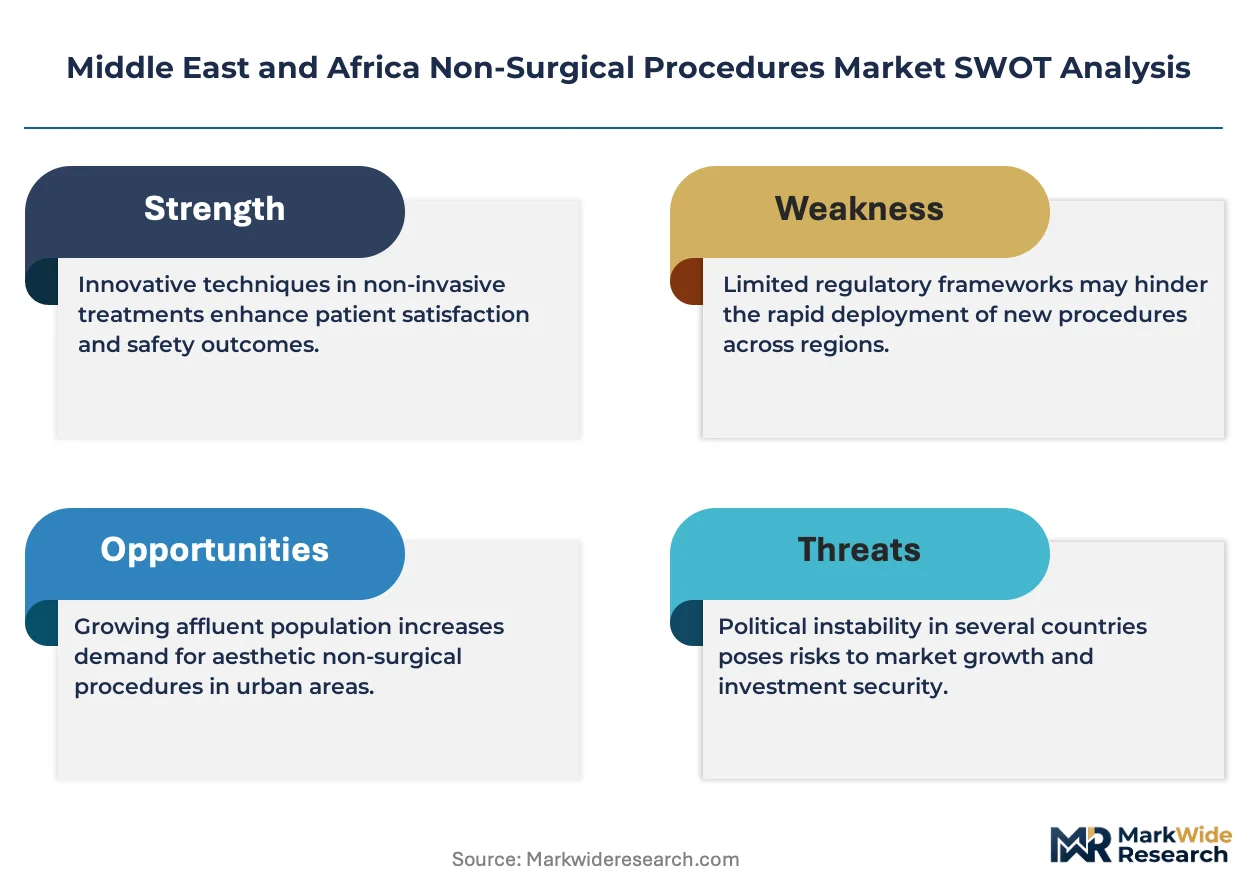
- Practitioner supply concentration:Board-certified dermatologists and plastic surgeons cluster in Dubai, Riyadh, and Johannesburg, leaving secondary cities underserved.
- Device amortization burdens:Picosecond laser platforms require 800-1200 annual treatment sessions to achieve positive clinic-level returns.
Strategic Opportunities
- Nigeria's urban corridor:Lagos and Abuja present underpenetrated demand for injectables among affluent demographics with limited local provider density.
- Teleconsultation pre-screening:Virtual assessment protocols are reducing no-show rates and expanding catchment areas for fixed-site medical spas.
- MOHAP quality tiering:The UAE's facility grading system creates differentiation pathways for premium-positioned clinics to command rate premiums.
Industry Challenges
- Combination therapy training gaps:Practitioners licensed for single-modality administration require upskilling to safely sequence neurotoxins with energy-based devices.
- SAHPRA import documentation:South Africa's Health Products Regulatory Authority imposes batch-specific testing requirements that extend dermal filler lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Non-Surgical Procedures Market |
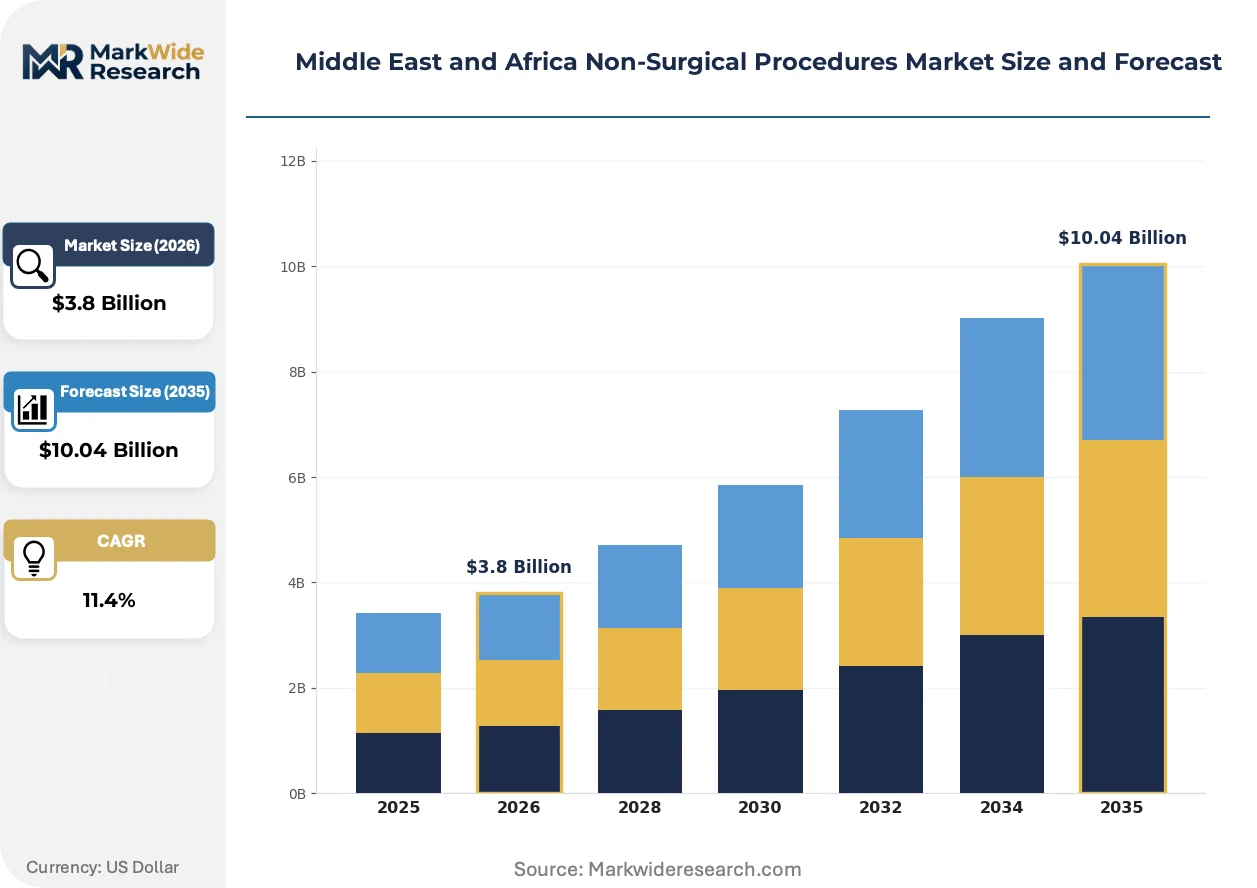
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Botulinum Toxin, Dermal Fillers, Laser Treatments, Chemical Peels End User: Clinics, Medical Spas, Dermatology Centers, Beauty Salons Technology: Radiofrequency, Ultrasound, Cryotherapy, IPL Application: Facial Rejuvenation, Body Contouring, Skin Tightening, Hair Removal |
| Companies Covered | Alma Lasers, Cynosure, Allergan, Prollenium Medical Technologies, Lumenis, Galderma, Johnson & Johnson Services, Inc., Bausch Health Companies Inc, Merz Pharma, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Non-Surgical Procedures Market Shifts & Advancements
Energy-based modalities and practitioner credentialing systems are fragmenting traditional service delivery models across Middle Eastern and African aesthetic markets.
Picosecond laser technology is fragmenting established nanosecond platforms in pigmented lesion and tattoo removal applications. High-volume medical spas in Dubai and Riyadh are replacing legacy Q-switched systems to reduce treatment sessions per indication. This hardware transition is fragmenting service pricing structures and compressing per-procedure margins for clinics retaining older equipment.
MOHAP's 2024 facility licensing amendments mandate real-time adverse event reporting for energy-based devices operating above 10 watts. The regulation forces clinic chains to deploy integrated practice management systems with automated incident logging. Smaller independent operators in Sharjah and Ajman face disproportionate compliance costs relative to hospital-affiliated networks.
Subscription-based maintenance packages are displacing per-visit fee structures among affluent patient cohorts in Saudi Arabia and the UAE. Medical spas in Jeddah and Abu Dhabi are bundling quarterly toxin touch-ups with annual laser resurfacing protocols. This shift concentrates patient lifetime value calculations and rewards clinics with superior retention infrastructure.
Middle East and Africa Non-Surgical Procedures Market Segmentation
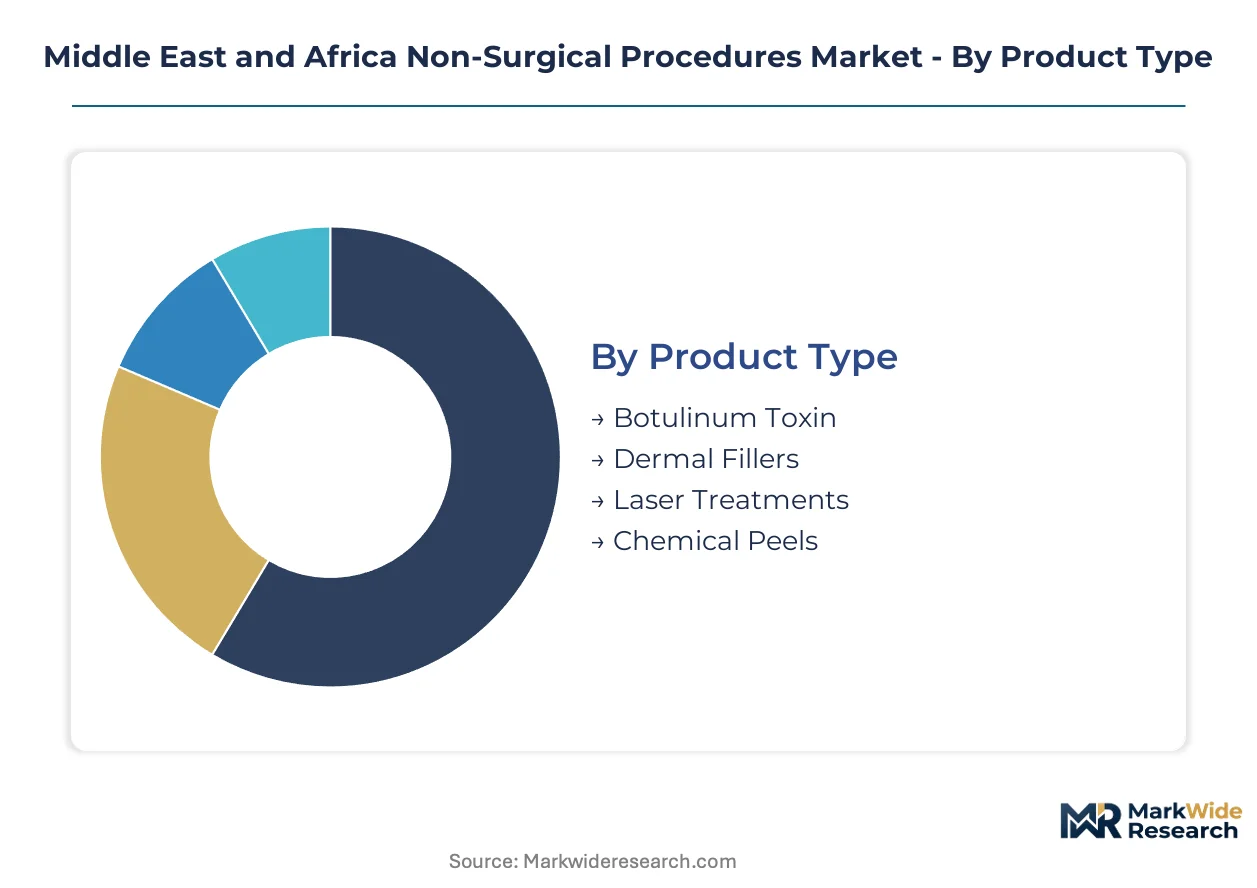
Segmentation in the Middle East and Africa non-surgical procedures market reveals how margin pools concentrate across product categories and where capital deployment follows patient flow patterns. Understanding these divisions exposes where clinic chains and device suppliers compete for pricing power and volume retention.
Product Type:
Margin pools in this category concentrate in injectable modalities where consumable costs structure recurring revenue streams differently than capital-intensive energy devices.
- Botulinum Toxin:Purified neurotoxin protein delivered via intramuscular injection to induce temporary chemodenervation of targeted facial muscles. Demand clusters in Dubai and Riyadh medical tourism corridors where repeat treatment intervals drive patient lifetime value calculations for clinic operators.
- Dermal Fillers:Cross-linked hyaluronic acid or calcium hydroxylapatite formulations injected subdermally to restore volume or contour facial architecture. Johannesburg and Jeddah dermatology centers report rising uptake among patients seeking alternatives to surgical rhinoplasty or blepharoplasty.
- Laser Treatments:Selective photothermolysis using calibrated wavelengths for pigment, vascular, or resurfacing indications.
- Chemical Peels:Acid-based exfoliation protocols ranging from superficial glycolic applications to deep phenol resurfacing.
Botulinum toxin holds installed capacity across Gulf Cooperation Council states. Dermal fillers are rotating up the share rankings in South African metropolitan markets.
End User:
Volume distribution across this category tracks facility licensing tiers and practitioner certification density, with patient flow concentrating where regulatory compliance creates barrier-protected catchment zones.
- Clinics:Outpatient facilities staffed by licensed physicians performing injectable and energy-based procedures under national medical practice regulations. Lagos and Abuja show expanding clinic counts as Nigerian physician entrepreneurs respond to affluent urban demand.
- Medical Spas:Hybrid hospitality-healthcare environments offering aesthetic services in amenity-rich settings. Dubai Health Authority certification requirements filter market entry, concentrating premium-positioned operators in Emirates Hills and Downtown Dubai corridors.
- Dermatology Centers:Specialist-led facilities with advanced diagnostic and therapeutic equipment portfolios.
- Beauty Salons:Non-medical establishments offering superficial aesthetic services with limited device penetration.
Dermatology centers hold installed capacity across the UAE and Saudi Arabia. Medical spas are climbing the fastest in patient visit volume rankings.
Technology:
Capital deployment intensity varies sharply across this category, with device amortization schedules and consumable attach rates determining clinic-level return thresholds.
- Radiofrequency:Electromagnetic energy delivery at 0.3-10 MHz to induce dermal collagen remodeling through controlled thermal injury. Jeddah and Riyadh clinic chains prioritize radiofrequency platforms for skin tightening protocols that avoid injectable dependency.
- Ultrasound:Focused or unfocused acoustic energy transmission for adipose tissue disruption or superficial muscular aponeurotic system lifting. Dubai medical spas deploy microfocused ultrasound for brow lifting applications targeting patients seeking alternatives to surgical facelifting.
- Cryotherapy:Controlled cold exposure for adipocyte apoptosis or superficial lesion destruction.
- IPL:Broadband light emission for photorejuvenation and hair reduction indications.
Radiofrequency holds installed capacity across Gulf dermatology networks. Ultrasound is expanding most quickly in premium clinic positioning strategies.
Application:
Patient motivation and pricing elasticity diverge across this category, with facial applications commanding premium rates and body applications requiring higher marketing expenditure per acquisition.
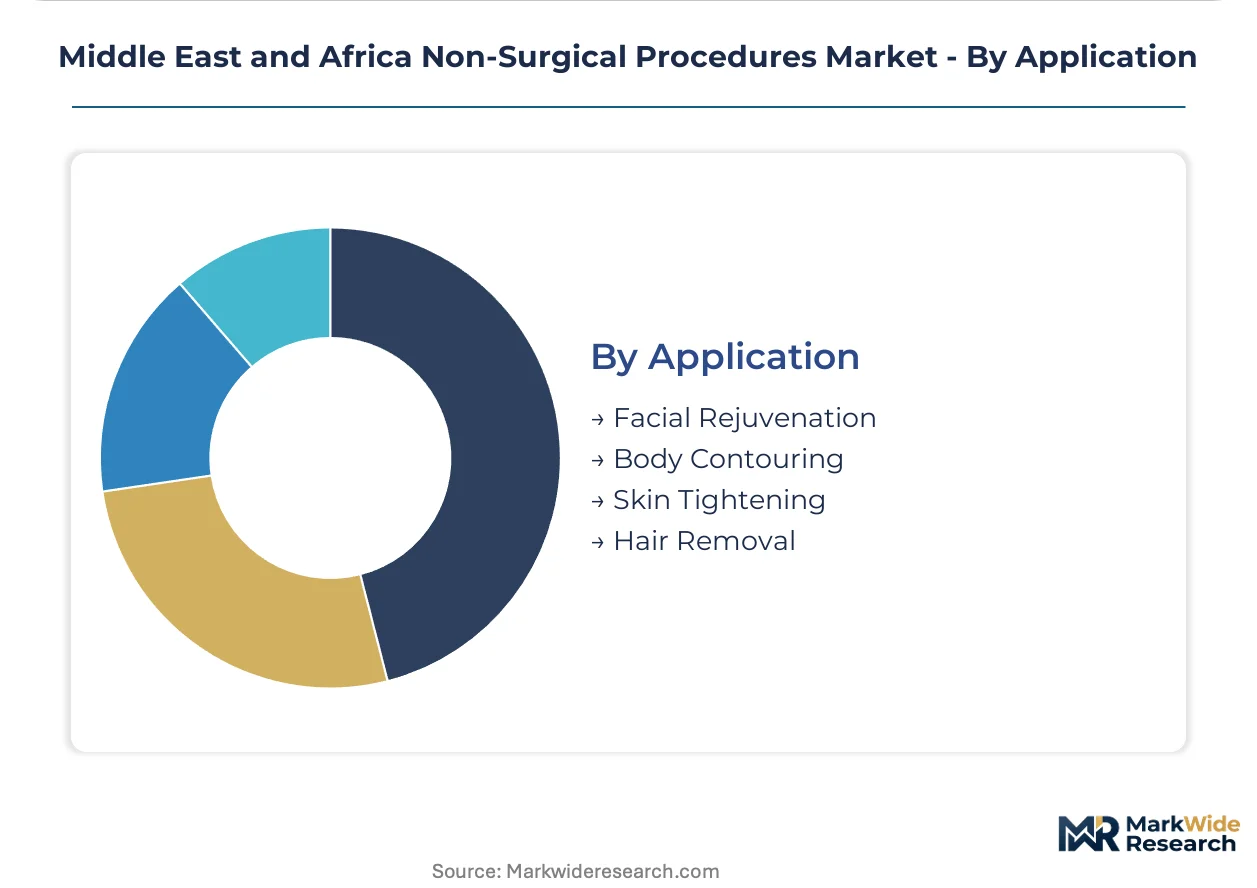
- Facial Rejuvenation:Comprehensive treatment protocols addressing rhytides, volume loss, and skin quality degradation through combined neurotoxin, filler, and energy-based interventions. Sharjah and Ajman clinics report rising demand for multi-modality facial packages among Emirati and expatriate patient cohorts.
- Body Contouring:Non-invasive adipose reduction and silhouette reshaping using cryolipolysis, radiofrequency, or high-intensity focused electromagnetic technologies. Johannesburg aesthetic practices target body contouring growth among postpartum demographics and weight-stable patients seeking localized fat reduction.
- Skin Tightening:Collagen induction and dermal contraction protocols for laxity correction.
- Hair Removal:Photothermal destruction of follicular units using laser or IPL platforms.
Facial rejuvenation holds installed capacity across Middle Eastern medical tourism destinations. Body contouring is gaining share fastest in South African urban markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Middle East and Africa non-surgical procedures market displays pronounced consumption-mix differentials, with Gulf Cooperation Council states prioritizing premium combination therapies while South African demand concentrates on accessible injectable modalities.
United Arab Emirates
Dubai's medical tourism corridor attracts cross-border patients from Sub-Saharan Africa and South Asia seeking facial rejuvenation protocols. MOHAP facility licensing amendments mandate real-time adverse event reporting for energy-based devices above 10 watts, forcing clinic chains toward integrated practice management systems. Emirates Hills and Downtown Dubai corridors concentrate premium-positioned medical spa operators.
Saudi Arabia
Jeddah and Riyadh dermatology centers report rising demand for radiofrequency skin tightening as an alternative to injectable dependency. SFDA accelerated review pathways for Class II energy-based devices compress approval cycles for radiofrequency and ultrasound systems. Western Region clinic chains prioritize subscription-based maintenance packages bundling quarterly toxin touch-ups with annual laser protocols.
South Africa
Johannesburg aesthetic practices target body contouring growth among postpartum demographics seeking localized fat reduction. SAHPRA imposes batch-specific testing requirements for dermal filler imports, extending lead times for Johannesburg and Cape Town distributors. Metropolitan markets show rotating demand from basic injectables toward advanced combination therapies.
Israel
Tel Aviv anchors regional R&D activity for laser and energy-device innovation, with technology transfer flowing into Gulf dermatology networks. The national pharmaceutical regulator maintains stringent clinical evidence requirements for device registrations. Herzliya Pituach clusters house development operations supplying picosecond platforms to high-volume medical spas.
Nigeria
Lagos and Abuja present underpenetrated demand for injectables among affluent demographics with limited local provider density. The country's national health regulator is developing framework legislation for aesthetic device classifications. Physician entrepreneurs in Lagos Island and Maitama districts are expanding outpatient clinic counts to capture urban professional demand.
Middle East and Africa Non-Surgical Procedures Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with device manufacturers and pharmaceutical suppliers occupying distinct competitive spaces. The upper tier combines energy-based platform portfolios with established distribution networks across Gulf dermatology centers. Specialist archetypes include Tel Aviv-based laser innovators, Swiss-German toxin and filler houses, and North American injectable platform holders. Dominant competitive moves center on medical education partnerships for practitioner certification and exclusive distribution agreements with hospital-affiliated clinic networks.
Within the integrated device tier, Alma Lasers and Lumenis exemplify vertically structured suppliers leveraging geographic proximity to Gulf markets. Among pharmaceutical injectable specialists, Galderma and Allergan occupy positions defined by hyaluronic acid filler and botulinum toxin portfolios respectively. These named entities represent archetype anchors rather than exhaustive market coverage, with each exemplifying distinct strategic postures around practitioner education investment and premium positioning through medical spa channel control.
| Leading Market Players |
|---|
| Alma Lasers |
| Cynosure |
| Allergan |
| Prollenium Medical Technologies |
| Lumenis |
| Galderma |
| Johnson & Johnson Services, Inc. |
| Bausch Health Companies Inc |
| Merz Pharma |
| Others |
Supply & Pricing Matrix
Subscription-based maintenance packages for toxin and laser bundling lock in Gulf clinic chains to predictable revenue streams while insulating them from hyaluronic acid filler spot-price volatility. These multi-year patient contracts tie device amortization schedules to consumable replenishment, creating price visibility that independent operators in secondary Emirati cities cannot replicate.
Pricing Analysis
Long-term offtake agreements between Jeddah clinic chains and Swiss-German toxin suppliers structure pricing around volume-commitment tiers rather than spot-market fluctuations. Three-tier pricing structure across premium, standard, and economy levels separates Dubai Health Authority-certified medical spas from MOHAP-registered clinics and unlicensed beauty salons. Pricing pressure stems from SAHPRA batch-testing requirements extending South African filler lead times and inflating landed costs. Price-sensitive patients concentrate in Johannesburg's outer metropolitan zones, while Dubai's medical tourism corridor sustains premium tolerance through bundled hospitality packages.
Supply Chain Analysis
Western Europe anchors bacterial fermentation capacity for cross-linked hyaluronic acid, while Israel's Tel Aviv corridor supplies picosecond laser platforms to Gulf dermatology networks. South Korean and German manufacturers feed radiofrequency and ultrasound device demand across Saudi Arabia and the UAE. Raw material dependencies rest on stabilized hyaluronic acid powder, precision optical components, and disposable injection needles. Single-source vulnerability concentrates in Swiss-German neurotoxin production facilities serving the GCC. Distribution runs through hospital-affiliated procurement consortia in Riyadh and Dubai, with Lagos and Abuja relying on gray-market intermediaries for filler access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Board-certified practitioner density in Dubai, Riyadh, and Johannesburg constrains service expansion, leaving secondary cities and underpenetrated Nigerian urban corridors exposed to quality-compromised entrants.
For Market Incumbents: Fortify practitioner certification pipelines through exclusive MOHAP and SFDA-accredited training partnerships, locking in supply access to toxin and filler portfolios before regulatory thresholds tighten. Vertical integration into energy-device maintenance services captures recurring revenue from picosecond laser platforms requiring 800-1200 annual sessions for positive returns. Defend against Tel Aviv-based laser innovators by securing exclusive distribution with hospital-affiliated clinic networks in the Western Region and Emirates Hills corridors. For New Entrants and Emerging Players: SFDA accelerated review pathways for Class II energy-based devices present the fastest certification fast-track for radiofrequency and ultrasound system suppliers seeking Saudi market entry. Lagos and Abuja's underpenetrated affluent demographics offer white-space targeting with limited local provider density and rising demand for injectables. Teleconsultation pre-screening protocols reduce no-show rates and expand catchment areas without fixed-site infrastructure investment. For Investors and Strategic Acquirers: Capital is best deployed toward clinic chains with integrated practice management systems capable of real-time adverse event logging under MOHAP's amended facility licensing requirements. Long-term viability hinges on patient retention infrastructure supporting subscription-based maintenance bundling across toxin touch-ups and annual laser protocols. Watch SFDA device registration backlogs as an inflection indicator for competitive entry timing in Saudi Arabia's Western Region.| Strategic Initiative | Industry Significance |
|---|---|
| Practitioner Certification Pipeline Investment | MOHAP and SFDA-accredited training partnerships lock in supply access to premium toxin and filler portfolios. |
| Integrated Practice Management System Deployment | Automated adverse event logging satisfies MOHAP's 2024 facility licensing amendments for energy-based devices. |
| Subscription-Based Maintenance Bundling | Quarterly toxin touch-ups with annual laser protocols concentrate patient lifetime value in Jeddah and Abu Dhabi. |
| Teleconsultation Pre-Screening Infrastructure | Virtual assessment protocols reduce no-show rates and expand catchment areas for fixed-site medical spas. |
| Exclusive Distribution with Hospital-Affiliated Networks | Channel control through Riyadh and Dubai hospital systems defends against Tel Aviv-based laser innovators. |
Research Methodology
A standing panel of board-certified dermatologists, plastic surgeons, medical spa operators, and SFDA regulatory affairs specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from MOHAP facility licensing databases, SAHPRA import documentation filings, Dubai Health Authority health tourism certification records, and GCC customs trade data for aesthetic device imports. Bottom-up procedure-volume estimates from Lagos, Abuja, Johannesburg, and Cape Town clinics triangulated against top-down market sizing from Gulf Cooperation Council national health accounts.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, end-user facility tier, technology modality, and application area, with regional regulatory cluster as an additional cross-cutting variable. CAGRs derived from procedure-volume growth trajectories, pricing elasticity assumptions for medical tourism versus domestic patient cohorts, and device replacement cycles for picosecond laser platforms displacing legacy Q-switched systems.
Decision-makers should treat outputs as directional under assumptions of stable SFDA and MOHAP regulatory frameworks; material deviation in practitioner certification thresholds or device registration timelines would warrant model refresh. Recalibration cycles align with material shifts in Gulf medical tourism patient flows, SAHPRA import documentation requirements, and Nigerian national health regulator framework legislation for aesthetic device classifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Craniomaxillofacial Devices Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Inversion Table Market
Medical Devices
Global Glaucoma Surgery Devices Market
Medical Devices
Mexico Ultrasound Devices Market
Medical Devices
EMG Biosensors Market
Medical Devices
Intravaginal Device Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market
Medical Devices
Pet Mobility Aids Market
Medical Devices
Indwelling Pleural Catheters Market
Medical Devices
Global Electrosurgery Generator Market
Medical Devices
Self-Sampling Blood Collection and Storage Devices Market
Medical Devices
Oxygen Delivery Units Market
Medical Devices
Telehealth Device Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Transradial Access Devices Market