
 Electric Bicycle Market | 2026-2036
Electric Bicycle Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Bicycle Market Analysis
Modular battery-swapping configurations is expanding buyer choice by decoupling vehicle purchase from energy ownership, reducing upfront costs for fleet operators and commuters alike. Giant Manufacturing Co., Ltd. leverages integrated frame-motor architectures to dominate premium original equipment channels across Asia and Europe. Rad Power Bikes competes through direct-to-consumer pricing and expansive accessory ecosystems that sustain repeat purchase frequency. Yamaha Motor Co., Ltd. anchors its position via proprietary drive unit reliability and long-standing relationships with Japanese and European assemblers.
An electric bicycle combines a pedal-driven cycle with an integrated electric motor, battery pack, and controller system, typically delivering supplementary power up to regulated speed thresholds through hub-mounted or crank-integrated drive units. Lithium-ion battery chemistry dominates product configurations due to superior energy density, cycle life, and declining cell costs relative to lead-acid alternatives. City bikes occupy the largest volume share as municipal congestion charges and parking scarcity push commuters toward motorized two-wheel alternatives. Mid-drive motor technology captures disproportionate margin pools among touring and mountain bike segments where torque sensing and gear integration command premium positioning.
The EU Green Deal and associated national subsidy frameworks in Germany, France, and the Netherlands directly shape demand by offsetting purchase prices and mandating cycling infrastructure investment. In the United States, the Consumer Product Safety Commission and state-level three-class designation systems govern motor wattage, speed limits, and trail access eligibility, creating fragmented compliance requirements for manufacturers. China's GB standards and NMPA-equivalent quality certifications enforce battery safety protocols and motor performance labeling that govern export eligibility. Stakeholders must monitor evolving subsidy phase-out schedules and emerging battery recycling mandates to anticipate margin compression and circular economy compliance obligations.
Market Dynamics
Fleet electrification mandates across European logistics operators are compressing replacement cycles for urban delivery vehicles, with cargo e-bikes capturing van displacement volume as congestion pricing and low-emission zones harden operational economics for combustion fleets.
Growth Catalysts
- EU Green Deal mobility targets:Binding carbon reduction commitments force municipal procurement toward zero-emission last-mile solutions, accelerating fleet conversion timelines across German, French, and Dutch urban logistics networks.
- Lithium-ion cell cost curves:Declining battery pack economics shrink total cost of ownership gaps against pedal bicycles and combustion alternatives, enabling price accessibility for commuter and commercial segments simultaneously.
- Amsterdam cycling infrastructure density:Network completeness demonstrates modal shift viability, with protected lane mileage and parking integration creating reference architecture replicable in Copenhagen, Utrecht, and emerging cycling cities.
Market Restraints
- Battery raw material concentration:Cathode precursor and cell manufacturing gravity in East Asian supply basins exposes European and North American assemblers to freight cost volatility and geopolitical supply rationing.
- Speed and power regulatory fragmentation:Divergent national classifications for pedal-assist thresholds, throttle legality, and trail access permissions force SKU proliferation and compliance engineering overhead.
- Lead-acid residual cost competition:Price-sensitive segments in emerging markets retain incumbent chemistry for entry-tier products, delaying lithium-ion penetration where total cost of ownership calculations exclude cycle life.
Strategic Opportunities
- Sub-Saharan African urban mobility:Grid reliability gaps and fuel price volatility position solar-charged e-bike networks as viable motorcycle displacement, with pay-as-you-go battery subscription models reducing capital barriers.
- Mid-drive torque sensing convergence:Integration of load-adaptive motor control with automatic transmission systems opens premium positioning in cargo and touring segments where gradient performance determines purchase decisions.
- France's cycle-to-work subsidy expansion:Employer-funded lease programs convert upfront purchase friction into recurring revenue streams for fleet operators and financial services intermediaries.
Industry Challenges
- Power electronics firmware specialization:Scarce embedded systems talent for motor control algorithm development concentrates at drive unit suppliers, constraining in-house R&D scaling for frame manufacturers.
- UNECE battery certification timelines:Extended type-approval procedures for novel cell formats and thermal management architectures delay product launch windows and freeze inventory commitments.
- Service network density requirements:Complex mid-drive drivetrain maintenance demands skilled technician availability that lags sales growth in markets without established bicycle service infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Bicycle Market |
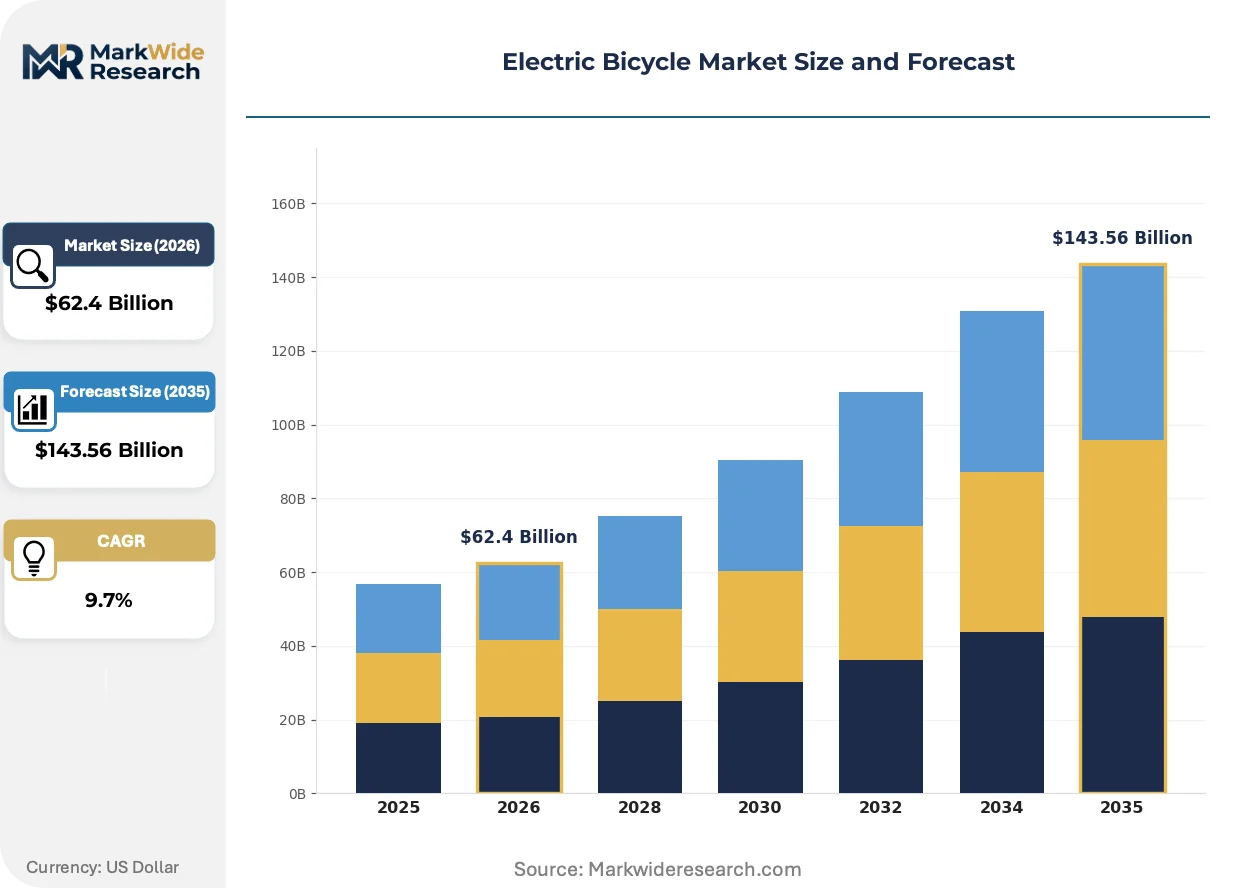
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $143.56 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: City Bikes, Mountain Bikes, Touring Bikes, Folding Bikes Technology: Hub Motor, Mid Drive, Battery Management, Regenerative Braking End User: Commuters, Recreational Users, Delivery Services, Fitness Enthusiasts Battery Type: Lead Acid, Lithium-Ion, Nickel-Metal Hydride, Others |
| Companies Covered | Giant Manufacturing Co., Ltd., Yamaha Motor Co., Ltd., Trek Bicycle Corporation, Rad Power Bikes, Aventon Bikes, Accell Group, Specialized, Bosch eBike Systems, Pedego Electric Bikes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Bicycle Market Emerging Trajectories
Battery-swapping infrastructure and smart motor control architectures are redefining ownership models and performance benchmarks, with interoperability standards emerging as the critical coordination mechanism across competing hardware ecosystems.
Cell-to-pack battery architectures are integrating thermal management and structural load-bearing functions into unified frame components. European cargo bike manufacturers are adopting these platforms to maximize range per kilogram while preserving payload capacity for commercial routes. This consolidation is integrating energy storage design into early-stage frame engineering, collapsing traditional supplier boundaries between battery pack assemblers and bicycle frame fabricators.
REACH battery recycling mandates and emerging EU Battery Regulation due diligence requirements are imposing chain-of-custody documentation obligations on cell suppliers and original equipment manufacturers. Industrial consequence includes mandatory recycled content thresholds and producer responsibility financing for end-of-life collection infrastructure. Premium city bike and cargo segments face earliest compliance pressure, with Dutch and German market leaders accelerating supplier qualification audits to secure qualified recycled material streams.
Subscription-based access models are displacing outright purchase for urban commuter and light commercial segments. Fleet operators and mobility-as-a-service platforms are capturing demand through all-inclusive monthly tariffs bundling hardware, maintenance, and energy access. This shift is most visible in Paris and Barcelona, where municipal micro-mobility concessions and corporate commute benefit programs normalize operational expenditure treatment over capital deployment.
Electric Bicycle Market Segmentation
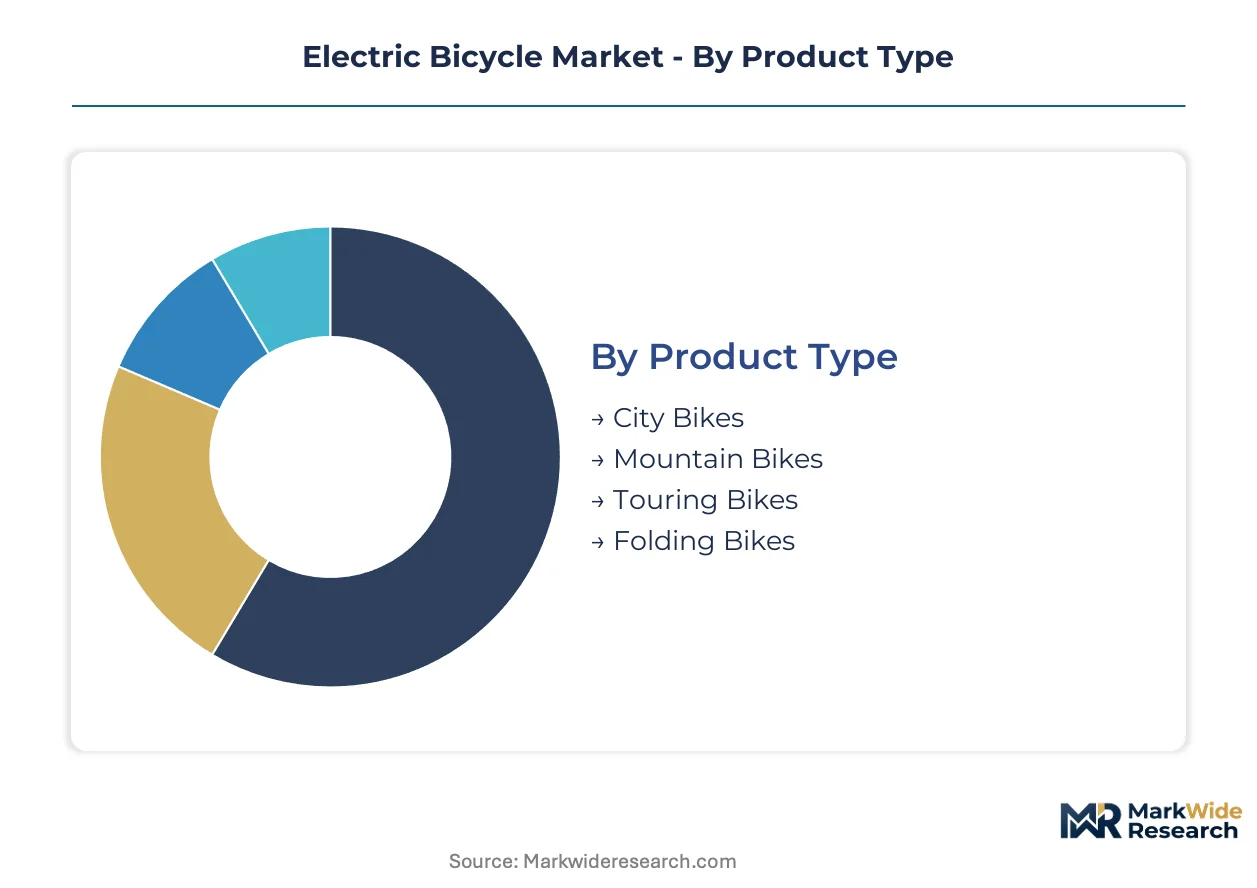
Electric bicycle segmentation reveals divergent margin structures across product architectures and user profiles. Understanding these splits enables manufacturers to align R&D investment with where purchase premiums concentrate versus where volume scales.
Product Type:
City bikes dominate unit economics through municipal subsidy alignment and parking scarcity, while mountain and touring variants extract premiums through component sophistication.
- City Bikes:Step-through frames and integrated lighting packages define the urban commuter specification. Dutch and German municipal procurement programs concentrate demand here, with protected lane infrastructure in Amsterdam, Copenhagen, and Utrecht validating modal shift economics for daily travel under 15 kilometers.
- Mountain Bikes:Full-suspension frames paired with high-torque mid-drive systems enable technical trail climbing. The segment commands disproportionate margins in Alpine regions of France, Switzerland, and Austria where gradient performance determines purchase decisions and service network density supports complex drivetrain maintenance.
- Touring Bikes:Long-range battery integration and rack-load compatibility serve multi-day route cyclists across European long-distance cycle networks.
- Folding Bikes:Hinge-frame engineering and reduced wheel diameters address intermodal commuters in London, Paris, and Barcelona rail systems.
Today's leader: City Bikes. Tomorrow's challenger: Mountain Bikes.
Technology:
Drive unit placement determines service complexity, battery thermal management shapes safety compliance, and energy recovery systems differentiate premium positioning.
- Hub Motor:Direct-drive or geared wheel-integrated motors simplify maintenance and reduce drivetrain wear. The configuration scales most cost-effectively in Asian manufacturing basins serving price-sensitive European fleet operators and North American direct-to-consumer channels.
- Mid Drive:Crank-integrated torque sensors optimize power delivery through gear ranges. German and Japanese drive unit suppliers dominate this technology layer, with KBA type-approval requirements in Germany and JIS certification in Japan creating regulatory moats around established assemblers.
- Battery Management:Cell balancing algorithms and thermal runaway prevention circuits govern warranty exposure and UNECE certification timelines.
- Regenerative Braking:Kinetic energy recovery systems extend range in hilly terrain and urban stop-start routes.
Hub Motor captures present volume. Mid Drive claims expanding margin pools.
End User:
Commercial fleet procurement cycles compress replacement timelines against individual consumer purchase patterns, while fitness applications sustain accessory aftermarket revenue.
- Commuters:Daily urban travelers prioritize reliability and theft deterrence through integrated locks and GPS tracking. France's cycle-to-work subsidy expansion and Netherlands employer lease programs convert this segment toward subscription-based access models.
- Recreational Users:Weekend riders and leisure cyclists respond to styling and brand positioning over technical specifications. Seasonal demand concentration in Mediterranean climates creates inventory planning challenges for Southern European retailers.
- Delivery Services:Last-mile logistics operators in Berlin, Paris, and London displace combustion vans with cargo-configured e-bikes under low-emission zone compliance pressure.
- Fitness Enthusiasts:Training-oriented riders demand power meter integration and app-connected performance analytics.
Delivery Services drive fastest fleet conversion. Commuters anchor installed base expansion.
Battery Type:
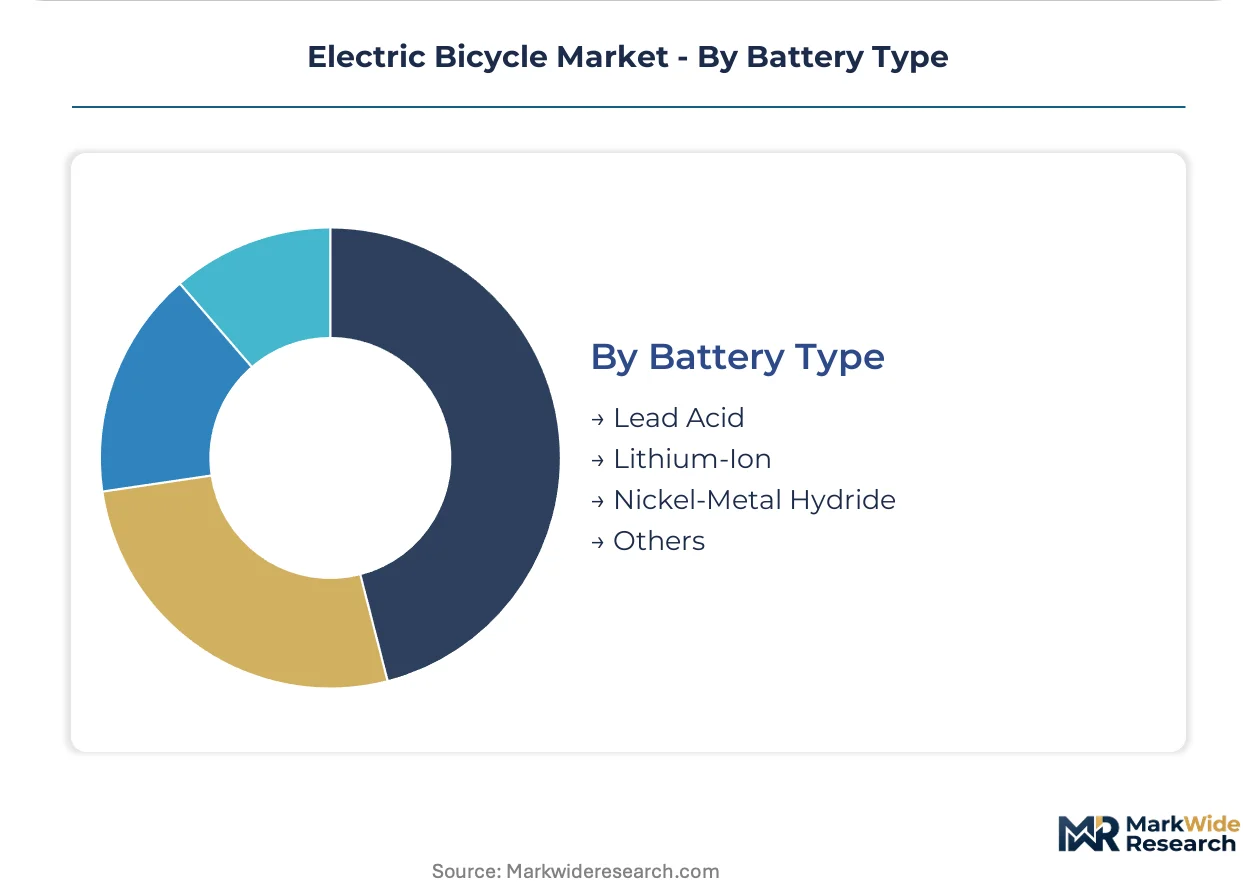
Chemistry selection governs energy density, cycle life, and compliance with emerging EU Battery Regulation due diligence requirements.
- Lithium-Ion:NMC and LFP cell formats deliver superior watt-hour density and 800-plus cycle durability. REACH recycling mandates and mandatory recycled content thresholds under EU Battery Regulation impose chain-of-custody documentation on European assemblers sourcing from East Asian cell manufacturers.
- Lead Acid:Mature chemistry retains cost advantage in Indian and Southeast Asian price-sensitive markets where total cost of ownership calculations exclude cycle life and replacement frequency.
- Nickel-Metal Hydride:Intermediate energy density serves niche applications in cold-climate deployments where lithium-ion thermal management adds cost.
- Others:Emerging solid-state and sodium-ion formats occupy pre-commercial development phases.
Lithium-Ion commands technology transition. Lead Acid persists in emerging market entry tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electric bicycle industry traces its commercial origins to Japanese and European engineering laboratories of the 1990s, where torque-sensing pedal-assist systems first achieved production viability. German and Dutch municipal procurement programs subsequently established the reference markets that shaped contemporary product specifications and subsidy frameworks.
Germany
KBA type-approval requirements for drive units and speed pedelecs create regulatory moats around established assemblers while compressing launch timelines for new entrants. The country's cycle-to-work subsidy expansion converts commuter purchase friction into employer-funded lease programs. Berlin and Munich anchor fleet procurement volumes as logistics operators displace combustion vans under low-emission zone compliance pressure.
Netherlands
Amsterdam's protected lane network density demonstrates modal shift viability, with cycling infrastructure completeness validating motorized two-wheel alternatives for daily travel under 15 kilometers. Municipal purchase subsidies and employer lease programs have created the highest per-capita adoption globally. Eindhoven and Utrecht concentrate cargo bike manufacturing clusters serving European logistics networks.
China
GB standards and NMPA-equivalent quality certifications enforce battery safety protocols and motor performance labeling that govern export eligibility for international markets. Domestic demand concentrates in tier-one cities where municipal congestion policies restrict combustion two-wheelers. The Yangtze River Delta and Pearl River Delta house cell manufacturing basins supplying global battery pack assemblers.
United States
The Consumer Product Safety Commission and state-level three-class designation systems govern motor wattage, speed limits, and trail access eligibility, creating fragmented compliance requirements across jurisdictions. Direct-to-consumer channels scale most effectively in metropolitan markets with limited established bicycle retail infrastructure. California and New York anchor early adopter concentrations where parking scarcity and congestion pricing push commuters toward motorized alternatives.
France
Employer-funded lease programs and municipal micro-mobility concessions normalize subscription-based access models over capital deployment for urban commuters. The country's long-distance cycle network development sustains touring bike demand across Alpine and coastal routes. Paris anchors fleet conversion volumes as last-mile logistics operators respond to low-emission zone enforcement.
Electric Bicycle Market Vendor Landscape
Premium-margin players sit above commodity-margin players across drive unit sophistication and frame-integrated battery architectures. The vendor base organizes into three tiers: drive unit specialists supplying proprietary motor systems to frame assemblers; integrated manufacturers controlling frame-motor-battery architectures; and direct-to-consumer brands competing through pricing accessibility and accessory ecosystems. Consolidation pressures concentrate among mid-tier frame fabricators lacking captive drive unit supply, while technology licensing agreements and strategic partnerships dominate competitive moves between drive unit suppliers and bicycle assemblers.
Within the integrated manufacturing tier, Giant Manufacturing Co., Ltd. and Yamaha Motor Co., Ltd. exemplify contrasting geographic origins and structural approaches to market positioning. Rad Power Bikes occupies a distinct archetype among direct-to-consumer specialists. These three entities collectively illustrate the competitive segmentation between proprietary technology control, manufacturing scale, and channel innovation that defines current market structure.
| Leading Market Players |
|---|
| Giant Manufacturing Co., Ltd. |
| Yamaha Motor Co., Ltd. |
| Trek Bicycle Corporation |
| Rad Power Bikes |
| Aventon Bikes |
| Accell Group |
| Specialized |
| Bosch eBike Systems |
| Pedego Electric Bikes |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cathode precursor costs cascade through three distinct pricing tiers before reaching fleet operators and commuters, with NMC and LFP cell formats commanding premium positioning over lead-acid alternatives in European and North American markets. Battery pack economics compress entry-tier pricing in Asian manufacturing basins while REACH compliance and EU Battery Regulation due diligence obligations inflate landed costs for European assemblers sourcing from East Asian cell manufacturers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates mid-drive torque-sensing configurations from hub-motor commuter specifications and lead-acid entry products. Price differentiation hinges on drive unit sophistication and battery certification grade, with KBA type-approval and JIS certification creating regulatory moats around German and Japanese suppliers. Cost compression in the economy tier intensifies as Chinese frame fabricators expand direct-to-consumer channels. Delivery services exhibit highest price sensitivity due to fleet-scale procurement volumes, while Alpine touring cyclists demonstrate lowest sensitivity where gradient performance commands purchase decisions.
Supply Chain Analysis
Cathode active material supply rests on Chinese, South Korean, and Japanese specialty chemical producers, with the Yangtze River Delta and Pearl River Delta housing concentrated cell manufacturing basins. Frame fabrication draws from Taiwanese aluminum forging and Vietnamese welding assembly, while drive unit production centers on German and Japanese precision engineering clusters. Single-source vulnerability concentrates in rare earth magnet supply for mid-drive motors. Distribution runs through established bicycle retail networks in European cities, direct-to-consumer platforms in North American metropolitan markets, and OEM supply agreements for fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electric bicycle market functions as a geographic-arbitrage play between EU Green Deal subsidy density in Amsterdam, Berlin, and Paris versus manufacturing cost basins in the Yangtze River Delta, with regulatory compliance costs offsetting labor differentials for European market access.
For Market Incumbents: Cement captive supply agreements for lithium-ion cells before EU Battery Regulation recycled content thresholds harden supplier qualification requirements. Secure KBA type-approval moats around mid-drive drive units to defend against Chinese hub-motor entrants expanding through direct-to-consumer channels. Vertical integration into battery pack assembly preserves margin control as cell costs decline.
For New Entrants and Emerging Players: France's cycle-to-work subsidy expansion opens a window for subscription-based fleet operators targeting employer-funded lease programs in Paris and Lyon. Target Sub-Saharan African urban mobility networks where solar-charged e-bike displacement of motorcycle taxis meets pay-as-you-go battery subscription capital barriers. Pursue cargo bike specialization for Berlin and London last-mile logistics operators under low-emission zone compliance pressure.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier frame fabricators lack captive drive unit supply and face margin compression from both integrated manufacturers and direct-to-consumer brands. Mid-cap specialists with established European service network density represent priority acquisition targets. Watch subsidy phase-out schedules in the Netherlands and Germany as inflection indicators for demand elasticity.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Swapping Infrastructure Deployment | Decouples vehicle purchase from energy ownership, reducing upfront capital barriers for fleet operators in Amsterdam and Paris. |
| Mid-Drive Torque Sensing Convergence | Integrates load-adaptive motor control with automatic transmission systems for Alpine cargo and touring segments. |
| EU Battery Regulation Compliance Investment | Establishes chain-of-custody documentation and recycled material sourcing ahead of mandatory thresholds. |
| Direct-to-Consumer Channel Expansion | Bypasses established bicycle retail infrastructure in North American metropolitan markets with limited dealer density. |
| Sub-Saharan African Mobility Network Buildout | Positions solar-charged e-bike networks as motorcycle displacement where grid reliability gaps persist. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drive unit engineering directors, fleet procurement managers at logistics operators, municipal cycling infrastructure planners, and battery pack assembly technical leads with secondary validation against KBA type-approval filings, EU Battery Regulation draft texts, and customs trade data for lithium-ion cell imports. Bottom-up triangulation across product segment volumes and top-down macroeconomic anchoring converged on market size estimates.
Comparable historical periods anchored the projection horizon to observed adoption curves in Amsterdam, Copenhagen, and Utrecht cycling infrastructure deployment timelines. Segmentation dimensions modeled include product architecture, drive unit technology, battery chemistry format, end-user archetype, and regional regulatory cluster. CAGRs derived from fitted growth curves incorporating fleet electrification mandate compliance schedules and lithium-ion cell cost decline trajectories.
Revisions become necessary when EU Green Deal subsidy phase-out schedules accelerate, REACH battery recycling mandates expand scope, or East Asian supply rationing disrupts cathode precursor availability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Car Battery Chargers Market
Electric Vehicles
Italy Hybrid Electric Vehicle Battery Market
Electric Vehicles
Railway Lithium Battery Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
EV Lightweight Materials Market
Electric Vehicles
Global Automotive Inductive Wireless Charging Systems Market
Electric Vehicles
Electric Water Pump for Electric Vehicles Market
Electric Vehicles
US Electric Vehicle Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Worldwide EV Range Extender Market
Electric Vehicles
Latin America Electric Bus Market
Electric Vehicles
Battery Electric Vehicle (BEV) Market
Electric Vehicles
Global EV Relay Market
Electric Vehicles
France Electric Bus Battery Pack Market
Electric Vehicles
Speed Pedelec E-Bike Market
Electric Vehicles
Electric Vehicle Battery Trays Market