
 Construction Electric Vehicle Market | 2026-2036
Construction Electric Vehicle Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Electric Vehicle Market Analysis
The EU Green Deal is repositioning procurement criteria for European construction fleets toward zero-emission machinery. Volvo leverages its electric excavator platform to anchor Nordic infrastructure contracts. BYD competes on battery cost scale, extending its cell-to-chassis architecture into heavy-duty construction applications. Ford positions its commercial EV division to capture municipal road-building tenders across North American cities.
Construction electric vehicles are battery-powered or hydrogen-fueled heavy machinery engineered for earthmoving, material handling, and site logistics, typically operating at 350-800V architectures with regenerative braking systems designed for stop-start duty cycles. Excavators dominate current deployment due to their predictable duty profiles and high fuel savings potential, while hydrogen fuel cell dump trucks represent the fastest-expanding power source segment for long-haul material transport. Battery electric forklifts already occupy a mature margin pool in warehousing-adjacent construction logistics, where charging infrastructure integrates with existing grid connections.
EPA Tier 4 Final standards and the EU F-Gas Regulation are tightening emissions compliance for diesel-powered equipment, directly accelerating electric alternatives in regulated markets. China's MIIT enforces GB standards for new energy commercial vehicles, creating mandatory electrification pathways for domestic manufacturers. Stakeholders must monitor how overlapping carbon border mechanisms and local content requirements reshape equipment certification costs across multi-jurisdictional project portfolios.
Market Dynamics
Fleet operators face a structural inflection as diesel fuel cost volatility collides with EU F-Gas Regulation phase-down schedules and China's MIIT enforcement of GB standards for new energy commercial vehicles. Electrification capex decisions now hinge on total-cost-of-ownership recalibration against residual value uncertainty in secondary equipment markets.
Growth Catalysts
- EU Green Deal procurement mandates:Public infrastructure tenders in Germany, France, and the Netherlands now specify zero-emission machinery, redirecting capital allocation from diesel fleets.
- Urban air quality frameworks:Low-emission zones in London, Oslo, and Copenhagen ban diesel construction equipment during peak pollution episodes, forcing fleet turnover.
- Battery energy density gains:Cell-to-pack architectures are compressing weight-per-kWh ratios, enabling 350-800V systems to power 50-ton excavators without payload penalties.
Market Restraints
- Lithium carbonate price volatility:Battery pack costs remain tethered to Chilean and Australian spodumene concentrate markets, squeezing OEM margins on fixed-price municipal contracts.
- Charging infrastructure gaps:Rural highway construction corridors lack 800V DC fast-charging depots, stranding electric dump trucks on material haul routes exceeding 150 kilometers.
- Residual value opacity:Secondary buyers demand diesel equipment for export to Southeast Asia and Africa, collapsing trade-in values for electric units.
Strategic Opportunities
- India's PLI scheme for advanced chemistry cells:Domestic battery manufacturing incentives are attracting construction equipment OEMs to localize assembly for South Asian mining and road-building verticals.
- Hydrogen fuel cell convergence:Proton-exchange-membrane stacks paired with 700-bar storage are opening 24-hour continuous-duty applications in tunnel boring and quarry operations.
- Telematics-enabled outcome pricing:Equipment-as-a-service models tied to cubic-meters-moved metrics are displacing capital sales in Nordic municipal markets.
Industry Challenges
- High-voltage technician scarcity:OEMs and fleet operators compete for electricians certified to 800V DC systems, inflating field service labor costs by 40% versus diesel mechanics.
- Multi-jurisdictional type approval:Equipment crossing EU, Swiss, and Norwegian borders requires parallel CE marking, Swissmedic notification, and KBA homologation, extending launch timelines by 8-14 months.
- Grid interconnection queues:Construction site temporary power permits face 6-18 month utility backlogs in Germany and California, delaying fleet electrification projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Electric Vehicle Market |
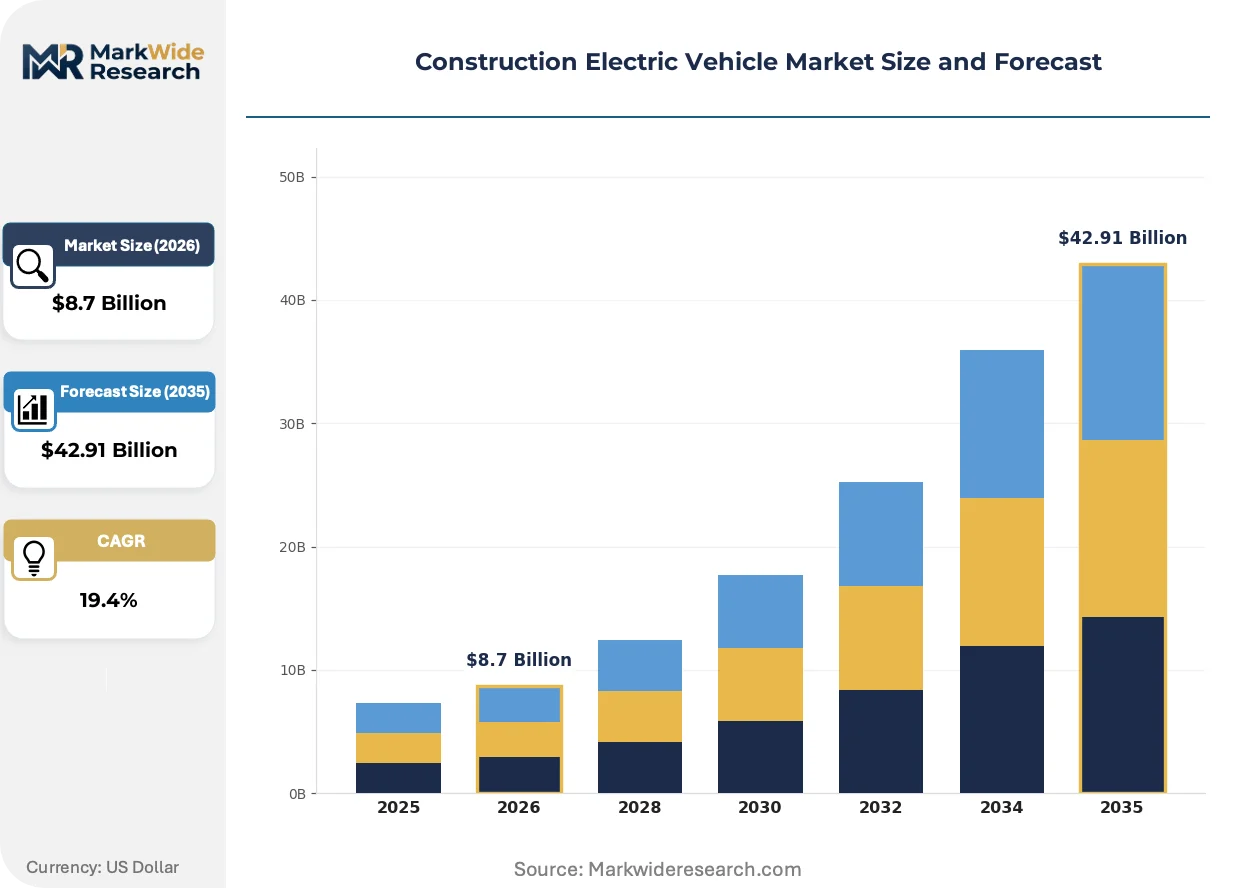
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Excavators, Dump Trucks, Forklifts, Loaders Power Source: Battery Electric, Hybrid, Hydrogen Fuel Cell, Plug-in Hybrid Charging Infrastructure: On-site Charging, Fast Charging Stations, Wireless Charging, Standard Charging End User: Construction Companies, Municipalities, Contractors, Road Builders |
| Companies Covered | Mercedes-Benz, Daimler, Volvo, General Motors, Hyundai, BYD, Rivian, Workhorse, Ford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Electric Vehicle Market Emerging Trajectories
Autonomous machine control and predictive load management are converging to reshape how electric construction equipment optimizes energy consumption across variable duty cycles. These advances are compressing the efficiency gap between battery-electric and diesel-hydraulic architectures.
Telematics-integrated battery management systems are automating charge scheduling, thermal preconditioning, and regenerative braking calibration based on real-time soil density and elevation data. Mining contractors in Western Australia and Chilean copper pits are deploying these systems to extend shift duration without midday charging. The technology is automating energy arbitrage decisions that previously required operator judgment, reducing per-cubic-meter energy costs by eliminating manual inefficiencies.
EPA Tier 4 Final and EU Stage V emissions standards are tightening particulate matter and NOx limits for diesel engines below 56 kW, pushing compact equipment categories toward full electrification. The regulatory compression is accelerating R&D spillover from automotive into off-road powertrains. Compact excavators and skid-steer loaders face the steepest compliance cost escalation, making battery-electric alternatives cost-competitive at 2,000 annual operating hours.
Municipal procurement departments are consolidating equipment specifications into framework agreements that mandate electric alternatives for contracts above threshold values. Stockholm, Copenhagen, and Amsterdam have synchronized tender requirements through the C40 Cities network, creating pooled demand volumes that justify OEM dedicated production lines. This concentration is forcing distributors to restructure inventory and service capabilities around charging infrastructure deployment rather than fuel logistics.
Construction Electric Vehicle Market Segmentation
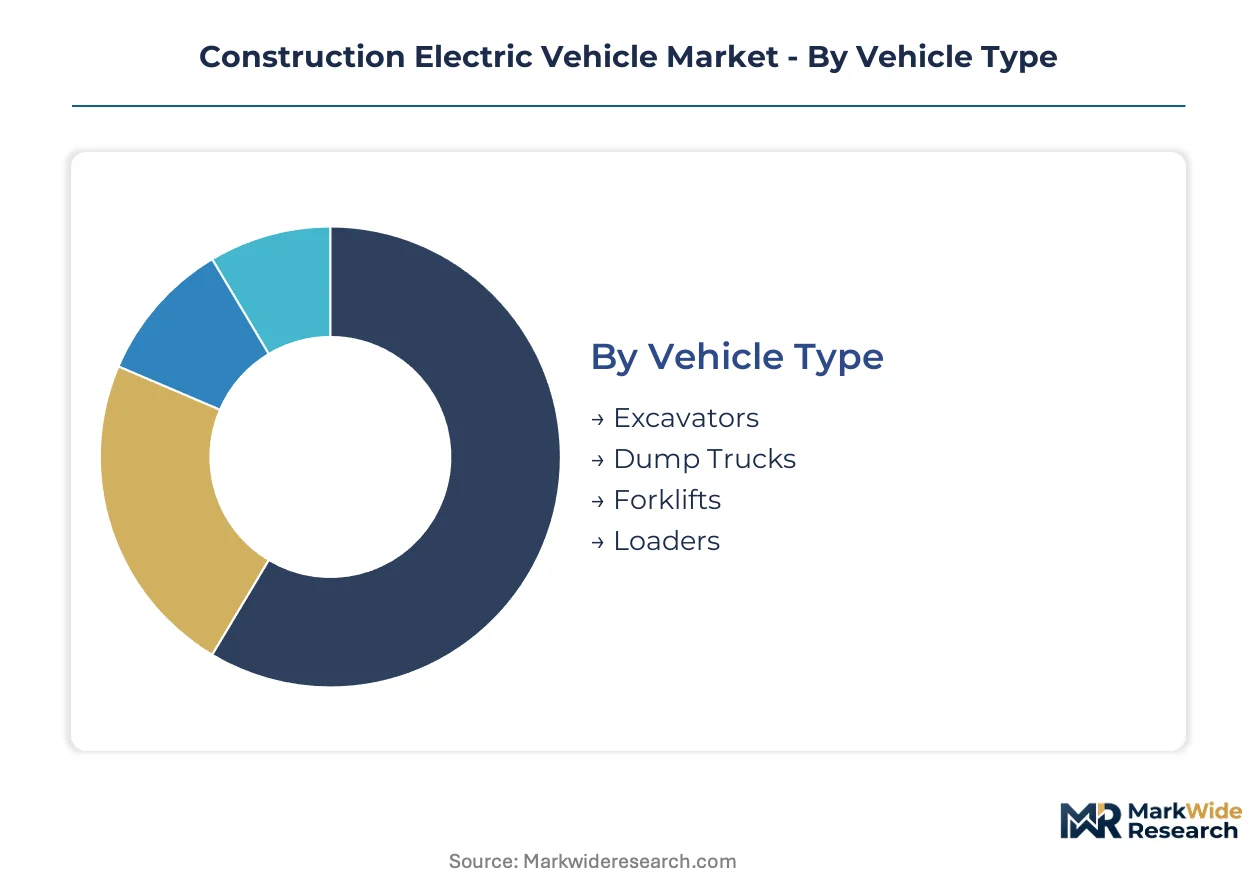
Segmentation in construction electric vehicles reveals how powertrain architecture, duty cycle intensity, and site logistics complexity dictate procurement patterns. Equipment buyers optimize across voltage platforms, charging accessibility, and project duration to match capital deployment with operational constraints.
Vehicle Type:
Voltage architecture and hydraulic system integration separate equipment categories by duty cycle predictability and fuel displacement potential.
- Excavators:These machines operate on 350-800V platforms with regenerative braking calibrated for repetitive dig-lift-swing cycles. German urban infrastructure projects and Chinese manufacturing clusters are concentrating orders for 20-50 ton units where diesel fuel costs exceed battery lease spreads.
- Dump Trucks:Long-haul material transport exceeding 150 kilometers per shift is driving hydrogen fuel cell adoption in Nordic tunneling and Australian mining corridors, where midday charging downtime disrupts continuous operations.
- Forklifts:Mature battery-electric penetration in warehousing-adjacent construction logistics leverages existing 480V grid connections for overnight charging.
- Loaders:Compact wheel loaders face steep EPA Tier 4 Final compliance cost escalation below 56 kW, accelerating electric alternatives for municipal road maintenance fleets.
Excavators lead on scale; hydrogen fuel cell dump trucks lead on momentum.
Power Source:
Energy storage chemistry and refueling infrastructure shape total-cost-of-ownership calculations across variable project durations.
- Battery Electric:Cell-to-pack architectures compressing weight-per-kWh ratios enable 50-ton excavators without payload penalties. Stockholm and Copenhagen municipal tenders mandate this configuration for framework agreements above threshold contract values.
- Hydrogen Fuel Cell:Proton-exchange-membrane stacks paired with 700-bar storage address 24-hour continuous-duty applications in Chilean copper pits and Western Australian iron ore operations where charging gaps strand battery alternatives.
- Hybrid:Diesel-electric architectures bridge residual value uncertainty in secondary markets targeting Southeast Asian export.
- Plug-in Hybrid:Smaller battery packs with combustion range extension appeal to rural highway contractors lacking 800V DC fast-charging depot coverage.
Battery electric dominates current deployment; hydrogen fuel cell configurations are climbing the fastest as heavy-duty applications electrify.
Charging Infrastructure:
Site power availability and grid interconnection timelines determine fleet operational readiness and capital scheduling.
- On-site Charging:Temporary construction power permits face 6-18 month utility backlogs in Germany and California, delaying project electrification timelines.
- Fast Charging Stations:800V DC infrastructure enables midday opportunity charging for excavators on intermittent duty cycles.
- Wireless Charging:Inductive pads at loading zones automate energy transfer for autonomous haul trucks in controlled quarry environments.
- Standard Charging:Overnight Level 2 AC suffices for forklifts and compact loaders with predictable daily utilization below 8 hours.
On-site charging leads on scale; fast charging stations lead on momentum.
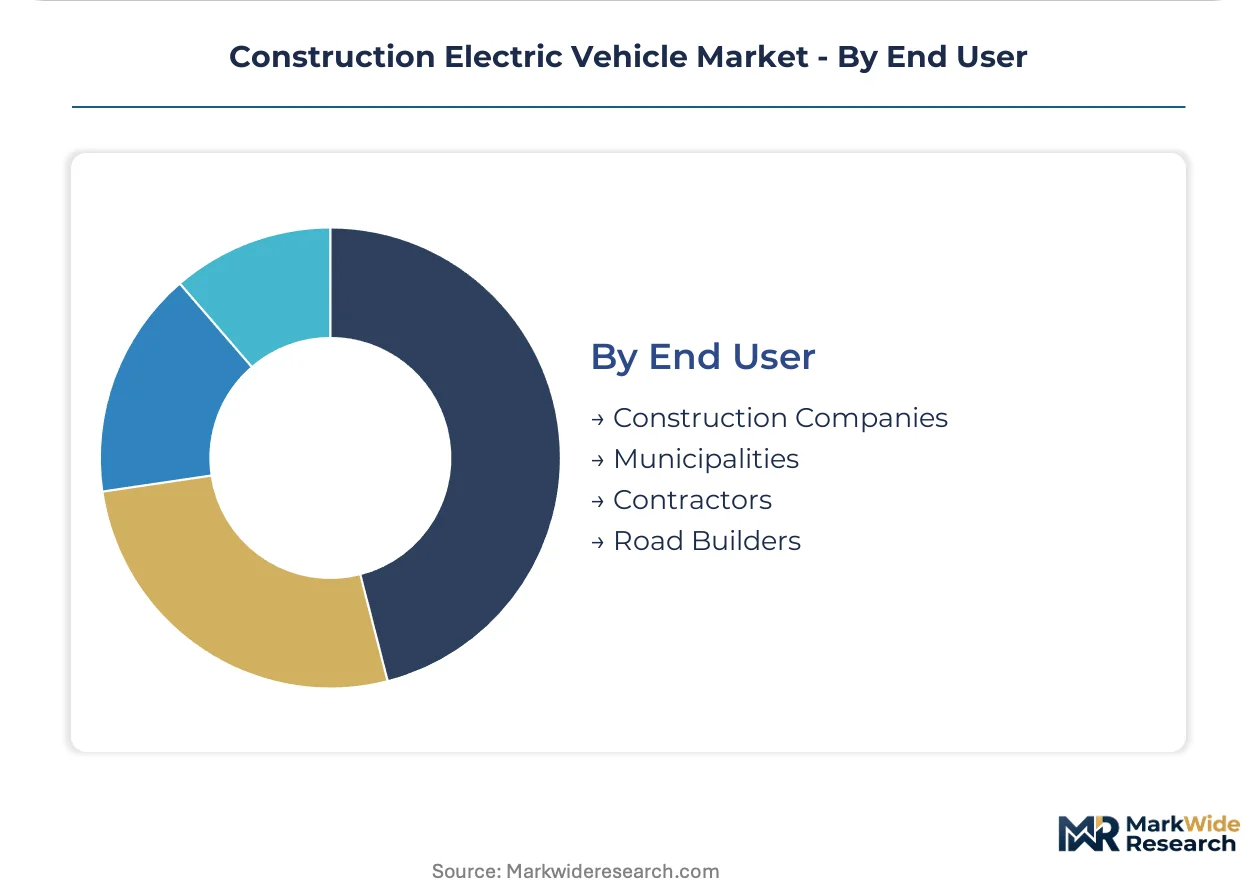
End User:
Procurement authority and project financing structure create divergent specifications for equipment performance and service integration.
- Construction Companies:Large fleet operators recalibrate total-cost-of-ownership models against diesel price volatility and EU F-Gas Regulation phase-down schedules.
- Municipalities:C40 Cities network members including Amsterdam, Copenhagen, and Stockholm synchronize tender requirements through framework agreements mandating zero-emission machinery.
- Contractors:Subcontractor equipment pools prioritize residual value liquidity for export to African and Southeast Asian secondary markets.
- Road Builders:Highway construction corridors spanning rural distances exceed current 800V DC fast-charging depot density, constraining electric dump truck deployment.
Municipalities lead on scale; construction companies lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering conglomerates pioneered electrified earthmoving platforms in the 2010s, establishing technical foundations that Chinese battery integrators and Nordic municipal fleets now scale across divergent regulatory environments.
China
Construction equipment manufacturing clusters in Changsha and Xuzhou concentrate electric excavator assembly lines serving domestic infrastructure stimulus. MIIT enforcement of GB standards for new energy commercial vehicles mandates electrification pathways for OEMs. BYD extends its cell-to-chassis architecture into heavy-duty applications from Shenzhen.
Germany
Urban infrastructure projects in Berlin, Munich, and Hamburg accelerate fleet electrification through framework tender specifications. The EU Green Deal tightens emissions standards for off-road machinery, redirecting public procurement budgets. KBA homologation requirements extend launch timelines for equipment crossing into Swiss and Norwegian markets.
United States
Municipal road-building tenders in California, Texas, and New York Metro drive commercial EV division positioning. EPA Tier 4 Final standards escalate compliance costs for diesel-powered compact equipment below 56 kW. Grid interconnection queues in California delay construction site temporary power permits by 6-18 months.
Sweden
Volvo anchors Nordic infrastructure contracts through its electric excavator platform deployment in Stockholm and Gothenburg. Low-emission zones in Oslo and Copenhagen ban diesel construction equipment during peak pollution episodes, forcing fleet turnover. The C40 Cities network synchronizes tender requirements with Amsterdam and Copenhagen.
India
The PLI scheme for advanced chemistry cells attracts construction equipment OEMs to localize assembly for South Asian mining and road-building verticals. Domestic battery manufacturing incentives reshape procurement patterns in Maharashtra and Gujarat. Road construction corridors spanning rural distances exceed current fast-charging depot density.
Construction Electric Vehicle Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent electrification strategies. The market structures around three tiers: integrated automotive conglomerates repurposing passenger EV architectures, dedicated commercial vehicle specialists engineering ground-up platforms, and battery-technology firms extending cell chemistries into off-road duty cycles. Strategic moves concentrate on M&A for charging infrastructure assets and capacity expansion in high-voltage powertrain assembly.
Among integrated automotive conglomerates, Volvo and BYD occupy archetypal positions—Volvo representing Nordic engineering-led platform development, BYD exemplifying battery-cost-scale integration. Ford sits within the commercial vehicle specialist tier, leveraging municipal procurement relationships. These three anchors demonstrate how divergent origin points—European machinery heritage, Chinese battery verticalization, American fleet distribution—converge on construction electrification.
| Leading Market Players |
|---|
| Mercedes-Benz |
| Daimler |
| Volvo |
| General Motors |
| Hyundai |
| BYD |
| Rivian |
| Workhorse |
| Ford |
| Others |
Supply Flow & Price Mechanics
Captive battery production in China and South Korea anchors both supply security and pricing power for construction electric vehicle OEMs. BYD's in-house cell manufacturing compresses pack costs below outsourced alternatives, while European assemblers absorb margin penalties from Chilean lithium carbonate volatility.
Pricing Analysis
Project-based equipment leasing with cubic-meters-moved outcome metrics dominates municipal procurement in Stockholm, Copenhagen, and Amsterdam. Price differentiation hinges on certification tier—CE-marked units command premiums over baseline configurations—and after-sales service bundling that includes 800V technician deployment. Cost compression in mid-tier excavators is intensifying because fixed-price municipal contracts expose OEMs to lithium carbonate swings. Subcontractor equipment pools show highest price sensitivity due to residual value opacity in African and Southeast Asian export markets.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Long Beach orchestrate hub-and-spoke patterns for high-voltage powertrain components. Geographic supply concentration centers on China for battery cell production, Chile and Australia for lithium spodumene concentrate, and Germany for hydraulic system integration. Raw material dependencies draw from cobalt hydroxide, rare earth permanent magnets, and copper busbar stock. Single-source vulnerability in 800V silicon carbide inverters from Taiwanese foundries threatens production continuity. Distribution runs through OEM-owned service depots that co-locate charging infrastructure and certified technician teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Construction electric vehicle procurement has shifted toward premium specifications as EU Green Deal mandates harden zero-emission requirements in German and Dutch infrastructure tenders.
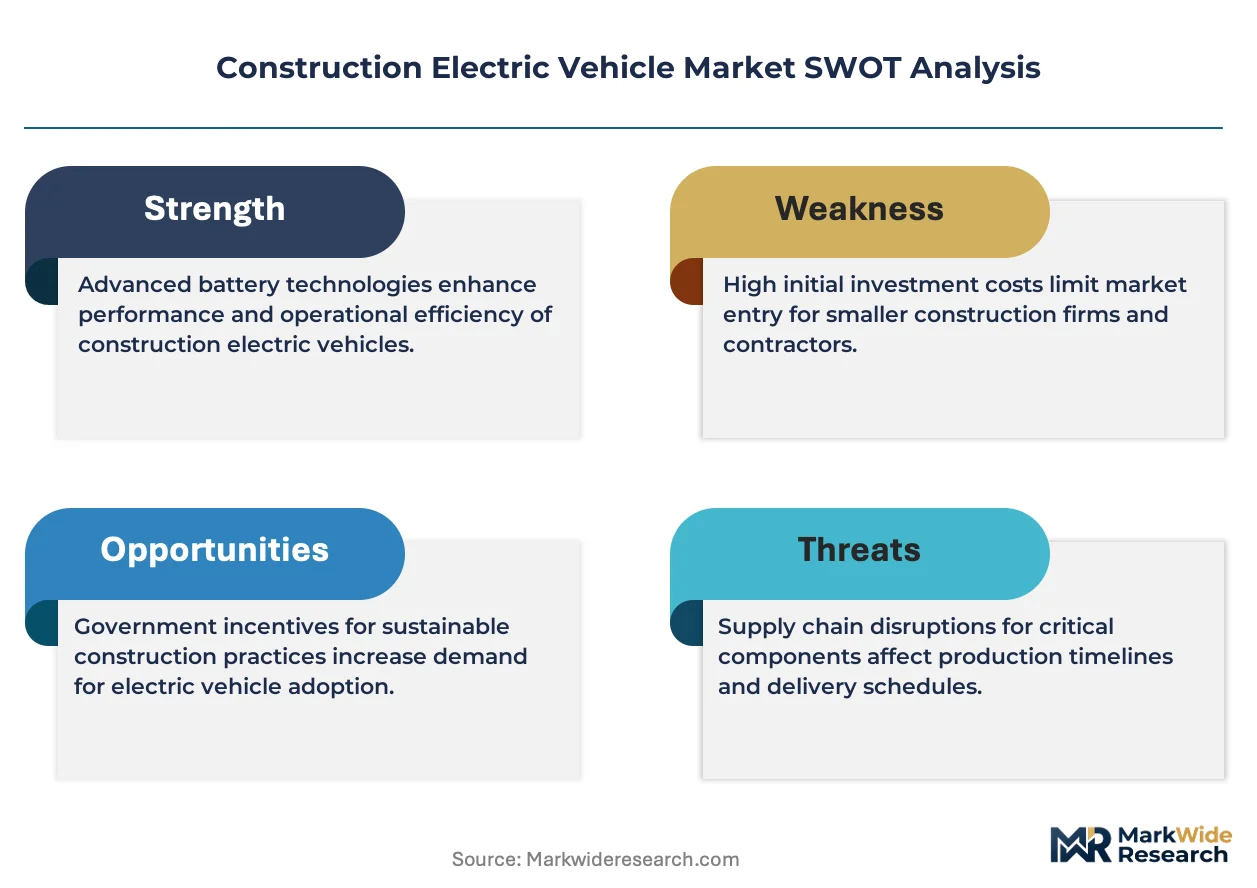
For Market Incumbents: Hedge lithium carbonate exposure through long-term offtake agreements with Chilean and Australian miners. Strengthen captive 800V inverter production to reduce Taiwanese foundry dependency. Battery cost volatility and emerging Chinese OEM price aggression threaten established margin structures in European municipal markets. For New Entrants and Emerging Players: EU F-Gas Regulation phase-down schedules in Germany open a window for hydrogen fuel cell dump truck specialization in Nordic tunneling corridors. Target India's PLI scheme for advanced chemistry cell localization to serve Maharashtra and Gujarat mining verticals. White-space exists in telematics-integrated battery management systems for Western Australian iron ore contractors. Go-to-market through equipment-as-a-service outcome pricing displaces capital sales in municipal frameworks. For Investors and Strategic Acquirers: Roll-up economics work for regional charging infrastructure operators because construction site electrification creates captive demand pools with 6-18 month utility interconnection backlogs. Long-term viability favors asset-light platform specialists over capital-heavy OEM manufacturing. Watch hydrogen fuel cell stack cost curves as the inflection signal for 24-hour continuous-duty market penetration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Cell Production | BYD's captive supply in Shenzhen insulates margins from Chilean lithium volatility. |
| Equipment-as-a-Service Platform Launch | Volvo's cubic-meters-moved pricing captures Stockholm municipal framework contracts. |
| Hydrogen Fuel Cell Range Extension | Proton-exchange-membrane stacks enable 24-hour duty in Chilean copper pit operations. |
| Telematics-Integrated Battery Management | Predictive load scheduling extends shift duration without midday charging in Western Australia. |
| Regional Distribution Center Expansion | Rotterdam hub consolidates EU spare parts logistics for 800V powertrain components. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged construction fleet managers, municipal procurement officers, OEM platform engineers, and high-voltage technician training program directors. Secondary validation drew from MIIT GB standard filings, EPA Tier 4 Final compliance databases, EU tender documentation through Tenders Electronic Daily, and customs trade data for lithium carbonate concentrate flows. Bottom-up equipment deployment tracking and top-down infrastructure investment analysis were triangulated against regional regulatory timelines.
Historical reference periods anchored the projection horizon to pre-pandemic baseline capacity and post-stimulus normalization phases. Segmentation modeling spanned vehicle type, power source architecture, charging infrastructure category, and end-user procurement authority. CAGRs were derived from equipment shipment trajectories and infrastructure investment commitments. Industry-specific inputs included grid interconnection queue durations in Germany and California, and hydrogen refueling station deployment cadence in Nordic corridors.
Revisions become necessary when lithium carbonate price bands shift beyond modeled scenarios, EU carbon border mechanisms expand coverage to construction equipment, or 800V fast-charging depot density in rural highway corridors accelerates beyond utility backlog assumptions. Forecasts reflect documented parameter sets and scenario weights. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
Electric Vehicle (EV) Battery Housing Market
Electric Vehicles
Oman Electric Vehicle (EV) Market
Electric Vehicles
Europe Electric Bus Market
Electric Vehicles
Scooter Market
Electric Vehicles
Electric Passenger Cars Market
Electric Vehicles
Water Proof E-Scooter Market
Electric Vehicles
E-Lock for Electric Vehicle Charging Market
Electric Vehicles
India Electric Vehicle Market
Electric Vehicles
Canada Solar E-Bike Market
Electric Vehicles
Global Vehicle to Grid Technology Market
Electric Vehicles
United States Electric Pick-Up Trucks Market
Electric Vehicles
China Electric Car Market
Electric Vehicles
UK Electric Bus Battery Pack Market
Electric Vehicles
France Electric Vehicle Market
Electric Vehicles
India Electric Car Market
Electric Vehicles
EV Condenser Market